
 Neon Gas Market | 2026-2036
Neon Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Neon Gas Market Analysis
Semiconductor-grade neon is collapsing the gap between commodity gas and critical lithography input, forcing buyers to qualify new supply sources outside traditional Eastern European channels. Messer Group GmbH leverages captive air separation capacity in Germany to sustain wafer-fab contracts without Ukrainian transit exposure. Linde plc anchors North American supply through new cryogenic distillation investments in Texas. Air Liquide competes on purification technology leadership, offering sub-ppm impurity specifications that match Tokyo Electron tool requirements.
Neon gas is a noble gas comprising single-atom molecules extracted through fractional distillation of liquid air, with semiconductor-grade material requiring purity levels exceeding 99.999% and particulate filtration below 0.1 micron for deep ultraviolet lithography systems. Its primary industrial purpose centers on excimer laser mixtures that generate 193-nanometer wavelengths for critical dimension patterning at 7nm and below process nodes. Display lighting applications retain volume leadership across the consumption base, though medical equipment segments in proton beam therapy systems represent the fastest-growing demand pool as cancer treatment facilities expand installed base. High-capacity lasers for semiconductor manufacturing command the largest margin concentration, with pricing multiples of three to five times over advertising sign-grade material due to certification burdens and supply scarcity.
EPA emissions tracking requirements and OSHA workplace exposure limits shape handling protocols for neon distribution across US semiconductor fabrication zones, while REACH substance registration in Europe governs import documentation for non-EU supply sources. South Korea's MFDS and Japan's METI coordinate strategic stockpile mandates that directly influence procurement contract structures and inventory holding obligations among Japanese and Korean device manufacturers. Stakeholders must monitor air separation unit commissioning timelines in Qatar and the United States against lithography tool delivery schedules to avoid qualification mismatches.
Market Dynamics
Semiconductor lithography systems are compressing qualification timelines for non-Ukrainian neon supply sources as 7nm and below process nodes expand production capacity. Air separation unit investments in Texas and Qatar face synchronization risks against Tokyo Electron and ASML tool delivery schedules.
Growth Catalysts
- Deep ultraviolet lithography expansion:193-nanometer excimer laser systems at Taiwanese logic foundries and South Korean memory fabs are pulling high-purity neon volumes beyond pre-2022 supply baselines.
- REACH substance registration:European import documentation requirements for non-EU supply sources are accelerating supplier certification investments that lock in long-term procurement contracts.
- Proton beam therapy proliferation:Cancer treatment facilities in Japan and South Korea are expanding installed base for particle accelerator systems that require medical-grade neon mixtures.
Market Restraints
- Air separation unit capital intensity:Cryogenic distillation facilities require three-to-five-year commissioning timelines that mismatch semiconductor tool procurement cycles.
- Eastern European supply concentration legacy:Pre-2022 Ukrainian and Russian purification infrastructure still accounts for significant historical production share, creating stranded asset risk.
- Helium-neon laser substitution:Solid-state diode lasers are capturing price-sensitive metrology and alignment applications that previously consumed lower-grade neon mixtures.
Strategic Opportunities
- Qatar air separation cluster:Industrial gas infrastructure expansion at Ras Laffan is positioning the emirate as a lithography-grade neon export hub with integrated marine logistics.
- Sub-ppm purification technology:Advanced cryogenic adsorption systems are opening specification tiers that match next-generation EUV lithography tool requirements.
- South Korean strategic stockpile mandates:MFDS inventory holding obligations are creating long-term offtake agreements that de-risk greenfield production investments.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized technicians for fractional distillation operations are concentrated at legacy Eastern European facilities, complicating Texas and Qatar staffing.
- Multi-year qualification protocols:Semiconductor fabs require 18-to-24-month impurity stability documentation that delays volume ramp at new supply sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neon Gas Market |
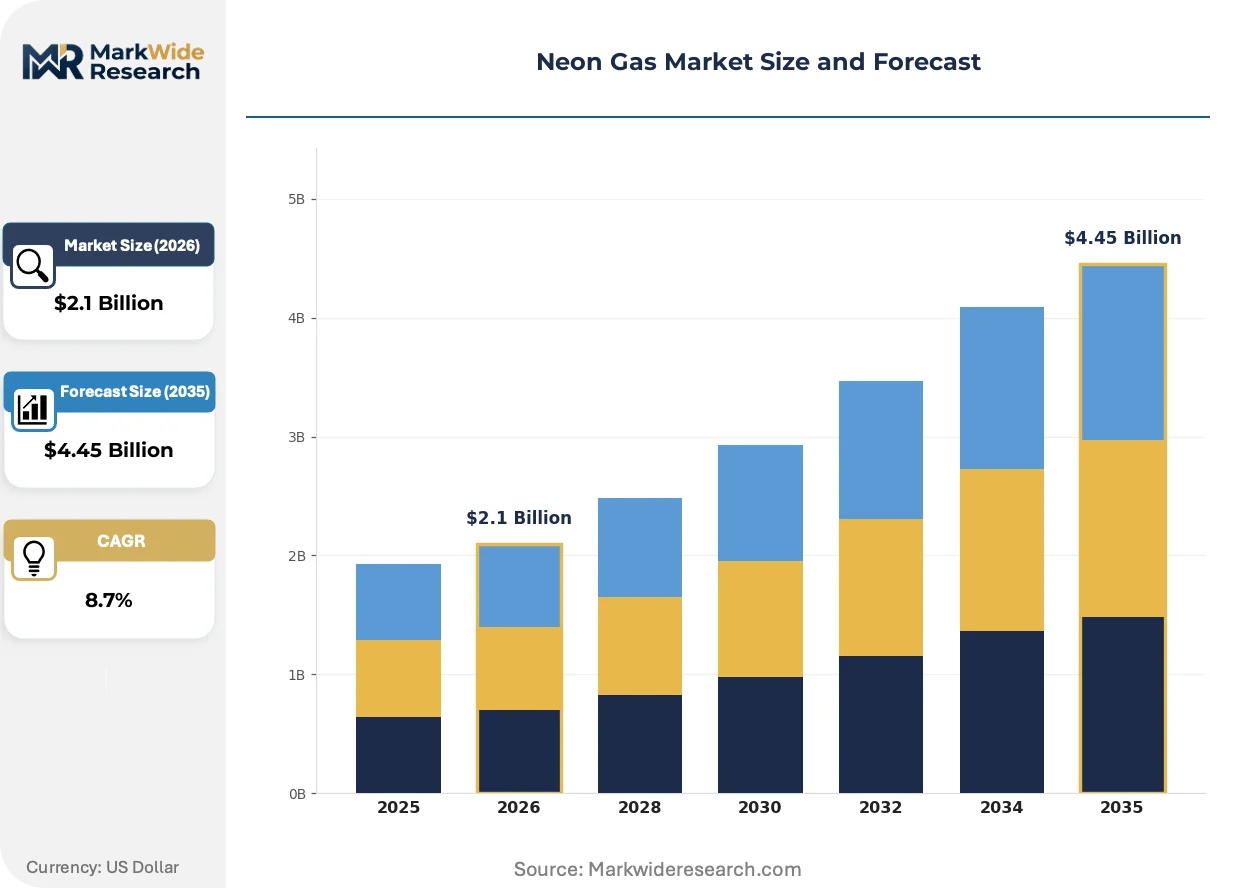
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.45 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neon Lights, High-Capacity Lasers, Advertising Signs, Neon Tubes Application: Display Lighting, Medical Equipment, Aerospace Applications, Optical Devices End User: Manufacturing, Entertainment, Telecommunications, Healthcare Distribution Channel: Wholesale, Retail, Online Sales, Direct Supply |
| Companies Covered | Messer Group GmbH, Taiyo Nippon Sanso Corporation, Air Liquide, Iceblick Ltd, Airgas, Linde plc, Matheson Tri-Gas, Axcel Gases, Air Products and Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neon Gas Market Emerging Trajectories
Neon supply architecture is fragmenting across purification technology tiers as lithography tool makers tighten impurity specifications. Three concurrent developments are compressing traditional procurement models.
Membrane-based pre-concentration systems are displacing conventional pressure-swing adsorption for initial air separation stages. Texas-based industrial gas operators are adopting these units to reduce energy intensity at cryogenic distillation facilities. The technology is displacing legacy purification trains that relied on Ukrainian crude neon feedstock, enabling captive production from atmospheric air without transit exposure.
EPA emissions tracking requirements are mandating fugitive gas monitoring at semiconductor fabrication zones. Handling protocols now require continuous leak detection instrumentation and quarterly reporting that adds operational overhead. US-based wafer fabs are responding by consolidating neon storage into centralized bulk tanks with vapor recovery systems rather than distributed cylinder networks.
Long-term take-or-pay contracts are supplanting spot market purchases for lithography-grade material. South Korean memory manufacturers are locking five-to-seven-year supply agreements that embed minimum volume commitments and price escalation caps. This shift concentrates procurement leverage at three-to-four domestic air separation operators while marginalizing trading intermediaries.
Neon Gas Market Segmentation
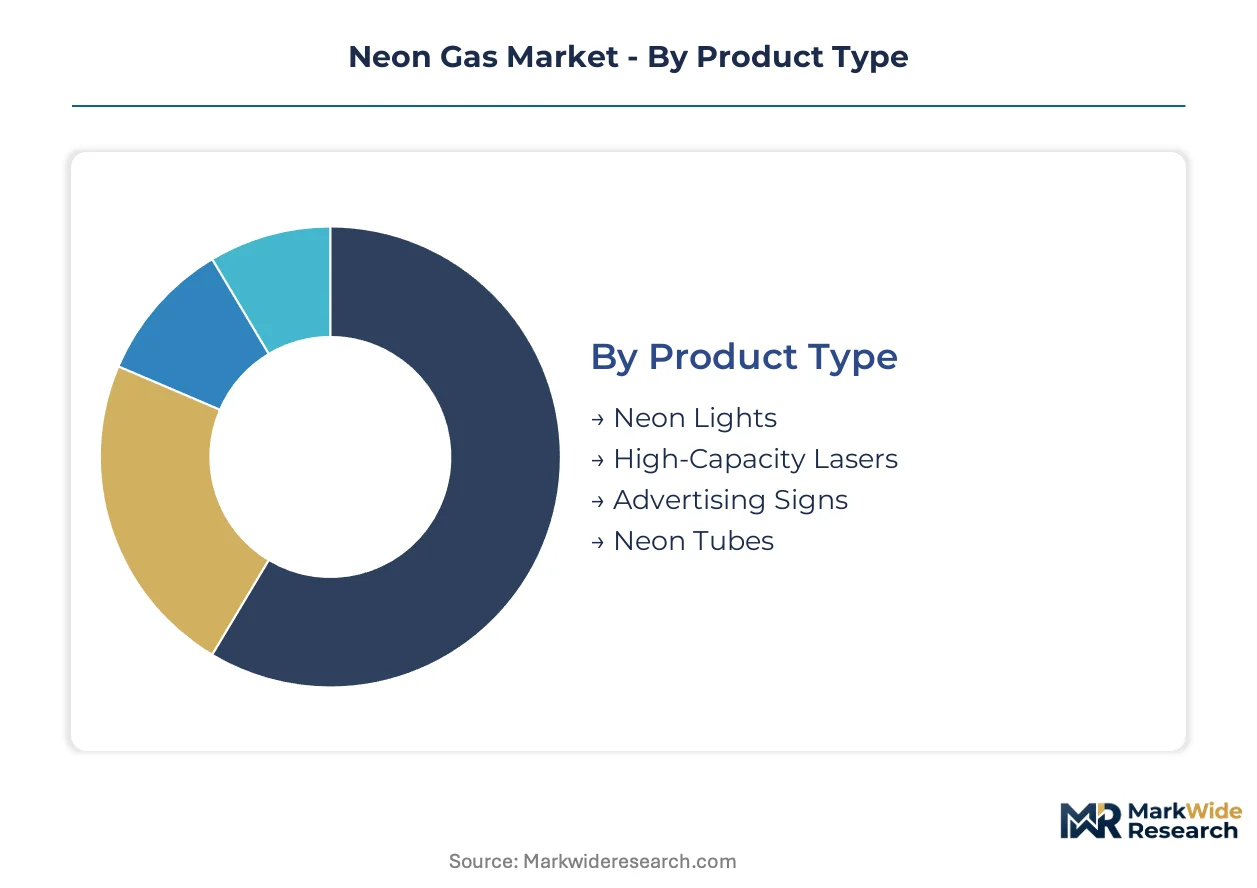
Neon gas segmentation reflects divergent purity specifications and regulatory compliance burdens across end-use categories. Semiconductor-grade material commands qualification protocols that advertising-grade products bypass entirely.
Product Type:
EPA emissions tracking and OSHA workplace exposure limits create tiered handling requirements that separate lithography-grade products from signage material.
- High-Capacity Lasers:Excimer laser mixtures for 193-nanometer wavelength generation require 99.999% purity with sub-0.1 micron particulate filtration. Taiwanese logic foundries and South Korean memory fabs are pulling volumes beyond pre-2022 supply baselines as 7nm and below process nodes expand.
- Neon Lights:Single-atom molecules in sealed glass tubes produce characteristic red-orange emission for commercial signage. Display lighting applications retain volume leadership across the consumption base despite margin compression from LED substitution.
- Advertising Signs:Lower-purity material suffices for outdoor illumination and decorative applications. EPA fugitive gas monitoring requirements apply less stringently than semiconductor handling protocols.
- Neon Tubes:Standardized borosilicate glass enclosures for general lighting installations. Distribution concentrates through wholesale industrial gas channels rather than direct fab supply.
High-Capacity Lasers handles the majority of throughput; Neon Lights is the fastest mover on share.
Application:
Cost tier differentiation separates medical-grade mixtures from commodity display lighting on pricing multiples of three to five times.
- Medical Equipment:Proton beam therapy systems require medical-grade neon mixtures for particle accelerator operation. Cancer treatment facilities in Japan and South Korea are expanding installed base as MFDS and METI coordinate strategic stockpile mandates.
- Display Lighting:Commercial signage and architectural illumination consume standard-purity material through retail and wholesale channels. REACH substance registration in Europe governs import documentation for non-EU supply sources.
- Aerospace Applications:High-altitude lighting and indicator systems specify reliability-grade material with extended service life requirements. Procurement runs through specialized aviation distributors with FAA-compliant handling protocols.
- Optical Devices:Helium-neon laser alignment and metrology equipment demand precise mixture ratios. Solid-state diode substitution is capturing price-sensitive applications that previously consumed lower-grade neon.
Display Lighting captures the widest volume base; Medical Equipment shows the steepest expansion trajectory.
End User:
Customer type determines contract structure, with strategic stockpile mandates creating long-term offtake agreements that spot purchases cannot match.
- Manufacturing:Semiconductor fabrication facilities and industrial laser operators specify sub-ppm impurity thresholds. Air separation unit investments in Texas and Qatar face synchronization risks against Tokyo Electron and ASML tool delivery schedules.
- Healthcare:Hospital proton therapy centers and diagnostic equipment manufacturers require certified medical-grade supply chains. South Korean MFDS inventory holding obligations are creating five-to-seven-year procurement contracts.
- Entertainment:Theaters, casinos, and hospitality venues deploy neon for atmospheric lighting effects. Lower certification burdens permit retail channel distribution without fab-grade documentation.
- Telecommunications:Fiber optic signal amplification and legacy network equipment consume modest neon volumes. Procurement concentrates through direct supply agreements with industrial gas majors.
Manufacturing dominates absolute consumption; Healthcare is climbing the fastest on contract value.
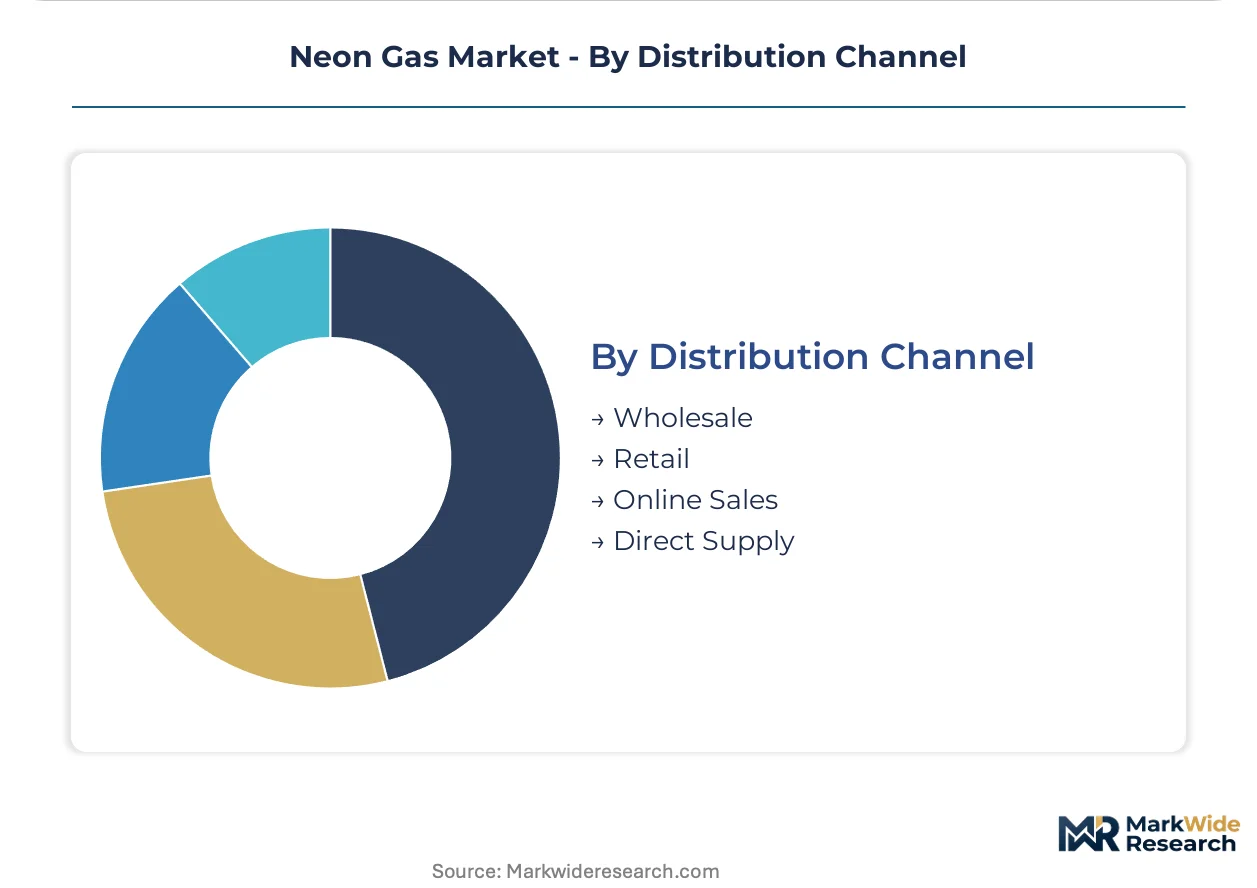
Distribution Channel:
Supply concentration geography dictates channel selection, with lithography-grade material bypassing intermediaries entirely.
- Direct Supply:Semiconductor fabs and medical facilities receive bulk liquid deliveries through dedicated cryogenic transport. Long-term take-or-pay contracts embed minimum volume commitments and price escalation caps.
- Wholesale:Industrial gas distributors serve manufacturing and aerospace accounts with cylinder and bulk tank options. EPA quarterly reporting requirements for fugitive gas monitoring add operational overhead.
- Retail:Small-scale signage contractors and entertainment venues purchase packaged gas through local suppliers. OSHA workplace exposure limits shape handling protocols across US fabrication zones.
- Online Sales:E-commerce platforms facilitate standard-grade cylinder orders for maintenance and replacement applications. Documentation requirements remain minimal compared to semiconductor qualification.
Direct Supply commands the premium tier; Wholesale retains the broadest geographic footprint.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Air separation capacity clusters in three distinct geographies, with new cryogenic distillation investments in Qatar and Texas displacing legacy Eastern European supply channels. Ukrainian production disruption has compressed qualification timelines for semiconductor-grade material. Regulatory stockpile mandates in East Asia are reshaping procurement contract structures.
United States
Texas-based air separation investments target captive supply for domestic wafer fabrication. EPA fugitive gas monitoring requirements under the Clean Air Act shape handling protocols at semiconductor zones in Austin and Phoenix. Linde plc anchors North American supply through cryogenic distillation facilities in the Gulf Coast corridor.
Qatar
Ras Laffan industrial gas infrastructure expansion positions the emirate as a lithography-grade neon export hub. The Qatar Financial Centre Authority facilitates long-term offtake agreements with East Asian device manufacturers. Integrated marine logistics at Ras Laffan Port enable direct bulk liquid delivery to Taiwanese and South Korean fabrication clusters.
South Korea
Memory foundries in Pyeongtaek and Yongin pull high-purity neon volumes for 193-nanometer excimer laser systems. MFDS strategic stockpile mandates create five-to-seven-year procurement contracts with minimum volume commitments. Samsung and SK Hynix operations concentrate demand in the Seoul Capital Area.
Taiwan
Logic chip facilities in Hsinchu and Tainan specify sub-ppm impurity thresholds for EUV and DUV lithography tools. The National Development Council coordinates critical material security policies that influence inventory holding obligations. TSMC's advanced process node expansion drives specification tightening across the supply base.
Germany
Messer Group GmbH leverages captive air separation capacity to sustain wafer-fab contracts without Ukrainian transit exposure. REACH substance registration governs import documentation for non-EU supply sources. Industrial gas infrastructure in the Ruhr region supports purification technology investments for semiconductor-grade material.
Neon Gas Market Vendor Landscape
Concentration sits with diversified industrial gas conglomerates that command cryogenic distillation infrastructure and purification technology portfolios. Three to four operators control lithography-grade supply through integrated air separation and distribution networks. Strategic archetypes span captive production specialists, purification technology leaders, and regional distribution consolidators. Competitive moves center on multi-year qualification protocols with semiconductor fabs and backward integration into atmospheric air extraction.
Among European-based industrial gas operators, Messer Group GmbH exemplifies the captive production archetype through German air separation assets. Air Liquide occupies a position as purification technology leader, while Linde plc anchors the scale-driven tier with North American infrastructure investments. Taiyo Nippon Sanso Corporation represents the East Asian specialist vector serving memory and logic fabrication clusters.
| Leading Market Players |
|---|
| Messer Group GmbH |
| Taiyo Nippon Sanso Corporation |
| Air Liquide |
| Iceblick Ltd |
| Airgas |
| Linde plc |
| Matheson Tri-Gas |
| Axcel Gases |
| Air Products and Chemicals |
| Others |
Supply Flow & Price Mechanics
Air separation unit scale economies in Texas and Qatar determine both supply concentration and price floors for lithography-grade material. Cryogenic distillation facilities with captive atmospheric extraction command three-to-five-fold premiums over advertising-grade neon by eliminating transit exposure and qualification risk.
Pricing Analysis
REACH substance registration dictates the pricing tier structure across European procurement channels. Three-tier pricing separates semiconductor-grade material with sub-ppm impurity specifications from standard-grade display lighting products and economy-tier signage material. Cost compression in the advertising segment intensifies because LED substitution erodes volume leverage. Display lighting buyers exhibit highest price sensitivity; semiconductor fabs accept premium positioning to secure qualification stability.
Supply Chain Analysis
Ras Laffan marine terminal chokepoints underwrite Qatar's emergence as a lithography-grade export hub with integrated bulk liquid logistics. Supply draws from atmospheric air extraction in the United States, Qatar, and Germany as Ukrainian crude neon feedstock exits the channel. Raw material dependencies center on cryogenic energy inputs, borosilicate glass containment, and specialized adsorbent media for purification trains. Single-source vulnerability concentrates at Texas and Qatar commissioning timelines against tool delivery schedules. Distribution runs through direct bulk liquid supply to semiconductor fabs and wholesale cylinder networks for industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Neon supply architecture is undergoing a platform-economics inflection as lithography tool makers standardize impurity specifications across Tokyo Electron and ASML ecosystems. Interoperability between purification technology tiers and qualification protocols is reshaping procurement leverage.
For Market Incumbents: Fortify captive production positions through backward integration into atmospheric air separation at Texas and Ras Laffan facilities. Solid-state diode laser substitution threatens helium-neon metrology volumes; incumbents should anchor long-term offtake agreements with South Korean memory manufacturers before greenfield capacity reaches qualification maturity. For New Entrants and Emerging Players: Differentiate on sub-ppm purification technology leadership for next-generation EUV lithography requirements. Medical-grade proton beam therapy mixtures offer the most penetrable white-space target as cancer treatment facilities expand across Japan and South Korea. A go-to-market angle through South Korean MFDS stockpile mandate compliance de-risks initial volume commitments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors air separation operators with integrated purification capabilities over trading intermediaries. Long-term viability rests on qualification protocol completion and lithography tool synchronization across the projection horizon. The acquisition target archetype is cryogenic engineering specialists with fractional distillation expertise concentrated at legacy Eastern European facilities. Watch air separation unit commissioning delays against ASML and Tokyo Electron delivery schedules as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Atmospheric Air Separation | Captive production eliminates Ukrainian transit exposure and secures semiconductor fab contracts. |
| Sub-ppm Purification Technology Investment | Advanced cryogenic adsorption matches EUV lithography tool specifications from ASML. |
| Long-term Supply Agreement with East Asian Fabs | Five-to-seven-year offtake contracts embed volume commitments and price escalation caps. |
| Qatar Ras Laffan Capacity Expansion | Integrated marine logistics enable direct bulk liquid delivery to Taiwanese foundries. |
| Medical-grade Mixture Certification | Proton beam therapy proliferation in Japan and South Korea opens premium pricing tiers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC filings from industrial gas conglomerates, and air separation unit commissioning announcements. Interviews with cryogenic engineering directors, semiconductor procurement leads at memory and logic fabs, and medical equipment supply chain managers informed demand-side validation. EPA emissions tracking databases and REACH substance registration records provided regulatory constraint inputs. Bottom-up volume modeling triangulated against top-down market sizing from cryogenic distillation capacity announcements.
Segmentation dimensions modeled include purity grade tier, end-use application, distribution channel structure, and regional production hub configuration across the projection horizon. CAGRs derive from regression analysis of lithography tool deployment schedules against air separation unit commissioning timelines. Forecast inputs incorporate excimer laser system installation rates at Taiwanese logic foundries and South Korean memory facilities, plus proton beam therapy center expansion trajectories in East Asian healthcare systems.
Forecasts assume regulatory continuity in EPA emissions tracking and OSHA workplace exposure limits; material policy shifts would require re-modeling. Supply disruption scenarios from Eastern European infrastructure stranded assets or Qatar logistics chokepoints could compress qualification timelines. Practitioners should keep alternative scenarios live as lithography node migration patterns and cryogenic engineering labor availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Noble Gas Market
Industrial Gases
Food-Grade Gases Market
Industrial Gases
US and Canada Helium Gas Market
Industrial Gases
Industrial Gas Regulator Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Middle East Industrial Gas Market
Industrial Gases
3D Printing Gases Market
Industrial Gases
Metal Cutting Gas Market
Industrial Gases
Commercial Hydrogen Market
Industrial Gases
Sulfur Recovery Tail Gas Analyzer Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Global Industrial Nitrogen Generator Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market
Industrial Gases
Industrial Gas Phase Filtration System Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
Welding Gas Market