
 3D Printing Gases Market | 2026-2036
3D Printing Gases Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printing Gases Market Analysis
Specialized gas supply engineering talent is bifurcating the competitive landscape between integrated industrial gas majors and regional specialists. Praxair Inc. leverages its North American cylinder distribution network to lock in aerospace contract renewals. Air Liquide S.A. anchors European medical-grade argon supply through its Antwerp purification hub. Linde plc dominates on-site generation installations for automotive serial production lines in Stuttgart and Wolfsburg.
3D printing gases are high-purity inert and reactive process gases—typically nitrogen, argon, and helium at 99.999% purity—used to create oxygen-deficient build chambers that prevent oxidation during laser powder bed fusion and directed energy deposition. Their primary purpose is to maintain metallurgical integrity across reactive alloys including titanium, aluminum, and cobalt-chrome. Argon commands the largest volume share in aerospace applications due to its universal compatibility with titanium and nickel superalloys, while nitrogen grows fastest in stainless steel automotive serial production where cost sensitivity favors lower-purity process gas. Cylinder delivery still occupies the majority revenue position among delivery modes, though on-site generation is displacing liquid bulk for high-volume automotive and consumer goods manufacturers running continuous build schedules.
EPA emissions tracking and OSHA workplace exposure limits shape US handling and venting protocols for helium and argon recovery systems. REACH registration requirements and the EU Green Deal carbon border adjustments constrain European import purity documentation and lifecycle emissions reporting for gas suppliers. FDA device manufacturing regulations extend into medical additive production, mandating batch-traceable inert gas certificates for implantable titanium builds. Stakeholders must monitor how tightening rare gas export controls from major helium-producing nations reshape long-term argon and nitrogen substitution economics for high-value medical and aerospace contracts.
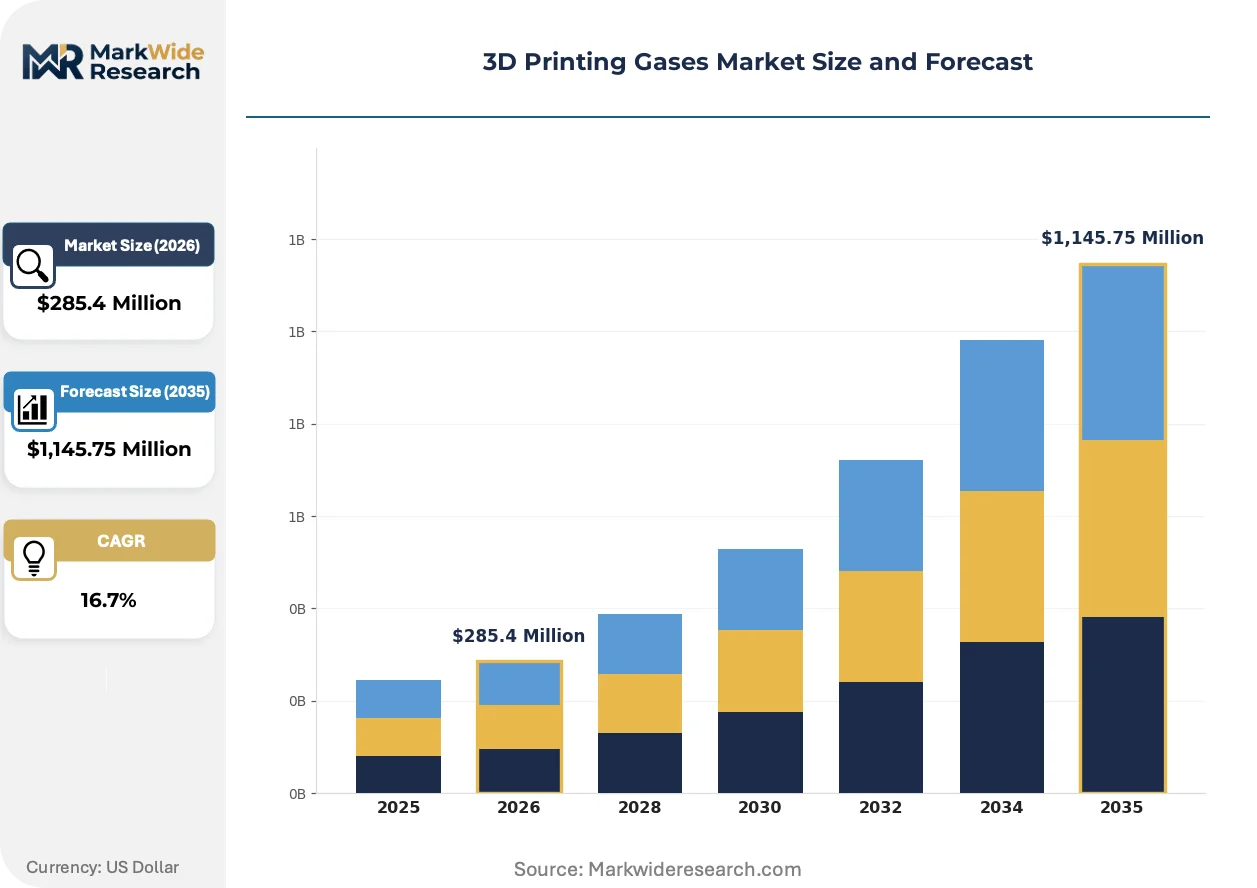
Market Dynamics
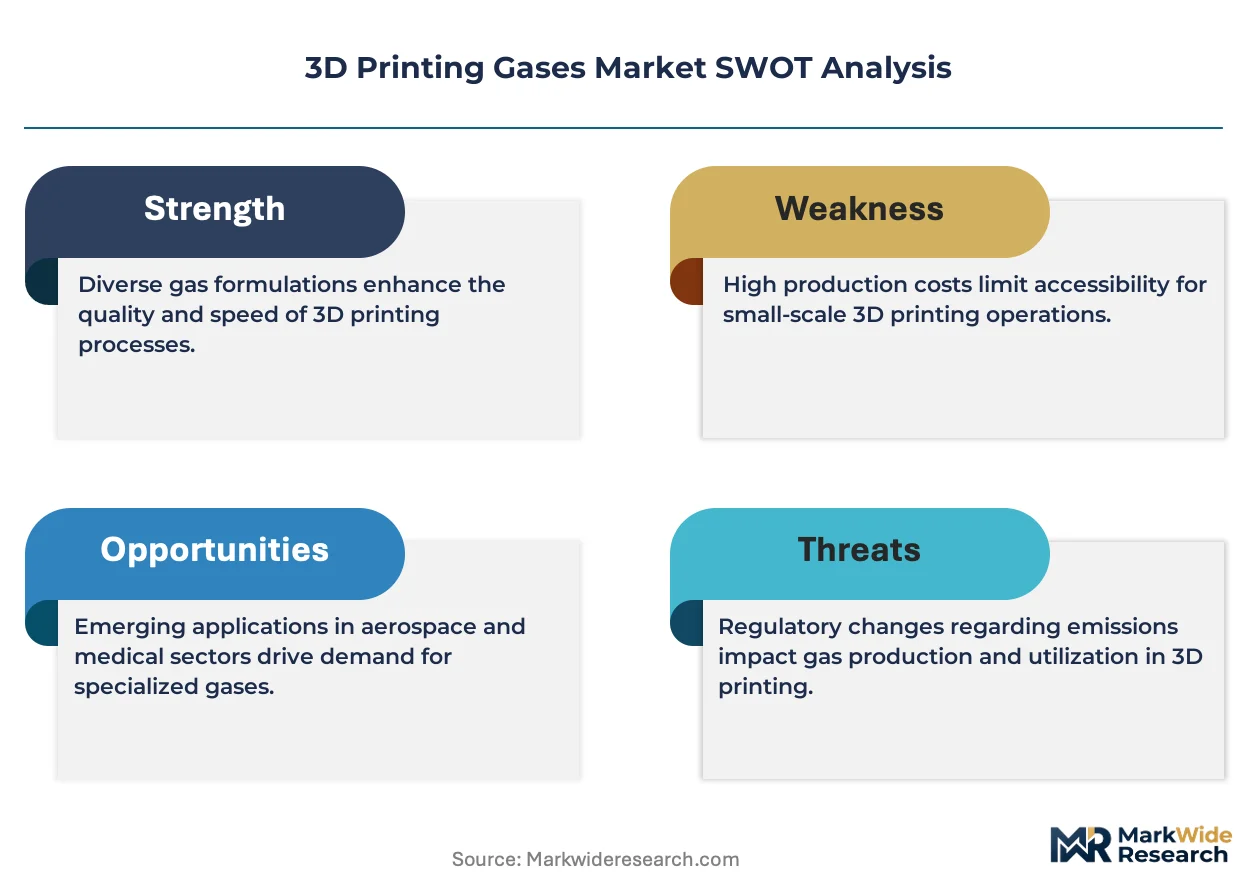
Helium supply concentration and REACH purity mandates are forcing additive manufacturers to redesign chamber gas recovery systems and dual-source argon contracts. Aerospace serial production schedules now depend on securing multi-year inert gas supply agreements before build-line commissioning.
Growth Catalysts
- Titanium aerospace builds:OEMs in Germany and the US are expanding laser powder bed fusion capacity for engine components, pulling high-purity argon through long-term cylinder contracts and on-site generation installations.
- REACH batch-traceability mandates:EU Green Deal carbon border adjustments now require lifecycle emissions documentation for imported process gases, privileging European purification hubs with existing certification infrastructure.
- Automotive stainless steel serial production:Nitrogen consumption is accelerating at Volkswagen's Wolfsburg and Porsche's Leipzig facilities where cost-per-part targets favor lower-purity process gas over argon.
Market Restraints
- Helium feedstock volatility:US Bureau of Land Management reserve depletion and Qatar export quotas are compressing availability for directed energy deposition applications requiring high thermal conductivity.
- Argon supply concentration:European merchant gas production clusters around Antwerp and northern France, creating single-point vulnerability for medical implant manufacturers requiring 99.999% purity certificates.
- On-site generation capex barriers:Cryogenic air separation units require 18-24 month installation timelines and €2-4 million capital commitments, freezing out mid-volume job shops.
Strategic Opportunities
- India defense additive manufacturing:DRDO titanium component programs and private aerospace contractors in Hyderabad and Bangalore lack established inert gas infrastructure, opening cylinder distribution partnerships.
- FDA device manufacturing traceability:Batch-certificated argon for spinal and cranial implants commands 40-60% price premiums over industrial grade, creating margin expansion for medical-grade purification investments.
- Helium recovery system integration:Closed-loop gas recycling technology is decomposing traditional vent-and-replace consumption models at NASA and ESA contractor facilities.
Industry Challenges
- Cryogenic engineering talent scarcity:Design and commissioning of on-site nitrogen generation systems requires specialized expertise concentrated at Linde, Air Liquide, and a handful of regional specialists.
- Multi-agency compliance timelines:FDA device manufacturing regulations, EPA emissions tracking, and OSHA workplace exposure limits impose overlapping certification requirements that extend contract negotiation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printing Gases Market |
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,145.75 Million |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Gas Type: Nitrogen, Argon, Carbon Dioxide, Helium Application: Aerospace, Automotive, Medical, Consumer Goods End User: Manufacturers, Research Institutions, Service Bureau, Education Delivery Mode: Cylinders, Liquid Supply, On-site Generation, Bulk Supply |
| Companies Covered | Praxair Inc., Airgas Inc., Linde plc, Matheson Tri-Gas Inc., Iwatani Corporation, Air Liquide S.A., BASF SE, Messer Group, Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printing Gases Market Emerging Trajectories
Membrane and pressure-swing adsorption technologies are fragmenting the traditional liquid-bulk-to-cylinder distribution hierarchy. Gas suppliers now compete on recovery-system integration rather than purity alone.
Closed-loop argon recycling using cryogenic distillation and getter-bed purification is decomposing the linear consumption model that treated process gas as disposable input. Boeing, Airbus tier-1 suppliers, and medical implant manufacturers in Switzerland and Germany are piloting these systems to hedge against supply interruptions. The technology is compressing effective per-unit gas costs by 30-50% over five-year operational horizons while locking customers into maintenance-intensive equipment relationships.
EU F-Gas Regulation phase-down schedules and REACH registration requirements are tightening documentation burdens for non-EU gas suppliers. Industrial gas majors with existing Antwerp and Rotterdam purification assets are leveraging compliance infrastructure as competitive moats against US and Middle Eastern import competition. Medical additive manufacturing in Ireland and Switzerland faces the steepest certification ramps as notified bodies apply MDR traceability standards to implantable titanium builds.
Procurement teams at automotive OEMs are consolidating cylinder contracts into multi-site framework agreements with price-volume bands indexed to argon and nitrogen commodity benchmarks. Tier-1 suppliers in Stuttgart and Munich report 12-18 month contract cycles replacing spot purchasing, with gas suppliers embedding field engineers at customer sites to optimize consumption rates. This concentration of buying power is visible most acutely in Germany's dense additive manufacturing ecosystem around Düsseldorf and Munich industrial gas clusters.
3D Printing Gases Market Segmentation
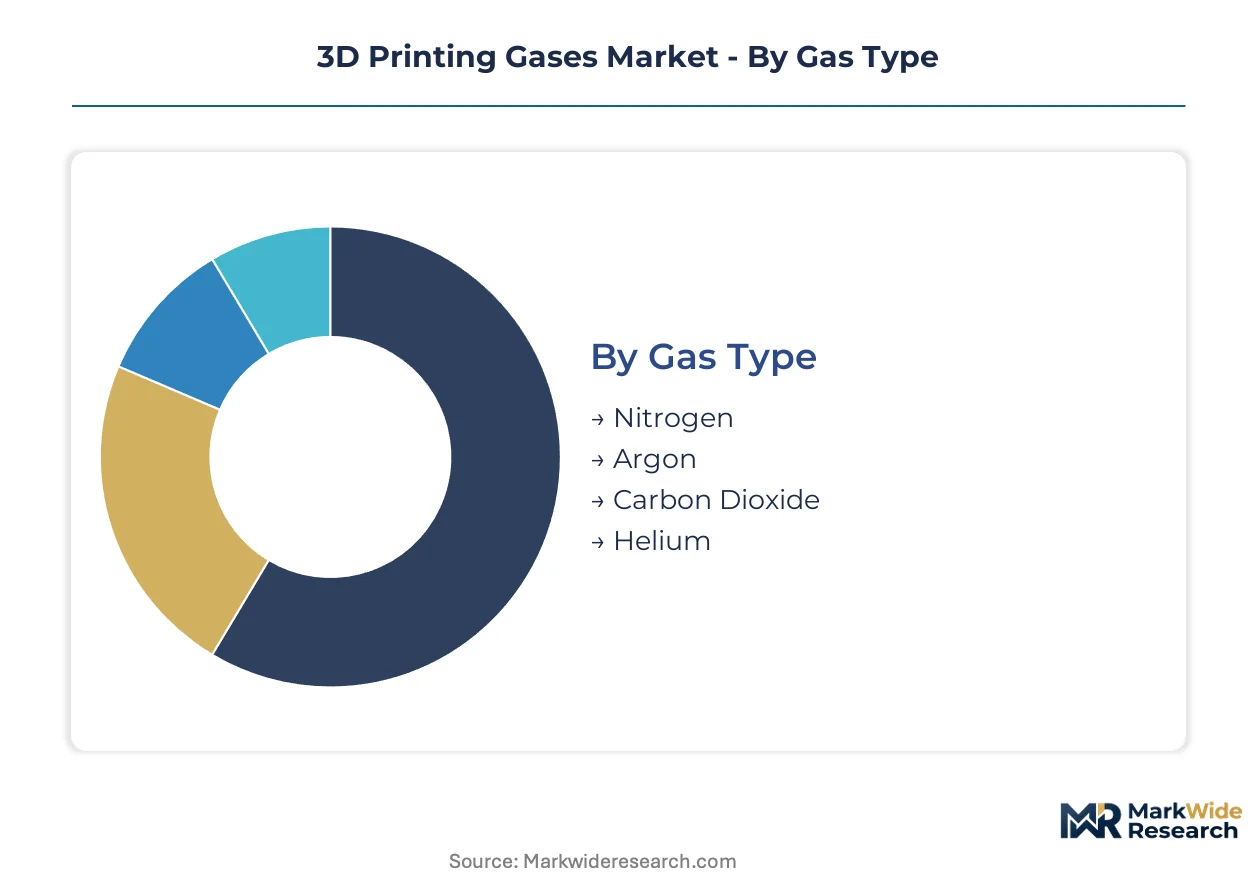
Gas type selection determines metallurgical outcomes and cost structures across additive manufacturing workflows. Delivery mode choices reflect capital availability and production scale. Application and end-user segmentation reveals where purity premiums command pricing power.
Gas Type:
Substitution pressure runs highest among inert gases serving titanium builds, where argon faces nitrogen incursion in cost-sensitive stainless steel applications.
- Argon:Delivers 99.999% purity with universal compatibility across titanium and nickel superalloy laser powder bed fusion. Aerospace component manufacturers in Germany and the US anchor demand through long-term cylinder contracts and on-site generation installations at serial production facilities.
- Nitrogen:Operates at lower purity thresholds sufficient for stainless steel and aluminum builds. Volkswagen's Wolfsburg and Porsche's Leipzig facilities favor nitrogen for automotive serial production where cost-per-part targets override metallurgical margin requirements.
- Helium:Provides thermal conductivity for directed energy deposition of copper and refractory metals. Supply concentration from Qatar and US Bureau of Land Management reserve depletion compresses availability for high-heat-dissipation applications.
- Carbon Dioxide:Serves reactive metal processing and specialty alloy conditioning where controlled oxidation profiles are required. Limited adoption outside research-scale directed energy deposition systems.
Argon anchors the volume base while nitrogen gains share at the steepest rate.
Application:
Cost tier differentiation separates aerospace certification premiums from automotive cost-down imperatives.
- Aerospace:Mandates 99.999% argon for titanium engine components and structural brackets. Boeing and Airbus tier-1 suppliers in Germany and Switzerland pilot closed-loop recovery systems to hedge supply interruptions.
- Automotive:Runs nitrogen-dominant workflows for stainless steel brackets and aluminum housings. Serial production lines in Stuttgart and Wolfsburg consolidate multi-site cylinder contracts with commodity-indexed pricing bands.
- Medical:Requires batch-traceable argon certificates under FDA device manufacturing regulations for spinal and cranial titanium implants. Swiss and Irish manufacturers face steepest MDR traceability certification ramps.
- Consumer Goods:Absorbs lowest-purity nitrogen for polymer conditioning and decorative metal prototyping. Price sensitivity favors spot purchasing over long-term supply agreements.
Aerospace commands the highest purity premiums while automotive expands most quickly.
End User:
Customer type determines contract structure complexity and field engineering intensity.
- Manufacturers:Dominate volume through on-site generation installations and multi-year framework agreements. Gas suppliers embed field engineers at Stuttgart and Munich sites to optimize consumption rates.
- Service Bureau:Relies on cylinder delivery for job-shop flexibility across mixed alloy portfolios. Mid-volume operators face cryogenic air separation capex barriers of €2-4 million.
- Research Institutions:Purchases small-batch helium and specialty blends for directed energy deposition experimentation. NASA and ESA contractor facilities pilot closed-loop recycling technology.
- Education:Consumes lowest-purity nitrogen for training systems and undergraduate prototyping programs. Budget constraints favor basic cylinder rental arrangements.
Manufacturers anchor contract value while service bureaus generate the highest transaction frequency.
Delivery Mode:
Supply concentration shapes competitive positioning between liquid-bulk majors and membrane technology entrants.
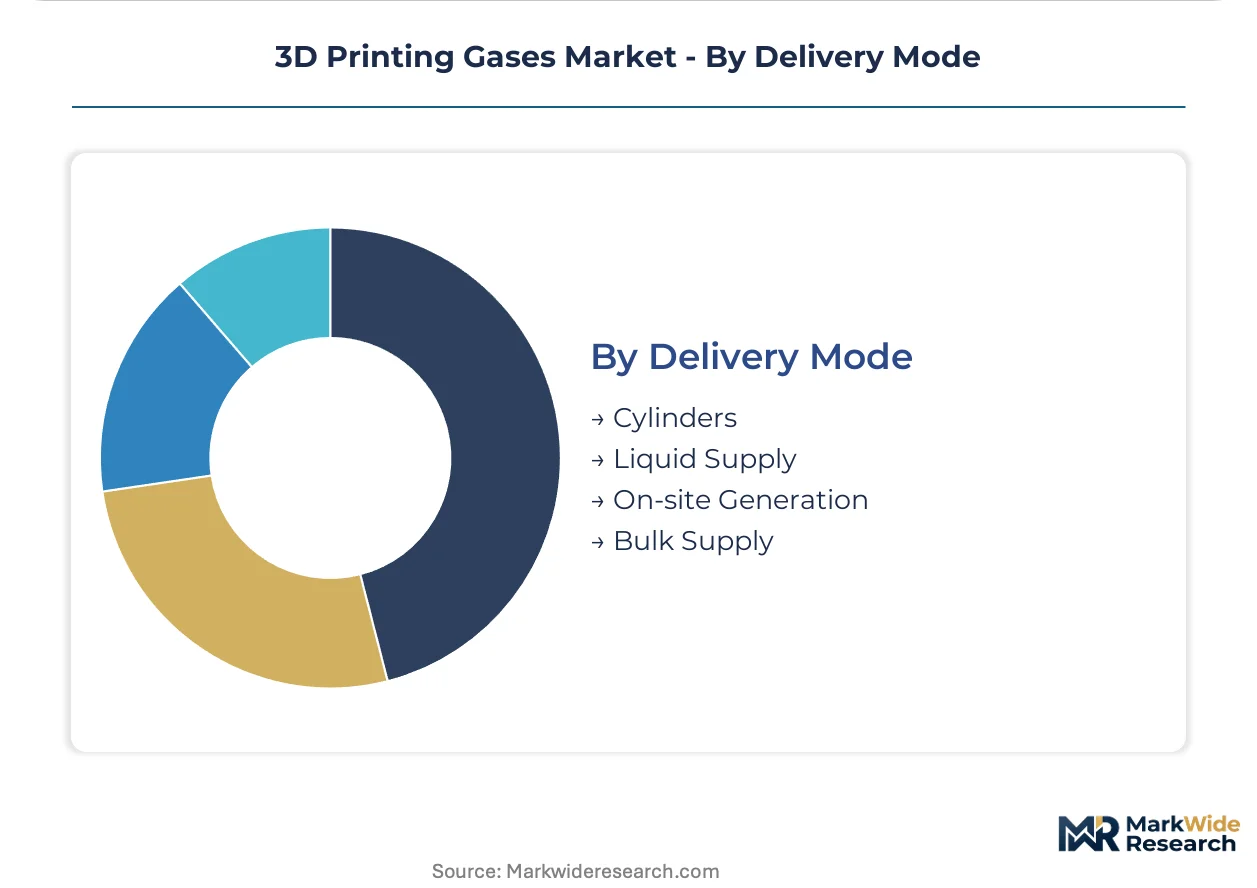
- Cylinders:Retains majority revenue position through distributed aerospace and medical contracts. Praxair leverages North American distribution networks for renewal lock-in.
- On-site Generation:Displaces liquid bulk for automotive and consumer goods manufacturers running continuous build schedules. Linde dominates installations at Stuttgart and Wolfsburg production lines.
- Liquid Supply:Serves mid-volume manufacturers lacking cryogenic engineering talent for air separation unit commissioning. Air Liquide anchors European medical-grade supply through Antwerp purification.
- Bulk Supply:Concentrates among integrated steel and chemical complexes with existing cryogenic infrastructure. Limited penetration in standalone additive manufacturing facilities.
Cylinder delivery maintains the broadest installed base while on-site generation climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany consumes argon at purity levels unmatched elsewhere, while the United States balances aerospace-grade certification against automotive cost-down pressures. India and China run nitrogen-dominant workflows for stainless steel builds where metallurgical margins permit lower-grade process gas.
United States
Aerospace OEMs in California and Washington State anchor argon consumption for titanium engine component builds. EPA emissions tracking and OSHA workplace exposure limits shape venting protocols for helium recovery systems at NASA contractor facilities. Houston industrial gas clusters support directed energy deposition programs for copper and refractory metal applications.
Germany
Automotive serial production lines in Stuttgart and Wolfsburg displace argon with nitrogen for stainless steel brackets where cost-per-part targets dominate. REACH batch-traceability mandates and EU Green Deal carbon border adjustments privilege domestic purification hubs with existing certification infrastructure. Düsseldorf and Munich industrial gas clusters embed field engineers at additive manufacturing sites to optimize consumption rates.
China
Domestic laser powder bed fusion capacity for titanium aerospace components pulls high-purity argon through long-term supply agreements. National standards under MIIT and dual carbon goals constrain import documentation for process gas suppliers. Yangtze River Delta manufacturing bases concentrate membrane nitrogen generation for automotive aluminum housing production.
India
DRDO titanium component programs and private aerospace contractors in Hyderabad and Bangalore lack established inert gas infrastructure, opening cylinder distribution partnerships. BIS certification requirements and PLI scheme incentives for defense manufacturing shape procurement timelines. Maharashtra industrial corridors attract on-site generation investments for stainless steel automotive prototyping.
Switzerland
Medical implant manufacturers in Zurich and Basel face steep MDR traceability certification ramps for batch-certificated argon used in spinal and cranial titanium builds. Swissmedic oversight extends FDA device manufacturing standards into European notified body frameworks. Swiss purification assets leverage EU F-Gas Regulation compliance infrastructure as competitive moats against non-European import competition.
3D Printing Gases Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with industrial gas majors controlling purification infrastructure and regional players capturing cylinder distribution niches. The upper tier commands on-site generation installations through captive cryogenic engineering talent. Three archetypes define competitive positioning: integrated industrial gas conglomerates with transcontinental purification hubs, regional cylinder specialists with dense last-mile networks, and membrane technology entrants fragmenting traditional liquid-bulk hierarchies. Dominant moves include backward integration into air separation assets and geographic expansion through framework agreements embedding field engineers at customer sites.
Within the integrated tier, Linde plc and Air Liquide S.A. occupy positions anchored by European purification infrastructure and North American distribution density. Praxair Inc. exemplifies the regional cylinder specialist archetype through renewal-focused contract structures. Messer Group represents mid-cap European players competing on medical-grade certification proximity. These three sit within a structure where purification asset ownership determines pricing power and field engineering intensity locks in multi-year automotive and aerospace agreements.
| Leading Market Players |
|---|
| Praxair Inc. |
| Airgas Inc. |
| Linde plc |
| Matheson Tri-Gas Inc. |
| Iwatani Corporation |
| Air Liquide S.A. |
| BASF SE |
| Messer Group |
| Air Products and Chemicals, Inc. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements with take-or-pay clauses lock in argon supply access for aerospace manufacturers while freezing price visibility across multi-year build schedules, embedding cost predictability into titanium component programs in Germany and the United States.
Pricing Analysis
Contract-based long-term offtake structures dominate aerospace and medical additive manufacturing, with price differentiation driven by certification grade (FDA batch-traceable versus industrial-grade argon) and volume scale. Cost compression in automotive nitrogen tiers intensifies as Volkswagen and Porsche consolidate multi-site framework agreements with commodity-indexed pricing bands. Service bureaus running mixed-alloy job shops exhibit the highest price sensitivity due to spot purchasing exposure, while medical implant manufacturers absorb 40-60% premiums for certificated argon without volume elasticity.
Supply Chain Analysis
Strategic stockpiling of liquid argon prevails among German and Swiss medical implant manufacturers hedging against Antwerp purification hub concentration, while just-in-time cylinder delivery serves automotive prototyping lines in Stuttgart and Wolfsburg. Feedstock draws from Qatar helium reserves, US Bureau of Land Management depletion schedules, and European air separation clusters around northern France and Belgium. Single-source vulnerability concentrates in 99.999% purity argon for titanium builds, with tariff exposure rising on rare gas export controls from major producing nations. Distribution runs through embedded field engineers at customer sites, locking in consumption optimization and maintenance-intensive equipment relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop gas recovery systems are transforming 3D printing gases from consumable inputs into platform-mediated equipment relationships, creating interoperability lock-in between purification technology vendors and aerospace tier-1 suppliers.
For Market Incumbents: Secure multi-year argon supply agreements with DRDO contractors in Hyderabad and Bangalore before indigenous purification infrastructure matures. Anchor backward integration into membrane nitrogen generation for automotive serial production lines facing cost-per-part compression. Cryogenic engineering talent scarcity at regional specialists threatens on-site generation margins if Linde and Air Liquide accelerate field engineer embedding programs. For New Entrants and Emerging Players: Differentiate on helium recovery system integration for NASA and ESA contractor facilities where closed-loop recycling decomposes traditional vent-and-replace models. Target cylinder distribution partnerships in Indian defense additive manufacturing where established inert gas infrastructure remains absent. Penetrate through FDA batch-traceability certification services for spinal and cranial implant manufacturers facing MDR compliance ramps. For Investors and Strategic Acquirers: Regional cylinder specialists with dense last-mile networks in underpenetrated aerospace clusters represent the most defensible acquisition archetype as purification asset ownership concentrates pricing power among integrated majors. Long-term viability hinges on membrane technology entrants fragmenting liquid-bulk hierarchies versus cryogenic air separation incumbents defending installed base. Watch for helium export quota tightening from Qatar and US reserve depletion as the inflection signal forcing argon substitution economics and recovery system capex acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Air Separation Assets | Captive argon purification at Antwerp and Rotterdam hubs locks in REACH batch-traceability compliance infrastructure. |
| Long-term Supply Agreement | Multi-year offtake contracts with Boeing and Airbus tier-1 suppliers hedge against Qatar helium export quota compression. |
| Joint Venture | Cylinder distribution partnerships in Hyderabad and Bangalore exploit DRDO titanium component program demand without indigenous infrastructure. |
| Technology Licensing | Closed-loop recovery system patents decompose linear consumption models at NASA contractor facilities. |
| Geographic Expansion | Field engineer embedding in Stuttgart and Munich optimizes nitrogen consumption rates for Volkswagen serial production lines. |
Methodological Framework
Desk research of SEC filings from industrial gas majors, EU ECHA REACH registration databases, and FDA device manufacturing guidance documents preceded structured interviews with cryogenic engineering directors, aerospace procurement leads at tier-1 suppliers, medical implant quality assurance managers, and automotive additive manufacturing operations heads. Primary fieldwork validated purity threshold requirements across titanium and nickel superalloy builds, while secondary triangulation against customs trade data and air separation unit installation records anchored supply concentration assumptions. Bottom-up segmentation modeling across gas type, delivery mode, and end-user category was cross-checked against top-down industrial gas revenue disclosures.
Variance decomposition across the projection horizon isolates volume drivers (aerospace build rate expansion, automotive serial production adoption) from price drivers (commodity argon benchmarks, certification premium persistence). Segmentation dimensions modeled include gas purity tier, delivery mode capital intensity, application metallurgical requirements, and regional regulatory cluster. CAGRs were derived from build-out schedules at identified laser powder bed fusion facilities and nitrogen consumption trajectories at named automotive OEM lines. Industry-specific inputs incorporate helium reserve depletion curves and EU F-Gas Regulation phase-down compliance timelines.
Forecasts assume regulatory continuity in REACH batch-traceability mandates, FDA device manufacturing standards, and EPA emissions tracking protocols; material policy shifts would require re-modeling of certification infrastructure investments and venting protocol compliance costs. Revision becomes warranted when Qatar helium export quotas or US Bureau of Land Management reserve auctions cross thresholds that accelerate argon substitution economics beyond modeled elasticity bands.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Helium Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Europe Specialty Gas Market
Industrial Gases
Nitrogen Generator Market
Industrial Gases
Gas Purifiers Market
Industrial Gases
North America Industrial Gases Market
Industrial Gases
Oxygen Market
Industrial Gases
Global Syngas and Derivatives Market
Industrial Gases
Asia-Pacific Industrial Gases Market
Industrial Gases
LAMEA Industrial Nitrogen Market
Industrial Gases
Global Nitrogen Market
Industrial Gases
Argon Gas Market
Industrial Gases
Global Liquid Nitrogen Market
Industrial Gases
Acetylene Gas Market
Industrial Gases
Neon Gas Market
Industrial Gases
Global Food-Grade Industrial Gases Market