
 Global Specialty Gas Market | 2026-2036
Global Specialty Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Global Specialty Gas Market Intelligence
The European Union's REACH regulation, governing chemical substance registration and evaluation, is hardening the purity verification and supply chain documentation requirements for specialty gas producers. Global suppliers like Air Liquide leverage extensive R&D capabilities to meet these evolving compliance standards across multiple jurisdictions. Linde plc sustains its market position through a vast global distribution network, while Taiyo Nippon Sanso Corporation specializes in electronic gases for the Asian semiconductor industry.
Specialty gases are gaseous materials of high purity, often exceeding 99.999% (Grade 5.0), which are either pure gases or precisely blended mixtures. They serve critical functions as process inputs, analytical standards, or controlled atmospheres in high-technology applications where contaminants can cause device failure. Electronic gases for semiconductor manufacturing represent the highest-margin product category, driven by extreme purity demands for advanced lithography. Medical gases, used in healthcare diagnostics and therapies, constitute a mature and stable demand segment with stringent quality control mandated by pharmacopeias.
Regulatory frameworks from the U.S. Environmental Protection Agency (EPA) and China's Ministry of Ecology and Environment (MEE) govern the handling and emission of certain fluorine-containing specialty gases. In parallel, compliance with the European Chemicals Agency (ECHA) standards for substance identification is mandatory for market access into the European Union. Producers must now decide whether to invest in captive purification technologies or rely on third-party suppliers to meet next-generation purity requirements for advanced manufacturing.
Market Dynamics
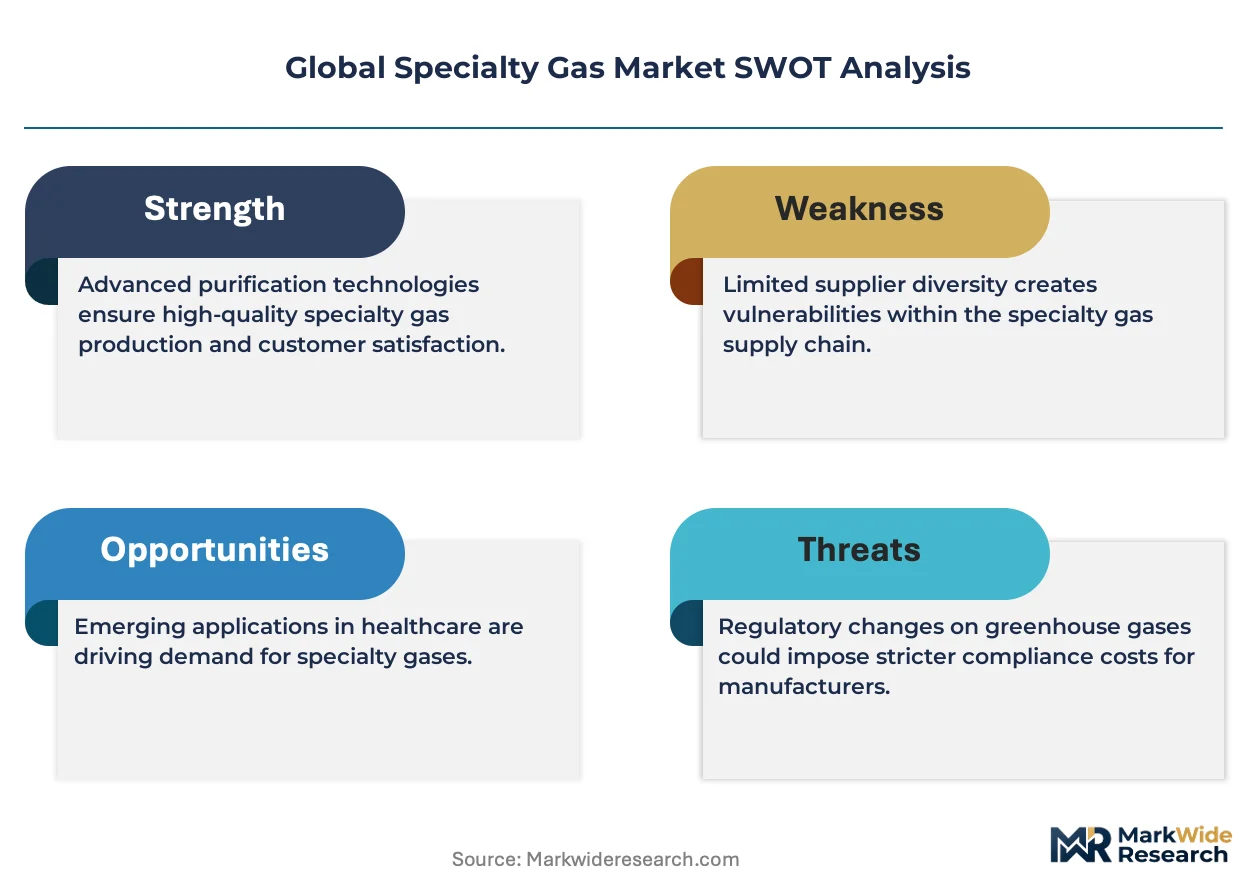
The specialty gas market's structure is defined by the tension between escalating purity demands from advanced manufacturing sectors and a tightening global regulatory environment that increases the cost and complexity of supply chain verification and documentation.
Growth Catalysts
- Advanced Semiconductor Fabrication:The push toward sub-10 nanometer chip production necessitates gases of extreme purity, creating non-discretionary demand from the electronics industry.
- Medical Gas Regulation:Increasingly stringent quality mandates for medical gases, governed by pharmacopeias, ensure stable consumption in healthcare for diagnostics and therapies.
- South Korean Fab Expansion:The concentration of new semiconductor fabrication plants in South Korea establishes a large, centralized consumption base for electronic gases.
Market Restraints
- Energy-Intensive Purification:Cryogenic distillation is extremely energy-intensive, exposing producers to significant cost volatility from fluctuating global electricity and natural gas prices.
- EU REACH Compliance:The European Union's REACH regulation adds substantial administrative and testing costs for producers seeking market access, requiring extensive documentation.
- Raw Material Bottlenecks:The supply of certain raw materials, like neon and xenon, is concentrated in a few geographic regions, creating significant price and availability risks.
Strategic Opportunities
- Gas Recycling Services:Offering recovery and recycling for high-value gases like xenon meets corporate sustainability goals and creates a service revenue stream.
- Quantum Computing Markets:The quantum computing sector requires ultra-pure gases for cryogenic cooling, opening a new high-margin application segment.
- On-Site Generation Systems:Expanding on-site generation technologies for nitrogen and oxygen reduces customer reliance on bulk liquid distribution and associated logistics.
Industry Challenges
- High Capital Requirements:Building new air separation units and purification plants requires immense capital, creating high barriers for new entrants and capacity expansion.
- Specialized Talent Gap:A shortage of technicians skilled in cryogenic operations and trace-level analytical methods creates operational bottlenecks for gas producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Specialty Gas Market |
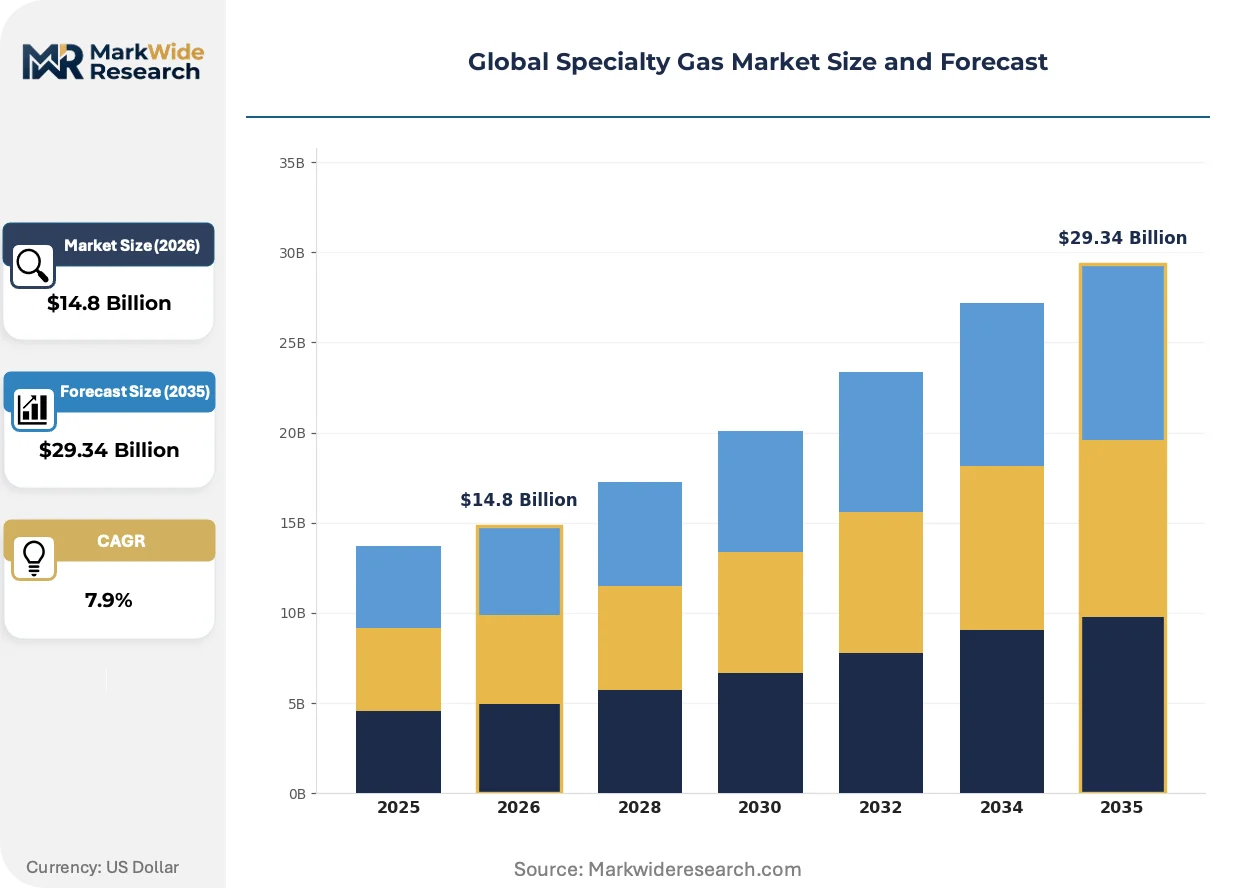
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $29.34 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rare Gases, Medical Gases, Electronic Gases, High-Purity Gases, Calibration Gases Application: Laboratory Analysis, Semiconductor Manufacturing, Food Processing, Healthcare Diagnostics, Environmental Monitoring Industry Vertical: Chemical Processing, Pharmaceutical Manufacturing, Electronics Fabrication, Aerospace Engineering, Research Institutions Packaging Type: Compressed Cylinders, Cryogenic Tanks, Tube Trailers, Microbulk Containers, Dewar Flasks |
| Companies Covered | Air Liquide, Linde plc, Air Products and Chemicals Inc., Messer SE & Co. KGaA, Taiyo Nippon Sanso Corporation, BASF SE, Iwatani Corporation, Matheson Tri-Gas Inc., Coregas Pty Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Specialty Gas Market Strategic Shifts & Innovations
A fundamental shift toward localized, on-demand supply is challenging the traditional centralized production and bulk distribution model. This evolution is driven by customer needs for greater process control, supply chain resilience, and cost optimization.
On-site gas generation systems provide end-users with a dedicated supply of gases like nitrogen or hydrogen. Semiconductor fabs and hospitals are early adopters, seeking to improve supply reliability and reduce logistical complexity. This technology is decentralizing the supply chain, shifting control from bulk suppliers to the point of consumption and reducing dependence on liquid gas transportation.
The European Union's F-Gas Regulation is actively phasing down the use of certain fluorinated gases with high global warming potential. This directly impacts the semiconductor industry, which uses these gases for critical etching and chamber cleaning processes. Consequently, gas producers are accelerating research and development into low-GWP alternative molecules to ensure compliance and maintain market access in Europe.
Customers are moving away from transactional purchases toward comprehensive gas management agreements that bundle supply, monitoring, and on-site services. This model displaces the simple sale of gas cylinders or bulk liquids with a more integrated, service-oriented relationship. This shift is most prominent within the electronics sector in Taiwan and South Korea, where supply continuity is paramount.
Global Specialty Gas Market Segmentation
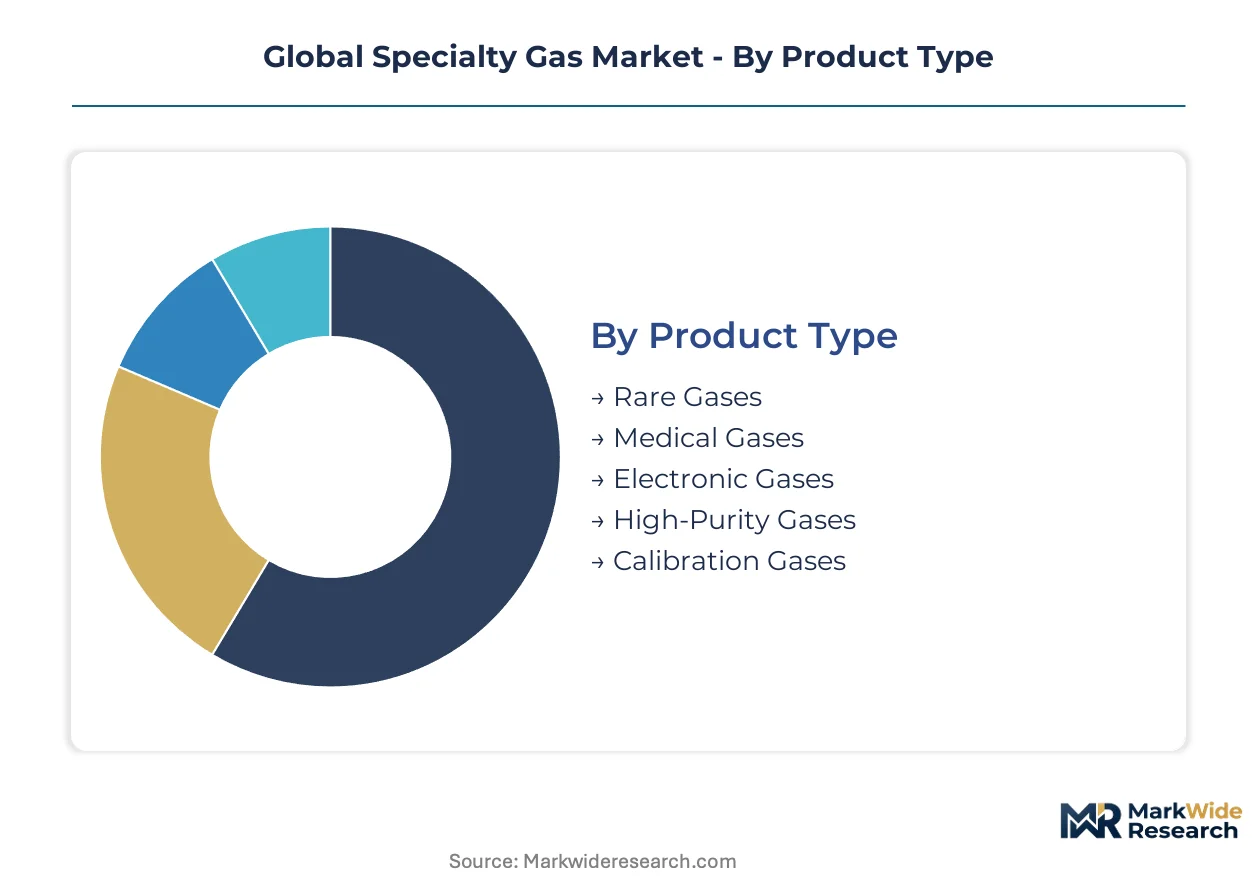
The global specialty gas market is fundamentally segmented by the distinct purity levels and application requirements demanded across various end-use sectors. Manufacturers tailor their offerings to meet precise specifications for process inputs, analytical standards, and controlled atmospheres. This granular breakdown reveals the specific drivers and challenges influencing supply and demand dynamics.
Product Type:
The classification of specialty gases by product type focuses on their chemical composition and purity grade, directly impacting their suitability for advanced technological processes.
- Electronic Gases:These ultra-high purity gases, often exceeding Grade 7.0, are critical for semiconductor manufacturing processes like etching and deposition. Demand concentrates in South Korea and Taiwan, driven by sub-10 nanometer chip fabrication requirements.
- Medical Gases:These gases adhere to stringent pharmacopeia standards for purity and composition, used in patient care, diagnostics, and surgical procedures. Stable consumption in healthcare facilities across Europe and North America persists.
- Rare Gases:This category includes neon, xenon, and krypton, essential for specialized applications like excimer lasers.
- High-Purity Gases:These gases, typically from 99.99% to 99.999% purity, serve as process inputs across diverse industrial applications.
- Calibration Gases:Precisely blended mixtures of known concentrations, these gases are vital for calibrating analytical instruments in environmental monitoring.
Mature deployment sits with Medical Gases. Newer deployment is concentrated in Electronic Gases.
Application:
Market segmentation by application highlights the diverse functional roles specialty gases perform across high-technology and critical infrastructure sectors.
- Semiconductor Manufacturing:This application demands extreme purity gases for photolithography, etching, and chamber cleaning in advanced chip production. The push toward sub-10 nanometer processes in South Korea creates non-discretionary demand.
- Healthcare Diagnostics:Specialty gases are integral to medical imaging, laboratory testing, and therapeutic gas mixtures. Regulatory mandates from the European Medicines Agency ensure stable consumption for patient safety.
- Laboratory Analysis:Gases like carrier gases are essential for chromatography, spectroscopy, and other analytical techniques in research institutions.
- Food Processing:Modified atmosphere packaging and cryogenic freezing utilize specialty gases to extend shelf life and maintain product quality.
- Environmental Monitoring:Calibration gas mixtures are critical for monitoring air quality, emissions, and industrial pollutants, adhering to EPA standards.
Semiconductor Manufacturing represents the fastest-growing trajectory. Healthcare Diagnostics provides a stable foundation for consumption.
Industry Vertical:
The industry vertical segmentation reflects how specific sector demands, regulations, and operational scales influence specialty gas procurement and usage patterns.
- Electronics Fabrication:This vertical is a primary consumer of electronic gases for producing integrated circuits, displays, and solar cells. Rapid technological advancement drives continuous demand for higher purity and new gas formulations.
- Pharmaceutical Manufacturing:Specialty gases maintain sterile environments, facilitate chemical synthesis, and support quality control in drug production. Strict adherence to pharmacopeia standards is mandatory for market entry.
- Chemical Processing:Inert atmospheres, reaction facilitators, and calibration standards are supplied to chemical plants for various synthesis processes.
- Aerospace Engineering:High-purity gases are used for welding, purging, and material testing in the manufacturing of aircraft components.
- Research Institutions:Universities and private laboratories utilize a broad range of specialty gases for experimental setups and analytical equipment.
Electronics Fabrication imposes the highest purity demands. Pharmaceutical Manufacturing faces significant regulatory oversight.
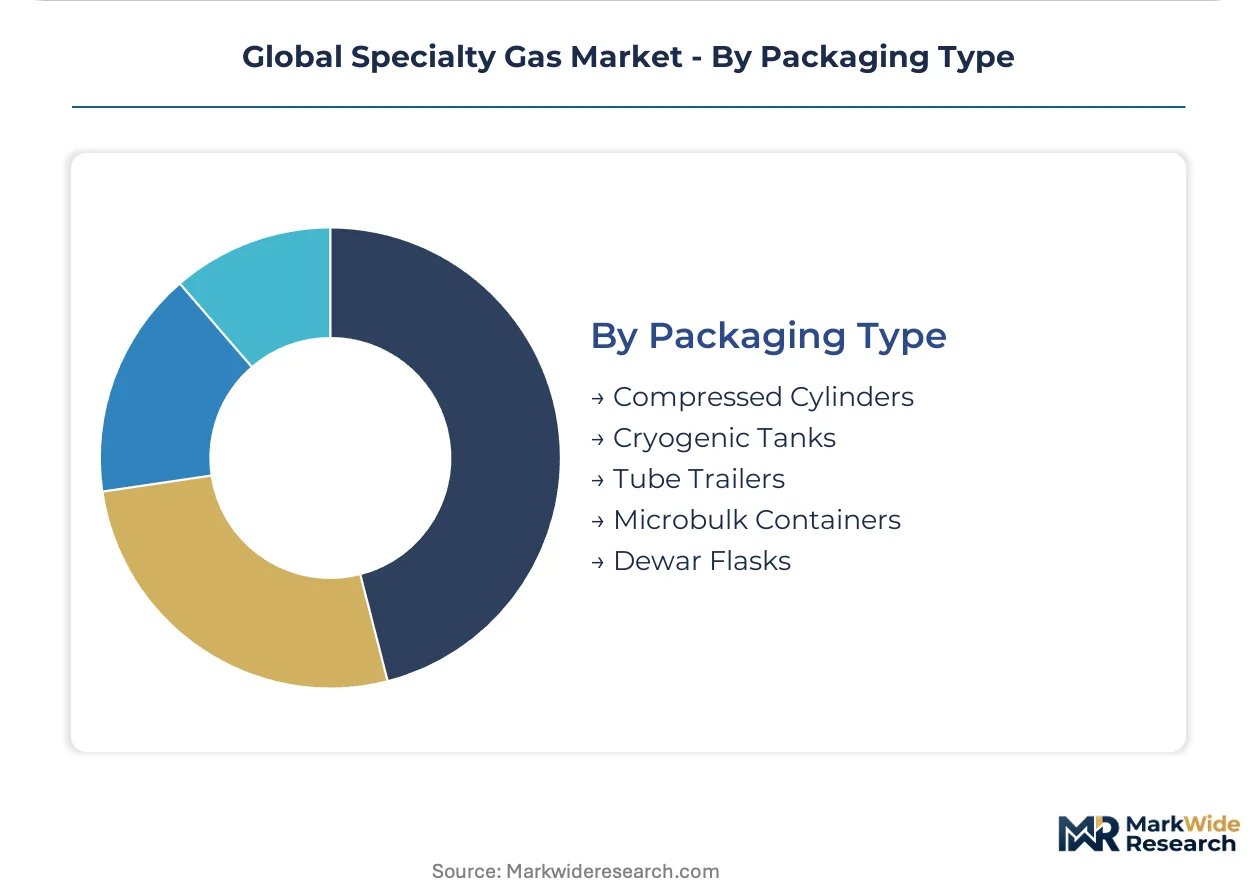
Packaging Type:
Segmentation by packaging type addresses the logistical and volume requirements for delivering specialty gases to diverse customer sites.
- Compressed Cylinders:These portable containers, ranging from small laboratory cylinders to larger industrial sizes, are widely used for lower-volume specialty gas delivery. They provide flexibility for various end-user applications.
- Cryogenic Tanks:Large, insulated tanks store gases in liquid form at extremely low temperatures, providing high-volume supply for major industrial consumers. This method is common for bulk nitrogen and oxygen delivery.
- Tube Trailers:High-pressure gas containers mounted on trailers transport large volumes of gaseous products over long distances.
- Microbulk Containers:These intermediate-sized tanks bridge the gap between cylinders and bulk cryogenic tanks, offering a cost-effective solution.
- Dewar Flasks:Specialized vacuum-insulated containers store small quantities of cryogenic liquids, such as liquid helium for quantum computing research.
Compressed Cylinders offer broad accessibility. Cryogenic Tanks provide the highest volume delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones like those in South Korea's Gyeonggi Province drive significant demand for specialty gases, particularly for advanced semiconductor fabrication. These areas benefit from government incentives, attracting major electronics manufacturers. This concentration fosters a localized ecosystem requiring ultra-pure process inputs.
South Korea
South Korea's push towards sub-10 nanometer chip production fuels extreme purity gas demand. The Ministry of Trade, Industry and Energy (MOTIE) supports domestic supply chain resilience. Semiconductor fabs in Gyeonggi Province, including Pyeongtaek, continuously expand, increasing electronic gas consumption.
United States
The United States requires high-purity gases for advanced semiconductor R&D and expanding healthcare diagnostics. EPA regulations govern fluorine-containing specialty gas emissions, influencing industrial practices. Major chip manufacturing investments in Arizona are creating new localized demand centers for electronic gases.
Germany
Germany's robust pharmaceutical and chemical sectors generate stable demand for high-purity and calibration gases. The European Union's REACH regulation mandates stringent purity verification. Industrial clusters in Bavaria and North Rhine-Westphalia drive continuous consumption for diverse manufacturing processes.
China
China's vast electronics manufacturing base and growing environmental monitoring needs drive significant specialty gas consumption. The Ministry of Ecology and Environment (MEE) enforces strict emission standards for industrial gases. Electronics fabrication hubs in the Yangtze River Delta concentrate demand for ultra-pure process gases.
Japan
Japan's advanced materials industry and semiconductor equipment sector require specialized high-purity and rare gases. The Ministry of Economy, Trade and Industry (METI) supports local innovation and supply chain security. Semiconductor manufacturing sites in Kyushu and industrial R&D centers in Kanto sustain consistent demand.
Global Specialty Gas Market Key Industry Players
North American and European producers anchor one tier; Asian specialists hold another within the global specialty gas market. This landscape features a mix of multinational conglomerates and regional pure-play providers. Archetypes include integrated industrial gas giants offering a broad portfolio, specialized electronic gas suppliers focusing on ultra-purity, and niche rare gas providers serving specific high-tech applications. Capacity expansion, particularly in Asia, and strategic partnerships for technology co-development are dominant competitive moves.
Within the integrated industrial gas giants, Air Liquide and Linde plc exemplify global reach and broad product portfolios. These entities leverage extensive distribution networks and R&D capabilities to meet diverse industrial and medical gas demands across multiple continents. Taiyo Nippon Sanso Corporation, conversely, represents a specialized player with a strong focus on electronic gases. This Japanese corporation anchors a significant position in the Asian semiconductor industry, providing critical inputs for advanced chip fabrication processes. These companies collectively demonstrate the tiered structure of the specialty gas market.
| Leading Market Players |
|---|
| Air Liquide |
| Linde plc |
| Air Products and Chemicals Inc. |
| Messer SE & Co. KGaA |
| Taiyo Nippon Sanso Corporation |
| BASF SE |
| Iwatani Corporation |
| Matheson Tri-Gas Inc. |
| Coregas Pty Ltd. |
| Others |
Cost & Logistics Intelligence
Ultra-high purity gas grades establish a clear divergence in the specialty gas market, directly influencing pricing structures and requiring distinct supply chain investments. These stringent purity specifications for semiconductor manufacturing drive premium pricing and necessitate advanced purification infrastructure.
Pricing Analysis
Short lead times for critical electronic gases command premium pricing, reflecting the urgency of semiconductor fabrication schedules. Contract-based long-term offtake agreements dominate for stable supply, while transactional pricing applies to lower-volume spot purchases. Price differentiation stems from the specific purity grade, complex geographic delivery logistics, and bundled gas management services. Cost compression in high-purity industrial gases stems from increasing competition and energy price volatility, while semiconductor fabs exhibit the lowest price sensitivity.
Supply Chain Analysis
Stringent regulatory qualification, such as EU REACH and pharmacopeia standards, gates market access and necessitates robust supply chain documentation. Supply concentration for electronic gases centers in South Korea, Japan, and China, while advanced R&D drives demand in the United States. Raw material dependencies for rare gases like neon and xenon create single-source vulnerability risks. Distribution runs through a hybrid model, combining bulk liquid delivery with cylinder and microbulk solutions, increasingly complemented by localized on-site generation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The specialty gas market is evolving into a vertical-integration race, as producers pursue captive purification technologies to meet escalating purity demands. This strategic move aims to control critical process inputs and ensure compliance with stringent regulations.
For Market Incumbents:Anchor existing market share by investing in advanced R&D for low-GWP alternative molecules, mitigating risks from the EU F-Gas Regulation. Expand global distribution networks, particularly in South Korea, to counter new entrant activity and secure long-term supply agreements with semiconductor fabs. Pursue certification investments to meet evolving REACH and pharmacopeia standards, reinforcing compliance as a competitive advantage. This also involves optimizing energy-intensive purification processes to manage cost volatility.
For New Entrants and Emerging Players:Smaller research institutions and regional healthcare facilities represent an underserved buyer archetype, seeking reliable, localized supply solutions. Target the quantum computing sector with ultra-pure cryogenic gases like helium, capitalizing on its specialized, high-margin requirements. Offer on-site generation systems for nitrogen and oxygen to mid-sized industrial users, reducing their logistical dependencies and improving reliability. A service-oriented gas management agreement model provides a strong go-to-market angle for these segments.
For Investors and Strategic Acquirers:Re-rating potential sits with specialized electronic gas suppliers given the non-discretionary demand from advanced semiconductor manufacturing. Specialty gases underpin critical high-tech industries for the foreseeable future, ensuring long-term viability and stable returns. Identify acquisition targets with proprietary purification technologies or established rare gas recycling capabilities to gain control over critical inputs. The signal to watch is the accelerating adoption rates of sub-10 nanometer chip manufacturing processes, indicating sustained demand for ultra-high purity inputs.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in South Korea | Secures supply for expanding semiconductor fabrication plants in Gyeonggi Province. |
| R&D in Low-GWP Alternatives | Ensures market access in Europe by complying with F-Gas Regulation. |
| On-Site Gas Generation Offerings | Reduces customer reliance on bulk logistics, enhancing supply chain resilience. |
| Rare Gas Recycling Service Launch | Addresses raw material bottlenecks for xenon and meets corporate sustainability goals. |
| Strategic Partnerships for Certification | Facilitates compliance with EU REACH and ECHA standards for market access. |
Research Approach
Document review covered industry association reports, patent databases, and regulatory filings from EPA, ECHA, and MEE, complemented by interviews. Primary research involved discussions with semiconductor fab managers, R&D chemists, procurement leads, and regulatory affairs specialists. This was triangulated with secondary data from trade statistics, company annual reports, and academic literature. A bottom-up and top-down approach validated market sizing and growth projections.
Volume and value forecasts were produced for each segment across the analysis window, integrating historical data with projected future trends. The analytical framework modeled segmentation dimensions including product type, application, industry vertical, packaging type, and regional regulatory frameworks. Compound annual growth rates were derived through regression analysis and expert consensus. Key industry-specific inputs included semiconductor fab expansion plans and evolving medical gas consumption trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts affecting rare gas supply or unexpected technological breakthroughs. Forecasts reflect documented assumptions, but new regulatory mandates could also alter projections. A model refresh is warranted upon material change in the evolution of sub-10 nanometer chip fabrication processes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Gases
Gas Processing Market
Industrial Gases
Fluorocarbon Gases Market
Industrial Gases
North America Specialty Gas Market
Industrial Gases
High Purity Gas/Ultra-High Purity Gas/Pure Gas Market
Industrial Gases
US Industrial Gas Regulator Market
Industrial Gases
Dielectric Gases Market
Industrial Gases
Pressure Swing Adsorption Nitrogen Generator Market
Industrial Gases
High Purity Methane Gas Market
Industrial Gases
Global Sulfur Dioxide Market
Industrial Gases
Oxygen Market
Industrial Gases
Transcritical CO2 Market
Industrial Gases
Gas and Liquid Argon Market
Industrial Gases
Welding Gas Market
Industrial Gases
Industrial Hydrogen Peroxide Market
Industrial Gases
Krypton Gas Market
Industrial Gases
CNG, RNG, and Hydrogen Tanks Market