
 EMI Microwave Absorber Market | 2026-2036
EMI Microwave Absorber Market Size, Share, and Industry Trends Forecast 2026-2036
EMI Microwave Absorber Market Insights
Japanese ferrite producers is realigning output toward higher-frequency formulations for millimeter-wave bands. Laird Technologies leverages vertical integration across magnetics and thermal management to sustain pricing power in North American defense contracts. Parker Hannifin anchors its position through aerospace channel control, while TDK Corporation differentiates via thin-film deposition expertise for consumer electronics miniaturization.
An EMI microwave absorber is a material engineered to attenuate electromagnetic energy through dielectric and magnetic loss mechanisms, typically formulated with carbonyl iron, ferrite powders, or conductive polymers in elastomeric or foam matrices, and designed to operate across frequencies from megahertz to terahertz ranges. These materials suppress reflected radiation, mitigate cavity resonances, and enable electromagnetic compatibility in enclosed electronic systems. Carbon-based formulations now lead volume shipments due to their broadband performance and lighter weight, while composite absorbers represent the fastest-expanding category as multilayer designs penetrate aerospace and telecommunications. Sheet form factors dominate OEM procurement for their ease of integration, though coating applications are gaining share in automotive where conformal shielding of complex geometries is essential.
The FCC enforces stringent Part 15 emissions limits that compel absorber deployment in telecommunications equipment, while EU REACH regulations restrict hazardous substances in polymer binders, reshaping material selection across European supply chains. Japan's METI promotes domestic absorber R&D through standards harmonization with IEC electromagnetic compatibility frameworks. Stakeholders must monitor how evolving 6G spectrum allocations and satellite constellation densities will redefine absorber performance thresholds before committing to long-term capacity investments.
Market Dynamics
Aerospace stealth requirements and 5G infrastructure densification are compressing absorber development cycles, forcing suppliers to reconcile broadband performance with weight reduction targets simultaneously.
Growth Catalysts
- FCC Part 15 mandates:Telecommunications OEMs must redesign shielding architectures to meet tightening electromagnetic emissions ceilings, creating absorber pull through base station and router supply chains.
- Millimeter-wave 5G deployment:China's telecommunications infrastructure buildout requires extensive microwave absorption materials for small cell concealment and interference mitigation at 28 GHz and 39 GHz bands.
- Radar cross-section management:Military aerospace platforms are expanding absorber procurement for signature reduction on unmanned systems and next-generation combat aircraft.
Market Restraints
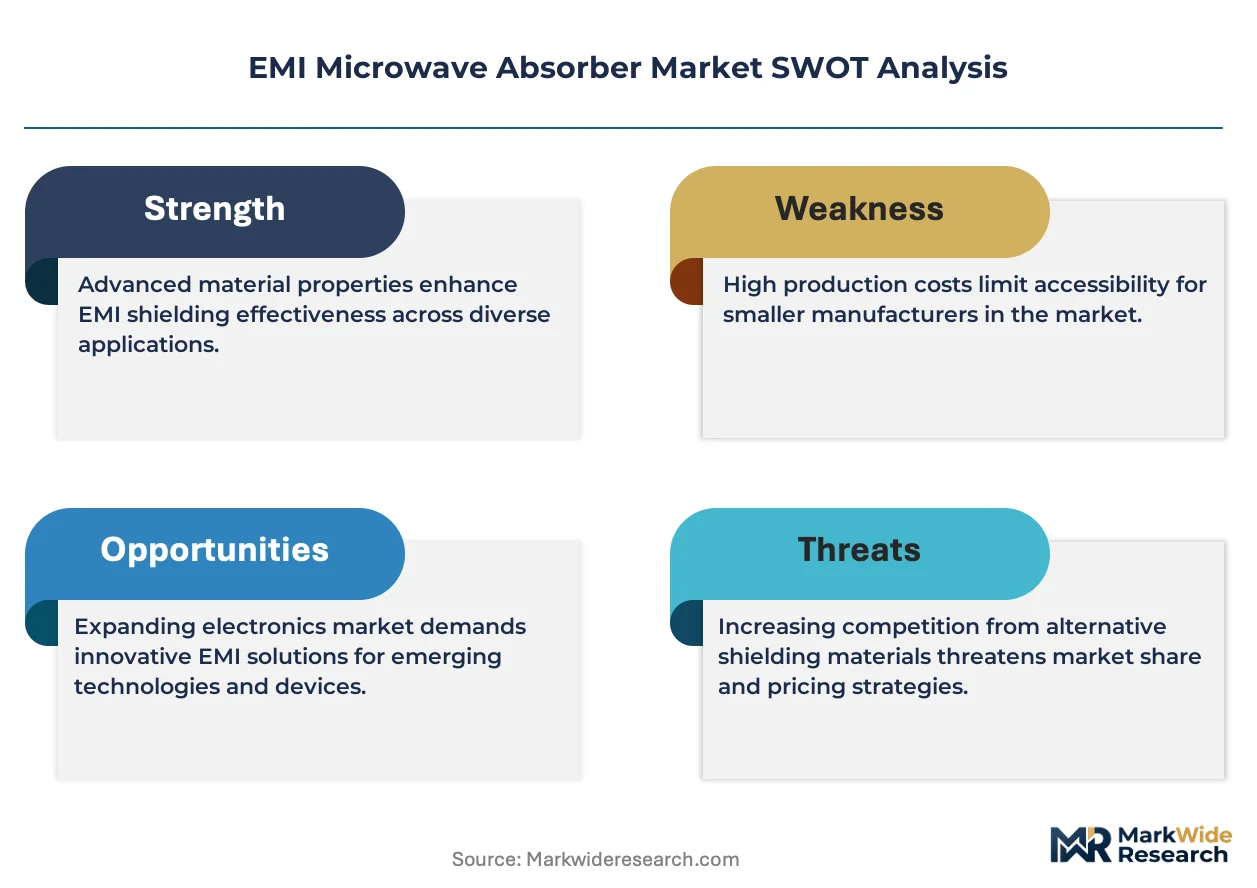
- Raw material concentration:High-purity carbonyl iron feedstock concentrates among Chinese and German chemical suppliers, exposing converters to input volatility and dual-use export controls.
- REACH polymer restrictions:EU regulations on hazardous substances in elastomer binders force European formulators to qualify alternative chemistries, extending qualification timelines.
- Technical bandwidth limits:Single-layer ferrite absorbers face fundamental magnetic loss degradation above 40 GHz, constraining their utility for emerging terahertz applications.
Strategic Opportunities
- Satellite constellation densification:Low Earth orbit broadband deployments by SpaceX and Amazon's Project Kuiper create demand for compact, thermally stable absorbers in phased array terminals.
- Automotive radar integration:77-81 GHz automotive radar proliferation in Germany and Japan opens conformal coating applications for complex bumper and fascia geometries.
- METI R&D harmonization:Japan's alignment of domestic electromagnetic compatibility standards with IEC frameworks accelerates absorber certification for regional electronics exports.
Industry Challenges
- Multiphysics simulation talent:Formulators struggle to recruit engineers proficient in combined electromagnetic-thermal-mechanical modeling for multilayer composite design.
- Aerospace qualification timelines:MIL-STD-285 and RTCA-DO-160 certification cycles for new absorber formulations extend 18-36 months, freezing development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EMI Microwave Absorber Market |
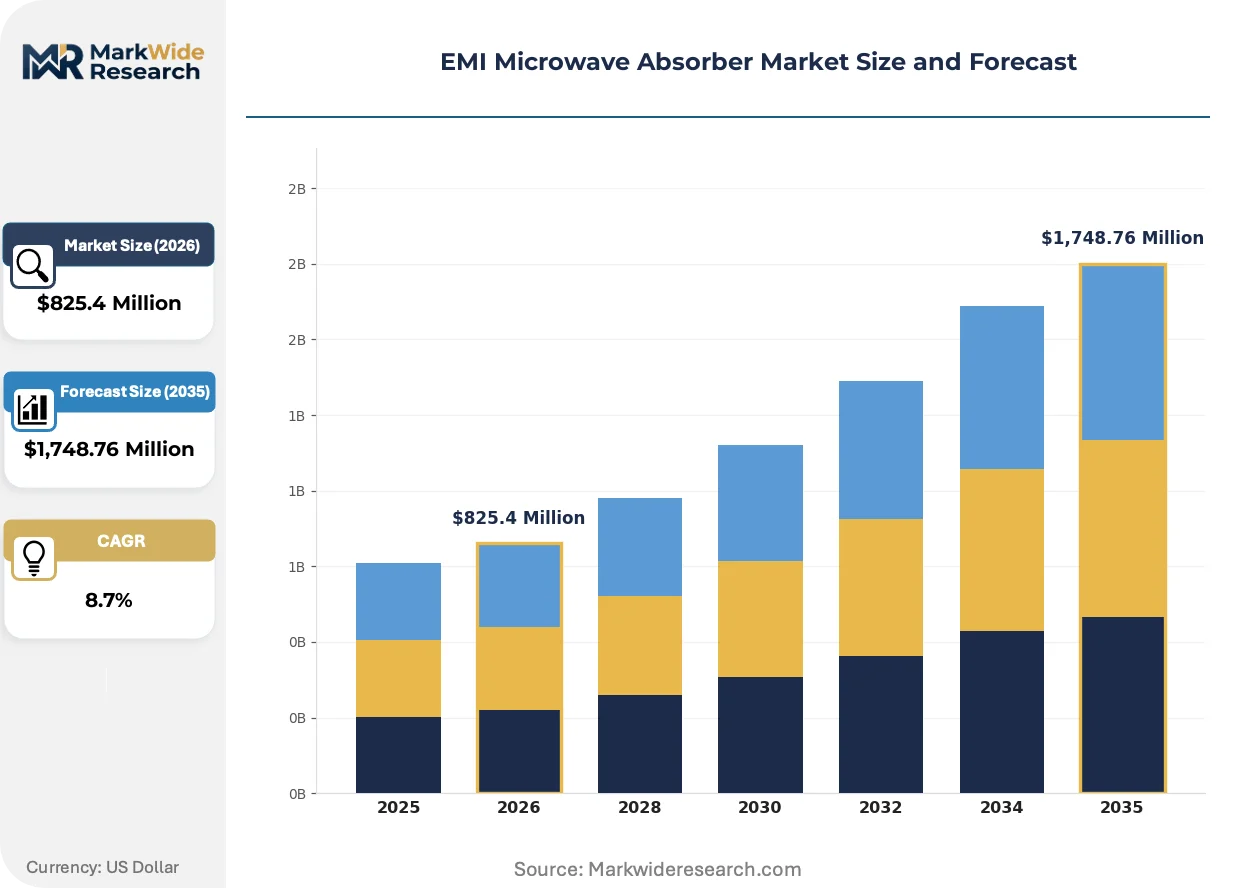
| Market Size in 2026 | $825.4 Million |
| Market Size in 2035 | $1,748.76 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Ferrite, Carbon-Based, Polymer, Composite Application: Automotive, Aerospace, Consumer Electronics, Telecommunications Form Factor: Sheet, Coating, Foam, Panel End User: OEMs, Manufacturers, Designers, Integrators |
| Companies Covered | Laird Technologies, Cuming Microwave, Parker Hannifin, TDK Corporation, 3M, Rogers Corp., Murata Manufacturing, Nitto Denko, Resin Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EMI Microwave Absorber Market Trends and Innovations
Absorber technology is bifurcating between commoditized broadband sheets and application-specific metamaterial architectures, with manufacturing process innovation determining competitive outcomes more than formulation chemistry alone.
Metamaterial absorbers incorporating periodic conductive patterns are converging with additive manufacturing to enable geometrically complex, frequency-selective surfaces. Aerospace prime contractors in the United States and United Kingdom are qualifying these structures for narrowband, high-power applications where traditional composites fail. The convergence is compressing the addressable market for conventional multilayer laminates in defense procurement.
EU REACH regulations on persistent organic pollutants in polymer matrices are compelling European absorber manufacturers to migrate from halogenated flame retardants to phosphorus-nitrogen systems. This industrial consequence extends reformulation timelines by 12-18 months but creates regulatory moats for early adopters. Consumer electronics and automotive segments in Germany and France are most affected, with Tier 1 suppliers now requiring full material disclosure down to the monomer level.
Buyer concentration among telecommunications infrastructure OEMs has compressed absorber specification cycles from annual to quarterly reviews. Long-term supply agreements with fixed pricing are displacing spot purchasing for carbon-based sheet products. This behavioral shift is most visible in China's 5G base station supply chain, where Huawei and ZTE procurement teams now dictate absorber thermal cycling test protocols directly to material suppliers.
EMI Microwave Absorber Market Segmentation
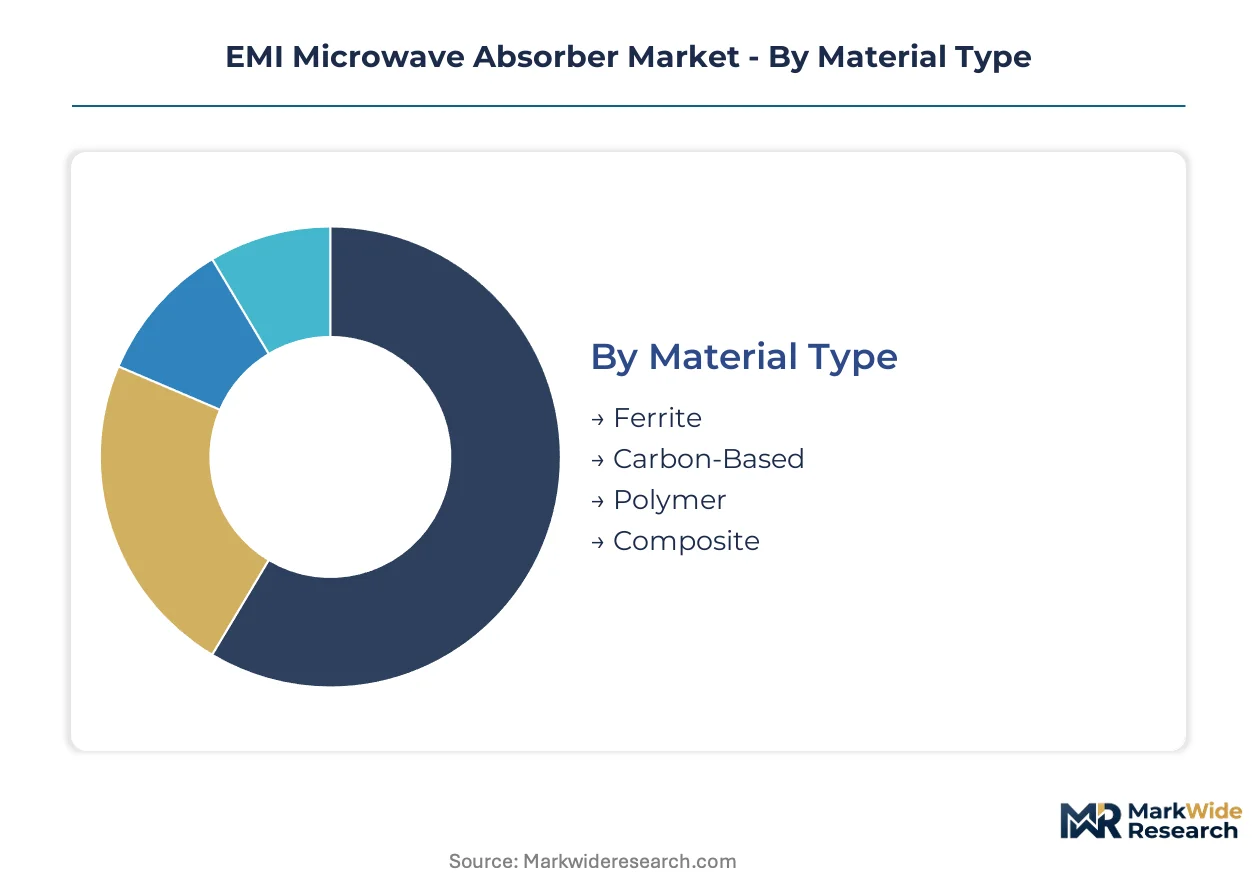
EMI microwave absorber procurement patterns diverge sharply across material chemistry, physical form, and end-use certification requirements. Buyers prioritize frequency bandwidth, weight constraints, and regulatory compliance differently depending on application environment and integration complexity.
Material Type:
Cost-performance tradeoffs dominate material selection, with frequency range and operating environment dictating chemistry choices.
- Carbon-Based:Formulations incorporating carbonyl iron powders or carbon black in elastomer matrices deliver broadband attenuation from megahertz through millimeter-wave bands. Telecommunications infrastructure OEMs in China specify carbon-based sheets for 5G base station shielding where weight reduction accelerates installation logistics. FCC Part 15 compliance mandates pull this chemistry through router and small cell supply chains.
- Composite:Multilayer architectures combining dielectric and magnetic loss layers enable tailored impedance matching across narrow frequency windows. Aerospace prime contractors qualify these for radar cross-section management on unmanned platforms where single-layer ferrite performance degrades above 40 GHz. The steepest expansion trajectory belongs to this category as satellite constellation terminal manufacturers seek thermally stable, compact solutions.
- Ferrite:Sintered or rubber-bonded ferrite powders provide cost-effective absorption at lower microwave frequencies through magnetic loss mechanisms.
- Polymer:Conductive polymer matrices offer conformal application potential for complex geometries in automotive radar integration.
Carbon-based formulations lead on scale; composite architectures lead on momentum.
Application:
Certification intensity and performance thresholds segment demand into radically different procurement behaviors.
- Telecommunications:Infrastructure densification for millimeter-wave 5G drives volume procurement of sheet-form absorbers for base station concealment and interference mitigation. China's deployment of 28 GHz and 39 GHz small cells requires extensive microwave absorption materials, with Huawei and ZTE procurement teams now dictating thermal cycling test protocols directly to suppliers.
- Aerospace:Military stealth requirements and commercial satellite terminal integration demand multilayer composites qualified to MIL-STD-285 and RTCA-DO-160. Radar cross-section management for next-generation combat aircraft and unmanned systems compresses development cycles while extending qualification timelines to 18-36 months.
- Automotive:77-81 GHz radar proliferation in Germany and Japan opens conformal coating applications for bumper and fascia geometries.
- Consumer Electronics:Miniaturization pressures in smartphones and wearables favor thin-film deposition techniques for integrated shielding.
Telecommunications commands volume; aerospace commands margin.
Form Factor:
Integration method determines manufacturing process selection and supply chain configuration.
- Sheet:Elastomeric or foam-backed sheets in standard thicknesses dominate OEM procurement for their ease of die-cutting and adhesive bonding to enclosure surfaces. China's telecommunications infrastructure buildout concentrates demand here, with quarterly specification reviews replacing annual cycles as buyer concentration increases.
- Coating:Sprayable or brushable conductive formulations enable conformal shielding of complex geometries where sheet application proves impractical. Automotive radar integration in Germany and Japan drives qualification of coating systems for bumper assemblies and fascia components.
- Foam:Reticulated or closed-cell foam absorbers provide lightweight cavity filling for aerospace applications.
- Panel:Rigid composite panels serve high-power test chamber and anechoic chamber installations.
Sheet formats dominate current procurement; coating applications gain share fastest.
End User:
Technical capability and volume scale create distinct purchasing authority patterns across the value chain.
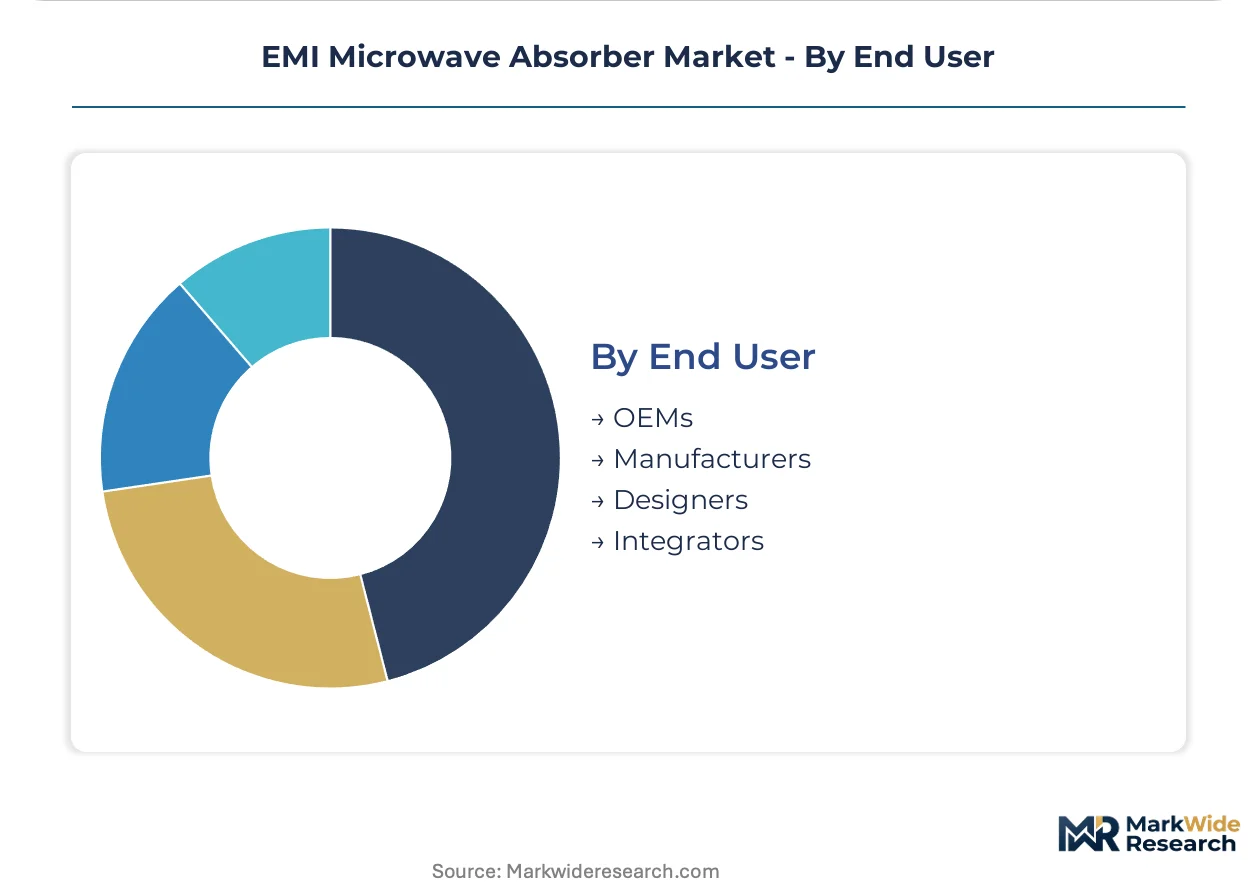
- OEMs:Original equipment manufacturers in telecommunications and aerospace wield direct specification authority, locking in long-term supply agreements with fixed pricing for carbon-based products. China's 5G base station OEMs now require full material disclosure down to the monomer level, extending qualification burden to Tier 2 suppliers.
- Manufacturers:Contract manufacturers and subsystem integrators procure to OEM specifications, with limited flexibility to substitute alternative formulations.
- Designers:Engineering firms and R&D centers specify absorbers for prototype and test applications.
- Integrators:System integrators select absorbers for retrofit and maintenance applications.
OEMs concentrate specification power; manufacturers concentrate transaction volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping absorber production geography. REACH polymer restrictions in Europe impose 12-18 month reformulation timelines that Japanese and Chinese suppliers exploit through faster certification cycles. This compliance-cost gap redirects procurement leverage toward Asia-Pacific converters while European formulators absorb qualification burdens.
United States
Aerospace stealth programs and 5G infrastructure densification drive procurement. FCC Part 15 emissions mandates compel telecommunications OEMs to redesign shielding architectures. Defense contractors in California and Texas concentrate radar cross-section management demand for unmanned systems and next-generation combat aircraft.
China
Telecommunications infrastructure buildout dominates volume demand. MIIT spectrum allocations for 28 GHz and 39 GHz millimeter-wave bands accelerate small cell deployment. Huawei and ZTE procurement teams in Shenzhen and Shanghai now dictate thermal cycling test protocols directly to material suppliers, compressing specification cycles to quarterly reviews.
Japan
Ferrite producers realign output toward higher-frequency formulations. METI standards harmonization with IEC electromagnetic compatibility frameworks accelerates absorber certification for regional electronics exports. Industrial clusters in Kanto and Kansai concentrate thin-film deposition expertise for consumer electronics miniaturization.
Germany
Automotive radar integration at 77-81 GHz opens conformal coating applications. EU REACH regulations on persistent organic pollutants force migration from halogenated flame retardants to phosphorus-nitrogen systems. Stuttgart and Munich anchor qualification programs for bumper and fascia shielding geometries.
South Korea
Consumer electronics miniaturization pressures favor thin-film deposition techniques. MFDS alignment with international electromagnetic compatibility standards streamlines absorber integration for smartphone and wearable exports. Seoul Capital Area manufacturers concentrate integrated shielding for premium device segments.
EMI Microwave Absorber Market Competitive Landscape
United States producers anchor defense-aerospace tier; Japanese specialists hold consumer electronics positioning. The vendor base concentrates among magnetics conglomerates, specialty chemical formulators, and precision coating houses. Three archetypes dominate: vertically integrated magnetics suppliers, thin-film deposition experts, and broadband sheet converters. Strategic moves center on aerospace channel control and qualification timeline compression through pre-certified material platforms.
Among North American fabricators, Laird Technologies and Parker Hannifin exemplify the vertically integrated magnetics archetype, while TDK Corporation anchors the thin-film deposition specialist tier. These three occupy positions that reflect divergent competitive vectors: magnetics conglomerates leverage backward integration into carbonyl iron feedstock, deposition houses capitalize on consumer electronics miniaturization cycles, and defense-channel players absorb extended MIL-STD-285 certification timelines as competitive moats.
| Leading Market Players |
|---|
| Laird Technologies |
| Cuming Microwave |
| Parker Hannifin |
| TDK Corporation |
| 3M |
| Rogers Corp. |
| Murata Manufacturing |
| Nitto Denko |
| Resin Systems |
| Others |
Pricing and Supply Chain Analysis
Multiphysics simulation talent concentration in Japanese industrial clusters feeds into pricing-tier spreads, as qualified engineers command premiums that compress margins on standard-grade absorbers while widening spreads to aerospace-certified formulations. REACH compliance costs in Europe extend reformulation timelines, creating labor-cost arbitrage that Asian converters exploit through faster certification cycles.
Pricing Analysis
Distributor margins in North American defense channels absorb MIL-STD-285 certification premiums, compressing net realized prices for converters while direct-to-OEM agreements in China's telecommunications sector lock in fixed pricing for carbon-based sheet products. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified multilayer composites from telecommunications-grade sheets and automotive coating formulations. Cost compression in standard-grade ferrite absorbers intensifies because Chinese carbonyl iron feedstock suppliers wield pricing power. Telecommunications OEMs exhibit highest price sensitivity due to quarterly specification reviews, while aerospace primes accept extended payback periods for qualified materials.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and German chemical suppliers controlling high-purity carbonyl iron feedstock, exposing converters to dual-use export control disruptions and input volatility. Manufacturing concentrates in China, Japan, and the United States, with Kanto and Kansai clusters anchoring thin-film deposition expertise and Shenzhen-Shanghai corridors dominating telecommunications volume. Raw material dependencies center on carbonyl iron powders, ferrite ceramics, and conductive polymer binders. Tariff exposure on Chinese-processed rare earth precursors threatens cost structures for North American formulators. Distribution runs through direct OEM supply agreements displacing spot purchasing, with long-term offtake contracts now standard for carbon-based sheet products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMI microwave absorber procurement operates as a geographic-arbitrage play where REACH-driven reformulation burdens in Europe create 12-18 month qualification gaps that Japanese and Chinese suppliers exploit through faster METI and GB standards harmonization.
For Market Incumbents: Anchor aerospace channel control through pre-certified material platforms that absorb RTCA-DO-160 timelines as competitive moats against emerging metamaterial specialists. Defend against additive manufacturing convergence by deepening backward integration into carbonyl iron feedstock. Prioritize capacity addition in Kanto industrial clusters to capture consumer electronics miniaturization cycles. For New Entrants and Emerging Players: The 40% price-point gap between aerospace-qualified composites and standard telecommunications sheets opens white-space in automotive conformal coatings for 77-81 GHz radar integration. Target Germany's Stuttgart-Munich corridor where REACH restrictions have frozen incumbent reformulation roadmaps. Pursue satellite constellation terminal manufacturers as the most penetrable segment, leveraging phosphorus-nitrogen flame retardant formulations as regulatory-compliant differentiation. For Investors and Strategic Acquirers: Magnetics conglomerates with captive carbonyl iron supply are the most active acquirer in this space, consolidating specialty chemical formulators to secure backward integration. Long-term viability hinges on 6G spectrum allocation timing and satellite constellation density inflections. Watch for MIIT millimeter-wave band expansions as the signal triggering capacity investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Carbonyl Iron Feedstock | Secures supply continuity against Chinese export control volatility for defense contractors. |
| Phosphorus-Nitrogen Flame Retardant Migration | Creates REACH compliance moats in European automotive and consumer electronics procurement. |
| Pre-Certified Material Platform Launch | Compresses MIL-STD-285 qualification timelines for aerospace prime contractor channel access. |
| Thin-Film Deposition Capacity Expansion | Captures smartphone and wearable miniaturization demand in Seoul Capital Area manufacturing clusters. |
| Satellite Terminal Phased Array Partnership | Positions composite absorbers for SpaceX and Amazon Project Kuiper thermal stability requirements. |
Research Methodology
Direct dialogue with absorber formulation chemists, telecommunications procurement leads at Huawei and ZTE, aerospace channel managers, and METI standards officials grounded qualitative assessments, cross-referenced against customs trade data, FCC Part 15 enforcement records, SEC 10-K filings from magnetics conglomerates, and IEC electromagnetic compatibility framework documents. Bottom-up volume estimates from material supplier interviews triangulated with top-down demand modeling from end-use OEM capex disclosures.
Segmentation outputs across material type, form factor, application, and end-user category drove analytical framework construction across the projection horizon. CAGRs derived from installed base growth in 5G infrastructure, unmanned aerial system procurement, and satellite constellation deployment schedules. Frequency band allocation decisions by FCC and MIIT served as exogenous demand shock inputs, while REACH regulatory phase-in timelines shaped European supply elasticity assumptions.
Caveats apply where 6G spectrum allocations, dual-use export control expansions, or metamaterial additive manufacturing breakthroughs could materially shift the outlook. Forecasts embed assumptions about qualification timeline stability and raw material supply continuity that geopolitical friction or technical substitution may revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Embedded Antenna Systems Market
RF Components
Radio Frequency Components Market
RF Components
433MHz Active RFID Reader Market
RF Components
Radio Frequency Duplexer Market
RF Components
Coaxial Splitters Market
RF Components
Harness-Level EMI and Shielding Component Systems Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
RF Acoustic Wave Filters Market
RF Components
LTCC Power Dividers Market
RF Components
FBAR Devices Market
RF Components
RF Tester Market
RF Components
Flat Antenna Market
RF Components
RF Semiconductor Market
RF Components
China Small Signal Transistor Market
RF Components
Low Noise Amplifier Market
RF Components
Dielectric Resonator Market