
 Space Traveling Wave Tube Amplifiers Market | 2026-2036
Space Traveling Wave Tube Amplifiers Market Size, Share, and Industry Trends Forecast 2026-2036
Space Traveling Wave Tube Amplifiers Market Insights
Project finance tied to sovereign satellite constellation programs is tilting competitive access toward vendors with proven space heritage. Tesat-Spacecom GmbH & Co. KG leverages its German manufacturing base to anchor European institutional demand for Ku-band and Ka-band flight hardware. Thales Group sustains dual-use capabilities across civil and military satellite programs, while L3Harris Technologies competes on the strength of its U.S. defense contractor relationships and extensive space qualification history.
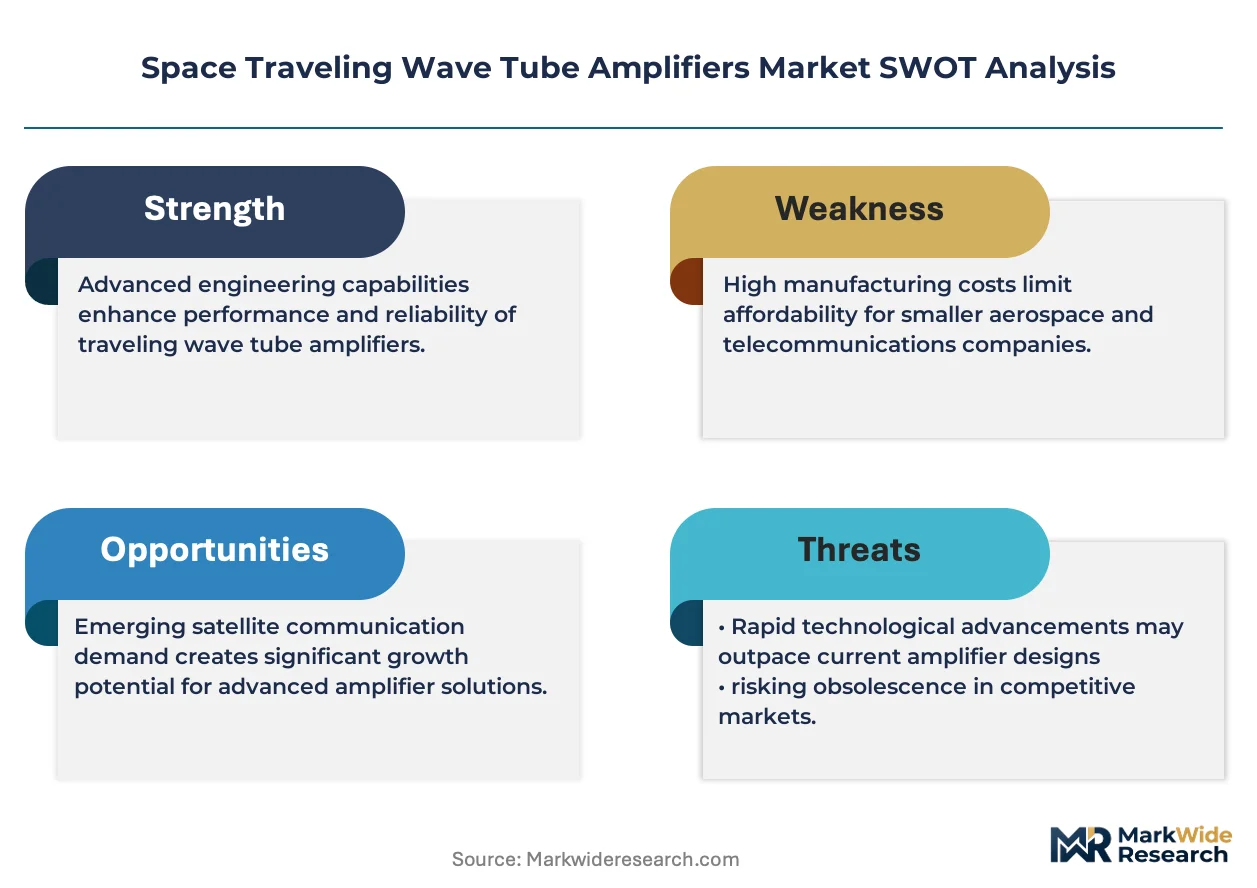
Space traveling wave tube amplifiers are vacuum electronic devices that convert electron beam kinetic energy into microwave RF power through interaction with a slow-wave helical or coupled-cavity structure, achieving output levels from tens to thousands of watts with efficiencies exceeding fifty percent in orbit. Their primary purpose is to provide reliable, high-power signal amplification for satellite transponders and deep-space communication links where solid-state alternatives face thermal and radiation limitations. Ku-Band and Ka-Band product categories dominate current procurement volumes driven by broadband satellite constellation deployments, while X-Band amplifiers retain entrenched positions in military radar and earth observation payloads where spectrum allocation and interference resilience matter. Application demand concentrates in satellite communications and deep space probes, with earth observation representing a mature segment where price competition from solid-state alternatives constrains margin expansion.
FAA launch licensing requirements, ESA space qualification standards, and U.S. International Traffic in Arms Regulations collectively shape product development cycles, export control classifications, and customer access tiers for amplifier manufacturers. ITAR restrictions particularly constrain technology transfer and foreign sales for U.S.-based suppliers, while ESA's ECSS standards drive harmonized reliability benchmarks across European supply chains. Stakeholders must monitor evolving spectrum reallocation decisions and national security export policy shifts that could abruptly resegment addressable markets between allied and restricted customer pools.
Market Dynamics
Sovereign satellite constellation programs are consolidating procurement authority around vendors with demonstrated space heritage, compressing qualification timelines while elevating technical barriers for new entrants.
Growth Catalysts
- LEO Constellation Deployment:Low-earth orbit broadband networks are pulling demand for high-power RF amplification in compact form factors. Satellite operators prioritize flight-proven hardware over unqualified alternatives.
- NASA Procurement Standards:Tightening thermal and radiation-hardening specifications for deep-space missions are locking in demand for vacuum electronic devices that solid-state alternatives cannot yet match.
- German Manufacturing Base:European institutional anchor demand concentrates around qualified suppliers with domestic production capabilities, creating stable order pipelines for Ku-band and Ka-band hardware.
Market Restraints
- ITAR Export Controls:U.S. International Traffic in Arms Regulations constrain technology transfer and foreign sales for domestic suppliers, fragmenting addressable customer pools along national security lines.
- Input Material Concentration:Specialized ceramics and high-purity tungsten for cathode assemblies face concentrated supply from limited qualified vendors, creating vulnerability to price volatility.
- Solid-State Substitution:Gallium nitride power amplifiers are encroaching on lower-power satellite applications where thermal budgets and radiation tolerance requirements permit.
Strategic Opportunities
- Deep-Space Probe Missions:ESA's expanding outer-planet exploration program creates demand for ultra-high reliability X-band and Ka-band amplifiers with extended operational lifetimes.
- Dual-Use Military-Civil Convergence:European governments are harmonizing procurement specifications across defense and commercial satellite programs, enabling suppliers to amortize qualification costs across larger production runs.
- On-Orbit Servicing Infrastructure:Emerging satellite life-extension vehicles require standardized amplifier interfaces compatible with robotic replacement, opening retrofit markets for qualified hardware.
Industry Challenges
- Specialized Vacuum Electronics Talent:The workforce pipeline for helix winding, electron gun assembly, and vacuum processing is contracting as university programs pivot toward semiconductor curricula.
- Qualification Timeline Compression:ESA ECSS standards demand extensive thermal cycling and radiation testing that extends product development cycles beyond constellation deployment schedules.
- Heritage Documentation Burden:Prime contractors require exhaustive flight history records that disadvantage newer suppliers lacking accumulated orbital performance data.
Report Scope
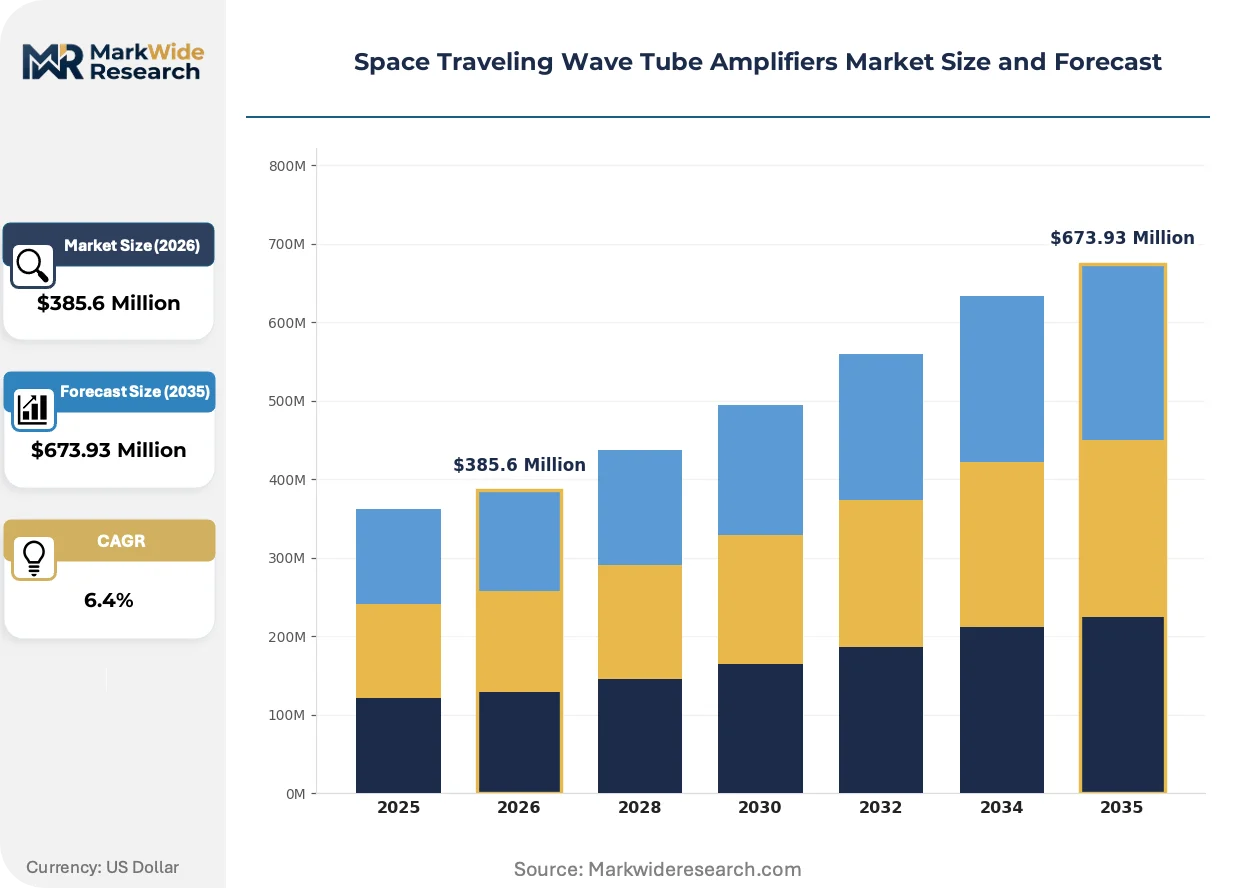
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Space Traveling Wave Tube Amplifiers Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ku-Band, Ka-Band, X-Band, S-Band, C-Band Technology: Thermionic Emission, Semiconductor, Vacuum Electronic, Solid State, Magnetron Application: Satellite Communications, Radar Systems, Deep Space Probes, Earth Observation, Scientific Research End User: Space Agencies, Telecommunication Providers, Defense Contractors, Research Institutions |
| Companies Covered | Tesat-Spacecom GmbH & Co. KG, Stellant Systems, Thales Group, NEC, TMD Technologies, Communications & Power Industries, Teledyne Technologies, General Dynamics, L3Harris Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Space Traveling Wave Tube Amplifiers Market Trends and Innovations
Helical slow-wave structures and coupled-cavity designs are converging with advanced thermal management to push power-density boundaries, while procurement centralization around sovereign programs is reshaping vendor qualification pathways.
Multi-stage depressed collector architectures are recovering kinetic energy from spent electron beams to boost DC-to-RF conversion efficiency above sixty percent. L3Harris and Thales are integrating these designs into Ka-band flight hardware for high-throughput satellites. This efficiency gain is rendering obsolete single-stage collector designs that waste thermal budget on rejected beam power.
ESA's ECSS-E-ST-20-07C qualification standard now mandates proton and heavy-ion radiation testing to total ionizing dose levels exceeding 100 krad(Si) for geostationary missions. European prime contractors are rejecting components lacking certified radiation hardness assurance data. Ka-band amplifiers for commercial broadband constellations face the steepest compliance cost escalation as test campaigns extend lead times.
Consolidated buying desks at national space agencies are replacing distributed procurement through satellite prime subcontractors. France's CNES and Germany's DLR now contract directly with amplifier specialists for qualified spares, bypassing traditional prime-channel markups. This disintermediation concentrates most visibly in earth observation payload programs where institutional customers prioritize cost transparency over integration convenience.
Space Traveling Wave Tube Amplifiers Market Segmentation
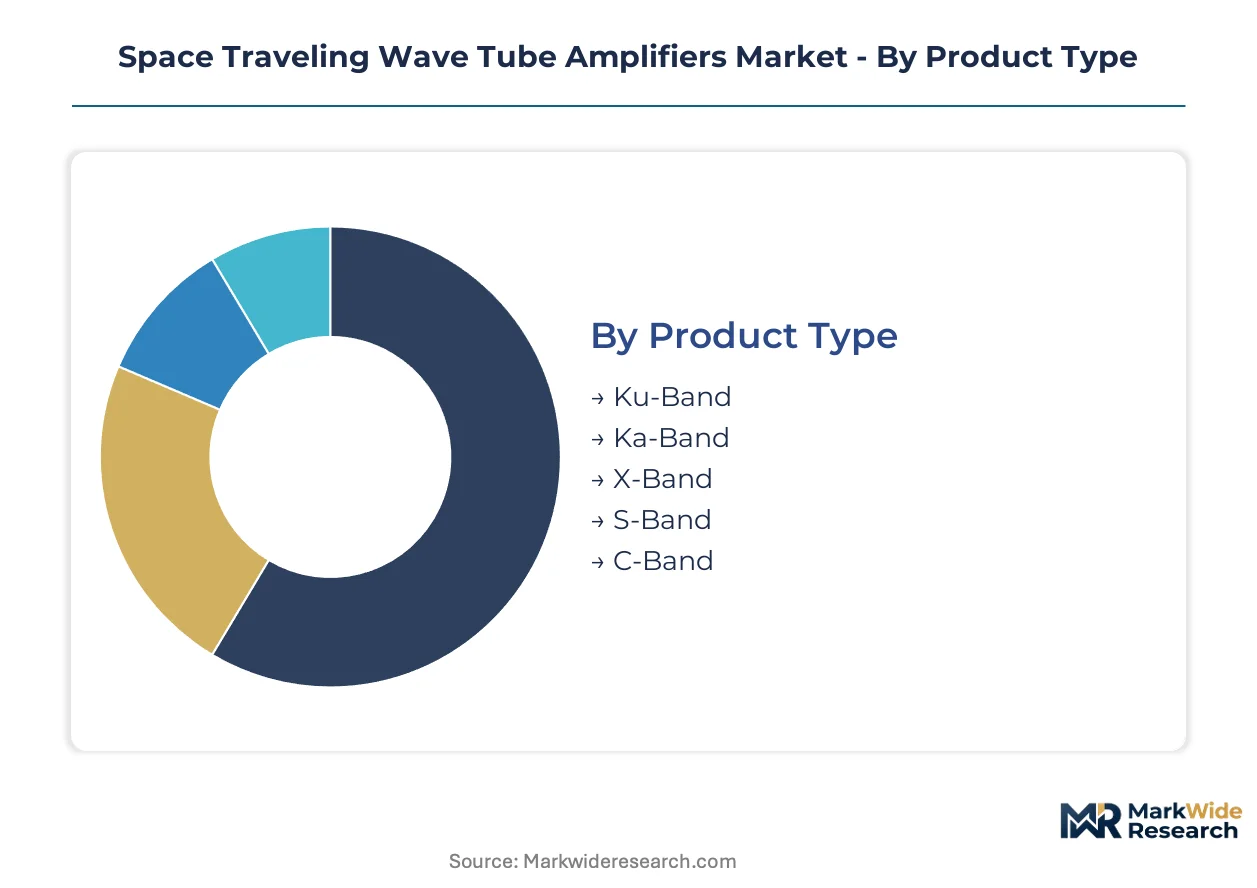
Segmentation in space traveling wave tube amplifiers reflects divergent technical requirements across orbital regimes and payload classes. Procurement specifications vary sharply between geostationary broadband satellites and deep-space exploration missions.
Product Type:
Use-case spectrum spans commercial broadband constellations requiring compact high-efficiency units through military radar platforms demanding hardened wideband performance.
- Ku-Band:Conventional helix-based designs deliver 100-200W output with established thermal management for medium-power transponder applications. Procurement concentrates among European prime contractors outfitting geostationary platforms, driven by institutional anchor demand from Germany's DLR and France's CNES for flight-proven hardware with extensive orbital heritage.
- Ka-Band:Coupled-cavity architectures achieve 500W+ output with multi-stage depressed collectors pushing efficiency past sixty percent. Broadband constellation operators in the United States and Japan prioritize these units for high-throughput spot-beam applications where power density and thermal budget constraints dominate payload design trade-offs.
- X-Band:Military radar and earth observation payloads retain entrenched positions where spectrum allocation and interference resilience matter.
- S-Band:Scientific missions and telemetry links employ lower-frequency units for deep-space communication where atmospheric penetration takes priority over bandwidth.
- C-Band:Legacy broadcast satellite infrastructure maintains steady replacement demand despite spectrum reallocation pressures.
The dominant share belongs to Ku-Band, while Ka-Band is closing the gap fastest.
Technology:
Cost tier stratification separates qualified vacuum electronics commanding premium pricing from emerging solid-state alternatives competing on lower-power applications.
- Thermionic Emission:Electron gun assemblies utilizing dispenser cathodes and precision-wound helices constitute the heritage foundation of space-qualified amplification. Prime satellite manufacturers specify these units for missions exceeding fifteen-year operational lifetimes where accumulated flight history validates reliability predictions.
- Vacuum Electronic:Coupled-cavity and extended-interaction designs push power-density boundaries for Ka-band and millimeter-wave applications. NASA deep-space missions and ESA outer-planet probes specify these architectures where solid-state alternatives face fundamental thermal and radiation tolerance limitations.
- Semiconductor:Gallium nitride devices encroach on sub-100W satellite applications with improving efficiency metrics.
- Solid State:Phased-array compatible modules gain traction in electronically steered antenna systems for LEO constellations.
- Magnetron:Pulsed-power applications in specialized radar payloads retain niche demand despite limited spaceflight heritage.
Thermionic emission retains the installed base, though vacuum electronic architectures are expanding most quickly into high-power missions.
Application:
Customer type differentiation separates institutional programs with extended qualification timelines from commercial operators prioritizing rapid constellation deployment.
- Satellite Communications:Geostationary broadcast and broadband platforms drive recurring procurement volumes with standardized transponder configurations. Telecommunication providers in Japan and Germany anchor demand through long-term supply agreements with qualified vendors possessing domestic manufacturing capabilities.
- Deep Space Probes:Outer-planet missions impose extreme reliability requirements with operational lifetimes spanning decades and radiation exposure exceeding 100 krad(Si). ESA's expanding exploration program and NASA's Discovery-class missions specify ultra-high reliability X-band and Ka-band units with exhaustive environmental testing protocols.
- Radar Systems:Synthetic aperture and weather monitoring payloads employ specialized waveforms requiring wide instantaneous bandwidth.
- Earth Observation:Optical and radar imaging satellites represent mature demand where solid-state substitution pressures margins.
- Scientific Research:Space telescopes and planetary science instruments require ultra-stable phase noise characteristics for precision measurement.
Satellite communications commands the dominant share, while deep space probes are gaining share fastest on ESA and NASA mission expansion.
End User:
Volume concentration clusters around sovereign space programs with consolidated procurement authority and stringent qualification requirements.
- Space Agencies:NASA, ESA, and national programs in Japan operate direct contracting channels for qualified flight hardware. These institutional customers prioritize accumulated orbital performance data over cost optimization, creating stable demand pipelines for vendors with multi-decade flight heritage.
- Defense Contractors:Dual-use military-civil convergence in Europe harmonizes procurement specifications across classified and commercial programs. Thales and L3Harris sustain integrated supply relationships spanning satellite prime contracting through subsystem delivery.
- Telecommunication Providers:Commercial constellation operators drive demand for standardized, cost-optimized units with reduced qualification overhead.
- Research Institutions:University-led CubeSat and small-satellite missions experiment with miniaturized amplification approaches.
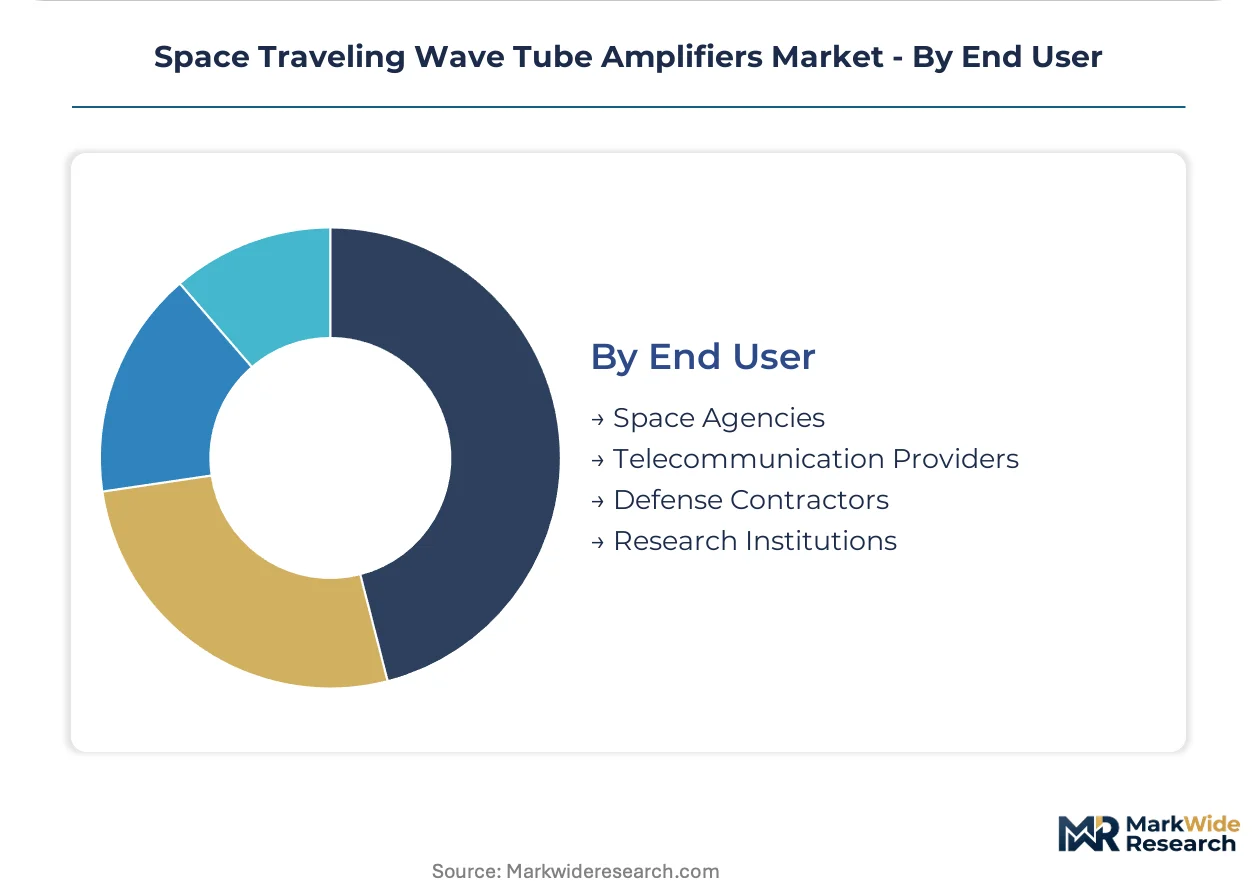
Space agencies retain the dominant share, while defense contractors are climbing the fastest on dual-use procurement harmonization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in space-qualified amplification hardware favor manufacturing bases with established space agency procurement relationships. Sovereign satellite programs in the United States, Germany, and Japan anchor import demand for flight-proven components. Domestic production capabilities in these markets concentrate around specialized vacuum electronics clusters with multi-decade heritage.
United States
NASA deep-space missions and LEO broadband constellation operators pull demand for high-power Ka-band and X-band units. FAA launch licensing requirements and ITAR export controls constrain foreign sales while privileging domestic suppliers with cleared manufacturing facilities. Los Angeles and Denver corridors host prime satellite manufacturers that contract directly with qualified amplifier specialists.
Germany
DLR institutional programs and European prime contractor supply chains anchor procurement of Ku-band and Ka-band flight hardware. ESA ECSS qualification standards mandate proton and heavy-ion radiation testing that extends lead times for geostationary missions. Bavaria and Baden-Württemberg concentrate precision manufacturing capabilities for helix winding and electron gun assembly.
Japan
JAXA exploration missions and commercial telecommunications satellite operators drive demand for ultra-high reliability amplification. METI industrial policy supports domestic production of space-qualified components to reduce import dependence. Tokyo and Nagoya metropolitan areas host integrated supply relationships spanning satellite prime contracting through subsystem delivery.
France
CNES earth observation programs and dual-use military-civil satellite initiatives harmonize procurement specifications across institutional and defense channels. CE marking and REACH compliance requirements shape material selection for specialized ceramics and high-purity tungsten. Toulouse and Paris-Saclay clusters anchor prime contractor engineering centers with direct contracting authority for qualified spares.
United Kingdom
UK Space Agency funding for small-satellite constellations and national security satellite programs generates demand for compact, cost-optimized amplification units. The country's national space regulator coordinates with ESA on harmonized reliability benchmarks. Harwell and Stevenage campuses concentrate payload engineering expertise with growing direct procurement from amplifier specialists.
Space Traveling Wave Tube Amplifiers Market Competitive Landscape
On the supply side, the industry is consolidating around vendors with accumulated orbital performance data and multi-decade flight heritage. Prime satellite manufacturers specify these suppliers for missions exceeding fifteen-year operational lifetimes. Three archetypes dominate: European institutional specialists with domestic manufacturing bases, U.S. defense contractors leveraging cleared facilities, and diversified aerospace conglomerates spanning civil and military programs. Competitive moves center on strategic partnerships with national space agencies and technology licensing for multi-stage depressed collector architectures.
Within the European institutional tier, Tesat-Spacecom GmbH & Co. KG represents German manufacturing-based supply relationships with ESA and DLR. Thales Group occupies a position spanning dual-use civil-military programs across European prime contractor channels. Among U.S.-based suppliers, L3Harris Technologies exemplifies defense contractor relationships and extensive space qualification history that anchor NASA and classified program access. These three entities sit within a vendor base where accumulated flight heritage serves as the primary barrier to competitive entry.
| Leading Market Players |
|---|
| Tesat-Spacecom GmbH & Co. KG |
| Stellant Systems |
| Thales Group |
| NEC |
| TMD Technologies |
| Communications & Power Industries |
| Teledyne Technologies |
| General Dynamics |
| L3Harris Technologies |
| Others |
Pricing and Supply Chain Analysis
Transatlantic air freight corridors connecting Bavaria to Los Angeles absorb elevated logistics costs for specialized ceramics and tungsten cathode assemblies, compressing margins for Ka-band amplifier shipments while enabling three-tier pricing stratification across heritage-qualified, radiation-tested, and commercial-grade product tiers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures with satellite prime manufacturers, where pricing stratifies across ESA-qualified heritage, radiation-hardened standard, and commercial-economy tiers differentiated by accumulated flight hours and thermal cycling documentation. Cost compression in commercial-economy tiers is intensifying because gallium nitride alternatives encroach on sub-100W applications, rendering telecommunication providers most price-sensitive while space agencies prioritize qualification over unit economics.
Supply Chain Analysis
Tariff exposure between the United States and European Union dominates strategic planning for vacuum electronic component flows, with specialized helix winding and electron gun assembly concentrated in Germany, Japan, and the United States. High-purity tungsten for dispenser cathodes, precision-machined ceramic insulators, and pyrolytic graphite heat sinks feed from limited qualified vendors, creating single-source vulnerability when ITAR restrictions fragment addressable customer pools. Distribution runs through direct agency contracting channels that bypass traditional prime-channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated buying desks at CNES and DLR are compressing supplier margins while elevating technical barriers, shifting bargaining power toward institutional anchor customers with multi-decade procurement horizons.
For Market Incumbents: Pre-empt solid-state substitution in lower-power tiers by accelerating multi-stage depressed collector deployment for Ka-band efficiency leadership, while securing captive supply of high-purity tungsten through backward integration into German ceramics clusters to neutralize input concentration risk. For New Entrants and Emerging Players: Build out radiation-hardening test capabilities targeting ESA's expanding outer-planet exploration program, where heritage documentation requirements are less stringent than geostationary applications and institutional budgets accommodate extended qualification timelines for novel vacuum electronic architectures. For Investors and Strategic Acquirers: Specialized vacuum electronics engineering boutiques with proton testing infrastructure and ECSS-E-ST-20-07C certification pathways represent priority acquisition targets, given five-to-ten year mission lifecycles that lock in recurring spares demand; monitor ESA Discovery-class mission award velocity as the inflection signal for qualification pipeline fill rates.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Stage Depressed Collector Integration | L3Harris and Thales push Ka-band efficiency past sixty percent for high-throughput satellites. |
| Radiation Hardness Assurance Certification | ESA ECSS-E-ST-20-07C compliance opens direct contracting channels bypassing prime markups. |
| Backward Integration into Tungsten Supply | German manufacturing clusters secure cathode assembly inputs against price volatility. |
| Dual-Use Military-Civil Qualification Harmonization | Thales amortizes development costs across European defense and commercial satellite programs. |
| On-Orbit Servicing Interface Standardization | Life-extension vehicle compatibility creates retrofit demand for qualified amplifier hardware. |
Research Methodology
The analysis maps Ku-band heritage hardware, Ka-band high-throughput units, X-band military payloads, and deep-space probe amplifiers, each validated through satellite prime procurement directors, ESA qualification engineers, vacuum electronics manufacturing specialists, and space agency contract officers. Primary interview intelligence triangulates against secondary sources including NASA technical standard publications, ESA ECSS qualification databases, FAA launch licensing records, and customs trade data for specialized ceramics and tungsten inputs. Bottom-up unit demand modeling reconciles with top-down sovereign program budget allocations.
Fixed assumptions across the projection horizon hold ITAR export control stringency, ESA radiation testing mandates, and gallium nitride performance trajectories within observed development curves. Segmentation dimensions span frequency band, thermionic versus vacuum electronic architecture, application mission class, and end-user procurement channel. CAGRs derive from satellite constellation deployment schedules and deep-space mission cadence modeled against amplifier replacement rates and new payload incorporation.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by gallium nitride foundries or relaxation of ITAR technology transfer restrictions would shift outcomes beyond modeled bounds. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Radiofrequency Identification (RFID) Market
RF Components
RFID Tags Market
RF Components
RF Components Market
RF Components
RF Microwave MLCC Market
RF Components
Europe Small Signal Transistor Market
RF Components
GPS Low Noise Amplifier Market
RF Components
Frequency Synthesizer Market
RF Components
Radio Frequency Front End Market
RF Components
RF Filters Market
RF Components
RF Passive Component Market
RF Components
RF Power Dividers Market
RF Components
Japan Small Signal Transistor Market
RF Components
Digital Radio Frequency Market
RF Components
RF Power Amplifiers Market
RF Components
Flat Panel Antenna Market
RF Components
Global Gan RF Devices Market