
 FBAR Devices Market | 2026-2036
FBAR Devices Market Size, Share, and Industry Trends Forecast 2026-2036
FBAR Devices Market Foresight
The divergence between premium integrated modules and commodity single-chip filters is repositioning supplier economics in the FBAR Devices Market. Qorvo leverages its captive GaN fab capacity to sustain margin structures on multi-chip arrays. Skyworks Solutions anchors North American smartphone RF front-end supply through module-level integration. Murata Manufacturing dominates ceramic packaging and filter miniaturization for Asian consumer electronics OEMs.
Film bulk acoustic resonators employ piezoelectric aluminum nitride thin films deposited on silicon substrates, vibrating at frequencies from 1 GHz to 10 GHz with quality factors exceeding 2,000 for RF filtering applications. These devices enable sharp bandpass characteristics essential for 5G base stations, Wi-Fi 6E routers, and automotive radar modules. Integrated modules command the deepest margin pools as OEMs consolidate front-end component counts, while custom devices for aerospace and defense applications retain pricing power through qualification barriers. Single-chip filters face volume pressure from Chinese suppliers but remain the default for cost-optimized IoT radios.
The FCC enforces stringent spurious emission limits under Part 15 rules, compelling filter vendors to tighten rejection specifications for unlicensed band devices. ETSI's harmonized standards in Europe mandate coexistence filtering for U-NII bands, shaping product development roadmaps for export-oriented manufacturers. China's MIIT imposes domestic testing protocols for cellular band filters entering its telecom infrastructure tenders. Stakeholders must monitor how national spectrum auctions redistribute filter demand across sub-6 GHz, mmWave, and Wi-Fi 7 frequency plans.
Market Dynamics
The FCC's Part 15 spurious emission rules and ETSI's U-NII coexistence mandates are compressing filter rejection tolerances, forcing foundries to retool deposition chambers for tighter aluminum nitride thickness control.
Growth Catalysts
- 5G Sub-6 GHz Deployment:Smartphone OEMs are expanding filter procurement for sub-6 GHz architectures, pulling bulk acoustic resonator demand into multi-band front-end modules.
- ETSI Harmonized Standards:European U-NII band coexistence filtering mandates are shaping product roadmaps for export-oriented manufacturers serving Wi-Fi 6E and Wi-Fi 7 ecosystems.
- Seoul RF Cluster Concentration:South Korea's foundry ecosystem around Seoul is concentrating thin-film deposition expertise, accelerating yield learning curves for piezoelectric stack optimization.
Market Restraints
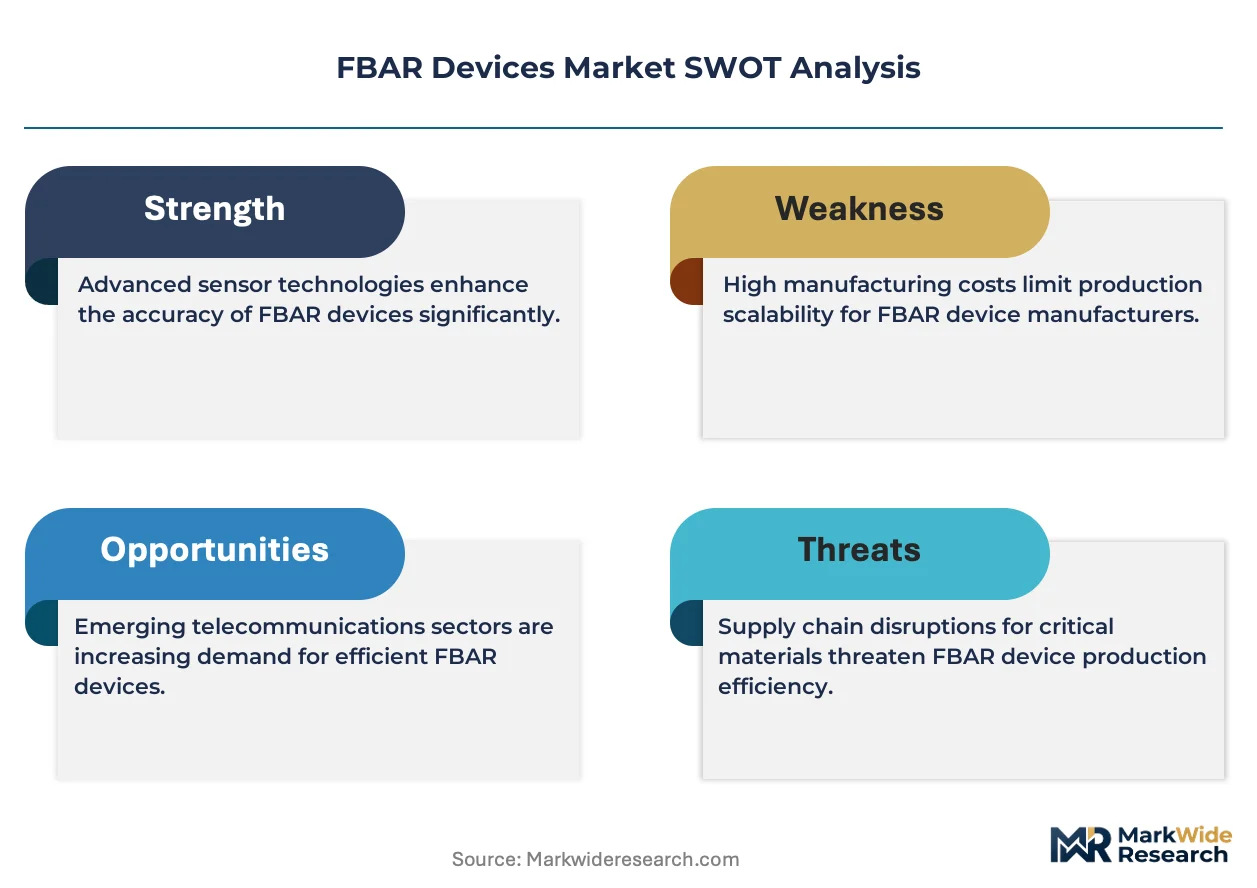
- Aluminum Nitride Supply Concentration:High-purity AIN sputtering target production concentrates among Japanese specialty ceramic suppliers, exposing filter foundries to input cost volatility and allocation risk.
- MIIT Domestic Testing Protocols:China's cellular infrastructure tenders impose domestic certification barriers that extend qualification timelines for foreign filter vendors.
- SAW Filter Substitution in IoT:Cost-optimized IoT radios continue defaulting to surface acoustic wave alternatives, capping FBAR penetration in sub-GHz license-exempt bands.
Strategic Opportunities
- Automotive Radar Module Integration:77-81 GHz radar filters for ADAS platforms represent an underpenetrated application requiring temperature-stable resonator architectures.
- India PLI Scheme Tailwinds:India's production-linked incentive scheme for telecom equipment is attracting module assembly investments that localize filter sourcing decisions.
- GaN-SOI Convergence:Integration of gallium nitride power amplifiers with silicon-on-insulator switches is creating demand for co-packaged filter arrays in transmit-receive modules.
Industry Challenges
- Piezoelectric Film Metrology Expertise:The scarcity of process engineers skilled in X-ray diffraction characterization of c-axis oriented aluminum nitride is constraining foundry expansion timelines.
- Multi-Band Certification Complexity:Each additional carrier aggregation band combination requires separate spurious emission validation, fragmenting qualification resources across regional carrier portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FBAR Devices Market |
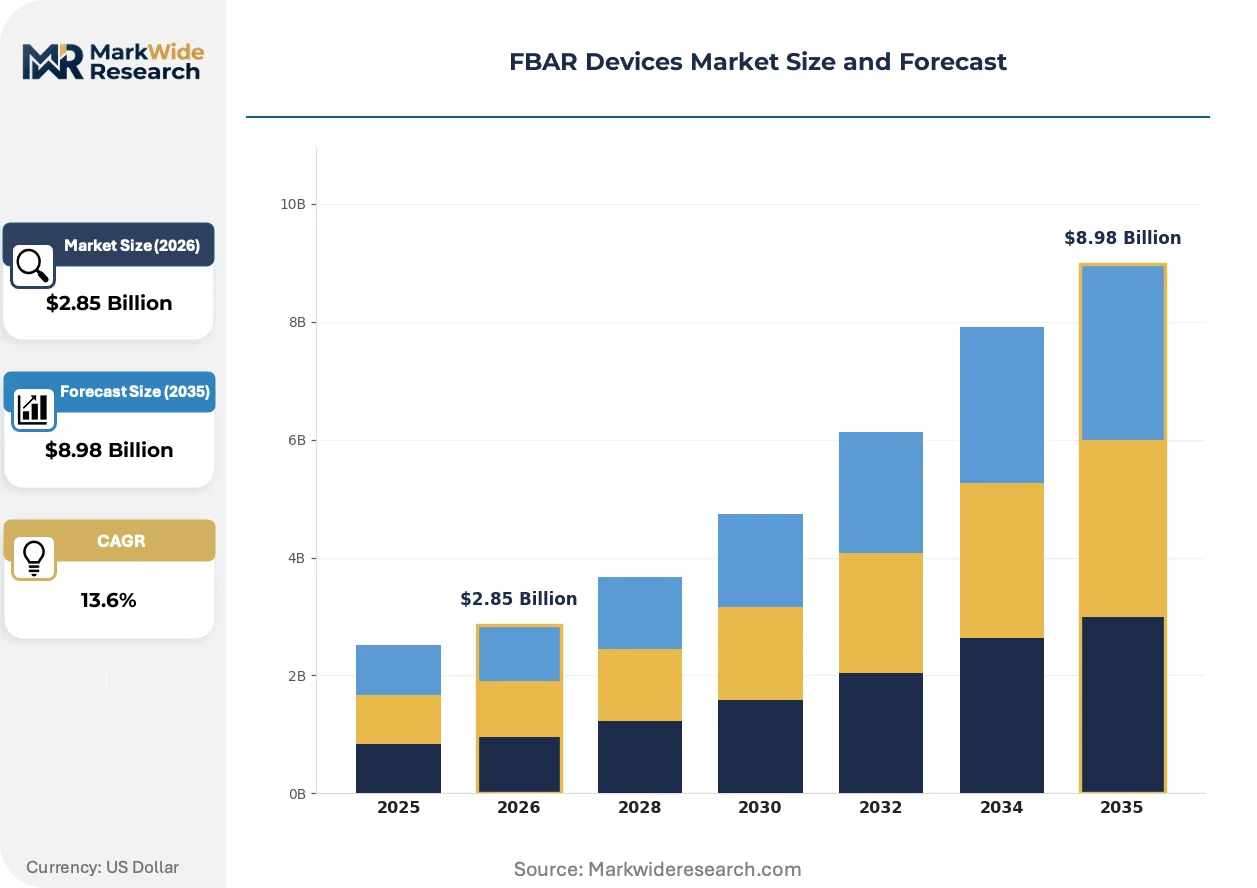
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $8.98 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Single Chip, Multi-Chip, Integrated Module, Custom Device End User: Telecommunications, Aerospace, Automotive, Consumer Electronics Technology: RF Filtering, Antenna Systems, Signal Processing, Power Management Application: Wireless Communication, Radar Systems, Medical Devices, High-Frequency Devices |
| Companies Covered | Qorvo, Skyworks Solutions, Qualcomm, Akoustis Technologies, Murata Manufacturing, Broadcom, Taiyo Yuden, Infineon Technologies, TDK Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FBAR Devices Market Shifts & Advancements
Deposition process control and packaging miniaturization are rewriting competitive differentiation in RF filtering. Three developments are compressing development cycles and reallocating value capture across the supply chain.
Scandium-doped aluminum nitride is rewriting frequency-temperature stability benchmarks for automotive and base station applications. Tier-one automotive radar suppliers are adopting ScAIN resonators for 77 GHz modules requiring sub-50 ppm drift across operational temperature ranges. This material transition is compressing the performance gap between FBAR and ceramic cavity filters in infrastructure markets.
ETSI's F-Gas Regulation is phasing out sulfur hexafluoride in plasma etching processes used for resonator cavity definition. European filter foundries are retrofitting etch chambers with fluorocarbon alternative chemistries, adding capital intensity to process transitions. Module suppliers serving EU telecom infrastructure tenders are prioritizing foundries with certified green process flows.
Consolidated front-end procurement is compressing supplier negotiation leverage. Smartphone OEMs are reducing qualified filter sources from six to three vendors per band class, concentrating volume commitments on module-integrated suppliers. This concentration is most visible in South Korea's device assembly ecosystem, where RF front-end consolidation has halved discrete filter procurement cycles.
FBAR Devices Market Segmentation
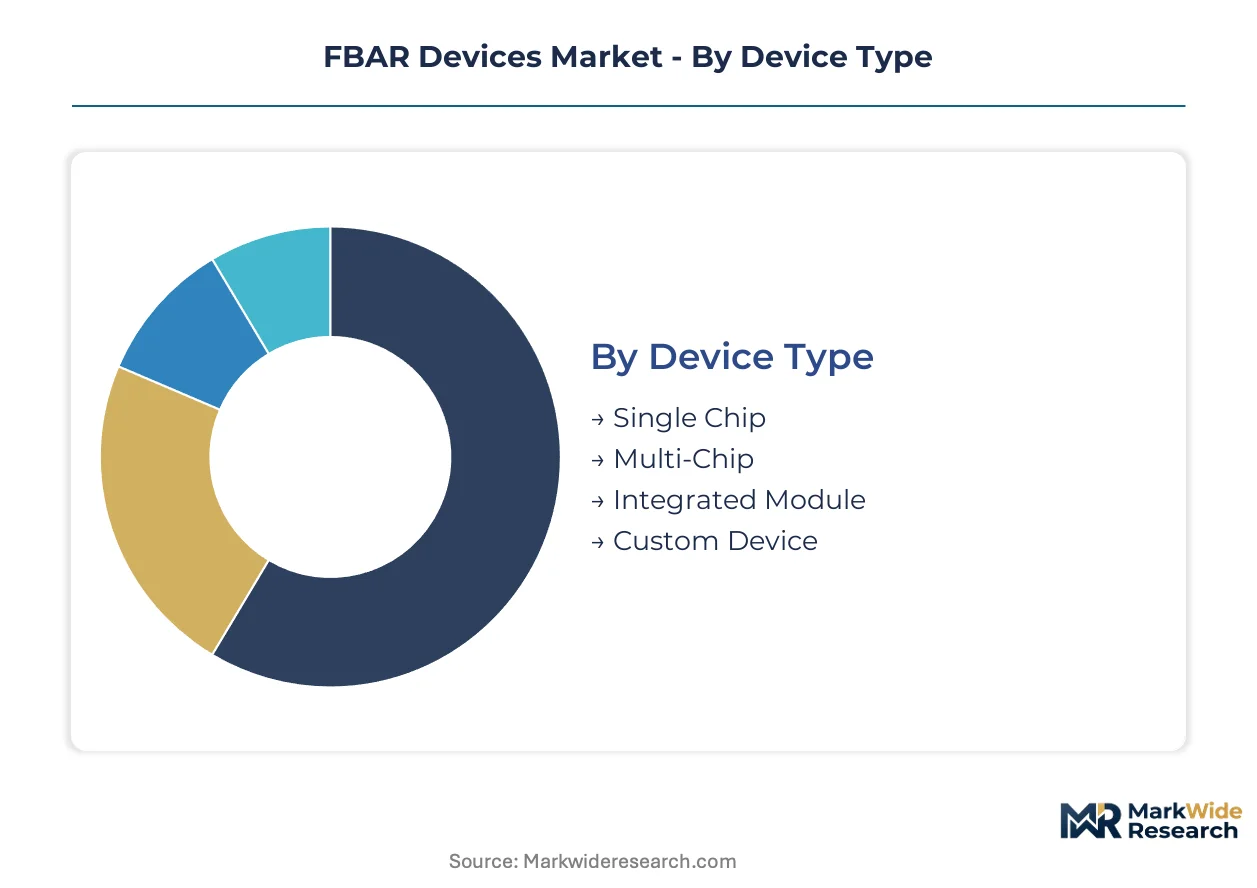
FBAR device segmentation reveals stark capital-intensity gradients across form factors and end-use verticals. Deposition chamber specifications, certification burdens, and customer consolidation patterns vary dramatically by segment, reshaping supplier economics and entry barriers.
Device Type:
Capital intensity escalates sharply from discrete single-chip filters to fully integrated modules, with deposition tool utilization and packaging complexity driving the spread.
- Integrated Module:Multi-resonator arrays co-packaged with switches and amplifiers require precision flip-chip bonding and hermetic ceramic enclosures. South Korean smartphone OEMs are consolidating procurement onto module-qualified suppliers, compressing vendor counts from six to three per band class.
- Custom Device:Aerospace and defense applications demand extended temperature-range qualification and ITAR-compliant traceability, sustaining pricing power through multi-year certification cycles. These specifications absorb disproportionate engineering resources relative to unit volumes.
- Multi-Chip:Hybrid assemblies combining FBAR filters with SAW devices for multi-band front-ends balance performance against die cost optimization.
- Single Chip:Discrete resonators for cost-optimized IoT radios face volume pressure from Chinese suppliers but remain the default for sub-GHz license-exempt bands.
Integrated modules absorb the bulk of installed capacity; custom devices are expanding most quickly through aerospace qualification pipelines.
End User:
Customer concentration and procurement scale diverge sharply across verticals, with telecommunications commanding volume commitments and automotive demanding automotive-grade reliability premiums.
- Telecommunications:5G base station and smartphone front-end procurement pulls the majority of FBAR wafer starts, with South Korea's RF cluster around Seoul concentrating thin-film deposition expertise for multi-band module supply.
- Automotive:ADAS radar modules at 77-81 GHz require ScAlN resonators with sub-50 ppm temperature drift, creating qualification barriers that filter out commodity suppliers.
- Consumer Electronics:Wi-Fi 6E and Wi-Fi 7 routers drive U-NII band coexistence filtering demand under ETSI harmonized standards.
- Aerospace:Satellite communication and military systems prioritize radiation-hardened specifications and extended operational lifecycles over unit cost.
Telecommunications absorbs the bulk of installed capacity; automotive is climbing the fastest on radar module integration timelines.
Technology:
Functional integration depth determines competitive differentiation, with RF filtering commanding the deepest technical moats and power management representing the newest application frontier.
- RF Filtering:Bandpass and band-reject characteristics with quality factors exceeding 2,000 enable sharp selectivity for cellular and unlicensed spectrum coexistence. FCC Part 15 spurious emission rules and ETSI U-NII mandates are compressing rejection tolerances, forcing foundry retooling for tighter aluminum nitride thickness control.
- Antenna Systems:Tunable matching networks and antenna-plexers integrate FBAR resonators with MEMS switches for adaptive impedance control.
- Signal Processing:Oscillator and mixer applications leverage FBAR frequency stability for low-phase-noise clock generation.
- Power Management:Emerging resonant converter topologies employ piezoelectric resonators for high-efficiency DC-DC conversion in mobile devices.
RF filtering absorbs the bulk of installed capacity; power management is gaining share fastest as converter architectures mature.
Application:
Frequency regime and environmental exposure define specification hierarchies, with radar systems demanding the most extreme thermal stability and medical devices imposing biocompatibility constraints.
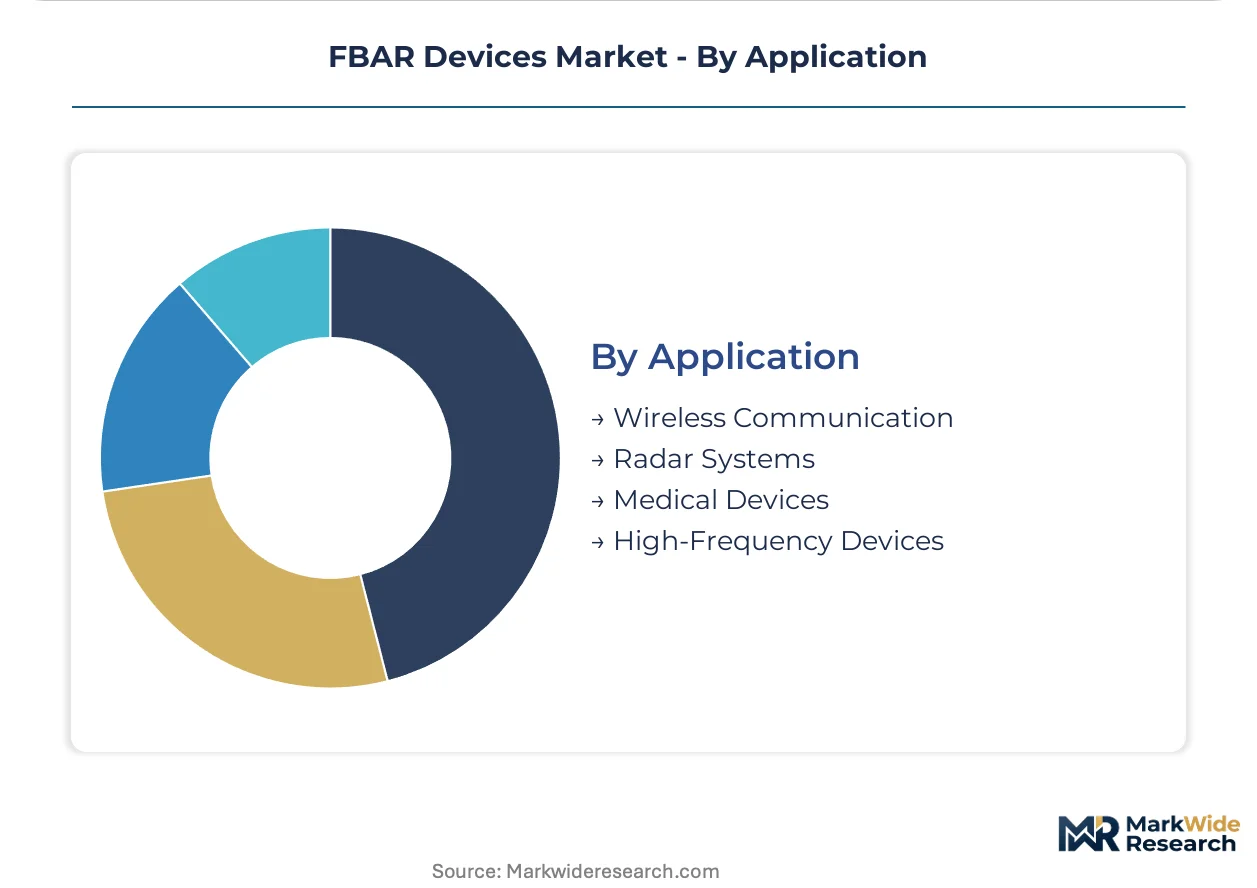
- Wireless Communication:Cellular handsets, base stations, and unlicensed spectrum equipment consume the majority of FBAR die output, with carrier aggregation band combinations fragmenting qualification resources across regional carrier portfolios.
- Radar Systems:77-81 GHz automotive and aerospace radar requires temperature-stable resonator architectures that ScAlN material transitions are now enabling.
- High-Frequency Devices:Test and measurement equipment and backhaul links push FBAR designs toward 10 GHz and beyond.
- Medical Devices:Implantable and wearable applications impose sterilization compatibility and hermetic longevity requirements distinct from consumer electronics specifications.
Wireless communication absorbs the bulk of installed capacity; radar systems are expanding most quickly on ADAS penetration curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors the densest concentration of FBAR foundry activity, with the capital region's RF component cluster housing thin-film deposition expertise that supplies smartphone OEMs and base station manufacturers across multiple continents.
United States
Smartphone RF front-end procurement and 5G base station deployment drive FBAR demand. FCC Part 15 spurious emission rules tighten filter rejection specifications for unlicensed band devices. Austin and Boston host design centers that architect multi-band front-end modules for North American carrier portfolios.
China
Domestic smartphone OEMs and telecom infrastructure tenders consume substantial filter volumes. MIIT imposes domestic testing protocols that extend qualification timelines for foreign vendors. Shenzhen and Shanghai concentrate module assembly operations that localize sourcing decisions for regional supply chains.
South Korea
Samsung and LG smartphone ecosystems pull bulk acoustic resonator demand into multi-band front-end modules. The national spectrum regulator shapes sub-6 GHz deployment timelines that filter procurement follows. Seoul's foundry corridor concentrates piezoelectric stack optimization expertise and yield learning curves.
Japan
High-purity aluminum nitride sputtering target production concentrates among specialty ceramic suppliers serving global filter foundries. METI oversees industrial standards that deposition equipment manufacturers adhere to. Kyoto and Osaka host materials suppliers that control critical input costs for resonator fabrication.
Germany
Automotive radar module integration for ADAS platforms creates demand for temperature-stable resonator architectures. ETSI F-Gas Regulation phases out sulfur hexafluoride in plasma etching processes, forcing foundry retooling. Munich and Stuttgart anchor automotive electronics development that specifies 77-81 GHz filter performance.
FBAR Devices Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and module integration capability. The vendor base stratifies between integrated module suppliers capturing smartphone front-end consolidation and discrete filter specialists serving cost-optimized IoT radios. Three archetypes dominate: captive GaN fab operators sustaining margin structures on multi-chip arrays; ceramic packaging specialists commanding miniaturization premiums; and deposition-focused foundries selling into merchant filter markets. Capacity expansion and strategic partnerships represent the dominant competitive vectors as OEMs reduce qualified sources per band class.
Within the integrated module tier, Qorvo and Skyworks Solutions occupy positions that exemplify the premium-margin archetype through front-end consolidation capture. Murata Manufacturing anchors the ceramic packaging and miniaturization specialist segment serving Asian consumer electronics OEMs. These three companies represent the competitive concentration that procurement consolidation has produced across sub-6 GHz and Wi-Fi ecosystem supply chains.
| Leading Market Players |
|---|
| Qorvo |
| Skyworks Solutions |
| Qualcomm |
| Akoustis Technologies |
| Murata Manufacturing |
| Broadcom |
| Taiyo Yuden |
| Infineon Technologies |
| TDK Corporation |
| Others |
Supply & Pricing Matrix
Module-integrated versus discrete-filter divergence separates premium-margin suppliers from commodity-margin competitors, with certification depth and deposition-tool utilization driving parallel spreads in both pricing power and supply chain configuration. FCC Part 15 spurious emission mandates and ETSI U-NII coexistence rules compress rejection tolerances for premium tiers, while Chinese SAW substitution caps pricing floors in sub-GHz IoT bands.
Pricing Analysis
Yield-based pricing anchors integrated module contracts, with foundries capturing premiums tied to piezoelectric stack consistency and hermetic ceramic enclosure reliability. Three-tier pricing structure across premium, standard, and economy levels separates ITAR-qualified aerospace suppliers from automotive-grade ScAlN adopters and cost-optimized single-chip vendors. Cost compression in discrete filters intensifies because Chinese suppliers expand wafer-start capacity for license-exempt IoT radios. Smartphone OEMs exhibit lowest price sensitivity for multi-band front-end modules; sub-GHz sensor manufacturers demonstrate highest sensitivity.
Supply Chain Analysis
Refurbishment flows for deposition chamber components concentrate in Japan and South Korea, where specialized ceramic suppliers reclaim high-purity aluminum nitride sputtering targets for resonator fabrication. Raw material dependencies center on Japanese specialty ceramics for AIN targets, German fluorocarbon chemistries for EU F-Gas-compliant etching, and Seoul-area foundries for piezoelectric stack optimization. Single-source vulnerability concentrates in high-purity AIN target supply, exposing filter foundries to allocation risk. Distribution runs through South Korean smartphone OEM module assembly hubs and Shenzhen telecom infrastructure tenders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smartphone front-end procurement consolidation from six to three qualified vendors per band class is squeezing weaker deposition-focused foundries from module supply chains. This concentration dynamic rewards scale and certification depth while penalizing discrete-filter specialists.
For Market Incumbents: Acquire captive GaN fab capacity to sustain margin structures on multi-chip transmit-receive modules as smartphone OEMs consolidate qualified sources. Defensive moves require deepening ITAR-compliant traceability for aerospace custom devices and accelerating ScAlN resonator qualification for automotive radar modules. SAW filter substitution in sub-GHz IoT bands threatens single-chip revenue pools; counter by expanding module-level integration for Wi-Fi 7 antenna-plexers. For New Entrants and Emerging Players: Capture India's PLI scheme tailwinds for telecom equipment module assembly, where localized sourcing decisions are decoupling from incumbent supply relationships. White-space targets include 77-81 GHz automotive radar filters for ADAS platforms and power management resonant converters for mobile DC-DC applications. Go-to-market leverage rests on deposition-tool partnerships with Seoul-area foundry clusters for yield-learning acceleration. For Investors and Strategic Acquirers: Re-rating potential sits with ceramic packaging specialists given ETSI F-Gas Regulation forcing European foundry retooling and green-process certification premiums. Long-term viability over the next decade favors suppliers with demonstrated multi-band carrier aggregation qualification pipelines and captive piezoelectric film metrology expertise. Monitor MIIT domestic testing protocol enforcement as inflection indicator for foreign vendor market access compression.| Strategic Initiative | Industry Significance |
|---|---|
| ScAlN Material Transition | Scandium-doped aluminum nitride enables sub-50 ppm temperature drift for automotive radar modules. |
| Green Process Certification | ETSI F-Gas Regulation compliance creates foundry differentiation for EU telecom infrastructure tenders. |
| Module Integration Expansion | Multi-resonator co-packaging with GaN power amplifiers captures smartphone front-end consolidation volume. |
| Deposition Tool Partnership | Seoul cluster alliances accelerate yield learning curves for piezoelectric stack optimization. |
| ITAR Traceability Investment | Extended qualification cycles sustain pricing power in aerospace and defense custom devices. |
Research Methodology
Document review covered SEC 10-K filings, FCC Part 15 enforcement records, ETSI harmonized standards documentation, and MIIT domestic testing protocols, complemented by interviews with RF front-end procurement managers at smartphone OEMs, deposition process engineers at foundry operations, ceramic packaging specialists, and automotive radar module suppliers. Secondary validation drew from trade customs data for aluminum nitride sputtering targets, semiconductor equipment utilization reports, and carrier aggregation band combination databases. Bottom-up wafer-start estimates triangulated against top-down smartphone RF front-end module revenue allocations.
Historical capacity expansion patterns cross-referenced against expert panel input on ScAlN adoption timelines and F-Gas Regulation compliance schedules shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include device type integration depth, end-user vertical certification requirements, technology functional layer, and application frequency regime. CAGRs derived from installed capacity growth rates, deposition-tool shipment forecasts, and module assembly expansion announcements. Industry-specific inputs encompassed carrier aggregation band proliferation curves and ADAS radar penetration assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MIIT protocol enforcement intensity, aluminum nitride target supply allocation decisions, and smartphone OEM module supplier consolidation velocity. Forecasts reflect documented assumptions regarding sub-6 GHz deployment timelines and ScAlN resonator yield maturation. Practitioners should monitor Seoul foundry cluster expansion announcements, ETSI F-Gas retrofit completion schedules, and India PLI scheme beneficiary lists for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
Gan RF Semiconductor Devices Market
RF Components
Wi-Fi Module Market
RF Components
5G Millimeter Wave RF Transceiver Market
RF Components
Global RF Power Semiconductor Market
RF Components
Europe Small Signal Transistor Market
RF Components
Low Noise Amplifier Market
RF Components
RF Front End Module Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
Frequency Synthesizer Market
RF Components
Digital Phase Shifter Market
RF Components
Global Gan RF Devices Market
RF Components
High Power RF Amplifier Module Market
RF Components
Multiband Booster Market
RF Components
Z-Wave Products Market
RF Components
RF Switches Market
RF Components
Microwave Devices Market