
 High Performance Fluoropolymers Market | 2026-2036
High Performance Fluoropolymers Market Size, Share, and Industry Trends Forecast 2026-2036
High Performance Fluoropolymers Market Intelligence
New capacity investments in China by domestic producers like DONGYUE Group are rebalancing the historical supply concentration from established Japanese and American manufacturers. The Chemours Company leverages its extensive patent portfolio in fluoropolymer chemistry. Meanwhile, Solvay specializes in specialty grades for demanding applications in aerospace and automotive. Daikin Industries sustains its market position through large-scale production and a diversified product offering.
High performance fluoropolymers are a class of polymers characterized by strong carbon-fluorine bonds, imparting exceptional chemical resistance and thermal stability. These properties make them essential for components that must withstand harsh environments in chemical processing and electronics manufacturing. Polytetrafluoroethylene (PTFE) constitutes a mature, high-volume product segment, while demand for melt-processable types like Perfluoroalkoxy (PFA) is rising. The semiconductor fabrication application offers significant margin potential due to its stringent purity requirements.
Regulations from the US EPA and the EU's ECHA under REACH place greater scrutiny on the lifecycle of certain fluorochemicals, including PFAS. These rules drive innovation towards materials with more favorable environmental profiles and influence market access. Navigating this evolving regulatory landscape while meeting performance demands for next-generation electronics will be the central challenge for material suppliers.
Market Dynamics
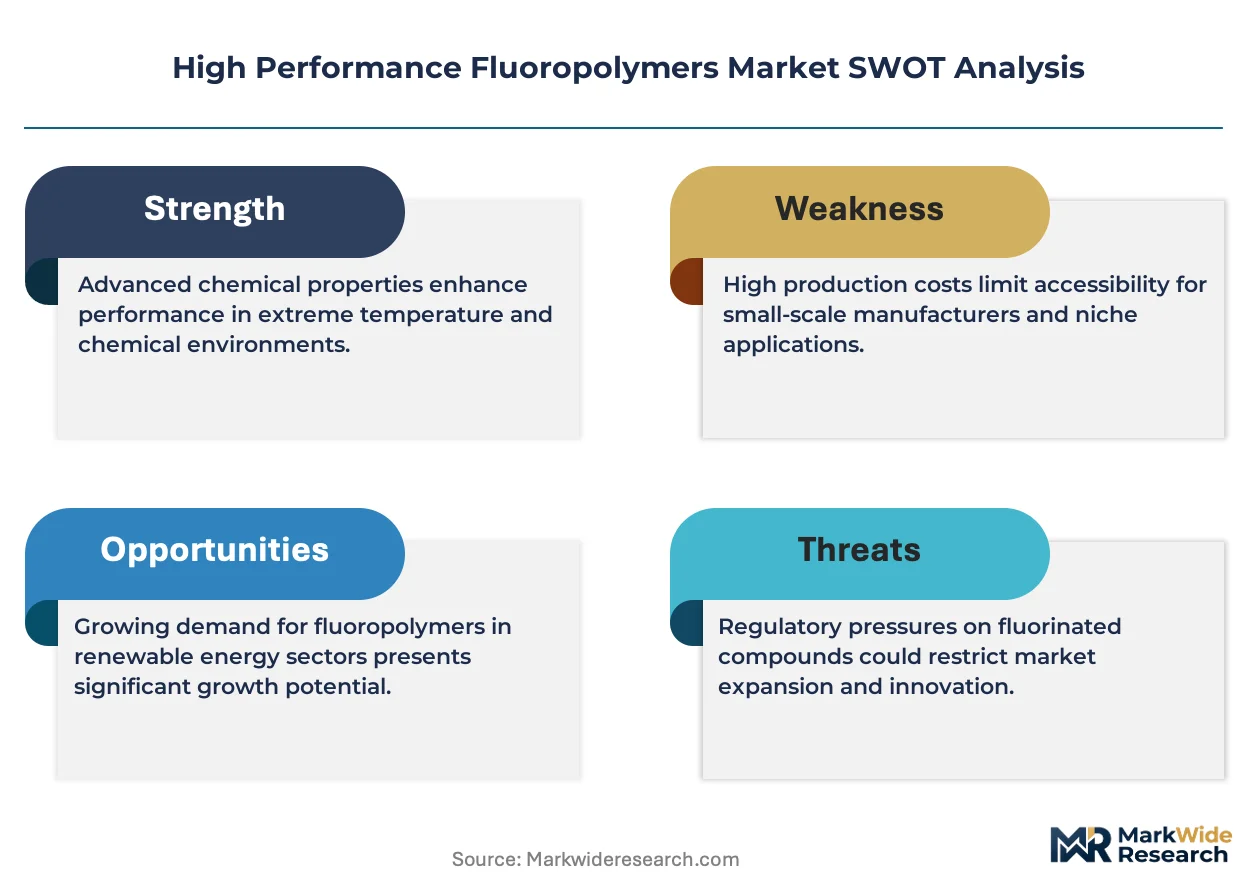
The central structural force shaping the high performance fluoropolymers market is the direct conflict between escalating performance demands from the semiconductor industry and intensifying global regulatory pressure on PFAS chemistries, including those governed by the EU's REACH framework.
Growth Catalysts
- Semiconductor Fabrication:Demand for ultra-high purity PFA and other melt-processable fluoropolymers for tubing, valves, and wafer carriers in advanced semiconductor fabs is a primary catalyst, particularly for sub-5nm process nodes.
- Aerospace and Defense Modernization:Requirements for materials with extreme thermal stability and chemical resistance in modern aircraft and defense systems in the United States and Europe drive consumption for wire insulation, seals, and fuel hoses.
- Electrification of Transport:The adoption of electric vehicles spurs demand for fluoropolymers as battery pack components, including gaskets and separator coatings, that require excellent dielectric properties and resistance to electrolyte chemicals.
Market Restraints
- Regulatory Scrutiny:Broad-scope regulatory actions by bodies like the US EPA and ECHA in Europe targeting PFAS create significant market uncertainty, threatening to restrict or ban certain fluorochemicals.
- Input Material Volatility:The market is subject to price fluctuations and supply constraints for key raw materials like fluorspar, the production of which is geographically concentrated and can be impacted by mining regulations.
- Threat of Substitution:In applications where performance requirements are less extreme, high costs and environmental concerns are driving end-users to evaluate alternative polymers like polyetheretherketone (PEEK) or polysulfones.
Strategic Opportunities
- Hydrogen Economy Components:The emerging hydrogen sector presents an opportunity for fluoropolymers in seals, gaskets, and membranes for fuel cells and electrolysis equipment, which require resistance to aggressive chemical environments.
- Advanced Medical Devices:The development of minimally invasive surgical tools and long-term implantable devices creates a niche for biocompatible grades of fluoropolymers that offer lubricity and chemical inertness.
- Circular Economy Innovations:Investment in advanced chemical recycling technologies to recover monomers from end-of-life fluoropolymer products offers a path to mitigate environmental concerns and create a more sustainable supply chain.
Industry Challenges
- Capital-Intensive Production:Constructing new fluoropolymer manufacturing plants, particularly for the high-purity grades required by the electronics industry, involves substantial capital investment and long lead times for commissioning.
- Navigating Global Regulations:Suppliers face the operational challenge of tracking and complying with a divergent and rapidly changing patchwork of national and regional chemical regulations, which complicates global trade.
- Specialized Talent Scarcity:A shortage of polymer scientists and chemical engineers with expertise in fluorochemistry can hinder research and development efforts for next-generation materials that meet new performance and environmental standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Performance Fluoropolymers Market |
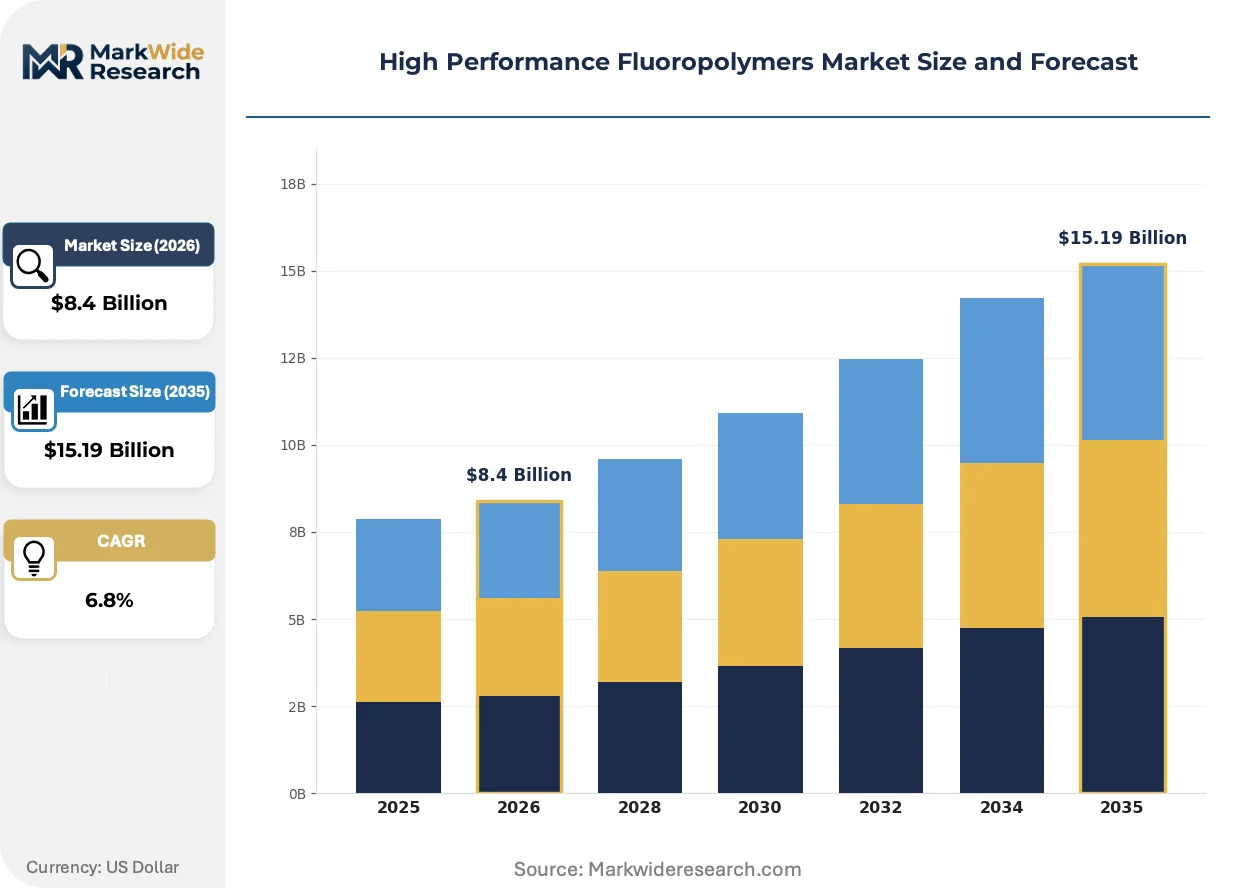
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polytetrafluoroethylene, Fluorinated Ethylene Propylene, Perfluoroalkoxy, Fluorinated Copolymers, Ethylene Tetrafluoroethylene Application: Electronics Manufacturing, Chemical Processing, Semiconductor Fabrication, Food Packaging, Aerospace Components End User: Electronics Manufacturers, Chemical Plants, Semiconductor Foundries, Packaging Producers, Aircraft Fabricators Form: Films, Tubes, Rods, Powders, Coatings |
| Companies Covered | AGC Chemicals, Arkema Group, Daikin Industries, DONGYUE Group, Saint-Gobain, The Chemours Company, 3M, Honeywell International, Solvay, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Performance Fluoropolymers Market Strategic Shifts & Innovations
Innovation in the fluoropolymer market is now intrinsically linked to lifecycle management and regulatory compliance. Material development is pivoting toward grades that deliver essential performance characteristics while presenting a more favorable environmental and health profile across their entire value chain.
Melt-processable fluoropolymers, particularly perfluoroalkoxy (PFA) and fluorinated ethylene propylene (FEP), offer superior fabrication flexibility compared to traditional PTFE. The semiconductor and chemical processing industries are accelerating adoption for manufacturing intricate components like convoluted tubing and injection-molded fittings. This technological shift is consolidating the market around materials that enable complex designs and automated manufacturing, reducing reliance on labor-intensive paste extrusion methods.
The European Chemicals Agency's (ECHA) proposal to restrict thousands of PFAS under the REACH framework represents a landmark regulatory shift. This measure forces a comprehensive re-evaluation of fluoropolymer use, pushing industries to justify applications as "essential" or find viable alternatives. The electronics and automotive sectors are most exposed, now actively engaging in regulatory advocacy and accelerating qualification programs for non-fluorinated materials where feasible.
A significant behavioral shift is underway as end-users in critical sectors now prioritize documented material purity and supply chain transparency. This change is disrupting conventional procurement models, favoring direct engagement with manufacturers who can provide extensive batch-level data and certificates of analysis. This trend is most visible in the semiconductor supply chains of South Korea and Japan, where process integrity depends on eliminating microscopic contaminants.
High Performance Fluoropolymers Market Segmentation
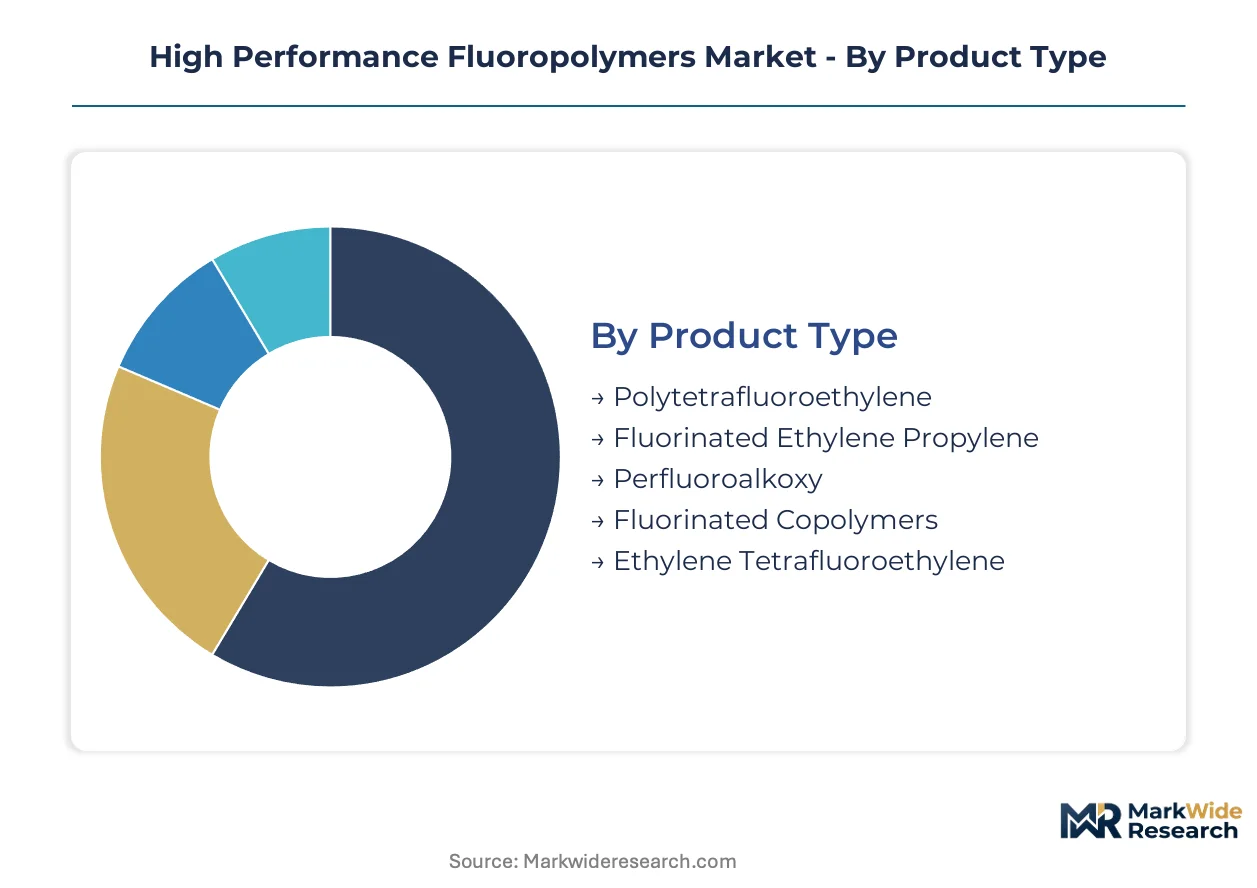
Segmentation within the high performance fluoropolymers market reveals distinct value propositions across specialized product forms and end-use applications. Understanding these granular divisions is critical for suppliers to align product development with stringent performance requirements. This analysis highlights specific material chemistries and their deployment in high-stakes environments.
Product Type:
The product type segmentation differentiates fluoropolymers based on their inherent chemical structures, which dictate their processing methods and suitability for integration into complex systems or standalone components.
- Polytetrafluoroethylene (PTFE):Polytetrafluoroethylene is a non-melt-processable fluoropolymer known for its exceptional chemical inertness and high thermal stability, derived from its robust carbon-fluorine bonds. Demand remains strong in chemical processing equipment and electrical insulation, driven by its unparalleled resistance to aggressive chemicals and high temperatures.
- Perfluoroalkoxy (PFA):Perfluoroalkoxy is a melt-processable fluoropolymer offering high purity and excellent chemical resistance, making it suitable for injection molding and extrusion processes. Its adoption is accelerating in semiconductor fabrication for ultra-high purity fluid handling components, where contamination control is paramount for sub-5nm process nodes.
- Fluorinated Ethylene Propylene (FEP):Fluorinated Ethylene Propylene provides melt-processability with good chemical resistance and electrical properties, finding use in wire insulation and laboratory ware.
- Fluorinated Copolymers:These materials combine properties of different fluoropolymers, offering tailored performance for specific applications like coatings and seals in harsh environments.
- Ethylene Tetrafluoroethylene (ETFE):Ethylene Tetrafluoroethylene is a tough, melt-processable fluoropolymer used for architectural membranes and electrical components requiring UV resistance.
Polytetrafluoroethylene leads volumes today; Perfluoroalkoxy is gaining share fastest.
Application:
This segment delineates fluoropolymer consumption based on the performance criticality and margin potential associated with each end-use environment.
- Semiconductor Fabrication:Fluoropolymers here require ultra-high purity and chemical inertness to prevent contamination of sensitive electronic materials and process fluids. Demand is concentrated in South Korea and Japan for components like tubing and wafer carriers, driven by semiconductor device miniaturization.
- Aerospace Components:Applications include wire insulation, seals, and fuel hoses that must endure extreme temperatures, corrosive fluids, and high vibration environments. Consumption is strong in the United States and Europe, propelled by modernization programs for military aircraft and the development of next-generation commercial airframes.
- Electronics Manufacturing:Fluoropolymers are used for insulation and protective coatings in various electronic devices, offering dielectric strength and chemical resistance.
- Chemical Processing:This sector utilizes fluoropolymers for linings, gaskets, and pipes due to their exceptional resistance to aggressive industrial chemicals.
- Food Packaging:Fluoropolymers provide non-stick and barrier properties for food contact surfaces and release films, ensuring product integrity and hygiene.
Semiconductor Fabrication exhibits the steepest expansion trajectory, while Chemical Processing maintains consistent baseline demand.
End User:
This segmentation reflects the diverse purchasing behaviors and technical requirements of various industrial customers for high performance fluoropolymer products.
- Semiconductor Foundries:These end-users demand fluoropolymers with ultra-high purity certifications and consistent batch-to-batch quality for critical process equipment. Procurement often involves direct engagement with manufacturers to ensure supply chain transparency and traceability, particularly in East Asian manufacturing hubs.
- Aircraft Fabricators:Aircraft fabricators require fluoropolymers meeting rigorous aerospace specifications for fire resistance, thermal stability, and mechanical strength. Demand originates from major original equipment manufacturers in the United States and Europe, driven by long product lifecycles and stringent safety standards.
- Electronics Manufacturers:These companies integrate fluoropolymers into various components like cables and circuit boards for their electrical insulation and protective qualities.
- Chemical Plants:Chemical plants utilize fluoropolymers for corrosion-resistant linings, seals, and piping systems in aggressive acidic or alkaline environments.
- Packaging Producers:Packaging producers apply fluoropolymers in non-stick coatings and barrier films for food, pharmaceuticals, and industrial products.
Semiconductor Foundries and Aircraft Fabricators represent high-value segments, while Chemical Plants serve volume-driven markets.
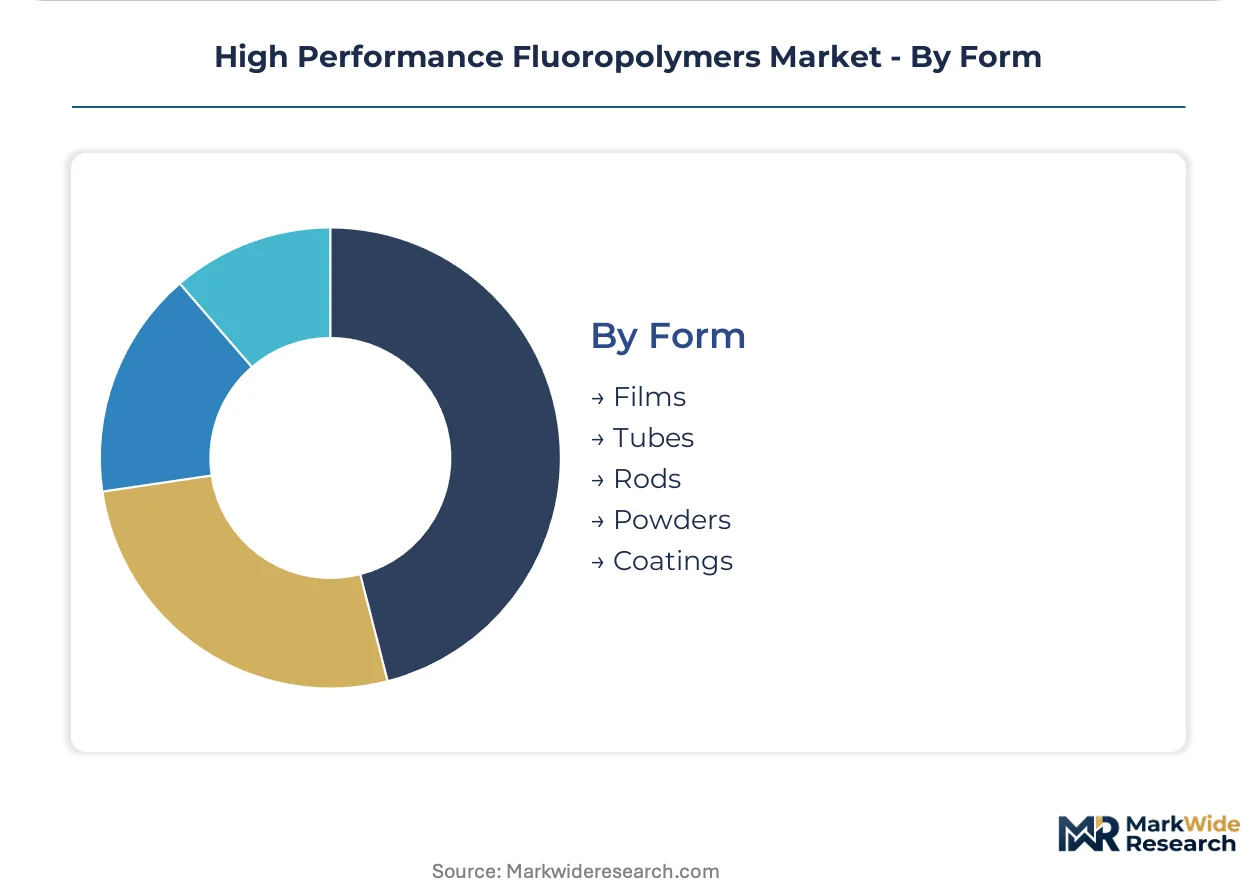
Form:
This category differentiates fluoropolymer products based on their physical form, which directly influences their processing methods and final application suitability.
- Films:Fluoropolymer films are thin, flexible sheets providing excellent chemical resistance, dielectric properties, and barrier characteristics. Demand is high in electronics for insulation and flexible circuits, and in architecture for lightweight, weather-resistant structural elements in Europe.
- Tubes:Fluoropolymer tubes, often melt-processed, are critical for fluid handling in environments requiring high purity and chemical inertness. The semiconductor industry in South Korea drives significant consumption for ultra-pure fluid transfer lines, where contamination-free transport is essential.
- Rods:Fluoropolymer rods are solid forms used for machining into seals, gaskets, and other custom components requiring high mechanical strength.
- Powders:These are raw material forms of fluoropolymers, processed into finished goods through techniques like compression molding or ram extrusion.
- Coatings:Fluoropolymer coatings provide non-stick, corrosion-resistant, and low-friction surfaces for industrial equipment and consumer products.
Films offer broad versatility across multiple sectors, while Tubes are indispensable for specialized fluid handling applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage influences the high performance fluoropolymers market, as producers seek jurisdictions with more favorable environmental compliance costs. This dynamic shifts manufacturing footprints and supply chain resilience globally. Demand for high-purity materials remains strong in advanced manufacturing hubs.
South Korea
South Korea's semiconductor industry drives significant demand for ultra-high purity PFA for fluid handling. The MFDS enforces strict material quality standards for critical components. Major foundries in Gyeonggi Province, including those in Suwon and Hwaseong, continuously upgrade process equipment.
United States
Demand in the United States stems from aerospace modernization and advanced electronics manufacturing. The US EPA regulations on PFAS are pushing innovation towards safer alternatives. Silicon Valley and aerospace clusters in Washington state require specialized fluoropolymer grades.
China
China's domestic electronics and chemical processing sectors fuel a substantial portion of fluoropolymer consumption. SAMR standards are increasingly influencing material specifications and local production. New production facilities in Jiangsu and Zhejiang provinces are expanding capacity rapidly.
Germany
Germany's automotive and chemical industries require high-performance fluoropolymers for seals and coatings. ECHA's REACH framework significantly impacts material selection and market access for fluorochemicals. The Rhine-Main region, a chemical industry hub, leads in specialty fluoropolymer applications.
Japan
Japan maintains robust demand from its advanced semiconductor and electronics manufacturing bases. METI guidelines encourage the development of environmentally sustainable materials. Industrial parks in Kyushu and Tohoku regions focus on precision fluoropolymer components.
High Performance Fluoropolymers Market Key Industry Players
Established producers occupy the standard tier, while emerging entrants pursue niche applications in advanced electronics and green energy. The market structure exhibits a tiered consolidation, with a few large integrated players and many specialized manufacturers. Strategic archetypes include diversified chemical giants, specialized fluoropolymer producers, and regional pure-plays. Dominant competitive moves involve capacity expansion and strategic partnerships for technology development.
Within the diversified chemical giants archetype, The Chemours Company leverages its extensive patent portfolio in fluoropolymer chemistry. Daikin Industries sustains its market position through large-scale production and a diversified product offering across various forms. DONGYUE Group, a Chinese producer, represents the emerging entrants expanding new capacity to rebalance historical supply concentrations.
| Leading Market Players |
|---|
| AGC Chemicals |
| Arkema Group |
| Daikin Industries |
| DONGYUE Group |
| Saint-Gobain |
| The Chemours Company |
| 3M |
| Honeywell International |
| Solvay |
| Others |
Cost & Logistics Intelligence
Fluorspar commodity prices directly influence the cost structure of high performance fluoropolymers, cascading through the supply chain into distinct pricing tiers for specialized grades. This volatility impacts producer margins and procurement strategies across end-use industries.
Pricing Analysis
Direct-to-OEM discount structures define pricing for high-purity fluoropolymers in critical applications. Contract-based long-term offtake agreements dominate for specialized grades, with high-purity certification and customization level driving differentiation. Pricing pressure stems from intensifying regulatory scrutiny on PFAS chemistries, compelling investment in compliant alternatives. Semiconductor Foundries exhibit the lowest price sensitivity due to extreme performance demands, contrasting with more price-sensitive chemical processing buyers.
Supply Chain Analysis
Advanced chemical recycling initiatives for end-of-life fluoropolymer products represent a nascent reverse-logistics flow, aiming to mitigate environmental concerns. Supply concentrates in China with new production, alongside established players in Japan and the United States. The supply chain relies on geographically concentrated fluorspar and specialized fluorine-containing intermediates. Regulatory restrictions on PFAS represent a significant structural risk, while direct sales to major OEMs characterize distribution for high-purity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The high performance fluoropolymers market presents a clear margin-expansion story driven by the increasing demand for ultra-high purity PFA in advanced semiconductor fabrication. This shift towards premium-tier materials commands higher pricing and specialized production.
For Market Incumbents:
To counter intensifying regulatory scrutiny on PFAS chemistries and the threat of substitution, incumbents must accelerate R&D into next-generation, environmentally favorable fluoropolymer grades. Strategic capacity additions for ultra-high purity PFA in key regions like South Korea will reinforce market position. Investing in advanced certification processes for new materials ensures continued market access in regulated sectors.
For New Entrants and Emerging Players:
Specialized distributors focusing on niche applications offer new entrants a viable pathway into the high performance fluoropolymers market. Targeting emerging segments like hydrogen economy components and advanced medical devices presents white-space opportunities. Developing biocompatible grades for minimally invasive surgical tools or membranes for fuel cells provides a focused go-to-market angle.
For Investors and Strategic Acquirers:
Asymmetric upside sits with vertically integrated specialists possessing proprietary fluoropolymer chemistries and advanced processing capabilities. The long-term viability remains strong, driven by essential roles in next-generation electronics. Target acquisition profiles should include firms with robust patent portfolios in sustainable fluorochemistry or expertise in ultra-high purity PFA production. Practitioners should monitor regulatory shifts for PFAS exemptions as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for PFA | Supports growing demand for ultra-high purity PFA in South Korean semiconductor fabs. |
| R&D for PFAS Alternatives | Addresses evolving EU REACH regulations and mitigates future market uncertainty. |
| Long-term Supply Agreements | Secures consistent material flow for critical aerospace and defense modernization programs. |
| Green Manufacturing Transition | Enhances environmental profiles, meeting sustainability targets for automotive battery components. |
| Joint Ventures in New Applications | Accelerates market entry into hydrogen economy and advanced medical device sectors. |
Research Approach
Direct dialogue with R&D directors at fluoropolymer companies, procurement leads at semiconductor foundries, and aerospace material engineers informed qualitative insights. This primary research was rigorously validated through comprehensive secondary data sources, including EU ECHA reports, US EPA publications, and relevant industry association documents. A triangulated approach, combining bottom-up market sizing with top-down validation, ensured robust data integrity.
A bottom-up analytical framework, complemented by top-down validation, projected market trends across the analysis window. The study modeled segmentation dimensions including product type, application, end user, form, and regional regulatory clusters. Compound annual growth rates were derived through a regression analysis of historical growth patterns. Key forecast inputs included semiconductor fab investment cycles and new vehicle electrification targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to unforeseen regulatory bans or rapid material substitution. These forecasts reflect assumptions regarding technological advancements and market dynamics. Practitioners should monitor ECHA decisions and new material qualification timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
High Friction Films Market
High-Value Chemicals
Europe Fine Chemical Market
High-Value Chemicals
Global 1-Hexanol Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
High Purity Isobutylene (HPIB) Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market