
 Ammonium Metavanadate Market | 2026-2036
Ammonium Metavanadate Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Metavanadate Market Analysis
The Ammonium Metavanadate Market is pivoting on a widening split between pharmaceutical-grade precision and industrial-grade volume plays. Premium tiers now command purity thresholds above 99.5 percent with full traceability chains, while commodity segments compete on vanadium unit cost alone. Largo Resources Ltd leverages its captive Brazilian mine-to-oxide pipeline to anchor supply security for specialty chemical buyers. U.S. Vanadium LLC sustains a differentiated position through electrolyte-grade material streams tied to North American vanadium redox battery demand. Bushveld Vanchem Ltd competes from Southern African feedstock, navigating logistics complexity with integrated roasting and leaching infrastructure.
Ammonium metavanadate is a water-soluble inorganic salt with the formula NH4VO3, typically synthesized via neutralization of vanadium pentoxide with aqueous ammonia followed by controlled crystallization at pH 6-8. The compound serves primarily as a precursor for vanadium catalysts, ceramic pigments, and high-purity vanadium oxides used in metallurgical and energy storage applications. Technical Grade material dominates current volume flows, though Research Grade segments command disproportionate margin pools due to stringent impurity specifications below 100 ppm total metals. Catalyst applications lead absolute consumption, while Laboratory Reagents represent the fastest-expanding demand vector driven by materials science and electrochemistry research programs.
Regulatory oversight spans OSHA workplace exposure limits for vanadium compounds in the United States, REACH registration requirements for European chemical importers, and China's GB standards for hazardous chemical classification and storage. These frameworks collectively elevate compliance costs for smaller traders while favoring producers with certified quality management systems and documented environmental controls. Stakeholders must monitor evolving battery-grade material specifications, as vanadium redox flow battery manufacturers tighten precursor purity requirements ahead of utility-scale deployment decisions.
Market Dynamics
Vanadium redox flow battery manufacturers are tightening precursor purity specifications ahead of utility-scale deployment decisions, forcing ammonium metavanadate suppliers to bifurcate between battery-grade and commodity-grade production lines.
Growth Catalysts
- Steel Micro-Alloying:High-strength construction grades in China and Japan now specify vanadium micro-alloying for rebar and structural beams, creating sustained feedstock demand.
- REACH Registration:European chemical importers face mandatory registration requirements that favor certified producers with documented environmental controls and quality management systems.
- East Asian Catalyst Clusters:Japanese and South Korean specialty chemical manufacturers concentrate catalyst precursor procurement around verified supply chains with full traceability documentation.
Market Restraints
- Vanadium Pentoxide Volatility:Feedstock prices fluctuate with steel industry slag recovery rates and primary mining output from South African and Brazilian deposits.
- Chinese Supply Concentration:Over half of global vanadium extraction capacity sits within Chinese state-owned enterprises, creating geopolitical exposure for non-domestic buyers.
- Technical Substitution:Alternative catalyst precursors including molybdenum and tungsten compounds compete in certain petrochemical cracking applications.
Strategic Opportunities
- Indian Specialty Chemical Expansion:CDSCO-regulated pharmaceutical intermediates manufacturing is attracting vanadium catalyst investments near Mumbai and Hyderabad chemical corridors.
- EU Green Deal Alignment:Battery-grade material specifications under the European Critical Raw Materials Act create preferential procurement channels for certified low-carbon extraction pathways.
- Direct-to-Battery Channel Formation:Vanadium redox flow battery integrators are bypassing traditional chemical distributors to secure long-term offtake agreements directly with oxide producers.
Industry Challenges
- Analytical Chemistry Talent Scarcity:Battery-grade specification testing requires ICP-MS and XRF expertise that remains concentrated in legacy metallurgical laboratories.
- Roasting Asset Intensity:Converting vanadium slag or ore to soluble pentoxide demands capital-intensive rotary kiln infrastructure with multi-year commissioning timelines.
- Multi-Jurisdiction Certification Overlap:Producers serving both OSHA-regulated US facilities and GB standards-compliant Chinese operations face duplicative audit burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Metavanadate Market |
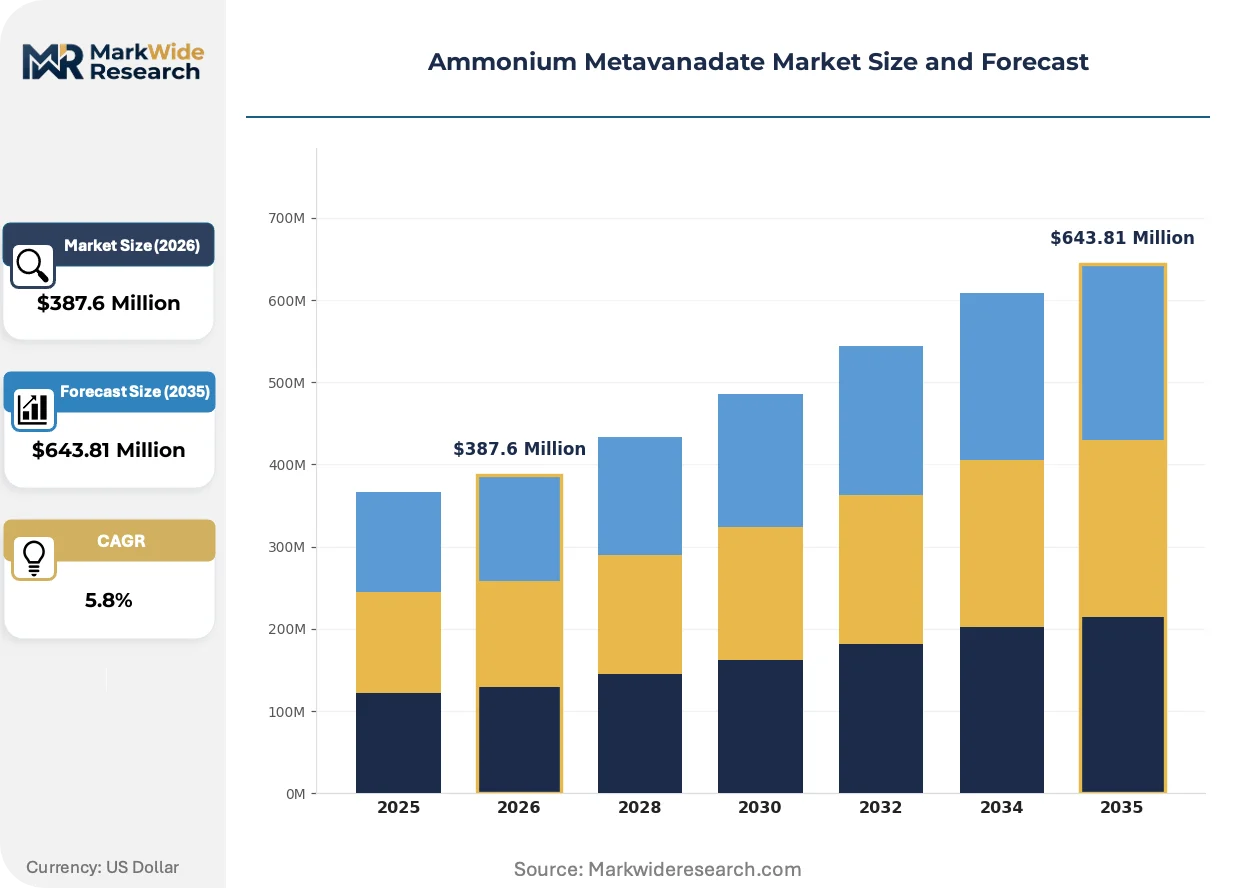
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Research Grade, Industrial Grade, Pharmaceutical Grade Application: Catalysts, Pigments, Chemical Synthesis, Laboratory Reagents End User: Manufacturers, Research Institutions, Pharmaceuticals, Educational Institutions Form: Powder, Crystals, Granules, Aqueous Solution |
| Companies Covered | Largo Resources Ltd, U.S. Vanadium LLC, Angang Steel Company Limited, Merck KGaA, American Elements, Bushveld Vanchem Ltd., Taiyo Koko Co., Ltd., Thermo Fisher Scientific, Ferro-Alloy Resources Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Metavanadate Market Emerging Trajectories
Solvent extraction and crystallization control technologies are converging to enable single-digit ppm impurity levels, while regulatory frameworks in major economies accelerate differentiation between commodity and premium material tiers.
Membrane electrolysis for vanadium electrolyte production is unifying upstream oxide processing with downstream battery manufacturing, eliminating intermediate ammonium metavanadate handling steps. North American vanadium redox flow battery developers are piloting this integration at demonstration scale. The structural consequence is compressing margins for standalone chemical processors who lack captive battery partnerships.
China's dual carbon goals and tightening MEE emissions protocols are redirecting vanadium feedstock priorities toward cleaner extraction pathways, particularly slag recovery and stone coal processing with flue gas desulfurization. Domestic producers face mandatory carbon intensity disclosures by 2026. Battery-grade material streams are responding with dedicated low-carbon certification tracks separate from commodity oxide flows.
Japanese and South Korean catalyst manufacturers now require full batch traceability from mine to crystallization, displacing spot-market procurement with multi-year framework agreements. Chemical distributors in Osaka and Ulsan are consolidating around integrated logistics providers who can document chain-of-custody. This behavioral shift concentrates procurement power among vertically integrated oxide producers with captive mining assets.
Ammonium Metavanadate Market Segmentation
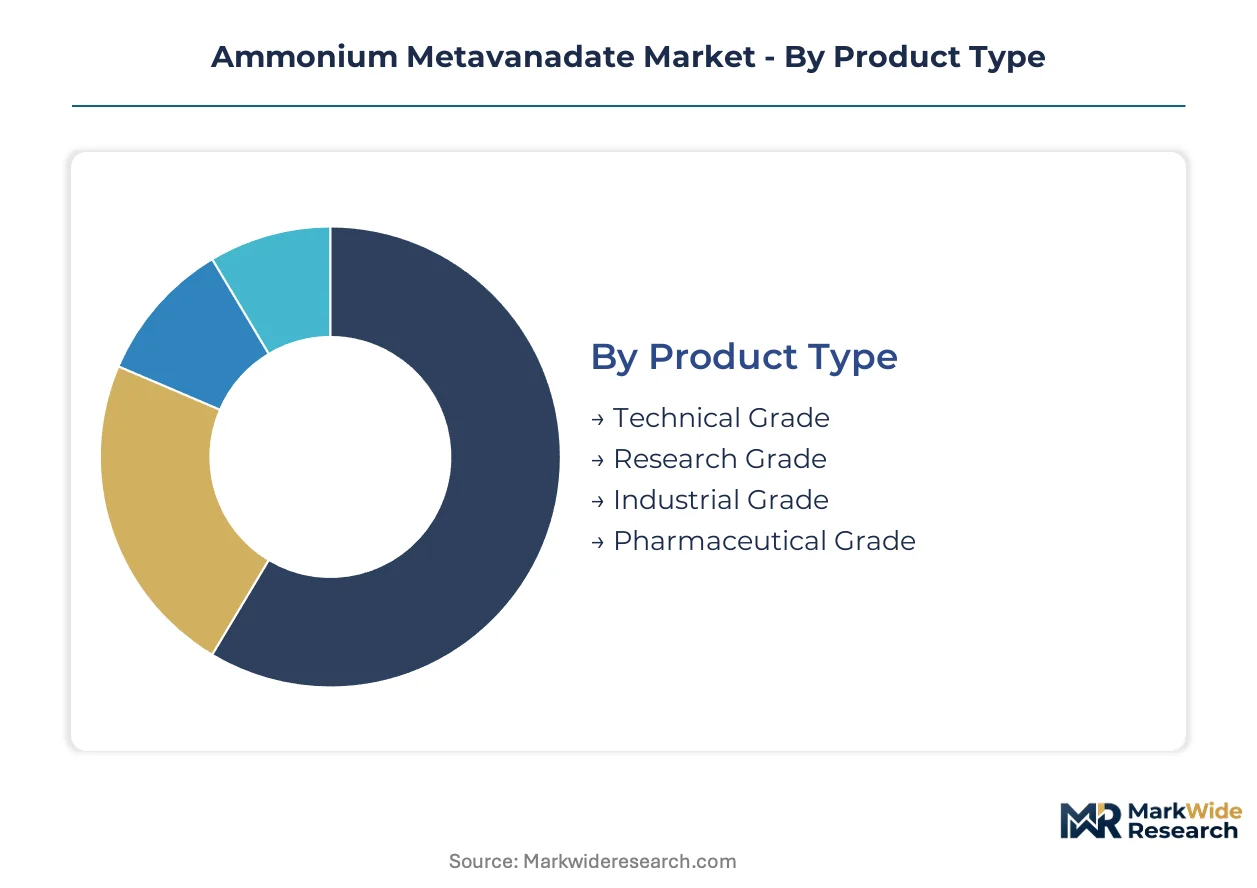
Ammonium metavanadate suppliers face divergent margin structures across purity tiers, with battery-grade specifications commanding certification premiums while commodity grades compete on vanadium unit economics. Segmentation discipline separates volume plays from precision chemistry opportunities.
Product Type:
Volume flows concentrate in industrial-grade channels, while premium tiers extract value through impurity control and documented traceability chains.
- Technical Grade:Material with total metallic impurities between 100-500 ppm serves catalyst manufacturers and ceramic pigment producers in Chinese and Japanese industrial clusters. Specifications align with GB standards for hazardous chemical classification, creating compliance barriers for uncertified traders.
- Research Grade:Purity thresholds above 99.5 percent with batch-level certificates of analysis support electrochemistry programs at MIT, Tsinghua University, and Tokyo Institute of Technology. Demand concentrates where ICP-MS verification is mandatory for publication-grade reproducibility.
- Industrial Grade:Bulk material for steel micro-alloying and vanadium pentoxide conversion carries the heaviest tonnage flows through Rotterdam and Shanghai port terminals.
- Pharmaceutical Grade:CDSCO and FDA-compliant material for vanadium-based insulin mimetics and diagnostic reagents requires endotoxin testing and sterile processing documentation.
Today's leader: Technical Grade. Tomorrow's challenger: Pharmaceutical Grade.
Application:
End-use diversification spreads risk across cyclical steel demand and emerging energy storage procurement.
- Catalysts:Fluid catalytic cracking and selective oxidation processes at South Korean and Japanese petrochemical complexes consume the largest absolute volumes. Mitsubishi Chemical and LG Chem specify full vanadium chain-of-custody documentation.
- Laboratory Reagents:Materials science departments and battery research consortia in Germany, the United States, and China drive the steepest expansion trajectory for high-purity material.
- Pigments:Ceramic colorants for construction materials in India's Gujarat and Maharashtra states utilize technical-grade feedstock with iron and chromium tolerance windows.
- Chemical Synthesis:Precursor demand for vanadium redox flow battery electrolyte production is consolidating around direct oxide-to-electrolyte pathways, compressing intermediate chemical processor margins.
Catalyst applications anchor current revenue. Laboratory reagents are climbing the fastest.
End User:
Procurement authority fragments between centralized manufacturing buyers and dispersed institutional purchasing.
- Manufacturers:Steel additive producers and catalyst formulators in Hebei province and the Ruhr region negotiate long-term offtake agreements with Brazilian and South African mine-oxide integrators.
- Research Institutions:National laboratories and university consortia in the United States, Japan, and Germany require small-lot flexibility with expedited analytical certification.
- Pharmaceuticals:Generic API producers in Hyderabad and Mumbai chemical corridors source pharmaceutical-grade material under CDSCO active pharmaceutical ingredient guidelines.
- Educational Institutions:Undergraduate chemistry programs represent price-sensitive demand served through regional chemical distributors with consolidated shipping.
Manufacturers dominate procurement volume. Research institutions are gaining share fastest.
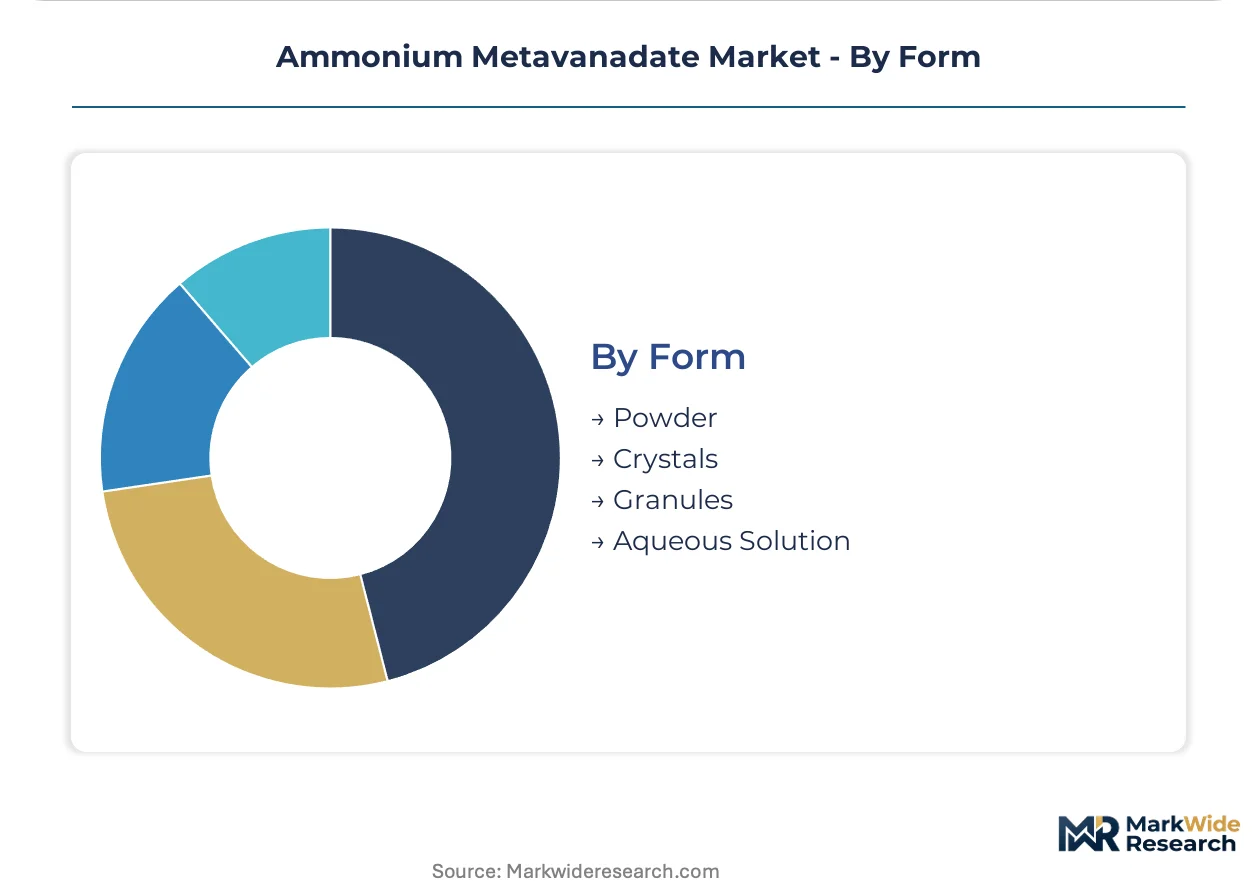
Form:
Physical presentation determines handling infrastructure requirements and shipping economics.
- Powder:Fine particulate with high surface area serves catalyst impregnation and rapid dissolution applications at BASF and Johnson Matthey production facilities.
- Crystals:Controlled crystallization at pH 6-8 yields free-flowing material preferred for precise weighing in analytical laboratories and pharmaceutical formulation.
- Granules:Compacted forms reduce dust exposure during steel mill additive handling and meet OSHA workplace exposure limit protocols.
- Aqueous Solution:Pre-dissolved material eliminates crystallization steps for battery electrolyte manufacturers and continuous-flow chemical synthesis operations.
Powder leads industrial consumption. Aqueous solution is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists and metallurgical engineers concentrate in legacy industrial corridors, anchoring regional production capabilities and quality certification infrastructure.
China
Hebei province steel additive producers and Sichuan stone coal processors drive technical-grade consumption volumes. MEE emissions protocols mandate carbon intensity disclosures by 2026, redirecting feedstock priorities toward slag recovery with flue gas desulfurization. Panzhihua and Xichang industrial clusters host integrated roasting-leaching operations serving domestic catalyst manufacturers.
Japan
Mitsubishi Chemical and specialty catalyst formulators in Osaka require full batch traceability documentation for pharmaceutical-grade procurement. METI industrial standards enforce vanadium compound handling protocols across chemical manufacturing facilities. Kansai region logistics providers consolidate chain-of-custody documentation for multi-year framework agreements.
Germany
BASF catalyst impregnation facilities in Ludwigshafen source powder-form material with ICP-MS verification certificates. REACH registration requirements favor certified producers with documented environmental management systems. Ruhr region steel micro-alloying negotiations center on long-term offtake agreements with Brazilian mine-oxide integrators.
United States
MIT and national laboratory electrochemistry programs drive research-grade demand with stringent impurity specifications below 100 ppm total metals. OSHA workplace exposure limits govern vanadium compound handling across catalyst production facilities. Pacific Northwest battery research consortia pilot membrane electrolysis integration for vanadium redox flow battery electrolyte manufacturing.
India
CDSCO-regulated pharmaceutical intermediate manufacturers near Mumbai and Hyderabad chemical corridors attract vanadium catalyst investments. BIS hazardous chemical classification standards align storage and transport protocols with GB and OSHA frameworks. Gujarat ceramic pigment producers utilize technical-grade feedstock with iron and chromium tolerance windows for construction material colorants.
Ammonium Metavanadate Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across a bifurcated structure. Integrated mine-to-oxide operators with captive roasting infrastructure command supply security premiums, while regional chemical traders serve spot-market laboratory reagent demand. Two strategic archetypes dominate: vertically integrated resource owners with multi-jurisdiction certification capabilities, and specialty chemical distributors with consolidated logistics and analytical certification services. Competitive moves concentrate on backward integration into slag recovery assets and direct-to-battery offtake agreements bypassing traditional distribution channels.
Among Brazilian and Southern African resource owners, Largo Resources Ltd and Bushveld Vanchem Ltd exemplify the integrated archetype with captive mining assets and in-house oxide conversion infrastructure. U.S. Vanadium LLC occupies a position on the North American battery-grade material vector, representing the regional specialization strategy tied to electrolyte-grade specification development. Merck KGaA and Thermo Fisher Scientific sit within the analytical certification and research-grade distribution tier, anchoring institutional procurement relationships with documented traceability chains.
| Leading Market Players |
|---|
| Largo Resources Ltd |
| U.S. Vanadium LLC |
| Angang Steel Company Limited |
| Merck KGaA |
| American Elements |
| Bushveld Vanchem Ltd. |
| Taiyo Koko Co., Ltd. |
| Thermo Fisher Scientific |
| Ferro-Alloy Resources Limited |
| Others |
Supply Flow & Price Mechanics
Membrane electrolysis integration for vanadium redox flow battery production is compressing margins for standalone chemical processors while rewarding mine-to-electrolyte operators with captive supply chains and pricing power over intermediate material tiers.
Pricing Analysis
Certification-bundled versus unbundled analytical services split the procurement landscape, with battery-grade material commanding premium-mid-economy pricing differentiation based on ICP-MS verification and carbon intensity documentation. Price differentiation stems from purity thresholds and REACH registration status, with laboratory reagent buyers showing least price sensitivity due to publication-grade reproducibility requirements. Cost compression in technical-grade channels is intensifying because Chinese state-owned enterprises flood commodity oxide markets. Steel additive manufacturers represent the most price-sensitive segment, negotiating on vanadium unit economics alone.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Osaka, and Shanghai consolidate hub-and-spoke patterns for technical-grade material, while battery-grade streams bypass chemical distributors entirely. Supply concentrates in China, Brazil, and South Africa, with feedstock drawing from vanadium slag recovery and stone coal deposits. The chain rests on vanadium pentoxide volatility and roasting asset intensity. Single-source vulnerability from Chinese state-owned enterprise concentration threatens non-domestic buyers. Distribution runs through integrated logistics providers with chain-of-custody documentation capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the European Critical Raw Materials Act's battery-grade specifications creating preferential procurement channels that amplify demand for certified low-carbon extraction pathways.
For Market Incumbents: Cement supply security through backward integration into Brazilian or South African slag recovery assets before membrane electrolysis adoption accelerates. Invest in ICP-MS and XRF analytical capabilities to defend battery-grade certification premiums against emerging laboratory service competitors. Prioritize multi-year framework agreements with Japanese and South Korean catalyst manufacturers displacing spot-market procurement. For New Entrants and Emerging Players: Research institutions requiring small-lot flexibility with expedited analytical certification represent the most penetrable buyer archetype currently underserved by bulk-oriented distributors. Target CDSCO-regulated pharmaceutical intermediate manufacturers near Mumbai and Hyderabad with pharmaceutical-grade material and endotoxin testing documentation. Pursue direct-to-battery channel formation by securing long-term offtake agreements with vanadium redox flow battery integrators bypassing traditional chemical distributors. For Investors and Strategic Acquirers: Roll-up economics work for analytical certification and research-grade distribution specialists because procurement power concentrates among vertically integrated oxide producers with documented traceability chains. Over a multi-year horizon, prioritize targets with captive mining assets and multi-jurisdiction certification capabilities spanning OSHA, REACH, and GB standards. Watch for utility-scale vanadium redox flow battery deployment decisions as the inflection indicator for battery-grade material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slag Recovery Assets | Largo Resources and Bushveld Vanchem secure captive Brazilian and South African feedstock against Chinese supply concentration. |
| Long-term Supply Agreement with Battery Integrators | U.S. Vanadium LLC anchors North American electrolyte-grade demand through direct-to-battery channel formation. |
| Green Manufacturing Transition | Chinese producers deploy flue gas desulfurization at Panzhihua clusters to meet MEE carbon intensity disclosure mandates. |
| Joint Venture with Analytical Certification Providers | Merck KGaA and Thermo Fisher Scientific institutionalize ICP-MS verification for research-grade procurement relationships. |
| Capacity Expansion in Low-Carbon Certification Tracks | EU Green Deal alignment creates preferential procurement channels for certified extraction pathways separate from commodity flows. |
Methodological Framework
Multiple input streams — primary interviews with vanadium oxide plant managers, catalyst procurement leads at Mitsubishi Chemical and LG Chem, distribution channel partners in Osaka and Ulsan, and technical R&D directors at national laboratories — were reconciled against secondary validation from customs and trade data, SEC 10-K filings, ECHA REACH registration databases, and GB standards documentation. Bottom-up tonnage estimates by grade tier and application were triangulated against top-down vanadium pentoxide consumption projections.
Data-stream reconciliation across the analysis window applied a segmented analytical framework modeling grade tier, end-use industry, physical form, and regional production hub dimensions. CAGRs were derived from slope-log regression on normalized consumption trajectories, incorporating battery-grade specification tightening, steel micro-alloying intensity in Chinese construction grades, and membrane electrolysis adoption curves as industry-specific forecast inputs.
Underlying measurement precision varies by segment; battery-grade and pharmaceutical-grade material carry tighter precision than technical-grade commodity flows due to certification documentation density. Forecasts reflect documented assumptions around utility-scale vanadium redox flow battery deployment timelines, Chinese dual carbon policy enforcement intensity, and REACH registration compliance cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
High Molecular Weight Polyisobutylene Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
Europe Fine Chemical Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market
High-Value Chemicals
Hydrogen Cyanide Market