
 High Purity Isobutylene (HPIB) Market | 2026-2036
High Purity Isobutylene (HPIB) Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Isobutylene (HPIB) Market Foresight
Buyer concentration in the tire and automotive supply chain is consolidating as major rubber compounders reduce their supplier base to secure volume commitments and technical collaboration. LyondellBasell Industries leverages its integrated refinery-petrochemical footprint to deliver consistent high-purity grades across North American automotive corridors. ExxonMobil Chemical anchors its position through captive isobutane dehydrogenation capacity and long-term offtake relationships with butyl rubber manufacturers. Kuraray competes by specializing in ultra-high-purity specifications demanded by pharmaceutical and specialty polymer end users in Asia.
High Purity Isobutylene refers to isobutylene refined to purity levels typically exceeding 99.5 percent, with controlled limits on sulfur, water, and butadiene content achieved through extractive distillation, sulfuric acid absorption, or catalytic dehydrogenation processes. The material serves primarily as a reactive monomer in butyl rubber, polyisobutylene, and methyl tert-butyl ether synthesis, where trace impurities degrade polymer chain length and cross-linking efficiency. Isobutylene derivatives command the largest value share within product type segmentation due to their downstream versatility in adhesives, sealants, and lubricant additives. Fuel additives represent the fastest-growing application segment as refiners reformulate for cleaner combustion standards, though polymer production retains the deepest margin pool through long-term automotive contracts. Chemical manufacturers dominate end-user channels by volume, while direct sales capture premium pricing for pharmaceutical-grade specifications.
EPA regulations under the Clean Air Act constrain volatile organic compound emissions from HPIB storage and transfer operations, forcing terminal operators to invest in vapor recovery systems. REACH registration requirements in Europe mandate full toxicological dossiers for isobutylene imports above one tonne annually, elevating compliance costs for non-EU producers. China's MEE enforces increasingly stringent emissions permits for dehydrogenation units near population centers. Stakeholders must monitor regulatory divergence across these jurisdictions to anticipate where purity premiums and compliance burdens will reshape competitive cost structures.
Market Dynamics
Refinery-petrochemical integration is compressing merchant HPIB availability as integrated producers prioritize captive consumption for butyl rubber and MTBE derivatives, tightening spot market liquidity and amplifying price volatility for non-integrated buyers.
Growth Catalysts
- REACH compliance thresholds:ECHA's tightening purity specifications for polymer-grade imports are disqualifying marginal producers and consolidating volume around qualified suppliers with extractive distillation capabilities.
- Tire industry reformulation:Higher-performance elastomer specifications from automotive OEMs are pulling HPIB demand toward ultra-high-purity grades that enable superior cross-linking density in butyl inner liners.
- China's petrochemical self-sufficiency:Domestic dehydrogenation capacity expansion under the 14th Five-Year Plan is redirecting procurement from import-dependent coastal provinces toward inland integrated complexes.
Market Restraints
- Propylene feedstock volatility:Steam cracker operating rate fluctuations tied to naphtha price swings transmit directly to HPIB production economics, squeezing margins for non-integrated operators.
- Merchant supply concentration:North American Gulf Coast refinery-petrochemical clusters control the majority of exportable spot volumes, creating geographic vulnerability for Asian compounders without long-term offtake.
- Butadiene impurity ceilings:Trace diene contamination hardens polymer chains unpredictably, forcing pharmaceutical and adhesive applications toward costlier ultra-purification routes.
Strategic Opportunities
- India's specialty polymer gap:Domestic butyl rubber capacity remains below pharmaceutical and sealant demand, creating import substitution potential for qualified exporters meeting BIS purity standards.
- Fuel additive regulatory tailwind:EPA Tier 3 sulfur regulations and China's National VI emissions standards are mandating cleaner-burning gasoline formulations that favor HPIB-derived octane boosters.
- Digital supply chain integration:Blockchain-enabled batch certification is converging with vapor recovery monitoring to create auditable custody chains for pharmaceutical-grade shipments.
Industry Challenges
- Process control expertise scarcity:Extractive distillation operation requires specialized knowledge of sulfuric acid circulation and corrosion management that aging workforces in mature production regions are not replenishing.
- MEE emissions permit timelines:China's Ministry of Ecology and Environment approval cycles for new dehydrogenation units near population centers now extend 18-24 months, delaying capacity additions.
- ISO 9001 pharmaceutical certification complexity:Auditable quality systems for GMP-grade HPIB require dedicated tankage and loading infrastructure that multi-product terminals struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Isobutylene (HPIB) Market |
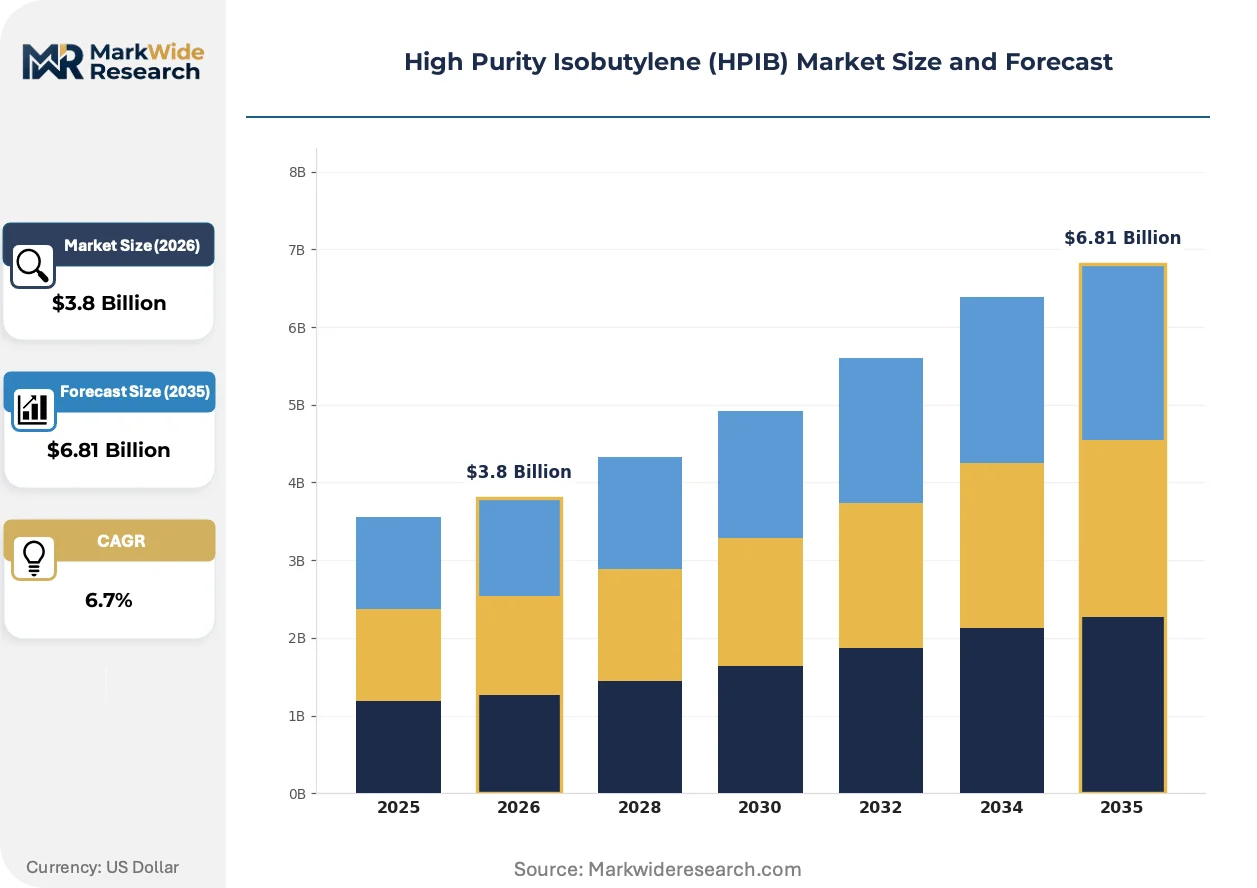
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Isobutylene, Isobutylene Derivatives, High Purity Isobutylene, Others Application: Fuel Additives, Polymer Production, Chemical Synthesis, Refrigerants End User: Chemical Manufacturers, Automotive Industry, Petrochemical Sector, Pharmaceutical Industry Distribution Channel: Direct Sales, Online Platforms, Distributors, Retailers |
| Companies Covered | LyondellBasell Industries, Enterprise Products Partners, ExxonMobil Chemical, Kuraray, Lanxess, Evonik Industries, Zibo Qixiangtengda Chemical, Songwon Industrial, TPC Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Isobutylene (HPIB) Market Shifts & Advancements
Catalytic dehydrogenation advances and regulatory precision are compressing traditional purification economics while digital traceability creates new service layers around commodity molecules.
Membrane separation technology is converging with traditional extractive distillation to reduce sulfuric acid consumption and energy intensity in high-purity production. Korean and Japanese specialty polymer manufacturers are piloting hybrid process trains at commercial scale. This convergence is compressing the cost gap between standard and ultra-high-purity grades, enabling broader specification upgrading across the value chain.
REACH authorization requirements under SVHC candidate list expansion are forcing non-EU producers to submit full toxicological dossiers for isobutylene derivatives above one tonne annually. The industrial consequence is a bifurcation between registered suppliers capturing automotive contract volumes and unregistered traders confined to spot fuel additive markets. Pharmaceutical and adhesive compounders in Germany and France are consolidating procurement around REACH-registered sources to eliminate regulatory risk in their own downstream registrations.
Specification-driven procurement is replacing volume-based contracting as tire OEMs unbundle compounding from rubber supply and impose direct HPIB purity audits on monomer suppliers. Long-term offtake agreements with indexed pricing are displacing annual spot tenders for premium automotive grades. This pattern is most visible in Japan and South Korea where METI industrial standards and MFDS pharmaceutical regulations create overlapping compliance requirements that favor integrated suppliers with multi-certification capabilities.
High Purity Isobutylene (HPIB) Market Segmentation
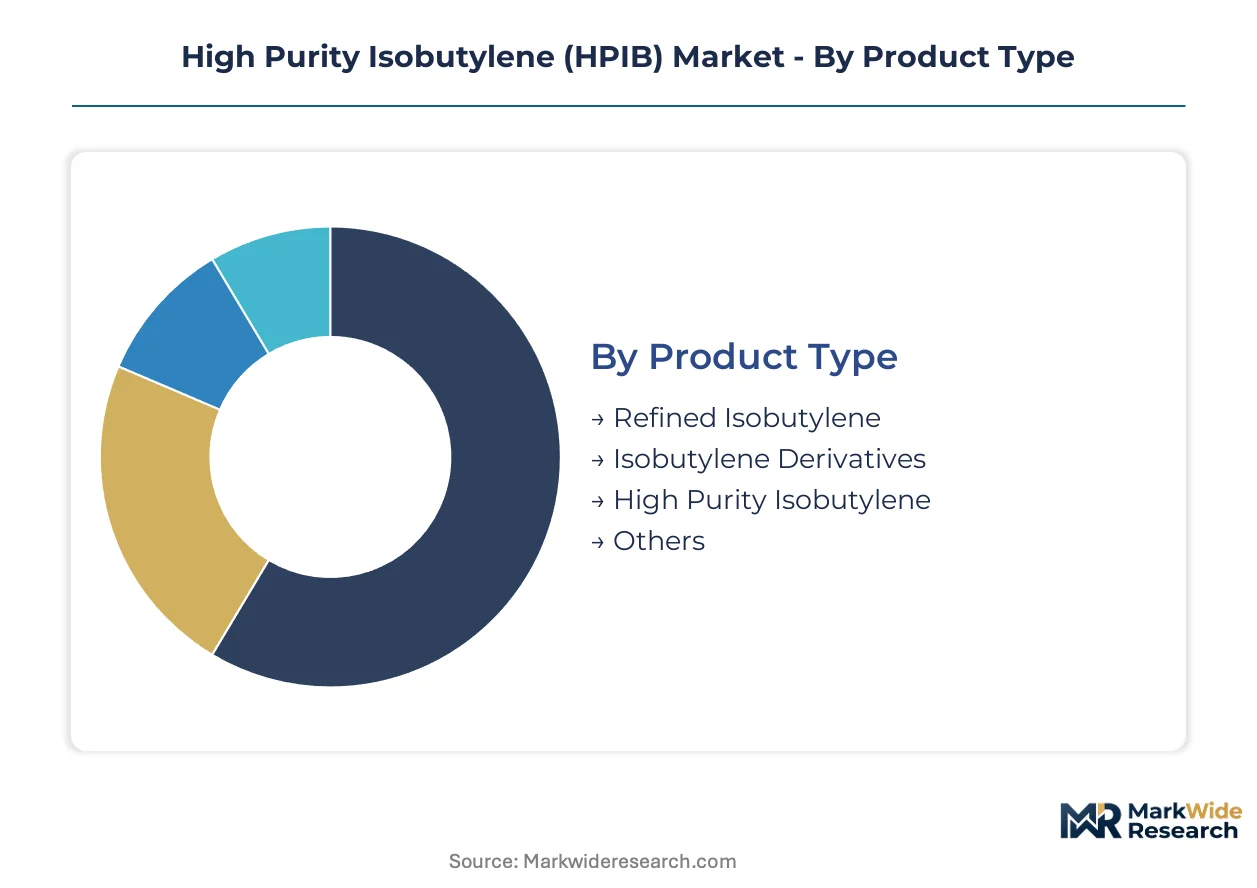
Segmentation in the HPIB market tracks how purity specifications, application chemistry, and regulatory compliance reshape procurement economics. Buyers now select grades based on downstream certification requirements rather than commodity pricing alone.
Product Type:
Upgrade cycles in polymer manufacturing are pulling specifications upward as tire OEMs unbundle compounding from rubber supply and impose direct purity audits.
- Isobutylene Derivatives:These downstream molecules—spanning polyisobutylene, butyl rubber precursors, and methyl tert-butyl ether intermediates—offer formulation flexibility across adhesives, sealants, and lubricant additives. Demand concentrates in automotive corridors where long-term offtake agreements with indexed pricing displace annual spot tenders for premium grades.
- High Purity Isobutylene:Material refined to 99.5 percent-plus purity with controlled sulfur, water, and butadiene limits serves reactive monomer applications where trace impurities degrade polymer chain length. Pharmaceutical and adhesive compounders in Germany and France consolidate procurement around REACH-registered sources to eliminate regulatory risk in downstream registrations.
- Refined Isobutylene:Standard purification grades meeting industrial polymer specifications without ultra-high purity overhead.
- Others:Specialty grades including pharmaceutical-certified and electronic-grade specifications for niche synthesis applications.
Isobutylene derivatives sit at the top of the volume ranking, with high purity isobutylene climbing the fastest.
Application:
Cost tier differentiation separates fuel additive buyers seeking volume pricing from polymer producers paying premiums for batch certification.
- Polymer Production:Butyl rubber and polyisobutylene synthesis consumes the deepest margin pool through long-term automotive contracts. Tire manufacturers in Japan and South Korea drive specification tightening as they seek higher-performance elastomers with superior cross-linking density in butyl inner liners.
- Fuel Additives:MTBE and related octane boosters serve refiners reformulating for EPA Tier 3 sulfur regulations and China's National VI emissions standards. The segment gains share fastest as cleaner-burning gasoline mandates expand across North American and Asian markets.
- Chemical Synthesis:Intermediate production for agrochemicals and specialty molecules requiring controlled isomer ratios.
- Refrigerants:Fluorocarbon precursor applications subject to F-Gas Regulation phase-down schedules in Europe.
Polymer production commands the largest value position, with fuel additives expanding most quickly.
End User:
Customer type stratification reflects divergent certification burdens—chemical manufacturers prioritize volume scale while pharmaceutical buyers demand auditable custody chains.
- Chemical Manufacturers:Volume buyers dominating by tonnage, operating continuous polymerization trains that reward supply security over purity premiums. These producers anchor demand in coastal China as domestic butyl rubber capacity scales and petrochemical self-sufficiency targets redirect procurement patterns.
- Pharmaceutical Industry:GMP-grade specifications requiring dedicated tankage and loading infrastructure that multi-product terminals struggle to justify. Korean and Japanese specialty polymer manufacturers pilot hybrid membrane-extractive distillation processes to compress the cost gap for this segment.
- Automotive Industry:Direct OEM contracting for tire and sealant specifications with embedded HPIB purity requirements.
- Petrochemical Sector:Integrated producers prioritizing captive consumption for derivatives, tightening merchant availability.
Chemical manufacturers hold the volume leadership, with pharmaceutical industry demand steepening fastest.
Distribution Channel:
Supply concentration geography dictates channel selection—direct relationships dominate where refinery-petrochemical integration controls exportable spot volumes.
- Direct Sales:Captures premium pricing for pharmaceutical-grade specifications through long-term offtake with blockchain-enabled batch certification. This channel converges with vapor recovery monitoring to create auditable custody chains for regulated shipments.
- Distributors:Serve mid-tier polymer compounders without scale to justify direct producer relationships, particularly in India's specialty polymer gap where domestic butyl rubber capacity remains below pharmaceutical and sealant demand.
- Online Platforms:Emerging for standard-grade fuel additive procurement with spot pricing transparency.
- Retailers:Minimal presence limited to small-volume laboratory and research chemical sales.
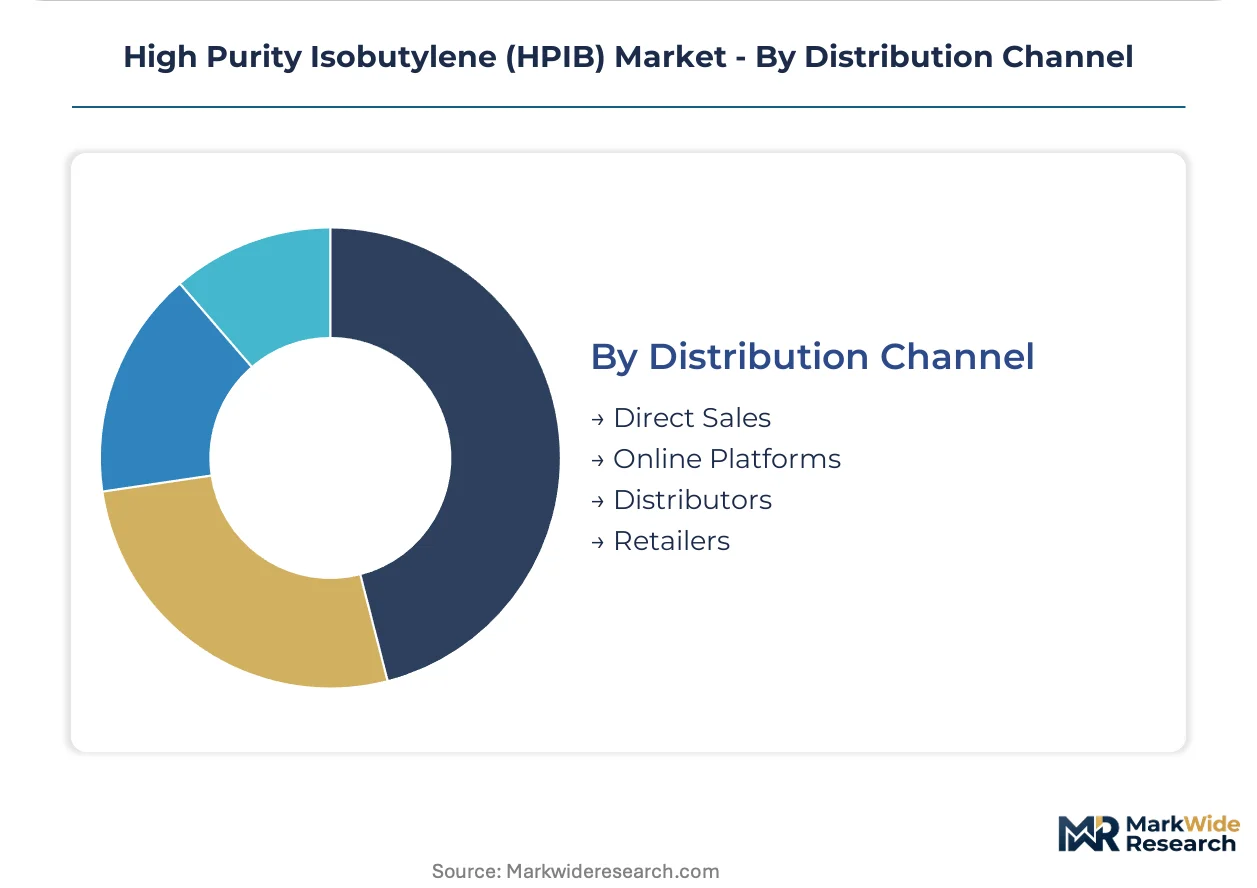
Direct sales dominates value capture, with distributors gaining ground fastest in underpenetrated import substitution markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's refinery-petrochemical integration outpaces United States merchant export capacity, while European REACH compliance costs reshape import sourcing patterns across polymer supply chains.
United States
Gulf Coast dehydrogenation clusters supply automotive corridor demand through captive butyl rubber integration. EPA Clean Air Act vapor recovery mandates tighten terminal infrastructure requirements. Houston-Beaumont-Port Arthur concentration controls exportable spot volumes, amplifying price volatility for Asian compounders lacking long-term offtake.
China
Domestic butyl rubber scaling under the 14th Five-Year Plan redirects procurement from coastal imports toward inland integrated complexes. MEE emissions permits for population-proximate dehydrogenation units now require 18-24 month approval cycles. Ningbo-Zhoushan and Dalian petrochemical zones anchor capacity expansion as self-sufficiency targets accelerate.
Germany
Automotive OEM specification tightening drives REACH-registered supplier consolidation for tire inner liner applications. ECHA SVHC candidate list expansion forces full toxicological dossiers for derivative imports above one tonne annually. Ludwigshafen-Cologne chemical corridor concentration exemplifies multi-certification capabilities spanning automotive and pharmaceutical grades.
Japan
Tire manufacturers unbundle compounding from rubber supply to impose direct HPIB purity audits on monomer suppliers. METI industrial standards overlap with MFDS pharmaceutical regulations, creating dual compliance burdens. Kashima and Chiba industrial zones pilot hybrid membrane-extractive distillation processes for specification upgrading.
South Korea
Specialty polymer manufacturers advance commercial-scale hybrid process trains to compress ultra-high-purity cost gaps. Domestic automotive contract volumes increasingly flow through long-term offtake with indexed pricing displacing spot tenders. Yeosu and Ulsan petrochemical complexes concentrate membrane separation technology deployment.
High Purity Isobutylene (HPIB) Market Competitive Landscape
North American integrated producers anchor the supply-secure tier; Asian specialists hold ultra-purity specification positions. Market structure bifurcates between refinery-petrochemical complexes prioritizing captive consumption and merchant-focused operators serving fuel additive spot demand. Three archetypes dominate: integrated petrochemical majors with backward control over feedstock, regional dehydrogenation specialists with extractive distillation expertise, and Asia-Pacific pure-play producers scaling pharmaceutical-grade certification. Capacity expansion and strategic partnerships constitute the primary competitive vectors as producers secure long-term automotive offtake.
Within the integrated major tier, LyondellBasell Industries and ExxonMobil Chemical exemplify refinery-petrochemical footprint leverage across North American automotive corridors. Kuraray occupies a position representing ultra-high-purity specialization for pharmaceutical and specialty polymer end users in Asia. These three entities collectively illustrate how geographic integration and specification focus stratify competitive positioning.
| Leading Market Players |
|---|
| LyondellBasell Industries |
| Enterprise Products Partners |
| ExxonMobil Chemical |
| Kuraray |
| Lanxess |
| Evonik Industries |
| Zibo Qixiangtengda Chemical |
| Songwon Industrial |
| TPC Group |
| Others |
Supply & Pricing Matrix
Propylene feedstock volatility transmits directly from steam cracker economics through to HPIB pricing tiers, with naphtha price swings compressing margins for non-integrated operators while integrated Gulf Coast producers capture wider spreads across automotive contract grades.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard polymer grades as domestic dehydrogenation units under the 14th Five-Year Plan displace import-dependent procurement. Contract-based long-term offtake with indexed pricing dominates premium automotive segments, while spot markets serve fuel additive buyers. Price differentiation rests on REACH registration status and pharmaceutical-grade certification. Pricing pressure stems from merchant supply concentration on the US Gulf Coast, where Houston-Beaumont-Port Arthur clusters control exportable volumes. Chemical manufacturers show highest price sensitivity due to continuous polymerization economics, while pharmaceutical compounders absorb premiums for auditable custody chains.
Supply Chain Analysis
Regional distribution centers near Ningbo-Zhoushan and Dalian anchor China's inbound logistics, with hub-and-spoke patterns radiating toward inland butyl rubber complexes. Supply concentrates in the United States, China, and South Korea, with raw material dependencies on isobutane feedstock, sulfuric acid for extractive distillation, and specialized membrane separation components. Single-source vulnerability runs through Gulf Coast dehydrogenation clusters exposed to hurricane disruption. Distribution runs through direct producer relationships for premium grades and distributor networks for mid-tier polymer compounders in import substitution markets like India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in ultra-high-purity segments where membrane-extractive hybrid processes compress cost structures, and in fuel additive applications benefiting from EPA Tier 3 and China National VI regulatory tailwinds.
For Market Incumbents: Lock in automotive offtake through multi-certification capabilities spanning REACH, MFDS, and ISO 9001 pharmaceutical standards before China's domestic capacity scales further. Deepen backward integration into captive isobutane dehydrogenation to insulate margins from naphtha volatility. Prioritize extractive distillation expertise retention as aging workforces in mature production regions thin operational benches. For New Entrants and Emerging Players: Specialty pharmaceutical compounders in India present the most penetrable buyer archetype, where domestic butyl rubber capacity sits below sealant and adhesive demand. Target BIS purity standard qualification as a regulatory moat against established REACH-registered suppliers. Pursue membrane separation technology licensing from Korean or Japanese pilot operators as a go-to-market differentiator. For Investors and Strategic Acquirers: Consolidation pressure builds where REACH compliance costs disqualify marginal producers and concentrate volume around extractive distillation specialists. Long-term viability favors integrated petrochemical majors with refinery-petrochemical footprints and ultra-purity pure-plays with pharmaceutical certification. Watch MEE emissions permit approval timelines in China as the inflection signal for capacity addition delays.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Dehydrogenation | Insulates margin structures from naphtha price transmission through Gulf Coast steam cracker economics. |
| Membrane-Extractive Hybrid Process Deployment | Korean and Japanese specialty polymer manufacturers pilot commercial-scale trains to compress ultra-high-purity cost gaps. |
| REACH Registration Investment | ECHA SVHC expansion forces full toxicological dossiers, consolidating automotive contract volumes around qualified suppliers. |
| Blockchain-Enabled Batch Certification | Converges with vapor recovery monitoring to create auditable custody chains for pharmaceutical-grade shipments. |
| Long-Term Supply Agreement with Indexed Pricing | Displaces annual spot tenders as tire OEMs unbundle compounding and impose direct HPIB purity audits. |
Research Methodology
Direct dialogue with plant managers at dehydrogenation facilities, procurement leads at tire OEMs, distribution channel partners in Asian petrochemical corridors, and technical R&D directors at membrane separation technology developers grounded qualitative findings. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE emissions permit disclosures. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across the analysis window.
Segment-level projections incorporated grade tier differentiation, end-use industry clustering, and regional production hub economics throughout the forecast period. CAGRs emerged from regression analysis against feedstock price indices, regulatory implementation schedules, and automotive OEM specification timelines. Model inputs included steam cracker operating rate assumptions, REACH registration status by supplier, and MEE permit approval cycle durations.
Underlying measurement precision varies by segment; fuel additive applications carry tighter precision than pharmaceutical-grade volumes due to more transparent spot market data. Forecasts reflect documented assumptions around naphtha price corridors, regulatory implementation fidelity, and automotive demand elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
Asia-Pacific Hydrogen Bromide Market