

High Molecular Ammonium Polyphosphate Market Size, Share, and Industry Trends Forecast 2026-2036
High Molecular Ammonium Polyphosphate Market Insights
Specialty chemical distribution channels serving flame retardant buyers is reconfiguring as regional formulators seek shorter lead times and certified material streams. Clariant leverages its European technical service network to sustain specification-grade supply relationships with tier-1 compounders. Perimeter Solutions anchors North American demand through integrated production of phosphorus derivatives for intumescent systems. Budenheim competes on purity thresholds, positioning its high-chain-length product for aerospace laminates where thermal stability requirements exceed standard commercial grades.
High molecular ammonium polyphosphate refers to a crystalline inorganic salt with polymerization degree typically exceeding 1,000, synthesized through thermal condensation of ammonium orthophosphate precursors under controlled dehydration conditions. The material functions primarily as a non-halogen flame retardant and intumescent char former, releasing ammonia and polyphosphoric acid under combustion temperatures to create thermally protective barrier layers on substrates. Flame retardant formulations currently lead volume absorption, reflecting sustained pull from construction materials and electronics housing sectors where UL-94 V-0 ratings remain mandatory. Intumescent coatings represent the fastest-expanding application dimension, driven by steel structure fireproofing mandates in commercial building codes across industrialized economies. Coating-grade material commands margin premiums due to particle size distribution requirements and surface compatibility demands that limit qualified supplier pools.
Regulatory frameworks including REACH in Europe, RoHS directives governing electronics substance restrictions, and FAA flammability standards for interior aerospace materials collectively elevate compliance burdens while favoring phosphorus-based alternatives over legacy brominated systems. EPA assessments under the Toxic Substances Control Act and evolving state-level restrictions on halogenated compounds in California and New York further channel R&D investment toward ammonium polyphosphate modification and synergist optimization. Stakeholders must monitor pending revisions to EN 13501-1 fire classification protocols and corresponding adoption timelines in EU member states, as these will determine whether existing formulation registrations require renewed testing against tightened smoke toxicity thresholds.
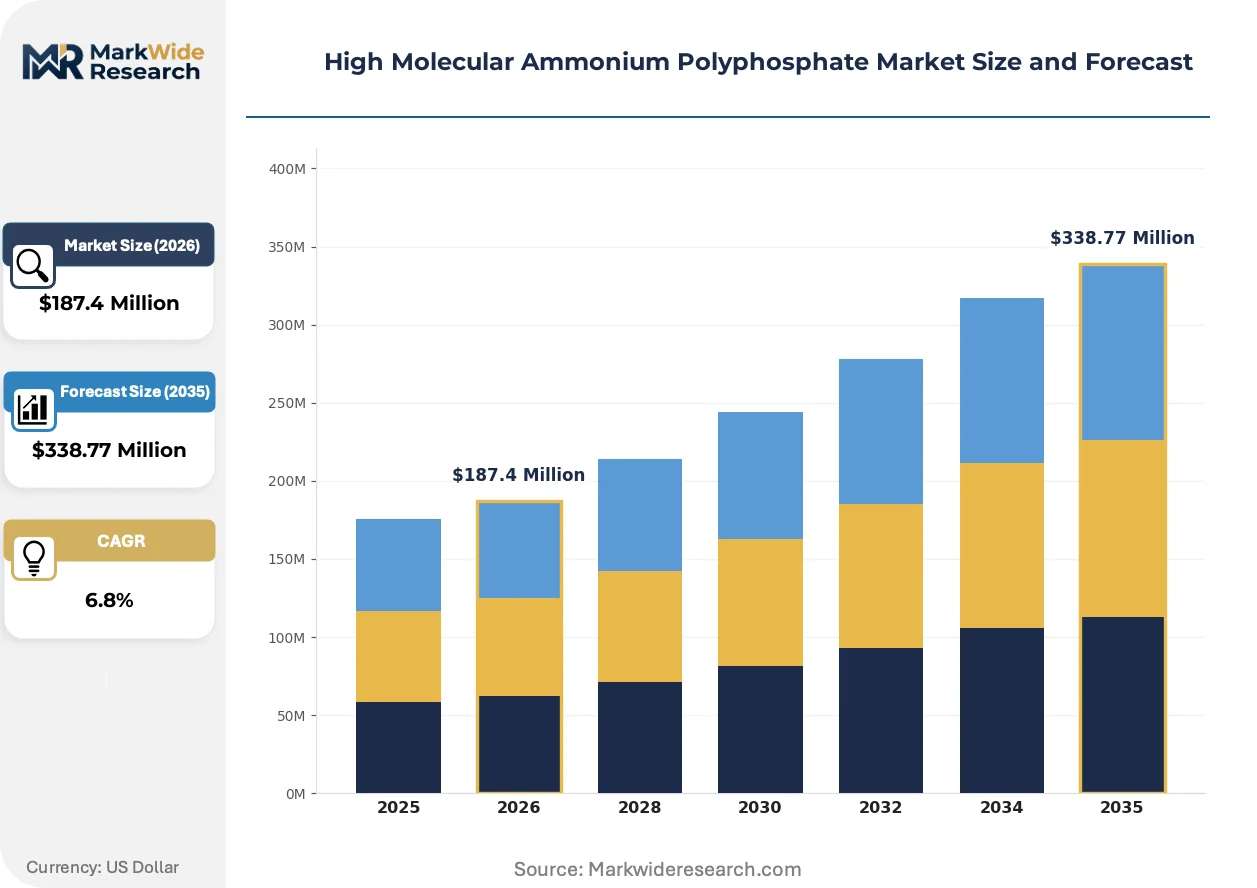
Market Dynamics
Building code harmonization around phosphorus-based halogen-free systems is compressing specification cycles and forcing compounders to pre-qualify multiple APP grades simultaneously.
Growth Catalysts
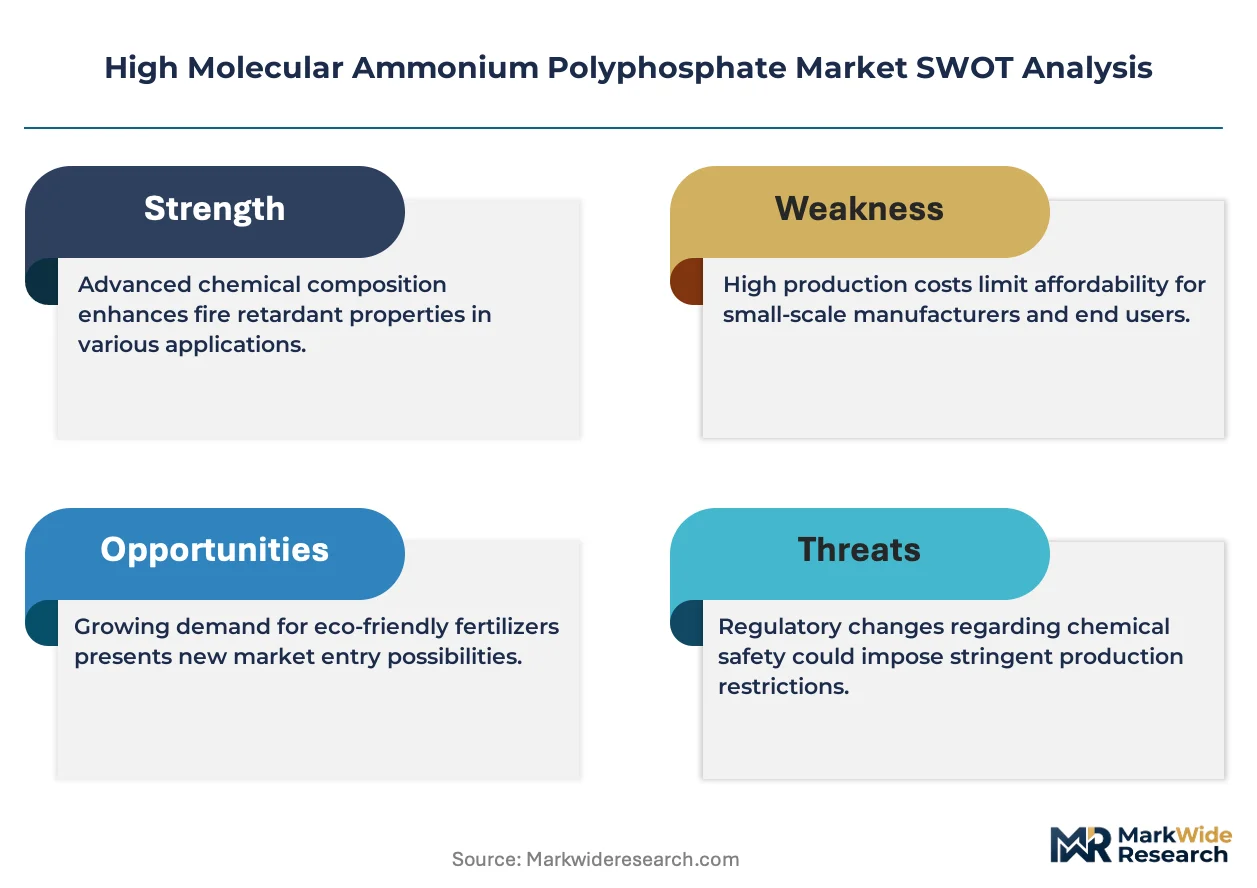
- REACH RoHS alignment:European electronics manufacturers face mandatory substance restrictions that eliminate brominated alternatives from printed circuit board laminates and connector housings.
- Steel fireproofing mandates:Commercial building codes in industrialized economies now require intumescent coating systems on structural steel, pulling coating-grade APP volumes upward.
- China's electronics-grade capacity:Domestic Chinese producers have scaled polymerization-degree control to serve regional PCB and battery enclosure demand without import dependency.
Market Restraints
- Phosphate rock feedstock volatility:Ammonium polyphosphate production ties directly to phosphate fertilizer market swings, creating margin pressure during agricultural demand spikes.
- High-chain-length purification bottlenecks:Aerospace-grade material requires solvent fractionation and crystallization steps that limit qualified supplier pools to three European and one North American producer.
- Melamine cyanurate substitution:Intumescent coating formulators in cost-sensitive building applications increasingly specify nitrogen-based char formers that undercut APP on raw material cost.
Strategic Opportunities
- India BIS standardization gap:Domestic fire safety codes for high-rise construction remain underpenetrated by certified phosphorus-based systems, creating first-mover positioning for compliant importers.
- Thermoplastic polyurethane integration:Wire and cable jacketing compounds represent an emerging application vector where APP synergist packages are displacing metal hydrate loadings.
- EU Green Deal procurement incentives:Public infrastructure tenders now embed lifecycle carbon scoring that favors halogen-free flame retardants over legacy brominated systems in tunnel and transit specifications.
Industry Challenges
- Polymerization-degree metrology shortage:Analytical chemists capable of operating 31P NMR and gel permeation chromatography for chain-length verification remain concentrated at European technical service laboratories.
- UL-94 V-0 recertification timelines:Reformulated compounds containing modified APP grades require 16-24 week testing cycles that delay customer qualification and revenue recognition.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Molecular Ammonium Polyphosphate Market Trends and Innovations
Formulation science is converging with regulatory chemistry to produce multi-functional additive packages that satisfy simultaneous fire, smoke, and toxicity performance thresholds.
Micro-encapsulated ammonium polyphosphate is hybridizing with silicone-based surface treatments to improve hydrophobicity in exterior intumescent coatings. Coating manufacturers serving infrastructure steel protection are adopting these grades to prevent premature degradation during construction-phase weather exposure. This hybridizing approach compresses the traditional separation between flame retardant and weatherability additive categories, forcing suppliers to demonstrate dual-performance data sets.
EPA assessments under the Toxic Substances Control Act are accelerating state-level halogen restrictions in California and New York that exceed federal minimums. Electronics compounders serving multi-state distribution must now maintain parallel formulation inventories or default to phosphorus-based systems universally. The wire and cable segment bears the heaviest compliance burden, with OEMs demanding pre-certification documentation that extends supplier qualification timelines.
Specification-grade buyers are consolidating approved vendor lists to reduce incoming material testing costs and liability exposure. Tier-1 compounders now require ISO 17025 laboratory accreditation and batch-level 31P NMR traceability as standard commercial terms. This concentration of procurement authority is most visible in German automotive supply chains, where OEMs delegate flame retardant sourcing decisions to tier-0 system suppliers who enforce unified material standards across multiple component categories.
High Molecular Ammonium Polyphosphate Market Segmentation
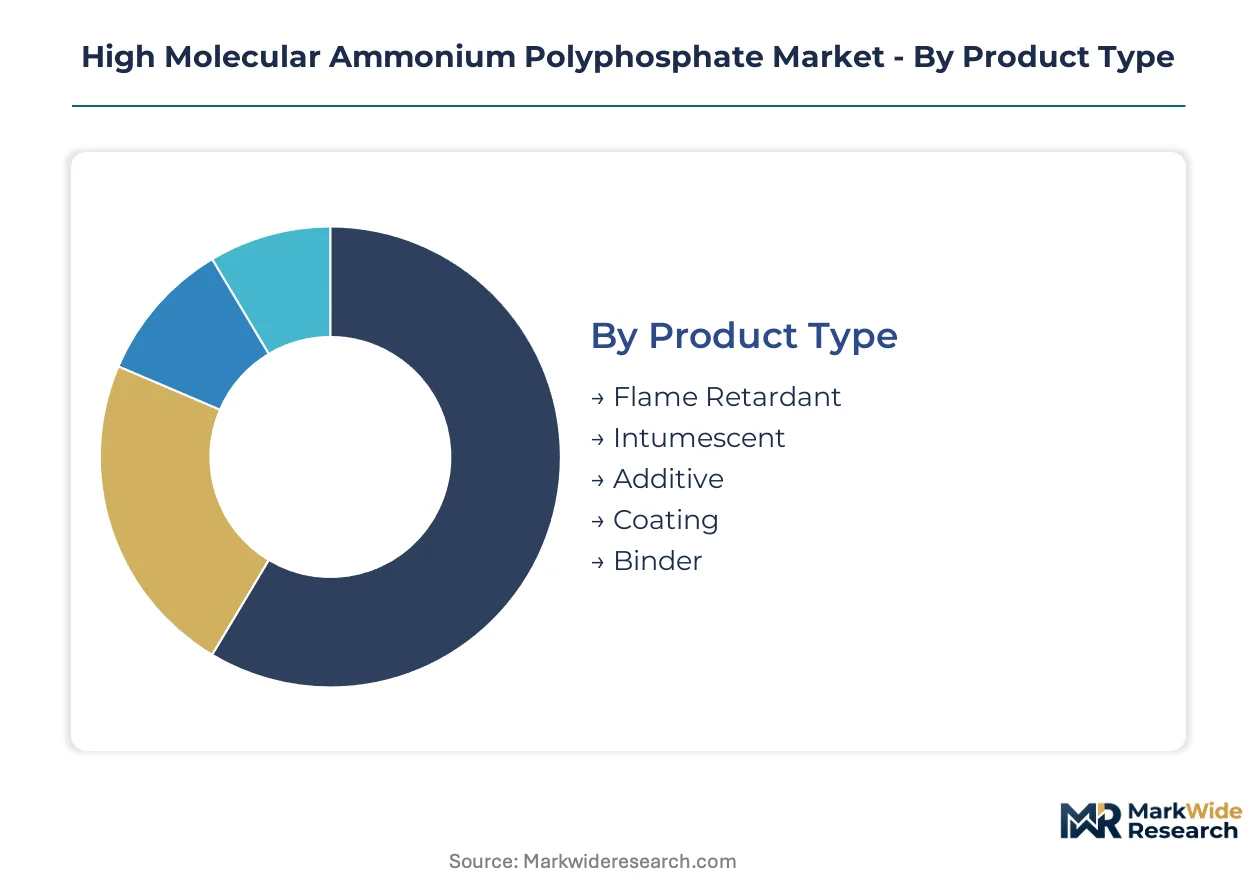
High molecular ammonium polyphosphate exhibits divergent specification requirements across end-use applications, forcing suppliers to maintain parallel production streams with distinct polymerization-degree targets and purity thresholds. Segmentation logic in this market tracks regulatory compliance tiers rather than conventional commodity grades, as UL-94 V-0 certification and REACH registration status determine commercial viability more than base chemistry.
Product Type:
Mature flame retardant formulations coexist with emerging coating-grade specializations, reflecting divergent technical barriers and margin architectures across the product spectrum.
- Flame Retardant:Crystalline APP with polymerization degrees exceeding 1,000 serves as the primary non-halogen char former in polyolefin and thermoset systems. Construction materials and electronics housing in China absorb the dominant volume share, driven by GB standard alignment with RoHS substance restrictions.
- Intumescent:Surface-treated grades with controlled particle size distributions below 20 microns enable uniform dispersion in water-based coating systems. Steel structure fireproofing mandates across German commercial building codes pull demand upward, though qualified supplier pools remain limited by solvent fractionation bottlenecks.
- Additive:Synergist-optimized packages combine APP with pentaerythritol and melamine derivatives for enhanced char cohesion.
- Coating:Hydrophobized grades with silicone surface treatments resist premature degradation during exterior construction-phase exposure.
- Binder:Lower-chain-length variants function as ceramic precursors in refractory and investment casting applications.
Flame Retardant retains volume leadership; Intumescent holds the steepest expansion curve.
Application:
Cost tier stratification separates specification-grade electronics demand from price-sensitive textile treatments, with construction materials occupying the intermediate value band.
- Electronics:High-purity APP with batch-level 31P NMR traceability serves printed circuit board laminates and battery enclosure compounds. Tier-1 compounders in Germany enforce ISO 17025 laboratory accreditation as standard procurement terms, compressing approved vendor lists to three European suppliers.
- Construction Materials:Intumescent coating systems for structural steel protection dominate volume absorption in industrialized economies. EN 13501-1 fire classification protocol revisions in EU member states are redirecting formulation strategies toward phosphorus-based halogen-free systems.
- Textiles:Back-coating applications for upholstery and drapery fabrics specify nitrogen-phosphorus synergist packages.
- Transportation:Wire and cable jacketing compounds in California face state-level halogen restrictions exceeding federal EPA minimums.
- Packaging:Expanded polystyrene and polyurethane foam treatments for cold-chain shipping containers represent emerging volume.
Construction Materials commands the largest installed base; Electronics is gaining share fastest.
End Use Industry:
Customer type concentration varies sharply, with aerospace-grade material requiring solvent fractionation capabilities that only four producers globally possess.
- Consumer Goods:Appliance housings and furniture textiles specify mid-tier APP grades with UL-94 V-0 pre-certification. OEMs serving multi-state US distribution maintain parallel formulation inventories to satisfy California and New York halogen restrictions.
- Building & Infrastructure:Public infrastructure tenders under the EU Green Deal embed lifecycle carbon scoring that favors phosphorus-based systems in tunnel and transit specifications.
- Automotive Tier-1:Wire harness compounds and interior trim applications require thermal stability above 280°C processing temperatures.
- Aerospace:FAA flammability standards for interior materials mandate high-chain-length APP with purity thresholds exceeding standard commercial grades.
- Marine:IMO fire safety codes for vessel construction specify intumescent coating systems on steel bulkheads and decks.
Building & Infrastructure retains volume leadership; Aerospace holds the steepest expansion curve.
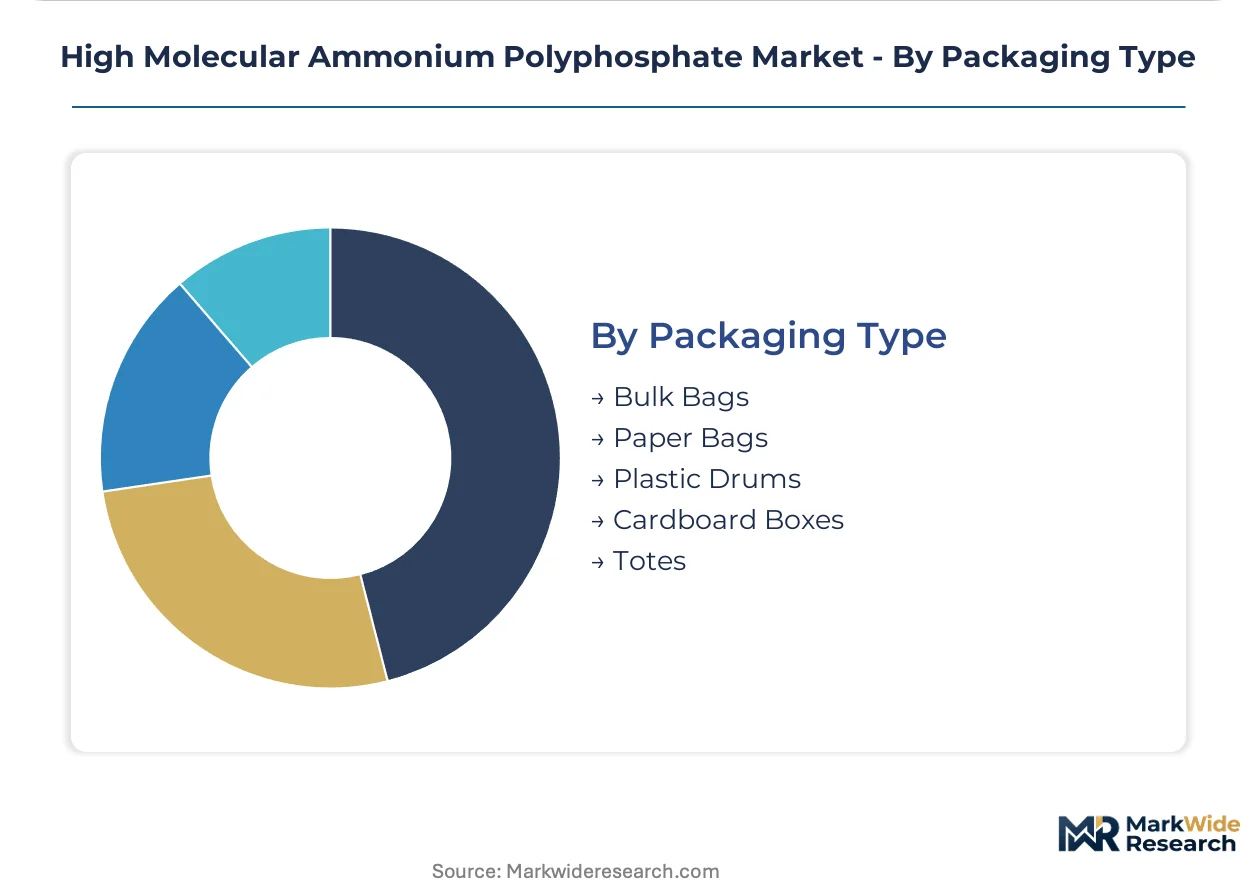
Packaging Type:
Supply concentration in bulk logistics reflects the fertilizer-industry heritage of phosphate derivative producers, while specialty packaging serves coating-grade material with moisture sensitivity.
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate flame retardant compounder procurement, enabling pneumatic conveying directly into extrusion lines. Chinese domestic producers have scaled bulk logistics to serve regional PCB demand without import dependency.
- Paper Bags:Multi-wall kraft constructions with polyethylene liners protect coating-grade APP from construction-phase humidity exposure.
- Plastic Drums:25-kilogram HDPE containers serve laboratory-scale formulation development and qualification batches.
- Cardboard Boxes:Corrugated fiberboard with moisture barriers accommodates smaller compounders lacking bulk handling infrastructure.
- Totes:Intermediate rigid containers enable just-in-time delivery to tier-1 automotive suppliers with vendor-managed inventory agreements.
Bulk Bags retains volume leadership; Totes holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German specification-grade supply while Chinese bulk volumes compress margins across Asia-Pacific. European technical service networks command certification premiums that Asian producers struggle to replicate. Regional demand fragmentation intensifies as building codes diverge on phosphorus-based halogen-free thresholds.
China
Domestic polymerization-degree control now serves regional PCB and battery enclosure demand without import dependency. GB standards alignment with RoHS substance restrictions accelerates electronics-grade absorption. Jiangsu and Zhejiang provinces host expanded production clusters where producers scaled crystallization capabilities to compete on chain-length consistency.
Germany
Steel structure fireproofing mandates under EN 13501-1 revisions pull coating-grade volumes upward. REACH registration status determines commercial viability more than base chemistry specifications. The Rhine-Main industrial corridor concentrates solvent fractionation capabilities that aerospace-grade material requires.
United States
State-level halogen restrictions in California and New York exceed federal EPA minimums under Toxic Substances Control Act assessments. Wire and cable OEMs demand pre-certification documentation that extends supplier qualification timelines. The Gulf Coast petrochemical corridor integrates phosphorus derivative production for intumescent system feedstock.
India
Domestic fire safety codes for high-rise construction remain underpenetrated by certified phosphorus-based systems. BIS standardization gaps create first-mover positioning for compliant importers. Maharashtra and Gujarat industrial zones concentrate formulation development for construction material applications.
Japan
METI guidance on electronics substance restrictions channels printed circuit board laminate demand toward phosphorus-based alternatives. JIS standards alignment with RoHS directives eliminates brominated options from connector housing specifications. The Kanto region maintains incoming material testing infrastructure that tier-1 compounders require for batch-level traceability.
High Molecular Ammonium Polyphosphate Market Competitive Landscape
Integrated phosphorus derivative producers and specialty chemical distributors split the market along specification-grade versus bulk-volume fault lines. The vendor base concentrates around four European solvent-fractionation specialists and three Asian scale producers with crystallization capabilities. Strategic archetypes include backward-integrated fertilizer heritage players, technical service-forward compounder partners, and purity-threshold specialists serving aerospace laminates. Dominant competitive moves encompass capacity expansion in China and strategic partnerships for coating-grade surface treatment technology.
Among European technical service networks, Clariant and Budenheim occupy positions anchored by specification-grade supply relationships with tier-1 compounders. Clariant represents the technical service-forward archetype through its laboratory accreditation infrastructure. Budenheim exemplifies purity-threshold specialization for thermal stability requirements exceeding standard commercial grades. Perimeter Solutions sits within the integrated production archetype, anchoring North American demand through captive phosphorus derivative supply.
| Leading Market Players |
|---|
| Clariant |
| Perimeter Solutions |
| Nutrien |
| Budenheim |
| JLS Chemical |
| Sanwa Flame Retardant Technology |
| Jingdong Chemical |
| Kingssun Group |
| Lanyang Chemical |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Main corridor's freight economics amplify cost differentials between specification-grade European supply and bulk Asian volumes, compressing margins for coating-grade material while rewarding solvent-fractionation specialists with certification premiums. This logistics tension concentrates pricing power with four qualified aerospace-grade producers while forcing commodity compounders toward shorter-haul Chinese sourcing.
Pricing Analysis
Customization-premium spreads separate aerospace-grade material commanding certification premiums from standard flame retardant grades serving construction applications. Three-tier pricing structure across premium, standard, and economy levels tracks polymerization-degree thresholds and 31P NMR traceability requirements. Cost compression in standard-grade construction material intensifies because Chinese crystallization capacity expansion feeds spot-market liquidity. Electronics compounders in Germany exhibit lowest price sensitivity due to REACH registration compliance costs, while Indian construction formulators remain most sensitive to landed cost differentials.
Supply Chain Analysis
Contract-manufacturing concentration sits with Jiangsu and Zhejiang crystallization facilities serving domestic PCB demand, while solvent fractionation for aerospace-grade material remains captive to four European and North American producers. Phosphate rock feedstock draws from Moroccan and Chinese mining operations, with ammonia supply tethered to fertilizer market cycles. Single-source vulnerability concentrates in high-chain-length purification steps where qualified supplier pools number fewer than five globally. Distribution runs through specialty chemical distributors for specification-grade buyers and direct bulk logistics for construction compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to phosphate fertilizer input costs, with agricultural demand spikes historically preceding flame retardant margin compression by two quarters.
For Market Incumbents: Build certification moats through ISO 17025 laboratory accreditation and batch-level 31P NMR traceability infrastructure. Deepen backward integration into phosphate rock sourcing to buffer fertilizer market volatility. Acquire surface-treatment technology for hydrophobized coating grades to defend against melamine cyanurate substitution in intumescent applications. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-standardization gap for high-rise construction fire safety codes. Target coating-grade surface treatment partnerships with German steel protection formulators seeking qualified second-source supply. Pursue thermoplastic polyurethane wire and cable qualification as metal hydrate displacement accelerates under California halogen restrictions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors solvent-fractionation specialists with aerospace laminate certifications over commodity crystallization capacity. Long-term viability hinges on regulatory persistence of phosphorus-based halogen-free mandates across EU and US jurisdictions. Monitor EN 13501-1 smoke toxicity threshold revisions as inflection indicator for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock | Captive feedstock supply buffers margin volatility from fertilizer market swings. |
| Surface Treatment Technology Licensing | Silicone-based hydrophobicity packages unlock exterior intumescent coating specifications. |
| ISO 17025 Laboratory Accreditation | Batch-level 31P NMR traceability meets tier-1 compounder procurement mandates in Germany. |
| India BIS Standardization Pre-Positioning | First-mover certification captures high-rise construction code evolution in Maharashtra and Gujarat. |
| TPU Wire and Cable Qualification | Metal hydrate displacement in California jacketing compounds opens specification-grade volume. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, SEC chemical sector filings, and ECHA REACH registration databases. Primary interviews engaged plant managers at phosphorus derivative facilities, procurement leads at tier-1 electronics compounders, distribution channel partners serving flame retardant formulators, and technical R&D directors overseeing intumescent coating development. Bottom-up volume estimates triangulated against top-down construction spending and electronics production indices.
Forecast inputs span polymerization-degree grade tiers, end-use industry absorption patterns, packaging format logistics costs, and regional production hub capacity utilization. Modeled dimensions include flame retardant versus intumescent application splits, electronics versus construction demand shares, and coating-grade versus standard-grade purity thresholds. CAGRs derived from regression analysis against historical phosphate fertilizer pricing cycles and regulatory adoption timelines for halogen-free mandates.
Stress conditions across phosphate rock spot volatility, REACH registration timeline delays, and Chinese crystallization capacity expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions of sustained EU and US regulatory preference for phosphorus-based systems. Quarterly review of EN 13501-1 revision progress, BIS standardization committee outputs, and Chinese GB standard alignment with RoHS is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.