
 Hydroxylamine Market | 2026-2036
Hydroxylamine Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxylamine Market Foresight
China is rewriting capacity dynamics in hydroxylamine production as new petrochemical complexes come online in Zhejiang province. BASF SE leverages its integrated Ludwigshafen site to sustain captive supply chains for pharmaceutical-grade material. Mitsubishi Gas Chemical Company anchors high-purity output for East Asian semiconductor fabs. UBE Industries competes through backward integration into nitric acid feedstock.
Hydroxylamine (NH₂OH) is a nitrogen-containing reducing agent synthesized via catalytic hydrogenation of nitric oxide or nitromethane reduction, typically supplied at 50% aqueous concentration for industrial handling safety. The compound serves primarily as a selective reducing agent in semiconductor photoresist stripping, pharmaceutical intermediate synthesis, and agrochemical manufacturing. Aqueous solutions dominate volume flows due to safer transport profiles, while anhydrous grades command premium positioning in electronics applications where moisture sensitivity governs process yield. Salt forms occupy mature demand channels in textile dyeing, whereas reducing agent applications in chemical manufacturing represent the fastest-expanding margin pool.
EPA oversight in the United States classifies hydroxylamine as a hazardous substance under Clean Air Act provisions, forcing domestic handlers into rigorous emissions controls and worker exposure limits. ECHA's REACH framework in Europe mandates registration and toxicity dossiers that filter out smaller importers, consolidating supply access for compliant producers. China's MEE enforces wastewater discharge standards on nitric acid derivative plants, reshaping regional cost structures. Stakeholders must monitor how dual carbon targets across major production zones redirect capital toward cleaner hydrogenation catalysts rather than conventional synthesis routes.
Market Dynamics
Semiconductor photoresist stripping requirements for sub-3nm nodes are compressing purity tolerances across the hydroxylamine supply base, forcing capital redeployment toward anhydrous production trains and captive distillation infrastructure.
Growth Catalysts
- EU REACH Article 33 compliance:Tighter substance-of-very-high-concern screening elevates demand for pharmaceutical-grade hydroxylamine in active pharmaceutical intermediate synthesis, particularly for cephalosporin antibiotics.
- East Asian electronics manufacturing clusters:Taiwan and South Korea fab expansion concentrates procurement volumes, creating pull-through for ultra-high-purity aqueous and anhydrous grades in chemical mechanical planarization and post-etch residue removal.
- Catalytic hydrogenation advances:Platinum-rhodium fixed-bed reactor improvements yield higher nitric oxide conversion efficiency, reducing unit production costs for 50% aqueous material serving agrochemical oxime synthesis.
Market Restraints
- Nitric acid feedstock volatility:Ammonia oxidation economics tie hydroxylamine production to natural gas price swings, compressing margins when Henry Hub benchmarks spike.
- Zhejiang province supply concentration:China's petrochemical complex buildout creates geographic dependency risk for international buyers seeking alternative sourcing during regional environmental enforcement actions.
- Anhydrous handling limitations:Thermal instability above 15°C restricts transport modes and storage duration, limiting market penetration outside integrated semiconductor fab campuses.
Strategic Opportunities
- India pharmaceutical API manufacturing:CDSCO's bulk drug park incentives and PLI scheme extensions attract hydroxylamine consumption for domestic cephalosporin and anti-tuberculosis intermediate production.
- Green hydrogen integration:Electrolytic hydrogen feedstock substitution in catalytic hydrogenation trains aligns with EU Green Deal carbon border adjustment mechanisms, creating premium positioning for low-carbon certified material.
- Direct-to-fab chemical management contracts:Semiconductor manufacturers in Dresden and Singapore are consolidating vendor bases through on-site inventory and waste-stream recovery partnerships, displacing traditional distributor channels.
Industry Challenges
- High-purity analytical chemistry talent scarcity:ICP-MS and ion chromatography expertise for parts-per-billion impurity quantification concentrates in Basel and Osaka, constraining quality control scaling at new production sites.
- Pharmaceutical-grade certification timelines:EMA and FDA active pharmaceutical ingredient master file preparation extends 18-24 months, delaying market entry for greenfield producers targeting regulated drug intermediate applications.
- Legacy nitromethane reduction asset stranding:Conventional batch synthesis infrastructure faces obsolescence as continuous catalytic hydrogenation achieves superior yield and safety profiles, forcing write-down decisions at European and Japanese facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxylamine Market |
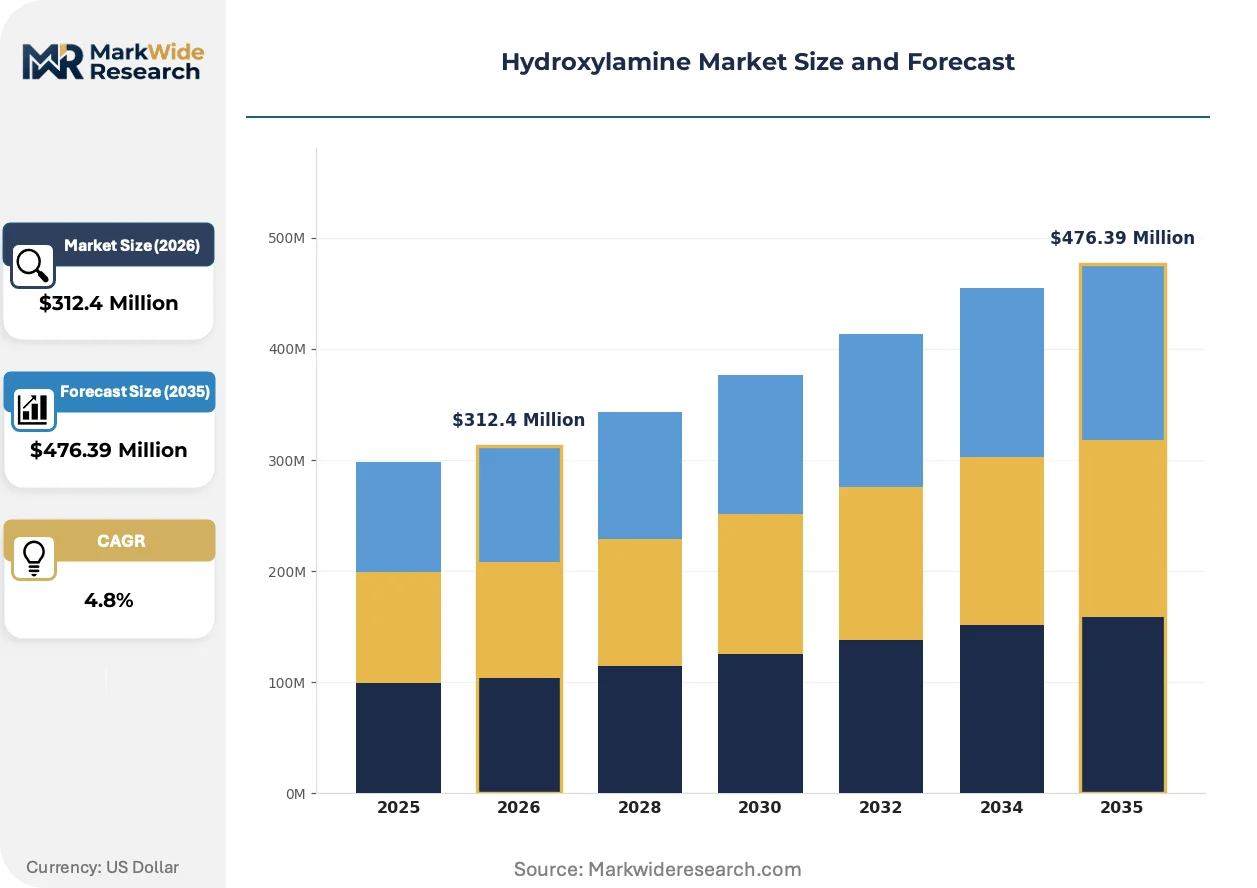
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $476.39 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anhydrous, Aqueous, Salt Forms, Solutions End Use Industry: Pharmaceuticals, Agriculture, Chemical Manufacturing, Textiles Distribution Channel: Online, Direct Sales, Distributors, Retail Application: Reducing Agent, Intermediate, Antioxidant, Fertilizer |
| Companies Covered | UBE Industries, BASF SE, Merck, Mitsubishi Gas Chemical Company, Evonik Industries, Lonza Group, Jarchem Industries Inc., SABIC, Zhejiang Jianye Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxylamine Market Shifts & Advancements
Membrane-based purification and point-of-use generation systems are restructuring how semiconductor fabs secure reducing agent supply, collapsing traditional bulk chemical logistics models in the process.
Continuous catalytic hydrogenation with structured ceramic monolith reactors is collapsing the cost gap between aqueous and anhydrous hydroxylamine production. Samsung and TSMC process engineers specify in-situ generation modules for sub-2nm logic nodes, eliminating moisture contamination risks from transported material. This technology compression is eroding the premium pricing power historically held by specialized anhydrous distributors.
EPA's National Emission Standards for Hazardous Air Pollutants for miscellaneous organic chemical manufacturing imposes stringent leak detection and repair protocols on domestic hydroxylamine producers. Ludwigshafen and Antwerp facilities face capital allocation decisions between US export compliance upgrades and regional EU demand capture. Semiconductor chemical suppliers in Pennsylvania and Texas are prioritizing closed-loop scrubbing investments over capacity expansion to maintain Clean Air Act operating permits.
Consolidated procurement through chemical management outsourcing is displacing spot purchasing for photoresist stripping agents. Leading memory and logic manufacturers in Hsinchu and Pyeongtaek now contract integrated chemical services spanning delivery, recovery, and waste treatment. This purchasing pattern shift concentrates supplier relationships and squeezes independent traders from the value chain.
Hydroxylamine Market Segmentation
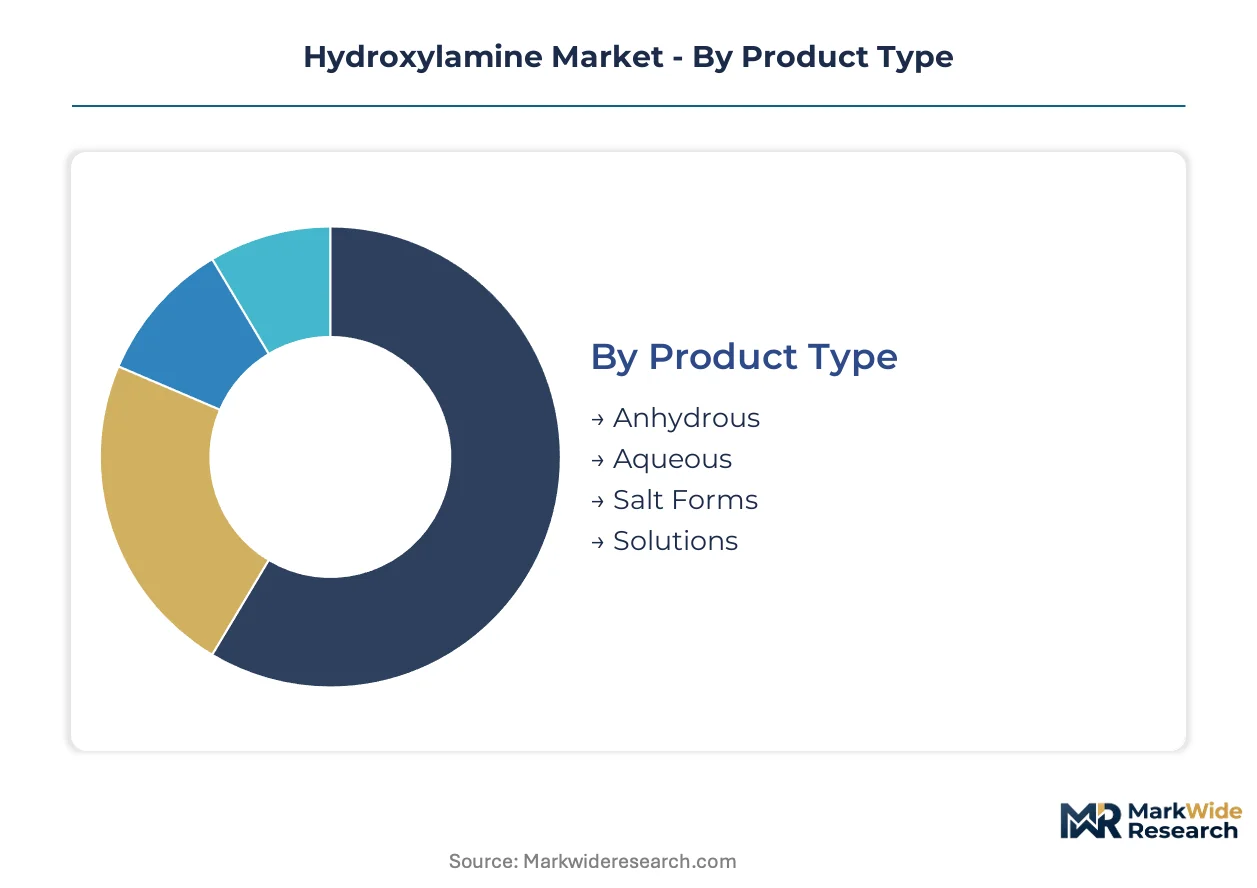
Hydroxylamine's chemical versatility fragments demand across purity grades, synthesis routes, and handling formats that dictate customer access and margin capture. Semiconductor fabs, pharmaceutical API manufacturers, and agrochemical formulators each impose distinct specification requirements that reshape supplier positioning.
Product Type:
Mature aqueous formats dominate tonnage flows while anhydrous grades command emerging premium positioning in moisture-sensitive electronics applications.
- Aqueous:Supplied at 50% concentration for safer transport and handling, this grade anchors volume consumption in agrochemical oxime synthesis and textile dyeing applications. Taiwan and South Korea fab clusters pull substantial volumes for photoresist stripping, though moisture content limits sub-3nm node compatibility.
- Anhydrous:Ultra-low moisture specifications serve EUV lithography and advanced packaging processes where water contamination degrades yield. Thermal instability above 15°C constrains logistics to integrated campus delivery or point-of-use generation systems at Dresden and Singapore facilities.
- Salt Forms:Hydroxylamine sulfate and hydrochloride occupy mature textile and chemical manufacturing channels with established handling protocols.
- Solutions:Custom concentration blends address specific pharmaceutical intermediate synthesis requirements, particularly cephalosporin antibiotic production.
Aqueous grades retain volume leadership; anhydrous formulations hold the steepest expansion curve.
End Use Industry:
Cost tier stratification separates electronics-grade premium positioning from commodity chemical manufacturing volumes.
- Pharmaceuticals:Active pharmaceutical intermediate synthesis for cephalosporin and anti-tuberculosis compounds drives REACH-compliant pharmaceutical-grade demand. CDSCO bulk drug park incentives in India concentrate new consumption growth.
- Agriculture:Pesticide and herbicide oxime synthesis consumes standard-grade aqueous material through established distributor networks.
- Chemical Manufacturing:Reducing agent applications in specialty chemical synthesis represent expanding margin pools as continuous catalytic hydrogenation improves yield economics.
- Textiles:Dyeing auxiliary applications occupy mature demand channels with price-sensitive procurement patterns.
Pharmaceuticals retains volume leadership; chemical manufacturing holds the steepest expansion curve.
Distribution Channel:
Customer type fragmentation separates integrated fab procurement from fragmented agricultural and textile purchasing.
- Direct Sales:Semiconductor manufacturers in Hsinchu and Pyeongtaek consolidate vendor relationships through chemical management outsourcing contracts spanning delivery, recovery, and waste treatment.
- Distributors:Agrochemical and textile customers rely on regional chemical distributors for standard-grade aqueous material.
- Online:Research-grade and small-volume specialty orders flow through B2B platforms serving pharmaceutical R&D laboratories.
- Retail:Limited to laboratory reagent sales through scientific supply channels.
Direct sales retains volume leadership; online channels hold the steepest expansion curve.
Application:
Supply concentration in East Asian electronics clusters shapes geographic deployment of technical resources.
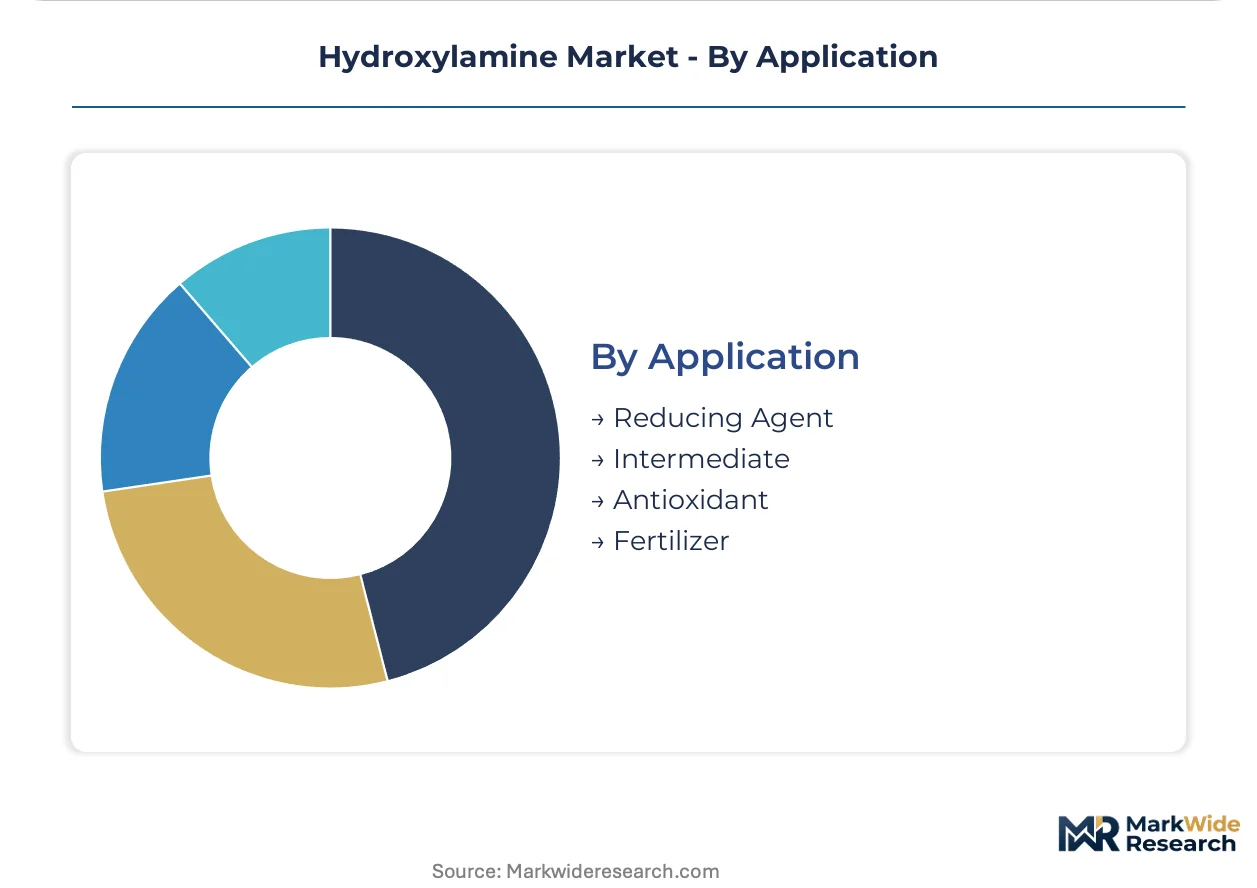
- Reducing Agent:Photoresist stripping and post-etch residue removal in semiconductor fabrication impose tightening purity tolerances for sub-2nm logic nodes. Samsung and TSMC process specifications drive anhydrous and in-situ generation adoption.
- Intermediate:Pharmaceutical API synthesis for cephalosporin antibiotics and agrochemical oxime production consumes standard aqueous grades through established supply chains.
- Antioxidant:Polymer stabilization and rubber processing applications occupy specialty chemical manufacturing segments.
- Fertilizer:Nitrogen-containing compound applications in agricultural inputs represent emerging demand development.
Reducing agent applications retain volume leadership; intermediate applications hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical complex buildouts in Zhejiang province and integrated chemical sites in Germany concentrate bulk hydroxylamine capacity, while semiconductor fab clusters in Taiwan and South Korea pull ultra-high-purity demand. Regulatory divergence across EPA, REACH, and China's MEE frameworks fragments compliance requirements for cross-border suppliers.
China
New nitric acid derivative plants in Zhejiang province expand standard-grade aqueous output for agrochemical oxime synthesis. MEE wastewater discharge standards force capital redeployment toward cleaner hydrogenation catalysts at existing facilities. Yangtze River Delta electronics manufacturers in Suzhou and Wuxi pull pharmaceutical-grade material for cephalosporin intermediate production.
Germany
BASF SE's Ludwigshafen integrated site sustains captive pharmaceutical-grade supply chains for European API manufacturers. ECHA REACH Article 33 substance-of-very-high-concern screening elevates compliance costs for importers, consolidating access for registered domestic producers. Dresden semiconductor fabs drive anhydrous grade specifications through direct chemical management contracts.
United States
EPA National Emission Standards for Hazardous Air Pollutants impose leak detection protocols on Pennsylvania and Texas production facilities. Semiconductor chemical suppliers prioritize closed-loop scrubbing investments over capacity expansion to maintain Clean Air Act operating permits. Domestic handlers face rigorous worker exposure limits that compress operational flexibility.
Japan
Mitsubishi Gas Chemical Company anchors high-purity output for East Asian semiconductor fabrication requirements. METI industrial standards govern nitric oxide feedstock handling in legacy catalytic hydrogenation infrastructure. Osaka and Kyushu-based analytical chemistry expertise concentrates ICP-MS and ion chromatography talent for parts-per-billion impurity quantification.
South Korea
TSMC and Samsung process engineers in Pyeongtaek specify in-situ generation modules for sub-2nm logic node photoresist stripping. MFDS pharmaceutical-grade certification timelines extend market entry barriers for greenfield API intermediate producers. Chemical management outsourcing contracts consolidate vendor relationships and displace traditional distributor channels.
Hydroxylamine Market Competitive Landscape
Integrated petrochemical conglomerates and specialized high-purity chemical producers split the market along purity-grade and end-use specialization lines. The structure favors players with backward integration into nitric acid feedstock or captive semiconductor fab relationships. Three archetypes dominate: diversified chemical majors with multi-site production networks, regional nitric acid derivative specialists with cost-advantaged hydrogenation capacity, and precision chemical suppliers focused on pharmaceutical-grade certification. Competitive dynamics center on capacity expansion in Zhejiang province and strategic partnerships for direct-to-fab chemical management contracts.
Among diversified chemical majors, BASF SE and UBE Industries exemplify integrated production archetypes with multi-regional manufacturing footprints. Mitsubishi Gas Chemical Company occupies a specialist position in high-purity electronics-grade supply. These three entities represent distinct strategic postures: Ludwigshafen-based integrated chemical production, nitric acid backward integration, and East Asian semiconductor-focused purity specialization.
| Leading Market Players |
|---|
| UBE Industries |
| BASF SE |
| Merck |
| Mitsubishi Gas Chemical Company |
| Evonik Industries |
| Lonza Group |
| Jarchem Industries Inc. |
| SABIC |
| Zhejiang Jianye Chemical |
| Others |
Supply & Pricing Matrix
Yangtze River Delta container freight corridors connecting Zhejiang production bases to Taiwan and South Korea fab clusters transmit feedstock cost volatility directly into electronics-grade hydroxylamine premiums, while REACH compliance overhead stratifies European pharmaceutical-grade pricing against commodity aqueous material.
Pricing Analysis
EPA National Emission Standards for Hazardous Air Pollutants dictate the pricing tier structure across the hydroxylamine market. Three-tier pricing separates pharmaceutical-grade certified material from standard aqueous grades and economy textile formulations, with EMA and FDA master file preparation costs anchoring premium positioning. Cost compression in anhydrous grades is intensifying because continuous catalytic hydrogenation collapses production economics between aqueous and anhydrous trains. Agrochemical oxime synthesis buyers exhibit highest price sensitivity, while semiconductor fabs in Hsinchu and Pyeongtaek absorb premium positioning for sub-2nm node compatibility.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for hydroxylamine procurement. Production gravity centers on Zhejiang province, Germany's Ludwigshafen complex, and Japan's Osaka-Kyushu corridor, with nitric acid, ammonia, and platinum-group metal catalysts feeding catalytic hydrogenation trains. Single-source vulnerability concentrates in East Asian electronics-grade purification capacity, where ICP-MS analytical expertise remains geographically locked. Distribution runs through direct chemical management contracts at integrated semiconductor campuses, displacing traditional bulk distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Point-of-use generation systems and alternative reducing chemistries threaten incumbent hydroxylamine suppliers as semiconductor fabs seek to eliminate moisture contamination risks and transport instability constraints entirely.
For Market Incumbents: Pre-empt substitution pressure from in-situ generation modules by embedding on-site production partnerships at Dresden and Singapore fabs before process engineers lock in alternative specifications. Secure backward integration into nitric acid feedstock at Zhejiang and Antwerp sites to defend margin position against ammonia oxidation cost swings. Pharmaceutical-grade certification investments at Ludwigshafen anchor European API manufacturer loyalty against Indian bulk drug park entrants. For New Entrants and Emerging Players: Establish a beachhead in India's cephalosporin intermediate synthesis segment, where CDSCO bulk drug park incentives concentrate demand growth ahead of domestic capacity buildout. Target green hydrogen integration for catalytic hydrogenation trains to capture EU Green Deal carbon border adjustment premiums before incumbents retrofit legacy assets. Lead with closed-loop scrubbing compliance packages that preempt EPA enforcement exposure for Pennsylvania and Texas handlers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical majors seeking to divest legacy nitromethane reduction assets rendered obsolete by continuous catalytic hydrogenation economics. Long-term viability hinges on exposure to semiconductor fab chemical management outsourcing contracts rather than spot-market commodity positioning. Watch for inflection when TSMC and Samsung process engineers finalize sub-2nm node material specifications that either validate or displace anhydrous hydroxylamine entirely.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitric Acid | UBE Industries' captive feedstock control insulates margin structures from Henry Hub volatility. |
| Green Hydrogen Feedstock Transition | Electrolytic hydrogen substitution aligns BASF Ludwigshafen output with EU carbon border mechanisms. |
| Point-of-Use Generation Deployment | Samsung Pyeongtaek in-situ modules eliminate thermal instability constraints above 15°C. |
| Pharmaceutical-Grade Certification Investment | EMA master file preparation extends 18-24 month barriers against Indian CDSCO park entrants. |
| Direct-to-Fab Chemical Management Contract | Dresden semiconductor consolidation squeezes independent distributors from photoresist stripping value chains. |
Research Methodology
A standing panel of plant managers at nitric acid derivative facilities, procurement leads at Taiwan and South Korea semiconductor fabs, distribution channel partners in agrochemical networks, and technical R&D directors at pharmaceutical API manufacturers provided ongoing calibration across the study. Primary interview insights triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from diversified chemical majors, and EPA enforcement records. Bottom-up capacity and consumption estimates reconciled with top-down trade flow analysis across the projection horizon.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation modeling spanning purity grade tiers, end-use industry verticals, and regional production hub clusters. CAGRs derived from installed capacity expansion timelines, fab buildout schedules, and regulatory compliance cost trajectories. Forecast inputs incorporated platinum-group metal catalyst pricing, natural gas benchmark volatility, and semiconductor node transition roadmaps.
Stress conditions across nitric acid feedstock pricing, EPA enforcement intensity, and EU REACH substance screening scope were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding catalytic hydrogenation yield improvements and pharmaceutical-grade certification timelines. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
Europe Fine Chemical Market
High-Value Chemicals
Ultra-High Purity Hydrofluoric Acid Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
High Friction Films Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Hydrogen Isotope Market
High-Value Chemicals
High Purity Magnesium Citrate Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market