
 Global Hydrofluoric Acid Market | 2026-2036
Global Hydrofluoric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydrofluoric Acid Market Intelligence
A shift from multi-sourcing towards dedicated single-supplier contracts for high-purity grades is recalibrating procurement strategies for semiconductor fabricators. Honeywell International Inc. leverages its significant manufacturing scale in refrigerant and fluorocarbon production. Solvay competes through its broad portfolio of specialty polymers and chemical intermediates derived from hydrofluoric acid. Meanwhile, Daikin Industries, Ltd. specializes in advanced fluorochemicals for niche electronics and automotive applications.
Hydrofluoric acid is a highly corrosive solution of hydrogen fluoride in water, existing in both anhydrous and aqueous forms. It serves as a critical precursor in the production of fluorocarbons and as a powerful etching agent in various industrial processes. Fluorocarbon production and refrigerant manufacturing constitute the largest application segments by volume, though they are relatively mature. The fastest expansion is observed in demand for high-purity reagent grade material, driven by semiconductor fabricators and electronics producers.
Strict handling, transport, and disposal protocols are mandated by agencies such as the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) under REACH. In parallel, China's Ministry of Ecology and Environment (MEE) enforces rigorous emissions controls on fluorspar processing and acid production facilities. Navigating raw material supply security for fluorspar while adhering to evolving environmental standards will define competitive success for producers.
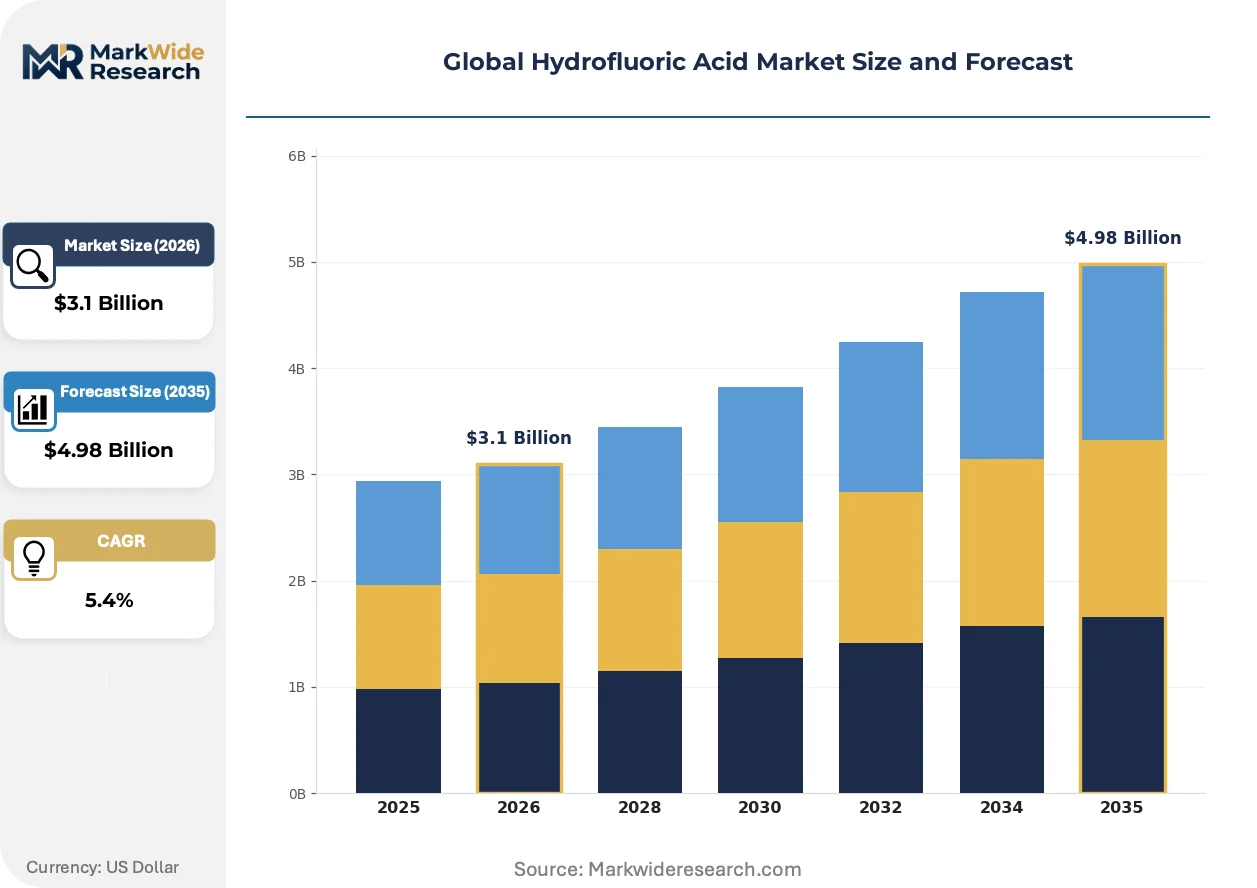
Market Dynamics
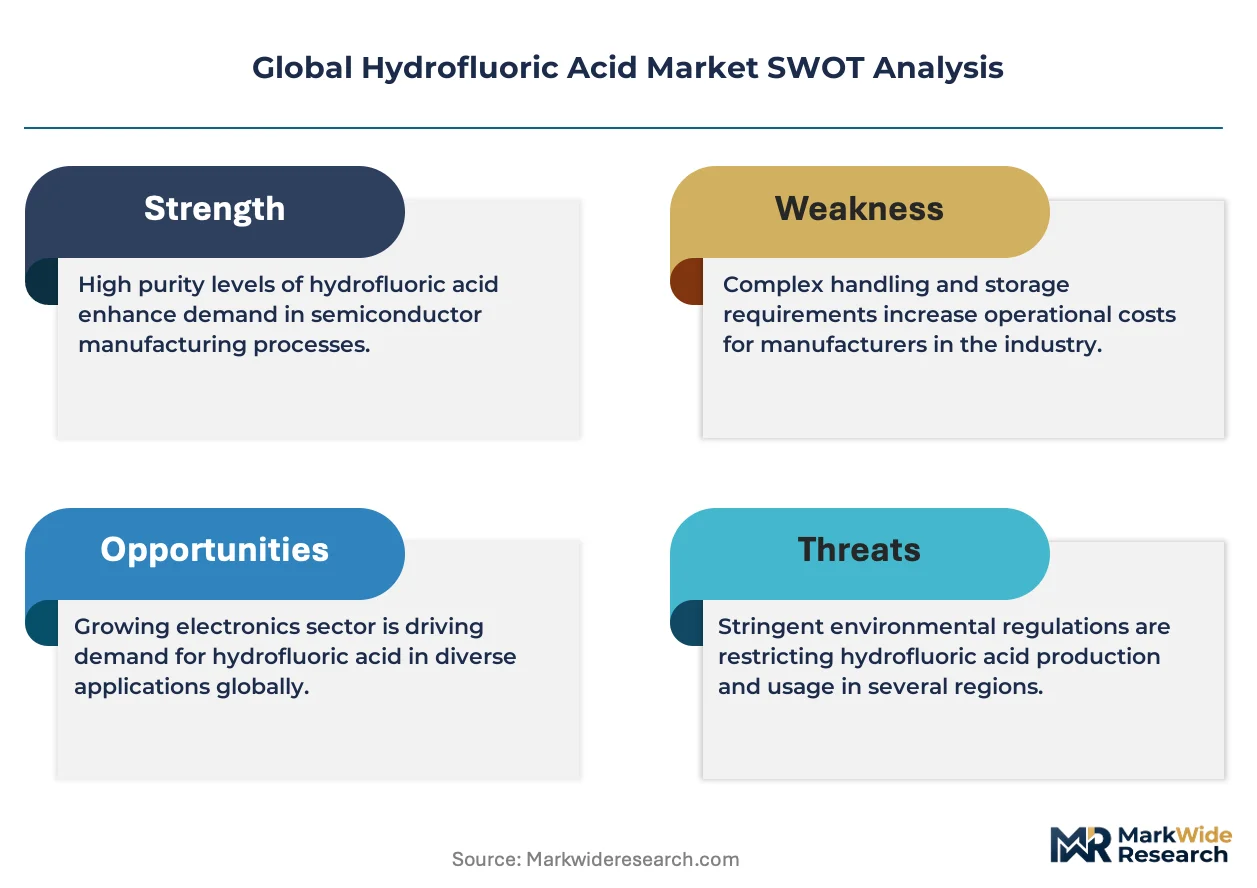
Demand for ultra-high purity grades from semiconductor manufacturing is pulling the market forward. This pull is counteracted by intense regulatory scrutiny over production emissions and transport safety, particularly concerning fluorspar processing and acid handling protocols globally.
Growth Catalysts
- EU F-Gas Regulation:This framework's mandate to phase down high-GWP refrigerants directly stimulates demand for hydrofluoric acid, a critical precursor in the production of alternative hydrofluoroolefins (HFOs).
- Semiconductor Fabrication Demand:The expansion of advanced logic and memory chip manufacturing requires ultra-high purity grades for precise silicon wafer etching, creating a significant value-add segment for specialized producers.
- Fluoropolymer Synthesis:Growth in automotive and chemical processing industries boosts consumption of fluoropolymers like PTFE and FKM, which are synthesized from hydrofluoric acid and used in demanding applications.
Market Restraints
- Raw Material Dependency:The market's reliance on fluorspar, with production heavily concentrated in China, exposes producers to significant price volatility and potential geopolitical supply chain disruptions.
- Safety and Handling Costs:The extreme corrosivity and toxicity of hydrofluoric acid necessitate expensive, specialized materials for storage and transport, and mandate strict compliance with ECHA and EPA handling protocols.
- High Capital Intensity:Establishing or expanding production capacity, particularly for high-purity grades, requires substantial investment in corrosion-resistant reactors, purification systems, and stringent environmental control technologies.
Strategic Opportunities
- On-Site Generation Systems:Developing modular, on-site hydrofluoric acid generation and recycling systems for large semiconductor fabricators presents an opportunity to improve supply chain security and reduce transportation risks.
- Rare Earth Element Recycling:The use of hydrofluoric acid as a leaching agent in hydrometallurgical processes for recycling rare earth elements from e-waste offers a new, high-value application stream.
- Domestic Supply Chain Initiatives:Government programs in the United States and Europe aimed at reshoring semiconductor manufacturing create opportunities for new, localized high-purity acid production facilities.
Industry Challenges
- Specialized Talent Scarcity:A limited pool of chemical engineers and plant operators with the requisite experience in handling highly hazardous fluorochemicals and managing corrosion-resistant infrastructure creates operational bottlenecks.
- Logistical Complexity:Adhering to a fragmented and stringent set of international and domestic transport regulations for a highly toxic substance complicates global supply chain management and increases logistics costs.
- Emission Control Compliance:Producers face the challenge of investing in and retrofitting facilities to comply with tightening air and water emission standards from regulators like China's MEE without disrupting production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydrofluoric Acid Market |
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $4.98 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aqueous Solution, Anhydrous, Stabilized Grade, Industrial Grade, Reagent Grade Application: Refrigerant Manufacture, Oil Refining, Glass Etching, Metal Pickling, Fluorocarbon Production End User Industry: Chemical Manufacturers, Semiconductor Fabricators, Petroleum Refiners, Metal Processing Plants, Electronics Producers Packaging Type: Drums, Iso Containers, Tank Trucks, Cylinders, Bulk Containers |
| Companies Covered | Daikin Industries, Ltd., Morita Chemical Industries Co., Ltd., Honeywell International Inc., Foosung Co., Ltd., Derivados del Fluor, S.A.U., Solvay, LANXESS, Orbia Fluor & Energy Materials, Stella Chemifa Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydrofluoric Acid Market Strategic Shifts & Innovations
A fundamental bifurcation is occurring within the hydrofluoric acid market. Innovation focuses on purification technologies and supply chain models for electronics applications, while the larger industrial segment centers on production efficiency and regulatory compliance.
Point-of-use generation and advanced recycling systems represent a significant technological shift for high-volume consumers. Semiconductor fabricators are early adopters, seeking to ensure supply continuity and consistent purity for their sensitive manufacturing processes. This adoption is decentralizing supply from bulk chemical distribution networks to localized, closed-loop systems within the fab itself, enhancing resilience.
China's Ministry of Ecology and Environment (MEE) continues to enforce stringent environmental standards on the fluorspar processing and acid manufacturing sectors. These policies mandate significant capital investment in emission control systems, leading to industry consolidation as smaller, non-compliant plants exit. The global fluorocarbon and refrigerant supply chains are most impacted, experiencing tighter supply from production curbs in China.
Long-term, single-source contracts are increasingly replacing traditional multi-sourcing strategies for high-purity hydrofluoric acid. This model favors suppliers capable of providing extensive quality documentation, dedicated production lines, and transparent supply chain audits, displacing transactional purchasing. This shift in procurement is most evident among leading-edge semiconductor manufacturers in South Korea and Taiwan seeking to mitigate supply risks.
Global Hydrofluoric Acid Market Segmentation
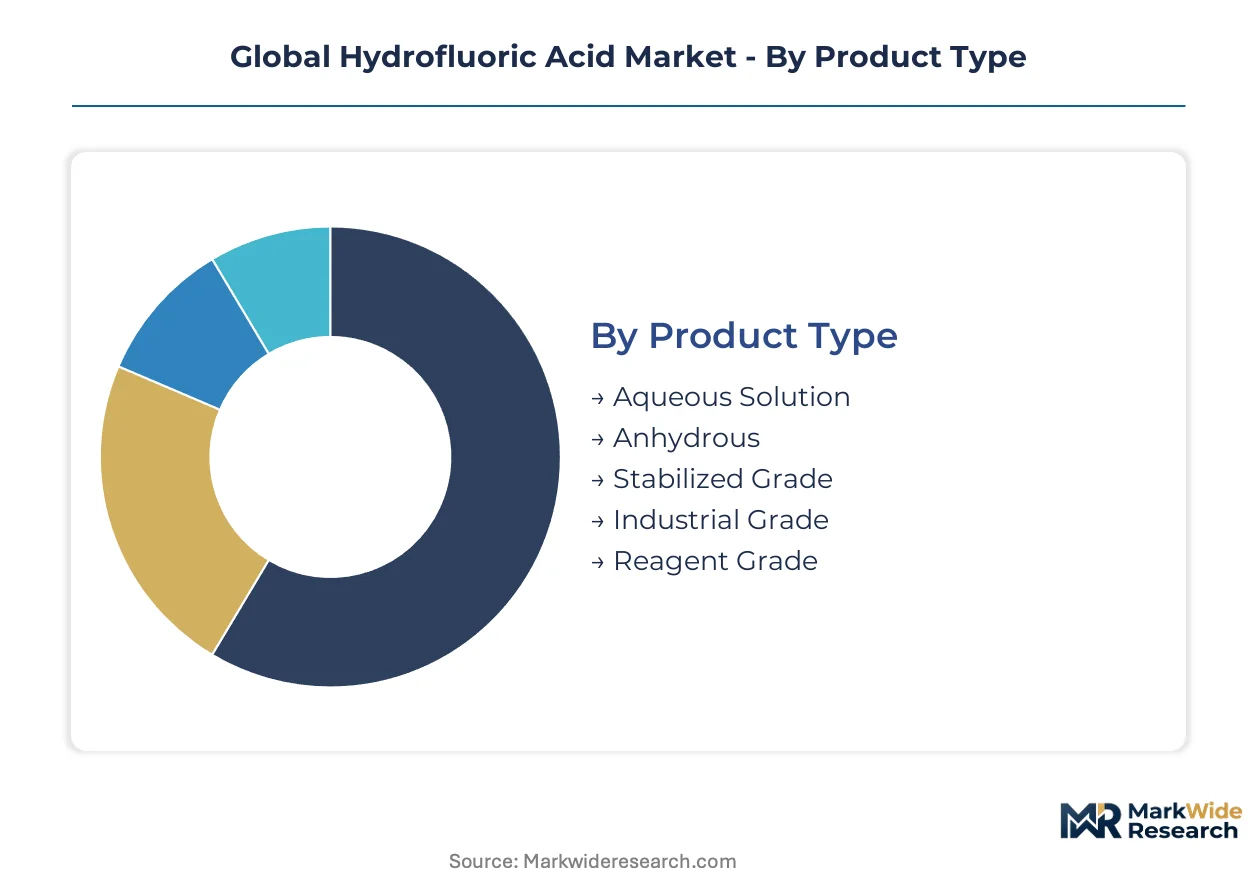
The hydrofluoric acid market exhibits distinct segmentation, driven by varying purity requirements, application specificities, and logistical considerations. Understanding these segments is crucial for producers to align product offerings with precise industrial demands and evolving regulatory landscapes.
Product Type:
The hydrofluoric acid market segments by product type reflect varying integration depths, from raw chemical forms to highly refined grades for embedded system use.
- Aqueous Solution:Aqueous solutions of hydrofluoric acid, diluted forms with specific water concentrations, find broad utility in industrial cleaning and glass processing applications.
- Anhydrous:Anhydrous hydrofluoric acid, a highly concentrated form with minimal water content, serves as a crucial building block in fluorocarbon synthesis. Demand from refrigerant manufacturers drives its consumption, particularly with the global transition to lower global warming potential (GWP) alternatives under the EU F-Gas Regulation.
- Stabilized Grade:Stabilized grades incorporate specific additives to reduce reactivity, improving safety and extending shelf life for specialized industrial uses.
- Industrial Grade:Industrial grade hydrofluoric acid, a standard purity level, supports large-scale chemical manufacturing and metal treatment processes.
- Reagent Grade:Reagent grade hydrofluoric acid boasts ultra-high purity, essential for precision applications requiring minimal impurities. Semiconductor fabricators in South Korea and Taiwan are concentrating demand for this grade, driven by the need for exact silicon wafer etching in advanced chip production.
Anhydrous hydrofluoric acid leads volumes today; Reagent Grade is gaining share fastest.
Application:
Segmentation by application highlights how hydrofluoric acid's diverse chemical properties enable its use across distinct industrial processes, often with varying volume requirements.
- Refrigerant Manufacture:Hydrofluoric acid is a vital precursor for producing fluorinated refrigerants, including HFCs and newer hydrofluoroolefins (HFOs), which are crucial for air conditioning and refrigeration systems. The EU F-Gas Regulation directly stimulates demand here, pushing towards sustainable refrigerant alternatives.
- Oil Refining:Oil refining operations utilize hydrofluoric acid as a catalyst in alkylation units, improving gasoline octane ratings and overall fuel quality.
- Glass Etching:Glass etching employs hydrofluoric acid for precise surface modification in display manufacturing, optical component fabrication, and decorative glass production.
- Metal Pickling:Metal pickling processes use hydrofluoric acid to remove oxides and impurities from stainless steel, titanium, and other specialized alloys before further processing.
- Fluorocarbon Production:Fluorocarbon production, a large-scale chemical process, relies on hydrofluoric acid as a fundamental reactant for creating a wide array of fluorinated compounds. Chemical manufacturers in China anchor significant demand, leveraging hydrofluoric acid for polymers and other specialty chemicals.
Fluorocarbon production represents the largest volume segment; glass etching and metal pickling are expanding steadily.
End User Industry:
The end user industry segmentation reveals the maturity levels and specific purity requirements driving hydrofluoric acid consumption across various sectors.
- Chemical Manufacturers:Chemical manufacturers consume large volumes of industrial-grade hydrofluoric acid as a primary reactant for synthesizing a vast range of fluorinated compounds and polymers. China's chemical industry anchors significant demand for these foundational chemical processes.
- Semiconductor Fabricators:Semiconductor fabricators demand ultra-high purity hydrofluoric acid for critical etching and cleaning steps in microchip manufacturing. Electronics producers in Taiwan and South Korea are driving this high-value segment, requiring stringent quality control and consistent supply.
- Petroleum Refiners:Petroleum refiners utilize hydrofluoric acid in alkylation processes to produce high-octane gasoline components, contributing to fuel efficiency and performance.
- Metal Processing Plants:Metal processing plants apply hydrofluoric acid for surface treatment, pickling, and cleaning of various metals, ensuring material integrity and preparation for subsequent manufacturing.
- Electronics Producers:Electronics producers, beyond semiconductors, use hydrofluoric acid for cleaning and etching in printed circuit board (PCB) manufacturing and display production, ensuring circuit precision.
Semiconductor fabricators drive the highest-value demand; chemical manufacturers account for the largest volume consumption.
Packaging Type:
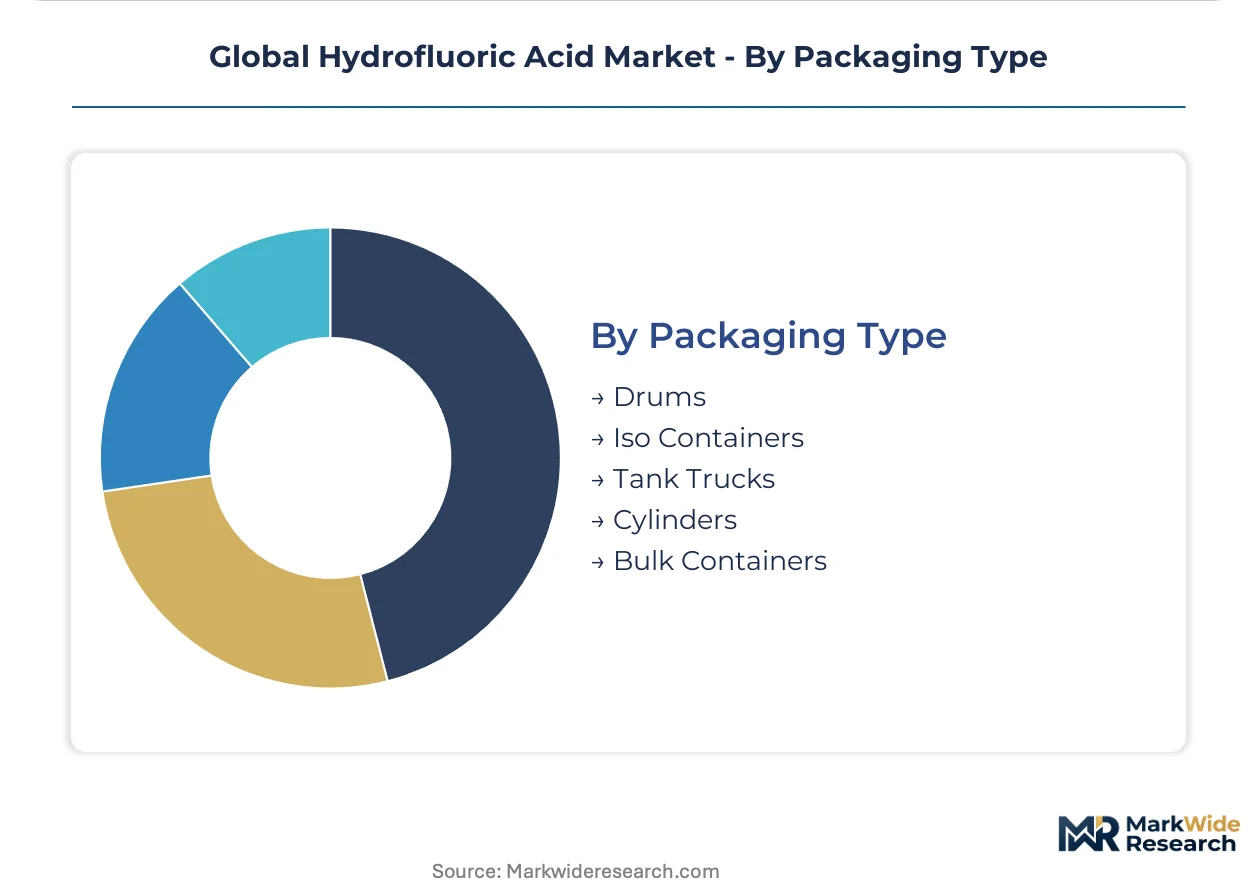
Packaging type segmentation illustrates the cost tiers and logistical considerations associated with hydrofluoric acid delivery, reflecting safety and volume requirements.
- Drums:Drums are used for smaller quantities of hydrofluoric acid, suitable for laboratories, specialized industrial applications, and regions with limited bulk infrastructure.
- Iso Containers:Iso containers facilitate the secure and efficient bulk transport of hydrofluoric acid across international borders and long distances. Their robust construction and specialized linings ensure safety for significant volumes, particularly for intercontinental trade between Asia and Europe.
- Tank Trucks:Tank trucks provide dedicated, large-volume road transport for hydrofluoric acid, primarily for regional distribution to industrial customers. Specialized drivers and corrosion-resistant materials are essential for adhering to strict transport regulations within countries like the United States.
- Cylinders:Cylinders store hydrofluoric acid gas or smaller liquid volumes, often for laboratory use, specialized research, or processes requiring precise dosing.
- Bulk Containers:Bulk containers, including railcars and barges, move very large volumes of hydrofluoric acid between major production sites and large consumers, optimizing cost-efficiency for high-volume transfers.
Tank trucks and iso containers handle the majority of hydrofluoric acid volume; drums serve niche, lower-volume requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's industrial chemical complex anchors the global hydrofluoric acid market, driving both production and consumption volumes. This market is bifurcated by purity requirements, with high-purity grades concentrated in East Asian semiconductor hubs and industrial grades widespread across other regions. Regulatory frameworks significantly influence regional supply dynamics.
China
China's chemical manufacturers and fluorocarbon producers generate substantial demand for industrial-grade hydrofluoric acid. The Ministry of Ecology and Environment (MEE) enforces stringent emissions controls on fluorspar processing and acid production. Shandong and Zhejiang provinces house major chemical clusters, impacting global supply chains with their production capacities.
South Korea
South Korean semiconductor fabricators demand ultra-high purity reagent grade hydrofluoric acid for advanced chip manufacturing processes. The country's government supports domestic supply chain initiatives to reduce reliance on external suppliers for critical materials. Gyeonggi Province, home to major electronics producers, drives this specialized, high-value segment.
United States
United States' semiconductor reshoring efforts stimulate demand for localized high-purity hydrofluoric acid production. The US Environmental Protection Agency (EPA) mandates strict handling and disposal protocols for corrosive chemicals, influencing facility design. Arizona and Texas are emerging as key hubs for new fabrication plants, requiring secure material sourcing.
Germany
Germany's chemical and automotive industries consume hydrofluoric acid for fluoropolymer synthesis and specialized metal treatment. The European Chemicals Agency (ECHA) under REACH sets rigorous standards for chemical safety and environmental protection. The Rhine-Ruhr region, a historic chemical production area, continues to be a center for industrial acid applications.
Taiwan
Taiwanese electronics producers, particularly in the semiconductor sector, require consistent supplies of ultra-high purity hydrofluoric acid. The government promotes supply chain resilience through strategic partnerships and local capacity building for critical raw materials. Hsinchu Science Park, a global semiconductor powerhouse, concentrates significant demand for these specialized chemicals.
Global Hydrofluoric Acid Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche high-purity segments and sustainable solutions. The market exhibits a tiered structure, with a few large integrated chemical companies dominating industrial grades and specialized players focusing on electronics applications. Companies pursue strategic partnerships to secure raw material supply and invest in capacity expansion for high-purity production. Portfolio diversification into advanced fluorochemicals also represents a key competitive move.
Specialists in advanced fluorochemicals include Daikin Industries, Ltd., leveraging its expertise in niche electronics and automotive applications. Honeywell International Inc. occupies a position as a large-scale manufacturer, particularly in refrigerant and fluorocarbon production, demonstrating significant manufacturing scale. Solvay represents a diversified chemical player, offering a broad portfolio of specialty polymers and chemical intermediates derived from hydrofluoric acid. These companies anchor different segments of the market through their distinct product focus, operational scale, and strategic emphasis on specific end-user requirements. Their long-standing presence and technical capabilities are critical for maintaining supply chain stability.
| Leading Market Players |
|---|
| Daikin Industries, Ltd. |
| Morita Chemical Industries Co., Ltd. |
| Honeywell International Inc. |
| Foosung Co., Ltd. |
| Derivados del Fluor, S.A.U. |
| Solvay |
| LANXESS |
| Orbia Fluor & Energy Materials |
| Stella Chemifa Corporation |
| Others |
Cost & Logistics Intelligence
The global fluorspar price index significantly influences hydrofluoric acid pricing, cascading through various purity grades and application segments. This volatility shapes long-term contract negotiations and spot market rates for industrial and reagent grades.
Pricing Analysis
Input-cost pass-through mechanisms are critical, especially for fluorspar, which drives pricing across all hydrofluoric acid grades. The dominant pricing model combines long-term contracts for high-purity reagent grades with transactional spot pricing for industrial volumes. Price differentiation stems from purity level, with ultra-high purity material commanding a premium, and from volume scale. Pricing pressure intensifies due to escalating environmental compliance costs and raw material supply constraints. Semiconductor fabricators exhibit the lowest price sensitivity for specialized grades, while industrial users of aqueous solutions are highly sensitive.
Supply Chain Analysis
Logistics and freight costs significantly impact hydrofluoric acid's delivered price, given its hazardous nature and specialized transport requirements. Supply concentration centers heavily on China for both fluorspar extraction and acid production. The market relies on fluorspar as a critical raw material, exposing producers to geopolitical supply chain disruptions and price volatility. Distribution runs through a dual model: bulk chemical distribution for industrial grades and increasingly localized, on-site generation systems for high-purity semiconductor applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrofluoric acid market presents a geographic-arbitrage play, driven by the significant regulatory cost differential between China's stringent environmental controls and less regulated production in other regions. This disparity impacts production costs and supply availability for global consumers.
For Market Incumbents: To counter raw material supply chain vulnerability and geopolitical risks, incumbents should diversify fluorspar sourcing beyond China. Invest in advanced purification technologies and expand high-purity production capacity in regions like the United States and Europe. Securing long-term supply agreements with key semiconductor fabricators also stabilizes demand.
For New Entrants and Emerging Players: Semiconductor fabricators seeking localized and resilient supply represent a key underserved buyer archetype. Target niche opportunities in on-site generation and recycling systems for high-purity hydrofluoric acid. A go-to-market strategy emphasizing closed-loop solutions and strong environmental compliance can differentiate new players.
For Investors and Strategic Acquirers: Consolidation pressure builds where high capital intensity and stringent regulatory compliance create barriers to entry for smaller players. The long-term viability of hydrofluoric acid as a foundational chemical, especially for high-purity electronics, remains strong. Target specialized producers with proprietary purification technologies or established regional supply chains. A key signal to watch is increased government incentives for domestic high-purity acid production in the United States or Europe.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Support growing demand from semiconductor manufacturing in Taiwan and South Korea. |
| Backward Integration | Secure fluorspar supply to mitigate raw material price volatility. |
| Green Manufacturing Transition | Comply with China's MEE emissions standards and gain competitive advantage. |
| Long-term Supply Agreement | Ensure consistent supply and pricing stability for electronics producers. |
| Joint Venture | Develop on-site generation systems for large-scale semiconductor fabricators in Arizona. |
Research Approach
Coverage spans China, South Korea, the United States, Germany, and Taiwan, with primary inputs from each region. Research involved interviews with plant managers, procurement leads at semiconductor fabricators, and chemical R&D directors. Secondary data sources included customs/trade data, ECHA/EPA regulatory documents, and company filings. This approach ensured robust bottom-up data collection, triangulated with top-down market sizing.
Rate-of-change decomposition formed the core analytical framework, projecting market evolution across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, and packaging format, alongside regulatory compliance costs. Compound annual growth rates were derived from historical growth patterns and future demand drivers. Key industry-specific forecast inputs included fluorspar availability and semiconductor fab expansion plans.
Underlying measurement precision varies by segment; reagent grade and semiconductor fabricator demand carry tighter precision than others. Forecasts reflect assumptions, but geopolitical shifts, sudden regulatory changes, and raw material supply shocks represent risk factors. Stakeholders should weigh these assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
High Purity Benzenethiol Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
Global High Potency Apis /HPAPI Market
High-Value Chemicals
Sodium Hexametaphosphate Market
High-Value Chemicals
High Purity Magnesium Citrate Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market
High-Value Chemicals
Hydrogen Cyanide Market
High-Value Chemicals
High-Heat Melamine Foam Market
High-Value Chemicals
High-K Dielectric Material Market