
 Friction Reducers Market | 2026-2036
Friction Reducers Market Size, Share, and Industry Trends Forecast 2026-2036
Friction Reducers Market Foresight
Aftermarket fluid reconditioning revenue is narrowing as operators shift toward single-use polymer systems designed for higher shear tolerance. Halliburton leverages its integrated wellsite chemistry services to capture recurring demand across major North American shale plays. Clariant anchors its position through specialty polymer manufacturing scale in European supply hubs. Dow competes on acrylamide-based chemistry cost curves that underpin mid-tier product lines.
Friction reducers are polymeric or surfactant-based additives, typically high-molecular-weight polyacrylamides or modified glycols, that lower pumping pressure by reducing turbulent flow resistance in tubular systems. These chemicals function by aligning long-chain molecules along flow streamlines, cutting frictional pressure losses by up to 80 percent in high-rate hydraulic fracturing operations. Polymer formulations dominate value capture due to their established performance in high-salinity reservoir conditions, while surfactant blends represent the fastest-growing category as operators address compatibility with recycled produced water. Hydraulic fracturing applications command the largest deployment volume, though enhanced oil recovery segments attract premium pricing for thermally stable chemistries.
The EPA regulates friction reducer constituents under the Toxic Substances Control Act, requiring pre-manufacture notification for novel polyacrylamide chemistries, while OSHA mandates exposure controls for acrylamide monomer residuals at wellsite blending facilities. State regulators in Texas and Colorado impose additional chemical disclosure thresholds that shape supplier formulation transparency. REACH compliance in Europe restricts certain cationic polymer chemistries, redirecting R&D investment toward biodegradable alternatives. Stakeholders must monitor evolving state-level fracturing fluid disclosure mandates and assess how produced water reuse regulations alter polymer compatibility requirements.
Market Dynamics
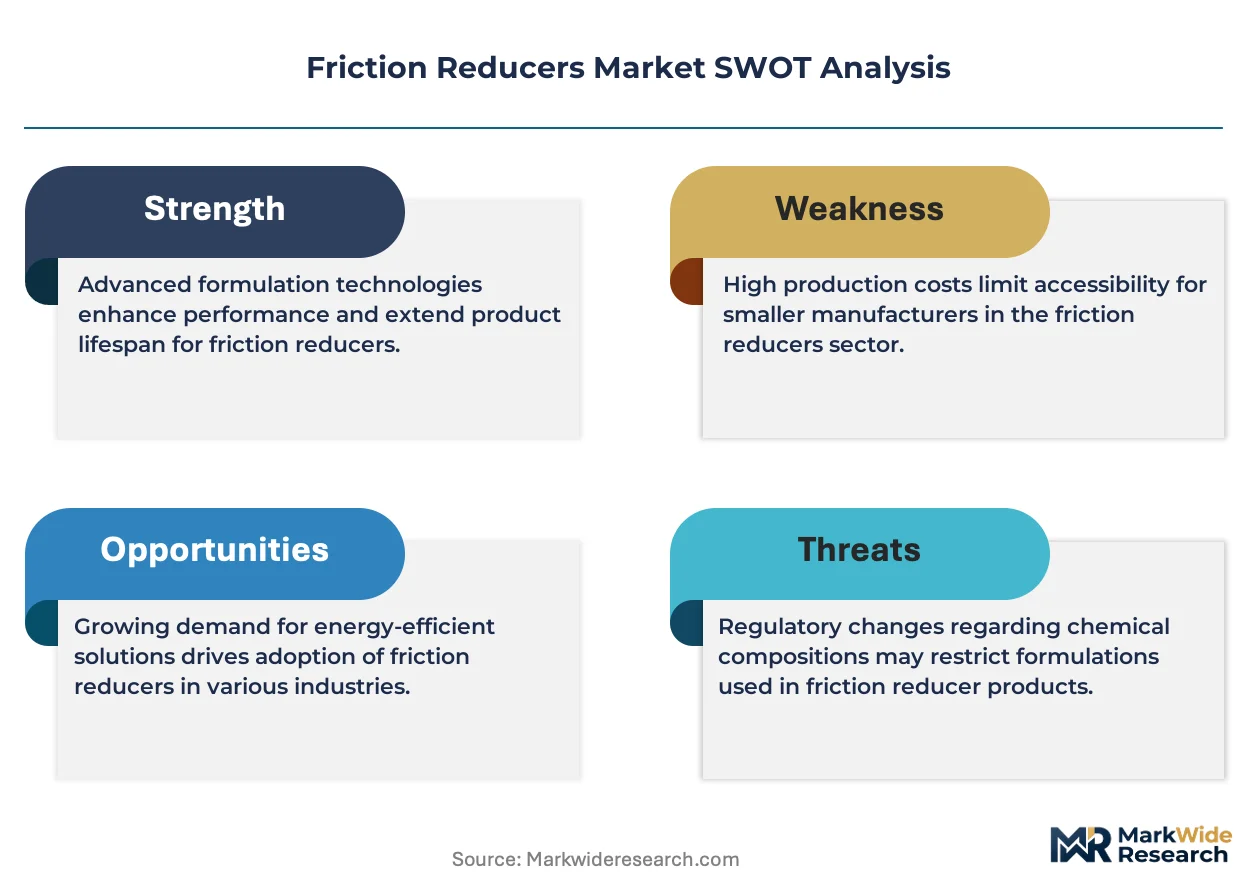
The shift toward single-use polymer systems with higher shear tolerance is compressing aftermarket fluid reconditioning revenue and forcing suppliers to capture value through integrated wellsite chemistry services rather than recurring hardware sales.
Growth Catalysts
- EPA Chemical Disclosure Rules:Updated disclosure thresholds for hydraulic fracturing fluids are accelerating demand for transparent, pre-certified polymer formulations that streamline operator compliance in Texas and Colorado.
- Produced Water Reuse Mandates:Surfactant-based friction reducers compatible with recycled brine are displacing conventional chemistries in Permian Basin operations seeking to cut freshwater procurement costs.
- Permian Basin Concentration:Operator clustering in West Texas and southeastern New Mexico is concentrating demand for high-flow-rate polymer systems that reduce pumping pressure by up to 80 percent.
Market Restraints
- Acrylamide Monomer Volatility:OSHA exposure controls at wellsite blending facilities impose capital-intensive ventilation and monitoring systems that elevate fixed costs for mid-tier suppliers.
- REACH Compliance Burden:ECHA restrictions on cationic polymer chemistries in Europe are forcing R&D redirection toward biodegradable alternatives with unproven field performance.
- Polymer Supply Concentration:Specialty acrylamide manufacturing scale concentrates among European chemical hubs, creating import dependency for North American friction reducer blenders.
Strategic Opportunities
- Enhanced Oil Recovery Premium Segment:Thermally stable polymer chemistries for high-temperature reservoirs command pricing multiples above standard hydraulic fracturing applications.
- Biodegradable Polymer Development:EU Green Deal funding mechanisms and REACH-driven formulation gaps create first-mover advantage for suppliers investing in enzymatically degradable polyacrylamide alternatives.
- Integrated Service Contracts:Bundling friction reducer supply with real-time friction monitoring and automated dosing systems is displacing transactional chemical sales in major shale plays.
Industry Challenges
- Polymer Compatibility Engineering:Formulating high-molecular-weight polyacrylamides that maintain viscosity in high-salinity produced water requires specialized rheology expertise scarce among regional blenders.
- State Disclosure Fragmentation:Divergent chemical reporting thresholds across Texas Railroad Commission, Colorado Oil and Gas Conservation Commission, and New Mexico Environment Department force redundant product registration and labeling systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Friction Reducers Market |
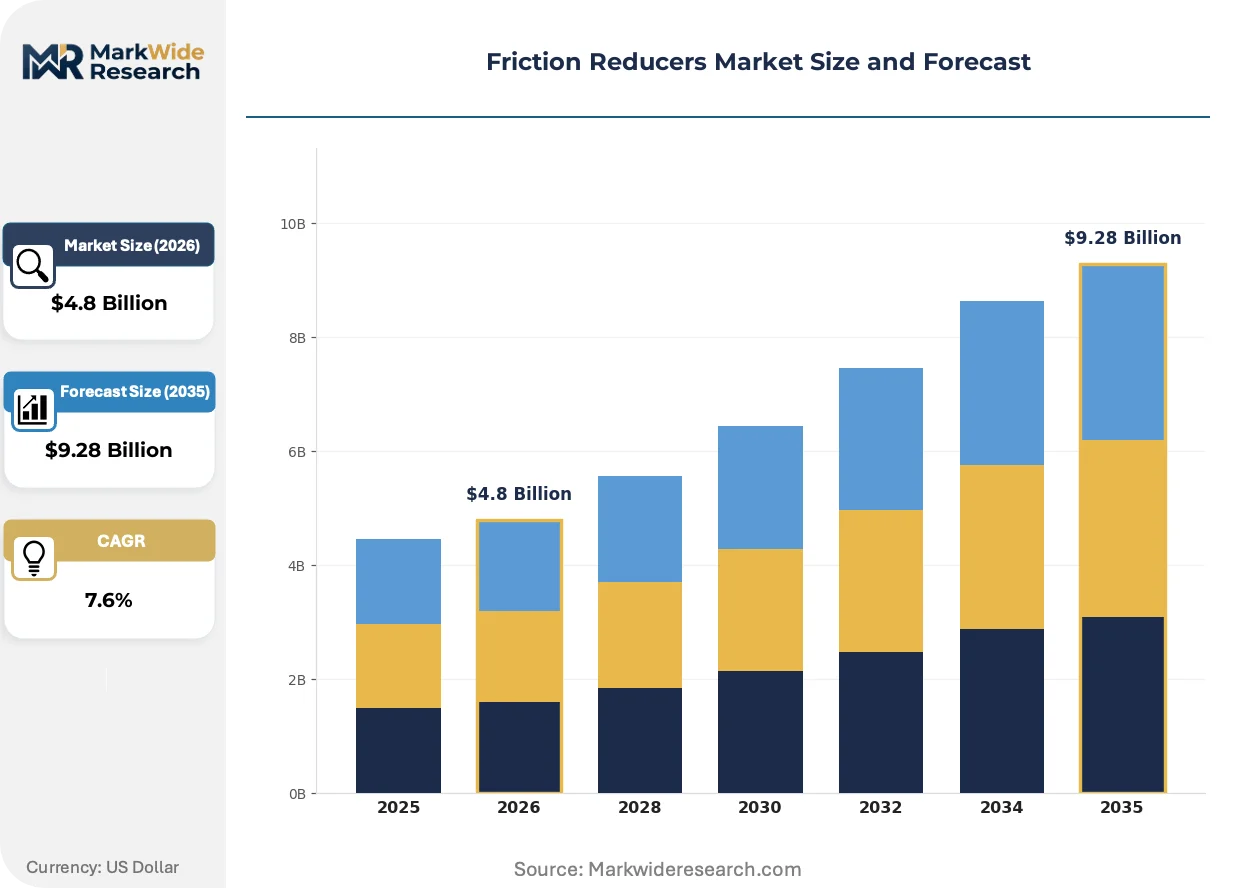
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
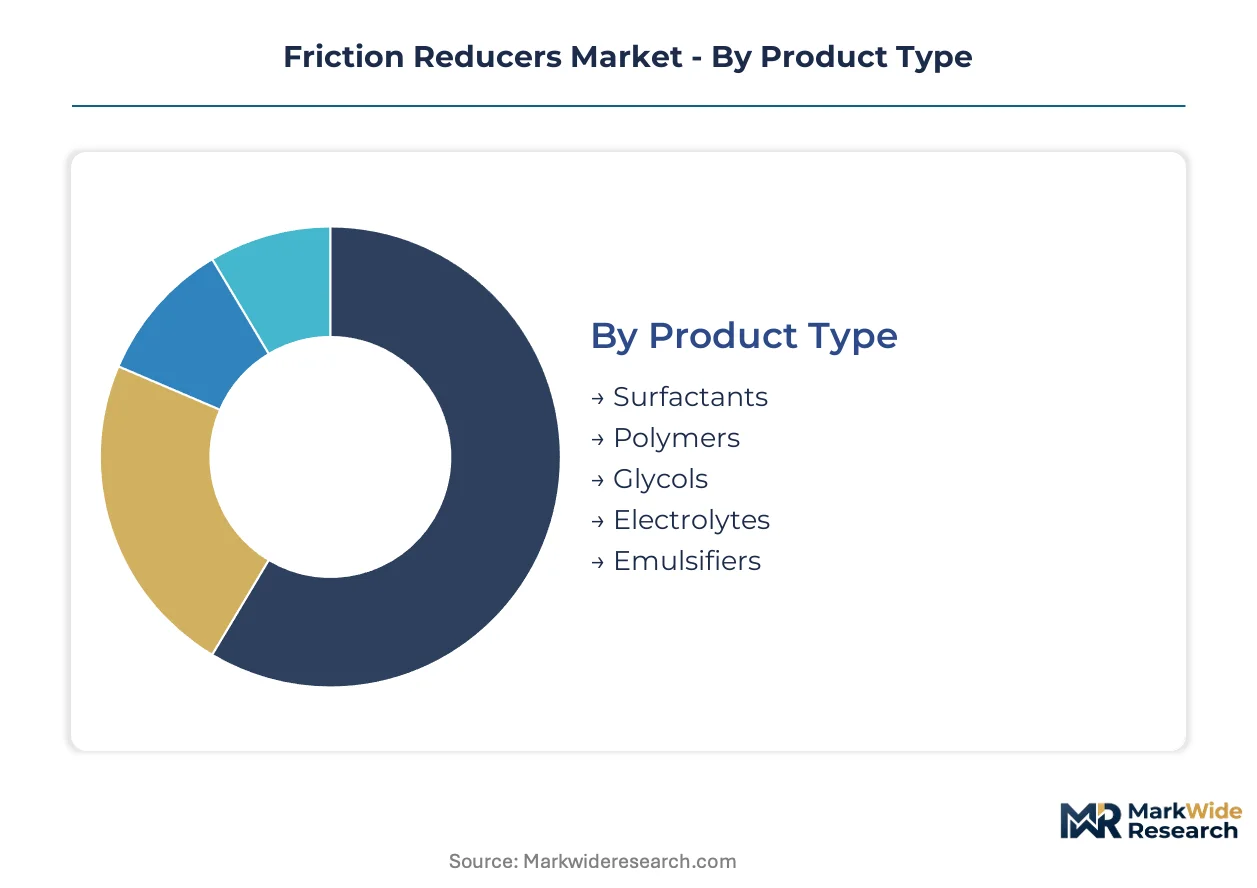
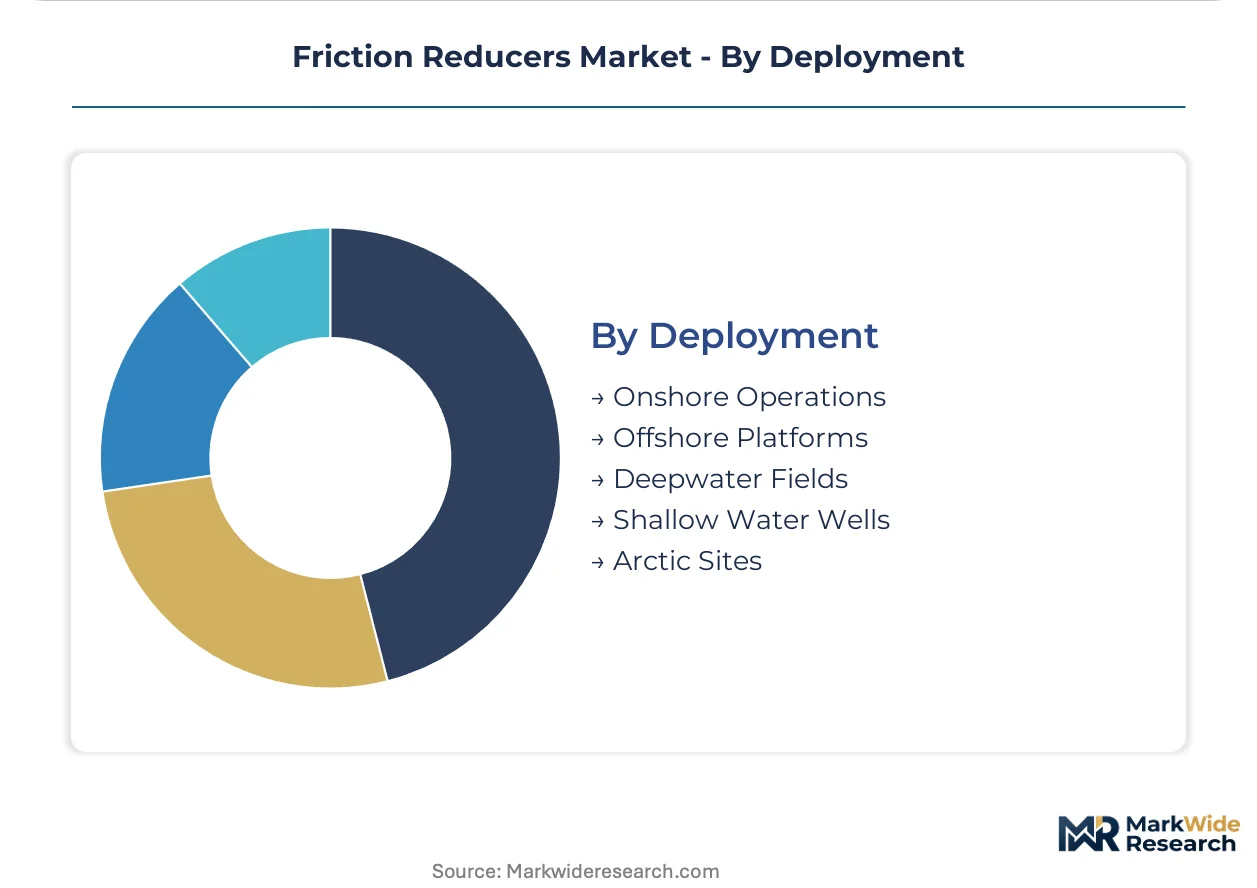
| Segmentation | Product Type: Surfactants, Polymers, Glycols, Electrolytes, Emulsifiers Application: Hydraulic Fracturing, Enhanced Oil Recovery, Drilling Fluids, Completion Fluids, Well Stimulation End User: Exploration Companies, Oilfield Services, Well Operators, Production Companies, Drilling Contractors Deployment: Onshore Operations, Offshore Platforms, Deepwater Fields, Shallow Water Wells, Arctic Sites |
| Companies Covered | Halliburton, Clariant, BASF, Lubrizol, Innospec, Dow, Baker Hughes, Nalco Champion, Schlumberger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Friction Reducers Market Shifts & Advancements
Friction reducer chemistry is pivoting from commodity polyacrylamide supply toward performance-guaranteed systems that integrate with automated wellsite monitoring, compressing traditional product-margin structures while opening service-revenue streams.
Hybrid anionic-cationic polymer architectures are collapsing the performance gap between freshwater and high-salinity formulations, enabling operators to switch to produced water without swapping chemical systems. Bakken and Eagle Ford operators are piloting these chemistries at scale, collapsing the historical two-product inventory requirement into single-tank operations that cut logistics costs and reduce surface footprint.
REACH restrictions on persistent cationic polymers are redirecting European supplier R&D budgets toward biodegradable polyacrylamide backbones with enzymatic cleavage points. ECHA compliance deadlines are compressing formulation timelines, forcing accelerated field trials in North Sea enhanced oil recovery projects where thermal stability requirements conflict with biodegradation targets.
Operators are consolidating chemical procurement under integrated wellsite service contracts that bundle friction reducers with real-time pressure monitoring and automated dosing optimization. This purchasing consolidation is displacing spot-market chemical transactions in the Permian Basin, favoring suppliers with captive polymer manufacturing and field engineering capabilities over standalone chemical distributors.
Friction Reducers Market Segmentation
Friction reducer purchasing cycles vary dramatically by application intensity and reservoir conditions. Operators in high-frequency shale basins rotate through chemistries quarterly, while offshore installations lock in formulations for multi-year campaigns. Understanding these velocity differentials shapes supplier inventory positioning and service contract structures.
Product Type:
Polymer-based friction reducers turn over fastest in high-salinity Permian Basin wells where shear degradation demands frequent reformulation, while electrolyte systems persist longest in stable freshwater environments.
- Polymers:High-molecular-weight polyacrylamides dominate hydraulic fracturing deployment, cutting frictional pressure losses by up to 80 percent in high-rate tubular systems. Demand concentrates in West Texas and southeastern New Mexico where operators push flow rates above 100 barrels per minute through 10,000-foot laterals. EPA chemical disclosure rules are accelerating pre-certified polymer adoption that streamlines operator compliance.
- Surfactants:Modified glycol and anionic surfactant blends deliver compatibility with recycled produced water containing total dissolved solids above 150,000 ppm. Colorado and Texas operators facing freshwater procurement constraints are displacing conventional chemistries with surfactant systems that maintain viscosity in high-brine matrices.
- Glycols:Propylene glycol derivatives serve lower-temperature drilling applications where freeze protection and lubricity combine.
- Electrolytes:Salt-based friction modifiers anchor shallow water well completions with minimal chemical complexity.
- Emulsifiers:Oil-external formulations address specialized reservoir conditions requiring phase-stabilized delivery systems.
Polymers dominate installed base. Surfactants are where expansion concentrates.
Application:
Cost tiering separates commodity hydraulic fracturing volumes from premium enhanced oil recovery pricing, with well stimulation occupying the mid-tier procurement band.
- Hydraulic Fracturing:High-volume slickwater operations consume polymer friction reducers at rates exceeding 2,000 gallons per well, driving the largest absolute chemical demand. Permian Basin concentration is compressing logistics costs through dedicated blending facilities co-located with proppant transload terminals.
- Enhanced Oil Recovery:Thermally stable polymer chemistries for high-temperature reservoirs command pricing multiples above standard fracturing applications. North Sea and Gulf of Mexico operators specify thermal stability above 250°F, requiring specialized acrylamide copolymer architectures that resist hydrolytic degradation.
- Drilling Fluids:Lubricity additives reduce torque and drag in extended-reach horizontal sections.
- Completion Fluels:Breaker-compatible friction reducers enable subsequent flowback without formation damage.
- Well Stimulation:Acid-fracturing applications demand corrosion-resistant polymer packages.
Hydraulic fracturing anchors volume procurement. Enhanced oil recovery captures margin expansion.
End User:
Customer type determines contract structure, with integrated oilfield services firms consolidating procurement under multi-year supply agreements while independent drilling contractors transact spot.
- Oilfield Services:Halliburton and Schlumberger-equivalent integrated providers bundle friction reducers with real-time friction monitoring and automated dosing optimization. These service contracts are displacing transactional chemical sales across major North American shale plays.
- Exploration Companies:Independent producers in the Permian Basin and Bakken formation specify friction reducer performance guarantees tied to pumping pressure reduction targets.
- Well Operators:Mid-sized leaseholders balance cost control against operational risk in chemical selection.
- Production Companies:Mature field operators prioritize compatibility with existing infrastructure over performance optimization.
- Drilling Contractors:Day-rate drilling providers minimize chemical inventory to reduce working capital requirements.
Oilfield services concentrate purchasing power. Exploration companies drive specification innovation.
Deployment:
Geographic deployment governs logistics intensity, with onshore operations permitting rapid chemistry switches while offshore platforms demand extended stability and supply security.
- Onshore Operations:Permian Basin and Eagle Ford shale plays enable just-in-time polymer delivery from regional blending facilities, collapsing inventory carrying costs. Texas and New Mexico regulators impose chemical disclosure thresholds that shape supplier formulation transparency and product registration requirements.
- Deepwater Fields:Gulf of Mexico installations require friction reducers with 18-month shelf stability and compatibility with subsea boosting systems. Thermally stable chemistries for high-pressure high-temperature wells command premium positioning.
- Offshore Platforms:Fixed installations in the North Sea face REACH compliance deadlines that redirect supplier R&D toward biodegradable alternatives.
- Shallow Water Wells:Gulf of Mexico shelf operations balance cost efficiency against environmental discharge regulations.
- Arctic Sites:Alaska North Slope and Canadian Beaufort Sea developments specify low-temperature rheology maintenance.
Onshore operations dominate active deployment. Deepwater fields concentrate technology premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty acrylamide manufacturing concentrates in European chemical hubs, creating import dependency for North American friction reducer blenders while Permian Basin operators drive the largest absolute demand growth.
United States
Permian Basin operators in West Texas and southeastern New Mexico consume polymer friction reducers at rates exceeding 2,000 gallons per well, pushing flow rates above 100 barrels per minute through extended laterals. EPA chemical disclosure rules under the Toxic Substances Control Act require pre-manufacture notification for novel polyacrylamide chemistries, accelerating pre-certified polymer adoption. Midland-Odessa chemical blending facilities co-locate with proppant transload terminals to collapse logistics costs.
Germany
Specialty polymer manufacturing scale anchors European supply security for high-molecular-weight polyacrylamide feedstock. REACH compliance deadlines from ECHA restrict certain cationic polymer chemistries, redirecting R&D investment toward biodegradable alternatives with enzymatic cleavage points. Ludwigshafen chemical complexes supply acrylamide monomer to friction reducer blenders across the continent.
Saudi Arabia
High-temperature reservoir conditions in Ghawar and Safaniya fields command thermally stable polymer chemistries that resist hydrolytic degradation above 250°F. The country's national oil company imposes stringent chemical disclosure thresholds that shape supplier formulation transparency. Eastern Province industrial cities host blending operations serving offshore and onshore enhanced oil recovery campaigns.
Canada
Alberta oil sands and tight oil formations in Saskatchewan specify friction reducers compatible with high-salinity produced water containing total dissolved solids above 150,000 ppm. Health Canada and PMRA regulate chemical constituents under environmental discharge frameworks. Calgary-headquartered oilfield services firms consolidate procurement under multi-year supply agreements with integrated chemistry providers.
China
Sichuan-Chongqing shale basins and Tarim Basin tight gas developments represent the largest untapped friction reducer demand outside North America. NMPA and MEE impose dual carbon goals that pressure suppliers toward lower-emission manufacturing processes. Yangtze River Delta chemical clusters produce acrylamide monomer for domestic friction reducer formulation.
Friction Reducers Market Competitive Landscape
Integrated service providers and specialty chemical manufacturers split the market between bundled wellsite contracts and standalone polymer supply. The vendor base organizes around three strategic archetypes: oilfield services firms with captive chemistry capabilities, European specialty chemical houses with acrylamide manufacturing scale, and diversified chemical conglomerates competing on feedstock cost curves. Competitive dynamics center on backward integration into polymer manufacturing and geographic expansion through regional blending facilities.
Within the integrated services tier, Halliburton and Schlumberger exemplify providers bundling friction reducer supply with real-time monitoring and automated dosing optimization. Among specialty chemical houses, Clariant anchors European supply security through manufacturing scale in continental hubs. Dow occupies a position on the cost-curve end, leveraging acrylamide-based chemistry scale for mid-tier product lines. Baker Hughes and Nalco Champion sit within the oilfield services archetype, capturing recurring demand across North American shale plays through integrated wellsite chemistry services rather than transactional chemical sales.
| Leading Market Players |
|---|
| Halliburton |
| Clariant |
| BASF |
| Lubrizol |
| Innospec |
| Dow |
| Baker Hughes |
| Nalco Champion |
| Schlumberger |
| Others |
Supply & Pricing Matrix
Acrylamide monomer volatility from European chemical hubs compresses margin spreads across polymer tiers while forcing North American blenders into long-term offtake commitments that reshape inventory carrying costs and procurement flexibility.
Pricing Analysis
EPA chemical disclosure rules dictate the pricing tier structure across the friction reducer market. Three-tier pricing separates pre-certified compliance-grade polymers from standard formulations and economy surfactant blends. Price differentiation rests on certification grade and volume scale, with integrated service bundles commanding premiums over transactional chemical sales. Pricing pressure stems from REACH-driven R&D redirection costs in Europe. Exploration companies exhibit highest price sensitivity, while enhanced oil recovery operators demonstrate lowest sensitivity due to thermal stability requirements.
Supply Chain Analysis
Acrylamide monomer production concentrates in Germany, China, and the United States as primary feedstock sources. Specialty polymer manufacturing draws from high-purity acrylamide, modified glycol derivatives, and enzymatic additive packages. Single-source vulnerability pervades the European supply hub concentration for high-molecular-weight polyacrylamides. Distribution runs through regional blending facilities co-located with proppant transload terminals in West Texas and southeastern New Mexico.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized rheology expertise for high-salinity polymer compatibility remains scarce among regional blenders, concentrating value capture with suppliers possessing captive manufacturing and field engineering capabilities.
For Market Incumbents: Build formulation transparency moats by pre-certifying polymer architectures under EPA and state disclosure frameworks before competitors complete registration. Expand captive acrylamide manufacturing scale in North American chemical clusters to reduce European import dependency. Consolidate regional blending facility networks to collapse logistics costs for Permian Basin operators. For New Entrants and Emerging Players: Establish a beachhead in biodegradable polymer segments where REACH compliance deadlines have forced incumbent R&D redirection and field performance data remains sparse. Target surfactant-based friction reducers compatible with produced water reuse mandates in Colorado and Texas. Pursue joint development agreements with oilfield services firms lacking in-house polymer chemistry capabilities. For Investors and Strategic Acquirers: REACH biodegradation deadlines reshape the acquisition landscape toward suppliers with enzymatically degradable polyacrylamide platforms and accelerated North Sea field trial data. Long-term viability centers on integrated service contracts displacing transactional chemical sales. Monitor state-level fracturing fluid disclosure mandate harmonization as the signal indicating regulatory consolidation or continued fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylamide Manufacturing | Captive monomer supply reduces European import exposure and stabilizes feedstock costs for polymer blenders. |
| Pre-Certified Polymer Registration | EPA-compliant formulations streamline operator disclosure obligations and accelerate procurement cycles in Texas and Colorado. |
| Biodegradable Polymer Development | Enzymatically degradable backbones address REACH restrictions while opening premium positioning in North Sea enhanced oil recovery. |
| Integrated Wellsite Service Contracts | Bundled friction reducer supply with real-time monitoring displaces spot-market transactions across major shale plays. |
| Regional Blending Facility Expansion | Co-location with proppant transload terminals collapses logistics costs and enables just-in-time delivery for Permian operators. |
Research Methodology
Operator-level perspectives from wellsite chemistry engineers, procurement leads at exploration companies, blending facility managers, and regulatory compliance officers anchored the qualitative base. Primary interviews combined with secondary validation from EPA chemical disclosure filings, state regulatory databases, American Chemistry Council sector reports, and SEC 10-K disclosures from integrated oilfield services firms. Bottom-up well count and completion activity models triangulated against top-down chemical consumption estimates.
Scenario bracketing across base, upside, and downside cases structured the analytical framework over the projection horizon. Segmentation dimensions modeled include product chemistry type, application intensity, deployment environment, and end-user procurement structure. CAGRs derived from historical consumption patterns, well completion trajectories, and polymer substitution elasticity. Industry-specific inputs encompassed produced water reuse regulatory timelines and thermal stability specification evolution in high-temperature reservoirs.
Stress conditions across acrylamide monomer price bands, state disclosure mandate fragmentation, and produced water salinity tolerance thresholds were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and operator capital allocation priorities. Material shifts in EPA chemical disclosure thresholds or REACH biodegradation compliance deadlines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Egypt Lubricants Market
Lubricants
Polyurea Greases Market
Lubricants
Global Grease Cartridges Market
Lubricants
Brazil Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Wire Rope Lubricants Market
Lubricants
Germany Automotive Lubricants Market
Lubricants
Germany Automotive Engine Oils Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Malaysia Lubricants Market
Lubricants
Marine Lubricants Market
Lubricants
Graphite Lubricant Market
Lubricants
Norway Lubricants Market
Lubricants
North America Lubricants Market
Lubricants
Qatar Automotive Lubricants Market