
 Europe Fine Chemical Market | 2026-2036
Europe Fine Chemical Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fine Chemical Market Foresight
Petrochemical-derived intermediates is shifting toward renewable feedstocks as European refiners reduce naphtha output and bio-based platform chemicals achieve cost parity at scale. BASF SE leverages its Ludwigshafen Verbund site to sustain integrated production of pharmaceutical precursors with lower carbon intensity. Evonik Industries AG anchors its competitive position through specialized amino acid and lipid chemistry for biologics manufacturing. Lonza Group dominates contract development and manufacturing for complex small-molecule APIs from its Swiss and Scottish facilities.
Fine chemicals encompass high-purity, low-volume substances typically manufactured in batch reactors with stringent purity thresholds exceeding 99.5 percent, serving as critical inputs for pharmaceuticals, agrochemicals, and performance materials where impurity profiles directly determine regulatory approval and end-product safety. Specialty chemicals command the deepest margin pools due to customer-specific formulation requirements and lengthy qualification cycles, while biochemicals represent the fastest-expanding category as enzymatic catalysis and fermentation-derived chiral intermediates displace traditional synthetic routes. Organic chemicals retain the largest volume share across the European fine chemical landscape, though inorganic rare-earth complexes for electronics and catalyst applications are gaining traction in German and French supply chains.
REACH registration requirements enforced by ECHA mandate comprehensive toxicity dossiers that raise barriers for non-European suppliers and redirect procurement toward established European registrants. The EU Green Deal's chemical sector decarbonization targets, combined with F-Gas Regulation restrictions on fluorinated solvents, are reshaping process chemistry choices and capital allocation across the industry. CSRD disclosure obligations will force fine chemical producers to quantify Scope 3 emissions from complex multi-tier supply networks. Stakeholders must monitor how the EU AI Act's deployment rules affect automated process control systems in GMP-regulated manufacturing environments.
Market Dynamics
REACH registration dossiers and EU Green Deal decarbonization mandates are compressing the supplier base while redirecting capital toward enzymatic process platforms and renewable feedstock integration. The Rhine-Ruhr cluster's naphtha supply contraction is forcing pharmaceutical precursor manufacturers to requalify supply chains around bio-based platform chemicals.
Growth Catalysts
- Active pharmaceutical ingredient demand:Biologics manufacturing expansion across Germany and Switzerland is pulling specialized amino acid and lipid chemistry volumes. Contract development organizations are scaling multi-ton production of complex small-molecule precursors.
- EU Green Deal chemical sector targets:Mandatory carbon intensity reductions are accelerating fermentation-derived chiral intermediate adoption. Bio-based solvents are achieving cost parity with petrochemical equivalents at commercial scale.
- Enzymatic catalysis platforms:Biocatalyst immobilization technologies are displacing traditional synthetic routes for high-purity pharmaceutical intermediates. Batch reactor retrofits are reducing solvent waste and energy consumption.
Market Restraints
- Naphtha feedstock volatility:European refinery output reductions are tightening aromatics and olefins availability. Price swings in benzene and toluene are compressing margin predictability for specialty intermediate producers.
- ECHA registration barriers:Comprehensive toxicity dossier requirements are excluding non-European suppliers from qualified vendor lists. Procurement teams are consolidating spend among established REACH registrants.
- Fluorinated solvent restrictions:F-Gas Regulation phase-down schedules are forcing process chemistry redesigns. Alternative solvent qualification cycles are extending new product introduction timelines.
Strategic Opportunities
- CSRD Scope 3 disclosure mandates:First-mover advantage exists for producers with quantified multi-tier supply network emissions data. Carbon accounting software integration is becoming a procurement differentiator.
- Cell and gene therapy raw materials:Viral vector manufacturing is creating demand for GMP-grade nucleotides and specialized lipids. Swiss and Scottish production hubs are expanding capacity for these high-margin categories.
- Rare-earth complex chemistry:Electronics and catalyst applications are pulling inorganic fine chemical volumes through German and French supply chains. Europium and terbium coordination compounds represent underpenetrated product lines.
Industry Challenges
- EU AI Act compliance for GMP automation:Automated process control systems in pharmaceutical manufacturing face new validation requirements. Retrofitting legacy distributed control systems is consuming engineering resources.
- Multi-step synthesis skill scarcity:Batch reactor optimization and chiral resolution expertise are retiring faster than training programs replace them. Contract manufacturers are competing for experienced process chemists.
- Cross-border qualification synchronization:Divergent national interpretations of EMA guidelines are duplicating analytical method validation work. Harmonized ICH implementation remains incomplete across member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fine Chemical Market |
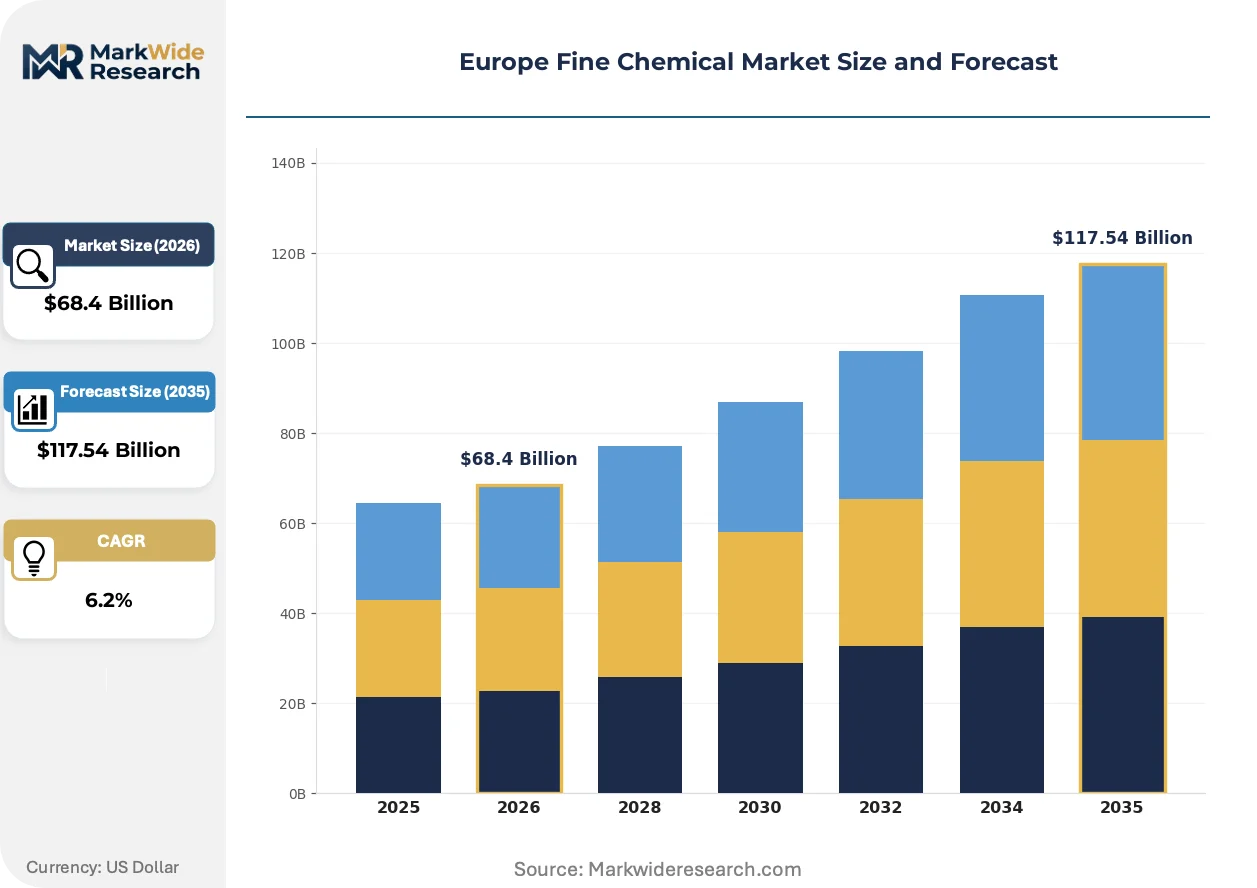
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $117.54 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Chemicals, Inorganic Chemicals, Specialty Chemicals, Biochemicals Application: Pharmaceuticals, Agrochemicals, Personal Care, Food Additives End User: Manufacturing, Healthcare, Agriculture, Cosmetics Distribution Channel: Direct Sales, Retail, Online Platforms, Distributors |
| Companies Covered | BASF SE, Evonik Industries AG, Lonza Group, Clariant AG, Lanxess AG, Nouryon, Arkema, AkzoNobel N.V., WeylChem International GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fine Chemical Market Shifts & Advancements
Continuous flow chemistry and modular manufacturing platforms are redrawing asset economics for high-purity intermediate production. Process intensification is collapsing batch cycle times while tightening impurity profiles.
Modular skid-mounted flow reactors are decentralizing pharmaceutical intermediate manufacturing from centralized Verbund sites to regional multi-product facilities. Mid-size contract manufacturers in the Netherlands and Belgium are adopting these units for rapid product changeover. Distributed production is reducing transport emissions and enabling just-in-time delivery to formulation sites.
CSRD disclosure obligations are forcing fine chemical producers to deploy blockchain-traceable carbon accounting across multi-tier supply networks. Scope 3 quantification requirements are reshaping procurement criteria and supplier scorecards. German and French producers with verified low-carbon process data are capturing preferential supply positions with pharmaceutical formulators.
Biopharma procurement teams are consolidating vendor panels around full-service platform chemistry providers. Single-source relationships for integrated precursor-to-API supply are displacing fragmented multi-supplier arrangements. Swiss and German CDMOs with captive amino acid, lipid, and nucleotide capabilities are winning preferred partnership status.
Europe Fine Chemical Market Segmentation
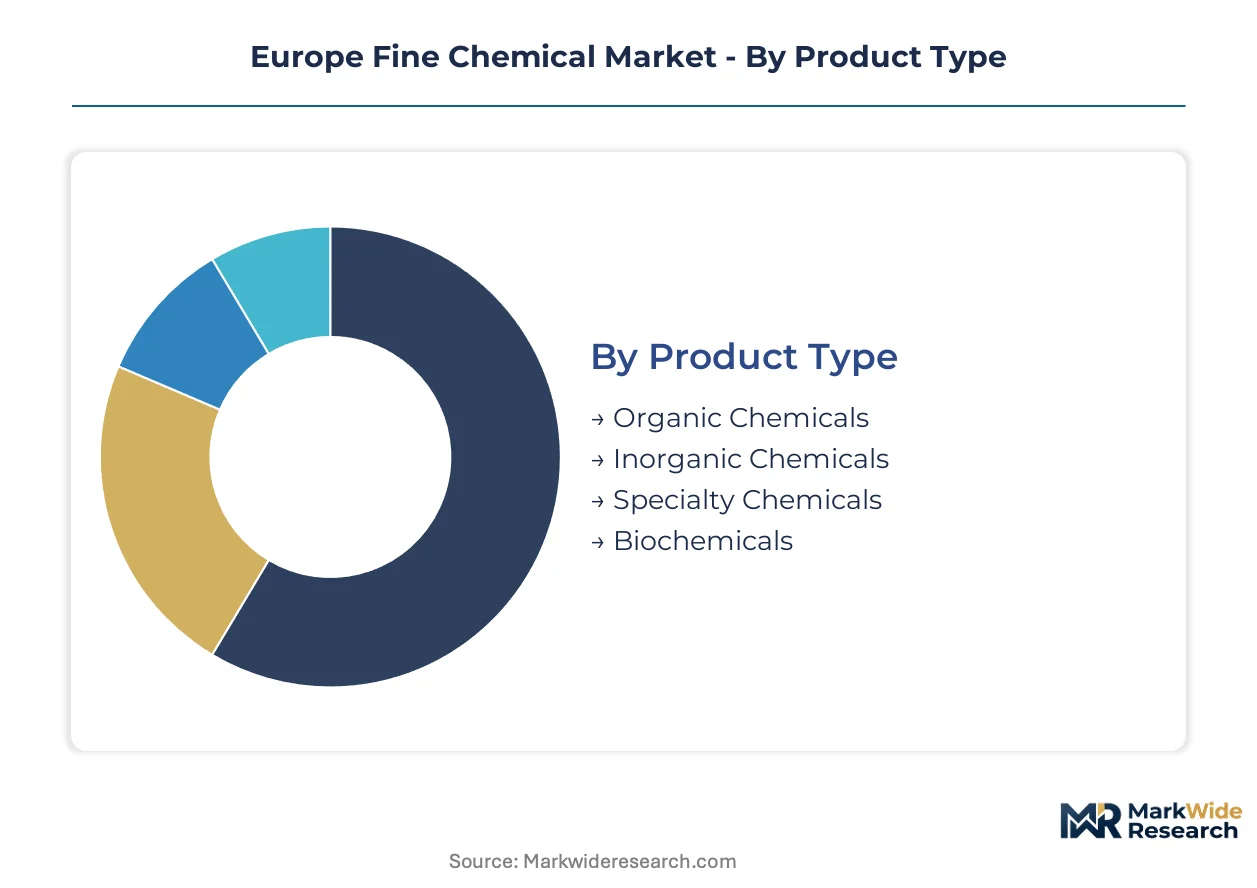
Fine chemical segmentation in Europe reflects divergent purity requirements, regulatory pathways, and capital intensity across product categories. Pharmaceutical-grade specifications impose stricter qualification cycles than industrial applications, reshaping supplier economics and customer loyalty patterns.
Product Type:
Customization intensity spans from commodity-scale organic intermediates to fully bespoke biochemical syntheses engineered for single-customer specifications.
- Organic Chemicals:Aromatic and aliphatic intermediates manufactured through multi-step synthesis with purity thresholds typically exceeding 99.5 percent. Demand concentrates in German and Swiss pharmaceutical precursor supply chains, where REACH-registered naphtha derivatives face tightening availability from refinery output reductions.
- Biochemicals:Enzymatic catalysis and fermentation-derived chiral intermediates displacing traditional synthetic routes for high-purity pharmaceutical applications. Swiss CDMOs and Rhine-Ruhr biotech facilities are scaling capacity as EU Green Deal carbon intensity mandates accelerate bio-based platform adoption.
- Specialty Chemicals:Customer-specific formulations with lengthy qualification cycles and deep margin pools.
- Inorganic Chemicals:Rare-earth coordination compounds for electronics and catalyst applications, gaining traction through German and French supply chains.
Leading the category by volume: Organic Chemicals. Expanding most quickly: Biochemicals.
Application:
End-use concentration varies by regulatory burden, with pharmaceutical applications commanding premium pricing against commoditized agrochemical volumes.
- Pharmaceuticals:Active pharmaceutical ingredients and advanced intermediates for small-molecule and biologics manufacturing. Germany and Switzerland anchor demand, where Lonza, Evonik, and BASF sustain integrated precursor-to-API production with lower carbon intensity profiles.
- Agrochemicals:Herbicide and fungicide intermediates with volume-scale production economics. Demand concentrates in French and German crop protection formulation sites, though margin compression from generic active ingredient competition limits supplier pricing power.
- Personal Care:High-purity emollients, surfactants, and active ingredients for cosmetic formulations.
- Food Additives:Preservatives, antioxidants, and flavor precursors meeting EFSA purity specifications.
Deepest margin pool: Pharmaceuticals. Steepest volume growth: Food Additives.
End User:
Procurement sophistication tiers separate GMP-regulated healthcare manufacturing from cost-driven agricultural and cosmetics purchasing.
- Healthcare:Hospitals, clinics, and diagnostic laboratories consuming reagent-grade chemicals with stringent lot-to-lot consistency requirements. Swiss and German healthcare systems consolidate purchasing through group procurement organizations, favoring established REACH registrants with verified supply security.
- Manufacturing:Industrial formulators across electronics, coatings, and performance materials. Demand clusters in Benelux and northern Italy, where just-in-time delivery requirements favor regional multi-product facilities over centralized Verbund sites.
- Agriculture:Crop protection and fertilizer additive manufacturers.
- Cosmetics:Beauty and personal care product formulators.
Highest qualification barriers: Healthcare. Fastest procurement consolidation: Manufacturing.
Distribution Channel:
Channel selection tracks order scale, technical service requirements, and geographic proximity to formulation sites.
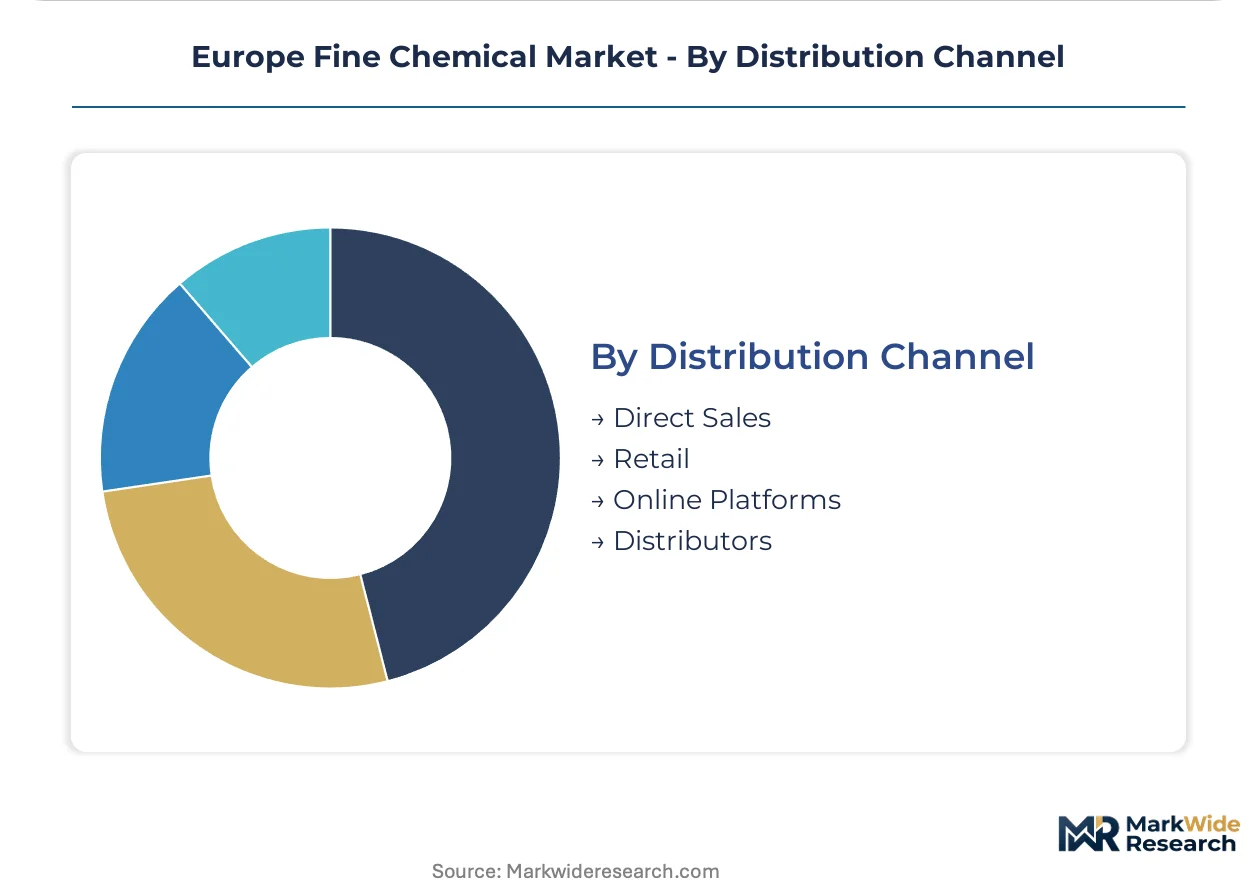
- Direct Sales:Long-term supply agreements for multi-ton pharmaceutical and agrochemical volumes. BASF and Evonik leverage dedicated account teams for German and Swiss pharmaceutical formulators, embedding technical service into contractual relationships.
- Distributors:Stocking intermediaries serving mid-size manufacturers with fragmented product needs. Benelux and Italian distributors are consolidating as ECHA registration costs exclude smaller non-European suppliers from qualified vendor lists.
- Online Platforms:Digital procurement for catalog chemicals and standard reagents.
- Retail:Small-volume sales to research institutions and pilot-scale operations.
Dominant by revenue: Direct Sales. Fastest digital adoption: Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical precursor demand concentrates in German and Swiss manufacturing corridors, while bio-based platform chemistry investments are redrawing production maps across the continent.
Germany
Active pharmaceutical ingredient manufacturing anchors demand in the Rhine-Ruhr and Ludwigshafen chemical clusters. REACH registration requirements enforced by ECHA consolidate procurement among established domestic registrants. BASF SE operates its Verbund site in Ludwigshafen to sustain integrated precursor production with lower carbon intensity profiles.
Switzerland
Biologics manufacturing expansion pulls specialized amino acid and lipid chemistry volumes through Swissmedic-regulated facilities. The country's national pharmaceutical regulator maintains stringent GMP standards that extend qualification cycles for imported intermediates. Lonza Group dominates contract development from its Basel-area and Scottish facilities for complex small-molecule APIs.
France
Crop protection formulation sites in Lyon and Paris basins consume herbicide and fungicide intermediates despite margin compression from generic competition. The EU Green Deal's chemical sector decarbonization targets are accelerating fermentation-derived chiral intermediate adoption in Rhône-Alpes biotech facilities. Arkema and Clariant AG anchor specialty chemical production in the region.
Netherlands
Modular flow reactor adoption is decentralizing pharmaceutical intermediate manufacturing to regional multi-product facilities in Rotterdam and Eindhoven. F-Gas Regulation phase-down schedules are forcing process chemistry redesigns for fluorinated solvent users. Benelux distributors are consolidating as ECHA registration costs exclude smaller non-European suppliers.
United Kingdom
Scottish production hubs are expanding capacity for GMP-grade nucleotides and specialized lipids serving cell and gene therapy raw material demand. MHRA alignment with EMA guidelines remains incomplete despite post-Brexit regulatory divergence concerns. Northern England contract manufacturers are retrofitting batch reactors for enzymatic catalysis platforms.
Europe Fine Chemical Market Competitive Landscape
Capacity expansion dominates the current landscape as established players retrofit batch reactors for enzymatic platforms and renewable feedstock integration. The supplier base compresses around REACH-registered incumbents with verified supply security and carbon accounting capabilities. Three archetypes define competitive positioning: integrated Verbund operators with captive precursor-to-API supply, specialized CDMOs with biologics chemistry expertise, and regional multi-product facilities adopting modular flow technologies. M&A activity and strategic partnerships for bio-based platform access are the primary competitive moves reshaping market share.
Among German-headquartered integrated operators, BASF SE and Evonik Industries AG exemplify the Verbund archetype with Ludwigshafen and Marl site advantages. Lonza Group anchors the specialized CDMO tier from its Swiss and Scottish manufacturing footprint. These three occupy positions that concentrate procurement decisions for pharmaceutical formulators seeking full-service platform chemistry providers with quantified Scope 3 emissions data.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| Lonza Group |
| Clariant AG |
| Lanxess AG |
| Nouryon |
| Arkema |
| AkzoNobel N.V. |
| WeylChem International GmbH |
| Others |
Supply & Pricing Matrix
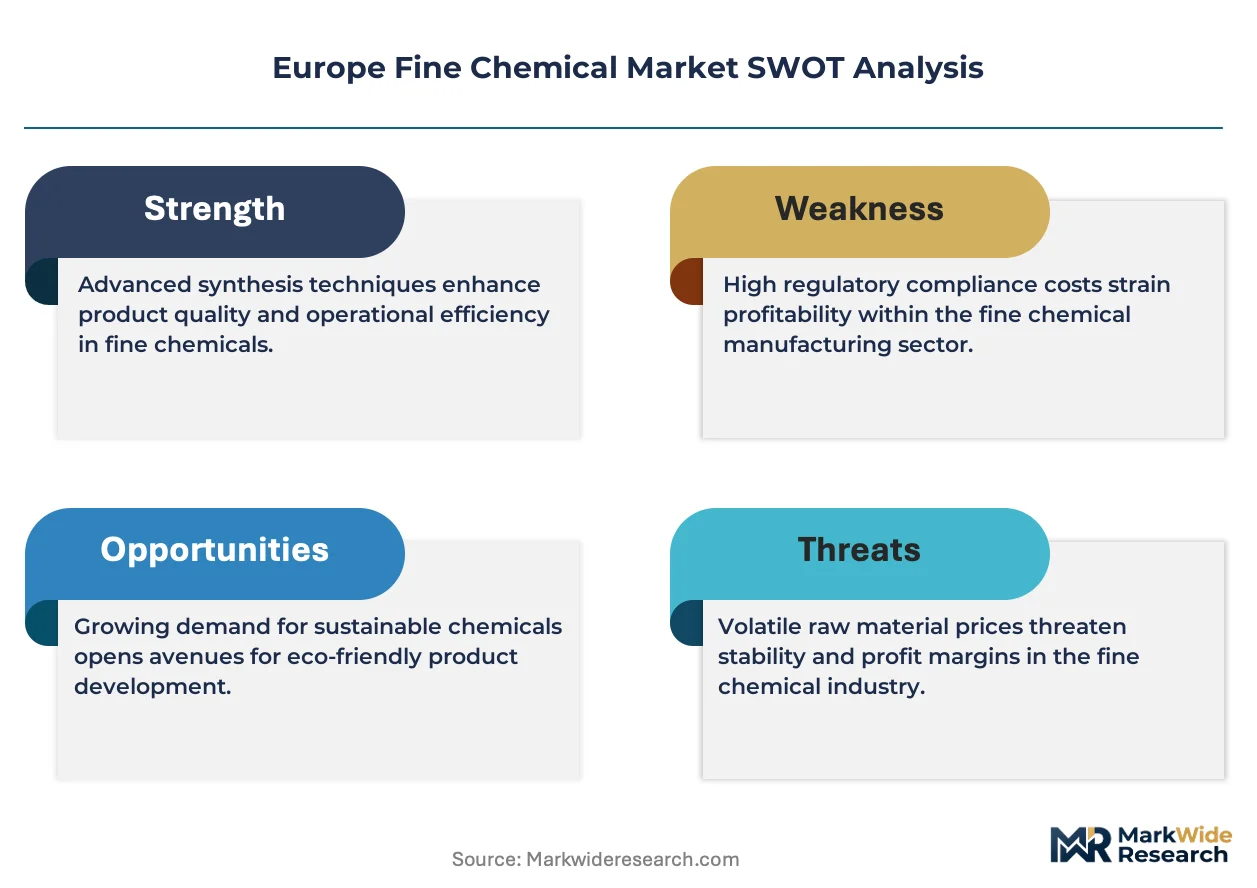
Batch reactor optimization expertise concentrated in the Rhine-Ruhr and Basel corridors commands wage premiums that widen spreads between GMP-certified premium tiers and standard-grade commodity supply. REACH registration costs and enzymatic platform investments are compressing mid-tier pricing power as qualified suppliers consolidate procurement relationships.
Pricing Analysis
Volume-scale organic intermediates trade on thin margins while specialty biochemicals and GMP-grade APIs capture deep value pools through lengthy qualification cycles. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered pharmaceutical precursors from industrial-grade agrochemical feedstocks and spot-market commodity chemicals. Cost compression in standard-grade aromatics is intensifying because European refinery naphtha output reductions are tightening benzene and toluene availability. Agrochemical formulators in France and Germany show highest price sensitivity, while Swiss biologics manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
Reverse-logistics flows for solvent recovery and catalyst regeneration are tightening loop between modular regional facilities and centralized Verbund sites, reducing virgin material intensity. Supply concentrates in Germany, Switzerland, and the Netherlands, with feedstock dependencies on bio-based platform chemicals, rare-earth coordination compounds, and fermentation-derived chiral intermediates. Single-source vulnerability around enzymatic biocatalyst suppliers is elevating dual-sourcing mandates for pharmaceutical CDMOs. Distribution runs through direct sales agreements for multi-ton pharmaceutical volumes and consolidated Benelux distributors for mid-size manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around REACH-registered incumbents with verified carbon accounting capabilities, as ECHA dossier requirements exclude non-European competitors from qualified vendor lists.
For Market Incumbents: Hedge against naphtha feedstock volatility by accelerating bio-based platform chemical integration at Ludwigshafen and Marl sites. Secure preferred partnership status with Swiss biologics manufacturers through captive amino acid and lipid chemistry capabilities. Counter modular flow reactor entrants by embedding technical service into long-term supply agreements with German pharmaceutical formulators. For New Entrants and Emerging Players: Online platform procurement for catalog biochemicals and standard reagents offers lower qualification barriers than direct sales channels. Target cell and gene therapy raw materials in Scottish production hubs, where GMP-grade nucleotide demand outpaces established capacity. Penetrate through carbon accounting software integration that meets CSRD Scope 3 disclosure mandates for pharmaceutical procurement teams. For Investors and Strategic Acquirers: Re-rating potential sits with specialized CDMOs possessing integrated amino acid, lipid, and nucleotide capabilities given biopharma vendor panel consolidation trends. Long-term viability favors Swiss and German operators with verified low-carbon process data and Swissmedic or EMA regulatory track records. Monitor enzymatic catalysis platform adoption rates as inflection indicator for bio-based displacement of petrochemical routes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | Secures renewable platform chemical supply as European naphtha output contracts tighten aromatics availability. |
| Enzymatic Platform Capacity Expansion | Captures EU Green Deal carbon intensity mandates by displacing traditional synthetic routes with biocatalysis. |
| Long-term Supply Agreement with CDMOs | Locks in multi-ton pharmaceutical precursor volumes as biopharma procurement consolidates vendor panels. |
| Joint Venture for Rare-earth Complex Chemistry | Accesses underpenetrated europium and terbium coordination compound demand in German electronics supply chains. |
| Green Manufacturing Transition Certification | Captures preferential procurement positioning as CSRD disclosure obligations reshape supplier scorecards. |
Research Methodology
Multi-period observation of ECHA registration trends, refinery output data, and enzymatic platform adoption anchored the trend analysis, supplemented by interviews with plant managers at Rhine-Ruhr chemical clusters, procurement leads at Swiss biologics manufacturers, distribution channel partners in Benelux, and technical R&D directors specializing in chiral resolution. Secondary validation drew from Cefic industry reports, customs and trade data for pharmaceutical precursor flows, SEC filings of listed chemical producers, and EU Green Deal implementation tracking. Bottom-up capacity assessments and top-down demand modeling were triangulated against regulatory milestone timelines.
Input-output matrices mapped feedstock availability constraints through process chemistry choices to end-use demand across pharmaceutical, agrochemical, and electronics applications. Segmentation dimensions included product grade tier, end-use industry, regional production hub, and regulatory qualification pathway. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion announcements. Forecast inputs incorporated REACH registration velocity, F-Gas Regulation phase-down schedules, and biologics manufacturing capacity buildouts in Germany and Switzerland.
The model holds under sustained EMA guideline harmonization and stable EU Green Deal enforcement; deviation in national regulatory interpretation or feedstock supply disruption would shift capacity utilization assumptions. Practitioners should monitor enzymatic biocatalyst supplier consolidation and carbon accounting verification standards for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Hydroxocobalamin Chloride Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market
High-Value Chemicals
High-Purity Acetic Acid Market
High-Value Chemicals
Global 1-Hexanol Market