
 High Friction Films Market | 2026-2036
High Friction Films Market Size, Share, and Industry Trends Forecast 2026-2036
High Friction Films Market Foresight
Specialized polymer chemists and coating engineers is rotating toward high-performance friction film development as compound formulation complexity outpaces general materials science training. DuPont leverages its fluoropolymer heritage to anchor premium aerospace contracts. SKC Inc. competes through backward integration into PET substrate production, sustaining cost discipline across Asian industrial channels.
High friction films are engineered multilayer structures, typically 25–250 microns thick, combining oriented polymer substrates with ceramic or rubber-modified surface coatings to achieve controlled coefficients of friction between 0.5 and 1.2. These films prevent slippage, damp vibration, and protect mating surfaces in mechanical assemblies subjected to cyclic loading. Polymer-based films dominate current volume due to thermoplastic processability and recyclability compliance, while composite films command margin premiums in aerospace torque-limiting applications where temperature excursions exceed 150°C. Coated films represent the fastest-expanding technology segment as slot-die and gravure coating methods enable sub-micron thickness precision for automotive clutch plate interfaces.
FDA regulations govern indirect food-contact friction films used in packaging machinery, while OSHA machinery guarding standards drive specification of high-friction surfacing on industrial equipment walk surfaces and hand controls. The EU Green Deal and associated F-Gas Regulation are restricting perfluorinated chemistry in European-manufactured films, redirecting formulation R&D toward silicone and acrylic alternatives. Stakeholders must monitor evolving chemical substance restrictions across multiple jurisdictions while building qualified supplier networks that can certify halogen-free and bio-based content claims.
Market Dynamics
REACH and F-Gas Regulation compliance pressures are forcing converters to abandon perfluorinated chemistries and rebuild formulation pipelines around silicone and acrylic alternatives, compressing development timelines and raising qualification costs.
Growth Catalysts
- Automotive torque transmission:Tier-one suppliers in Germany operate dedicated lamination facilities for brake and clutch interfaces, pulling volume through qualified supply chains.
- Aerospace OEM procurement:Landing gear and flight control system manufacturers specify polymer-based friction surfaces for weight reduction and corrosion resistance.
- Coated film precision:Slot-die and gravure coating methods enable sub-micron thickness control for clutch plate applications, expanding addressable automotive assemblies.
Market Restraints
- Halogen-free reformulation costs:RoHS and REACH compliance requires complete resin system changes, raising raw material expenses and requalification burdens.
- Substrate supply concentration:PET film supply chains cluster in East Asian manufacturing corridors, exposing converters to logistics volatility and tariff exposure.
- Temperature ceiling limitations:Standard polymer films degrade above 150°C, excluding them from high-performance aerospace torque-limiting segments where ceramic composites dominate.
Strategic Opportunities
- India industrial automation:Packaging machinery OEMs under BIS standards seek FDA-compliant friction films for food-contact conveying systems.
- EU Green Deal tailwinds:Bio-based content mandates and carbon border adjustments reward early movers with certified halogen-free formulations.
- Medical device convergence:Surgical robotics and diagnostic equipment manufacturers combine vibration damping with sterilization compatibility, opening premium niches.
Industry Challenges
- Compound formulation expertise scarcity:General materials science training lags behind multilayer polymer-ceramic interface engineering requirements.
- Multi-jurisdiction certification timelines:Simultaneous FDA, REACH, and BIS qualification processes extend product launch windows and strain R&D budgets.
- Legacy equipment integration:Gravure and slot-die coating lines require retrofitting for sub-micron precision, demanding capital deployment without guaranteed volume commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Friction Films Market |
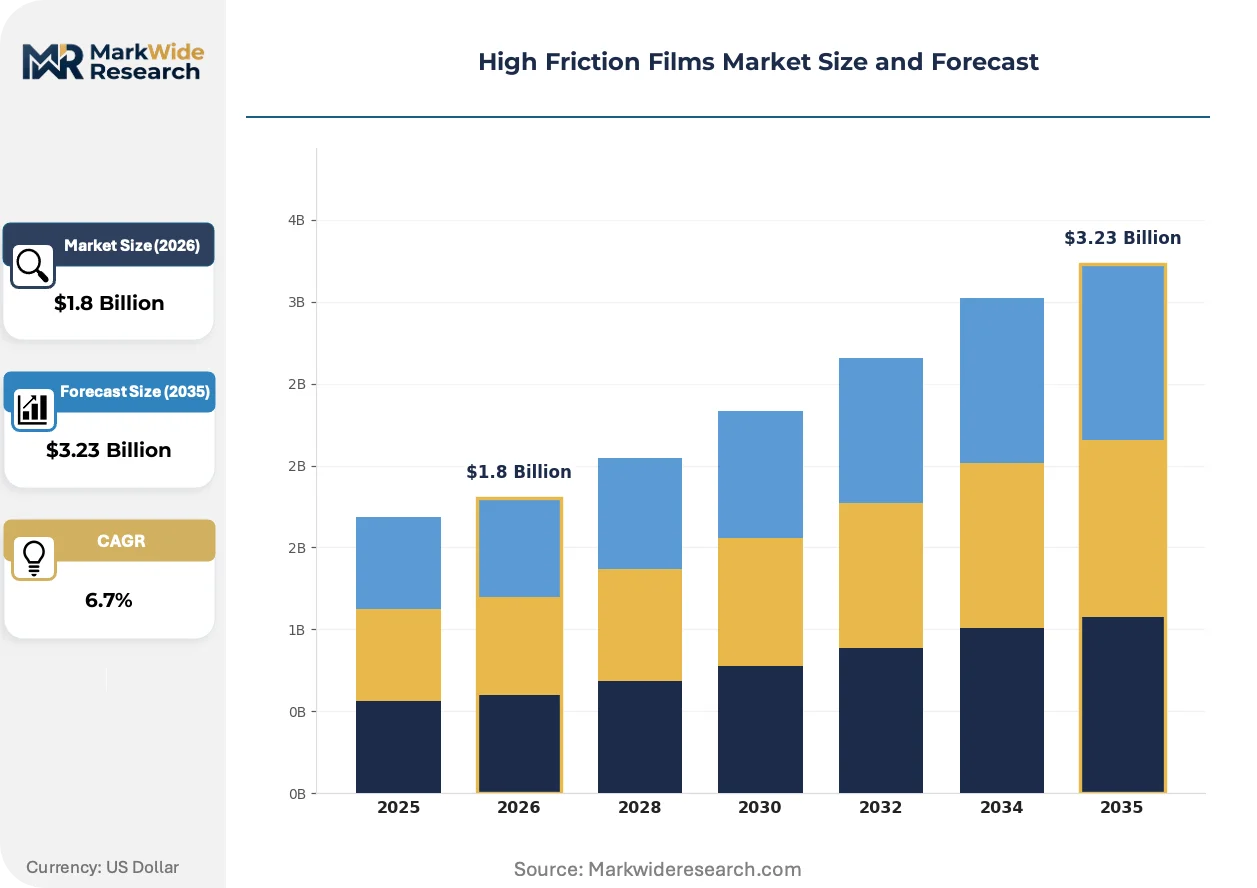
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer-based Films, Rubber Films, Composite Films, Coated Films Application: Aerospace, Automotive, Sports Equipment, Industrial Machinery End User: Manufacturers, Designers, Engineers, Contractors Technology: Extrusion, Lamination, Coating, Injection Molding |
| Companies Covered | Ester Industries Ltd., Toray Plastics (America) Inc., FlexFilms Ltd., Jindal Poly Films Ltd., TEKRA, A Division of EIS, Inc., SKC Inc., Cosmo Films Ltd., DuPont, Mitsubishi Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Friction Films Market Shifts & Advancements
Formulation chemistry, coating precision, and procurement models are simultaneously transforming how friction films are engineered, qualified, and commercialized across industrial verticals.
Multilayer coextrusion with ceramic-modified surface layers is miniaturizing functional thickness from 100 microns toward 25 microns while maintaining coefficient targets. Automotive transmission suppliers in Germany and Japan are qualifying these reduced-gauge films for compact dual-clutch assemblies. The technology is miniaturizing material consumption per unit and compressing cost structures in high-volume brake and clutch applications.
F-Gas Regulation restrictions on perfluorinated substances are redirecting European formulation R&D toward silicone and acrylic polymer systems. Industrial film converters face complete resin platform changes and accelerated requalification cycles. Aerospace OEMs sourcing from EU-based suppliers are most affected, driving joint development agreements with specialty chemical partners.
Automotive tier-one suppliers are consolidating vendor bases and demanding certified halogen-free supply chains with full material disclosure. Long-term supply agreements with embedded compliance documentation are displacing spot purchasing through distributors. This concentration is most visible in Germany, where dedicated film lamination facilities now require backward integration into substrate production or captive coating capacity.
High Friction Films Market Segmentation
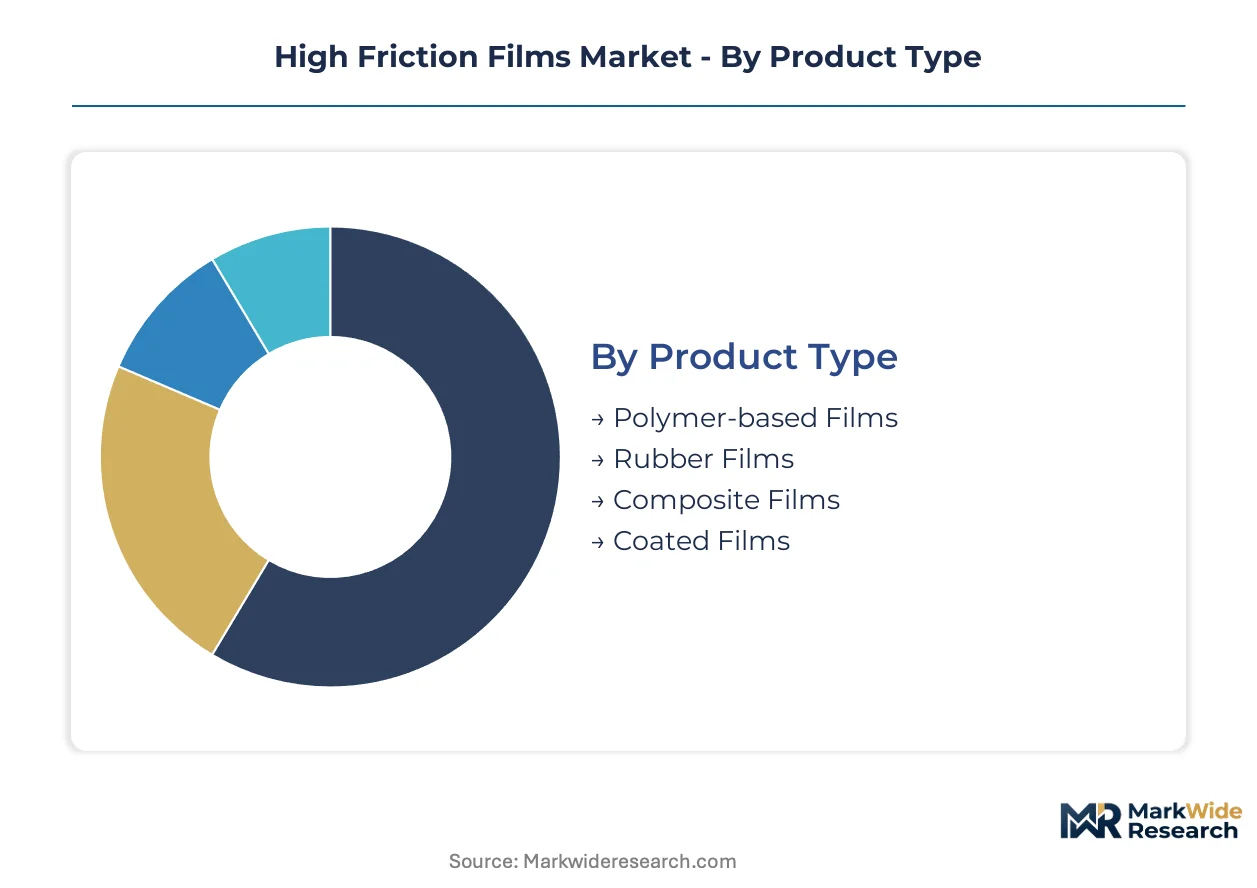
High friction films serve divergent performance requirements across aerospace torque systems, automotive clutch interfaces, and industrial vibration damping. Segmentation reveals how formulation chemistry and manufacturing precision determine addressable end-use markets and margin structures.
Product Type:
Polymer-based films anchor domestic production in Germany and Japan where automotive tier-one suppliers operate captive lamination lines. Rubber and composite formulations travel through export channels to aerospace OEMs in France and the United States.
- Polymer-based Films:Thermoplastic structures combining oriented PET or polyamide substrates with ceramic-modified surfaces achieve coefficients of friction between 0.5 and 0.8. German automotive suppliers in Stuttgart and Munich pull volume through qualified supply chains for brake and clutch applications where REACH compliance mandates halogen-free formulations.
- Coated Films:Slot-die and gravure coating methods deposit sub-micron precision layers for clutch plate interfaces. Japanese transmission manufacturers in Aichi Prefecture specify these films for compact dual-clutch assemblies where thickness control below 50 microns determines shift quality.
- Rubber Films:Natural and synthetic rubber compounds bonded to textile carriers provide vibration damping in industrial machinery.
- Composite Films:Ceramic-polymer hybrids withstand temperature excursions exceeding 150°C in aerospace torque limiters.
Polymer-based films command the established base. The steepest expansion runs through coated films.
Application:
Cost tier separation distinguishes premium aerospace specifications from high-volume automotive procurement. Aerospace programs absorb qualification overhead for temperature performance; automotive buyers compress unit economics through scale.
- Automotive:Brake pad backing plates, clutch friction interfaces, and transmission synchronizers consume multilayer films in 25–100 micron gauges. German tier-one suppliers operate dedicated lamination facilities in Baden-Württemberg and Bavaria, pulling compound formulations through backward-integrated supply chains.
- Aerospace:Landing gear shim stacks, flight control torque limiters, and cargo restraint systems specify polymer-based friction surfaces for weight reduction and corrosion resistance. French OEMs sourcing under EU Green Deal constraints demand certified halogen-free formulations with full material disclosure.
- Industrial Machinery:Packaging equipment conveyors and machine tool slideways employ FDA-compliant films for food-contact and precision positioning.
- Sports Equipment:Ski bases and bicycle brake pads use modified polymer films for controlled glide and stopping friction.
Automotive absorbs the volume base. Aerospace captures the margin premium.
End User:
Customer type determines procurement sophistication and qualification burden. OEMs impose material disclosure requirements; contractors and designers purchase through distribution with shorter lead times.
- Manufacturers:Tier-one automotive and aerospace OEMs consolidate vendor bases and demand certified halogen-free supply chains with embedded compliance documentation.
- Engineers:Application-specific specification authority in industrial machinery and medical equipment drives formulation customization.
- Designers:Sports equipment and consumer product developers prioritize aesthetic surface finish and brand differentiation.
- Contractors:Industrial maintenance and retrofit channels purchase standard gauges through distributor networks.
Manufacturers concentrate procurement authority. Engineers open premium niches through specification influence.
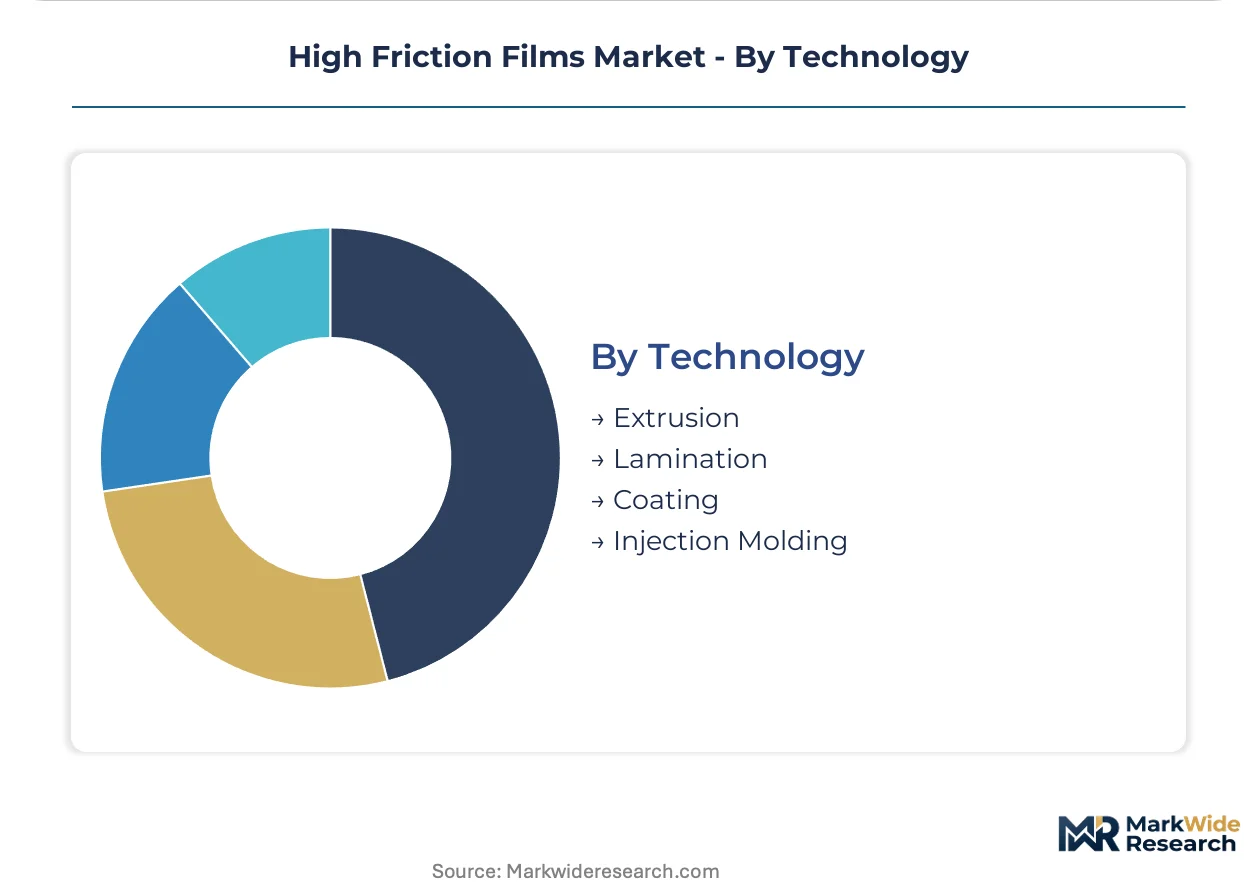
Technology:
Supply concentration in East Asian manufacturing corridors shapes technology adoption patterns. Extrusion and coating capacity clusters in South Korea and China; European converters retrofit legacy lamination lines for sub-micron precision.
- Coating:Slot-die and gravure methods enable sub-micron thickness precision for automotive clutch plate interfaces. South Korean equipment suppliers dominate coating line installation, though European converters face capital deployment demands without guaranteed volume commitments.
- Extrusion:Multilayer coextrusion with ceramic-modified surface layers miniaturizes functional thickness toward 25 microns. Japanese resin compounders in Osaka and Nagoya supply modified polyamides for transmission applications.
- Lamination:Adhesive bonding of dissimilar substrates serves industrial machinery and sports equipment markets.
- Injection Molding:Compression molding of rubber-modified compounds produces three-dimensional friction components.
Coating technology captures the steepest capability investment. Extrusion retains the volume foundation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH and RoHS compliance in Europe is tightening material specifications and pushing converters toward halogen-free formulations. Demand concentrates in Germany, where automotive tier-one suppliers operate dedicated film lamination facilities for brake and clutch applications.
Germany
Automotive tier-one suppliers in Baden-Württemberg and Bavaria operate dedicated lamination facilities for brake and clutch interfaces. REACH compliance mandates complete halogen-free formulation overhauls, raising raw material expenses and requalification burdens. Stuttgart and Munich clusters pull compound formulations through backward-integrated supply chains qualified under EU Green Deal carbon border adjustments.
United States
Aerospace OEMs in the Pacific Northwest and Southeast specify polymer-based friction surfaces for landing gear weight reduction and corrosion resistance. FDA regulations govern indirect food-contact friction films used in packaging machinery across industrial Midwest corridors. Boeing suppliers in Washington state and Gulf Coast aerospace clusters absorb qualification overhead for temperature-performance specifications.
Japan
Transmission manufacturers in Aichi Prefecture specify coated films with sub-micron thickness control below 50 microns for compact dual-clutch assemblies. METI industrial standards drive precision coating investments among Osaka and Nagoya resin compounders. Japanese resin suppliers in these prefectures deliver modified polyamides qualified under JIS standards for automotive torque transmission.
India
Packaging machinery OEMs under BIS standards seek FDA-compliant friction films for food-contact conveying systems in Maharashtra and Gujarat industrial corridors. The country's national industrial standards regulator enforces compliance documentation for imported film substrates. Pune and Ahmedabad manufacturing clusters are qualifying halogen-free formulations for domestic automation equipment.
South Korea
Coating line equipment suppliers dominate precision slot-die and gravure installation across Gyeonggi-do and Chungcheong manufacturing belts. MFDS pharmaceutical and medical device standards create adjacent demand for sterilization-compatible friction surfaces. Suwon and Daejeon industrial zones host converters retrofitting legacy lamination lines for sub-micron precision without guaranteed volume commitments.
High Friction Films Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the high friction films market. The vendor base separates into three tiers: integrated chemical conglomerates commanding aerospace premium contracts, mid-scale converters with captive substrate production, and regional specialists serving spot industrial demand. Two dominant competitive moves are reshaping positioning: backward integration into PET substrate production to secure supply chain control, and joint development agreements with specialty chemical partners to accelerate halogen-free requalification cycles.
Among integrated chemical conglomerates, DuPont leverages its fluoropolymer heritage to anchor premium aerospace contracts. SKC Inc. competes through upstream control over PET substrate production, sustaining cost discipline across Asian industrial channels. Mitsubishi Chemical occupies a position within the materials science tier, exemplifying diversified portfolio strategies that span multiple friction film chemistries.
| Leading Market Players |
|---|
| Ester Industries Ltd. |
| Toray Plastics (America) Inc. |
| FlexFilms Ltd. |
| Jindal Poly Films Ltd. |
| TEKRA, A Division of EIS, Inc. |
| SKC Inc. |
| Cosmo Films Ltd. |
| DuPont |
| Mitsubishi Chemical |
| Others |
Supply & Pricing Matrix
Capacity utilization at German automotive lamination facilities anchors price floors across European supply chains, compressing margins for converters without backward-integrated substrate production. East Asian PET manufacturing corridors exploit scale economies to undercut qualified supply chains, forcing European and North American buyers into long-term contract structures that embed compliance documentation premiums.
Pricing Analysis
German tier-one suppliers command pricing premiums over South Korean and Chinese converters, reflecting REACH qualification overhead and carbon border adjustment exposure. Three-tier pricing structure across aerospace-certified, automotive-qualified, and industrial-standard levels separates margin pools. Price differentiation hinges on halogen-free certification grade and volume scale commitments. Cost compression in industrial-standard tiers is intensifying because spot purchasers are migrating to distributor channels with shorter lead times. Automotive OEM procurement teams exhibit highest price sensitivity; aerospace program offices absorb premium pricing for temperature-performance specifications.
Supply Chain Analysis
Strategic stockpiling of ceramic-modified resin compounds dominates German and Japanese procurement desks, while just-in-time substrate delivery prevails among South Korean coating line operators. PET film supply chains cluster in China, South Korea, and Taiwan, exposing converters to logistics volatility and tariff exposure. Raw material dependencies rest on oriented polyamide substrates, ceramic particle feedstocks, and silicone-based coating chemistries. Single-source vulnerability concentrates in East Asian substrate manufacturing corridors. Distribution runs through qualified tier-one supplier networks with embedded compliance documentation, displacing spot purchasing through distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High friction films face substitution pressure from sintered metal friction plates in aerospace torque limiters above 150°C, compelling polymer film incumbents to defend application scope through temperature-performance certification.
For Market Incumbents: Shield market position by accelerating halogen-free requalification cycles under EU Green Deal constraints and securing captive PET substrate production in Germany or Japan. Backward integration into resin compounding anchors supply chain control against East Asian cost pressure. Certification investment in FDA-compliant food-contact formulations opens adjacent industrial machinery segments. For New Entrants and Emerging Players: Differentiate on sterilization-compatible friction surfaces for surgical robotics and diagnostic equipment manufacturers in South Korea under MFDS standards. White-space targets include India packaging machinery OEMs seeking BIS-qualified halogen-free formulations and compact dual-clutch transmission applications below 50 microns. Go-to-market through joint development agreements with specialty chemical partners accelerates qualification timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among converters with long-term supply agreements embedding compliance documentation and backward-integrated substrate production. Five-to-ten year viability favors acquisition targets with qualified aerospace contracts and halogen-free formulation pipelines. Signal to watch: joint development agreement announcements between European converters and silicone polymer suppliers indicating F-Gas Regulation adaptation progress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PET Substrate Production | SKC Inc. anchors cost discipline across Asian industrial channels through upstream control. |
| Halogen-Free Formulation Requalification | REACH and F-Gas Regulation compliance forces complete resin platform changes among EU converters. |
| Joint Development Agreement with Specialty Chemical Partners | Accelerates silicone and acrylic alternative pipelines for aerospace OEM procurement. |
| Long-term Supply Agreement with Embedded Compliance Documentation | German tier-one suppliers displace spot purchasing through qualified vendor base consolidation. |
| Capacity Expansion in Medical Device-Adjacent Friction Surfaces | MFDS standards in South Korea create sterilization-compatible premium niches for diagnostic equipment. |
Research Methodology
Cross-validation between primary interviews with polymer chemists, coating engineers, automotive tier-one procurement leads, and aerospace OEM material specialists anchors the qualitative findings. Secondary validation draws from customs and trade data, ECHA REACH registration databases, SEC 10-K filings of listed film converters, and automotive production registration databases. Bottom-up segment sizing triangulates against top-down market envelope checks.
Sensitivity analysis around ceramic raw material cost volatility and REACH compliance timeline slippage informs projection robustness across the analysis window. Segmentation dimensions modeled include product type, application vertical, end-user procurement archetype, and coating technology precision tier. CAGRs derive from compound annual growth trajectory fitting against historical volume elasticities. Industry-specific forecast inputs incorporate automotive transmission platform standardization cycles and aerospace OEM landing gear procurement patterns.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or accelerated F-Gas Regulation phase-out schedules would require recalibration. Forecasts reflect assumptions around halogen-free formulation adoption curves and substrate supply chain stability. Revision becomes warranted when ceramic feedstock price volatility or logistics chokepoint severity crosses thresholds that compress converter margins below reinvestment levels.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market
High-Value Chemicals
High-Purity Nitrogen Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market
High-Value Chemicals
Global Hyaluronidase Market
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
Global Epichlorohydrin (ECH) Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
Hydroquinone Market
High-Value Chemicals
Potassium Hydroxide Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Diethylhydroxylamine (DEHA) Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
High-K Dielectric Material Market