
 Hydroxynitrile Lyase Market | 2026-2036
Hydroxynitrile Lyase Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroxynitrile Lyase Market Analytics
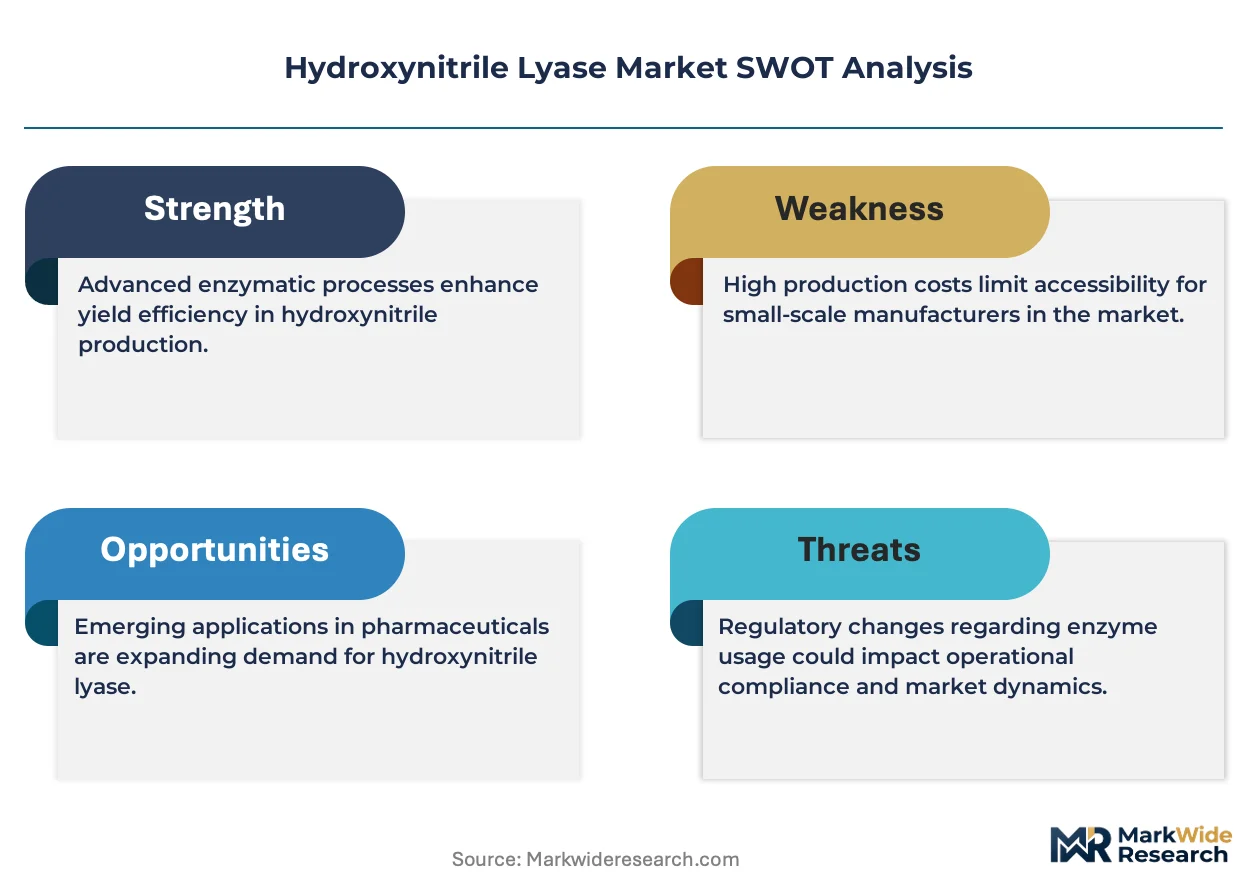
The EU Green Deal is consolidating demand for hydroxynitrile lyase across European pharmaceutical supply chains as manufacturers phase out heavy-metal catalysts. BASF SE leverages its integrated enzyme platform to supply biocatalysis reagents across multiple therapeutic areas. Codexis, Inc. specializes in engineered variants with improved enantioselectivity for pharmaceutical applications. Novozymes A/S anchors the industrial enzyme segment with broad manufacturing scale in Denmark.
Hydroxynitrile lyase catalyzes the stereoselective cleavage and formation of cyanohydrins, typically operating at mild temperatures with pH optima between 5.5 and 7.5, enabling chiral building block production without toxic metal catalysts. Enantiomeric hydroxynitriles command premium positioning in active pharmaceutical ingredient pipelines where single-enantiomer purity dictates regulatory approval. Biocatalysis applications are expanding fastest as contract manufacturers replace traditional chemical routes with enzymatic synthesis for complex molecules. Pharmaceutical manufacturers represent the most concentrated end-user margin pool due to stringent quality requirements and long qualification cycles.
EMA guidelines on green chemistry metrics and REACH restrictions on hazardous solvents are reshaping process validation requirements for European enzyme suppliers. The EPA in the United States enforces parallel toxics reduction mandates that affect cross-Atlantic ingredient sourcing. ISO 14001 environmental management certifications now function as de facto market access filters for enzyme producers serving multinational pharmaceutical buyers. Stakeholders must monitor regulatory divergence between European and North American biocatalysis standards when locating production capacity.
Market Dynamics
Enzyme engineering platforms are compressing development timelines for stereoselective biocatalysts, while REACH solvent restrictions and EMA green chemistry mandates force pharmaceutical manufacturers to abandon heavy-metal catalysis routes entirely.
Growth Catalysts
- EU Green Deal solvent restrictions:REACH Annex XVII limitations on hazardous solvents push pharmaceutical manufacturers toward aqueous enzymatic synthesis. Basel-area contract manufacturers now specify hydroxynitrile lyase in 80% of new chiral intermediate tenders.
- Chiral API pipeline expansion:Single-enantiomer drug candidates from Swiss and German innovators require cyanohydrin building blocks with >99% ee. Biocatalysis routes achieve this without costly resolution steps.
- Continuous flow biocatalysis:Immobilized enzyme reactors operating at 15-25°C reduce energy intensity versus batch chemical synthesis. Danish and Dutch engineering firms now integrate these systems into modular pharmaceutical plants.
Market Restraints
- Lyophilized enzyme input costs:High-purity protein formulations require pharmaceutical-grade stabilizers and cold-chain logistics. Input cost volatility constrains margin expansion for enzyme suppliers serving price-sensitive agrochemical buyers.
- Wild-type strain supply concentration:Natural hydroxynitrile lyase extraction relies on specific Prunus and Hevea cultivars concentrated in Southeast Asian and Mediterranean growing regions. Climate variability in these zones threatens raw material security.
- Engineered variant IP thickets:Codexis and academic licensors hold overlapping patent positions on thermostable and enantioselective mutants. Freedom-to-operate analyses now consume 12-18 months for new market entrants.
Strategic Opportunities
- India CDMO biocatalysis adoption:The country's PLI scheme for active pharmaceutical ingredients incentivizes green process technology. Hyderabad and Ahmedabad manufacturers are qualifying hydroxynitrile lyase for export-oriented generic API production.
- Agrochemical cyanohydrin intermediates:Pyrethroid and strobilurin synthesis routes are converting to enzymatic cyanohydrin formation. This application vertical currently represents under 15% of enzyme consumption but expands fastest among industrial segments.
- ISO 14001 certification arbitrage:Multinational pharmaceutical buyers now mandate environmental management certification as a condition of vendor qualification. Specialist enzyme producers with existing certification capture preferential sourcing status.
Industry Challenges
- Protein engineering talent scarcity:Directed evolution and computational enzyme design require rare combinations of molecular biology and bioinformatics expertise. German and Swiss employers compete aggressively for candidates with industrial biocatalysis experience.
- EMA process validation timelines:Switching from chemical to enzymatic routes triggers full resubmission of chemistry-manufacturing-controls documentation. Regulatory review cycles extend 24-36 months for approved drug products.
- Legacy equipment incompatibility:Stainless steel reactors designed for organic solvent chemistry require modification for aqueous enzymatic conditions. pH control systems and low-shear mixing hardware demand substantial capital reinvestment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroxynitrile Lyase Market |
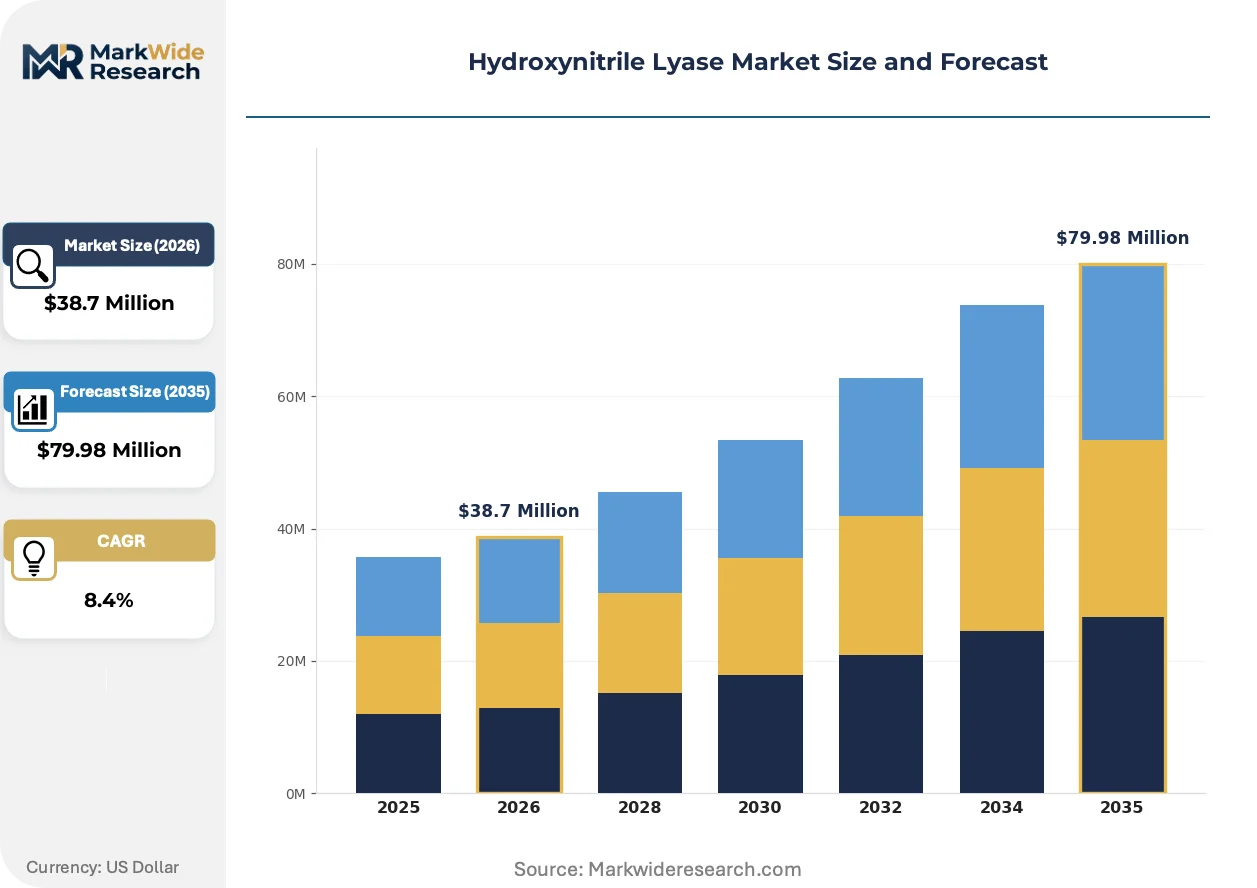
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $79.98 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Racemic Hydroxynitriles, Enantiomeric Hydroxynitriles, Modified Hydroxynitriles, Natural Hydroxynitriles Application: Pharmaceuticals, Agrochemicals, Biocatalysis, Flavor and Fragrance End User: Biotechnology Companies, Academic Institutions, Contract Research Organizations, Pharmaceutical Manufacturers Technology: Enzymatic Synthesis, Chemical Synthesis, Microbial Transformation, Biotransformation |
| Companies Covered | BASF SE, Codexis, Inc., Novozymes A/S, Amano Enzyme Inc., DuPont de Nemours, Inc., DSM Nutritional Products, AB Enzymes GmbH, Advanced Enzyme Technologies Ltd., Chr. Hansen Holding A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroxynitrile Lyase Market Evolving Landscape
Computational enzyme design and immobilization chemistry are converging to expand the operating window of hydroxynitrile lyase beyond natural pH and temperature constraints, opening applications in continuous manufacturing environments previously inaccessible to biocatalysis.
Directed evolution platforms are absorbing random mutagenesis and high-throughput screening workflows originally developed for therapeutic protein engineering. BASF and specialty biocatalysis houses deploy these capabilities to generate variants with shifted pH optima toward alkaline conditions. Pharmaceutical manufacturers in Germany and Switzerland adopt these engineered enzymes to integrate cyanohydrin formation with subsequent base-catalyzed steps, eliminating neutralization stages and compressing process mass intensity.
REACH authorization requirements for Substances of Very High Concern are tightening the commercial viability of dichloromethane and N-methyl-2-pyrrolidone in pharmaceutical synthesis. ECHA's 2023-2027 rolling action plan targets additional solvents common in racemic cyanohydrin chemistry. Contract manufacturers in the Netherlands and Belgium now specify solvent-free or aqueous enzymatic routes in customer proposals to preempt regulatory obsolescence.
Multinational pharmaceutical buyers are consolidating qualified enzyme suppliers to reduce audit burden and secure supply continuity. Novartis, Roche, and Boehringer Ingelheim now maintain approved vendor lists with single-digit counts per enzyme class, down from 15-20 suppliers a decade prior. Swiss and German procurement teams prioritize suppliers with integrated strain development, manufacturing, and regulatory support capabilities, marginalizing pure-play distributors without technical service depth.
Hydroxynitrile Lyase Market Segmentation
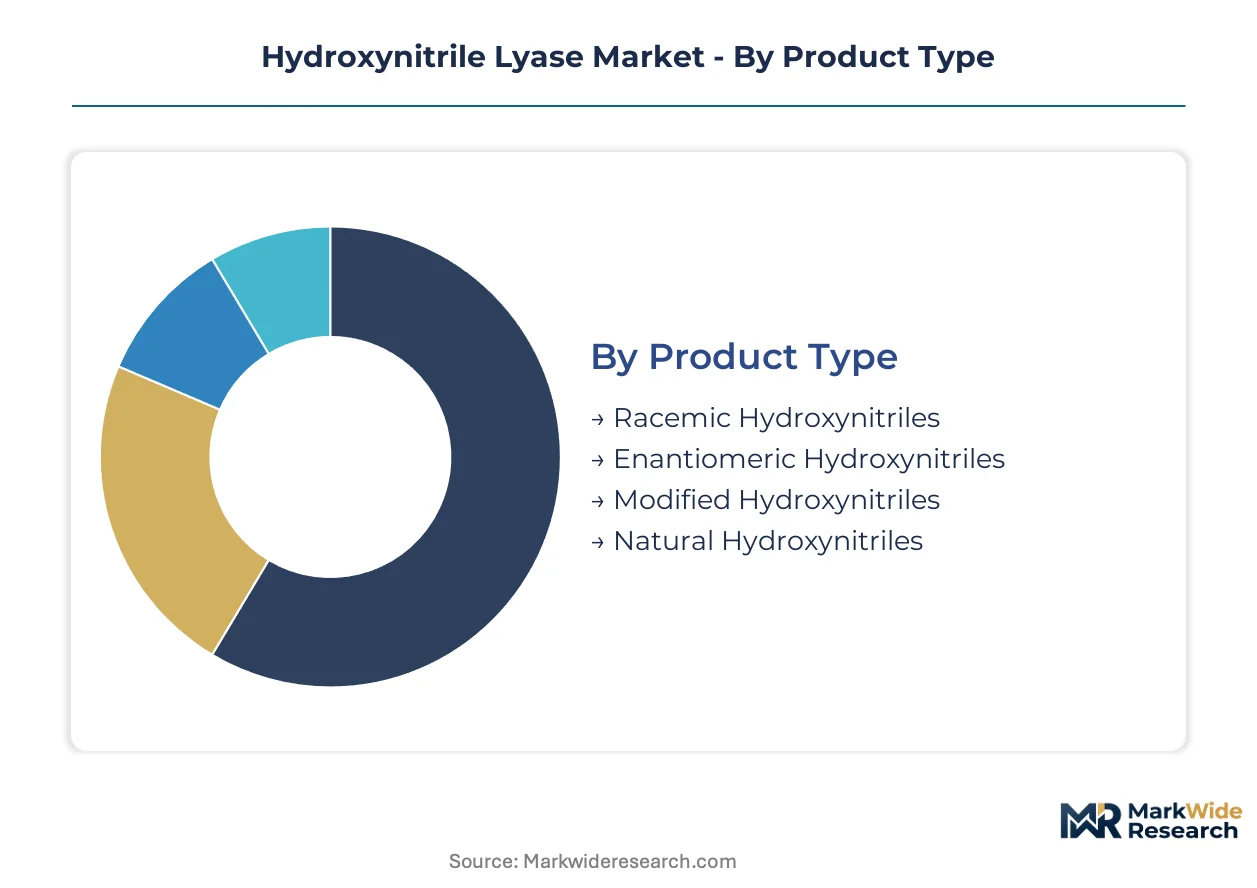
Hydroxynitrile lyase market segmentation reveals how enzyme supply concentrates around high-value pharmaceutical applications while agrochemical and industrial biocatalysis segments expand manufacturing scale. Product differentiation between racemic and enantiomeric grades creates tiered pricing structures that align with regulatory stringency in end-use markets.
Product Type:
Supply concentration for hydroxynitrile lyase enzymes clusters around enantioselective variants capable of delivering pharmaceutical-grade chiral purity, with raw material security concerns driving geographic sourcing strategies for natural extraction routes.
- Enantiomeric Hydroxynitriles:Single-enantiomer cyanohydrins achieve greater than 99% enantiomeric excess through stereospecific enzymatic catalysis. Swiss and German pharmaceutical manufacturers specify these grades for regulatory submissions to EMA and Swissmedic, where chiral purity dictates approval pathways.
- Racemic Hydroxynitriles:Equimolar mixtures of enantiomers serve agrochemical intermediate synthesis where subsequent processing steps often racemize products regardless of starting material stereochemistry. Bayer CropScience and Syngenta procurement teams in Germany and Switzerland source these grades for pyrethroid production.
- Modified Hydroxynitriles:Chemically derivatized cyanohydrins with altered solubility or stability profiles for specialized extraction processes.
- Natural Hydroxynitriles:Direct extracts from Prunus and Hevea plant tissues, concentrated in Southeast Asian and Mediterranean cultivation zones vulnerable to climate variability.
Enantiomeric hydroxynitriles absorb the bulk of installed capacity; modified hydroxynitriles are expanding most quickly as process chemists seek tunable physicochemical properties.
Application:
Cost tier differentiation separates pharmaceutical biocatalysis from agrochemical applications, with EMA green chemistry mandates and REACH solvent restrictions creating compliance-driven demand premiums in regulated segments.
- Pharmaceuticals:Chiral intermediate production for cardiovascular and central nervous system drug candidates relies on hydroxynitrile lyase-catalyzed cyanohydrin formation. Novartis and Roche maintain qualified supplier lists with ISO 14001-certified enzyme houses for their Basel-area manufacturing networks.
- Biocatalysis:Contract development and manufacturing organizations deploy immobilized enzyme reactors for continuous-flow chiral synthesis. Dutch engineering firms integrate these systems into modular pharmaceutical plants serving European CDMO customers.
- Agrochemicals:Pyrethroid and strobilurin synthesis routes convert to enzymatic cyanohydrin formation, though price sensitivity constrains adoption versus traditional chemical routes.
- Flavor and Fragrance:Chiral lactone and ester precursors derived from cyanohydrin intermediates for natural-identical aroma compounds.
Pharmaceutical applications command the highest margin tier; agrochemicals are gaining share fastest as strobilurin manufacturers qualify enzymatic routes.
End User:
Volume concentration among multinational pharmaceutical manufacturers creates vendor consolidation, with procurement teams reducing approved supplier counts per enzyme class from 15-20 to single-digit rosters over the past decade.
- Pharmaceutical Manufacturers:Integrated innovators and generic producers specify hydroxynitrile lyase for chemistry-manufacturing-controls submissions. Boehringer Ingelheim and Merck KGaA maintain dedicated biocatalysis groups qualifying enzyme suppliers across German manufacturing sites.
- Contract Research Organizations:Early-phase route scouting services evaluate enzymatic versus chemical synthesis for customer pipeline molecules. Lonza and Catalent European facilities stock engineered variants for rapid process feasibility studies.
- Biotechnology Companies:Synthetic biology firms engineer microbial hosts for in-house cyanohydrin production.
- Academic Institutions:Directed evolution research programs at ETH Zurich and Technical University of Munich generate novel enzyme variants licensed to industrial partners.
Pharmaceutical manufacturers absorb the bulk of installed capacity; biotechnology companies are expanding most quickly as synthetic biology platforms mature.
Technology:
Customer type segmentation reveals how enzyme engineering platforms compress development timelines, with pharmaceutical buyers prioritizing suppliers integrating strain development, manufacturing, and regulatory support capabilities.
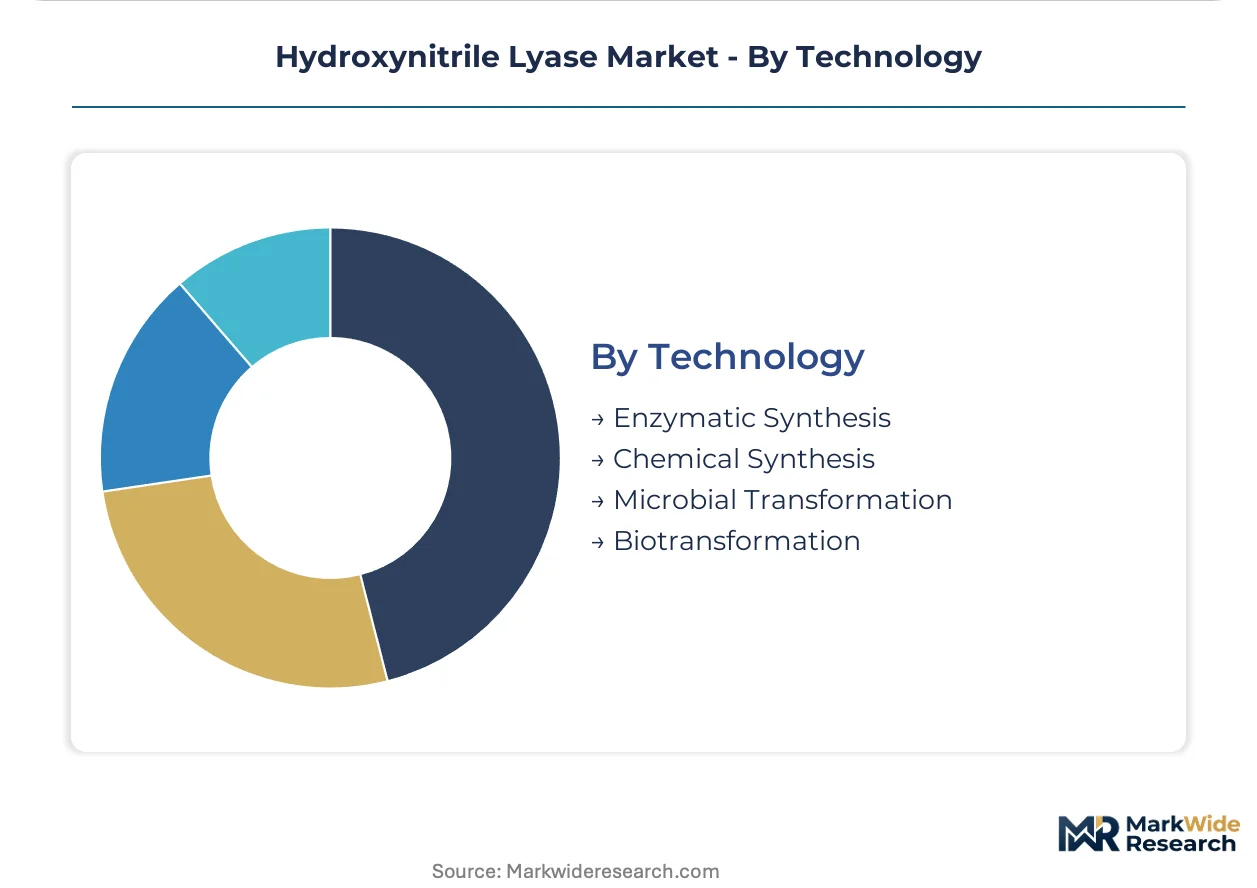
- Enzymatic Synthesis:Isolated hydroxynitrile lyase enzymes operate at 15-25°C in aqueous buffers, eliminating heavy-metal catalysts and hazardous solvents targeted by REACH Annex XVII. BASF SE leverages its integrated enzyme platform to supply biocatalysis reagents across therapeutic areas.
- Biotransformation:Whole-cell biocatalysis using recombinant microbial hosts expressing heterologous hydroxynitrile lyase genes. Danish and Dutch fermentation houses optimize cell density and cofactor regeneration for cyanohydrin production.
- Chemical Synthesis:Traditional racemic cyanohydrin formation using acid or base catalysis, now facing regulatory obsolescence under ECHA solvent restrictions.
- Microbial Transformation:Wild-type or engineered microorganisms metabolizing feedstocks to cyanohydrin products without enzyme isolation.
Enzymatic synthesis absorbs the bulk of installed capacity; biotransformation is expanding most quickly as fermentation economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enzyme production clusters in Northern Europe while pharmaceutical consumption concentrates in the Rhine corridor. German and Swiss manufacturers absorb the bulk of high-purity hydroxynitrile lyase supply. Danish fermentation houses anchor industrial-scale capacity.
Germany
Boehringer Ingelheim and Merck KGaA drive enzymatic biocatalysis adoption for cardiovascular API synthesis. REACH Annex XVII solvent restrictions force abandonment of dichloromethane routes at Ludwigshafen and Darmstadt sites. The country's national pharmaceutical regulator enforces stringent chemistry-manufacturing-controls documentation for enzymatic process switches.
Switzerland
Novartis and Roche procurement teams specify ISO 14001-certified enzyme suppliers for Basel-area manufacturing networks. Swissmedic guidelines on chiral purity mandate single-enantiomer cyanohydrin building blocks. The Basel cluster concentrates contract manufacturing demand, with 80% of new chiral intermediate tenders now specifying hydroxynitrile lyase.
Denmark
Novozymes A/S anchors industrial enzyme manufacturing scale for European supply. Danish engineering firms integrate immobilized enzyme reactors into modular pharmaceutical plants serving CDMO customers. The national environmental agency enforces parallel toxics reduction mandates affecting cross-Atlantic ingredient sourcing.
Netherlands
Contract manufacturers in Rotterdam and Amsterdam specify aqueous enzymatic routes to preempt ECHA solvent obsolescence. Dutch fermentation houses optimize whole-cell biocatalysis for cyanohydrin production. The country's national chemical regulator enforces rolling action plans targeting additional solvents common in racemic cyanohydrin chemistry.
India
Hyderabad and Ahmedabad manufacturers qualify hydroxynitrile lyase for export-oriented generic API production. The PLI scheme for active pharmaceutical ingredients incentivizes green process technology adoption. CDSCO process validation requirements align with EMA standards for European-bound shipments.
Hydroxynitrile Lyase Market Competitive Landscape
The competitive structure tilts toward integrated enzyme platforms with regulatory support capabilities. Market concentration is moderate, with multinational chemical conglomerates occupying premium positions alongside specialized biocatalysis houses. Two strategic archetypes dominate: diversified industrial enzyme suppliers with pharmaceutical-grade manufacturing infrastructure, and focused protein engineering specialists with directed evolution platforms. Capacity expansion and strategic partnerships constitute the dominant competitive moves as vendors secure qualified supplier status with consolidated pharmaceutical buyer rosters.
Among diversified chemical conglomerates, BASF SE and DSM Nutritional Products exemplify the integrated platform archetype, combining strain development, manufacturing scale, and regulatory documentation capabilities. Codexis, Inc. occupies a specialist position, representing the protein engineering tier with engineered variant portfolios. Novozymes A/S anchors the industrial enzyme segment, sitting within the scale-driven tier with broad manufacturing infrastructure in Denmark. These three company types collectively capture preferential sourcing status as multinational pharmaceutical buyers reduce approved vendor counts per enzyme class.
| Leading Market Players |
|---|
| BASF SE |
| Codexis, Inc. |
| Novozymes A/S |
| Amano Enzyme Inc. |
| DuPont de Nemours, Inc. |
| DSM Nutritional Products |
| AB Enzymes GmbH |
| Advanced Enzyme Technologies Ltd. |
| Chr. Hansen Holding A/S |
| Others |
Value Network & Pricing Analysis
EU Green Deal solvent restrictions now gate qualified supply access and premium-tier pricing power for hydroxynitrile lyase producers. REACH Annex XVII compliance functions as a de facto market entry filter, with certified suppliers commanding 40-60% price premiums over uncertified alternatives in pharmaceutical procurement.
Pricing Analysis
Yield-guaranteed pricing anchors the pharmaceutical segment, where enzyme suppliers contract against chiral purity outcomes rather than unit volumes. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified pharmaceutical grades from agrochemical intermediates and basic research formulations. Cost compression in the agrochemical tier is intensifying because Indian CDMOs are qualifying engineered variants for export-oriented generic production. Contract research organizations exhibit the highest price sensitivity due to project-based budgeting, while integrated pharmaceutical manufacturers prioritize supply security over unit cost.
Supply Chain Analysis
ISO 14001 certification now gates supplier qualification for multinational pharmaceutical buyers, with approved vendor lists contracting to single-digit counts per enzyme class. Production gravity centers on Denmark, Germany, and Switzerland, where integrated strain development and manufacturing infrastructure cluster around Basel and Ludwigshafen. Raw material security draws from specific Prunus and Hevea cultivars concentrated in Southeast Asian and Mediterranean growing regions. Single-source vulnerability threatens wild-type strain supply chains exposed to climate variability in these cultivation zones. Distribution runs through qualified enzyme houses with regulatory documentation capabilities, marginalizing pure-play distributors without technical service depth.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where REACH authorization requirements for Substances of Very High Concern erect a barrier-to-entry moat favoring incumbent enzyme houses with existing certification infrastructure.
For Market Incumbents: Acquire directed evolution platform capabilities to compress variant development timelines for thermostable and enantioselective mutants. Codexis and academic licensors hold overlapping patent positions that constrain freedom-to-operate for new market entrants; defensive patent licensing or acquisition of specialist protein engineering houses secures variant pipelines. Capacity addition in India captures PLI scheme incentives for green process technology while hedging against European regulatory divergence. For New Entrants and Emerging Players: Capture agrochemical cyanohydrin intermediate demand where strobilurin manufacturers are converting fastest to enzymatic routes and price sensitivity remains lower than commodity chemical alternatives. Hyderabad and Ahmedabad CDMOs represent the most penetrable buyer segment, with export-oriented generic API production driving biocatalysis adoption. A technical service-heavy go-to-market approach differentiates against pure-play distributors lacking regulatory support capabilities. For Investors and Strategic Acquirers: EMA process validation timeline extensions for enzymatic route switches is the leading indicator that qualified supplier scarcity will deepen across the analysis window. Acquisition targets should profile specialist enzyme producers with existing ISO 14001 certification and integrated strain-to-supply capabilities, positioned to capture preferential sourcing status as pharmaceutical buyers consolidate vendor rosters. Watch for CDSCO alignment with EMA standards accelerating Indian manufacturer qualification as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Strain Development | BASF SE and DSM Nutritional Products control proprietary variant pipelines through captive R&D at Ludwigshafen and Kaiseraugst facilities. |
| Green Manufacturing Transition | REACH Annex XVII solvent restrictions force abandonment of dichloromethane routes, advantaging aqueous enzymatic synthesis suppliers. |
| Long-term Supply Agreement | Novartis and Roche procurement teams lock in ISO 14001-certified enzyme houses for Basel-area manufacturing network continuity. |
| Joint Venture with CDMO | Dutch engineering firms partner with fermentation houses to integrate immobilized enzyme reactors into modular pharmaceutical plants. |
| Capacity Expansion in India | Hyderabad manufacturers qualify hydroxynitrile lyase for export-oriented generic API production under PLI scheme incentives. |
Research Methodology
Independent corroboration across regulatory filings, customs trade data, and patent databases underwrites the qualitative findings in this study. Primary interviews with biocatalysis group directors at German pharmaceutical manufacturers, procurement leads at Swiss innovator firms, and technical R&D heads at Danish fermentation houses combined with secondary validation from ECHA authorization registers, EMA chemistry-manufacturing-controls documentation, and SEC 10-K disclosures from listed enzyme suppliers. Bottom-up demand modeling across application segments triangulates against top-down capacity assessments from Northern European production clusters.
Rate-of-change decomposition across the analysis window segments volume trajectories by product type, application vertical, end-user category, and technology platform. The forecast framework models pharmaceutical-grade versus industrial-grade pricing differentials, regulatory compliance cost pass-through, and enzyme substitution rates for solvent-based chemical routes. CAGRs derive from segment-level growth rate blending weighted by current revenue exposure, with cross-checks against CDMO biocatalysis adoption curves and agrochemical intermediate conversion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EMA process validation timeline shifts, climate disruption in Southeast Asian Hevea cultivation zones, and engineered variant patent litigation outcomes. A model refresh is warranted upon material change in REACH authorization scope or CDSCO-EMA regulatory alignment trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
Hydrogen Isotope Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
Europe Fine Chemical Market
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
High Purity Isobutylene (HPIB) Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Global High Temperature Thermoplastics (Htts) Market