
 High Purity Silica Market | 2026-2036
High Purity Silica Market Size, Share, and Industry Trends Forecast 2026-2036
High Purity Silica Market Analysis
The EU Green Deal's embodied carbon tracking for imported materials is hardening compliance requirements for silica feedstocks entering European electronics supply chains. Evonik Industries AG leverages its fumed silica R&D pipeline to sustain premium positioning in medical and cosmetic grades. Sibelco anchors Atlantic basin supply through its Spruce Pine operations in North Carolina, while Jiangsu Pacific Quartz Co., Ltd. dominates high-purity quartz crystal growth for semiconductor crucibles.
High purity silica denotes silicon dioxide refined to impurity levels below 50 parts per million, typically achieved through acid leaching, thermal treatment, and flotation separation of naturally occurring quartz or synthetic routes via silicon tetrachloride hydrolysis. The material serves as an essential input for semiconductor wafers, optical fiber preforms, and pharmaceutical excipients where trace metal contamination degrades performance. Fumed silica leads value generation due to its reinforcement properties in silicone elastomers and thixotropic control in coatings, while precipitated silica competes aggressively on cost in tire and rubber applications. Electronic grade silica commands the steepest purity premiums as chipmakers push sub-10nm node requirements.
REACH registration and RoHS substance restrictions in Europe, alongside China's GB standards for electronic materials and the EPA's crystalline silica permissible exposure limits in the United States, collectively elevate purification capital requirements and testing protocols for market participants. Japan's METI has similarly tightened JIS specifications for silica used in photovoltaic ingot production. Stakeholders must monitor evolving purity thresholds across these regulatory regimes while assessing synthetic versus natural feedstock arbitrage opportunities.
Market Dynamics
Semiconductor node shrinkage below 10nm is compressing impurity tolerances for crucible-grade silica, forcing refiners to retool acid-leaching circuits and thermal treatment furnaces across the supply base.
Growth Catalysts
- Photovoltaic ingot demand:Solar cell manufacturers in Jiangsu province are scaling orders for semiconductor-grade silica crucibles as PERC and TOPCon cell architectures proliferate.
- China's dual carbon goals:NMPA impurity thresholds for domestic electronics-grade silica are tightening, creating premium pricing tiers for sub-50ppm material.
- Fumed silica reinforcement:Silicone elastomer formulators are expanding thixotropic additive volumes for medical device and cosmetic applications.
Market Restraints
- Feedstock concentration:Ultra-high-purity natural quartz deposits cluster in limited geologic formations, concentrating mining rights among state-backed and legacy operators.
- Energy cost volatility:Thermal purification furnaces consume substantial electricity, exposing margins to grid pricing swings in refining corridors.
- REACH compliance friction:ECHA registration requirements for synthetic silica intermediates extend certification timelines for European market entry.
Strategic Opportunities
- Indian electronics manufacturing:PLI scheme incentives for semiconductor fabs create captive demand for imported crucible-grade material as domestic refining capacity remains nascent.
- Synthetic route arbitrage:Silicon tetrachloride hydrolysis offers impurity control unattainable from natural quartz, commanding premiums in optical fiber preform applications.
- EU Green Deal embodied carbon tracking:Low-carbon purification processes qualify for preferential procurement in European electronics supply chains.
Industry Challenges
- Metallurgical analysis talent scarcity:ICP-MS and glow discharge mass spectrometry expertise for sub-ppm impurity detection commands premium compensation in refining hubs.
- Crucible dimensional certification:Semiconductor OEMs require 18-24 month qualification cycles for new silica suppliers, freezing out mid-cap entrants.
- Legacy flotation circuit retrofit:Acid leaching infrastructure upgrades demand capital deployment while maintaining existing output commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Purity Silica Market |
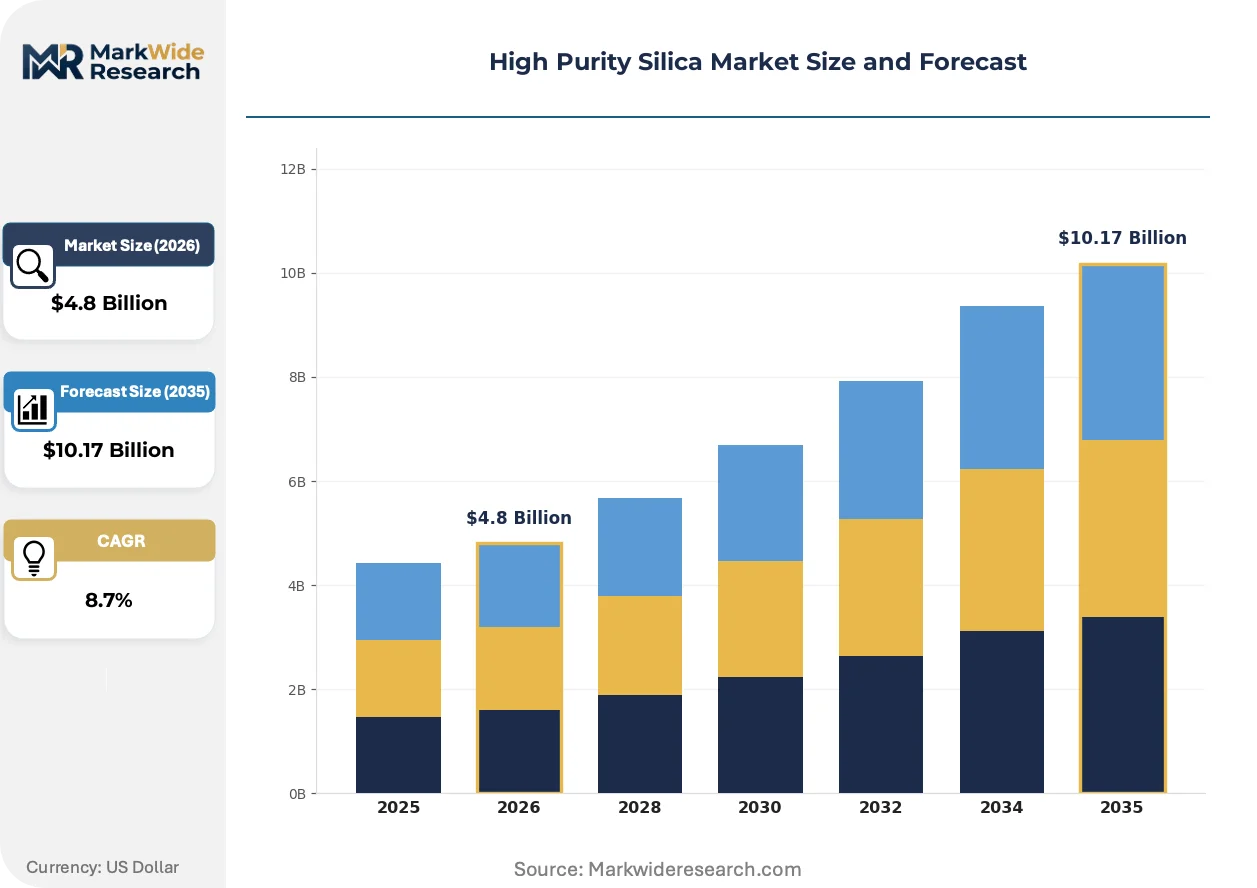
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aerosil, Fumed Silica, Precipitated Silica, Ground Silica Grade: Standard, Medical, Electronic, Pharmaceutical Form: Powder, Granules, Beads, Slurry Application: Cosmetics, Electronics, Construction, Food & Beverage |
| Companies Covered | Covia Holdings LLC, Evonik Industries AG, Sibelco, Tokuyama Corporation, Wacker Chemie AG, The Quartz Corp, U.S. Silica Holdings, Inc., Heraeus Holding GmbH, Jiangsu Pacific Quartz Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Purity Silica Market Emerging Trajectories
Process intensification and regulatory tightening are reshaping competitive differentiation, with purification technology and carbon accounting emerging as primary battlegrounds.
Plasma-enhanced chemical vapor deposition for synthetic silica synthesis is integrating into optical fiber preform manufacturing, enabling impurity profiles below 10 parts per billion. Corning and Shin-Etsu are expanding reactor capacity at existing sites rather than greenfield development. This is integrating premium material supply directly into cable producer specifications, compressing spot market volumes for legacy natural quartz routes.
REACH authorization requirements for crystalline silica are tightening occupational exposure documentation across European electronics supply chains. ECHA's 2023-2025 substance evaluation roadmap prioritizes respirable silica in downstream semiconductor applications. German and Dutch compounders are accelerating synthetic fumed silica substitution to preempt workplace safety liabilities.
Long-term offtake contracting is displacing spot purchasing for crucible-grade material as solar wafer manufacturers secure volume commitments through 2028-2030. Tier-one photovoltaic producers in Southeast Asia are negotiating directly with Spruce Pine and Jiangsu refiners, bypassing traditional distributor networks. This concentration is most visible in Vietnam and Malaysia, where new cell and module capacity is clustering near port infrastructure.
High Purity Silica Market Segmentation
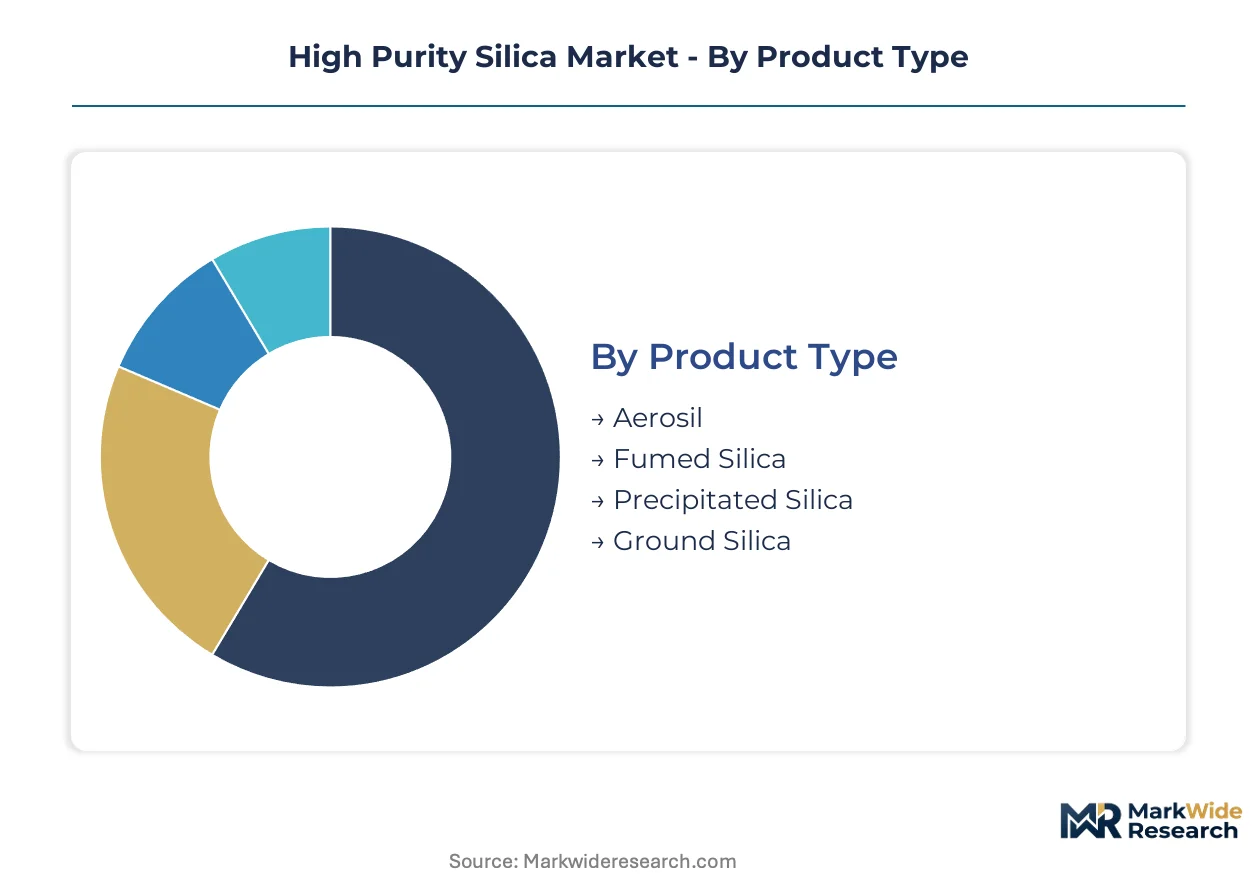
High purity silica refiners must align purification intensity with end-use impurity thresholds. Product type and grade specifications determine furnace investment, acid-leaching circuit design, and qualification timelines for semiconductor versus industrial customers.
Product Type:
Upgrade cycles for thermal treatment furnaces differ sharply across synthetic versus natural processing routes, driving divergent capital recovery timelines.
- Fumed Silica:Silicon tetrachloride hydrolysis in hydrogen-oxygen flames yields sub-50nm primary particles with surface areas exceeding 300 m²/g. Silicone elastomer formulators in Germany and Japan consume volumes for medical-grade tubing and high-consistency rubber reinforcement. REACH registration for synthetic intermediates extends European qualification cycles.
- Precipitated Silica:Sodium silicate acidification produces controlled pore structures for tire tread compounds and oral care abrasives. Automotive OEMs in South Korea specify precipitated grades for green tire formulations to meet rolling resistance targets under K-REACH.
- Aerosil:Evonik's trademarked pyrogenic silica dominates thixotropic applications in coatings and adhesives with hydrophobic surface treatments.
- Ground Silica:Mechanical milling of high-purity quartz serves foundry and construction applications where sub-ppm metal control is unnecessary.
Volume placements concentrate in Precipitated Silica; the faster expansion belongs to Fumed Silica.
Grade:
Customer certification requirements stratify pricing tiers across three- to four-order-of-magnitude impurity tolerance spreads.
- Electronic:Sub-10ppb alkali and transition metal specifications enable semiconductor wafer and crucible production. Jiangsu province's quartz processors and North Carolina's Spruce Pine operations supply ingot manufacturers pushing below 10nm nodes. China's NMPA tightened GB standards for domestic electronics-grade material.
- Medical:USP and ISO 10993 biocompatibility compliance governs implantable device and diagnostic applications. German compounders source medical grades for silicone prosthetics and drug delivery matrices.
- Pharmaceutical:ICH Q3D elemental impurity limits apply to excipient grades for oral solid dosage forms.
- Standard:Industrial coatings and sealants accept 50-500ppm impurity levels at commodity pricing.
Revenue concentration sits with Electronic grade; Pharmaceutical grade is climbing the fastest.
Form:
Handling economics and dust exposure regulations favor densified formats in high-volume industrial channels.
- Powder:Uncompacted material offers maximum surface area for catalytic and adsorption applications. OSHA and EPA crystalline silica permissible exposure limits drive substitution toward granulated alternatives in US manufacturing facilities.
- Granules:Spray-dried agglomerates reduce dust generation during pneumatic conveying. Food and beverage processors in the Netherlands specify granules for anti-caking applications under EFSA additive regulations.
- Beads:Spherical particles for chromatography and precision polishing command premium uniformity tolerances.
- Slurry:Pre-dispersed aqueous formulations eliminate on-site mixing for chemical mechanical planarization in semiconductor fabrication.
Shipment volumes favor Powder; regulatory pressure is accelerating Granule uptake.
Application:
End-use switching costs and qualification inertia protect incumbent suppliers in semiconductor and pharmaceutical channels.
- Electronics:Optical fiber preform manufacturing and semiconductor crucible growth consume ultra-high-purity material. Corning and Shin-Etsu integrate synthetic silica synthesis directly into cable specifications, compressing spot market volumes. Japan's METI revised JIS standards for photovoltaic ingot production.
- Cosmetics:Thixotropic control and sensory modification drive fumed silica demand in color cosmetics and sunscreens. French and Italian formulators specify hydrophobic grades for anhydrous formulations.
- Construction:High-performance concrete and engineered stone incorporate ground silica for rheology control and strength enhancement.
- Food & Beverage:Anti-caking and carrier applications for seasonings and powdered ingredients operate under FDA and EFSA food additive codes.
Electronics commands the steepest purity premiums; Cosmetics is expanding most quickly on medical-grade cross-selling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province's quartz processing corridor anchors global high purity silica refining, with Pacific Quartz and state-backed operators clustering capacity near Yangzhou and Donghai to serve semiconductor crucible manufacturers.
China
Photovoltaic ingot producers in Jiangsu are scaling semiconductor-grade silica procurement as PERC and TOPCon architectures proliferate. NMPA impurity thresholds for domestic electronics-grade material are tightening under dual carbon goals, creating premium tiers for sub-50ppm quartz. Donghai county hosts the country's densest concentration of high-purity crystal growth facilities.
United States
Spruce Pine operations in North Carolina supply Atlantic basin demand for ultra-high-purity natural quartz deposits. EPA crystalline silica permissible exposure limits are elevating purification capital requirements for domestic refiners. The Carolina mining corridor concentrates mining rights among legacy operators with established acid-leaching infrastructure.
Germany
Silicone elastomer formulators consume fumed silica volumes for medical-grade tubing and high-consistency rubber reinforcement. REACH registration requirements for synthetic intermediates extend qualification cycles for European market entry. The Ruhr industrial region hosts compounders accelerating synthetic substitution to preempt workplace safety liabilities.
Japan
Optical fiber preform manufacturers integrate synthetic silica synthesis directly into cable specifications, compressing spot market volumes. METI revised JIS standards for photovoltaic ingot production, tightening domestic purity benchmarks. Nagoya-based cable producers are expanding reactor capacity at existing sites rather than pursuing greenfield development.
India
PLI scheme incentives for semiconductor fabs are creating captive demand for imported crucible-grade material as domestic refining capacity remains nascent. The national pharmaceutical regulator is aligning with ICH Q3D elemental impurity limits for excipient applications. Gujarat's emerging electronics manufacturing cluster is negotiating long-term offtake contracts directly with Spruce Pine and Jiangsu refiners.
High Purity Silica Market Vendor Landscape
The competitive structure tilts toward integrated refiners with captive deposit access and synthetic synthesis capabilities. State-backed operators and legacy mining concerns control ultra-high-purity natural quartz formations, while chemical conglomerates dominate fumed and precipitated grades through silicon tetrachloride hydrolysis. Three archetypes prevail: deposit-integrated miners with acid-leaching infrastructure, synthetic silica specialists with CVD reactor networks, and diversified chemical majors with cross-selling reach into medical and cosmetic channels. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with long-term offtake contracting displacing spot purchasing in photovoltaic channels.
Among Asia-Pacific-based refiners, Jiangsu Pacific Quartz Co., Ltd. exemplifies the deposit-integrated archetype with its Yangzhou corridor concentration, while Tokuyama Corporation occupies a position within the synthetic silica tier serving optical fiber specifications. Evonik Industries AG represents the diversified chemical major model, leveraging its fumed silica R&D pipeline across medical and cosmetic grade applications. These three anchors illustrate how purification technology depth and regulatory compliance breadth determine competitive positioning across electronic, pharmaceutical, and industrial end-uses.
| Leading Market Players |
|---|
| Covia Holdings LLC |
| Evonik Industries AG |
| Sibelco |
| Tokuyama Corporation |
| Wacker Chemie AG |
| The Quartz Corp |
| U.S. Silica Holdings, Inc. |
| Heraeus Holding GmbH |
| Jiangsu Pacific Quartz Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Semiconductor OEM procurement concentration around crucible-grade specifications anchors value-based pricing tied to ingot yield performance rather than tonnage metrics. Long-term offtake contracting with Jiangsu and Spruce Pine refiners compresses spot market liquidity while elevating purity premiums for sub-10ppb material.
Pricing Analysis
Yield-guarantee contracts with photovoltaic ingot manufacturers establish the dominant value-based pricing anchor, with crucible performance warranties commanding substantial premiums over standard electronics-grade material. Three-tier pricing structure across electronic, medical, and industrial grades reflects certification intensity and qualification timeline differentials. Cost compression in precipitated silica runs through automotive tire compounder negotiations, while fumed silica maintains pricing resilience through medical-grade cross-selling. Standard industrial grades exhibit highest buyer price sensitivity; semiconductor crucible specifications show lowest elasticity due to 18-24 month supplier qualification cycles.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Long Beach handle bulk fumed and precipitated silica consolidation before downstream formulation. Ultra-high-purity natural quartz supply concentrates in the United States, China, and Norway, while synthetic silica production clusters in Germany, Japan, and the United States. Refining capacity draws from silicon tetrachloride feedstocks, high-purity natural quartz deposits, and hydrogen-oxygen thermal infrastructure. Single-source vulnerability around Spruce Pine's ultra-high-purity deposits exposes Atlantic basin semiconductor supply to geological concentration risk. Distribution runs through direct mill-to-fab relationships for crucible-grade material, bypassing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where REACH authorization requirements and China's NMPA impurity thresholds erect regulatory moats protecting capital-intensive incumbents with certified acid-leaching infrastructure.
For Market Incumbents: Hedge against synthetic route substitution by securing long-term offtake commitments with Southeast Asian photovoltaic manufacturers before plasma-enhanced CVD capacity expands. Accelerate thermal furnace upgrades in Jiangsu corridor facilities to preempt NMPA's tightening GB standards for domestic electronics-grade material. Backward integration into captive quartz deposits in North Carolina and Norway reduces feedstock concentration exposure. For New Entrants and Emerging Players: Indian pharmaceutical compounders represent the most penetrable buyer archetype as domestic refining capacity remains nascent despite PLI scheme semiconductor fab incentives. Target Gujarat's emerging electronics manufacturing cluster with USP-grade precipitated silica for excipient applications under aligned ICH Q3D elemental impurity limits. Pursue tolling arrangements with established European refiners to circumvent REACH registration timelines for synthetic intermediates. For Investors and Strategic Acquirers: Distressed-cycle entries favor deposit-integrated mid-cap refiners with underutilized acid-leaching capacity in North Carolina's Carolina mining corridor. Five-to-ten year viability hinges on purification technology depth rather than scale economies alone. Monitor METI's JIS specification revisions for photovoltaic ingot production as inflection signal for premium tier demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement | Direct mill-to-fab contracts with Vietnam and Malaysia cell manufacturers displace distributor networks. |
| Backward Integration | Captive quartz deposit control in Spruce Pine and Donghai county reduces geological concentration risk. |
| Capacity Expansion | Thermal furnace upgrades in Jiangsu corridor address NMPA's tightening sub-50ppm impurity thresholds. |
| Joint Venture | Plasma-enhanced CVD partnerships with Nagoya cable producers compress spot market for natural quartz routes. |
| Green Manufacturing Transition | Low-carbon purification processes qualify for EU Green Deal preferential procurement in European electronics chains. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with quartz processing plant managers, semiconductor procurement leads, silicone elastomer formulators, photovoltaic ingot manufacturers, and pharmaceutical excipient specialists. Bottom-up volume modeling triangulated against top-down industry association aggregates from ACC, Cefic, and China Non-Metallic Minerals Industry Association. SEC 10-K disclosures, ECHA registration databases, and METI production statistics provided secondary validation layers.
Granularity-level modeling distinguished synthetic versus natural processing routes, electronic-medical-pharmaceutical-industrial grade tiers, and powder-granule-bead-slurry form factors across the projection horizon. CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Industry-specific inputs included photovoltaic capacity expansion pipelines, semiconductor node migration roadmaps, and silicone elastomer formulation trends.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA regulatory acceleration, REACH authorization scope expansion, and photovoltaic technology substitution beyond PERC and TOPCon architectures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
High-K Dielectric Material Market
High-Value Chemicals
Hydroxynitrile Lyase Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
Hydrogen Isotope Market
High-Value Chemicals
High-Purity Boehmite Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
High Molecular Ammonium Polyphosphate Market
High-Value Chemicals
Alpha Hydroxy Acid Market
High-Value Chemicals
Global Hydrofluoric Acid Market
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
Hydroxylamine Sulfate Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Global High Purity AHCL Market
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market