
 Global High Purity Oxygen Market | 2026-2036
Global High Purity Oxygen Market Size, Share, and Industry Trends Forecast 2026-2036
Global High Purity Oxygen Market Foresight
Long-term gas supply contracts with embedded maintenance and remote monitoring services is broadening what industrial buyers purchase beyond molecule delivery. Linde plc leverages its on-site generation infrastructure to anchor multi-decade relationships with semiconductor fabs. Air Liquide sustains competitive differentiation through proprietary purification technologies that guarantee parts-per-billion impurity levels. Nippon Sanso Holdings Corporation dominates cryogenic distribution networks across East Asian port cities.
High purity oxygen denotes gaseous or liquid oxygen refined to impurity thresholds below ten parts per million, typically produced via cryogenic air separation or pressure swing adsorption and certified for processes where contaminant sensitivity threatens yield or safety. Compressed gas formats lead current revenue contribution due to entrenched infrastructure in metal fabrication and welding, while liquid oxygen volumes expand fastest among healthcare providers retrofitting centralized hospital supply systems. Manufacturing plants represent the deepest margin pool because bulk contracts integrate engineering services and captive on-site generation assets that lock in switching costs.
FDA purity standards for medical oxygen and EPA emissions limits on combustion processes in the United States, coupled with REACH chemical safety classifications and EU Green Deal industrial decarbonization mandates in Europe, collectively elevate compliance costs for new entrants while reinforcing incumbent certification advantages. China's MEE enforces progressively stricter GB standards on steel sector emissions that favor oxygen-enriched production methods. Stakeholders must monitor divergence between medical-grade and industrial-grade certification requirements as regional regulators tighten specifications asymmetrically.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are consolidating oxygen supply relationships around on-site generation assets that embed cryogenic infrastructure and remote monitoring services, compressing procurement cycles and locking out spot-market alternatives.
Growth Catalysts
- Advanced lithography requirements:Sub-3nm chip fabrication in Hsinchu and Pyeongtaek demands parts-per-billion oxygen purity that only cryogenic distillation achieves.
- China's GB 31574-2015 steel emission standards:MEE enforcement redirects electric arc furnace operators toward oxygen-enriched combustion to meet tightening particulate limits.
- Centralized hospital supply retrofitting:Liquid oxygen bulk tanks with vaporizer systems replace cylinder deliveries across tertiary care networks in Germany and Japan.
Market Restraints
- Cryogenic energy intensity:Air separation units consume 0.4-0.5 kWh per cubic meter, exposing margins to European natural gas price volatility.
- East Asian supply concentration:Three-quarters of ultra-high purity capacity clusters within 500 kilometers of Taipei, Kaohsiung, and Seoul, creating geographic risk.
- Pressure swing adsorption ceiling:PSA systems cannot reliably achieve below 10 ppm total impurities, blocking adoption in advanced semiconductor nodes.
Strategic Opportunities
- India's PLI scheme for specialty chemicals:Bulk oxygen contracts for agrochemical and pharmaceutical intermediates production remain underdeveloped outside Maharashtra and Gujarat.
- Green hydrogen electrolysis coupling:Oxygen byproduct streams from PEM electrolyzers in Denmark and the Netherlands offer captive supply for adjacent industrial clusters.
- EU Green Deal industrial decarbonization:Oxygen-enhanced combustion mandates in cement and glass sectors create new demand pools beyond metals.
Industry Challenges
- Cryogenic technician scarcity:Pipeline maintenance and cold-box overhaul require specialized welding certifications that training programs in Vietnam and Indonesia cannot yet supply.
- Dual-grade certification complexity:Diverging FDA medical oxygen standards and EPA industrial emission requirements force redundant testing protocols for multi-use production assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global High Purity Oxygen Market |
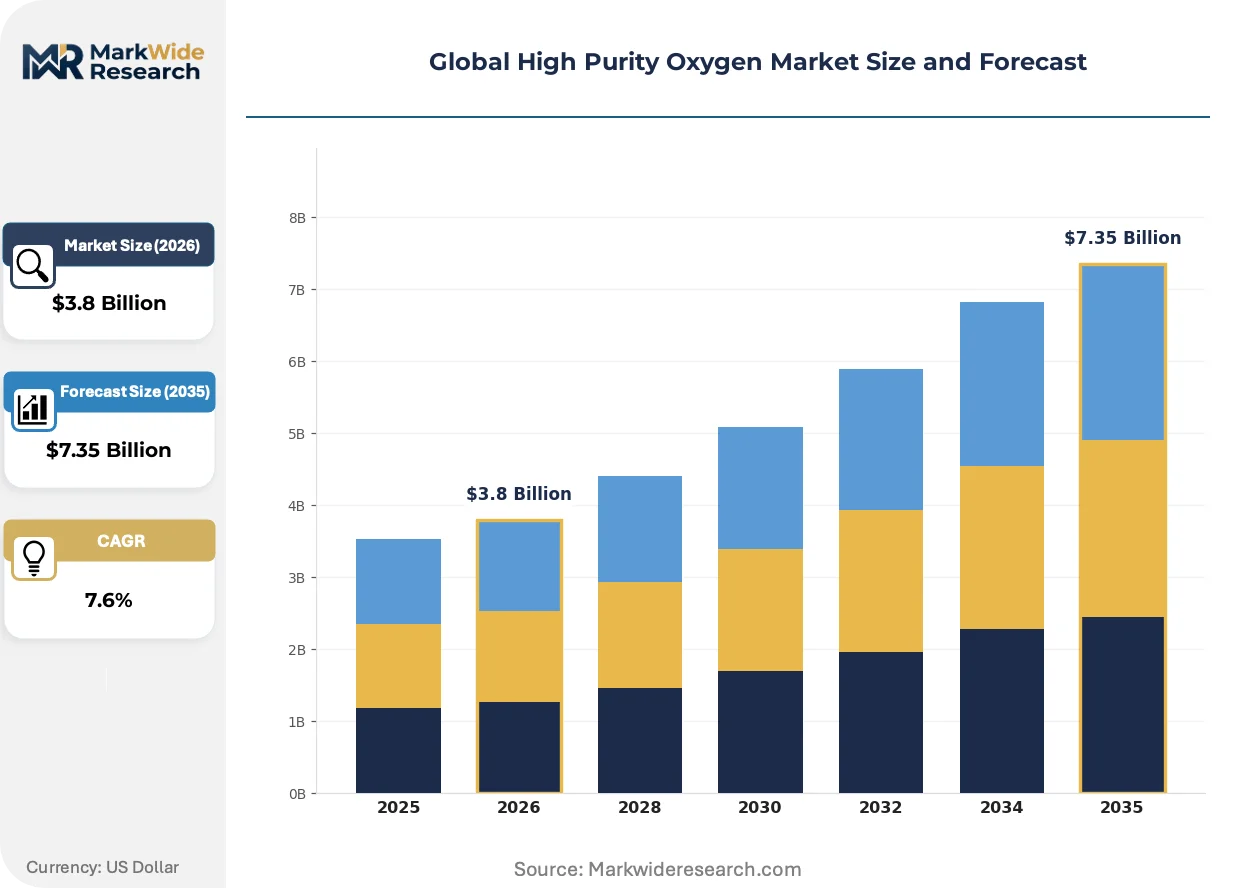
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressed Gas, Liquid Oxygen, Oxygen Concentrators, Oxygen Cylinders Application: Industrial Use, Medical Use, Aerospace, Chemical Processing End User: Healthcare Providers, Manufacturing Plants, Research Laboratories, Oil & Gas Companies Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesale |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Nippon Sanso Holdings Corporation, Messer Group GmbH, Taiyo Nippon Sanso Corporation, Air Water Inc., Matheson Tri-Gas, Inc., SOL Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global High Purity Oxygen Market Shifts & Advancements
Digital twin modeling of air separation performance and predictive maintenance algorithms are compressing unplanned downtime windows while enabling remote certification audits that reduce regulatory compliance costs.
Membrane-assisted cryogenic hybrid systems is unifying the energy efficiency of selective permeation with the purity thresholds of low-temperature distillation. Steelmakers in Duisburg and Port Talbot are piloting these configurations for oxygen-enriched blast furnace injection. The technology is unifying previously separate equipment footprints into single-train installations that reduce capital intensity for mid-scale consumers.
REACH chemical safety classifications and EU F-Gas Regulation phase-down schedules are tightening refrigerant specifications for oxygen liquefaction plants. Industrial gas operators in Antwerp and Rotterdam are retrofitting cold boxes with alternative cooling cycles. Semiconductor fabs in Leuven and Dresden now require documentation of fluorinated gas containment in supplier qualification protocols.
Hospital procurement departments are consolidating oxygen supply contracts under five-year bundled agreements that wrap molecule delivery, tank maintenance, and emergency backup into single-source arrangements. This model displaces fragmented cylinder rental relationships across National Health Service trusts in England and university hospital networks in Catalonia. The shift concentrates purchasing power with distributors operating captive engineering service teams.
Global High Purity Oxygen Market Segmentation
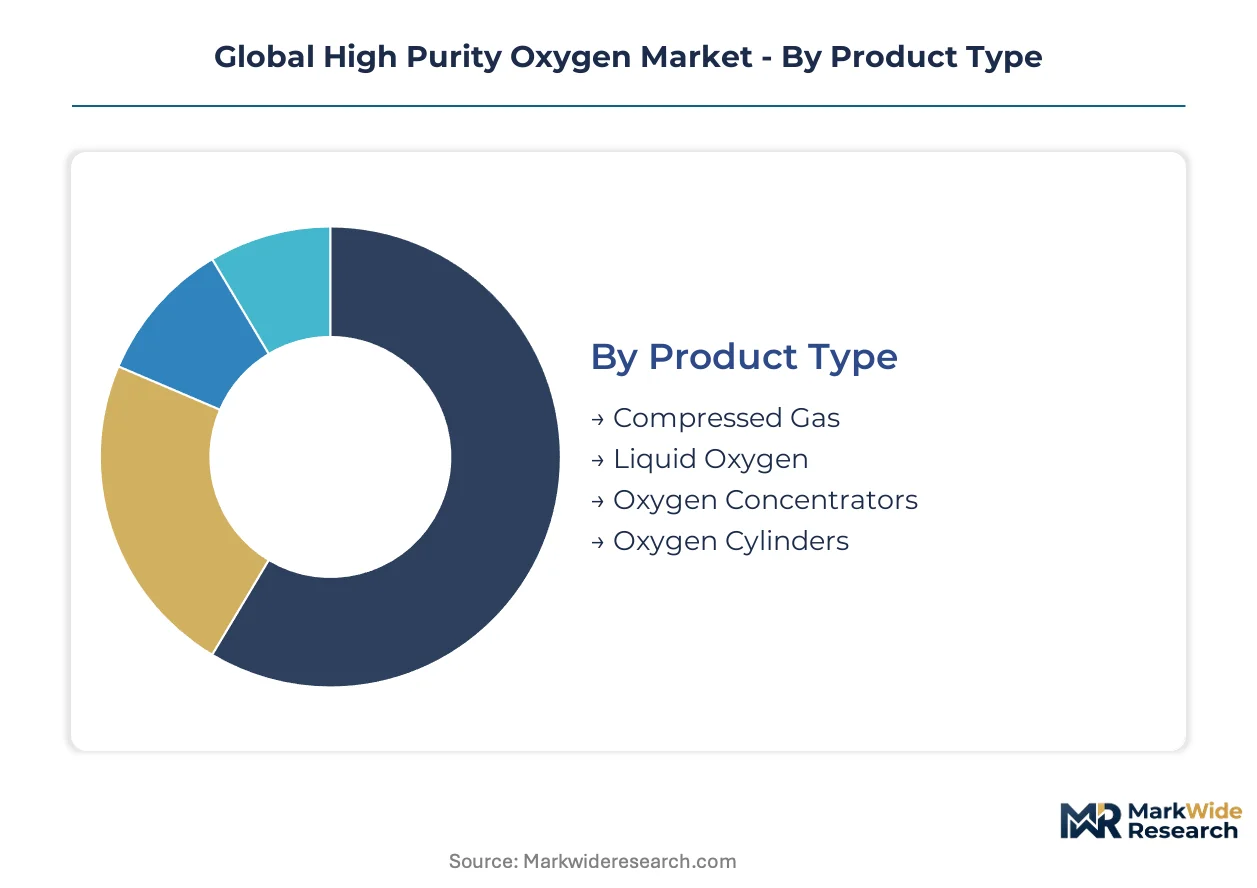
High purity oxygen markets fragment sharply across delivery format and buyer sophistication. Semiconductor fabs in Hsinchu demand parts-per-billion purity that compressed gas cannot achieve, while hospital networks in Osaka prioritize liquid bulk for centralized supply economics. Each segment carries distinct certification burdens and switching costs that reshape competitive positioning.
Product Type:
Cost tier separates spot buyers from integrated supply relationships.
- Liquid Oxygen:Cryogenic storage at minus 183 degrees Celsius enables bulk delivery to semiconductor fabrication plants in Pyeongtaek and hospital networks in Düsseldorf. Taiwan's TSMC fabs consume thousand-ton annual volumes under twenty-year on-site generation contracts that embed Linde and Air Liquide infrastructure.
- Compressed Gas:High-pressure cylinder and tube trailer formats dominate metal fabrication and welding applications where ten parts per million purity suffices. German automotive suppliers in Stuttgart and Wolfsburg maintain fragmented procurement across multiple regional distributors.
- Oxygen Cylinders:Portable aluminum and steel vessels serve emergency medical response and remote construction sites in Alberta and Queensland.
- Oxygen Concentrators:Pressure swing adsorption units generate 90-95% purity for home healthcare and veterinary clinics where medical-grade certification is not required.
Volume sits with compressed gas; growth tilts toward liquid oxygen.
Application:
Regulatory stringency fragments demand across EPA emission limits and FDA medical standards.
- Industrial Use:Steelmakers in Duisburg and Port Talbot inject oxygen-enriched blast furnace streams to meet EU Green Deal decarbonization mandates. China's MEE enforcement of GB 31574-2015 redirects electric arc furnace operators toward high-purity combustion methods that cut particulate emissions.
- Medical Use:FDA 21 CFR 210-211 cGMP compliance and EMA medical device regulations govern ventilator and anesthesia supply chains. Japan's university hospital networks in Tokyo and Osaka are retrofitting liquid bulk tanks with vaporizer systems that displace cylinder rental fragmentation.
- Chemical Processing:Oxidation reactions for specialty chemical intermediates in Maharashtra and Gujarat absorb bulk oxygen under India's PLI scheme incentives.
- Aerospace:Launch vehicle propulsion and life support systems in Florida and French Guiana require MIL-STD-1246 cleanliness specifications.
Revenue concentrates in industrial contracts; steepest expansion trajectory emerges in medical applications.
End User:
Volume scale and technical capability determine captive generation versus merchant supply.
- Manufacturing Plants:Semiconductor fabs in Taiwan and South Korea anchor multi-decade cryogenic infrastructure investments. On-site air separation units at Samsung's Pyeongtaek complex and TSMC's Hsinchu facilities eliminate logistics costs while locking in parts-per-billion purity guarantees.
- Healthcare Providers:NHS trusts in England and Catalonia's hospital networks consolidate under five-year bundled contracts wrapping molecule delivery, tank maintenance, and emergency backup into single-source arrangements.
- Research Laboratories:CERN in Geneva and RIKEN in Saitama demand ultra-high purity for particle detection and materials science experiments.
- Oil & Gas Companies:Enhanced oil recovery operations in the Permian Basin and North Sea platforms use oxygen for miscible flooding and gasification processes.
Margin depth favors manufacturing plants; procurement consolidation accelerates among healthcare providers.
Distribution Channel:
Geographic density and customer technical sophistication shape route-to-market economics.
- Direct Sales:Linde and Air Liquide deploy captive engineering teams for semiconductor fab and steel mill accounts in Kaohsiung and Seoul. These relationships embed remote monitoring, predictive maintenance, and regulatory audit support that distributors cannot replicate.
- Distributors:Regional gas specialists in Antwerp and Rotterdam serve mid-scale chemical processors and metal fabricators with cylinder exchange programs and emergency response capabilities.
- Wholesale:Bulk liquid transfers between production hubs and secondary packaging facilities optimize logistics across Nippon Sanso's East Asian port network.
- Online Retail:E-procurement platforms supply concentrators and small cylinders to home healthcare agencies and veterinary clinics in dispersed geographies.
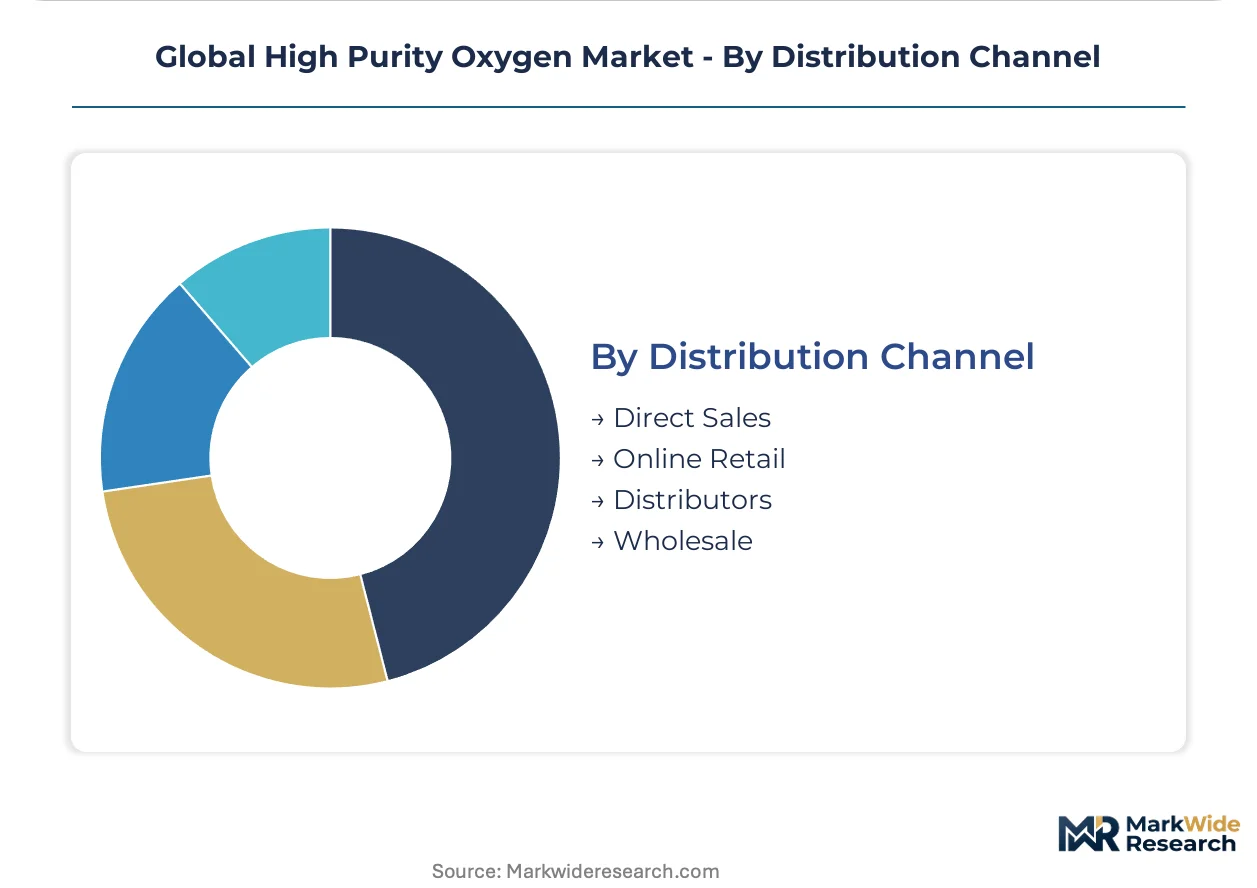
Revenue gravity centers on direct sales; digital channels gain share fastest in concentrator segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in East Asian manufacturing corridors while consumption spreads across semiconductor fabrication, steel decarbonization, and hospital supply networks. Cryogenic air separation capacity clusters near Taipei, Seoul, and Shanghai, creating supply-side density that shapes logistics economics. Demand fragmentation across medical, industrial, and electronics applications generates divergent regional growth trajectories.
China
Steelmakers in Tangshan and Baoshan redirect toward electric arc furnace methods as MEE tightens GB 31574-2015 enforcement on particulate emissions. The dual carbon goals framework accelerates oxygen-enriched combustion adoption across Hebei and Jiangsu provinces. Yangtze River Delta chemical processors absorb expanding merchant oxygen volumes under specialty chemicals expansion mandates.
United States
FDA 21 CFR 210-211 cGMP compliance shapes ventilator and anesthesia supply chains across Cleveland and Boston hospital networks. EPA emissions limits on combustion processes elevate oxygen demand from Texas and Louisiana petrochemical corridors. Permian Basin enhanced oil recovery operations sustain bulk oxygen offtake despite drilling cycle volatility.
Germany
EU Green Deal industrial decarbonization mandates drive oxygen-enhanced combustion pilots in Duisburg steelworks and Port Talbot adjacent facilities. REACH chemical safety classifications tighten refrigerant specifications for liquefaction plants serving Antwerp and Rotterdam. NHS trusts in England consolidate under bundled contracts that German distributors seek to replicate across Catalonia and Lombardy.
South Korea
Samsung's Pyeongtaek complex and SK Hynix fabs anchor multi-decade on-site generation contracts with cryogenic infrastructure embedding. MFDS medical device regulations govern hospital supply standardization across Seoul Capital Area networks. Busan-Ulsan chemical processors expand oxidation reaction capacity under specialty chemicals export incentives.
Japan
Tokyo and Osaka university hospital networks retrofit liquid bulk tanks with vaporizer systems that displace fragmented cylinder logistics. METI industrial efficiency standards promote oxygen-enriched combustion in Kyushu steel and cement operations. RIKEN Saitama and KEK Tsukuba research facilities sustain ultra-high purity demand for particle physics and materials science applications.
Global High Purity Oxygen Market Competitive Landscape
Top-tier vendors anchor integrated supply relationships, while regional distributors serve fragmented cylinder exchange markets. The vendor base stratifies across cryogenic infrastructure owners, purification technology specialists, and logistics-focused distributors. Three archetypes dominate: captive on-site generators, merchant liquid suppliers, and packaged gas distributors. Consolidation pressure operates through multi-decade fab contracts and hospital bundling, while capacity expansion concentrates in East Asian port corridors.
Within the integrated industrial gas tier, Linde plc, Air Liquide, and Nippon Sanso Holdings Corporation occupy positions that exemplify divergent geographic anchoring and infrastructure ownership models. Linde represents the on-site generation archetype with embedded cryogenic assets. Air Liquide sits within the purification technology specialization. Nippon Sanso Holdings anchors East Asian distribution density. These three structures illustrate how competitive positioning crystallizes around captive infrastructure, proprietary process know-how, or network logistics rather than interchangeable molecule supply.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Nippon Sanso Holdings Corporation |
| Messer Group GmbH |
| Taiyo Nippon Sanso Corporation |
| Air Water Inc. |
| Matheson Tri-Gas, Inc. |
| SOL Spa |
| Others |
Supply & Pricing Matrix
Cryogenic technician scarcity in Vietnam and Indonesia widens labor-cost differentials between East Asian port cities and emerging Southeast Asian hubs, compressing pricing spreads between premium on-site generation contracts and standard merchant supply arrangements. Steelmakers in Duisburg absorb higher service premiums for embedded maintenance, while chemical processors in Maharashtra negotiate spot-market alternatives.
Pricing Analysis
Margin tightening in compressed gas tiers reflects cylinder exchange commoditization across German automotive supplier clusters. Three-tier pricing structure across parts-per-billion purity, medical-grade certification, and industrial-standard tiers separates semiconductor fabs in Hsinchu from hospital networks in Osaka and metal fabricators in Stuttgart. Cost-down pressure on standard-grade deliveries accelerates because pressure swing adsorption systems cap purity ceilings at ten parts per million. Healthcare providers consolidating under bundled contracts show lowest price sensitivity; spot-market cylinder buyers exhibit highest.
Supply Chain Analysis
Regional distribution centers in Kaohsiung, Busan, and Rotterdam anchor hub-and-spoke patterns that feed secondary packaging facilities across East Asian port corridors. Cryogenic air separation capacity clusters in Taiwan, South Korea, and China, with merchant liquid transfers optimizing logistics across Nippon Sanso's network. Raw material draws from industrial air intake, specialized refrigerants for liquefaction cycles, and high-grade aluminum for cryogenic storage vessels. Single-source vulnerability concentrates in East Asian ultra-high purity capacity within five hundred kilometers of Taipei and Seoul. Distribution runs through direct sales for semiconductor fabs, regional distributors for chemical processors, and wholesale bulk transfers between production hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic infrastructure ownership scarcity props pricing power for incumbent industrial gas operators, constraining new entrant expansion across advanced lithography supply relationships.
For Market Incumbents: Deploy predictive maintenance algorithms to compress unplanned downtime windows at TSMC and Samsung on-site generation assets. Deepen certification investments for dual-grade FDA and EPA compliance to block emerging regional distributors from multi-use production contracts. Pressure from membrane-assisted cryogenic hybrid pilot programs in Duisburg and Port Talbot threatens traditional air separation margins. For New Entrants and Emerging Players: EU Green Deal industrial decarbonization mandates in cement and glass sectors open a window for oxygen-enhanced combustion specialists without legacy steel-sector entrenchment. India's PLI scheme for specialty chemicals in Maharashtra and Gujarat offers the most penetrable geography for bulk oxygen contracts outside East Asian manufacturing clusters. Pursue agrochemical intermediate producers with project-based engineering service bundling rather than molecule-only spot sales. For Investors and Strategic Acquirers: Re-rating potential sits with cryogenic distribution network owners given East Asian semiconductor capacity expansion catalysts. Five-to-ten year viability favors operators with captive port infrastructure and remote monitoring capabilities over regional cylinder exchange specialists. Watch for MEE enforcement intensity on GB 31574-2015 steel emission standards as inflection indicator for oxygen-enriched combustion demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| On-Site Generation Infrastructure Expansion | Twenty-year fab contracts in Hsinchu and Pyeongtaek lock out spot-market alternatives for semiconductor lithography supply. |
| Membrane-Assisted Cryogenic Hybrid Deployment | Single-train installations in Duisburg reduce capital intensity for mid-scale steelmaker oxygen-enriched blast furnace injection. |
| Dual-Grade Certification Investment | Simultaneous FDA medical oxygen and EPA industrial compliance blocks redundant testing protocols for multi-use production assets. |
| Centralized Hospital Supply Retrofitting | Liquid bulk tanks with vaporizer systems displace fragmented cylinder logistics across NHS trusts and Catalonia networks. |
| Green Hydrogen Electrolysis Coupling | Oxygen byproduct streams from PEM electrolyzers in Denmark offer captive supply for adjacent industrial chemical clusters. |
Research Methodology
Document review covered customs and trade data, industrial gas operator SEC filings, and MEE regulatory enforcement records, complemented by interviews with cryogenic plant managers, semiconductor fab procurement leads, hospital supply chain directors, and steel sector technical R&D heads. Secondary validation drew from EU Green Deal implementation reports, FDA 21 CFR guidance documents, and REACH chemical safety classifications. Bottom-up volume modeling across delivery formats and applications triangulated against top-down macroeconomic indicators.
Market size outputs across the analysis window reflect segmentation by purity grade tier, end-use industry, and captive versus merchant supply mode. CAGRs were derived from elasticity modeling against semiconductor fabrication capacity expansion, steel sector emission standard enforcement trajectories, and healthcare infrastructure investment cycles. Forecast inputs incorporated cryogenic energy intensity exposure to European natural gas price volatility and pressure swing adsorption purity ceiling constraints.
Caveats apply where MEE enforcement intensity, East Asian geographic concentration risk, or cryogenic technician training program expansion could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Purity Lignin Market
High-Value Chemicals
High Purity MTBE Market
High-Value Chemicals
L-Lysine Hydrochloride (HCL) Market
High-Value Chemicals
Ammonium Metavanadate Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
High-Heat Melamine Foam Market
High-Value Chemicals
Hydroxyethyl Urea Market
High-Value Chemicals
Ultra-High-Purity Anhydrous Hydrogen Chloride (Hcl) Gas Market
High-Value Chemicals
Global High Dispersible Silica Market
High-Value Chemicals
Barium Hydroxide Monohydrate Market
High-Value Chemicals
Global High Temperature Grease Market
High-Value Chemicals
High-Temperature Epoxy Market
High-Value Chemicals
High-Purity Hydrogen Fluoride Market
High-Value Chemicals
High Purity Silica Market
High-Value Chemicals
High-Silica Zeolite Market
High-Value Chemicals
Hydroxylamine Market