
 Ultra-High Purity Hydrofluoric Acid Market | 2026-2036
Ultra-High Purity Hydrofluoric Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra-High Purity Hydrofluoric Acid Market Analytics
Semiconductor companies is reorganizing procurement priorities as logic and memory fabs scale sub-7nm production. Stella Chemifa Corporation leverages captive purification technology to serve Japanese chipmakers with consistent ppb-trace specifications. Honeywell International Inc. anchors North American supply through integrated fluorine chemistry operations. Solvay SA differentiates via European semiconductor-grade certification and REACH-compliant logistics networks.
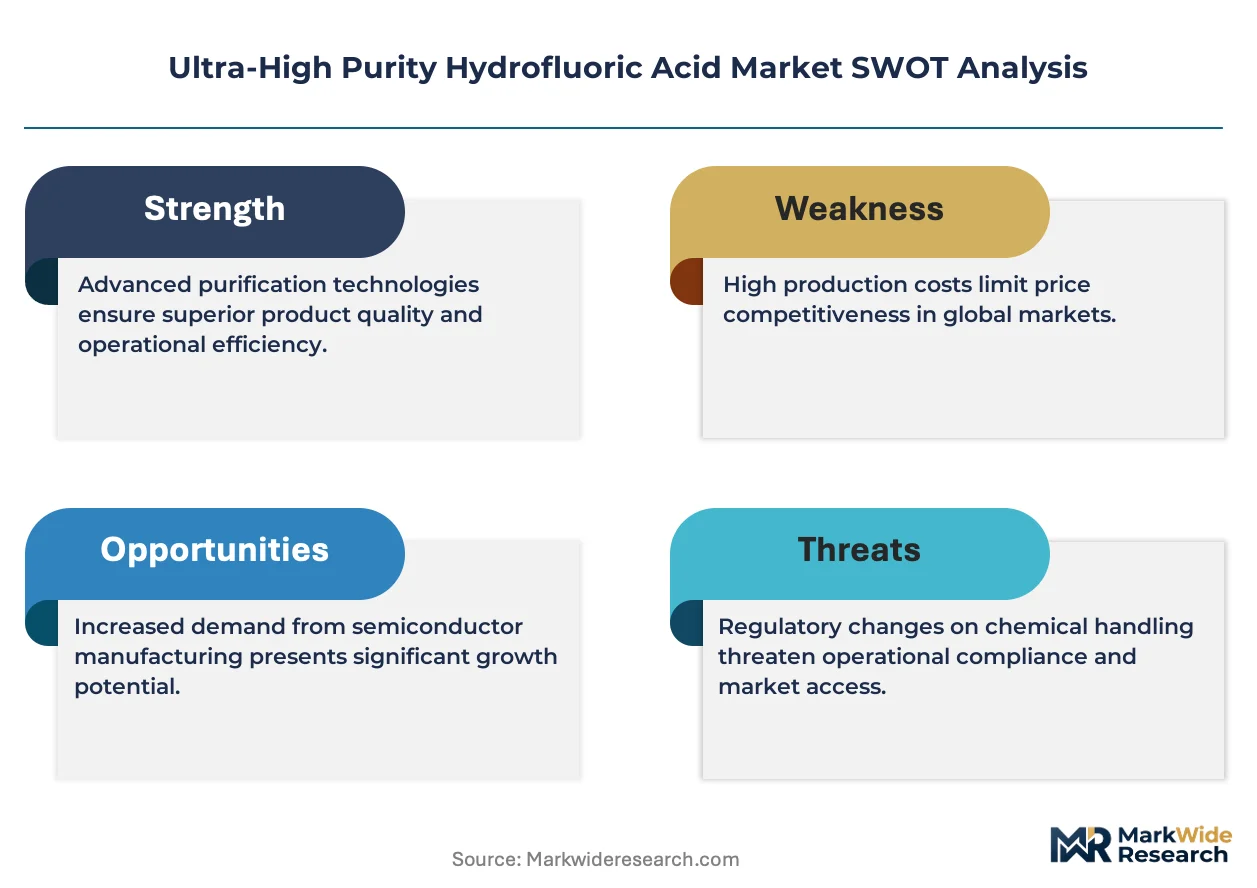
Ultra-high purity hydrofluoric acid denotes HF refined to sub-ppb metallic impurity levels, typically exceeding SEMI Grade 5 standards with particle counts below 100 per liter for semiconductor wafer etching and cleaning. The product serves as an indispensable reagent for silicon oxide removal and surface conditioning in electronics fabrication. Semiconductor grade material commands the dominant value share as foundries enforce ever-tighter contamination thresholds at advanced nodes. Electronic grade applications in display panel manufacturing represent the fastest-expanding consumption pool. Industrial grade segments face margin compression from commoditized supply and environmental handling surcharges.
Japan's METI enforces fluorochemical emission caps that elevate compliance investments for domestic producers. China's MEE implements GB standards for hazardous chemical storage that restrict inland distribution of UHP-HF. The EU F-Gas Regulation phases down hydrofluorocarbon production, indirectly tightening precursor acid availability for European semiconductor clusters. Stakeholders must monitor regulatory divergence across Japan, China, and the EU to anticipate supply chain reconfigurations and qualification timeline extensions.
Market Dynamics
Logic foundries below 5nm nodes now consume UHP-HF at triple the volume-per-wafer of mature processes, forcing purification suppliers to expand sub-ppb capacity ahead of demand curves.
Growth Catalysts
- Sub-7nm Etching Intensity:Advanced node silicon oxide removal requires multiple cleaning cycles per wafer, multiplying UHP-HF throughput per thousand wafer starts at TSMC and Samsung fabs.
- China's Dual Carbon Mandate:Beijing's emission caps on fluorochemical production are accelerating domestic substitution of imported acid with locally refined ultra-high purity grades.
- GB Standard Harmonization:China's MEE hazardous chemical storage rules now align with SEMI handling protocols, reducing qualification friction for imported UHP-HF into Yangtze River Delta clusters.
Market Restraints
- Fluorspar Supply Concentration:Acid-grade fluorspar mining concentrates in Mexico and China, exposing purification plants to export quota volatility and ocean freight surcharges.
- EU F-Gas Phase-Down:The European regulation tightening hydrofluorocarbon production indirectly constrains precursor acid availability for semiconductor clusters in Dresden and Leuven.
- Caustic Soda Co-Product Dependency:HF production via fluorspar-sulfuric acid reaction generates calcium sulfate waste requiring landfill permits that METI caps restrict in Japan.
Strategic Opportunities
- India's Semiconductor PLI Scheme:New Delhi's production-linked incentives for display and chip fabrication are creating first-mover advantage for UHP-HF suppliers establishing Gujarat corridor logistics.
- On-Site Generation Systems:Membrane-based anhydrous HF purification units at fab perimeters are eliminating bulk transport contamination risks and reducing tanker turnaround times.
- Photovoltaic Texturing:PERC and TOPCon cell manufacturing in Southeast Asia is adopting semiconductor-grade HF for silicon surface conditioning, opening non-chip demand pools.
Industry Challenges
- SEMI Grade 6 Qualification Timelines:Sub-ppt metallic impurity certification requires 18-24 month validation cycles at leading foundries, locking working capital in inventory before revenue recognition.
- Fluorine Chemistry Talent Scarcity:Universities in Japan and Germany graduate fewer inorganic chemists specializing in ultra-trace analysis, forcing producers to poach from analytical instrument manufacturers.
- Legacy Bulk Handling Infrastructure:Older fabs in Hsinchu and Gumi lack double-contained piping systems for UHP-HF, requiring costly retrofitting to receive next-generation material specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra-High Purity Hydrofluoric Acid Market |
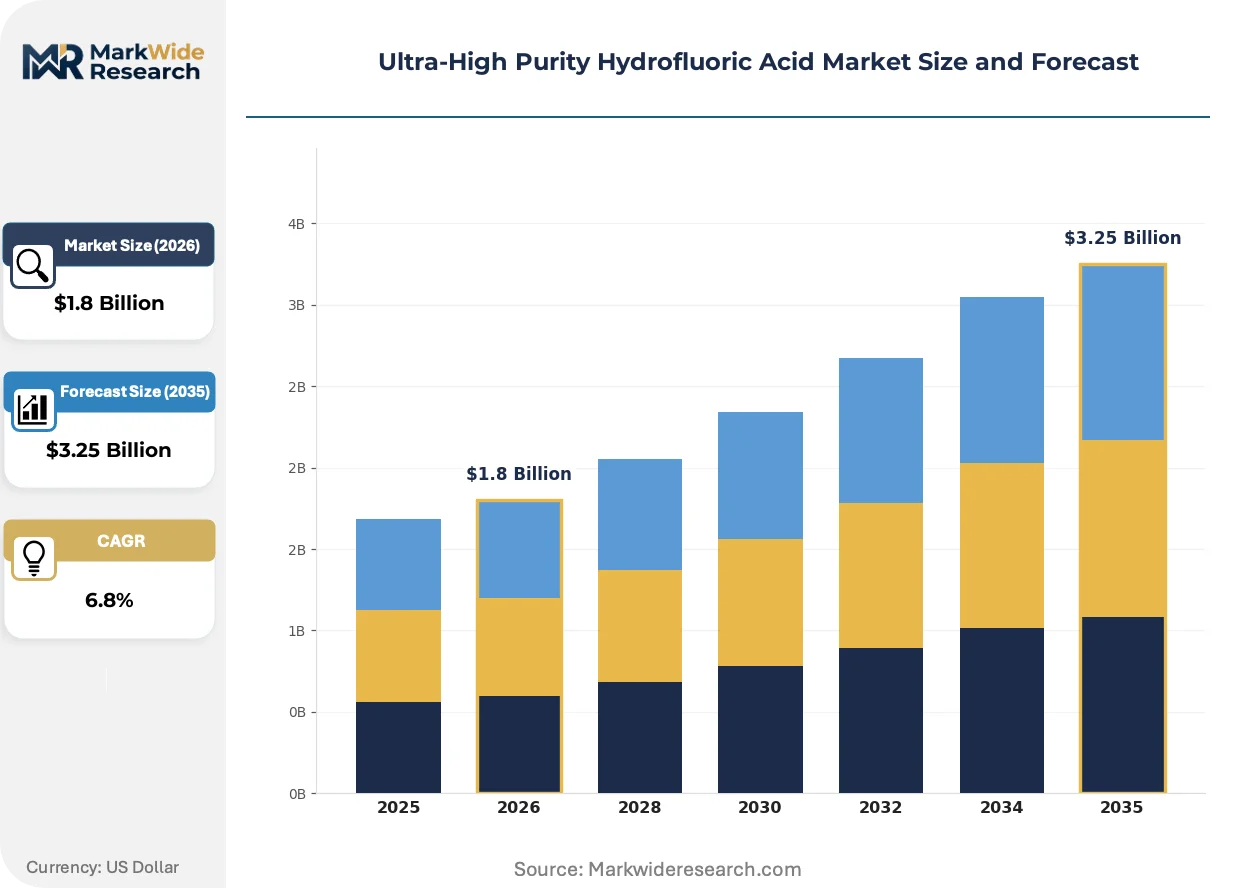
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Semiconductor Grade, Electronic Grade, Industrial Grade, Reagent Grade Application: Electronics Manufacturing, Metal Etching, Chemical Synthesis, Glass Treatment End User: Semiconductor Companies, Laboratories, Chemical Manufacturers, Glass Producers Packaging Type: Drums, Cylinders, IBCs, Totes |
| Companies Covered | Morita Chemical Industries Co., Ltd., Zhejiang Kaiheng Electronic Materials Co., Ltd., Stella Chemifa Corporation, Shaowu Huaxin Chemical Industry Co., Ltd., Do-Fluoride Chemicals, Honeywell International Inc., Sunlit Chemical, Jiangyin Jianghua Microelectronics Materials Co., Ltd., Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra-High Purity Hydrofluoric Acid Market Evolving Landscape
Point-of-use purification and closed-loop recycling systems are displacing centralized bulk supply models, while regulatory fragmentation across East Asian jurisdictions forces multi-standard compliance architectures.
Membrane electrodialysis purification is displacing traditional distillation towers in new acid plants. Samsung and SK Hynix fabs in South Korea now specify membrane-refined material for 3nm gate etching. The technology is displacing incumbent thermal separation methods by cutting energy intensity 40% while achieving equivalent particle counts.
Japan's METI fluorochemical emission caps now require real-time stack monitoring and quarterly reporting from all domestic HF producers. The regulation forces capital allocation toward scrubber upgrades rather than capacity expansion. Japanese suppliers are responding by consolidating purification operations at coastal sites with deepwater export capabilities.
Long-term supply agreements with fixed-volume, variable-price clauses are replacing spot market purchases at major foundries. The contract structure transfers inventory risk to producers while securing allocation during supply crunches. This pattern is most pronounced in Taiwan's Science Park procurement offices, where 36-month deals now dominate 7nm and below material sourcing.
Ultra-High Purity Hydrofluoric Acid Market Segmentation
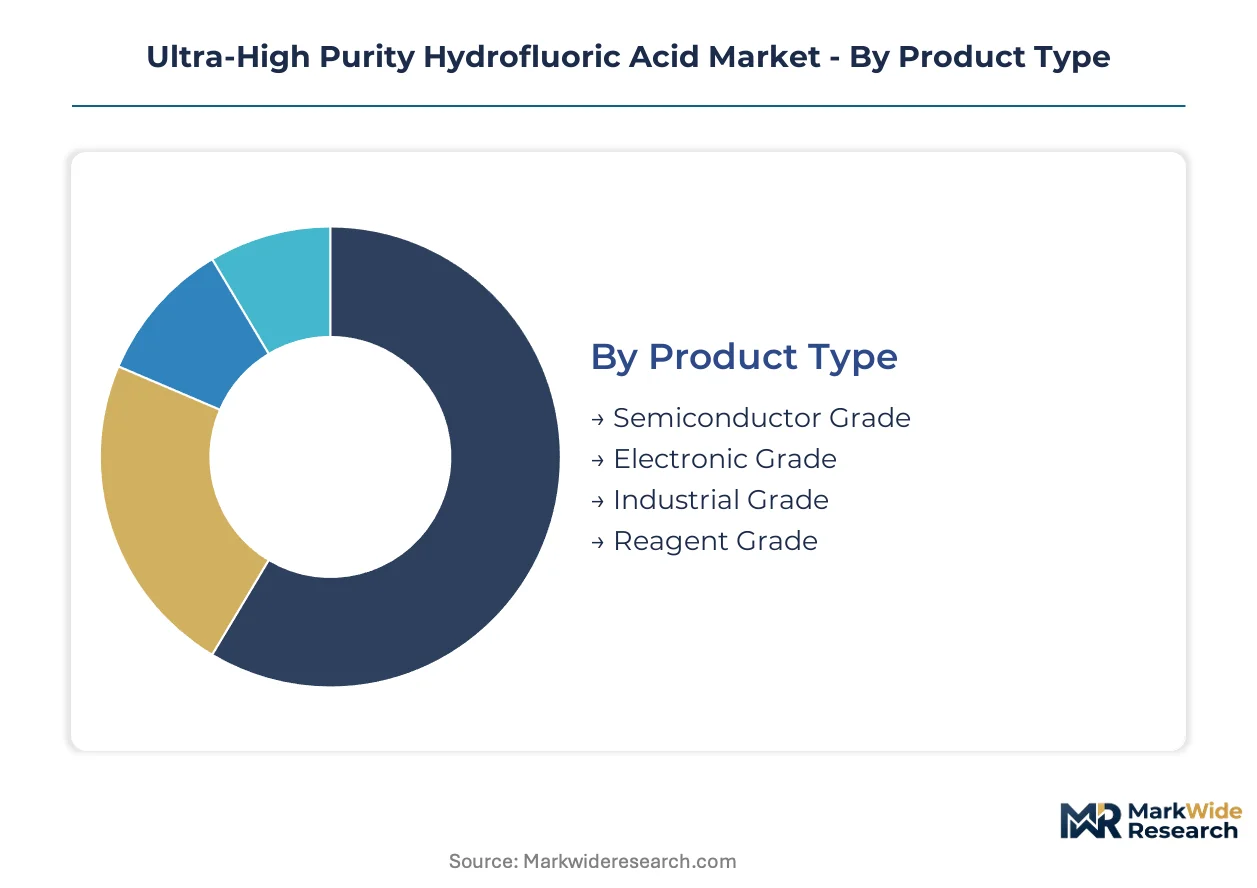
Ultra-high purity hydrofluoric acid markets stratify sharply across purity thresholds and handling protocols. Each segment carries distinct qualification timelines, contamination risk profiles, and logistics infrastructure requirements that reshape supplier economics.
Product Type:
Margin pools concentrate at the highest purity tiers where SEMI certification creates supply scarcity and pricing power.
- Semiconductor Grade:Material refined to sub-ppb metallic impurity levels exceeding SEMI Grade 5 standards with particle counts below 100 per liter. TSMC and Samsung fabs in Hsinchu and Pyeongtaek now specify this grade for 3nm gate etching, consuming triple the volume-per-wafer of mature nodes.
- Electronic Grade:HF meeting display panel manufacturing specifications for silicon oxide removal in TFT-LCD and OLED fabrication. BOE and TCL CSOT fabs in China's Yangtze River Delta are rotating up procurement of this grade as domestic display capacity expands under Beijing's dual carbon mandates.
- Industrial Grade:Standard purity material for general chemical processing and metal pickling operations facing margin compression from environmental handling surcharges.
- Reagent Grade:Laboratory-specified HF for analytical chemistry and research applications requiring documented traceability but tolerating higher metallic content than electronic grades.
Semiconductor Grade holds installed capacity. Electronic Grade is rotating up the share rankings.
Application:
Volume concentration follows wafer start intensity and etching cycle frequency across fabrication geometries.
- Electronics Manufacturing:Silicon wafer cleaning, oxide removal, and surface conditioning in semiconductor and display fabrication. Logic foundries below 5nm nodes now require multiple cleaning cycles per wafer, multiplying throughput requirements at TSMC and Samsung facilities.
- Metal Etching:Precision removal of metal oxides in aerospace and automotive component finishing where surface integrity specifications are less stringent than semiconductor applications.
- Chemical Synthesis:Fluorinated intermediate production for pharmaceuticals and agrochemicals consuming lower-purity grades with relaxed particle count tolerances.
- Glass Treatment:Frosting and etching of architectural and automotive glass using industrial-grade material with minimal purification overhead.
Electronics Manufacturing commands the steepest expansion trajectory. Metal Etching maintains stable offtake in mature industrial corridors.
End User:
Procurement sophistication varies dramatically across customer technical capabilities and qualification bandwidth.
- Semiconductor Companies:Integrated device manufacturers and pure-play foundries enforcing 18-24 month validation cycles for sub-ppt metallic impurity certification, locking supplier working capital in pre-revenue inventory.
- Laboratories:Research institutions and analytical facilities with fragmented demand patterns and stringent documentation requirements but limited volume scale.
- Chemical Manufacturers:Downstream fluorochemical producers consuming HF as feedstock for refrigerants and fluoropolymers facing regulatory pressure from EU F-Gas phase-down schedules.
- Glass Producers:Architectural and specialty glass fabricators with commoditized purchasing patterns and minimal purity differentiation requirements.
Semiconductor Companies anchor volume commitments. Laboratories are gaining procurement sophistication as research funding concentrates in East Asian technology clusters.
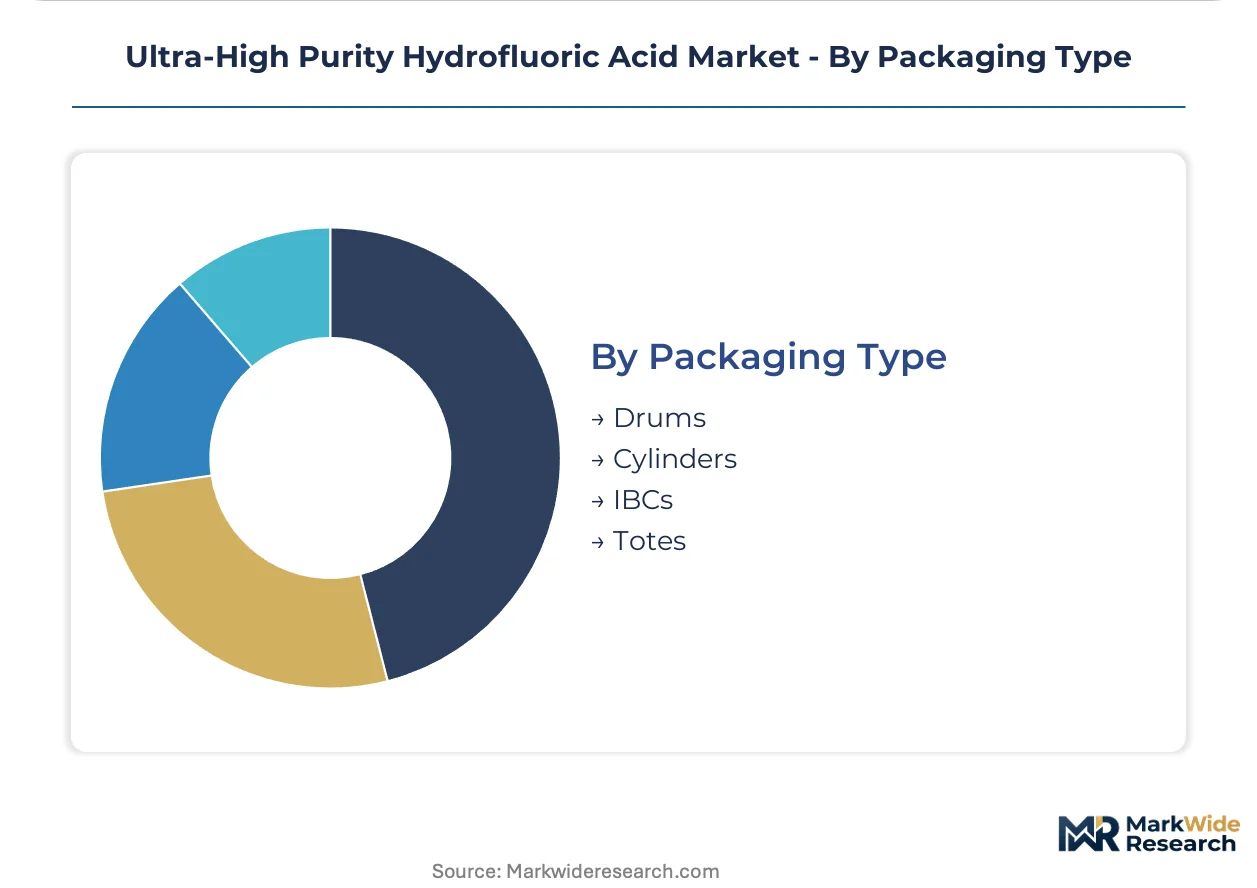
Packaging Type:
Contamination risk and logistics economics determine format selection across supply chain configurations.
- Drums:Standard 200-liter containers for industrial-grade distribution where particle ingress tolerances permit single-wall construction and shorter shelf-life requirements.
- Cylinders:High-pressure vessels for anhydrous HF transport to fabs with on-site purification infrastructure, reducing bulk tanker contamination exposure.
- IBCs:Intermediate bulk containers gaining share in electronic-grade distribution for mid-volume customers lacking bulk unloading systems.
- Totes:Disposable and returnable totes for semiconductor-grade material requiring nitrogen padding and double-contained configurations to prevent atmospheric moisture ingress.
Cylinders hold installed capacity in East Asian manufacturing corridors. Totes are rotating up the share rankings as point-of-use purification displaces centralized bulk supply models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese producers ship UHP-HF through coastal ports to semiconductor clusters in Taiwan and South Korea, while Chinese domestic refiners capture share from imports under Beijing's dual carbon mandates. This trade-flow reconfiguration is redrawing supply security calculations for advanced node fabs.
China
Domestic display panel and logic foundry expansion drives consumption of electronic and semiconductor-grade material. MEE hazardous chemical storage rules under GB standards restrict inland distribution, concentrating qualified supply in Yangtze River Delta clusters around Shanghai and Suzhou where BOE and SMIC operate.
Japan
Captive purification technology serves domestic chipmakers with sub-ppb specifications. METI fluorochemical emission caps force capital toward scrubber upgrades rather than capacity expansion, pushing producers to consolidate operations at coastal sites with deepwater export capabilities to Taiwan and South Korea.
South Korea
Samsung and SK Hynix fabs in Pyeongtaek and Yongin specify membrane-refined material for 3nm gate etching. Local procurement offices favor 36-month supply agreements with fixed-volume, variable-price clauses that transfer inventory risk to producers while securing allocation.
Taiwan
TSMC facilities in Hsinchu and Tainan consume triple the UHP-HF volume-per-wafer at sub-5nm nodes compared to mature processes. Science Park procurement offices enforce 18-24 month qualification timelines for sub-ppt metallic impurity certification, locking supplier working capital.
United States
Integrated fluorine chemistry operations anchor North American supply for domestic semiconductor fabrication. EPA and OSHA handling protocols govern bulk tanker movements to Arizona and Texas fab corridors, while on-site generation systems gain traction for eliminating transport contamination risks.
Ultra-High Purity Hydrofluoric Acid Market Competitive Landscape
Listed leaders compete with private specialists across purification technology tiers, creating a tiered structure where scale-driven multinationals and captive-technology domestic players split value pools. Three archetypes dominate: integrated fluorochemical conglomerates with backward control over fluorspar supply, captive-purification specialists serving single-country chipmaker ecosystems, and membrane-technology pure-plays displacing thermal separation methods. Competitive moves concentrate on long-term supply agreement structures and coastal logistics consolidation to meet emission-capped production constraints.
Within the integrated-conglomerate tier, Honeywell International Inc. and Solvay SA exemplify operators with diversified fluorine chemistry portfolios spanning multiple industrial verticals. Among Asia-Pacific captive-purification specialists, Stella Chemifa Corporation occupies a position representing Japanese producers with coastal consolidation strategies under METI compliance regimes. Zhejiang Kaiheng Electronic Materials Co., Ltd. and Jiangyin Jianghua Microelectronics Materials Co., Ltd. sit within the China-based specialist group capturing domestic substitution opportunities under dual carbon mandates. Morita Chemical Industries Co., Ltd. anchors the Osaka-centered supplier archetype with historical exposure to Japanese semiconductor material qualification protocols.
| Leading Market Players |
|---|
| Morita Chemical Industries Co., Ltd. |
| Zhejiang Kaiheng Electronic Materials Co., Ltd. |
| Stella Chemifa Corporation |
| Shaowu Huaxin Chemical Industry Co., Ltd. |
| Do-Fluoride Chemicals |
| Honeywell International Inc. |
| Sunlit Chemical |
| Jiangyin Jianghua Microelectronics Materials Co., Ltd. |
| Solvay SA |
| Others |
Value Network & Pricing Analysis
Membrane electrodialysis purification displacing thermal distillation simultaneously redraws production geography toward coastal Japan and South Korea while compressing energy-cost differentials that once anchored pricing power in legacy purification corridors.
Pricing Analysis
The technology-generation pricing gap separating membrane-refined 3nm-grade material from thermal-distilled legacy stock now exceeds the spread between semiconductor-grade and electronic-grade tiers. Three-tier pricing structure across premium membrane-refined, standard thermal-distilled, and economy industrial grades dominates contract structures. Pricing pressure stems from China's domestic substitution accelerating under MEE emission caps, eroding import premiums. Display panel manufacturers exhibit highest price sensitivity due to commoditized electronic-grade specifications, while logic foundries below 5nm nodes show lowest sensitivity given qualification lock-in effects.
Supply Chain Analysis
Strait of Malacca transit underwrites acid-grade fluorspar movements from Chinese and Mexican mining concentrations to purification plants in Japan and South Korea. Fluorspar concentrate, sulfuric acid, and calcium sulfate waste handling permits constitute critical input dependencies. Single-source vulnerability concentrates in acid-grade fluorspar export quotas from China and Mexico. Distribution runs through deepwater coastal consolidation points serving Taiwan Science Park and Pyeongtaek fab clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as TSMC and Samsung procurement offices consolidate 36-month supply agreements, squeezing supplier margins while locking in allocation security.
For Market Incumbents: Consolidate purification operations at coastal sites with deepwater export capabilities to satisfy METI emission caps while preserving Taiwan and South Korea access. Invest in membrane electrodialysis capacity additions to defend against Chinese domestic substitution threatening import volumes. Certification investment in SEMI Grade 6 qualification pipelines secures 3nm node allocation. For New Entrants and Emerging Players: SEMI Grade 6 fast-track certification through partnership with analytical instrument manufacturers bypasses the 18-24 month validation bottleneck. India's Gujarat corridor under the Semiconductor PLI scheme offers the most penetrable geography given first-mover absence. Solar cell texturing applications in Southeast Asia provide a go-to-market angle outside foundry qualification cycles. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors membrane-technology pure-plays over thermal-distillation incumbents. Long-term viability over the next decade hinges on coastal logistics consolidation and emission-compliant production architecture. Watch for Chinese domestic refiner capacity announcements as the inflection signal indicating import displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Electrodialysis Capacity Expansion | Samsung and SK Hynix specifications now require membrane-refined material for 3nm gate etching. |
| Coastal Site Consolidation | METI emission caps force Japanese producers toward deepwater export points serving Taiwan. |
| Long-term Supply Agreement Restructuring | Fixed-volume variable-price clauses transfer inventory risk to producers while securing foundry allocation. |
| On-Site Generation System Deployment | Membrane-based anhydrous HF units at fab perimeters eliminate bulk tanker contamination exposure. |
| Photovoltaic Texturing Market Entry | PERC and TOPCon cell manufacturing in Southeast Asia opens non-chip demand pools for semiconductor-grade material. |
Research Methodology
The analysis maps semiconductor-grade, electronic-grade, industrial-grade, and reagent-grade tiers, each validated through purification plant managers, foundry procurement leads, and fluorochemical R&D directors. Primary interviews combined with secondary validation from customs trade data, SEMI standards documentation, and METI emission filings anchor estimates. Bottom-up capacity assessments triangulate against top-down consumption models derived from wafer start projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segments by purity tier, end-use application, packaging format, and regional production hub. CAGRs derive from wafer start intensity curves and etching cycle frequency modeling at sub-7nm nodes. Membrane technology adoption rates and Chinese domestic substitution velocity constitute industry-specific forecast inputs.
Decision-makers should treat outputs as directional under stable fluorspar export quota and dual carbon mandate enforcement assumptions; material deviation would warrant model refresh. Practitioners should keep alternative scenarios live as EU F-Gas phase-down schedules and Indian PLI scheme implementation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
High-Value Chemicals
High Purity Aluminum Hydroxide Market
High-Value Chemicals
Battery Grade High Purity Lithium Fluoride Market
High-Value Chemicals
High Purity Isobutylene (HPIB) Market
High-Value Chemicals
P-Hydroxybenzoates (PHB) Market
High-Value Chemicals
Phenanthroline Monohydrate Market
High-Value Chemicals
Sodium Methyl P-Hydroxybenzoate Market
High-Value Chemicals
High Methoxyl Pectin Market
High-Value Chemicals
Ultra-High Purity Materials Market
High-Value Chemicals
Hydroxycarboxylic Acids Market
High-Value Chemicals
Global High Heat Foam Market
High-Value Chemicals
High-Nickel NCM Cathode Binder Latex Market
High-Value Chemicals
High Performance Fluoropolymers Market
High-Value Chemicals
Hydroxylamine Market
High-Value Chemicals
Global High Purity Oxygen Market
High-Value Chemicals
Mono Methyl Ether of Hydroquinone (MEHQ) Market
High-Value Chemicals
Global High Purity AHCL Market