
 Asia Pacific Cancer Biological Therapy Market | 2026-2036
Asia Pacific Cancer Biological Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Cancer Biological Therapy Market Outlook
China's biologics manufacturing corridor is reshaping regional supply dynamics for cancer biological therapies. F. Hoffmann-La Roche Ltd leverages its established oncology infrastructure across East Asian markets. Bristol-Myers Squibb Company anchors its presence through deep immuno-oncology expertise. Innovent Biologics competes aggressively on biosimilar and novel biologic development within domestic Chinese channels.
Cancer biological therapy encompasses therapeutics derived from living organisms or their components, including monoclonal antibodies engineered to target specific tumor antigens and cytokines modulating immune responses against malignancies. These agents function by interrupting cancer cell signaling, enhancing host immune surveillance, or delivering cytotoxic payloads with precision. Monoclonal antibodies occupy the largest revenue share given their established efficacy across hematological malignancies and solid tumors. Gene therapy represents the fastest-expanding segment as CRISPR-based platforms and CAR-T manufacturing scale across Asia Pacific contract development organizations. Hospitals dominate end-user consumption due to the infusion infrastructure and monitoring protocols required for intravenous biological administration.
Japan's PMDA, China's NMPA, and India's CDSCO govern biological therapy approval, manufacturing standards, and post-market surveillance across the region, with each regulator tightening cold-chain validation and biosimilar interchangeability requirements. Australia's TGA alignment with ICH Q5A-Q5D guidelines further harmonizes quality benchmarks for viral safety and cell substrate characterization. Stakeholders must monitor evolving biosimilar naming conventions and pharmacovigilance data-sharing agreements that will determine competitive positioning in biological therapy procurement across Asia Pacific healthcare systems.
Market Dynamics
China's NMPA accelerated biosimilar approval pathways are compressing development timelines and forcing originator manufacturers to defend positioning through indication expansion rather than exclusivity alone.
Growth Catalysts
- Japan's PMDA Sakigake designation:This fast-track pathway cuts review periods for breakthrough oncology biologics, enabling earlier patient access to CAR-T and bispecific antibody platforms.
- Hospital infusion center expansion:China's tier-one cities are building dedicated biological therapy units with cold-chain infrastructure, creating captive demand channels for intravenous monoclonal antibodies.
- Gene editing platform maturation:CRISPR-based manufacturing protocols are reducing cell therapy production costs across Asia Pacific contract development organizations.
Market Restraints
- Plasma-derived raw material concentration:Albumin and immunoglobulin feedstock supply concentrates in US and European fractionation facilities, exposing Asia Pacific manufacturers to import dependency.
- Cold-chain infrastructure gaps:India's last-mile temperature-controlled distribution remains underdeveloped outside metropolitan corridors, limiting biological therapy reach.
- Biosimilar interchangeability uncertainty:Australia's TGA and Japan's PMDA maintain divergent standards for automatic substitution, complicating multi-country portfolio strategies.
Strategic Opportunities
- Southeast Asia manufacturing relocation:Singapore's Biopolis and South Korea's Songdo clusters offer tax incentives and skilled bioprocessing labor for cell therapy production.
- Subcutaneous formulation development:Self-administered biological therapies bypass hospital dependency and expand addressable patient populations in China's tier-two cities.
- Real-world evidence regulatory acceptance:China's NMPA pilot programs allow post-approval efficacy data to support label expansion, shortening commercialization cycles.
Industry Challenges
- Cell therapy manufacturing technician scarcity:GMP-compliant aseptic processing skills lag demand across Asia Pacific, inflating labor costs and batch failure rates.
- Multi-jurisdiction pharmacovigilance harmonization:Divergent adverse event reporting timelines between Japan's PMDA and China's NMPA strain centralized safety database management.
- Legacy small-molecule oncology infrastructure stranded assets:Hospital pharmacies face capital reallocation pressures as biological therapies displace cytotoxic chemotherapy protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Cancer Biological Therapy Market |
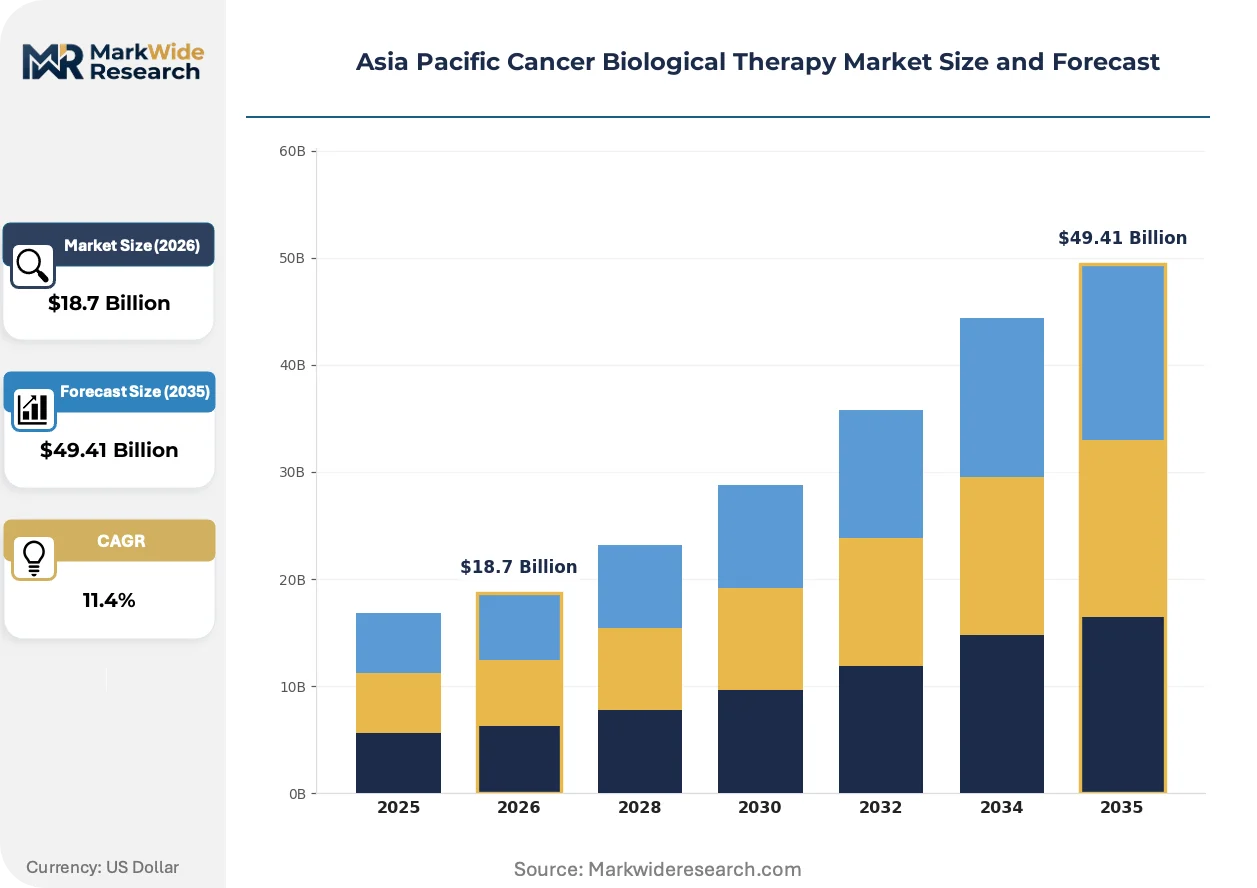
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Cytokines, Vaccines, Gene Therapy End User: Hospitals, Research Institutions, Clinics, Oncological Centers Delivery Mode: Intravenous, Subcutaneous, Oral, Topical Application: Hematological Malignancies, Solid Tumors, Immunotherapy, Targeted Therapy |
| Companies Covered | F. Hoffmann-La Roche Ltd, Merck & Co. Inc., Bristol-Myers Squibb Company, Novartis AG, Amgen Inc., Pfizer Inc., AstraZeneca, Johnson & Johnson Services, Inc., Innovent Biologics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Cancer Biological Therapy Market Strategic Shifts
Next-generation biologic modalities are compressing development paradigms and forcing regulatory adaptation across Asia Pacific oncology markets.
Allogeneic CAR-T platforms are eliminating patient-specific manufacturing bottlenecks through healthy donor-derived cell banks. Chinese contract manufacturers are scaling these off-the-shelf inventories at cost structures 60% below autologous equivalents. This standardization is rendering obsolete the regional autologous cell therapy infrastructure built during 2018-2023.
PMDA's conditional early approval system for regenerative medicines now covers bispecific T-cell engagers, compressing Japan's traditional 12-month review window. Domestic sponsors leverage this pathway to secure reimbursement listing before completion of Phase III confirmatory trials. Oncology departments in Tokyo and Osaka are prioritizing these accelerated-access biologics in formulary negotiations.
China's tier-one hospital groups are consolidating biological therapy procurement through centralized tendering platforms operated by provincial health commissions. This volume aggregation displaces fragmented hospital-level purchasing and compresses net pricing for originator monoclonal antibodies. The concentration is most visible in Shanghai and Beijing, where three hospital alliances now control 40% of biological therapy volume in their catchment areas.
Asia Pacific Cancer Biological Therapy Market Segmentation
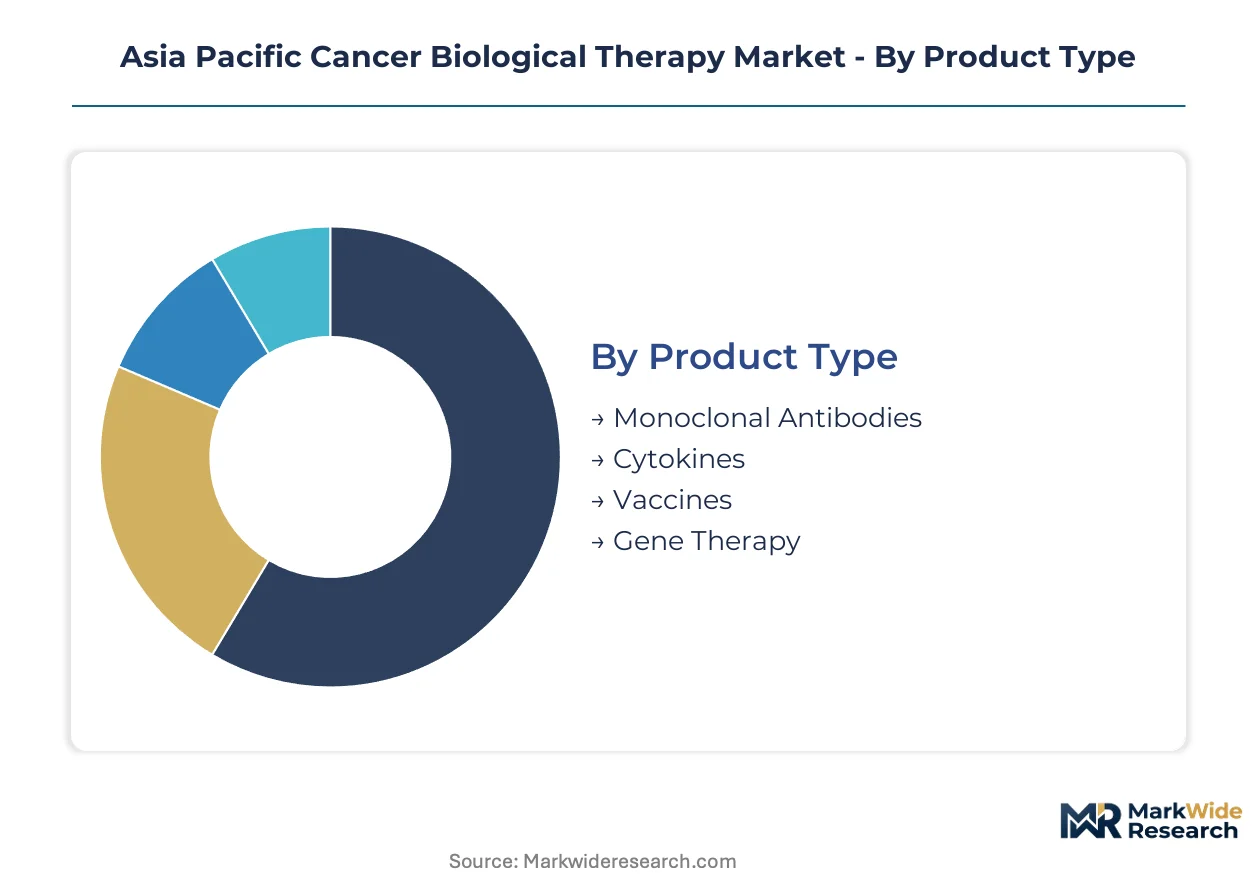
Biological therapy segmentation in Asia Pacific reflects divergent infrastructure requirements across administration settings and molecular platforms. Product type determines manufacturing complexity and cold-chain investment, while end-user channels dictate reimbursement pathways and patient access velocity.
Product Type:
Clinical application spans precision targeting to systemic immune modulation across molecular classes.
- Monoclonal Antibodies:Engineered immunoglobulins bind tumor-specific antigens to interrupt proliferative signaling or mark malignant cells for immune destruction. Demand concentrates in Japan's metropolitan oncology centers where PMDA-approved checkpoint inhibitors anchor first-line protocols for lung and gastric malignancies.
- Gene Therapy:CRISPR-edited cellular platforms and viral vector deliveries correct oncogenic mutations or engineer patient-derived immune cells. China's NMPA pilot programs for CAR-T manufacturing are compressing autologous production timelines at Suzhou and Shanghai contract development organizations.
- Cytokines:Interleukin and interferon formulations modulate anti-tumor immune responses through systemic administration.
- Vaccines:Therapeutic cancer vaccines prime patient-specific T-cell recognition of tumor-associated antigens.
Established volume favors monoclonal antibodies; emerging adoption favors gene therapy.
End User:
Channel structure mirrors the concentration of infusion infrastructure and specialized monitoring capabilities.
- Hospitals:Comprehensive oncology departments maintain GMP-compliant pharmacy units, cold-chain storage, and adverse event response protocols required for intravenous biological administration. China's tier-one hospital alliances in Beijing and Shanghai aggregate procurement through provincial tendering platforms.
- Oncological Centers:Dedicated cancer facilities concentrate biological therapy expertise and clinical trial access for novel immuno-oncology agents. Japan's National Cancer Center hospitals in Tokyo and Kashiwa prioritize PMDA Sakigake-designated biologics in formulary negotiations.
- Research Institutions:Academic medical centers conduct early-phase trials and manufacture investigator-initiated cell therapies under GMP-adjacent protocols.
- Clinics:Outpatient settings with limited infusion capacity handle subcutaneous biological formulations and post-treatment monitoring.
Volume concentrates in hospital channels; patient access expansion favors oncological centers.
Delivery Mode:
Administration route determines site-of-care requirements and patient compliance profiles across the region.
- Intravenous:Infusion-dependent biologics require hospital-based administration with cardiac monitoring and hypersensitivity response capability. China's tier-one cities are building dedicated biological therapy units with validated cold-chain infrastructure.
- Subcutaneous:Self-administered formulations bypass hospital dependency and extend reach into China's tier-two cities where infusion center density remains limited.
- Oral:Small-molecule biologic derivatives and targeted protein degraders enable outpatient adherence without injection requirements.
- Topical:Localized biological applications address cutaneous lymphomas and superficial malignancies through direct lesion penetration.
Hospital infrastructure anchors intravenous dominance; subcutaneous development targets geographic expansion.
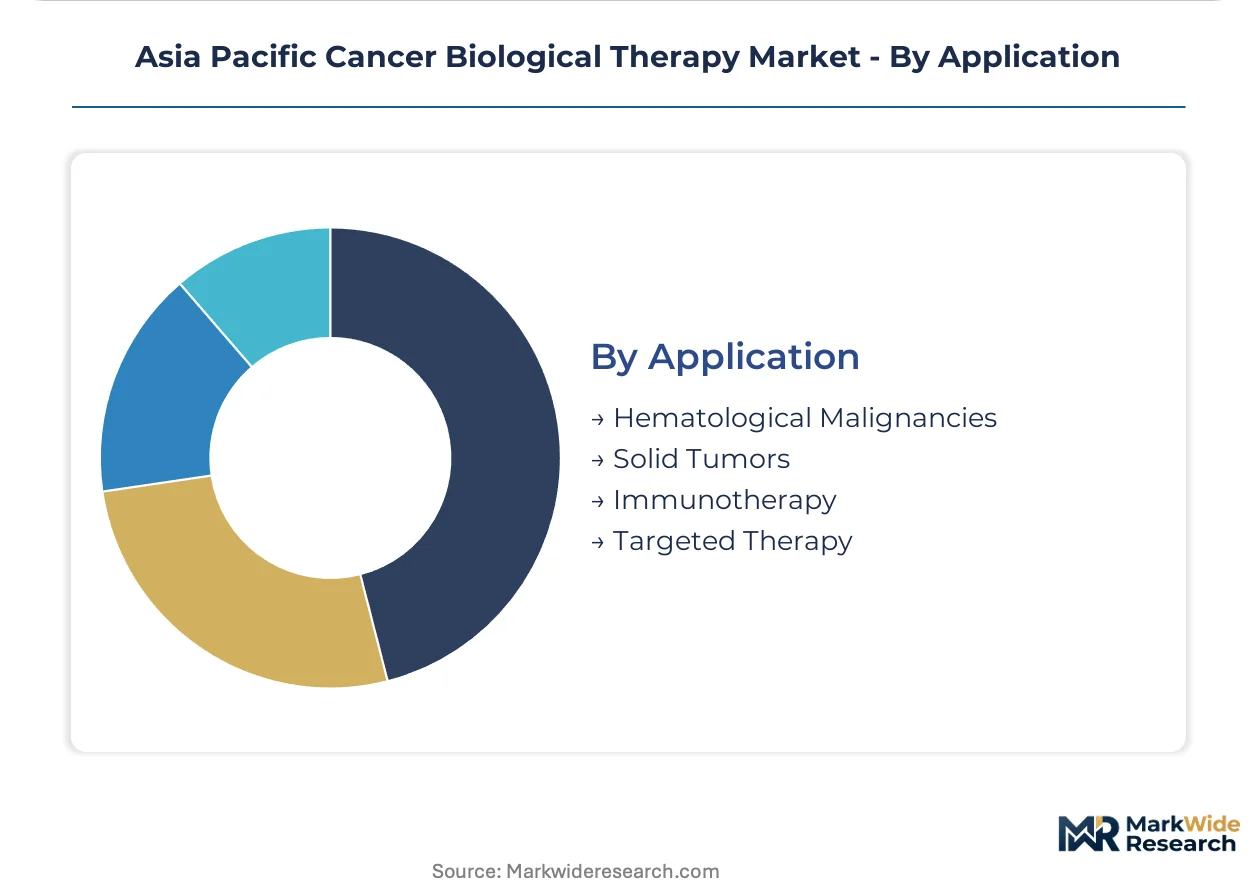
Application:
Therapeutic focus shifts between hematological and solid tumor indications based on biological mechanism and regulatory approval status.
- Hematological Malignancies:CAR-T and bispecific antibody platforms demonstrate curative potential in B-cell leukemias and lymphomas through lineage-specific antigen targeting. Japan's PMDA accelerated approval pathways prioritize these indications given established surrogate endpoints.
- Immunotherapy:Checkpoint inhibitors and cytokine modulators unleash anti-tumor immune responses across multiple malignancy types. Australia's TGA alignment with ICH guidelines harmonizes quality benchmarks for viral safety in these living-system therapeutics.
- Solid Tumors:Tumor-infiltrating lymphocyte therapies and antibody-drug conjugates penetrate microenvironment barriers in breast, lung, and gastrointestinal malignancies.
- Targeted Therapy:Molecularly matched biologics interrupt oncogenic driver mutations in patient-selected populations.
Revenue concentration favors hematological applications; pipeline investment favors solid tumor penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biologics manufacturing clusters concentrate in China's Yangtze River Delta and Japan's Kanto corridor, with specialized cold-chain infrastructure anchoring regional supply capacity. Hospital procurement consolidation across tier-one cities is compressing pricing bandwidth for originator monoclonal antibodies. Regulatory divergence between NMPA, PMDA, and TGA continues to fragment multi-country launch strategies.
China
NMPA accelerated biosimilar pathways are compressing development timelines for domestic sponsors. Suzhou and Shanghai biologics manufacturing clusters are scaling CAR-T production through contract development organizations. Provincial hospital alliances in Beijing and Shanghai now control 40% of biological therapy volume through centralized tendering platforms.
Japan
PMDA Sakigake designation prioritizes breakthrough oncology biologics including CAR-T and bispecific antibody platforms. Tokyo and Osaka oncology departments anchor formulary negotiations for accelerated-access therapies. The conditional early approval system for regenerative medicines now covers bispecific T-cell engagers, compressing traditional review windows.
India
CDSCO tightening of cold-chain validation requirements is exposing last-mile distribution gaps outside metropolitan corridors. Mumbai and Hyderabad biologics manufacturing hubs are expanding plasma-derived feedstock processing capacity. Domestic sponsors face import dependency for albumin and immunoglobulin raw materials concentrated in US and European fractionation facilities.
Australia
TGA alignment with ICH Q5A-Q5D guidelines harmonizes quality benchmarks for viral safety and cell substrate characterization. Melbourne and Sydney hospital networks are prioritizing biosimilar interchangeability standards that diverge from Japan's PMDA protocols. The regulator's post-market surveillance requirements strain centralized safety database management for multi-jurisdiction portfolios.
South Korea
MFDS cell therapy manufacturing standards are attracting regional production relocation to Songdo's bioprocessing cluster. Seoul-based hospital groups are expanding infusion center infrastructure for intravenous monoclonal antibody administration. Domestic sponsors leverage government R&D tax incentives to develop subcutaneous formulations that bypass hospital dependency.
Asia Pacific Cancer Biological Therapy Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with manufacturing technology and raw material supply. The competitive structure stratifies between originator biologics manufacturers defending indication expansion and biosimilar developers compressing price points. Three archetypes dominate: multinational oncology incumbents with established infusion infrastructure, domestic Chinese biologics specialists leveraging NMPA accelerated pathways, and contract development organizations scaling cell therapy production. Consolidation through hospital procurement alliances and capacity expansion into Southeast Asian manufacturing clusters represent the dominant competitive vectors.
Among Swiss-headquartered incumbents, F. Hoffmann-La Roche Ltd exemplifies the established oncology infrastructure archetype across East Asian markets. Bristol-Myers Squibb Company represents the immuno-oncology expertise anchor within the multinational tier. Innovent Biologics occupies a position as the domestic Chinese specialist competing on biosimilar and novel biologic development within NMPA-regulated channels.
| Leading Market Players |
|---|
| F. Hoffmann-La Roche Ltd |
| Merck & Co. Inc. |
| Bristol-Myers Squibb Company |
| Novartis AG |
| Amgen Inc. |
| Pfizer Inc. |
| AstraZeneca |
| Johnson & Johnson Services, Inc. |
| Innovent Biologics |
| Others |
Value Chain & Pricing Dynamics
Suzhou's biologics manufacturing corridor anchors regional capacity for monoclonal antibodies and CAR-T platforms, concentrating upstream supply power among contract development organizations that feed into China's provincial hospital tendering alliances. This geographic clustering enables volume aggregation that compresses net pricing for originator molecules while amplifying procurement leverage for downstream buyers.
Pricing Analysis
China's NMPA accelerated biosimilar approval pathways dictate the pricing tier structure across the region, separating originator checkpoint inhibitors from domestic biosimilars and economy-tier molecules lacking interchangeability designation. Price differentiation rests on cold-chain certification grade and PMDA versus NMPA regulatory pedigree, with Japan's metropolitan oncology centers showing lowest price sensitivity and India's tier-two hospital procurement demonstrating acute cost compression. Margins are tightening for originator manufacturers forced to defend positioning through indication expansion rather than exclusivity alone.
Supply Chain Analysis
Export controls on CRISPR editing technologies and viral vector manufacturing equipment limit flows into Asia Pacific contract development organizations, constraining gene therapy capacity expansion. Plasma-derived feedstock concentrates in US and European fractionation facilities, exposing Chinese and Indian manufacturers to import dependency for albumin and immunoglobulin raw materials. Single-source vulnerability runs through the albumin supply chain, with distribution running through validated cold-chain networks anchored by hospital-based GMP pharmacy units and specialized oncological center infusion infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GMP-compliant aseptic processing technician scarcity across Asia Pacific inflates labor costs and batch failure rates, creating a structural bottleneck that favors sponsors with captive training pipelines and long-tenured manufacturing workforces.
For Market Incumbents: Harden cold-chain infrastructure ownership across China's tier-one hospital alliances to defend against biosimilar displacement, while deepening indication expansion investments in solid tumor applications to offset originator price erosion. Prioritize PMDA Sakigake pathway navigation to secure accelerated reimbursement listing before confirmatory trial completion. For New Entrants and Emerging Players: Establish a beachhead in subcutaneous biological formulation development for China's tier-two cities, where hospital infusion center density remains limited and self-administered therapies bypass infrastructure dependency. Target real-world evidence regulatory acceptance pilot programs to compress commercialization cycles through post-approval efficacy data submission. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors contract development organizations with validated CAR-T manufacturing platforms and established China-NMPA regulatory relationships over pure-play biosimilar developers facing interchangeability uncertainty. Long-term viability hinges on allogeneic cell therapy standardization capabilities. Watch PMDA-NMPA pharmacovigilance data-sharing agreement progress as the signal for multi-jurisdiction portfolio scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Subcutaneous Formulation Development | Bypasses hospital dependency and expands patient access into China's underserved tier-two urban corridors. |
| Allogeneic CAR-T Platform Scale-Up | Eliminates patient-specific manufacturing bottlenecks through healthy donor-derived cell bank standardization. |
| PMDA Sakigake Pathway Navigation | Compresses review windows for breakthrough oncology biologics and secures earlier reimbursement listing. |
| Provincial Tendering Platform Alignment | Positions sponsors for volume aggregation through Beijing and Shanghai hospital alliance procurement consolidation. |
| GMP Aseptic Processing Workforce Investment | Addresses technician scarcity that inflates batch failure rates across Asia Pacific cell therapy manufacturing. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors across Japan, China, and Australia; and secondary validation against NMPA and PMDA filings, ClinicalTrials.gov records, hospital procurement databases, and GPO contract repositories. Bottom-up patient-volume modeling and top-down manufacturer capacity assessments were triangulated to reconcile segmentation outputs.
Forecast inputs span product type, end-user channel, delivery mode, and application across the analysis window, with CAGRs derived from regulatory approval velocity, biosimilar entry timing, and hospital infrastructure expansion curves. Modeled variables include provincial tendering platform consolidation rates, PMDA conditional approval uptake, and cold-chain last-mile penetration outside metropolitan corridors.
Sensitivities concentrate around NMPA-PMDA pharmacovigilance harmonization progress, biosimilar interchangeability standard divergence, and plasma-derived feedstock supply disruptions. Forecasts reflect documented assumptions on regulatory pathway timelines and hospital procurement alliance formation. Material shifts in CAR-T manufacturing cost structures or accelerated approval pathway scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Middle East and Africa Cancer Vaccines Market
Cell & Gene Therapy
Global T-Cell Lymphoma Market
Cell & Gene Therapy
Progressive Familial Intrahepatic Cholestasis Type 2 Treatment Market
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Autologous Cell Therapy Market
Cell & Gene Therapy
Osteoarthritis Gene Therapy Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
High Density (HD) Cell Banking Market
Cell & Gene Therapy
Viral Vector Purification Market
Cell & Gene Therapy
Gene Vector Market
Cell & Gene Therapy
MRNA Therapeutics Contract Development and Manufacturing Organization Market
Cell & Gene Therapy
Oncolytic Virus Cancer Therapy Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Therapeutics Market
Cell & Gene Therapy
Stem Cell Manufacturing Market