
 North America Gene Therapy Market | 2026-2036
North America Gene Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
North America Gene Therapy Market Insights
Market Context with Strategic Players
Capital-intensity divergence between vector manufacturing capabilities and clinical-stage research operations is rotating strategic priorities across the competitive landscape. Novartis AG leverages its integrated CDMO infrastructure to control lentiviral supply chains from plasmid to finished dose. Gilead Sciences sustains dominance in CAR-T commercialization through Kite Pharma's manufacturing network. Vertex Pharmaceuticals anchors its position in CRISPR-based therapies via the exagamglogene autotemcel program.
Technical Definition and Structural Segments
Gene therapy comprises the therapeutic delivery of nucleic acids into patient cells to correct or compensate for disease-causing genetic mutations, utilizing viral vectors engineered to achieve tissue-specific transduction efficiencies exceeding standard biologics. The field's primary commercial purpose centers on addressing monogenic disorders and malignancies refractory to conventional small-molecule or protein interventions. Lentiviral vectors command the largest revenue share among product types due to their stable genomic integration profile in hematopoietic stem cell applications. Oncology applications generate disproportionate investment flows, though rare disease programs exhibit the fastest clinical trial enrollment acceleration. Contract Manufacturing Organizations represent the most margin-concentrated end-user segment as sponsors outsource vector production to de-risk capacity investments.
Regulatory Framework and Forward Outlook
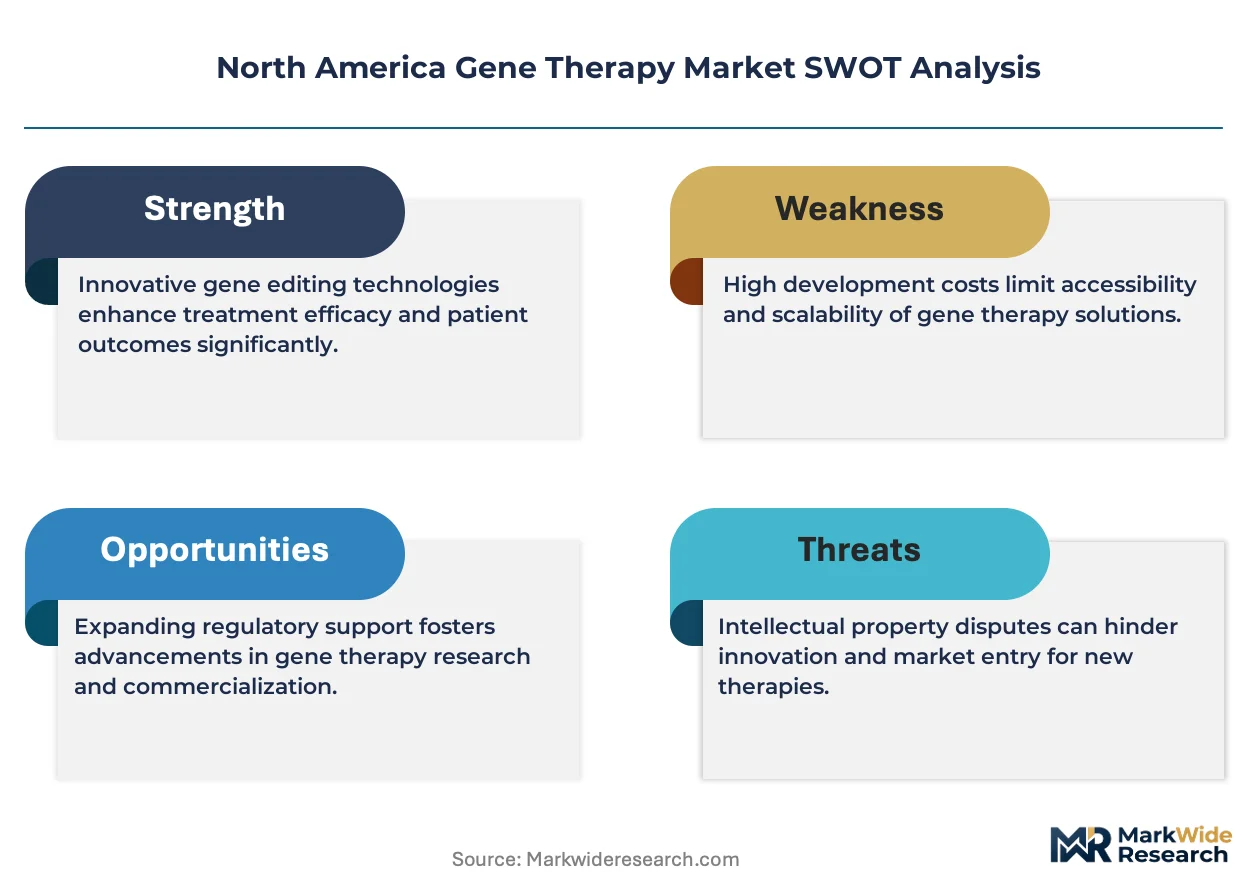
The FDA's Office of Therapeutic Products within CBER governs gene therapy IND reviews, while the NIH Recombinant DNA Advisory Committee maintains oversight of novel vector platforms. Health Canada and PMRA coordinate parallel scientific advice with FDA to streamline North American development pathways. Stakeholders must monitor emerging guidance on long-term follow-up requirements for integrating vectors, as these post-marketing obligations will reshape program economics and portfolio prioritization decisions.
Market Dynamics
Vector manufacturing bottlenecks are compressing clinical trial timelines and forcing sponsors into capital-intensive capacity commitments before proof-of-concept data matures. This supply-constraint dynamic is reshaping partnership structures across the value chain.
Growth Catalysts
- FDA Accelerated Approval:The Regenerative Medicine Advanced Therapy designation compresses development timelines for qualifying programs, reducing time-to-market for novel vectors.
- Oncology Infusion Network Expansion:Academic medical centers in Boston and Philadelphia are building in-house gene therapy administration capabilities, decentralizing treatment delivery.
- CRISPR Platform Maturation:Editing efficiency improvements in ex vivo hematopoietic applications are expanding addressable patient populations beyond prior technical limits.
Market Restraints
- Plasmid Supply Concentration:Critical raw material production clusters in a limited number of GMP facilities, creating single-source vulnerability for lentiviral programs.
- Long-Term Follow-Up Burden:FDA guidance on 15-year post-marketing surveillance for integrating vectors imposes persistent cost obligations that distort portfolio economics.
- Allogeneic Cell Therapy Substitution:Off-the-shelf CAR-T approaches threaten autologous gene therapy addressable markets in hematologic malignancies.
Strategic Opportunities
- Central Nervous System Indications:Adeno-associated viral vectors targeting neurological monogenic disorders represent underpenetrated therapeutic territory with limited competing modalities.
- Canadian Parallel Pathways:Health Canada and PMRA scientific advice coordination with FDA enables synchronized North American development strategies.
- In Vivo Base Editing Convergence:Integration of CRISPR-derived base editors with lipid nanoparticle delivery creates potential for liver-directed metabolic disease correction.
Industry Challenges
- Vector Process Development Talent Scarcity:GMP-compliant viral production expertise concentrates at a handful of contract manufacturers, constraining sponsor scale-up velocity.
- Quality Control Standardization Delays:Absence of harmonized potency assays across vector platforms complicates multi-site manufacturing and regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Gene Therapy Market |
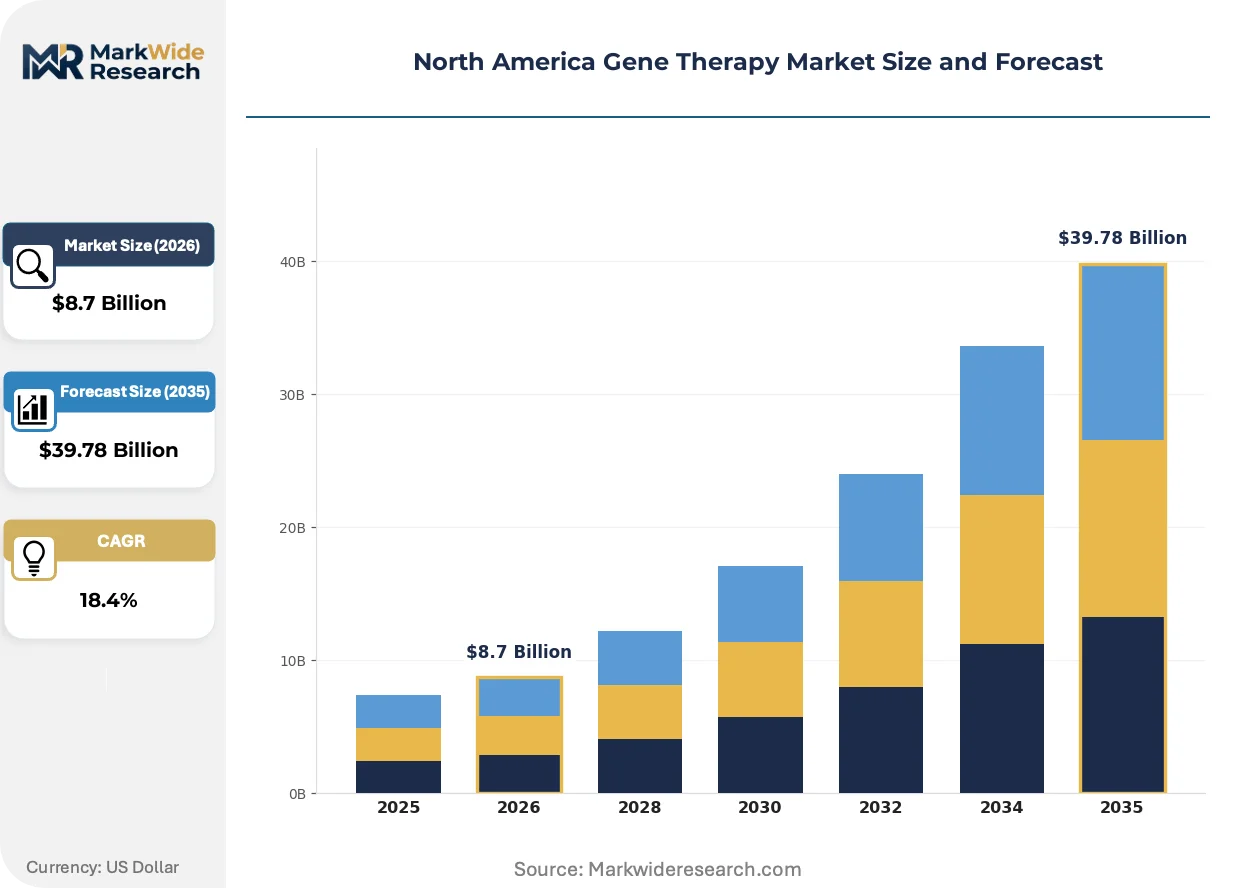
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adenoviral Vectors, Lentiviral Vectors, Plasmid DNA, RNA-Based Therapies End User: Hospitals, Research Institutions, Contract Manufacturing Organizations, Biopharmaceutical Companies Application: Oncology, Neurology, Cardiovascular, Rare Diseases Delivery Method: In Vivo, Ex Vivo, Intravenous, Local Injection |
| Companies Covered | Novartis AG, Gilead Sciences, Bristol Myers Squibb, Vertex Pharmaceuticals, Spark Therapeutics, Sangamo Therapeutics, Bluebird Bio, Regeneron Pharmaceuticals, Biogen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Gene Therapy Market Trends and Innovations
Next-generation delivery technologies are collapsing the boundary between ex vivo cell modification and direct in vivo genetic correction, enabling new therapeutic modalities while threatening incumbent platform economics.
Suspension-based lentiviral production is supplanting adherent cell culture systems in commercial-scale manufacturing. CDMOs and integrated sponsors are retrofitting bioreactor trains to accommodate suspension adaptation, cutting per-dose production costs and enabling thousand-liter batch scales previously unattainable with flask-based methods. This transition is compressing the cost structure for late-stage hematopoietic stem cell programs.
The NIH Recombinant DNA Advisory Committee has streamlined oversight protocols for previously reviewed vector backbones, eliminating redundant institutional biosafety reviews for platform derivatives. This policy revision accelerates site activation timelines for multi-center gene therapy trials. Sponsors with established vector master files are exploiting this efficiency gain to compress clinical development schedules.
Hospital procurement departments are consolidating gene therapy purchasing under centralized pharmacy and therapeutics committees, displacing individual physician-driven ordering. This concentration shifts negotiation leverage toward integrated delivery networks and away from specialty distributors. The Northeast corridor academic medical centers are pioneering this governance evolution, with Philadelphia and Boston health systems establishing dedicated gene therapy value assessment frameworks.
North America Gene Therapy Market Segmentation
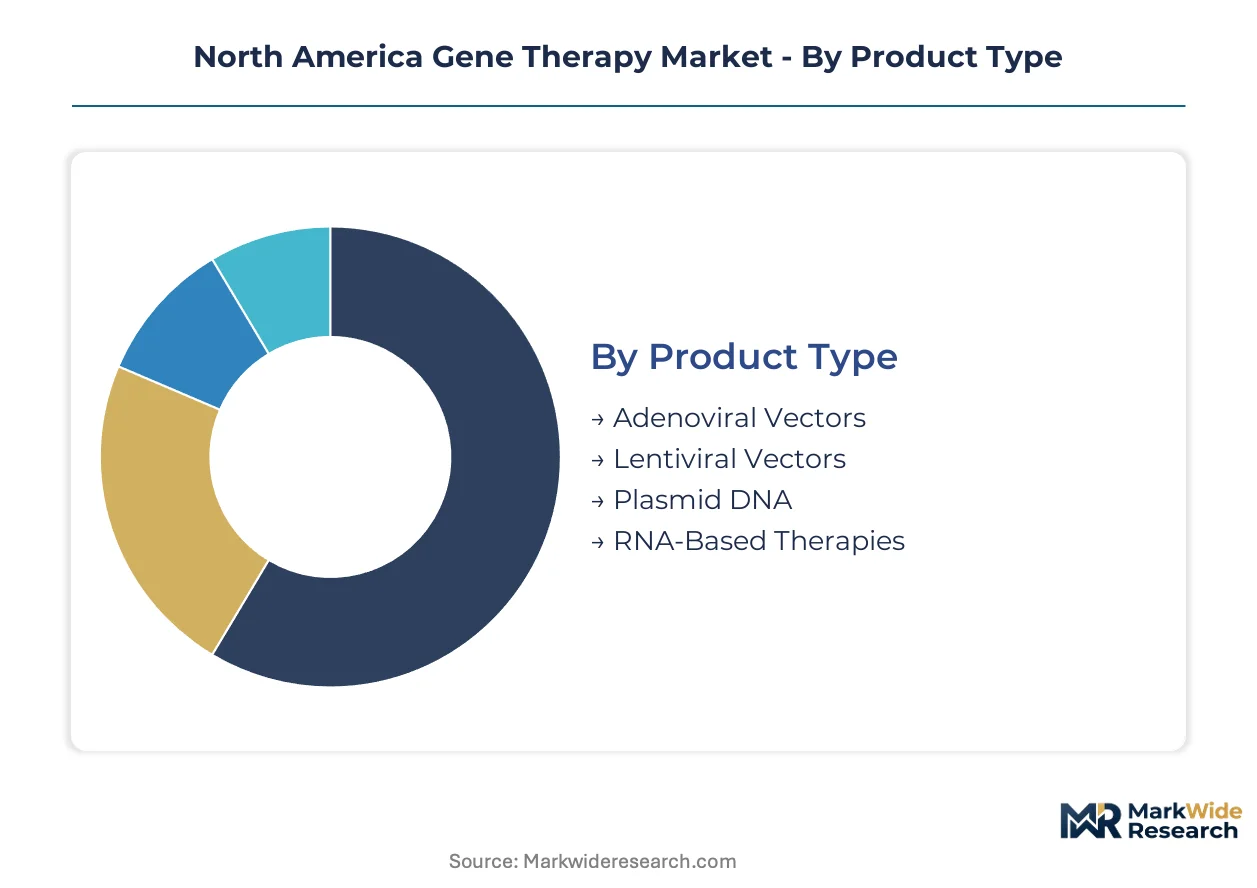
Gene therapy market segmentation reveals where capital commitments concentrate and which technical platforms command manufacturing priority. Vector selection and delivery modality determine regulatory pathways, reimbursement complexity, and commercial scalability across therapeutic categories.
Product Type:
Margin pools concentrate in lentiviral platforms where stable genomic integration commands premium pricing in hematopoietic stem cell applications.
- Lentiviral Vectors:Engineered from HIV-1 backbone with self-inactivating LTR modifications to prevent insertional mutagenesis. Demand concentrates in Boston and Philadelphia academic medical centers expanding CAR-T manufacturing capabilities, though 15-year FDA post-marketing surveillance obligations inflate program economics.
- Adenoviral Vectors:Non-integrating double-stranded DNA delivery vehicles with high transduction efficiency in dividing and non-dividing cells. Northeast corridor hospitals prioritize these for oncology applications where transient expression suffices, driven by compressed clinical trial timelines under Regenerative Medicine Advanced Therapy designation.
- Plasmid DNA:Circular bacterial DNA constructs serving as critical raw material for viral vector production and direct therapeutic applications.
- RNA-Based Therapies:Messenger RNA and self-amplifying RNA platforms enabling transient protein expression without genomic integration.
Lentiviral vectors hold installed capacity. RNA-based therapies are rotating up the share rankings.
End User:
Customer concentration patterns split between integrated sponsors controlling supply chains and outsourced manufacturers absorbing capital risk.
- Contract Manufacturing Organizations:GMP-compliant viral vector production facilities offering plasmid-to-finished-dose services. CDMOs in the Northeast corridor capture disproportionate margin pools as sponsors defer capacity investments until proof-of-concept data matures, with Philadelphia and Boston clusters dominating regional supply.
- Biopharmaceutical Companies:Integrated developers with captive manufacturing infrastructure spanning vector design through clinical supply. Vertex Pharmaceuticals and Novartis AG anchor this segment through controlled lentiviral and CRISPR platform supply chains, though talent scarcity in GMP viral production constrains scale-up velocity.
- Hospitals:Academic medical centers building in-house infusion and limited manufacturing capabilities for patient-specific therapies.
- Research Institutions:Preclinical vector development and early-phase investigator-initiated trials.
Contract Manufacturing Organizations hold installed capacity. Hospitals are rotating up the share rankings.
Application:
Therapeutic focus areas distribute investment flows unevenly, with oncology commanding near-term revenue and rare disease programs expanding addressable populations.
- Oncology:CAR-T cell therapies and tumor-infiltrating lymphocyte modifications targeting hematologic and solid malignancies. CRISPR platform maturation in ex vivo hematopoietic applications is expanding patient eligibility beyond prior technical limits, with Kite Pharma's manufacturing network sustaining commercial dominance.
- Rare Diseases:Monogenic disorder corrections including sickle cell disease and inherited retinal dystrophies. The exagamglogene autotemcel program anchors this segment through FDA-coordinated Health Canada and PMRA parallel pathways, representing the steepest expansion trajectory in clinical trial enrollment acceleration.
- Neurology:Adeno-associated viral vectors targeting central nervous system monogenic disorders with limited competing modalities.
- Cardiovascular:Gene therapies addressing ischemic heart disease and inherited cardiomyopathies through angiogenic and direct cardiac correction approaches.
Oncology holds installed capacity. Rare diseases are rotating up the share rankings.
Delivery Method:
Technical modality selection determines manufacturing complexity, regulatory burden, and reimbursement architecture.
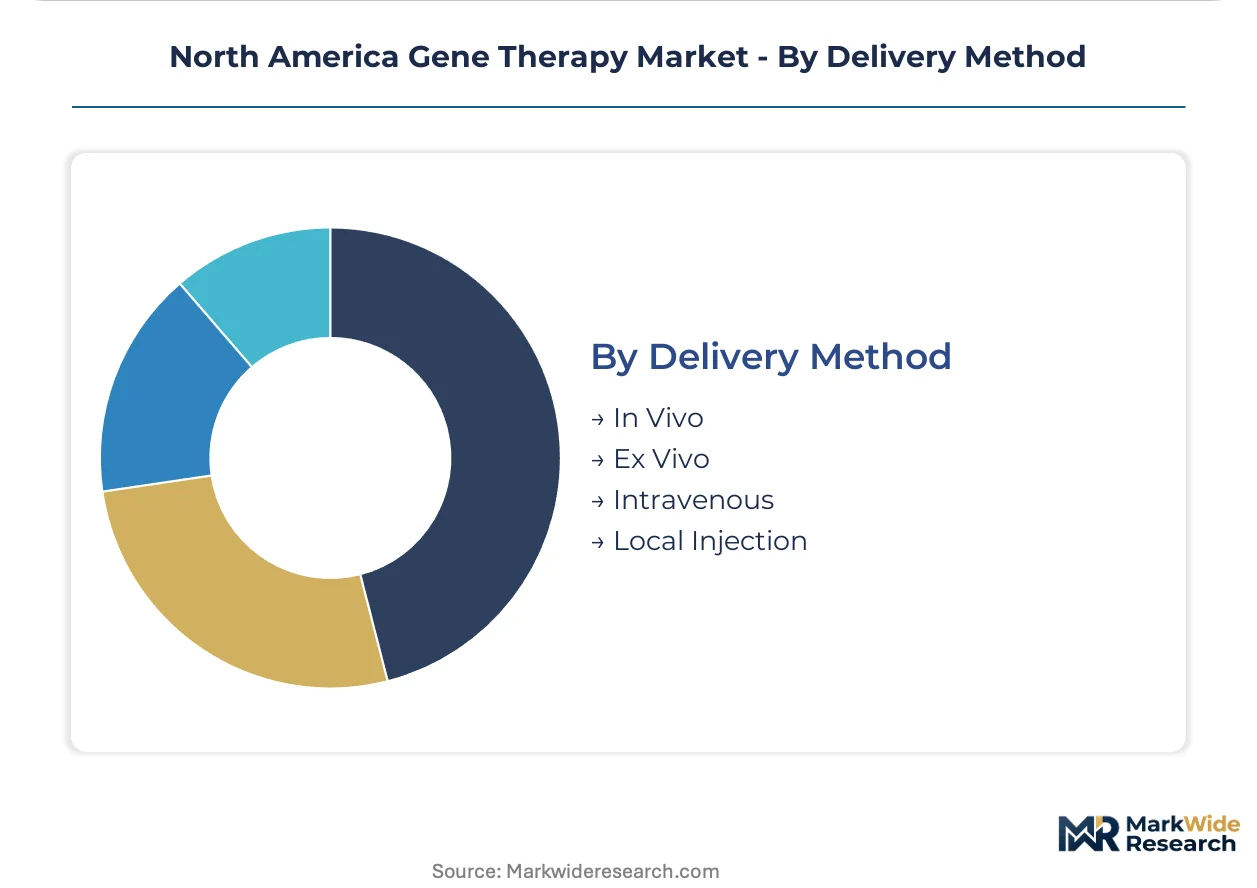
- Ex Vivo:Cell harvesting, genetic modification in controlled manufacturing environments, and reinfusion. This approach dominates hematopoietic stem cell applications where lentiviral transduction efficiency exceeds standard biologics, with suspension-based production systems cutting per-dose costs across Northeast corridor manufacturing networks.
- In Vivo:Direct vector administration to patients through systemic or localized delivery. Lipid nanoparticle integration with CRISPR-derived base editors is creating liver-directed metabolic disease correction opportunities, though long-term follow-up requirements for integrating vectors reshape program economics.
- Intravenous:Systemic vector distribution enabling broad tissue transduction for hematologic and metabolic targets.
- Local Injection:Site-specific delivery concentrating therapeutic payload in target tissues while limiting systemic exposure.
Ex vivo holds installed capacity. In vivo is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial gene therapy trade surplus, exporting lentiviral vectors and CRISPR platforms while importing specialized plasmid raw materials from concentrated European suppliers. Canada and Mexico anchor North American capacity expansion through coordinated FDA-Health Canada regulatory alignment.
United States
FDA's Regenerative Medicine Advanced Therapy designation compresses development timelines for qualifying programs, drawing sponsor investment toward accelerated approval pathways. The NIH Recombinant DNA Advisory Committee streamlined oversight protocols for established vector backbones, eliminating redundant biosafety reviews. Boston and Philadelphia academic medical centers anchor the Northeast corridor's manufacturing concentration, with hospital procurement committees consolidating gene therapy purchasing under centralized pharmacy frameworks.
Canada
Health Canada and PMRA coordinate parallel scientific advice with FDA to synchronize North American development strategies for sponsors pursuing cross-border trials. The country's national pharmaceutical regulator maintains aligned post-marketing surveillance requirements for integrating vectors, reducing regulatory friction for US-based sponsors. Ontario and Quebec host contract manufacturing clusters serving US sponsors seeking to de-risk capacity investments before proof-of-concept data matures.
Mexico
COFEPRIS regulatory modernization efforts align Mexican clinical trial frameworks with FDA standards, enabling inclusion in multi-center North American studies. The country's national pharmaceutical regulator participates in FDA-led scientific advice coordination for gene therapy sponsors targeting Latin American expansion. Mexico City and Monterrey metropolitan areas concentrate hospital infrastructure capable of supporting gene therapy administration, though vector manufacturing remains import-dependent.
North America Gene Therapy Market Competitive Landscape
Concentration sits with integrated biopharmaceutical developers controlling captive vector manufacturing infrastructure from plasmid supply through finished dose. The competitive structure splits between large-cap sponsors with in-house CDMO capabilities and mid-cap developers dependent on outsourced production. Three archetypes dominate: vertically integrated platform holders, CAR-T commercialization specialists, and CRISPR editing technology licensors. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as manufacturing bottlenecks force premature capital commitments.
Among integrated platform developers, Novartis AG and Vertex Pharmaceuticals exemplify the archetype of sponsors controlling lentiviral and CRISPR supply chains respectively. Gilead Sciences occupies a parallel position in CAR-T commercialization through manufacturing network dominance. These three entities anchor the premium tier, representing distinct strategic bets on vector modality and therapeutic application concentration.
| Leading Market Players |
|---|
| Novartis AG |
| Gilead Sciences |
| Bristol Myers Squibb |
| Vertex Pharmaceuticals |
| Spark Therapeutics |
| Sangamo Therapeutics |
| Bluebird Bio |
| Regeneron Pharmaceuticals |
| Biogen Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity reservation contracts with take-or-pay obligations lock in lentiviral vector access for integrated sponsors while exposing mid-cap developers to price volatility when spot purchases become necessary. These structures concentrate pricing power with Northeast corridor CDMOs serving Boston and Philadelphia academic medical centers, where FDA's 15-year post-marketing surveillance requirements inflate total cost of ownership for integrating vector programs.
Pricing Analysis
Industrial OEM buyers anchor value-based pricing structures that tie reimbursement to clinical outcomes in hematopoietic stem cell applications. Pricing stratifies across premium GMP-grade lentiviral vectors, standard research-use materials, and economy-tier plasmid DNA constructs, with FDA certification tier serving as the primary differentiation driver. Cost compression in standard-grade vectors is intensifying because suspension-based manufacturing platforms are collapsing per-dose production economics. Mid-cap biopharmaceutical developers exhibit highest price sensitivity due to capital constraints, while integrated sponsors with captive CDMO infrastructure demonstrate lowest sensitivity.
Supply Chain Analysis
The United States and Canada anchor North American vector manufacturing, with Mexico concentrating hospital administration infrastructure for patient-specific therapies. Critical raw material production draws from specialized European plasmid suppliers and domestic GMP cell culture media producers, creating trans-Atlantic dependency for lentiviral program inputs. Single-source vulnerability concentrates in plasmid DNA supply, where limited GMP facility count creates bottleneck risk for clinical-stage sponsors. Distribution runs through integrated delivery networks and specialty pharmacy channels serving academic medical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector manufacturing capacity cycles drive recovery timing, with suspension-based platform maturation compressing cost structures and reopening margin expansion for sponsors with installed production infrastructure.
For Market Incumbents: Fortify lentiviral supply chain control through backward integration into plasmid production or captive suspension bioreactor capacity in the Northeast corridor. Allogeneic cell therapy substitution threatens autologous program addressable markets, requiring incumbents to deepen CRISPR platform differentiation and secure long-term hospital procurement committee relationships before centralized purchasing fully consolidates. For New Entrants and Emerging Players: Anchor in Canadian parallel regulatory pathways coordinated with FDA through Health Canada scientific advice mechanisms, enabling synchronized North American development without redundant infrastructure investment. Central nervous system indications using adeno-associated viral vectors represent the most penetrable therapeutic territory, with limited competing modalities and favorable reimbursement architecture for monogenic neurological disorders. For Investors and Strategic Acquirers: CDMO-specialist mid-caps with established GMP viral production expertise and suspended manufacturing capabilities offer acquisition profiles aligned with capacity-constrained market dynamics. Long-term viability hinges on vector platform diversification beyond lentiviral dependence. The signal to watch is FDA guidance evolution on long-term follow-up requirements, which would reshape program economics and portfolio prioritization across the installed base.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | FDA's Regenerative Medicine Advanced Therapy designation compresses development timelines for qualifying vector programs. |
| Manufacturing Scale-Up | Suspension-based lentiviral production enables thousand-liter batch scales previously unattainable with adherent methods. |
| Pipeline Diversification | In vivo base editing convergence with lipid nanoparticle delivery expands addressable populations for metabolic disease correction. |
| Strategic Partnership | Health Canada and PMRA scientific advice coordination enables synchronized North American development strategies. |
| Reimbursement Strategy | Hospital procurement committee consolidation shifts negotiation leverage toward integrated delivery networks in Boston and Philadelphia. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with gene therapy development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists; and secondary validation against FDA filings, ClinicalTrials.gov records, Health Canada submissions, and GPO contract databases. Bottom-up vector demand modeling triangulated against top-down market sizing across therapeutic application and delivery method segments.
Across the projection horizon, the analytical framework modeled segmentation dimensions including vector platform type, end-user category, therapeutic application, and delivery method, with regional regulatory cluster as an additional industry-specific dimension. CAGRs derived from installed capacity trajectories, clinical trial enrollment velocity, and reimbursement pathway maturation. Forecast inputs incorporated vector manufacturing yield improvements and plasmid supply expansion timelines.
Decision-makers should treat outputs as directional under assumptions of sustained FDA accelerated approval pathway access and stable Health Canada coordination; material deviation in regulatory timelines or plasmid supply concentration would warrant model refresh. Recalibration cycles align with material shifts in vector manufacturing technology adoption and post-marketing surveillance guidance evolution.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
Global Gene Therapy Market
Cell & Gene Therapy
Global Viral Vector Vaccines Market
Cell & Gene Therapy
North America Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell Therapy Biomanufacturing Market
Cell & Gene Therapy
Cell Therapy Technologies Market
Cell & Gene Therapy
Leukapheresis Products Market
Cell & Gene Therapy
Europe Stem Cell Therapy Market
Cell & Gene Therapy
Global Tissue Regeneration Market
Cell & Gene Therapy
Cell Therapy Systems Market
Cell & Gene Therapy
Global Cell Based Immunotherapy Market
Cell & Gene Therapy
Nucleic Acid Therapeutics CDMO Market
Cell & Gene Therapy
Stem Cell Reconstructive Market
Cell & Gene Therapy
Regenerative Medicine Market
Cell & Gene Therapy
Animal Stem Cell Therapy Market
Cell & Gene Therapy
Global Lentiviral Vectors Market
Cell & Gene Therapy
Gene Therapy Products Market