
 Global Therapeutic Vaccines Market | 2026-2036
Global Therapeutic Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Therapeutic Vaccines Market Foresight
Project finance partnerships between biotech innovators and institutional investors is reshaping capital deployment across therapeutic vaccine development. Pfizer Inc. leverages its established oncology infrastructure to accelerate platform scale-up. Merck & Co., Inc. anchors its position through sustained R&D intensity in immune-oncology combinations. BioNTech SE specializes in mRNA-encoded neoantigen architectures that differentiate its pipeline from conventional approaches.
Therapeutic vaccines constitute biologically active immunological preparations designed to stimulate cell-mediated or humoral immune responses against established disease states, typically incorporating patient-specific or pathogen-derived antigens formulated with adjuvants or delivery vectors to achieve targeted immune modulation. These products function primarily to treat existing conditions rather than prevent infection, with manufacturing processes demanding cold-chain integrity and sterile fill-finish capabilities to preserve immunogenicity. Dendritic cell vaccines command premium positioning due to personalized manufacturing complexity and limited supplier base. Viral vector vaccines extend rapidly across oncology applications as lentiviral and adenoviral platforms demonstrate durable antigen expression. Peptide vaccines occupy niche indications where defined epitope targeting aligns with companion diagnostic strategies.
FDA's Center for Biologics Evaluation and Research and EMA's Committee for Medicinal Products for Human Use enforce divergent standards for autologous cell therapy manufacturing that complicate multi-territory registration strategies. ISO 14644 cleanroom classifications and WHO prequalification protocols further constrain production site selection and capacity expansion timelines. Stakeholders must monitor evolving FDA guidance on real-world evidence requirements for accelerated approvals while calibrating manufacturing investments against reimbursement uncertainty in European national health systems.
Market Dynamics
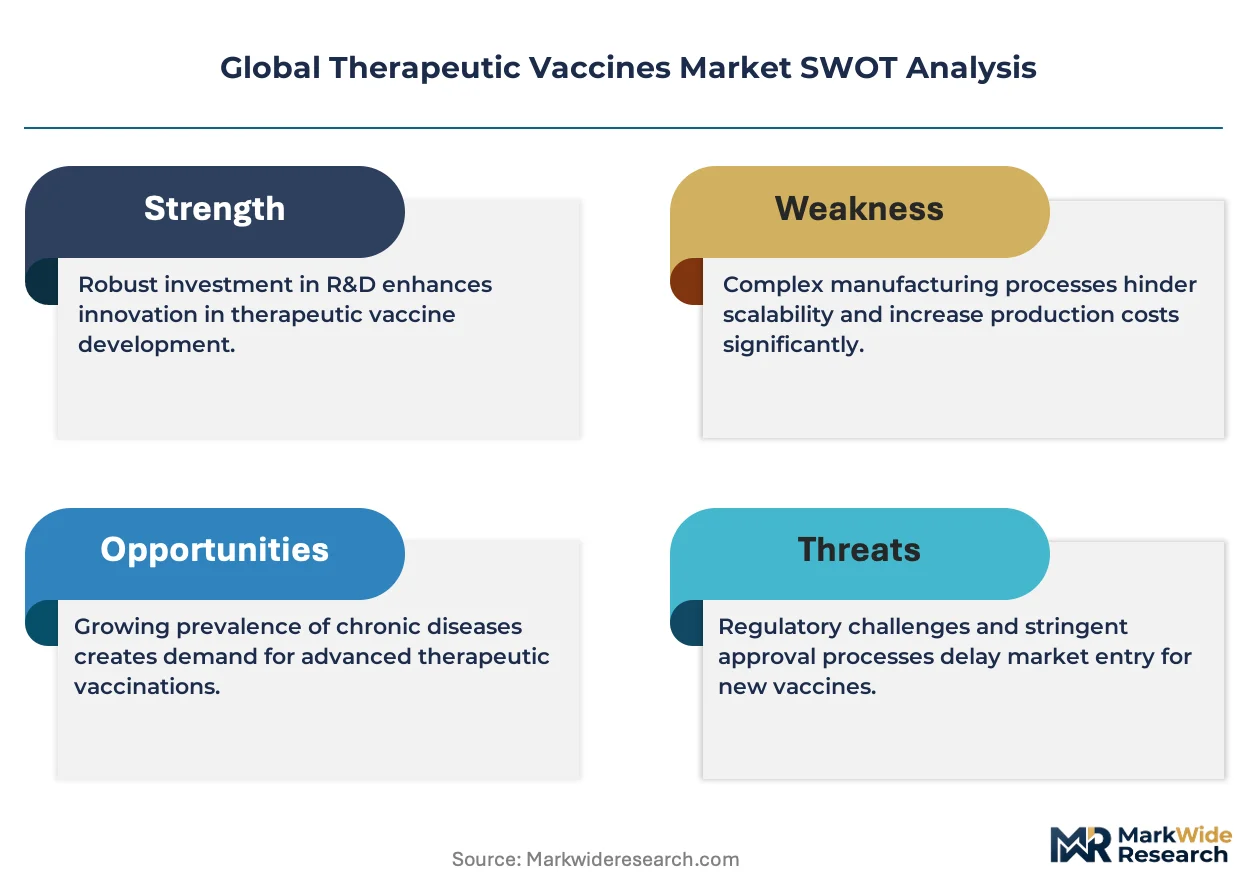
Platform specialization is fragmenting competitive advantage across the Global Therapeutic Vaccines Market, with mRNA-encoded neoantigen architectures, dendritic cell manufacturing, and viral vector delivery systems creating distinct capability moats that reshape capital allocation and partnership structures.
Growth Catalysts
- Immune-oncology combinations:Checkpoint inhibitor pairing protocols expand addressable patient populations beyond monotherapy responders. Academic medical centers in the United States prioritize combination trial enrollment.
- FDA accelerated approval pathways:Real-world evidence guidance enables earlier commercial entry for autologous cell therapies. Biologics license application timelines compress for breakthrough-designated candidates.
- Specialized infusion infrastructure:Germany and Japan deploy dedicated cellular therapy administration suites. Reimbursement frameworks align with site-of-care requirements.
Market Restraints
- Cold-chain integrity requirements:Liquid nitrogen storage and cryogenic transport constrain distribution reach. Temperature excursion risks limit site qualification for autologous products.
- EMA-FDA manufacturing divergence:Autologous cell therapy standards differ across jurisdictions. Multi-territory registration strategies face compliance complexity.
- Limited dendritic cell supplier base:Personalized manufacturing complexity concentrates production among specialized contract manufacturers. Capacity bottlenecks extend lead times.
Strategic Opportunities
- Infectious disease therapeutic applications:Chronic hepatitis B and HIV cure-directed vaccines represent underpenetrated indications. Clinical proof-of-concept data attracts non-oncology investors.
- Digital patient identification platforms:Biomarker-driven screening tools integrate with electronic health records. Health systems in Japan deploy predictive analytics for neoantigen eligibility.
- ISO 14644 cleanroom standardization:Harmonized classification protocols reduce multi-site qualification burden. Contract manufacturers achieve faster regulatory inspection readiness.
Industry Challenges
- Vector manufacturing scale-up:Lentiviral and adenoviral platform production requires dedicated bioreactor capacity. Viral titer consistency challenges plague process validation.
- Companion diagnostic co-development:Biomarker assay validation timelines frequently misalign with vaccine clinical programs. Synchronization failures delay regulatory submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Therapeutic Vaccines Market |
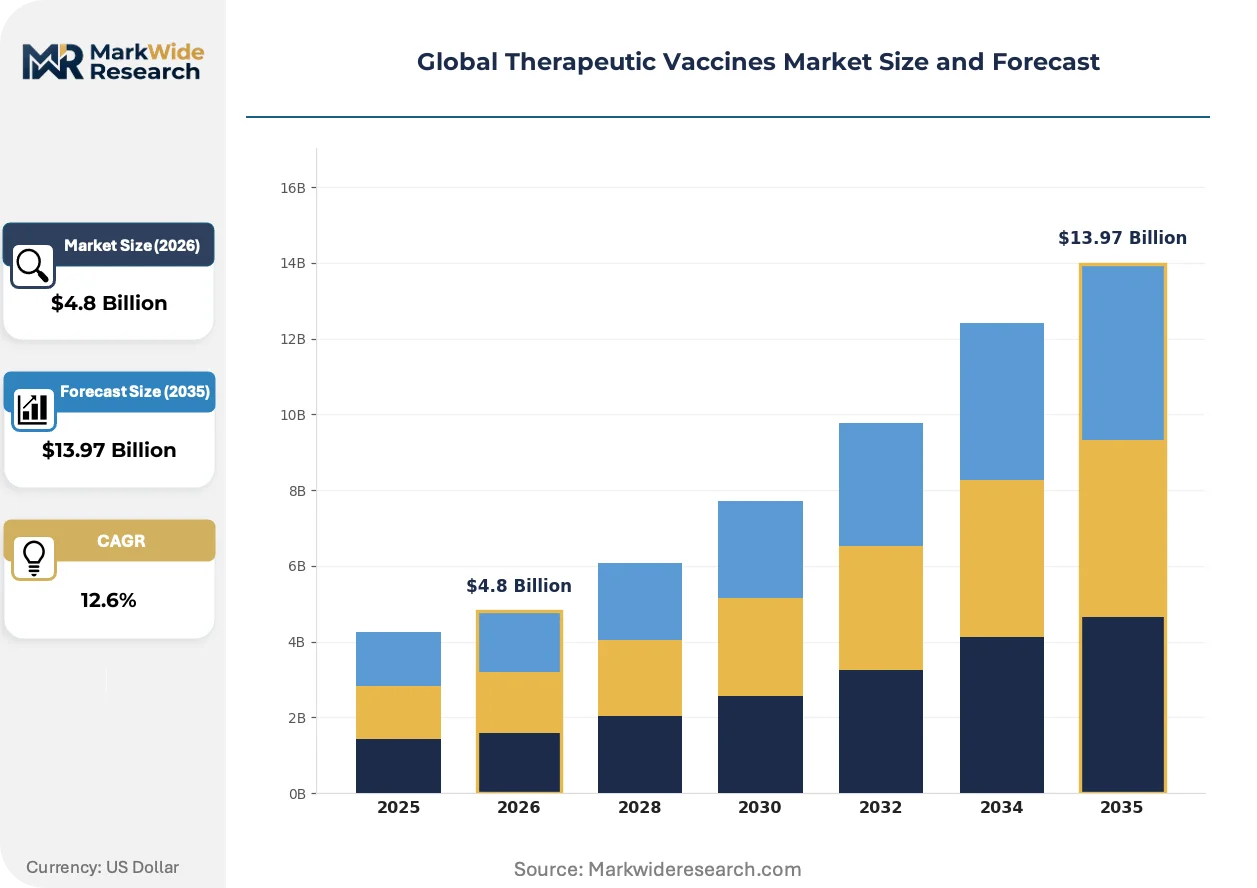
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DNA Vaccines, Peptide Vaccines, Dendritic Cell Vaccines, Viral Vector Vaccines, Protein Subunit Vaccines Therapy Area: Oncology, Infectious Diseases, Autoimmune Disorders, Neurological Diseases, Cardiovascular Disorders End User: Hospitals, Specialty Clinics, Research Institutes, Diagnostic Laboratories, Cancer Centers Delivery Mode: Intramuscular Injection, Subcutaneous Injection, Intradermal Injection, Intravenous Infusion, Oral Administration |
| Companies Covered | Novartis AG, Pfizer Inc., Merck & Co., Inc., GlaxoSmithKline plc, Agenus Inc., Bavarian Nordic A/S, BioNTech SE, Inovio Pharmaceuticals, Dendreon Corp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Therapeutic Vaccines Market Shifts & Advancements
Computational antigen prediction and automated manufacturing control systems are compressing development timelines while fragmenting traditional competitive boundaries between platform technologies.
Artificial intelligence-driven neoantigen selection algorithms are digitizing target identification workflows. Oncology biotech developers integrate machine learning pipelines with mass spectrometry data. This convergence compresses preclinical validation cycles and reduces animal model dependency.
EMA's evolving guidance on quality-by-design for advanced therapy medicinal products mandates enhanced process analytical technology deployment. Manufacturers retrofit legacy suites with in-line monitoring sensors. Viral vector producers in the Netherlands and Belgium face accelerated inspection schedules.
Hospital purchasing consortia are consolidating procurement authority for high-cost cellular therapies. Integrated delivery networks negotiate outcome-guaranteed contracts directly with manufacturers. This concentration is most visible in United States academic medical center systems.
Global Therapeutic Vaccines Market Segmentation
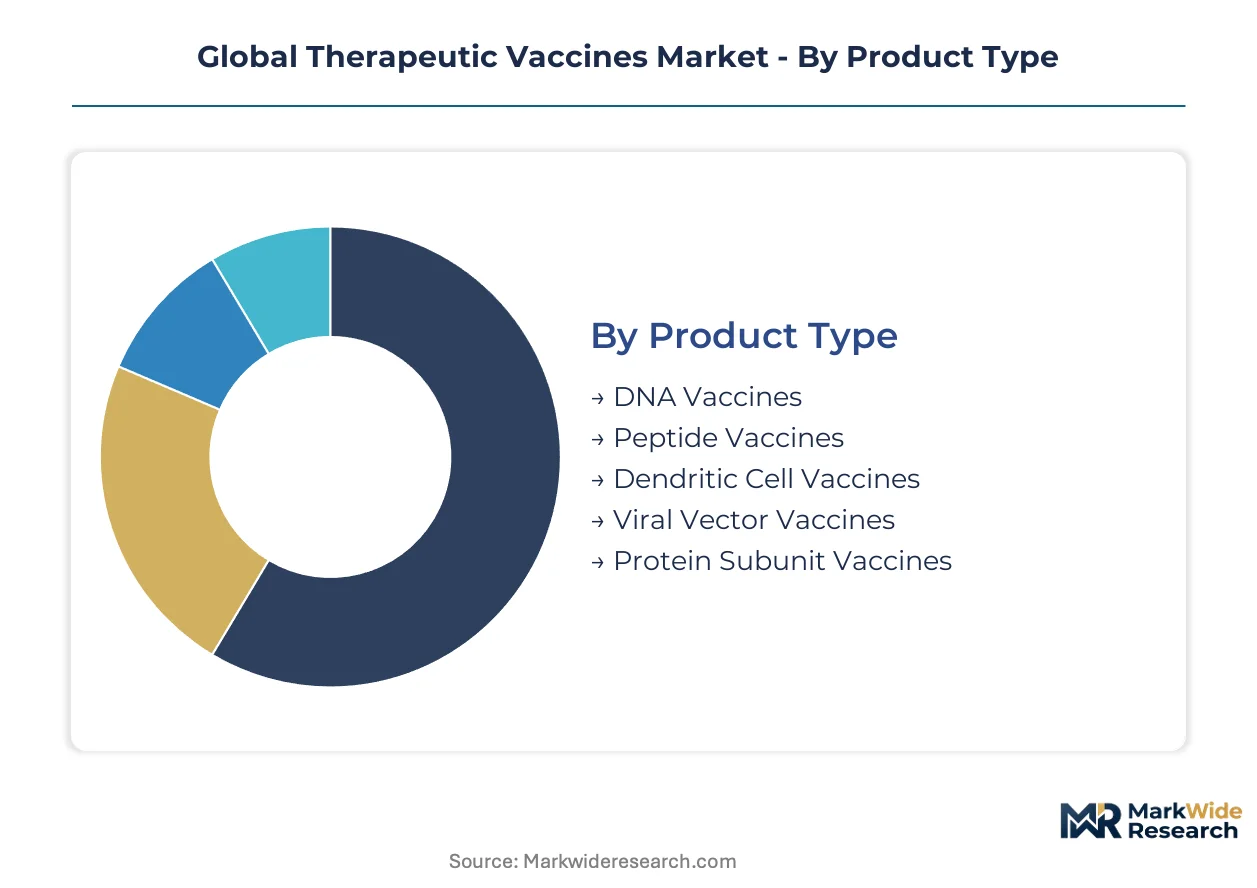
Therapeutic vaccine segmentation reveals distinct capability requirements across manufacturing platforms, clinical applications, and site-of-care infrastructure. Platform selection dictates cold-chain specifications, regulatory pathways, and reimbursement negotiations. Understanding segment boundaries enables targeted investment in specialized production assets and distribution partnerships.
Product Type:
Use-case spectrum spans preventive oncology maintenance through curative infectious disease intervention, with each platform demanding unique biomanufacturing competencies and patient logistics.
- Dendritic Cell Vaccines:Autologous cell processing requires patient-specific leukapheresis, ex vivo antigen loading, and cryopreserved infusion scheduling. Demand concentrates in United States academic medical centers where specialized apheresis units and cellular therapy suites justify premium reimbursement. FDA breakthrough therapy designation accelerates site qualification for autologous platforms.
- Viral Vector Vaccines:Lentiviral and adenoviral delivery systems enable durable antigen expression in dendritic cells and tumor microenvironments. Germany's Paul-Ehrlich-Institut has approved multiple viral vector manufacturing facilities, concentrating European supply in the Rhine-Main biotechnology cluster. EMA quality-by-design mandates drive process analytical technology investments.
- DNA Vaccines:Plasmid manufacturing scales through microbial fermentation with established purification protocols.
- Peptide Vaccines:Synthetic epitope production aligns with companion diagnostic strategies for defined patient populations.
- Protein Subunit Vaccines:Recombinant antigen expression leverages mammalian cell culture infrastructure from monoclonal antibody manufacturing.
Established volume favors viral vector platforms; emerging adoption favors dendritic cell personalization.
Therapy Area:
Cost tier stratification separates curative intent applications commanding premium pricing from chronic disease management programs with outcome-guaranteed contracts.
- Oncology:Neoantigen-directed therapies target solid tumors with checkpoint inhibitor combination protocols. Japan's Ministry of Health, Labour and Welfare expanded reimbursement for personalized cancer vaccines in designated cancer care hospitals. PMDA sakigake designation compresses review timelines for breakthrough oncology candidates.
- Infectious Diseases:Therapeutic vaccines for chronic hepatitis B and HIV pursue functional cure endpoints distinct from prophylactic approaches. Clinical proof-of-concept programs in France and the Netherlands attract non-oncology venture capital. ANSM early access pathways enable compassionate use authorization.
- Autoimmune Disorders:Tolerance-inducing antigen delivery targets rheumatoid arthritis and multiple sclerosis with distinct immunological mechanisms.
- Neurological Diseases:Alzheimer's and Parkinson's immunotherapies face blood-brain barrier delivery challenges limiting commercial viability.
- Cardiovascular Disorders:Atherosclerosis vaccines targeting oxidized LDL remain in early clinical development with unproven endpoints.
Oncology commands current revenue concentration; infectious disease applications are climbing the fastest toward commercial validation.
End User:
Customer type determines site qualification requirements, with infusion complexity and adverse event management capability filtering addressable provider networks.
- Cancer Centers:Comprehensive oncology units integrate apheresis, cellular processing, and immune monitoring in centralized facilities. United States National Cancer Institute-designated centers anchor demand for autologous dendritic cell therapies. Specialized nursing protocols manage cytokine release syndrome monitoring.
- Hospitals:General acute care settings administer viral vector and peptide vaccines through established pharmacy and infusion services. German hospital purchasing consortia negotiate outcome-based contracts for high-cost cellular therapies.
- Specialty Clinics:Focused immunology and infectious disease practices handle chronic disease therapeutic vaccination.
- Research Institutes:Academic centers conduct early-phase clinical trials with dedicated good manufacturing practice adjacent facilities.
- Diagnostic Laboratories:Companion diagnostic providers integrate biomarker testing with patient eligibility screening for personalized vaccine programs.
Site-of-care consolidation favors cancer centers; decentralized administration favors hospital infusion networks.
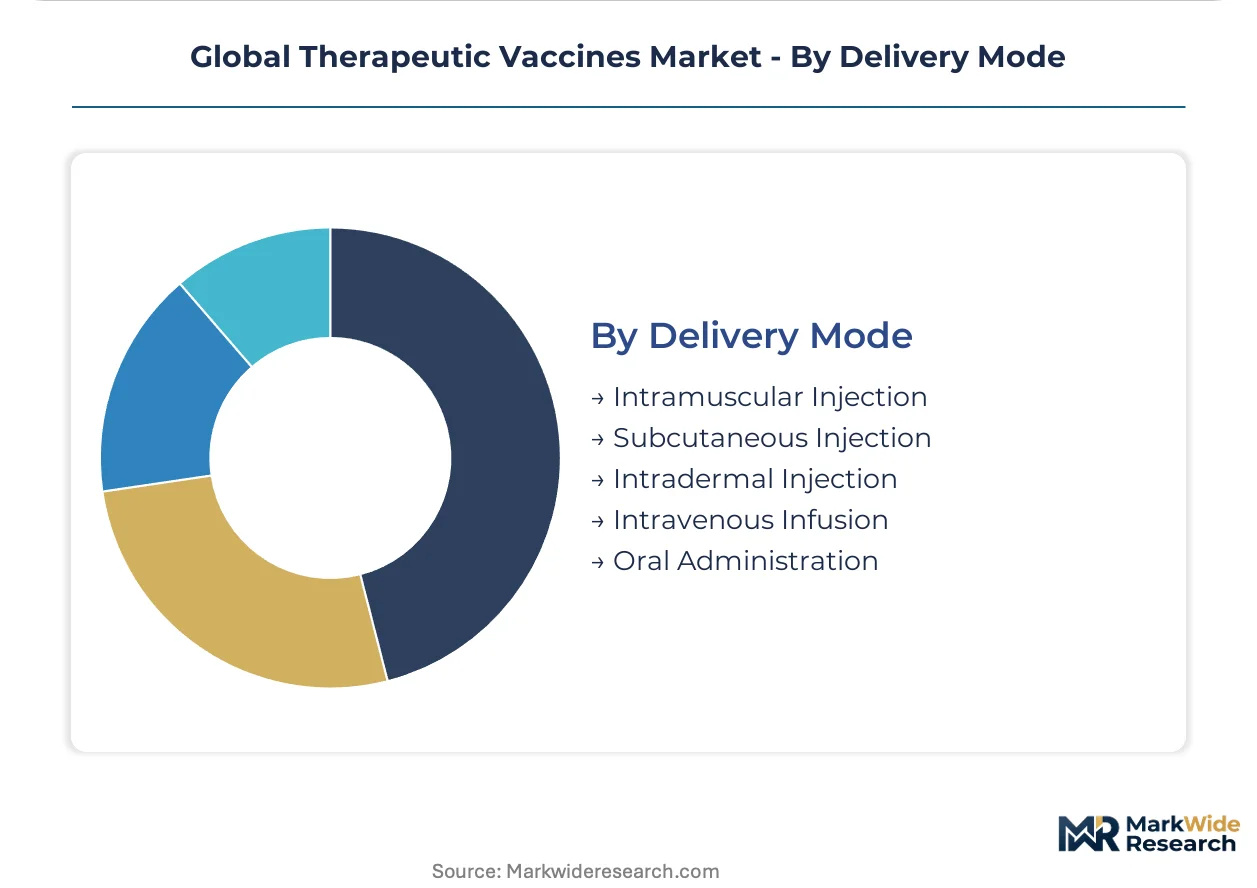
Delivery Mode:
Supply concentration varies by administration complexity, with intravenous platforms requiring specialized pharmacy preparation distinct from injection-based alternatives.
- Intravenous Infusion:Cellular therapy delivery demands controlled-rate administration with emergency response capability for infusion reactions. Japan's cancer care hospitals deploy dedicated cellular therapy suites with continuous monitoring infrastructure. METI reimbursement guidelines align site payments with infusion duration and complexity.
- Intramuscular Injection:Standard vaccine administration enables broad site qualification through existing immunization infrastructure. United States retail pharmacy networks and primary care practices extend reach for peptide and protein subunit candidates.
- Subcutaneous Injection:Self-administration potential reduces site-of-care burden for chronic disease maintenance protocols.
- Intradermal Injection:Specialized technique requirements limit administration to trained immunization centers.
- Oral Administration:mucosal delivery platforms remain experimental with unvalidated immunogenicity profiles.
Infusion complexity concentrates supply in specialized centers; injection simplicity enables primary care expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States maintains a substantial trade surplus in therapeutic vaccine intellectual property and platform technologies, while importing specialized viral vector manufacturing equipment from Germany and cryogenic logistics systems from Japan. Export licensing for autologous cell therapy protocols generates cross-border revenue streams concentrated in academic medical center networks.
United States
FDA breakthrough therapy designations for dendritic cell platforms drive clinical trial concentration in NCI-designated cancer centers. The Biologics License Application pathway compresses review timelines for personalized cancer vaccines. Boston's Longwood Medical Area anchors autologous processing infrastructure with integrated apheresis and cellular therapy suites.
Germany
Paul-Ehrlich-Institut approvals for lentiviral vector manufacturing concentrate European supply in the Rhine-Main biotechnology cluster. EMA quality-by-design mandates for advanced therapy medicinal products accelerate process analytical technology investments. Frankfurt's industrial corridor hosts dedicated cleanroom facilities serving cross-border clinical programs.
Japan
PMDA sakigake designation compresses regulatory review for oncology therapeutic vaccines in designated cancer care hospitals. METI reimbursement guidelines align site payments with infusion complexity and duration. Tokyo's Koto Ward concentration of cellular therapy administration suites supports premium pricing for autologous platforms.
Switzerland
Swissmedic's streamlined advanced therapy authorization attracts platform developers seeking rapid European market entry. Federal coordination between cantonal health systems enables standardized reimbursement for high-cost immunotherapies. Basel's pharmaceutical corridor integrates viral vector research with contract manufacturing capabilities.
United Kingdom
MHRA's post-Brexit recognition agreements with FDA and EMA facilitate multi-territory clinical trial designs for mRNA-encoded neoantigen candidates. NHS England's specialized commissioning framework concentrates cellular therapy delivery in designated treatment centers. London's Royal Marsden and Manchester's Christie Hospital anchor national autologous vaccine infrastructure.
Global Therapeutic Vaccines Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in vector production, adjuvant formulation, and cryogenic logistics. The market structure consolidates around three to five vertically integrated oncology developers while fragmenting across specialized contract manufacturers and diagnostic companion providers. Dominant archetypes include mRNA platform architects, dendritic cell personalization specialists, and viral vector production houses. Competitive moves center on capacity reservation agreements for lentiviral manufacturing slots and exclusive biomarker assay licensing for patient identification platforms.
Within the platform integrator tier, Pfizer Inc., Merck & Co., Inc., and BioNTech SE exemplify divergent strategic positioning. Pfizer leverages established oncology infrastructure for commercial scale-up. Merck anchors immune-oncology combination protocols through sustained R&D intensity. BioNTech occupies the mRNA-encoded neoantigen specialization with differentiated pipeline architectures. These three represent distinct capability moats that reshape partnership structures and capital allocation across the development landscape.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Merck & Co., Inc. |
| GlaxoSmithKline plc |
| Agenus Inc. |
| Bavarian Nordic A/S |
| BioNTech SE |
| Inovio Pharmaceuticals |
| Dendreon Corp |
| Others |
Supply & Pricing Matrix
Rhine-Main biotechnology cluster concentration for lentiviral vector manufacturing concentrates margin capture among German contract manufacturers serving cross-border oncology programs. Dendritic cell personalization complexity sustains premium positioning as limited supplier base constrains competitive entry. Cold-chain infrastructure investments in Japan and the United States further segment pricing power by site-of-care capability.
Pricing Analysis
Cancer centers anchor three-tier pricing structure across premium, standard, and economy levels for autologous cellular therapies. Price differentiation hinges on FDA breakthrough therapy designation status and companion diagnostic bundling. Cost compression in viral vector platforms intensifies as capacity expansion in Belgium and the Netherlands accelerates. Academic medical centers exhibit lowest price sensitivity due to specialized infusion infrastructure and outcome-guaranteed contracting.
Supply Chain Analysis
Upstream plasmid DNA and viral seed stocks draw from United States, Germany, and Belgium manufacturing bases. Production rests on cryogenic storage systems from Japan, specialized bioreactor equipment from Germany, and sterile fill-finish capacity concentrated in Switzerland and the Netherlands. Single-source vulnerability in dendritic cell apheresis collection centers constrains patient access. Distribution runs through hospital purchasing consortia and integrated delivery networks negotiating direct manufacturer contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Checkpoint inhibitor combination protocols pose substitution risk to monotherapy therapeutic vaccines as oncology treatment paradigms shift. Incumbents must navigate this threat through combination trial positioning and immune-oncology partnership structures.
For Market Incumbents: Entrench dendritic cell personalization capabilities through captive apheresis network expansion in NCI-designated centers. Secure exclusive biomarker assay licensing for patient identification platforms to lock out emerging mRNA platform competitors. FDA accelerated approval pathway expertise constitutes a defendable moat against late entrants lacking regulatory navigation experience.
For New Entrants and Emerging Players: Infectious disease therapeutic applications in France and the Netherlands offer geographic underpenetration with lower competitive density than oncology. Chronic hepatitis B functional cure endpoints attract non-oncology venture capital with distinct valuation frameworks. Digital patient identification platforms integrating electronic health records represent a service-layer entry angle bypassing manufacturing scale requirements.
For Investors and Strategic Acquirers: Capital is best deployed toward viral vector production houses with Paul-Ehrlich-Institut approval and established EMA quality-by-design compliance. Long-term viability in this market centers on platform integrators capable of spanning manufacturing scale-up through reimbursement negotiation. PMDA sakigake designation velocity serves as an inflection indicator for Japanese market access premium capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Checkpoint inhibitor combination protocols expand addressable populations beyond monotherapy responders. |
| Manufacturing Scale-Up | Lentiviral vector bioreactor capacity in Rhine-Main cluster serves cross-border European demand. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses biologics license application timelines for autologous platforms. |
| Pipeline Diversification | Infectious disease therapeutic vaccines for chronic hepatitis B attract non-oncology investor capital. |
| Licensing Agreement | Exclusive biomarker assay partnerships lock patient identification capability against emerging competitors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across this study. Primary interviews captured perspectives from oncology clinical trial investigators, cellular therapy manufacturing directors, hospital formulary directors, and payer access specialists. Secondary validation drew from FDA biologics license application filings, EMA advanced therapy medicinal product submissions, ClinicalTrials.gov protocol registries, and hospital procurement databases. Bottom-up patient population modeling and top-down platform revenue triangulation anchored market size estimation.
Calibration against historical approval timelines and site qualification patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include platform technology, therapy area, end-user facility type, and regional regulatory cluster. CAGRs were derived from patent expiration impacts, pipeline progression probabilities, and reimbursement expansion scenarios. Manufacturing capacity build-out schedules and cold-chain infrastructure investments served as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mRNA platform specialists or Asian contract manufacturers would shift outcomes. Cross-checking against FDA breakthrough therapy designation velocity and EMA quality-by-design inspection readiness is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cell & Gene Therapy
RNA Based Therapeutics and Vaccines Market
Cell & Gene Therapy
Lentiviral Vector Contract Development and Manufacturing Organizations Market
Cell & Gene Therapy
Oncolytic Virus Immunotherapy Market
Cell & Gene Therapy
CNS Specific Antisense Oligonucleotide Market
Cell & Gene Therapy
Automated and Closed Cell Therapy Processing Systems Market
Cell & Gene Therapy
North America Stem Cell Market
Cell & Gene Therapy
Rare Disease Gene Therapy Market
Cell & Gene Therapy
Gene Therapy Products Market
Cell & Gene Therapy
Global Gene Delivery Systems Market
Cell & Gene Therapy
Global Duchenne Muscular Dystrophy Treatment Market
Cell & Gene Therapy
Global Neoantigen Cancer Vaccine Market
Cell & Gene Therapy
Rheumatoid Arthritis Stem Cell Therapy Market
Cell & Gene Therapy
Europe Gene Therapy Market
Cell & Gene Therapy
RNA Therapy Clinical Trials Market
Cell & Gene Therapy
Global Cell and Gene Therapy Thawing Equipment Market
Cell & Gene Therapy
Cell and Gene Therapy Contract Development and Manufacturing Organization Market