
 Ocular Inserts Market | 2026-2036
Ocular Inserts Market Size, Share, and Industry Trends Forecast 2026-2036
Ocular Inserts Market Analysis
Consolidation among hospital purchasing groups is restructuring procurement patterns for ocular inserts across major health systems. Johnson & Johnson leverages its surgical ophthalmology footprint to sustain institutional contracts for therapeutic inserts. Alcon competes through direct distribution networks that anchor its presence in ambulatory surgical centers. Ocular Therapeutix specializes in bioresorbable formulations that differentiate its portfolio from conventional hydrogel alternatives.
Ocular inserts are solid or semisolid devices designed for placement on or within the eye, typically composed of silicone hydrogel, biodegradable polymers, or collagen matrices that enable controlled drug release over hours to months. These devices serve clinical purposes ranging from corneal hydration maintenance to sustained pharmaceutical delivery for chronic conditions. Drug delivery systems command premium positioning due to the technical complexity of achieving zero-order release kinetics for glaucoma and dry eye indications. Hydrogel-based contact lenses occupy the highest volume tier, while biodegradable polymer inserts represent the fastest-expanding material category as surgeons seek elimination-removal procedures.
The FDA maintains stringent premarket review pathways for combination drug-device ocular products, while the EMA's Medical Device Regulation imposes additional clinical evidence requirements on European market entrants. Japan's PMDA evaluates novel polymer compositions through dedicated consultation frameworks that extend development timelines but reduce post-approval risk. Stakeholders must monitor regulatory divergence between major agencies when designing multi-region clinical trial strategies and manufacturing scale-up plans.
Market Dynamics
Biodegradable polymer formulations are electrifying product development pipelines as manufacturers race to eliminate explant procedures and capture surgeon preference for single-intervention therapies.
Growth Catalysts
- EMA MDR compliance frameworks:European clinical evidence requirements for combination products are accelerating investment in robust trial infrastructure among established manufacturers.
- Glaucoma surgical suites:Ambulatory surgical centers are expanding sustained-release insert utilization to reduce post-operative medication burden and improve adherence metrics.
- Silicone hydrogel chemistry:Advances in oxygen permeability and drug-loading capacity are extending wear time for therapeutic contact lenses beyond conventional limits.
Market Restraints
- Polymer raw material concentration:Specialty biodegradable polymer supply chains cluster among a limited set of European chemical suppliers, creating input vulnerability.
- FDA combination product pathway complexity:Premarket review timelines for drug-device ocular inserts extend development cycles and compress effective patent life.
- Topical drop substitution:Generic prostaglandin analogs and preservative-free formulations retain cost advantage for early-stage glaucoma management.
Strategic Opportunities
- Japan PMDA consultation frameworks:Dedicated polymer evaluation pathways reduce post-approval risk for novel compositions, incentivizing first-molecule development.
- Retinal disease applications:Anti-VEGF sustained-release inserts for age-related macular degeneration represent an underdeveloped therapeutic category with significant unmet need.
- Direct-to-clinic distribution:Bypassing wholesale distributors for ambulatory surgical center accounts improves margin capture and inventory visibility.
Industry Challenges
- Biocompatibility testing capacity:ISO 10993 cytotoxicity and sensitization studies face bottlenecks at specialized contract research organizations, delaying submission timelines.
- Surgeon training standardization:Insert placement techniques vary across cornea, conjunctival fornix, and intracanalicular approaches, complicating clinical trial endpoint consistency.
- Legacy sterilization validation:Ethylene oxide and gamma irradiation protocols for novel polymer matrices require extensive dose-mapping studies that extend quality assurance cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ocular Inserts Market |
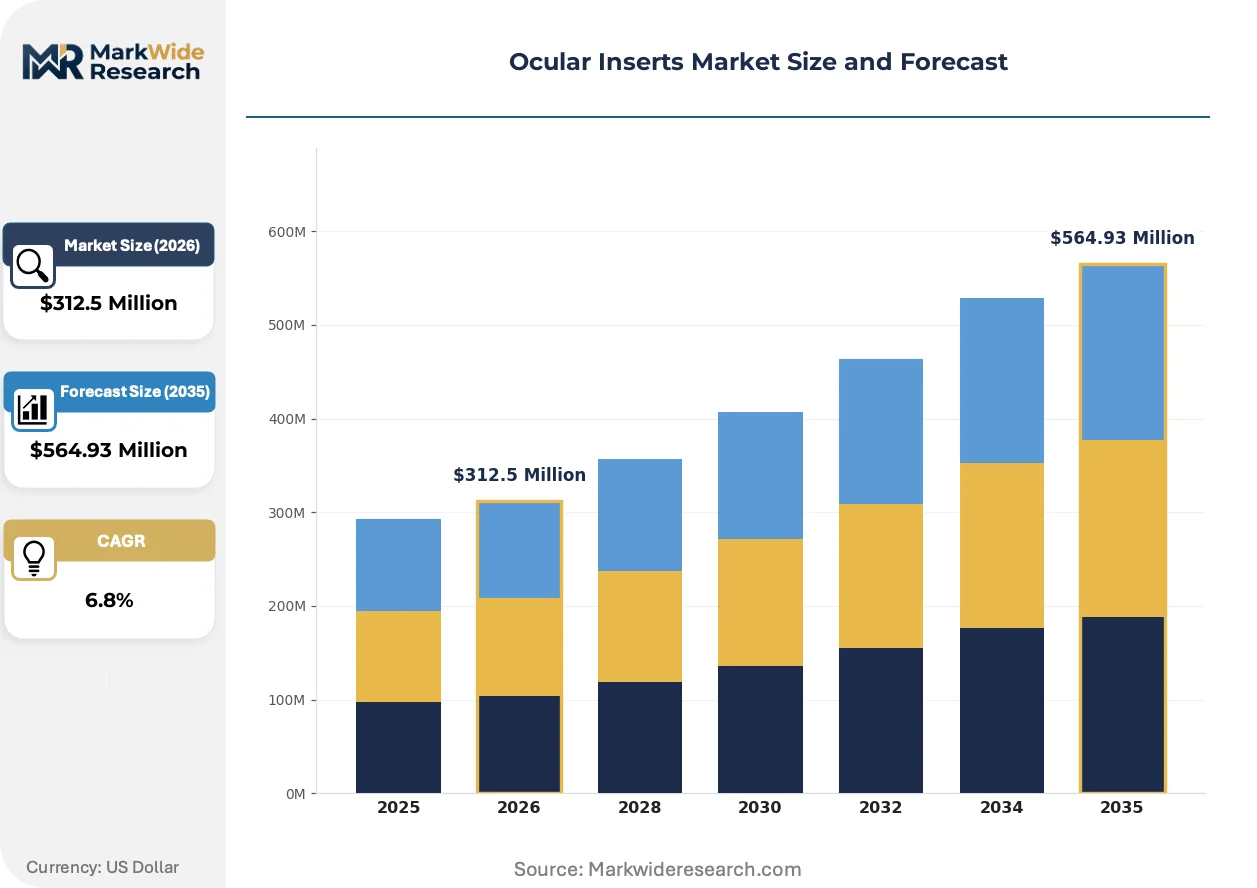
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contact Lenses, Therapeutic Inserts, Drug Delivery Systems, Diagnostic Inserts Indication: Dry Eye Disease, Glaucoma, Allergies, Infection End User: Hospitals, Clinics, Retail Pharmacies, Homecare Material: Silicone Hydrogel, Hydrogels, Biodegradable Polymers, Others |
| Companies Covered | Johnson & Johnson, Abbott, Ocular Therapeutix, Santen Pharmaceutical, EyePoint Pharmaceuticals, Bausch + Lomb, Alcon, Glaukos Corporation, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ocular Inserts Market Emerging Trajectories
Zero-order release kinetics engineering is compressing competitive differentiation as manufacturers pursue flat plasma concentration curves that eliminate peak-trough variability in chronic ophthalmic therapy.
Electrospun nanofiber matrices are electrifying controlled-release architecture by enabling tunable porosity and surface-area-to-volume ratios that surpass conventional hydrogel limitations. Ophthalmology clinics in the United States are piloting these formulations for post-surgical anti-inflammatory delivery. The technology is electrifying surgeon preference by reducing dosing frequency from multiple daily instillations to single-insert interventions.
Japan's PMDA has implemented dedicated consultation frameworks for novel polymer compositions that extend pre-submission timelines but reduce post-market surveillance obligations. European manufacturers are leveraging these pathways to access Asian markets with reduced regulatory duplication. Bioresorbable insert developers are responding by prioritizing PMDA-aligned toxicology packages in early-phase development.
Hospital purchasing group consolidation is compressing vendor rosters as integrated delivery networks demand single-source contracts for ophthalmic surgical supplies. Ambulatory surgical centers are displacing independent procurement with centralized distribution agreements. This concentration is most visible in the United States, where three major group purchasing organizations control substantial volume across cataract and glaucoma procedure suites.
Ocular Inserts Market Segmentation
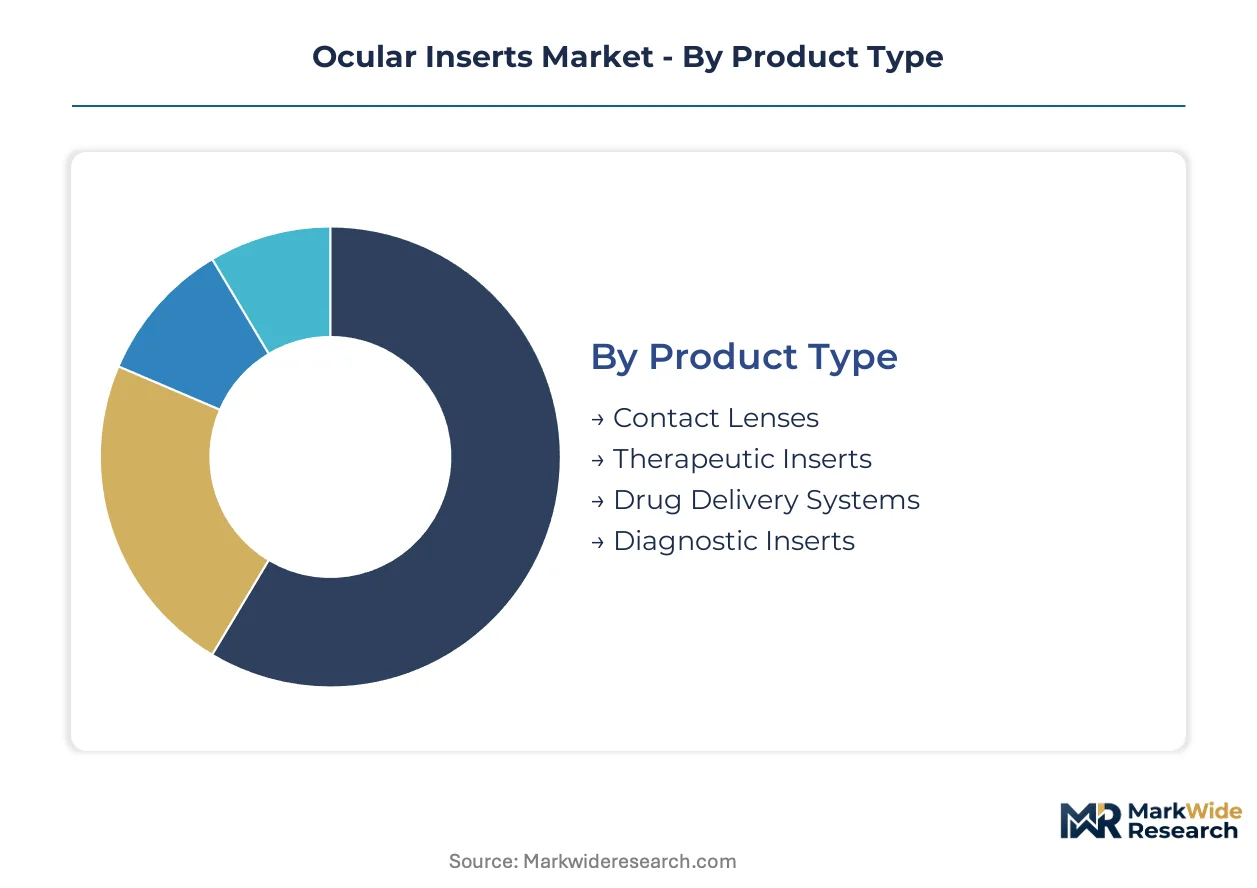
Product differentiation in ocular inserts hinges on regulatory pathway complexity and material biocompatibility requirements. Each segment carries distinct FDA combination product classifications or EMA MDR compliance burdens that reshape development timelines and commercialization strategies.
Product Type:
FDA premarket review intensity varies sharply across this category, with drug-device combinations triggering lengthier approval cycles than standalone diagnostic or therapeutic devices.
- Contact Lenses:Silicone hydrogel formulations dominate commercial volume through extended wear indications and oxygen permeability advances. United States ambulatory surgical centers drive demand for therapeutic lens protocols that reduce post-operative drop regimens.
- Drug Delivery Systems:Zero-order release kinetics engineering enables sustained pharmaceutical delivery for chronic ophthalmic conditions. Glaucoma management suites in the United States are expanding utilization to improve patient adherence metrics and reduce medication burden.
- Therapeutic Inserts:Bioresorbable formulations eliminate explant procedures for corneal hydration maintenance.
- Diagnostic Inserts:Tear film analysis devices support point-of-care testing in ophthalmology clinics.
Leading the category by volume: Contact Lenses. Expanding most quickly: Drug Delivery Systems.
Indication:
Reimbursement access and disease prevalence create divergent margin profiles across therapeutic applications.
- Glaucoma:Sustained-release inserts target intraocular pressure reduction through prostaglandin analog or beta-blocker elution. United States Medicare coverage for minimally invasive glaucoma surgeries supports procedure volume expansion in hospital outpatient departments.
- Dry Eye Disease:Hydrogel-based inserts address tear film instability through punctal occlusion or surface lubrication. Prescription dry eye therapeutics command premium positioning against over-the-counter artificial tear substitutes.
- Allergies:Antihistamine-eluting inserts target seasonal allergic conjunctivitis with reduced dosing frequency.
- Infection:Antimicrobial-loaded devices support post-surgical prophylaxis in cataract procedure suites.
Widest reimbursement coverage: Glaucoma. Steepest expansion trajectory: Dry Eye Disease.
End User:
Procurement concentration and inventory management requirements fragment distribution economics across care settings.
- Hospitals:Integrated delivery network contracts consolidate purchasing for surgical ophthalmology departments. Group purchasing organization aggregation compresses vendor rosters and demands single-source agreements for implantable devices.
- Clinics:Ambulatory surgical centers prioritize direct-to-clinic distribution models that bypass wholesale markups. Specialty ophthalmology practices in the United States drive adoption of sustained-release inserts for chronic disease management.
- Retail Pharmacies:Over-the-counter therapeutic lenses and lubricating inserts serve self-directed dry eye management.
- Homecare:Patient-administered punctal plugs and collagen shields support post-operative recovery protocols.
Highest procedure value concentration: Hospitals. Fastest channel growth: Clinics.
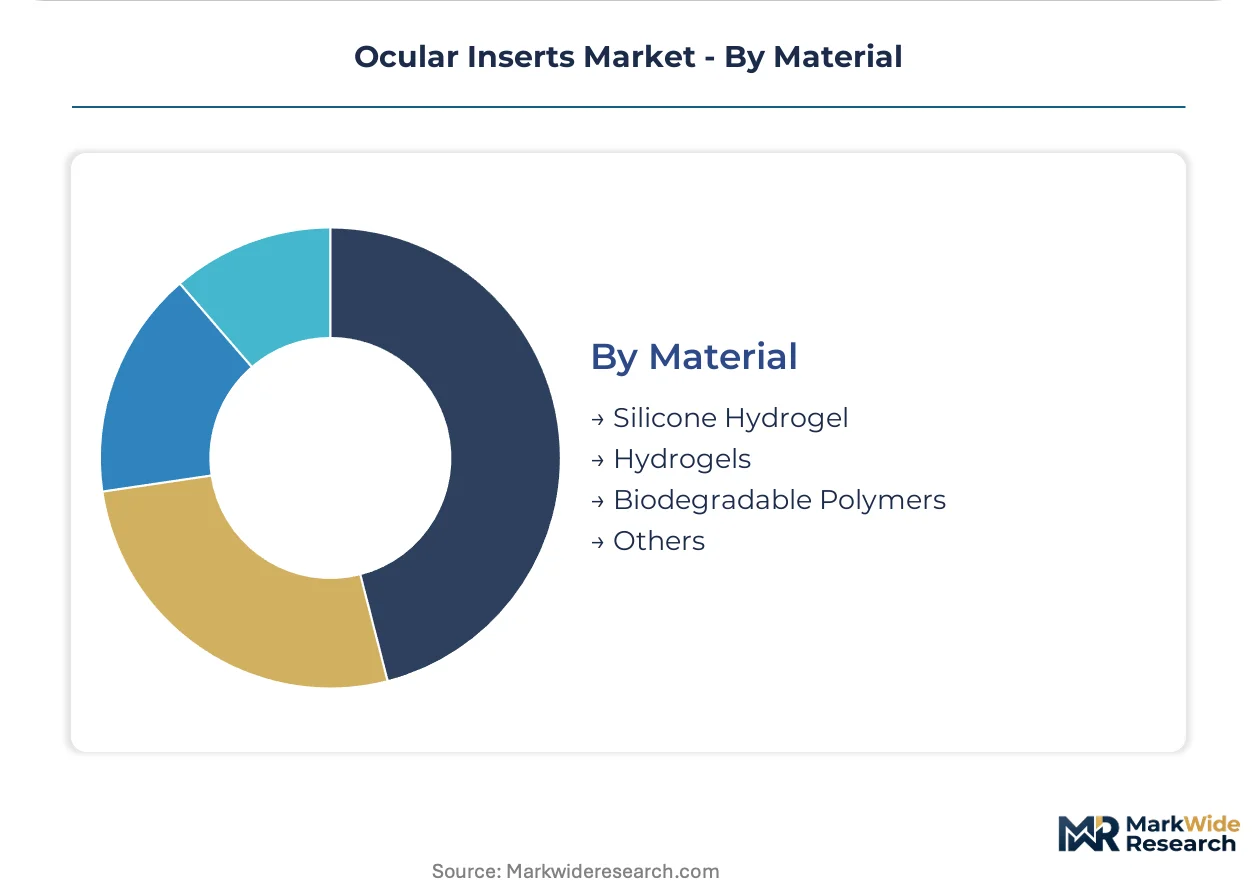
Material:
Supply chain vulnerability and sterilization validation complexity differentiate input categories.
- Biodegradable Polymers:Polylactic acid and polyglycolic acid compositions enable complete resorption without explantation. European chemical suppliers concentrate specialty polymer production, creating input bottlenecks for device manufacturers.
- Silicone Hydrogel:High oxygen permeability supports extended wear therapeutic applications. Japan's PMDA maintains dedicated consultation frameworks for novel silicone formulations that extend pre-submission timelines.
- Hydrogels:Collagen and synthetic hydrogel matrices dominate punctal plug and bandage lens segments.
- Others:Proprietary polymer blends target niche indications with customized release profiles.
Dominant by commercial volume: Silicone Hydrogel. Gaining share fastest: Biodegradable Polymers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty biodegradable polymer production concentrates in European chemical clusters, while demand for sustained-release ocular inserts expands fastest in aging populations with established reimbursement infrastructure.
United States
Medicare coverage for minimally invasive glaucoma surgeries drives sustained-release insert adoption in hospital outpatient departments. The FDA maintains stringent premarket review pathways for combination drug-device products, extending development timelines for novel formulations. The Boston-Cambridge corridor anchors bioresorbable polymer R&D, with multiple device manufacturers locating toxicology and clinical operations near specialized contract research organizations.
Germany
EMA MDR compliance frameworks accelerate investment in robust clinical trial infrastructure among established manufacturers. The country's national pharmaceutical regulator enforces additional evidence requirements on combination product market entrants. The Rhine-Ruhr industrial basin concentrates specialty polymer chemical production, creating supply chain leverage for device manufacturers sourcing polylactic acid and polyglycolic acid inputs.
Japan
Aging demographics and high procedure volumes support premium positioning for zero-order release drug delivery systems. PMDA consultation frameworks for novel polymer compositions extend pre-submission timelines but reduce post-market surveillance obligations. The Kansai region around Osaka hosts specialized ophthalmology device manufacturing clusters serving domestic and export markets.
Switzerland
Premium pricing for therapeutic inserts aligns with the country's sophisticated hospital procurement systems and strong reimbursement for innovative ophthalmic interventions. Swissmedic evaluates combination products through streamlined pathways that leverage prior EMA assessments. The Basel-Zurich corridor concentrates pharmaceutical-device hybrid development capabilities.
India
Expanding private ophthalmology clinic networks create demand for cost-optimized punctal plugs and bandage lenses. CDSCO regulatory pathways for imported medical devices require local clinical bridging studies, extending market entry timelines. The Mumbai-Pune pharmaceutical manufacturing belt attracts contract manufacturing organizations serving multinational device companies.
Ocular Inserts Market Vendor Landscape
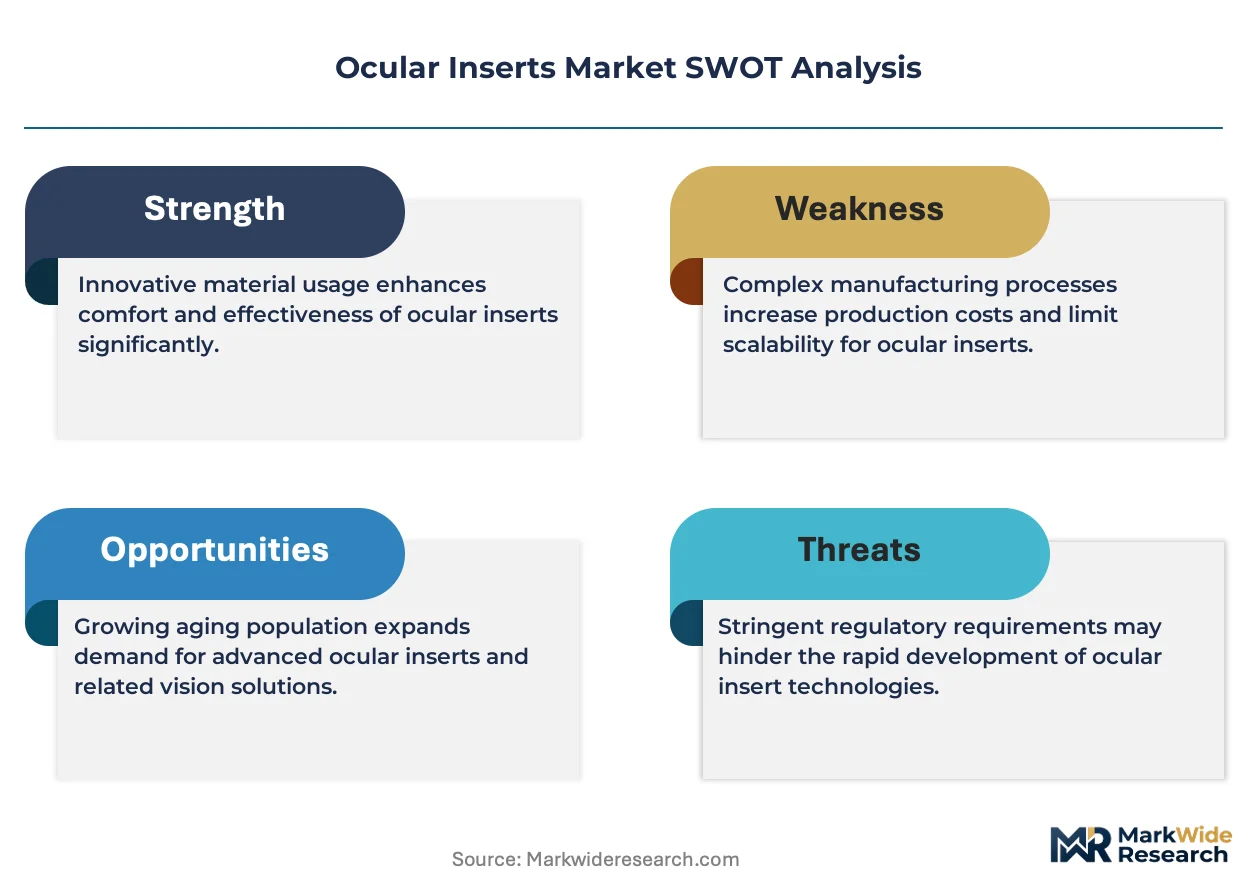
Established producers occupy the standard tier; emerging entrants pursue bioresorbable formulations and electrospun nanofiber architectures. The market exhibits moderate consolidation, with surgical ophthalmology incumbents leveraging institutional contracts against specialized device innovators. Three archetypes dominate: diversified healthcare conglomerates with surgical footprints, dedicated ophthalmology device specialists, and polymer chemistry innovators. Competitive dynamics center on M&A activity to acquire novel release-kinetics platforms and strategic partnerships with European chemical suppliers to secure biodegradable polymer feedstocks.
Among diversified healthcare conglomerates, Johnson & Johnson and Abbott occupy positions that exemplify the institutional-contract archetype, anchoring presence across hospital purchasing group networks. Alcon represents the pure-play ophthalmology device specialist, while Ocular Therapeutix sits within the polymer-innovation tier focused on bioresorbable differentiation.
| Leading Market Players |
|---|
| Johnson & Johnson |
| Abbott |
| Ocular Therapeutix |
| Santen Pharmaceutical |
| EyePoint Pharmaceuticals |
| Bausch + Lomb |
| Alcon |
| Glaukos Corporation |
| Novartis |
| Others |
Supply Flow & Price Mechanics
Polylactic acid resin pricing indices cascade through ocular insert manufacturing tiers, compressing margins for standard hydrogel producers while insulating bioresorbable specialists with polymer chemistry control.
Pricing Analysis
Warranty and explant-procedure bundling separates premium biodegradable polymer inserts from unbundled conventional alternatives requiring surgical retrieval. Three-tier pricing structure across premium, standard, and economy levels reflects FDA combination product pathway complexity and sterilization validation burden. Price differentiation hinges on certification tier and surgeon training support inclusion. Cost compression in economy hydrogel segments intensifies because generic topical drop substitution erodes volume. Ambulatory surgical centers exhibit highest price sensitivity; hospital purchasing groups anchored by Johnson & Johnson and Alcon contracts show lowest.
Supply Chain Analysis
Explant return flows and biodegradable polymer resorption validation create reverse-logistics complexity absent in conventional silicone hydrogel supply chains. Specialty chemical production concentrates in Germany, Switzerland, and the Netherlands, with Rhine-Ruhr and Basel-Zurich clusters dominating polylactic acid and polyglycolic acid feedstock. Raw material dependencies rest on European chemical suppliers for biodegradable polymers, Japanese silicone refiners for hydrogel oxygen permeability enhancement, and US-based collagen processors for punctal plug matrices. Single-source vulnerability in European specialty polymer supply chains threatens input security for bioresorbable insert developers. Distribution runs through hospital purchasing organization consolidation and direct-to-clinic ambulatory surgical center channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ocular inserts occupy a material-transition inflection as biodegradable polymers displace explant-dependent silicone hydrogel legacy platforms.
For Market Incumbents: Deepen backward integration into European specialty polymer supply chains to secure polylactic acid and polyglycolic acid feedstock against single-source concentration risk. Anchor hospital purchasing organization contracts through bundled surgeon training and explant-procedure warranty coverage. Fortify positions against Ocular Therapeutix and electrospun nanofiber entrants by accelerating ISO 10993 biocompatibility testing capacity investment. For New Entrants and Emerging Players: Launch via direct-to-clinic distribution targeting ambulatory surgical centers bypassing consolidated hospital purchasing group vendor rosters. Prioritize Japan PMDA consultation pathways for novel polymer compositions to reduce post-market surveillance burden and accelerate Asian market access. White-space targets include retinal disease anti-VEGF sustained-release applications and cost-optimized punctal plugs for India private clinic networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor bioresorbable polymer innovators with PMDA-aligned toxicology packages in the Boston-Cambridge corridor and Kansai manufacturing clusters. Long-term viability over the next decade hinges on elimination of explant procedures and zero-order release kinetics platform ownership. Monitor FDA combination product review timeline compression and EMA MDR clinical evidence requirement harmonization as inflection indicators for valuation multiple expansion.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Polymer Consultation Pathway | Reduces post-market surveillance obligations for novel biodegradable compositions entering Japan. |
| Direct-to-Clinic Distribution | Bypasses wholesale markups for ambulatory surgical center accounts in United States markets. |
| Biocompatibility Testing Capacity Expansion | Addresses ISO 10993 study bottlenecks at specialized contract research organizations. |
| Electrospun Nanofiber Platform Acquisition | Captures tunable porosity architectures surpassing conventional hydrogel release limitations. |
| Hospital Purchasing Organization Contract Anchoring | Secures volume commitments through integrated delivery network single-source agreements. |
Methodological Framework
Document review covered FDA 510(k) and PMA filings, EMA MDR technical documentation, PMDA consultation framework guidance, and ClinicalTrials.gov ocular insert protocols, complemented by interviews with ophthalmology device regulatory affairs leads, ambulatory surgical center procurement managers, group purchasing organization contract directors, and biodegradable polymer chemical supply specialists. Secondary validation drew from hospital procurement databases, CMS Medicare reimbursement schedules, and SEC 10-K ophthalmology segment disclosures. Bottom-up demand modeling and top-down supply capacity estimates underwent cross-referencing triangulation.
Historical FDA review timeline patterns and expert panel input on polymer innovation trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions encompassed product type, indication, end user, and material composition alongside regional regulatory pathway cluster differentiation. CAGRs derived from procedure volume elasticity to reimbursement access and surgeon adoption curve modeling for sustained-release technologies. Forecast inputs incorporated EMA MDR compliance cost escalation and Japan aging demographic procedure volume projections.
The model assumes a particular technology adoption path; alternative pathways for electrospun nanofiber matrices or topical gene therapy would alter the outlook substantially. Forecasts reflect embedded assumptions regarding FDA combination product review efficiency and European polymer supply chain stability. Practitioners should monitor PMDA consultation framework expansion, EMA MDR harmonization progress, and biodegradable polymer raw material price volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Asia-Pacific Glaucoma Treatment Market
Ophthalmology
Retinal Detachment Market
Ophthalmology
Blue Light Blocking Contact Lenses Market
Ophthalmology
Macular Edema Treatment Market
Ophthalmology
Trachoma Treatment Market
Ophthalmology
Diabetic Retinopathy Treatment Market
Ophthalmology
Leber Congenital Amaurosis Market
Ophthalmology
Vision Care Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Global Diabetic Macular Edema Market
Ophthalmology
Ophthalmic Lasers Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Cataract Treatment Market
Ophthalmology
Ophthalmic Disease Therapeutics Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
Global Ocular Inflammation Treatment Market