
 Global Aphakia Market | 2026-2036
Global Aphakia Market Size, Share, and Industry Trends Forecast 2026-2036
Global Aphakia Market Foresight
The EU Medical Device Regulation is expanding compliance burdens for intraocular lens manufacturers seeking CE marking access across European markets. ZEISS International leverages its precision optics heritage to sustain premium positioning in customizable IOL development. Alcon Inc. dominates the foldable IOL segment through manufacturing scale and surgeon training ecosystems. Johnson & Johnson Services, Inc. competes across the full cataract workflow, anchoring its position in phacoemulsification systems and disposable instrumentation.
Aphakia denotes the absence of the crystalline lens from the eye, whether from surgical extraction, trauma, or congenital failure of lens development, with optical correction requiring implanted or external lens substitutes that restore refractive power to approximately 20 diopters. Intraocular lenses command the largest product value pool due to permanent implantation and premium technology tiers, while contact lenses retain significant volume among patients contraindicated for surgery. Multifocal IOL technology leads growth within the technology dimension as presbyopia-correcting designs displace monofocal standards in paid segments, though toric IOLs occupy the strongest margin position through astigmatism management protocols.
FDA premarket approval pathways and the EU MDR clinical evidence requirements shape product development timelines and market entry costs for manufacturers. Japan's PMDA enforces stringent biocompatibility standards that filter subscale competitors from its high-value ophthalmology market. Stakeholders must monitor evolving reimbursement thresholds for premium IOL technologies across national health systems as these determinations directly reshape accessible patient volumes and manufacturer pricing authority.
Market Dynamics
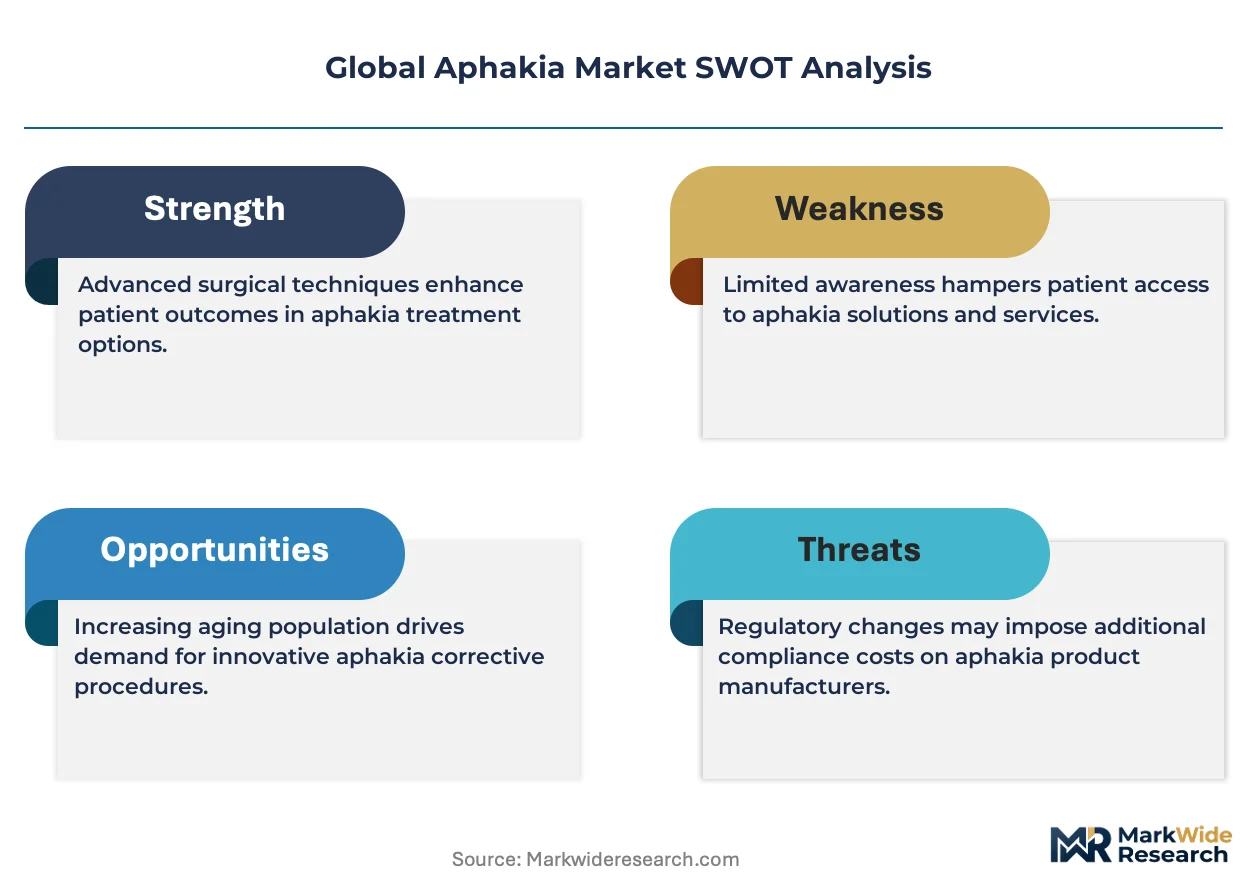
The foldable intraocular lens technology wave is compressing procedural recovery windows while expanding ambulatory surgical center eligibility criteria, fundamentally restructuring where aphakia correction occurs and who performs it.
Growth Catalysts
- EU MDR compliance pathways:The Medical Device Regulation's tightened clinical evidence requirements for CE marking is filtering out marginal competitors and concentrating volume among established manufacturers with robust quality management systems.
- Presbyopia-correcting IOL designs:Multifocal and extended depth-of-focus lens platforms are expanding addressable patient pools beyond traditional monofocal candidates into the 45-60 age bracket seeking spectacle independence.
- Japan's aging surgical population:PMDA's streamlined biocompatibility review processes for predicate devices is accelerating market entry timelines for incremental IOL innovations in the world's most aged major economy.
Market Restraints
- Silicone oil and acrylic polymer input volatility:Specialized optical-grade polymers face petrochemical feedstock price swings that compress IOL manufacturing margins without corresponding pricing flexibility in contracted hospital procurement.
- Single-source supply concentration:High-precision lathe and milling equipment for IOL manufacturing concentrates among German and Swiss machine tool suppliers, creating geographic chokepoints for capacity expansion.
- Posterior capsular opacification limitation:Secondary cataract formation rates following IOL implantation necessitate Nd:YAG laser capsulotomy procedures that erode long-term cost-effectiveness claims against contact lens alternatives.
Strategic Opportunities
- India's tier-2 and tier-3 city expansion:Underpenetrated secondary urban centers with emerging ophthalmology infrastructure present volume growth corridors as domestic surgical training capacity expands.
- Teleophthalmology screening integration:Remote diagnostic platforms are converging with AI-powered cataract grading to identify surgical candidates earlier in disease progression, compressing time-to-treatment intervals.
- US Medicare Advantage premium IOL carve-outs:Supplemental benefit structures in managed care plans are creating reimbursement tailwinds for presbyopia-correcting and toric IOL categories outside traditional fee-for-service constraints.
Industry Challenges
- Micro-incision cataract surgery skill certification:The 2.2mm and smaller incision techniques require specialized training pathways that outpace current fellowship program output, creating surgeon capacity bottlenecks.
- ISO 11979 biocompatibility testing timelines:Extended preclinical evaluation periods for novel lens materials delay product launches by 18-36 months relative to predicate device pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Aphakia Market |
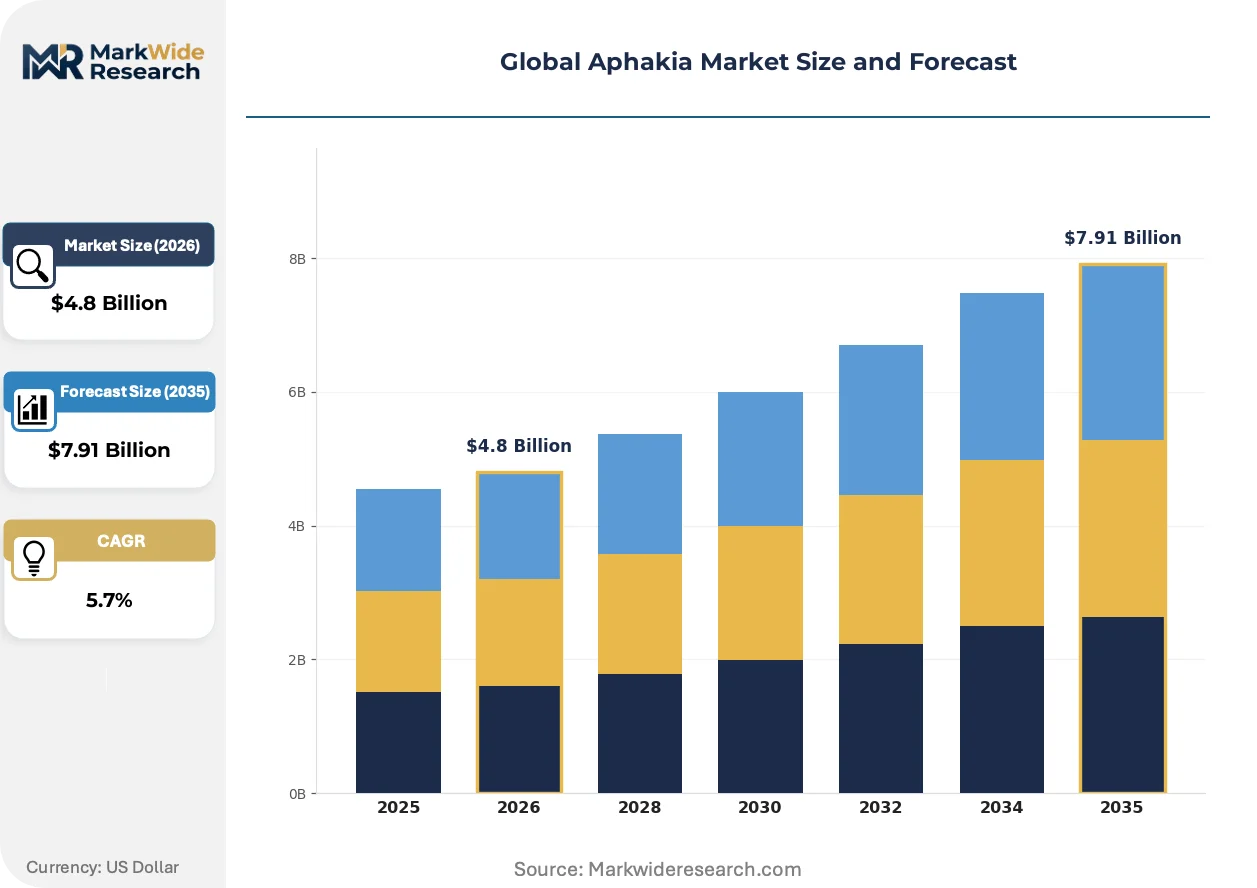
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Contact Lenses, Spectacles, Surgical Instruments Application: Cataract Surgery, Traumatic Lens Removal, Congenital Lens Absence, Secondary Lens Implantation End User: Eye Care Clinics, Ambulatory Surgical Centers, Specialized Ophthalmology Hospitals, Optical Retailers Technology: Foldable IOL, Rigid IOL, Multifocal IOL, Toric IOL, Customizable IOL |
| Companies Covered | ZEISS International, The Cooper Companies Inc., Johnson & Johnson Services, Inc., Novartis, Ophtec BV, Alcon Inc., Rayner, Abbott, Bausch + Lomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Aphakia Market Shifts & Advancements
Digital surgical planning platforms and femtosecond laser integration are recalibrating the precision-to-cost equation in aphakia correction, while patient-specific IOL customization is shifting competitive advantage from manufacturing scale to optical design software capabilities.
Extended depth-of-focus IOL platforms are absorbing market share from traditional multifocal designs by reducing photic phenomena complaints while maintaining functional near vision. Premium cataract practices in the United States and Germany are adopting these hybrid optics at accelerated replacement cycles. The technology is absorbing volume that previously bifurcated between monofocal safety and multifocal performance, compressing the middle tier of the IOL value pyramid.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical follow-up obligations to 10-15 years for permanently implanted devices. IOL manufacturers must now maintain active implant registries and periodic safety update reports that inflate regulatory affairs staffing. High-volume hospital chains in France and Italy are prioritizing suppliers with established MDR technical documentation, displacing smaller CE-marked competitors.
Direct-to-consumer refractive surgery financing platforms are disintermediating traditional ophthalmology referral networks. Patients in Brazil and Mexico are increasingly self-directing to surgical centers through digital channels rather than optometrist-mediated pathways. This channel shift concentrates volume at high-visibility metropolitan clinics while fragmenting regional eye care practice economics.
Global Aphakia Market Segmentation
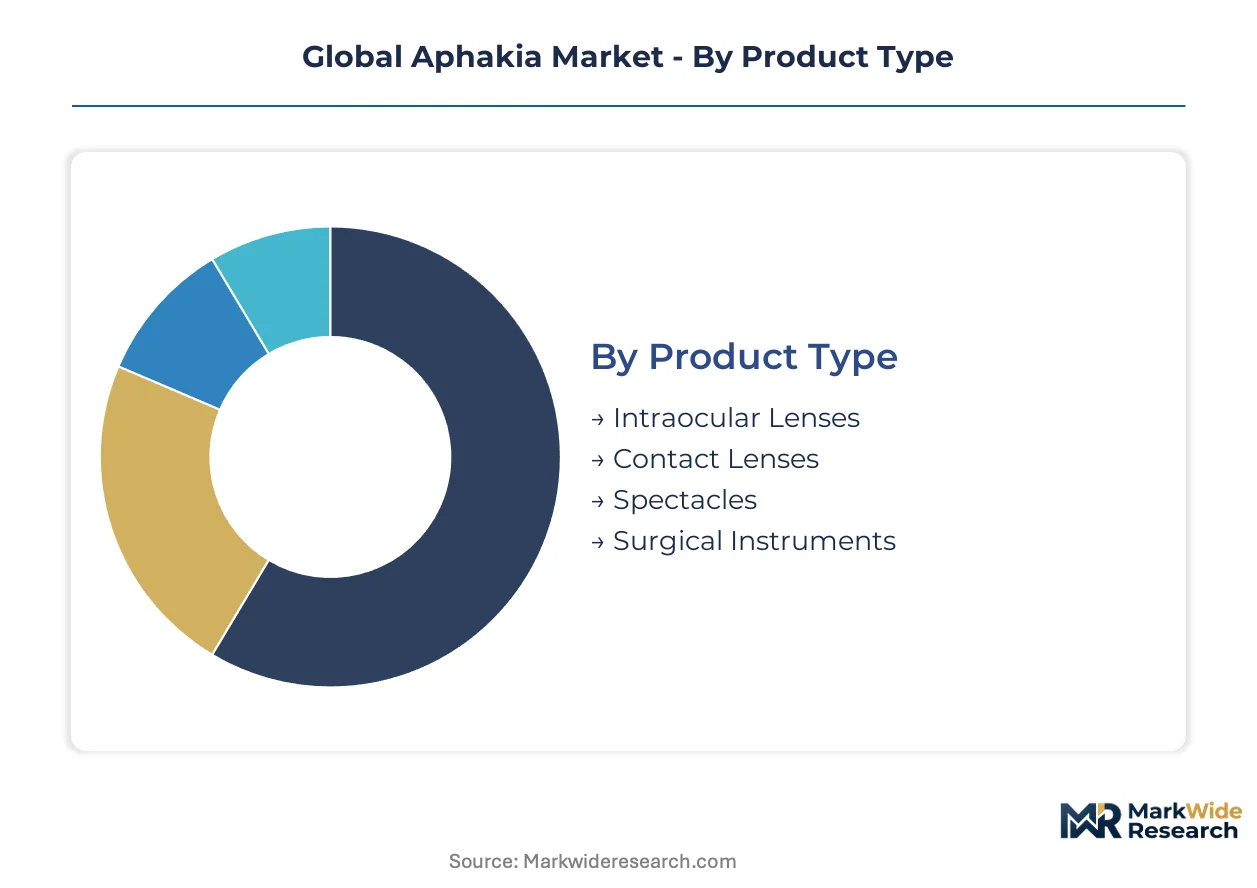
Segmentation in the aphakia market reveals how optical correction preferences split between permanent implantable solutions and reversible external alternatives, with technology tiers and surgical settings determining margin structures and competitive intensity differently across each divide.
Product Type:
Supply concentration in optical-grade polymer manufacturing shapes competitive dynamics across product categories, with foldable silicone and acrylic platforms commanding premium positioning against legacy alternatives.
- Intraocular Lenses:Permanent implantable devices fabricated from hydrophobic acrylic, hydrophilic acrylic, or silicone elastomer materials restore approximately 20 diopters of refractive power through capsular bag or sulcus fixation. Demand concentrates in specialized ophthalmology hospitals across the United States, Germany, and Japan where surgeon certification density supports premium technology adoption. Foldable platforms dominate procedural volume due to micro-incision compatibility and reduced endothelial cell loss.
- Contact Lenses:External optical correction using high-power aphakic designs (+10D to +20D) or gas-permeable materials serves patients contraindicated for implantation or awaiting definitive surgery. Pediatric aphakia management in congenital cases and post-trauma temporary rehabilitation in India and Brazil sustain volume against permanent solutions.
- Spectacles:Aphakic eyeglasses with thick lenticular lenses provide non-invasive correction for patients declining surgery or with significant comorbidities precluding implantation.
- Surgical Instruments:Phacoemulsification handpieces, IOL injectors, and capsular tension rings constitute the enabling hardware for lens extraction and replacement procedures.
Intraocular lenses absorb the bulk of installed capacity; customizable IOL platforms are expanding most quickly.
Application:
Volume distribution across clinical indications reflects demographic aging patterns and trauma epidemiology differently, with reimbursement frameworks segmenting addressable populations by procedure type.
- Cataract Surgery:Age-related lens extraction constitutes the dominant procedural volume, with senile cataract progression driving scheduled interventions in patients over 65. Medicare Advantage carve-outs in the United States and statutory health insurance coverage in Germany anchor paid volume for premium IOL upgrades.
- Traumatic Lens Removal:Acute lens extraction following ocular injury requires emergency surgical protocols and often delayed definitive IOL implantation due to capsular integrity concerns. Demand clusters in industrial accident corridors and traffic injury hotspots across Brazil, Mexico, and South Africa where safety regulation enforcement varies.
- Congenital Lens Absence:Pediatric aphakia from failed lens development necessitates early optical rehabilitation to prevent amblyopia, with contact lens management typical in infancy before secondary IOL implantation.
- Secondary Lens Implantation:Definitive IOL placement following primary trauma repair or congenital case maturation captures patients transitioning from temporary to permanent correction.
Cataract surgery anchors absolute procedure volume; traumatic lens removal applications are climbing the fastest in emerging surgical markets.
End User:
Site-of-care migration from inpatient to ambulatory settings is restructuring procurement relationships and capital equipment requirements across the delivery infrastructure.
- Eye Care Clinics:Diagnostic and referral hubs performing preoperative biometry and postoperative monitoring without surgical suites. Volume concentrates in metropolitan clusters where ophthalmologist density supports specialized practice economics.
- Ambulatory Surgical Centers:Standalone facilities optimized for high-volume cataract workflows with same-day discharge protocols. Medicare reimbursement differentials in the United States and NHS contracting reforms in the United Kingdom are accelerating volume migration from hospital-based settings.
- Specialized Ophthalmology Hospitals:Academic medical centers and dedicated eye hospitals managing complex cases, training fellows, and hosting clinical trials for novel IOL platforms. Japan's Juntendo University Hospital and Germany's University Eye Hospital Heidelberg anchor regional referral networks.
- Optical Retailers:Distribution points for contact lens and spectacle correction serving non-surgical candidates and postoperative patients requiring supplemental near vision aids.
Ambulatory surgical centers are gaining share fastest; specialized ophthalmology hospitals retain the highest complexity case concentration.
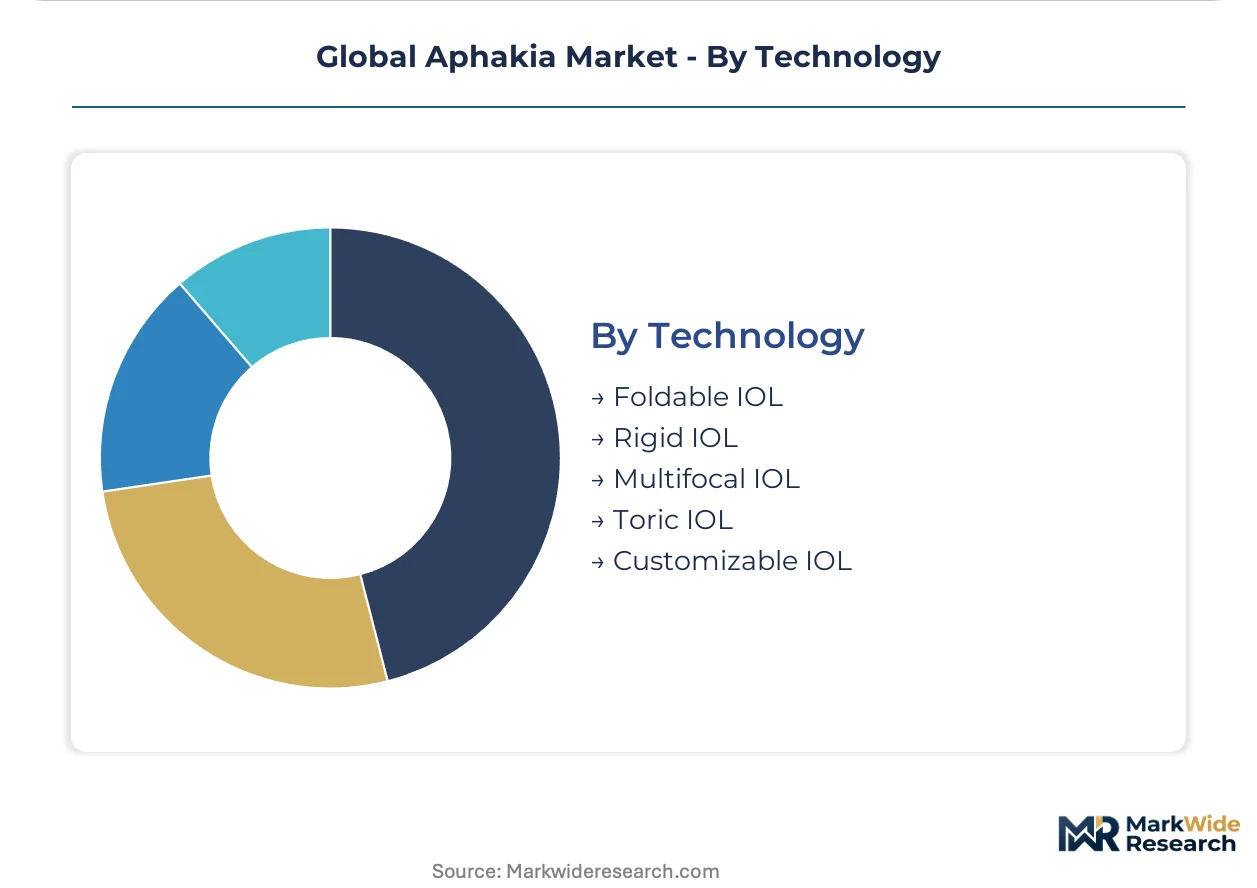
Technology:
Material science advances and optical design software capabilities are segmenting competitive advantage between manufacturing scale and customization precision.
- Foldable IOL:Silicone and acrylic platforms compressing through sub-3mm incisions dominate contemporary practice, with injector systems standardizing delivery mechanics across manufacturers.
- Rigid IOL:Polymethylmethacrylate lenses requiring larger incisions persist in limited volume for specific clinical scenarios and price-sensitive procurement environments.
- Multifocal IOL:Diffractive and refractive designs splitting light across distance and near focal points target presbyopia correction, with patient selection protocols filtering candidates by corneal health and lifestyle requirements.
- Toric IOL:Astigmatism-correcting platforms with cylindrical power incorporation command margin premiums through reduced postoperative spectacle dependence, with digital marking systems and intraoperative aberrometry refining alignment precision.
- Customizable IOL:Light-adjustable and femtosecond laser-customized platforms enabling post-implantation power modification represent the technology frontier, with RxSight's LAL system and similar platforms gaining traction in premium private-pay segments across the United States and Germany.
Foldable IOL technology retains the dominant installed base; customizable IOL platforms are gaining share fastest in paid segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heidelberg's University Eye Hospital anchors European ophthalmology training and complex case referral networks, while Tokyo's Juntendo University Hospital drives Japan's aged surgical population protocols. These metropolitan clusters concentrate premium IOL adoption and regulatory influence across three continents.
United States
Medicare Advantage supplemental benefit structures and ambulatory surgical center migration propel premium IOL volume. FDA premarket approval pathways enforce 18-36 month clinical evidence timelines for novel lens materials. The Cleveland Clinic and Bascom Palmer Eye Institute in Miami anchor surgeon training density and clinical trial hosting for customizable IOL platforms.
Germany
Statutory health insurance coverage for premium IOL upgrades and precision optics manufacturing heritage sustain market depth. EU MDR post-market surveillance requirements extend clinical follow-up obligations to 10-15 years for permanently implanted devices. The Mannheim-Heidelberg corridor concentrates high-precision lathe equipment suppliers and IOL manufacturing infrastructure.
Japan
The world's most aged major economy generates procedural volume from patients over 75 seeking spectacle independence. PMDA streamlined biocompatibility review processes for predicate devices accelerate incremental IOL innovation timelines. Tokyo's Juntendo University Hospital and Osaka's Kansai Medical University anchor regional referral networks and fellow training capacity.
India
Tier-2 and tier-3 city expansion with emerging ophthalmology infrastructure presents volume growth corridors as domestic surgical training capacity scales. The country's national pharmaceutical regulator enforces biocompatibility standards that filter subscale competitors from high-value segments. Aravind Eye Hospital in Madurai and LV Prasad Eye Institute in Hyderabad anchor charitable and private-pay surgical volume respectively.
Brazil
Direct-to-consumer refractive surgery financing platforms disintermediate traditional optometrist-mediated referral networks. ANVISA ophthalmic device registration requirements shape market entry costs for imported IOL platforms. São Paulo's metropolitan clinics concentrate self-directed patient volume through digital channels, fragmenting regional eye care practice economics.
Global Aphakia Market Competitive Landscape
Premium-margin players sit above commodity-margin players across optical customization and surgeon training ecosystem dimensions. The vendor base stratifies between diversified ophthalmology conglomerates, precision optics specialists, and contact lens manufacturers extending into surgical adjacencies. Three archetypes dominate: diversified medical device conglomerates with full cataract workflow coverage, precision optics heritage players with customizable IOL platforms, and contact lens specialists leveraging distribution reach. Capacity expansion through ambulatory surgical center partnerships and technology licensing for extended depth-of-focus designs constitute the dominant competitive moves.
Within the diversified conglomerate tier, Alcon Inc. and Johnson & Johnson Services, Inc. exemplify scale-driven positioning across phacoemulsification systems and disposable instrumentation. ZEISS International occupies a position within the precision optics heritage archetype, leveraging German manufacturing credibility in customizable IOL development. These three entities represent the concentration of manufacturing scale, surgeon training ecosystems, and optical design software capabilities reshaping competitive advantage.
| Leading Market Players |
|---|
| ZEISS International |
| The Cooper Companies Inc. |
| Johnson & Johnson Services, Inc. |
| Novartis |
| Ophtec BV |
| Alcon Inc. |
| Rayner |
| Abbott |
| Bausch + Lomb |
| Others |
Supply & Pricing Matrix
Optical-grade silicone and acrylic polymer feedstock costs cascade through intraocular lens manufacturing tiers, with hydrophobic acrylic premiums reflecting petrochemical volatility and precision lathe depreciation absorbed differently across German, Swiss, and Japanese supplier bases.
Pricing Analysis
Outcome-linked pricing for spectacle independence anchors premium IOL tiers, with toric and extended depth-of-focus platforms commanding multiples over monofocal standards based on reduced postoperative correction rates. Price differentiation rests on CE marking tier and surgeon training certification density, with FDA premarket approval pathways adding 18-36 month cost recovery premiums. Pricing pressure stems from hospital procurement consolidation and Medicare Advantage carve-out negotiations, squeezing margin flexibility in contracted segments. Ambulatory surgical centers exhibit highest price sensitivity due to fixed reimbursement schedules, while private-pay premium practices maintain lowest sensitivity through direct patient financing.
Supply Chain Analysis
Precision optics manufacturing workforce availability concentrates in the Mannheim-Heidelberg corridor, Jura region of Switzerland, and Nagoya prefecture, anchoring high-precision lathe and milling equipment operations. Raw material dependencies center on optical-grade silicone elastomers, hydrophobic acrylic monomers, and diamond-tipped cutting tools. Single-source vulnerability runs through German and Swiss machine tool suppliers for sub-micron surface finishing equipment. Distribution runs through specialized ophthalmology hospital procurement committees, GPO contracts, and direct ambulatory surgical center agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Foldable intraocular lens technology is displacing rigid polymethylmethacrylate platforms, compressing the legacy supply base while expanding addressable procedural volume through micro-incision compatibility.
For Market Incumbents: Anticipate EU MDR post-market surveillance obligations extending clinical follow-up to 10-15 years, requiring active implant registry maintenance that smaller CE-marked competitors cannot sustain. Defensive consolidation through backward integration into optical-grade polymer manufacturing and captive surgeon training academy expansion in India and Brazil will secure volume corridors against emerging domestic competitors.
For New Entrants and Emerging Players: Enter via India's tier-2 and tier-3 city expansion corridors where ophthalmology infrastructure is scaling faster than fellowship program output creates surgeon bottlenecks. Target traumatic lens removal applications in Brazil, Mexico, and South Africa where safety regulation enforcement variance sustains emergency procedural volume. Pursue teleophthalmology screening partnerships as the go-to-market angle to identify surgical candidates earlier and compress time-to-treatment intervals.
For Investors and Strategic Acquirers: PMDA streamlined biocompatibility review process activation for predicate devices is the leading indicator that incremental IOL innovation timelines will compress in Japan's aged surgical population, signaling capacity for premium platform absorption. Long-term viability over the next decade hinges on software-defined optical customization capabilities displacing manufacturing scale advantages. Target precision optics heritage players with light-adjustable lens platforms and femtosecond laser integration expertise. Monitor EU MDR technical documentation completion rates as the inflection signal for supplier consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR compliance secures 10-15 year follow-up registry capacity for permanently implanted devices. |
| Hospital System Partnership | Aravind Eye Hospital and LV Prasad Eye Institute anchor charitable and private-pay volume in India. |
| Software Companion Development | Digital surgical planning platforms recalibrate precision-to-cost equations in premium cataract workflows. |
| Reimbursement Strategy | Medicare Advantage supplemental benefit structures create carve-outs for presbyopia-correcting IOL categories. |
| Geographic Manufacturing Footprint | Mannheim-Heidelberg corridor concentration of lathe equipment suppliers creates chokepoint leverage. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across ophthalmic device executives, regulatory affairs leads, hospital procurement managers, and biomedical engineers. FDA 510(k) and PMA submissions, PMDA review documents, EU MDR technical documentation databases, and hospital GPO contract repositories provided validation layers. Bottom-up procedure volume estimates and top-down manufacturer revenue triangulation calibrated market sizing.
Data-stream reconciliation across foldable IOL technology penetration rates, ambulatory surgical center migration patterns, and premium IOL upgrade ratios shaped the analytical framework over the projection horizon. Segmentation dimensions spanned product type, application indication, end-user site-of-care, and technology tier including customizable platform adoption curves. CAGRs derived from surgical volume growth trajectories, demographic aging elasticities, and reimbursement threshold sensitivity analyses across national health systems.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU MDR enforcement intensity shifts and petrochemical feedstock volatility. Forecasts reflect assumptions around surgeon training capacity expansion rates and teleophthalmology screening penetration. Material deviation in PMDA review timeline acceleration or Medicare Advantage benefit structure reforms warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Canada Ophthalmology Drugs and Devices Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Light Therapy Glasses Market
Ophthalmology
Ophthalmic Femtosecond Lasers Market
Ophthalmology
Laser Vision Correction Market
Ophthalmology
Global Fundus Cameras Market
Ophthalmology
Global Ophthalmic Sutures Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Ophthalmic Lasers Therapeutic Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Ophthalmic Drugs and Devices Market
Ophthalmology
India Ophthalmology Devices Market
Ophthalmology
Superficial Punctate Keratitis Treatment Market
Ophthalmology
Lubricating Eye Drops Market
Ophthalmology
Lazy Eye Market