
 Ophthalmic Operating Room Microscope Market | 2026-2036
Ophthalmic Operating Room Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Operating Room Microscope Market Analytics
Ambulatory surgical centers is reorganizing procurement patterns across the ophthalmic microscope landscape. Carl Zeiss Meditec AG anchors its position through captive optical manufacturing and deep R&D intensity in surgical visualization. Leica Microsystems differentiates via modular microscope architectures that adapt across anterior and posterior segment procedures. Takagi Seiko Co., Ltd. specializes in compact, cost-optimized designs that compete aggressively in price-sensitive Asian markets.
An ophthalmic operating room microscope is a high-magnification stereoscopic instrument engineered for ocular microsurgery, typically delivering variable zoom ratios from 4:1 to 10:1 with integrated coaxial illumination to enable precise manipulation of corneal, lenticular, and retinal tissues. Digital microscopes are capturing the fastest growth trajectory as surgeons demand real-time image capture, heads-up display integration, and AI-assisted overlay capabilities for cataract and retinal interventions. Optical technology remains the dominant revenue pool, though video technology is displacing conventional eyepiece-dependent workflows in premium surgical centers.
FDA 510(k) clearance pathways and ISO 13485 quality management standards govern market access, with the former dictating clinical validation requirements and the latter mandating traceable manufacturing controls for optical component suppliers. The EU MDR and CE marking framework impose additional post-market surveillance obligations on manufacturers serving European surgical centers. Stakeholders must monitor how regulatory divergence between FDA and MDR requirements reshapes product development roadmaps and geographic launch sequencing.
Market Dynamics
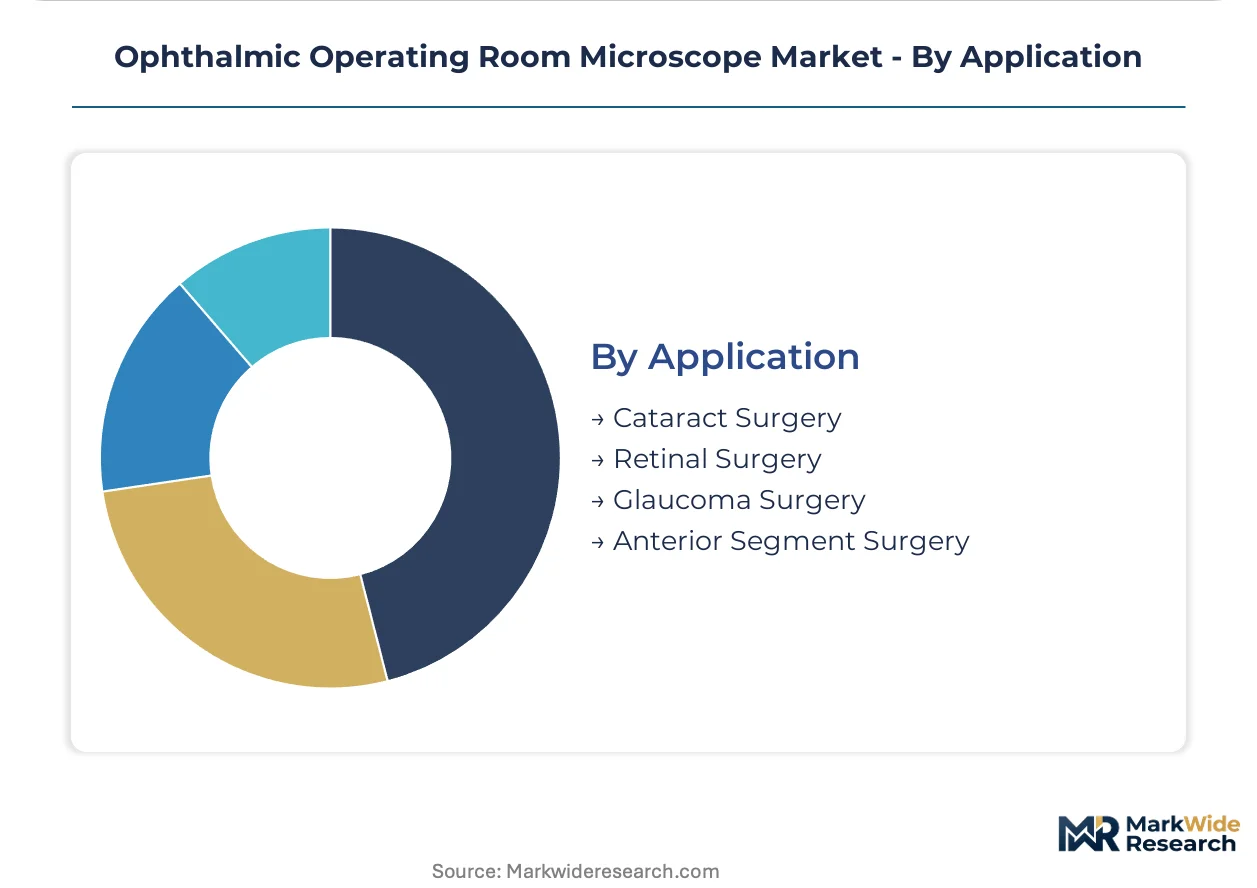
The migration of ophthalmic surgery from inpatient hospitals to outpatient facilities is restructuring capital equipment procurement, with ambulatory surgical centers demanding compact, digitally integrated microscopes that support higher surgical throughput and reduced facility footprints.
Growth Catalysts
- FDA 510(k) pathway clarity:Streamlined premarket notification for digital microscope iterations accelerates product refresh cycles and reduces time-to-revenue for manufacturers targeting United States surgical centers.
- Coaxial LED illumination:Advanced lighting systems reduce thermal tissue damage and extend bulb lifespan, cutting per-procedure operating costs for high-volume cataract practices.
- Aging demographics in Japan:The world's oldest population drives sustained demand for retinal and glaucoma microsurgery, expanding the installed base of premium surgical microscopes in Tokyo and Osaka metropolitan clusters.
Market Restraints
- Precision optical component concentration:German and Japanese suppliers dominate high-NA objective lens manufacturing, creating single-source vulnerability for microscope assemblers.
- EU MDR post-market surveillance:Expanded clinical data requirements and notified body capacity constraints extend recertification timelines for existing CE-marked devices.
- Phacoemulsification system integration:Microscope purchases increasingly bundle with cataract platform commitments, reducing standalone procurement flexibility for independent ASCs.
Strategic Opportunities
- India's tier-2 city expansion:Underpenetrated markets in Chennai, Hyderabad, and Pune present first-mover potential for cost-optimized microscope configurations as domestic surgical volume rises.
- AI-assisted overlay convergence:Real-time image analysis integration with heads-up displays creates premium pricing power for digital microscope platforms in retinal surgery.
- Health Canada streamlined approval:Mutual recognition agreements with FDA 510(k) clearances reduce regulatory duplication for manufacturers entering Canadian provincial procurement frameworks.
Industry Challenges
- Stereoscopic visualization training:Surgeon adaptation to three-dimensional heads-up displays requires extended proctoring periods, slowing digital microscope adoption in fellowship programs.
- ISO 13485 supplier audit complexity:Multi-tier optical component traceability demands strain quality management resources for mid-tier microscope manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Operating Room Microscope Market |
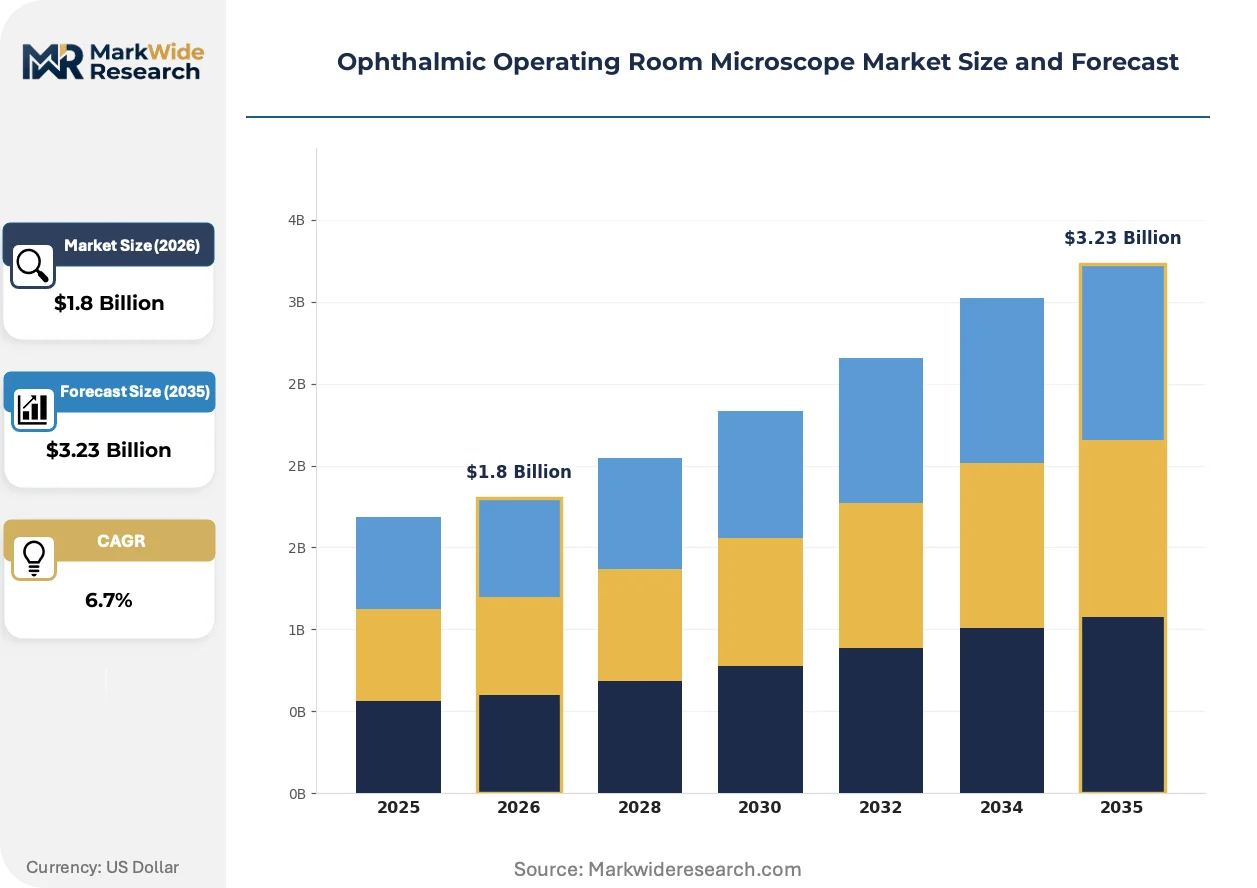
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Microscopes, Digital Microscopes, Inverted Microscopes, Vacuum Microscopes End User: Hospitals, Surgical Centers, Research Institutions, Ophthalmology Clinics Technology: Optical Technology, Video Technology, Laser Technology, Imaging Technology Application: Cataract Surgery, Retinal Surgery, Glaucoma Surgery, Anterior Segment Surgery |
| Companies Covered | Alcon, Carl Zeiss Meditec AG, Johnson & Johnson, Leica Microsystems, Topcon Corporation, Takagi Seiko Co., Ltd., Inami & Co., Ltd., Haag-Streit Holding, Karl Kaps GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Operating Room Microscope Market Evolving Landscape
Digital visualization architectures are supplanting traditional binocular eyepiece workflows, compressing the technology refresh cycle and redefining surgeon ergonomics across anterior and posterior segment procedures.
Integrated 4K/3D video microscopy is displacing conventional optical pathways in premium United States ambulatory surgical centers. Surgeons at high-volume cataract and vitreoretinal practices in Florida and California are adopting heads-up display configurations to reduce cervical strain during lengthy procedures. This shift is compressing demand for eyepiece-dependent microscope variants and forcing optical purists to develop hybrid platforms.
The EU MDR's enhanced clinical evidence requirements for Class IIa surgical devices are extending time-to-market for microscope software updates. Manufacturers must now submit post-market clinical follow-up data for digital overlay functionalities, increasing regulatory affairs staffing. German and Swiss surgical centers are prioritizing MDR-compliant suppliers, creating certification-driven procurement preferences that disadvantage smaller competitors.
Equipment-as-a-service contracting is gaining traction among United States ASC chains seeking to convert capital expenditures into predictable operating expenses. Multi-site ophthalmology platforms in Texas and Arizona are bundling microscope leases with preventive maintenance and software upgrade commitments. This shift concentrates purchasing authority at corporate procurement offices, reducing individual surgeon influence over equipment selection.
Ophthalmic Operating Room Microscope Market Segmentation
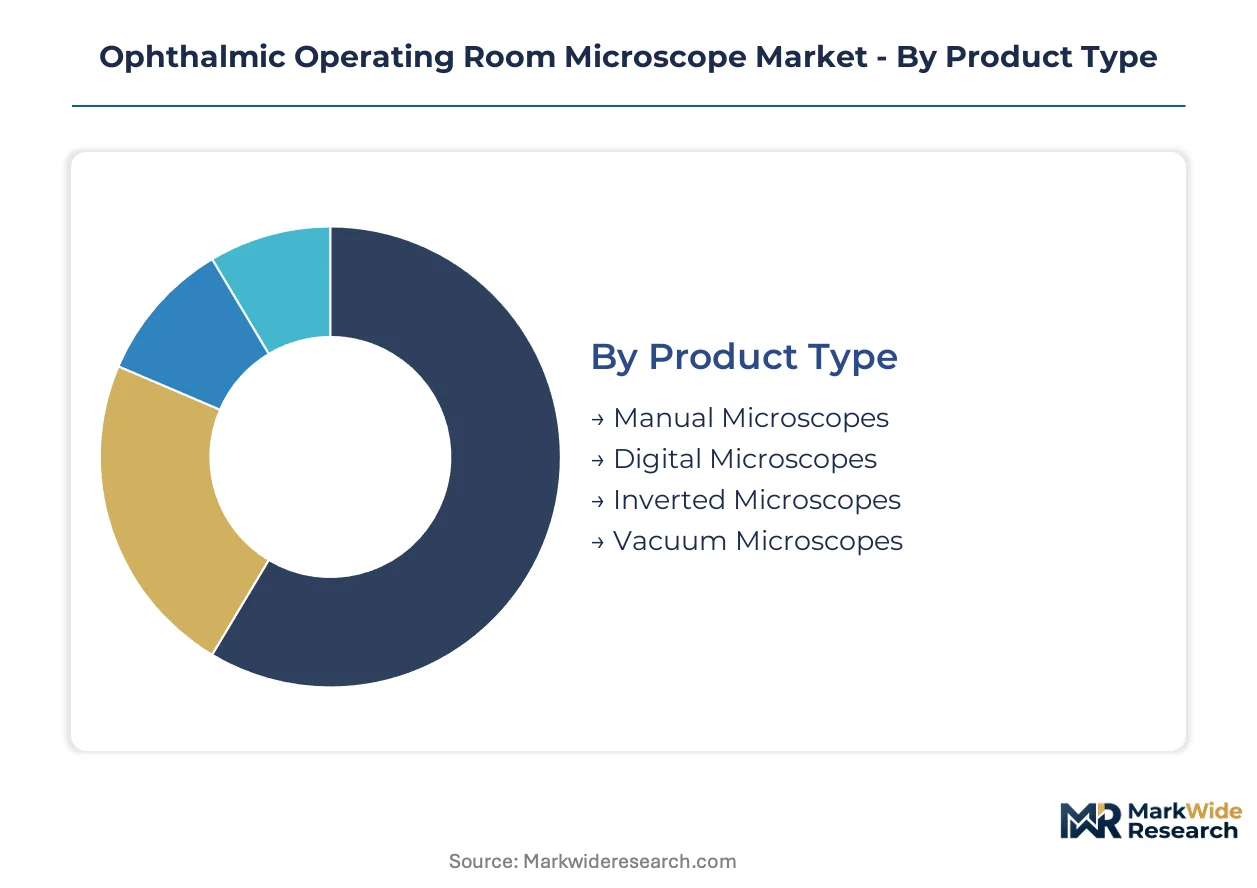
Segmentation in ophthalmic microscopes reveals how regulatory pathways, surgical workflow demands, and reimbursement structures partition procurement decisions across facility types. Each dimension carries distinct compliance burdens and capital allocation logic that manufacturers must address separately.
Product Type:
FDA 510(k) clearance timelines diverge sharply between analog and digital microscope platforms, with software-enabled devices facing enhanced cybersecurity documentation requirements under updated FDA guidance.
- Manual Microscopes:Conventional binocular stereoscopic designs with mechanical zoom ratios and halogen or LED coaxial illumination. Demand concentrates in India's tier-2 surgical centers where capital constraints favor proven optical platforms over digital premiums, though maintenance costs accumulate from bulb replacements and mechanical wear.
- Digital Microscopes:Integrated 4K/3D video pathways with heads-up display compatibility and AI overlay readiness. United States ambulatory surgical centers in Florida and Texas are where expansion concentrates, driven by surgeon ergonomics mandates and bundled service contracting models that amortize upfront costs.
- Inverted Microscopes:Specialized configurations for posterior segment access with angled objective positioning. Research institutions in Germany and Japan maintain installed bases for experimental surgical techniques.
- Vacuum Microscopes:Stabilized platforms using suction fixation for tremor-sensitive procedures. Niche deployment in high-volume cataract practices seeking motion compensation.
Manual microscopes dominate installed base in price-sensitive markets. Digital microscopes are where expansion concentrates fastest.
End User:
Procurement authority is shifting from individual surgeons toward centralized supply chain functions as facility networks consolidate purchasing across multiple sites.
- Hospitals:Inpatient surgical departments with legacy capital equipment depreciation schedules and slower replacement cycles. United States academic medical centers in Boston and Baltimore maintain hybrid procurement models balancing research mandates with clinical throughput.
- Surgical Centers:Dedicated outpatient ophthalmic facilities with compressed procedure turnaround requirements. These facilities are expanding most quickly in Arizona and Texas, where corporate ownership structures favor equipment-as-a-service contracts over outright purchase.
- Research Institutions:University-affiliated laboratories and teaching hospitals with dual clinical-experimental missions. Funding volatility from NIH and equivalent bodies creates lumpy procurement patterns.
- Ophthalmology Clinics:Single-specialty private practices with limited surgical volume. Cost sensitivity drives leasing arrangements and refurbished equipment markets.
Hospitals retain the largest cumulative installed base. Surgical centers are where manufacturer revenue growth concentrates.
Technology:
Component sourcing strategies differ markedly across technology platforms, with video-dependent systems requiring semiconductor supply chain management that optical purists avoid.
- Optical Technology:Precision-engineered lens assemblies with variable aperture control and stereoscopic light paths. German and Japanese suppliers dominate high-NA objective manufacturing, creating supply concentration that constrains margin pressure for microscope assemblers.
- Video Technology:CMOS sensor-based image capture with digital signal processing and display integration. Demand is climbing the fastest in premium United States markets where heads-up displays reduce surgeon cervical strain during lengthy vitreoretinal procedures.
- Laser Technology:Integrated femtosecond or photocoagulation delivery through microscope optics. Retinal surgery suites in Tokyo and Osaka metropolitan clusters drive specialized demand.
- Imaging Technology:OCT or angiography overlay capabilities fused with surgical visualization. Research hospitals in Switzerland and the Netherlands pilot intraoperative diagnostic convergence.
Optical technology anchors current revenue. Video technology is where R&D investment concentrates.
Application:
Procedure reimbursement rates directly influence microscope feature requirements, with higher-compensated surgeries justifying premium digital configurations.
- Cataract Surgery:High-volume anterior segment procedures demanding rapid zoom transitions and stable red reflex illumination. United States Medicare reimbursement clarity supports premium microscope adoption in high-throughput practices, though phacoemulsification system bundling reduces standalone procurement flexibility.
- Retinal Surgery:Lengthy posterior segment interventions requiring extreme magnification stability and assistant viewing ports. Japan's aging population sustains demand for diabetic retinopathy and macular degeneration procedures in Tokyo and Osaka surgical clusters.
- Glaucoma Surgery:Micro-invasive and filtration procedures with specialized gonio lens compatibility. Emerging economy markets in India show rising procedural volume.
- Anterior Segment Surgery:Corneal transplantation and refractive procedures with precise tissue manipulation requirements. European surgical centers prioritize MDR-compliant suppliers for these Class IIa device applications.
Cataract surgery dominates procedure volume. Retinal surgery is where premium pricing power concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German optical component exports supply microscope assemblers across United States surgical centers and Japanese metropolitan clusters. Trade corridors link precision lens manufacturing in Stuttgart and Jena to final assembly operations in North American and Asian markets.
United States
Ambulatory surgical centers in Florida and Texas drive capital equipment procurement as corporate ownership consolidates purchasing authority. FDA 510(k) clearance pathways streamline premarket notification for digital microscope iterations, reducing time-to-revenue for manufacturers. Surgeon ergonomics mandates in high-volume cataract practices accelerate heads-up display adoption.
Germany
Research institutions in Berlin and Munich maintain hybrid clinical-experimental procurement models balancing innovation mandates with throughput requirements. EU MDR post-market surveillance obligations extend recertification timelines for CE-marked devices, favoring established suppliers with regulatory affairs capacity. Stuttgart and Jena anchor precision objective lens manufacturing for global microscope assembly.
Japan
The world's oldest population sustains demand for retinal and glaucoma microsurgery in Tokyo and Osaka metropolitan clusters. PMDA regulatory frameworks govern Class IIa surgical device approvals, with notified body capacity constraining market entry for new entrants. Domestic manufacturers leverage compact design expertise for cost-optimized configurations.
India
Tier-2 surgical centers in Chennai, Hyderabad, and Pune present first-mover potential as domestic cataract and glaucoma procedural volume rises. CDSCO medical device regulations impose quality management requirements on imported optical equipment, creating compliance barriers for non-ISO 13485 certified suppliers. Capital constraints favor manual microscope platforms over digital premiums.
Switzerland
Swissmedic certification requirements drive procurement preferences for MDR-compliant suppliers serving university-affiliated surgical centers in Zurich and Geneva. Research hospitals pilot intraoperative diagnostic convergence with OCT overlay capabilities fused to surgical visualization. Dual clinical-experimental missions create lumpy funding patterns tied to federal research allocations.
Ophthalmic Operating Room Microscope Market Competitive Landscape
Listed leaders compete with private specialists across regulatory compliance capabilities and manufacturing scale. The vendor base concentrates around precision optical heritage and surgical visualization expertise, with tiered positioning separating premium digital platforms from cost-optimized manual configurations. Three archetypes dominate: captive optical manufacturers with backward integration into lens production, modular architecture specialists serving mixed procedure portfolios, and compact design houses targeting price-sensitive emerging markets. Competitive moves center on equipment-as-a-service contracting conversions and AI-assisted overlay convergence for heads-up display platforms.
Among German and Swiss precision optical fabricators, Carl Zeiss Meditec AG and Leica Microsystems occupy positions anchored by captive manufacturing capabilities and modular platform architectures. Takagi Seiko Co., Ltd. exemplifies the compact design archetype competing aggressively in Asian markets through cost-optimized configurations. These three represent distinct strategic postures: optical purity with R&D intensity, adaptable modularity across surgical segments, and manufacturing efficiency for volume penetration.
| Leading Market Players |
|---|
| Alcon |
| Carl Zeiss Meditec AG |
| Johnson & Johnson |
| Leica Microsystems |
| Topcon Corporation |
| Takagi Seiko Co., Ltd. |
| Inami & Co., Ltd. |
| Haag-Streit Holding |
| Karl Kaps GmbH & Co. KG |
| Others |
Value Network & Pricing Analysis
Equipment-as-a-service contracting locks in multi-year microscope access for United States ambulatory surgical center chains while converting volatile capital expenditures into predictable operating budgets. This structure binds pricing visibility to service-level commitments across preventive maintenance, software upgrades, and replacement cycles.
Pricing Analysis
Current-generation digital microscopes with 4K/3D video pathways command substantial premiums over prior-generation optical platforms, while next-generation AI-assisted overlay configurations are entering limited beta deployment. Three-tier pricing structure across premium, standard, and economy levels separates MDR-certified digital platforms from ISO 13485-compliant manual systems and refurbished legacy units. Cost compression in manual microscope tiers is intensifying because Takagi Seiko and domestic Indian manufacturers compete aggressively on manufacturing efficiency. India's tier-2 surgical centers exhibit highest price sensitivity, while Japan's Tokyo metropolitan clusters show lowest sensitivity due to reimbursement clarity and aging-driven procedural volume.
Supply Chain Analysis
High-NA objective lens manufacturing concentrates in Stuttgart and Jena, Germany, and Tokyo, Japan, creating single-source vulnerability for microscope assemblers seeking precision optical components. Final assembly operations draw from German optical exports, Japanese precision mechanics, and Chinese electronic subassemblies for CMOS sensors and display panels. Tariff exposure on semiconductor components from East Asian foundries threatens cost stability for video-enabled microscope platforms. Distribution runs through authorized dealer networks serving hospital systems and direct corporate procurement offices for ASC chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital visualization architectures are disrupting procurement patterns as FDA 510(k) pathway clarity accelerates software-enabled microscope iterations and compresses technology refresh cycles.
For Market Incumbents: Consolidate backward integration into precision objective lens manufacturing to reduce dependency on Stuttgart and Jena suppliers. Lock in multi-year equipment-as-a-service contracts with United States ASC chains before emerging competitors achieve FDA clearance. Prioritize MDR certification maintenance as EU notified body capacity constraints extend recertification timelines for smaller rivals. For New Entrants and Emerging Players: Health Canada streamlined approval leveraging FDA 510(k) mutual recognition agreements offers fastest market entry for digital microscope platforms. Target India's tier-2 cities with cost-optimized manual configurations as domestic cataract volume rises in Chennai, Hyderabad, and Pune. Pursue hospital system partnership models bundling microscope leases with phacoemulsification platform commitments. For Investors and Strategic Acquirers: Capital is best deployed toward modular architecture specialists with regulatory affairs capacity spanning FDA, MDR, and PMDA frameworks. Long-term viability hinges on AI-assisted overlay convergence for heads-up display platforms. Watch surgeon ergonomics mandates in high-volume United States cataract practices as adoption inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Digital Pathway Expansion | Accelerates premarket notification for software-enabled microscope iterations in United States surgical centers. |
| EU MDR Certification Investment | Extends market access for CE-marked devices as notified body capacity constraints disadvantage smaller competitors. |
| Equipment-as-a-Service Contracting | Converts capital expenditures to operating budgets for ASC chains in Texas and Arizona. |
| AI-Assisted Overlay Development | Creates premium pricing power for retinal surgery platforms with real-time image analysis integration. |
| India Tier-2 Distribution Buildout | Captures rising procedural volume in Chennai, Hyderabad, and Pune surgical centers. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across ophthalmic surgeons, ASC procurement directors, biomedical engineers, and GPO contracts managers. Secondary validation drew from FDA 510(k) filings, EU MDR notified body registers, hospital procurement databases, and CMS Medicare reimbursement schedules. Bottom-up and top-down triangulation reconciled facility-level equipment installation data with manufacturer shipment records.
Across the analysis window, the forecasting framework modeled technology platform transitions, end-user facility type migration, and regional regulatory cluster differentiation. CAGRs were derived from procedure volume trajectories, reimbursement rate stability, and equipment replacement cycle compression. Industry-specific inputs included phacoemulsification system bundling rates and heads-up display adoption curves in high-volume cataract practices.
Underlying assumptions cover reimbursement clarity persistence, regulatory pathway stability, and semiconductor supply continuity, with deviation risk concentrated in EU MDR recertification delays and optical component supply concentration. Practitioners should keep alternative scenarios live as FDA cybersecurity guidance for software-enabled devices and PMDA notified body capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Diabetes Associated Ophthalmic Treatment Market
Ophthalmology
Herpes Zoster Ophthalmicus Market
Ophthalmology
Ocular Hypertension Treatment Market
Ophthalmology
Ophthalmic Devices Market
Ophthalmology
Inherited Retinal Diseases Treatment Market
Ophthalmology
Global Optic Nerve Disorders Treatment Market
Ophthalmology
Global Ophthalmology Drugs and Devices Market
Ophthalmology
Latin America Dry Eye Syndrome Market
Ophthalmology
Vernal Keratoconjunctivitis Treatment Market
Ophthalmology
Global Macular Degeneration Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
US Ophthalmic Sutures Market
Ophthalmology
Global Ophthalmic Equipment Market
Ophthalmology
Eye Care Surgical Market
Ophthalmology
Age-Related Macular Degeneration Market
Ophthalmology
Ophthalmic Eye Drops Market