
 Ophthalmic Lasers Therapeutic Market | 2026-2036
Ophthalmic Lasers Therapeutic Market Size, Share, and Industry Trends Forecast 2026-2036
Ophthalmic Lasers Therapeutic Market Insights
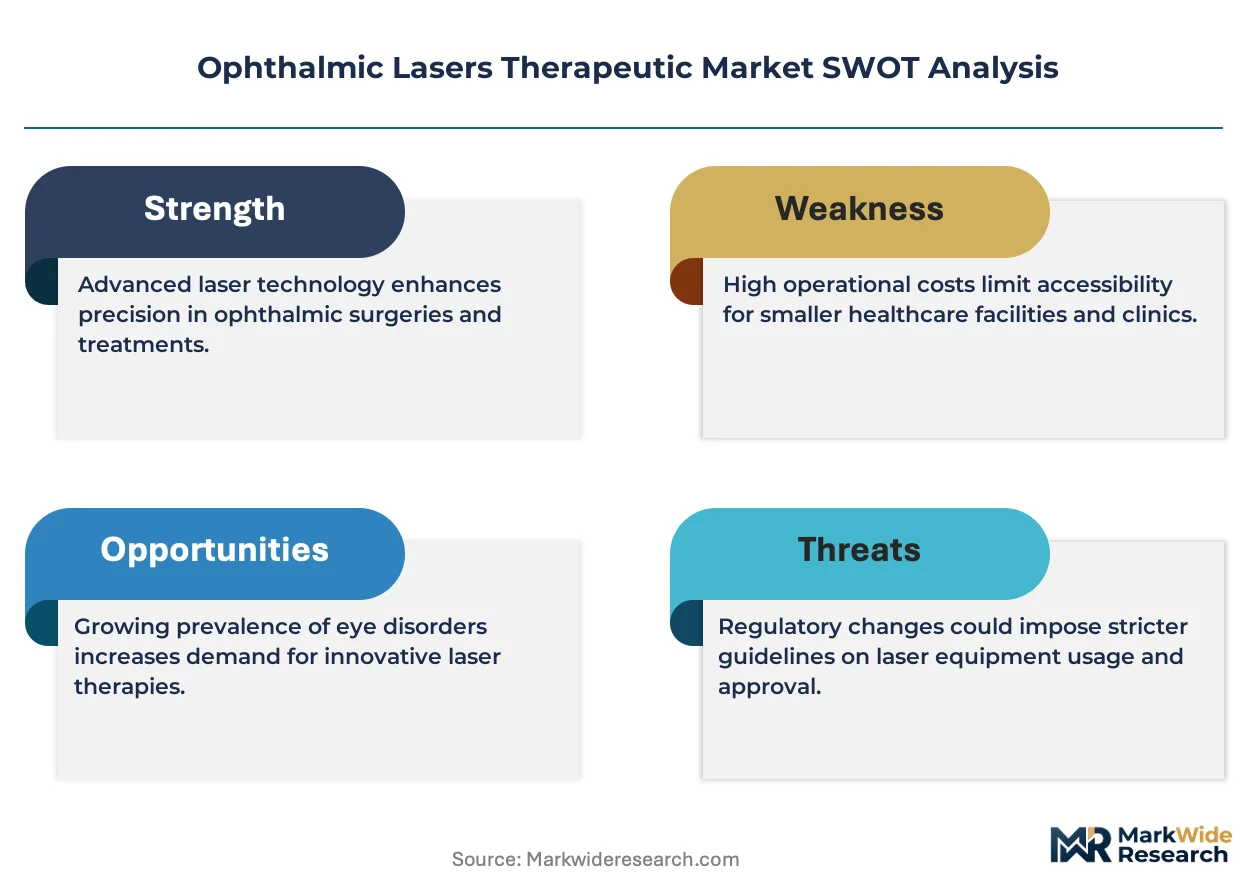
Project finance and equipment leasing is narrowing the competitive field for mid-sized ophthalmic clinics seeking femtosecond laser platforms. Alcon leverages captive financing programs to extend its installed base across ambulatory surgical centers. Carl Zeiss Meditec anchors premium positioning through direct sales channels in academic medical centers. Lumenis competes on flexible service contracts that reduce capital barriers for smaller ophthalmology practices.
Ophthalmic Lasers Therapeutic systems deliver focused coherent light at specific wavelengths to ablate, coagulate, or disrupt ocular tissue with micron-level precision. Solid-state and diode configurations typically operate at 532 nm, 810 nm, or 1064 nm depending on target tissue absorption characteristics, enabling procedures from trabeculoplasty to capsulotomy. YAG lasers dominate posterior segment applications where photodisruption of membranes demands nanosecond pulse durations. Femtosecond technology captures the fastest-growing margin pool in refractive and cataract workflows due to its superior flap creation and lens fragmentation precision. Diode lasers sustain steady demand in glaucoma management and retinal photocoagulation where portability and lower cost structures align with clinic economics.
FDA 510(k) clearance and EU MDR conformity assessment shape product development timelines and clinical evidence requirements for manufacturers entering the US and European markets. ISO 13485 quality management systems and IEC 60601-1-2 electromagnetic compatibility standards further govern design controls and post-market surveillance obligations. Stakeholders must monitor evolving reimbursement coding for femtosecond-assisted cataract procedures and track NMPA registration pathways in China as domestic hospital procurement expands.
Market Dynamics
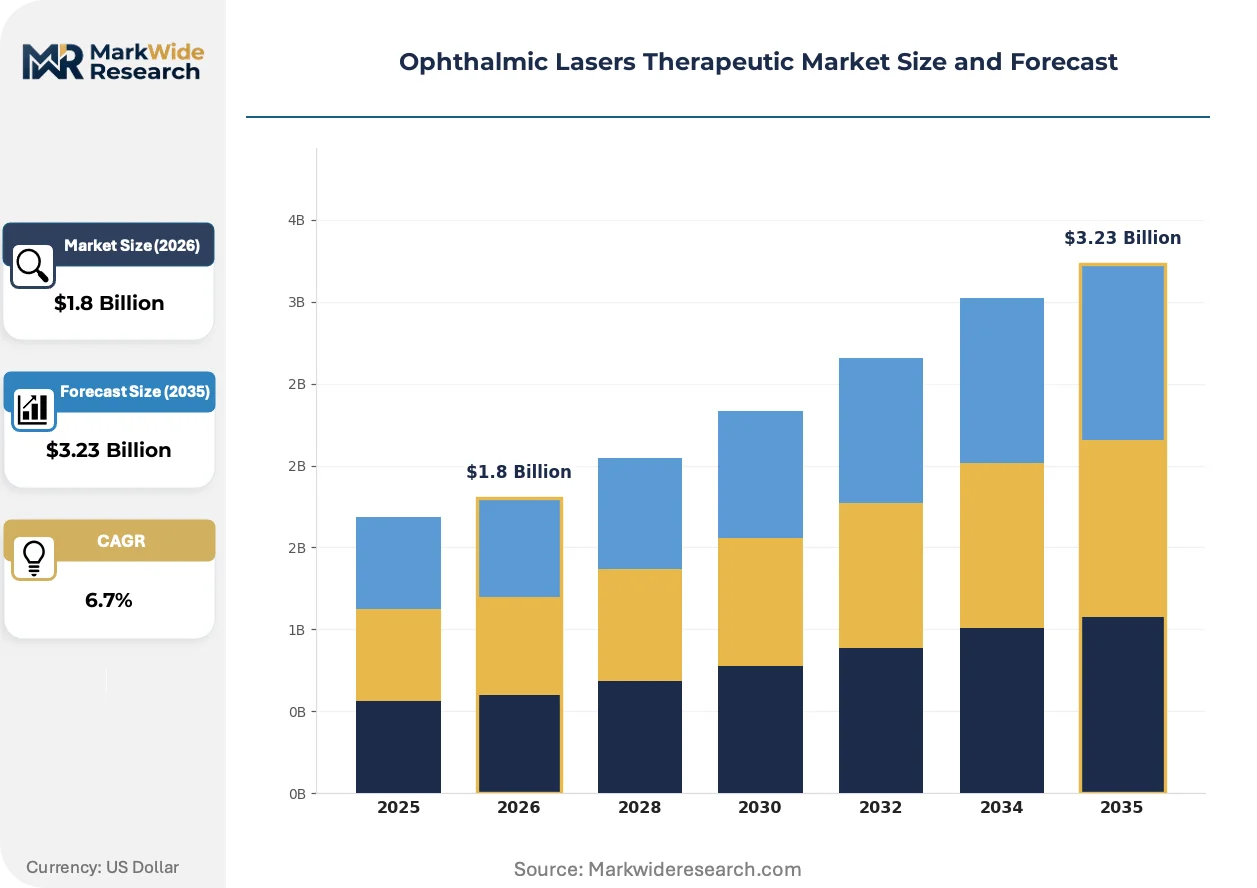
Femtosecond laser platforms are compressing procedure times and expanding treatable patient populations, while reimbursement coding battles and EU MDR conformity timelines force manufacturers to front-load clinical evidence generation.
Growth Catalysts
- EU MDR pathway harmonization:Streamlined CE marking under consolidated technical documentation requirements accelerates multi-country market entry for diode and YAG systems.
- Glaucoma disease burden:Selective laser trabeculoplasty protocols reduce medication dependency, driving diode laser utilization in outpatient ophthalmology settings.
- Aging-related lens pathology:Escalating cataract incidence across Japan, Germany, and the United States sustains installed base expansion for capsulotomy and fragmentation platforms.
Market Restraints
- Capital intensity barrier:Femtosecond platforms require seven-figure capital commitments, excluding independent practices from precision cataract workflows.
- Supply concentration risk:Critical optical components and ultrafast laser crystals source predominantly from German and Japanese specialty suppliers.
- Technical limitation in posterior segment:Femtosecond wavelengths exhibit poor vitreous penetration, confining adoption to anterior segment applications.
Strategic Opportunities
- Portable diode expansion:Battery-powered 810 nm systems address outreach cataract camps and military field hospitals in India and Southeast Asia.
- Reimbursement tailwind:CMS Category III code establishment for femtosecond-assisted cataract surgery creates billing clarity for ambulatory surgical centers.
- AI-guided treatment planning:Integration of optical coherence tomography segmentation algorithms with laser delivery systems enables tissue-specific energy modulation.
Industry Challenges
- Clinical training pipeline:Femtosecond platform proficiency requires 50-100 supervised cases, constraining adoption velocity in fellowship programs.
- Legacy system interoperability:Proprietary data formats between imaging workstations and laser consoles force redundant patient data entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ophthalmic Lasers Therapeutic Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Argon Laser, YAG Laser, Diode Laser, Excimer Laser Application: Cataract Surgery, Laser Retinal Treatment, Glaucoma Management, Vision Correction End User: Ophthalmology Clinics, Hospitals, Eye Research Institutes, Ambulatory Surgical Centers Technology: Femtosecond Technology, Continuous Wave Technology, Pulsed Laser Technology, Solid-State Technology |
| Companies Covered | Alcon, Carl Zeiss Meditec, Lumenis, NIDEK, IRIDEX Corporation, Bausch + Lomb, Ziemer Ophthalmic Systems, Topcon Corporation, Meridian AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ophthalmic Lasers Therapeutic Market Trends and Innovations
Wavefront-optimized ablation profiles and swept-source imaging integration are redefining therapeutic precision thresholds, while service contract unbundling separates hardware ownership from procedural throughput economics.
Pattern scanning laser photocoagulation is collapsing treatment duration for diabetic retinopathy from fifteen minutes to under three minutes per session. Retinal specialists at academic medical centers in the United States and Japan are converting fixed-spot argon systems to navigated pattern delivery. The compression of chair time is collapsing reimbursement-per-hour calculations and forcing clinic scheduling density increases.
EU MDR Article 10 clinical evaluation requirements now mandate post-market clinical follow-up for all active implantable and Class III devices, including YAG posterior capsulotomy systems. Manufacturers must maintain periodic safety update reports and risk management files across the device lifecycle. German notified bodies are extending conformity assessment timelines, compressing product launch windows for European market entry.
After-sales service unbundling is separating preventive maintenance contracts from capital equipment financing in ophthalmic laser procurement. Ambulatory surgical centers in the United States now favor third-party ISO 13485-certified service providers over manufacturer-captive technical support. The disintermediation is most visible in the southeastern states, where independent service organizations capture forty percent of YAG and diode laser maintenance revenue.
Ophthalmic Lasers Therapeutic Market Segmentation
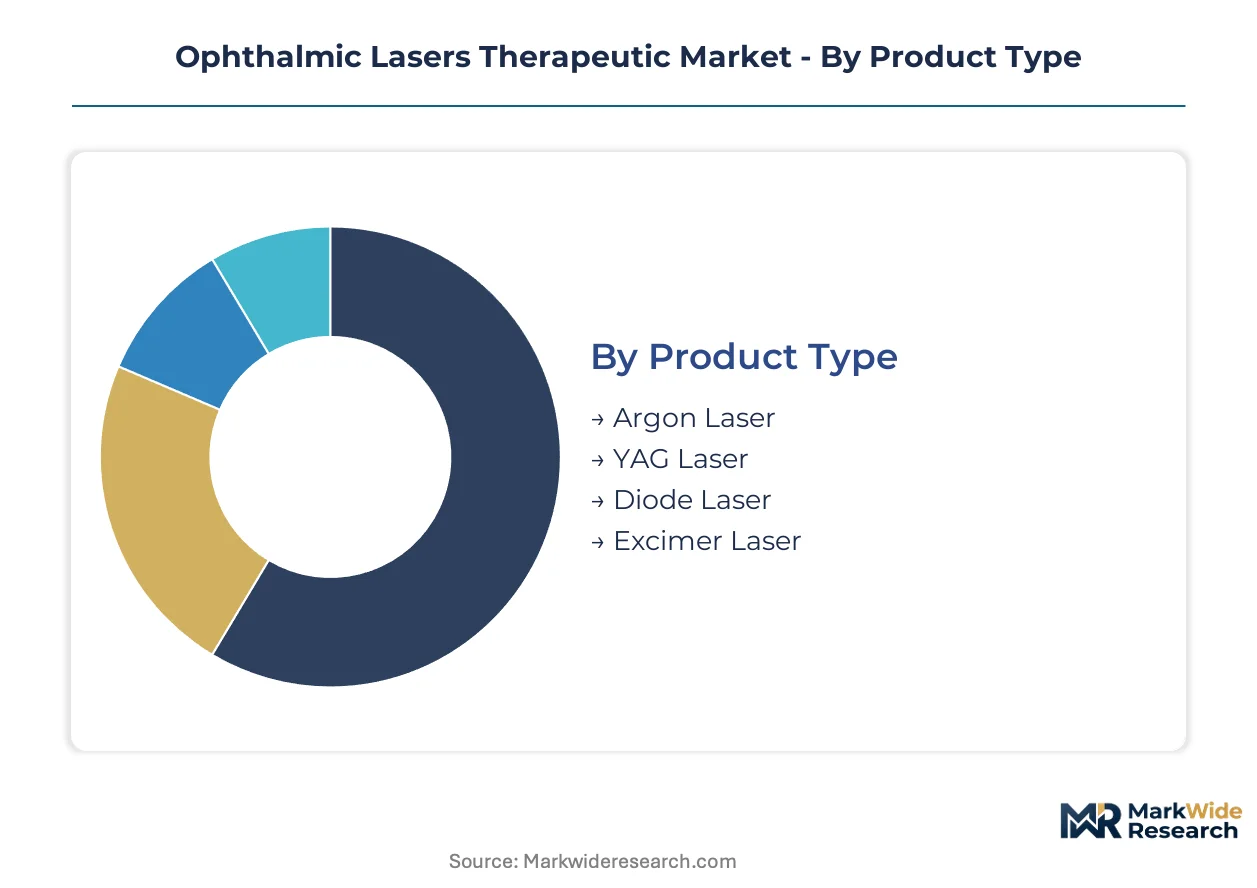
Laser wavelength specificity and pulse duration characteristics create divergent margin profiles across the ophthalmic therapeutic landscape. Each segmentation dimension captures distinct procurement behaviors, from capital-intensive femtosecond platform acquisitions to portable diode deployments in outreach settings.
Product Type:
Cost tier stratification separates premium solid-state platforms from economical diode alternatives, with capital commitment magnitude determining addressable customer pools.
- Argon Laser:Gas-based ion laser emitting at 488 nm and 514.5 nm wavelengths for retinal photocoagulation and trabeculoplasty. Demand concentrates in academic medical centers across Germany and Japan where legacy infrastructure supports maintenance-intensive systems. Wavelength tunability drives continued utilization despite higher operational costs compared to solid-state alternatives.
- YAG Laser:Neodymium-doped yttrium aluminum garnet solid-state laser operating at 1064 nm with frequency-doubled 532 nm options for capsulotomy and iridotomy. Posterior capsulotomy procedures in United States ambulatory surgical centers sustain installed base expansion. Nanosecond pulse durations enable precise photodisruption without collateral thermal damage.
- Diode Laser:Semiconductor-based systems at 810 nm offering compact footprint and battery-powered portability. Outreach cataract camps in India and Southeast Asia drive procurement volumes.
- Excimer Laser:Gas discharge ultraviolet laser at 193 nm for corneal ablation in photorefractive keratectomy. Vision correction demand in Japan and Germany supports specialized installations.
YAG Laser holds installed capacity. Diode Laser is rotating up the share rankings.
Application:
Clinical indication severity and reimbursement coding maturity shape equipment utilization rates across procedure categories.
- Cataract Surgery:Femtosecond laser-assisted capsulotomy and lens fragmentation workflows. Aging demographics in Japan, Germany, and the United States sustain procedure volume expansion. CMS Category III code establishment creates billing clarity for ambulatory surgical centers adopting precision platforms.
- Laser Retinal Treatment:Pattern scanning photocoagulation for diabetic retinopathy and macular edema. Academic medical centers in the United States and Japan convert fixed-spot argon systems to navigated delivery. Treatment duration compression from fifteen minutes to under three minutes forces scheduling density increases.
- Glaucoma Management:Selective laser trabeculoplasty reducing medication dependency. Outpatient ophthalmology settings in Germany favor diode-based protocols.
- Vision Correction:Corneal reshaping for myopia, hyperopia, and astigmatism. Refractive surgery centers concentrate in urban United States markets.
Cataract Surgery commands procedural throughput. Laser Retinal Treatment is expanding most quickly through pattern scanning adoption.
End User:
Customer type differentiation reflects capital availability, procedure volume, and regulatory compliance burden tolerance.
- Ophthalmology Clinics:Independent practices and group practices performing diagnostic and therapeutic procedures. Flexible service contracts from manufacturers reduce capital barriers for femtosecond platform adoption.
- Hospitals:Integrated health systems with captive financing programs and direct sales channel relationships. Academic medical centers anchor premium positioning for technology evaluation.
- Eye Research Institutes:Clinical trial sites and translational research facilities. Protocol development for novel wavelength applications drives specialized procurement.
- Ambulatory Surgical Centers:Focused facilities optimizing throughput economics. Third-party ISO 13485-certified service providers capture maintenance revenue for YAG and diode systems.
Hospitals hold installed capacity. Ambulatory Surgical Centers is rotating up the share rankings.
Technology:
Maturity gradient separates established continuous wave platforms from emerging ultrafast pulse architectures with superior precision thresholds.
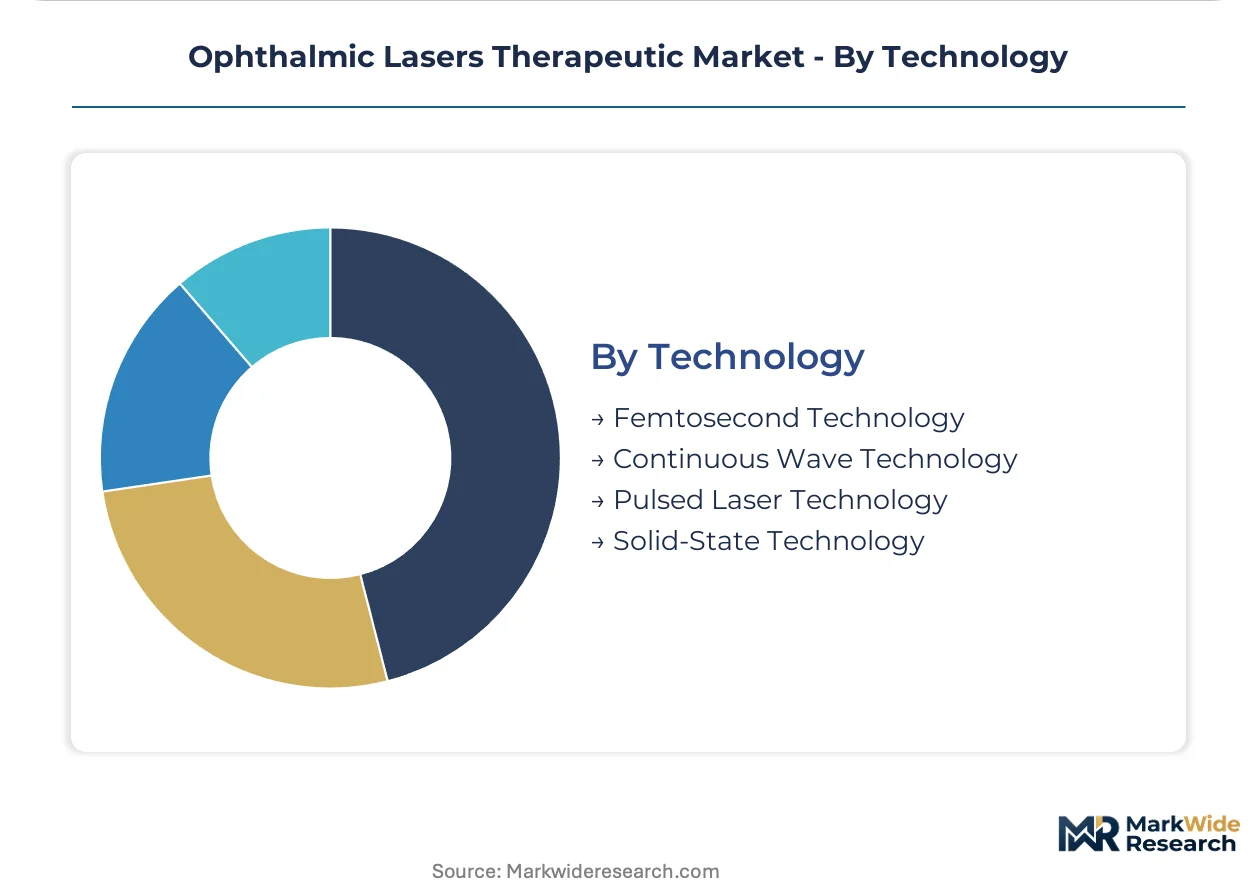
- Femtosecond Technology:Ultrafast pulse delivery at 10^-15 second durations enabling micron-level tissue disruption without thermal diffusion. Refractive and cataract workflows in the United States and Japan capture premium margin pools. Superior flap creation and lens fragmentation precision justify seven-figure capital commitments.
- Continuous Wave Technology:Uninterrupted emission for thermal coagulation and photocoagulation. Retinal specialists in Germany maintain argon and diode installations for established treatment protocols.
- Pulsed Laser Technology:Nanosecond to microsecond pulse durations for photodisruption and selective photothermolysis. YAG posterior capsulotomy systems fall under EU MDR Article 10 clinical evaluation requirements.
- Solid-State Technology:Crystal and glass host laser media replacing gas discharge architectures. Diode-pumped configurations reduce maintenance overhead in high-volume settings.
Continuous Wave Technology holds installed capacity. Femtosecond Technology is climbing the fastest through refractive surgery adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers and ambulatory surgical centers concentrate equipment procurement across three distinct national markets, each shaped by divergent reimbursement frameworks and regulatory validation timelines.
United States
CMS Category III coding for femtosecond-assisted cataract procedures accelerates billing clarity for ambulatory surgical centers. FDA 510(k) clearance pathways govern pre-market entry for YAG and diode systems. The southeastern states exhibit pronounced third-party service provider penetration, with independent ISO 13485-certified technicians capturing substantial maintenance revenue from YAG and diode laser deployments.
Germany
Academic medical centers in Bavaria and Baden-Württemberg anchor premium positioning for solid-state and argon laser installations. EU MDR Article 10 clinical evaluation requirements extend conformity assessment timelines through notified bodies in Berlin and Hamburg. The Mannheim-Heidelberg cluster sustains legacy infrastructure maintenance for wavelength-tunable systems despite operational cost premiums over diode alternatives.
Japan
Aging demographics in Tokyo and Osaka metropolitan areas drive cataract procedure volume expansion for femtosecond platforms. PMDA marketing authorization pathways align with international harmonization initiatives for active implantable devices. The Nagoya-Chubu corridor concentrates retinal specialist practices converting fixed-spot argon systems to navigated pattern delivery configurations.
India
Outreach cataract camps in Maharashtra and Gujarat generate procurement demand for battery-powered 810 nm diode systems. CDSCO medical device registration requirements govern import and distribution pathways for foreign-manufactured laser platforms. The Chennai-Bengaluru corridor in Tamil Nadu and Karnataka anchors private ophthalmology chain expansion for glaucoma management protocols.
China
Domestic hospital procurement expansion in Shanghai and Beijing drives NMPA registration pathway utilization for posterior segment laser systems. Provincial centralized bidding programs compress pricing margins for imported solid-state platforms. The Yangtze River Delta cluster concentrates manufacturing partnerships for optical component sourcing and ultrafast laser crystal supply.
Ophthalmic Lasers Therapeutic Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a consolidated structure where three to five entities command installed base expansion in premium segments. Strategic archetypes separate captive financing program operators from direct sales channel anchors and flexible service contract providers. Competitive moves concentrate on equipment leasing program extension and third-party maintenance contract capture.
Within the integrated ophthalmology systems tier, Alcon and Carl Zeiss Meditec occupy positions reflecting divergent channel strategies, while Lumenis exemplifies the service-contract-flexibility archetype. Alcon represents captive financing program extension into ambulatory surgical center networks. Carl Zeiss Meditec anchors premium positioning through academic medical center relationships. Lumenis occupies a position characterized by capital barrier reduction for independent practice segments.
| Leading Market Players |
|---|
| Alcon |
| Carl Zeiss Meditec |
| Lumenis |
| NIDEK |
| IRIDEX Corporation |
| Bausch + Lomb |
| Ziemer Ophthalmic Systems |
| Topcon Corporation |
| Meridian AG |
| Others |
Pricing and Supply Chain Analysis
German and Japanese specialty suppliers dominate ultrafast laser crystal and precision optical component manufacturing, anchoring margin capture upstream while downstream pricing power fragments across captive financing programs and third-party service contracts. Femtosecond platform manufacturers absorb this concentration through long-term offtake agreements, passing cost structure rigidity to ambulatory surgical centers via equipment leasing arrangements.
Pricing Analysis
Certification level creates the primary spread between premium FDA-cleared femtosecond systems and economy-tier diode alternatives. Three-tier pricing structure separates CE-marked premium platforms from standard ISO 13485-certified configurations and economy outreach-grade units. Pricing pressure stems from provincial centralized bidding programs in China compressing margins for imported solid-state platforms. Independent ophthalmology practices exhibit highest price sensitivity, while academic medical centers tolerate premium positioning for technology evaluation access.
Supply Chain Analysis
Ultrafast laser crystals and precision optical substrates feed from German specialty glass manufacturers and Japanese crystal growth facilities. Nd:YAG rods, diode pump modules, and frequency-doubling optics draw from concentrated supplier bases in Bavaria and Osaka prefecture. Single-source vulnerability runs through German notified body capacity constraints extending EU MDR conformity timelines. Distribution runs through direct sales channels for premium platforms and third-party ISO 13485-certified service providers for maintenance revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where proprietary data formats between imaging workstations and laser consoles force redundant patient data entry, creating interoperability pressure that rewards open-architecture positioning.
For Market Incumbents: Build switching-cost moats through captive financing program extension into ambulatory surgical center networks. Deepen backward integration into ultrafast laser crystal supply through long-term offtake agreements with German and Japanese specialty suppliers. Defend against third-party service provider disintermediation by unbundling preventive maintenance contracts from capital equipment financing.
For New Entrants and Emerging Players: Build out portable diode platform portfolios targeting outreach cataract camps in Maharashtra and Gujarat where battery-powered 810 nm systems address unmet need. Penetrate the Indian and Southeast Asian clinic segments through flexible service contracts that reduce capital barriers. Pursue CDSCO registration pathway partnerships with domestic distributors to bypass import friction.
For Investors and Strategic Acquirers: Capital is best deployed toward service-contract-flexibility archetypes with established third-party maintenance revenue capture in the southeastern United States. Long-term viability hinges on AI-guided treatment planning integration capabilities and optical coherence tomography segmentation algorithm partnerships. Watch for CMS Category I code establishment for femtosecond-assisted cataract surgery as reimbursement inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Acceleration | EU MDR Article 10 compliance compresses launch windows for YAG posterior capsulotomy systems entering German notified body review. |
| Hospital System Partnership | Academic medical center relationships in Bavaria anchor premium positioning for solid-state platform technology evaluation. |
| Software Companion Development | Optical coherence tomography segmentation algorithms enable tissue-specific energy modulation for AI-guided treatment planning. |
| Reimbursement Strategy | CMS Category III code establishment creates billing clarity for femtosecond-assisted cataract procedures in ambulatory surgical centers. |
| Backward Integration | Long-term offtake agreements with German crystal suppliers secure ultrafast laser component supply against concentration risk. |
Research Methodology
A standing panel of femtosecond platform clinical specialists, ambulatory surgical center purchasing directors, biomedical engineers, and GPO contracts managers provided ongoing calibration against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS reimbursement coding updates, and hospital procurement contract registries. Bottom-up installed base modeling triangulated with top-down addressable procedure volume estimates across the analysis window.
Scenario-bracketing framed demand projections across product type, application, end user, and technology segmentation dimensions. CAGRs derived from procedure volume elasticity to aging demographic penetration and reimbursement coding maturity. Forecast inputs incorporated femtosecond platform adoption curves in academic medical centers and pattern scanning laser photocoagulation conversion rates in retinal specialist practices.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese domestic manufacturers with NMPA-registered posterior segment systems would shift outcomes through provincial bidding program penetration. Cross-checking against hospital capital equipment procurement databases and GPO contract award registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ophthalmology
Global Photochromic Lenses Market
Ophthalmology
Ophthalmic Loupes Market
Ophthalmology
North America Vision Care Market
Ophthalmology
Global Aphakia Market
Ophthalmology
Retinal Detachment Diagnostic Market
Ophthalmology
Retinal Vasculitis Treatment Market
Ophthalmology
Tonometry Market
Ophthalmology
Europe Ophthalmology Market
Ophthalmology
Ptosis Treatment Market
Ophthalmology
Global Tonometer Market
Ophthalmology
Australia Ophthalmic Devices Market
Ophthalmology
Head Band Ophthalmoscopes Market
Ophthalmology
Optic Nerve Glioma Market
Ophthalmology
Global Ophthalmic Perimeters Market
Ophthalmology
Presbyopia Treatment Market
Ophthalmology
Leber Congenital Amaurosis Market