
 Panama Container Glass Market | 2026-2036
Panama Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Panama Container Glass Market Insights
Central American container glass capacity is narrowing as regional producers consolidate furnace investments near Pacific shipping lanes. VICAL Centroamérica leverages its regional furnace network to supply Panamanian bottlers with reduced lead times. Owens-Illinois Inc. anchors its Central American operations through bulk supply agreements with multinational beverage brands. Ardagh Group competes on lightweighting technology, offering gram-weight reductions that cut freight costs for exporters using the Panama Canal corridor.
Container glass refers to hollow glassware formed by blow-and-blow or press-and-blow processes, typically comprising silica sand, soda ash, limestone, and cullet in ratios yielding 2.5–4.0 mm wall thicknesses for mechanical durability. These vessels serve as chemically inert, infinitely recyclable packaging for liquids and semi-solids requiring oxygen and moisture barriers. The beverage industry segment dominates volume throughput, driven by beer and spirits bottling for domestic consumption and re-export through Colón. Jars command structural attention in the food industry segment, where hermetic sealing specifications for tropical climate stability create specification premiums. Customized design work captures margin concentration as craft distilleries and cosmetic brands seek differentiated shelf presence.
Panama's Ministry of Health enforces sanitary registration for all food-contact packaging, while the Autoridad Nacional del Ambiente monitors emissions from natural-gas-fired furnaces under national air quality protocols. These frameworks elevate compliance investment for importers and domestic manufacturers alike. Stakeholders must weigh furnace fuel switching timelines against the canal logistics premium that defines Panama's strategic packaging role.
Market Dynamics
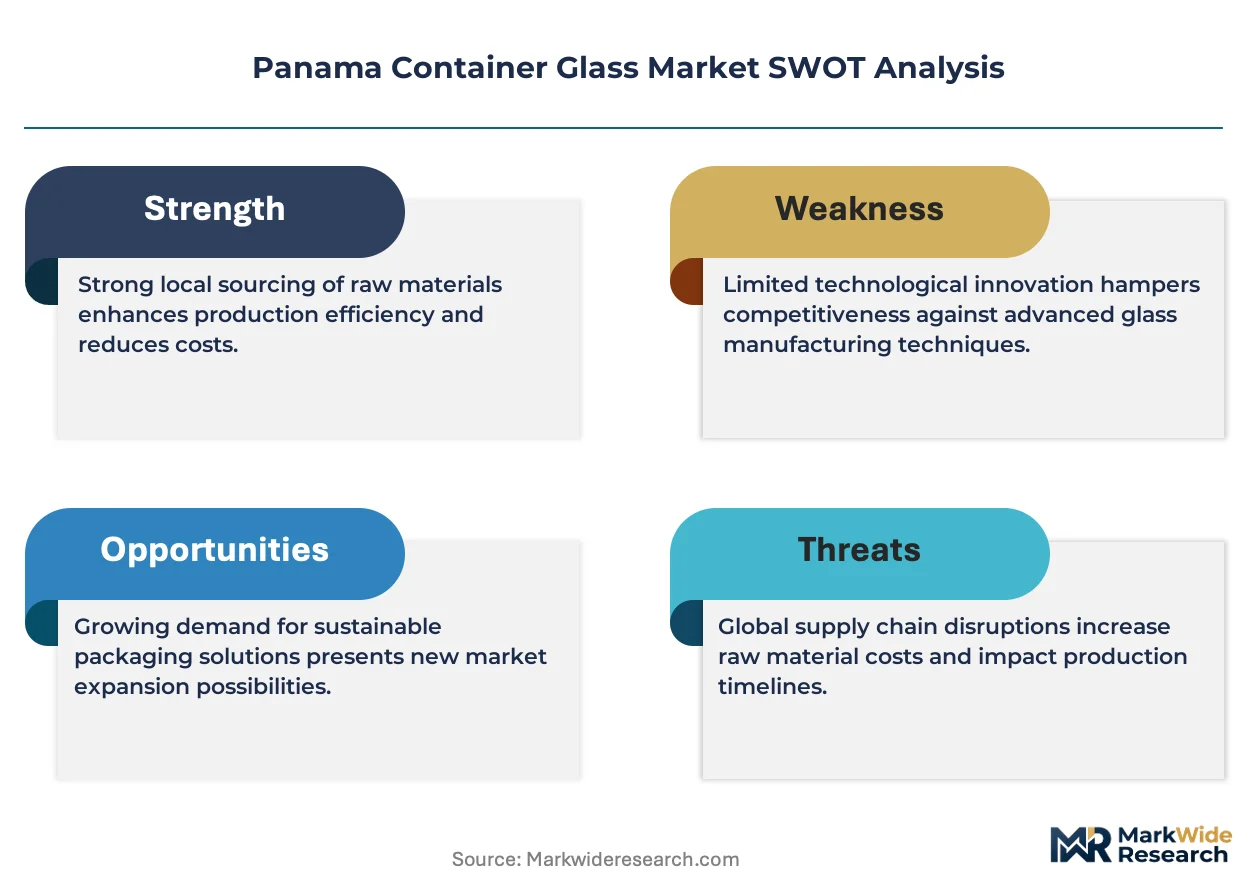
Panama's container glass market pivots on furnace fuel economics and canal corridor logistics premiums. Natural gas price volatility and Ministry of Health sanitary registration timelines compress operating margins for importers and domestic distributors.
Growth Catalysts
- Colón Free Trade Zone re-export demand:Multinational beverage brands route premium spirits and craft beer through Panamanian logistics corridors, generating container glass throughput for regional redistribution.
- Lightweighting technology adoption:Gram-weight reductions in bottle design cut freight costs for exporters leveraging Panama Canal shipping lanes.
- Sanitary registration compliance:Ministry of Health enforcement creates specification premiums for certified packaging suppliers serving domestic food and beverage processors.
Market Restraints
- Natural gas input cost volatility:Furnace operations depend on imported LNG pricing, exposing regional producers to energy cost swings without hedging infrastructure.
- Central American furnace concentration:Regional glassmaking capacity consolidates around VICAL Centroamérica's Pacific network, narrowing supplier alternatives for Panamanian bottlers.
- Aluminum can substitution:Beverage brands increasingly specify metal packaging for carbonated soft drinks and energy drinks, compressing glass volume in select segments.
Strategic Opportunities
- Panama City craft distillery cluster:Small-batch spirits producers seek differentiated bottle designs, opening customized design work for niche glass decorators.
- Circular economy incentives:Autoridad Nacional del Ambiente emissions protocols reward cullet recycling investments, favoring domestic re-melting operations over virgin material imports.
- Cosmetic and pharmaceutical packaging:Hermetic sealing specifications for tropical climate stability create specification premiums in adjacent industries beyond beverages.
Industry Challenges
- Furnace engineering talent scarcity:Specialized refractory maintenance and combustion optimization skills concentrate in legacy manufacturing regions, complicating local workforce development.
- Sanitary registration timeline compression:Ministry of Health approval cycles for new food-contact packaging formulations extend go-to-market schedules for imported specialty glass.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Panama Container Glass Market |
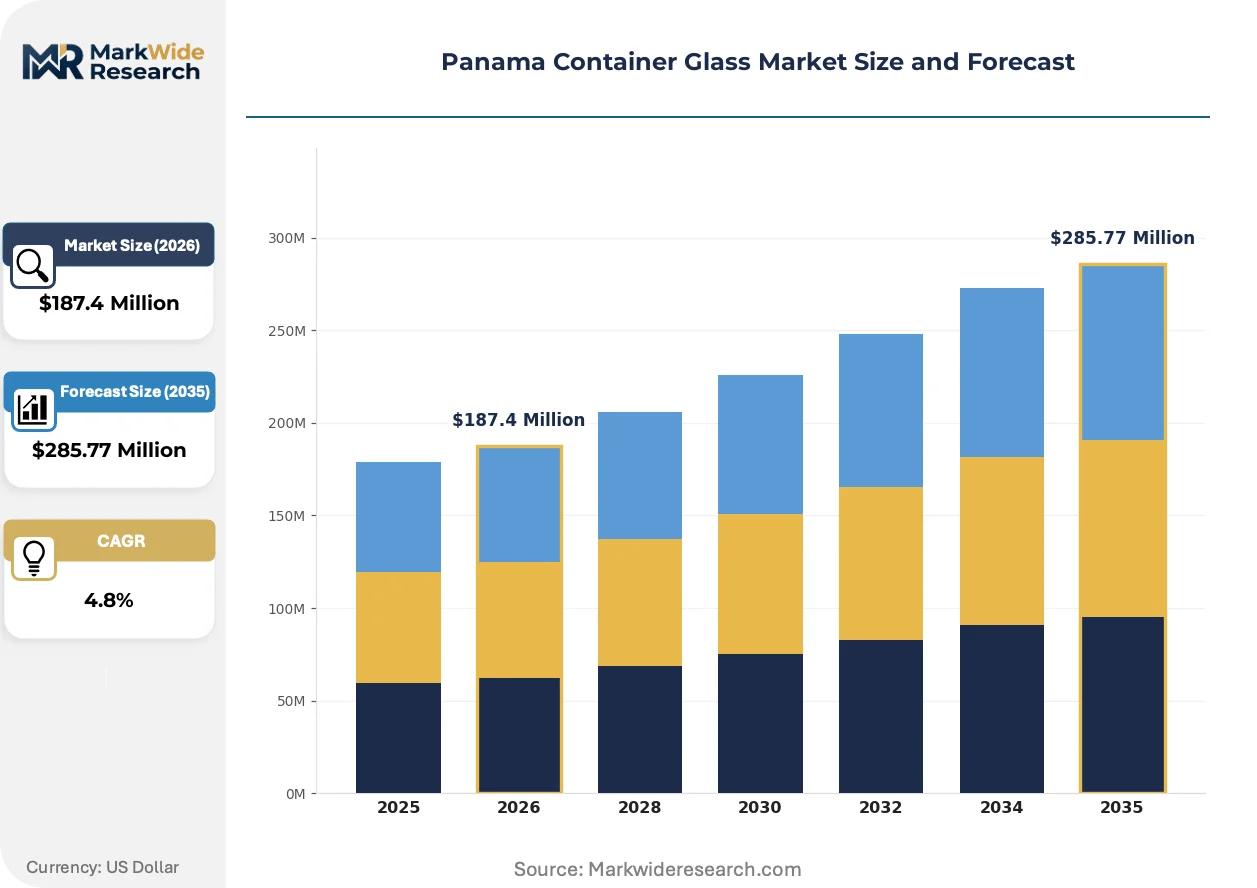
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Cans End User: Beverage Industry, Pharmaceutical Sector, Food Industry, Cosmetics Capacity: 50ml, 200ml, 500ml, 1L Design: Customized, Standard, Decorative, Functional |
| Companies Covered | VICAL Centroamérica, BPS Glass, VETROelite S.r.l., Owens Illinois Argentina, VIDRIOS Y ESPEJOS AMÉRICA, Owens-Illinois Inc., Ardagh Group, Vitro, Saint-Gobain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Panama Container Glass Market Trends and Innovations
Digital process control and sustainability mandates are reconfiguring how container glass moves through Panama's logistics corridors. These shifts alter specification workflows and supplier qualification criteria.
Digital twin simulation is virtualizing furnace thermal profiling and forming process optimization. Regional producers deploy virtual modeling to reduce physical trial runs and cullet waste. The technology compresses new product introduction timelines for custom bottle designs requested by craft distilleries.
Autoridad Nacional del Ambiente air quality protocols tighten emissions monitoring for natural-gas-fired melting operations. Furnace operators must install continuous emissions measurement systems and report particulate and NOx outputs. Bulk supply agreements with multinational beverage brands now incorporate environmental compliance clauses affecting supplier selection.
Consolidated procurement by multinational beverage brands concentrates specification authority at regional headquarters. Panama-based bottlers lose autonomy over packaging design decisions as global standards override local preferences. This pattern concentrates volume with furnace operators capable of pan-regional quality consistency.
Panama Container Glass Market Segmentation
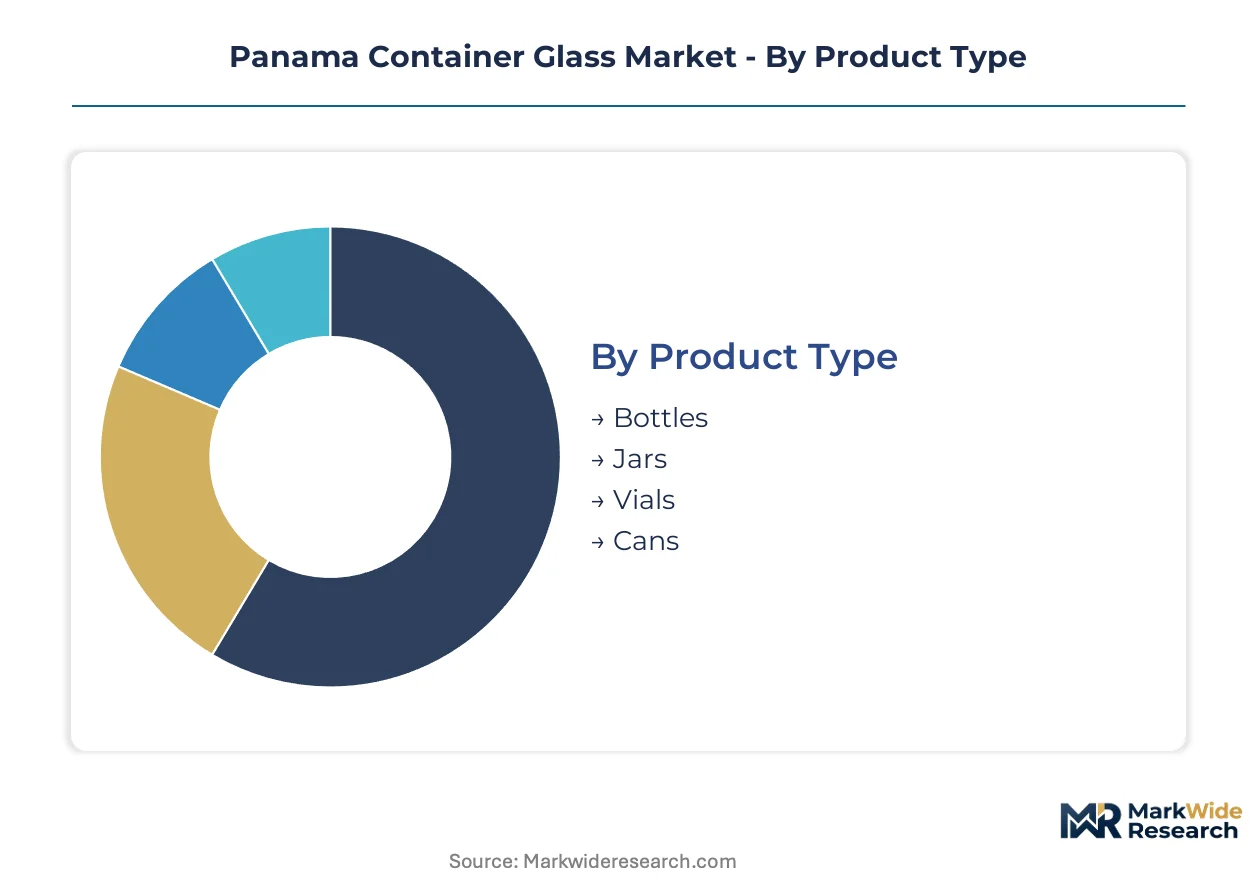
Panama's container glass segmentation reflects the canal corridor's dual role as domestic consumption hub and re-export logistics node. Specification requirements diver sharply between bulk beverage throughput and premium craft positioning.
Product Type:
Mature formats dominate volume flows while emerging shapes capture specification premiums.
- Bottles:Blow-and-blow formed vessels with 2.5–4.0 mm wall thickness serve beer and spirits bottlers in Panama City and Colón Free Trade Zone re-export corridors. Ministry of Health sanitary registration requirements elevate compliance investment for food-contact specifications.
- Jars:Press-and-blow processed containers with hermetic sealing interfaces command structural attention from food processors requiring tropical climate stability. Demand concentrates among domestic manufacturers seeking oxygen and moisture barriers for semi-solid preservation.
- Vials:Small-format pharmaceutical packaging with narrow neck specifications serves Autoridad Nacional del Ambiente-monitored production facilities.
- Cans:Non-traditional glass formats face aluminum substitution pressure in carbonated beverage segments.
Bottles handle the majority of throughput; jars are the fastest mover on share.
End User:
Cost tier differentiation separates commodity volume from specification-driven procurement.
- Beverage Industry:Beer and spirits bottlers generate the dominant volume flow through Panamanian logistics corridors. Multinational brand procurement consolidation concentrates specification authority at regional headquarters, compressing local design autonomy.
- Food Industry:Hermetic sealing requirements for tropical climate stability create specification premiums. Domestic processors face extended Ministry of Health approval cycles for new food-contact packaging formulations.
- Pharmaceutical Sector:Vial and bottle demand ties to sanitary registration compliance timelines for imported specialty glass.
- Cosmetics:Customized design work captures margin concentration as brands seek differentiated shelf presence in Panama City retail corridors.
The beverage industry commands volume leadership; cosmetics is expanding most quickly on specification premiums.
Capacity:
Volume scale determines furnace batch economics and freight optimization through canal shipping lanes.
- 500ml:Standard beer and spirits format optimizes palletization density for Colón Free Trade Zone re-export operations. Lightweighting technology adoption cuts gram-weight to reduce freight costs for exporters leveraging Panama Canal routes.
- 1L:Large-format spirits and premium beverage packaging serves craft distillery cluster demand in Panama City. Customized design work opens niche opportunities for differentiated bottle shapes.
- 200ml:Travel retail and sample formats align with duty-free corridor throughput.
- 50ml:Miniature formats serve airline and hospitality sampling programs.
500ml handles the majority of throughput; 1L is climbing the fastest on craft positioning.
Design:
Margin structure separates functional commodity supply from value-added customization services.
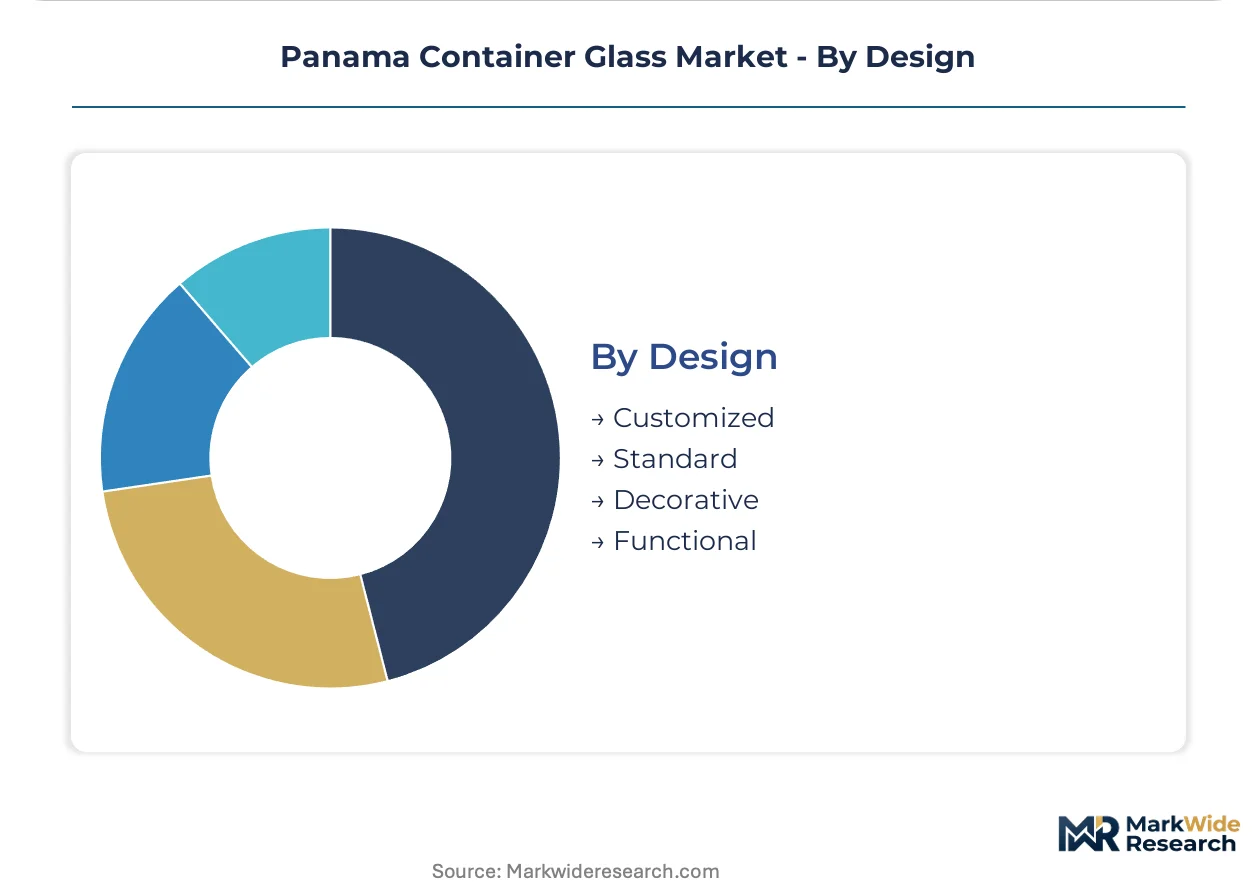
- Customized:Bespoke mold development and decorative finishing capture premium pricing from craft distilleries and cosmetic brands seeking shelf differentiation. Digital twin simulation compresses new product introduction timelines for regional producers.
- Standard:Catalog designs serve multinational beverage brand bulk supply agreements requiring pan-regional quality consistency.
- Decorative:Applied ceramic labeling and embossed surface treatments serve premium spirits positioning.
- Functional:Specification-optimized designs prioritize hermetic sealing and mechanical durability for tropical logistics stress.
Standard designs handle the majority of throughput; customized work is gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Panama's container glass consumption diverges from regional peers through its dual function as domestic bottling hub and canal logistics re-export node, whereas neighboring Central American markets prioritize local beverage supply chains over international transit corridors.
Panama City Metro
Craft distillery clusters and premium spirits bottlers drive demand for customized bottle designs with hermetic sealing specifications. The Ministry of Health enforces sanitary registration timelines that compress product introduction schedules for imported specialty glass. Colón Free Trade Zone logistics corridors concentrate re-export throughput for multinational beverage brands.
Colón Province
Bulk beverage redistribution operations generate standardized container glass volume flows through Pacific shipping lanes. Autoridad Nacional del Ambiente emissions protocols govern natural-gas-fired furnace operations near port facilities. Duty-free corridor infrastructure supports travel retail and sampling format demand.
Chiriquí Highlands
Domestic food processors source jar formats requiring tropical climate stability for semi-solid preservation. Ministry of Health approval cycles extend lead times for new food-contact packaging formulations. David industrial corridor hosts regional distribution nodes serving western Panama agricultural zones.
Veraguas Corridor
Emerging logistics infrastructure connects Pacific port facilities to interior bottling operations. Cullet recycling investments align with Autoridad Nacional del Ambiente circular economy incentives. Santiago commercial hub intermediates between Panama City supply chains and rural consumption centers.
Darién Frontier
Limited road infrastructure constrains container glass distribution to subsistence-level beverage markets. Informal supply chains dominate local packaging procurement. La Palma river port serves as minimal throughput node for eastern zone logistics.
Panama Container Glass Market Competitive Landscape
Capability concentration sits with regional furnace operators; scale advantage sits with multinational packaging conglomerates. The market structures around three tiers: Pacific-network furnace operators with regional batch economics, global glass manufacturers with pan-regional quality protocols, and specialized decorators serving niche design segments. Strategic moves center on lightweighting technology licensing and bulk supply agreement consolidation with multinational beverage brands.
Among regional furnace operators, VICAL Centroamérica anchors the Pacific network tier with cross-border supply capabilities. Owens-Illinois Inc. and Ardagh Group exemplify the multinational conglomerate archetype, occupying positions defined by pan-regional quality consistency and environmental compliance integration. These three represent the dominant competitive anchors shaping procurement patterns across Panamanian logistics corridors.
| Leading Market Players |
|---|
| VICAL Centroamérica |
| BPS Glass |
| VETROelite S.r.l. |
| Owens Illinois Argentina |
| VIDRIOS Y ESPEJOS AMÉRICA |
| Owens-Illinois Inc. |
| Ardagh Group |
| Vitro |
| Saint-Gobain |
| Others |
Pricing and Supply Chain Analysis
Natural gas price volatility at regional Pacific furnace networks determines both premium-to-economy pricing spreads and the geographic shape of Panamanian supply chains. LNG import cost swings compress margins for Colón Free Trade Zone re-export operations while pushing procurement toward consolidated bulk supply agreements with multinational beverage brands.
Pricing Analysis
Geographic price spreads widen between Panama City craft distillery clusters and Colón bulk re-export corridors. Pricing stratifies across premium customized designs, standard catalog formats, and economy-grade bulk supply tiers. Cost compression in the economy tier intensifies because aluminum can substitution pressure forces glass suppliers to absorb freight differentials. Multinational beverage procurement teams exhibit lowest price sensitivity; craft distilleries show highest sensitivity to mold development costs.
Supply Chain Analysis
Tariff exposure between Central American furnace networks and Panamanian bottlers dominates supply chain risk assessment. Manufacturing concentrates in Costa Rica, Guatemala, and El Salvador as VICAL Centroamérica anchors regional batch economics. Silica sand, soda ash, and cullet feedstock dependencies rest on Pacific shipping lane reliability. Single-source vulnerability concentrates around natural-gas-fired furnace operations. Distribution runs through Colón Free Trade Zone logistics corridors for re-export volume and Panama City metro nodes for domestic consumption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Panama's container glass market sits at a platform-economics inflection where digital twin simulation ecosystems are collapsing new product introduction timelines and reshaping supplier qualification protocols across canal corridor logistics.
For Market Incumbents: Build switching-cost moats through embedded digital process control partnerships with craft distillery clusters. Secure exclusive lightweighting technology licensing agreements to lock in multinational beverage brand volume. Aluminum can substitution in carbonated soft drinks threatens volume retention; vertical integration into cullet recycling operations defends margin position against virgin material cost spikes.
For New Entrants and Emerging Players: Build out niche decorative finishing capabilities targeting Panama City cosmetic brand procurement. The pharmaceutical vial segment offers most penetrable white-space given extended Ministry of Health approval cycles that disadvantage established import channels. Lead with rapid digital prototyping services that compress sanitary registration timelines for domestic food processors.
For Investors and Strategic Acquirers: Autoridad Nacional del Ambiente emissions protocol tightening reshapes the acquisition landscape toward furnace operators with continuous monitoring infrastructure already deployed. Long-term viability centers on pan-regional quality consistency capabilities rather than single-country positioning. Target furnace operators with demonstrated compliance integration across multiple Central American jurisdictions. The signal to watch is bulk supply agreement renewal concentration with multinational beverage brands.
| Strategic Initiative | Industry Significance |
|---|---|
| Lightweighting Technology Licensing | Gram-weight reductions cut freight costs for exporters using Panama Canal shipping lanes. |
| Cullet Recycling Infrastructure Investment | Autoridad Nacional del Ambiente protocols reward domestic re-melting over virgin imports. |
| Digital Twin Simulation Deployment | Virtual furnace modeling compresses new product introduction timelines for craft distilleries. |
| Bulk Supply Agreement Consolidation | Multinational beverage brand procurement concentrates volume with pan-regional quality operators. |
| Hermetic Sealing Specification Development | Tropical climate stability requirements create premium positioning in food and pharmaceutical segments. |
Research Methodology
Operator-level perspectives from furnace engineering directors, beverage brand procurement leads, Ministry of Health regulatory affairs officers, and Colón Free Trade Zone logistics coordinators anchored the qualitative base. Primary interview data combined with secondary validation from Autoridad Nacional del Ambiente emissions filings, Panama Ministry of Health sanitary registration databases, and Central American customs trade records. Bottom-up volume modeling and top-down market sizing triangulated across the analysis window.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation modeled by product type, end-use industry, capacity tier, and design customization level. CAGRs derived from historical trajectory analysis adjusted for furnace fuel cost elasticity and canal logistics premium persistence. Forecast inputs incorporated natural gas price volatility assumptions and lightweighting technology adoption curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Pacific-network furnace operators or accelerated aluminum can substitution by beverage brands would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Belarus Container Glass Market
Glass Packaging
Glass Bottle Molds Market
Glass Packaging
France Glass Packaging Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Glass Jugs Market
Glass Packaging
Pharmaceutical Glass Packaging Market
Glass Packaging
Morocco Container Glass Market
Glass Packaging
Philippines Container Glass Market
Glass Packaging
Indonesia Container Glass Market
Glass Packaging
Oman Container Glass Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Thailand Container Glass Market
Glass Packaging
Asia Pacific Glass Packaging Market
Glass Packaging
United States Glass Packaging Market
Glass Packaging
Germany Container Glass Market