
 South Korea Wound Care Management Market | 2026-2036
South Korea Wound Care Management Market Size, Share, and Industry Trends Forecast 2026-2036
South Korea Wound Care Management Market Analytics
Home healthcare is broadening the addressable patient base for wound management beyond traditional institutional settings. Molnlycke Health Care leverages its European manufacturing heritage to sustain premium positioning in advanced dressing categories. Young Chemical Co Ltd anchors domestic supply chains through localized production of hydrocolloid and foam substrates. Daewoong Pharmaceutical competes via pharmaceutical-distribution integration that extends reach into provincial clinics.
Wound care management encompasses the clinical assessment, treatment, and monitoring of acute and chronic tissue injuries using absorbent dressings, antimicrobial barriers, moisture-retentive substrates, and biologically active matrices designed to accelerate re-epithelialization and prevent secondary infection. The primary commercial purpose centers on reducing healing time, lowering complication rates, and shifting appropriate cases from inpatient to outpatient or home-based settings. Advanced dressings command margin concentration due to polymer science differentiation and reimbursement premiums for moist-wound-healing efficacy. Biologics represent the fastest-expanding technology segment as skin-substitute grafts and growth-factor formulations penetrate diabetic foot ulcer protocols. Hospital end users still occupy the largest volume share, though home healthcare channels are gaining structural importance as telemedicine integration and caregiver training standards mature.
MFDS governs medical device registration and clinical evidence requirements for advanced wound products entering the South Korean market, while the Ministry of Health and Welfare sets reimbursement tiers that directly influence hospital procurement decisions and patient out-of-pocket exposure. MFDS alignment with MDR-equivalent standards is forcing multinational manufacturers to resubmit technical documentation, creating compliance delays that advantage domestic incumbents with established quality-management systems. Stakeholders must monitor how post-acute bundling reforms and home-care reimbursement expansion reshape channel economics and product-form requirements.
Market Dynamics
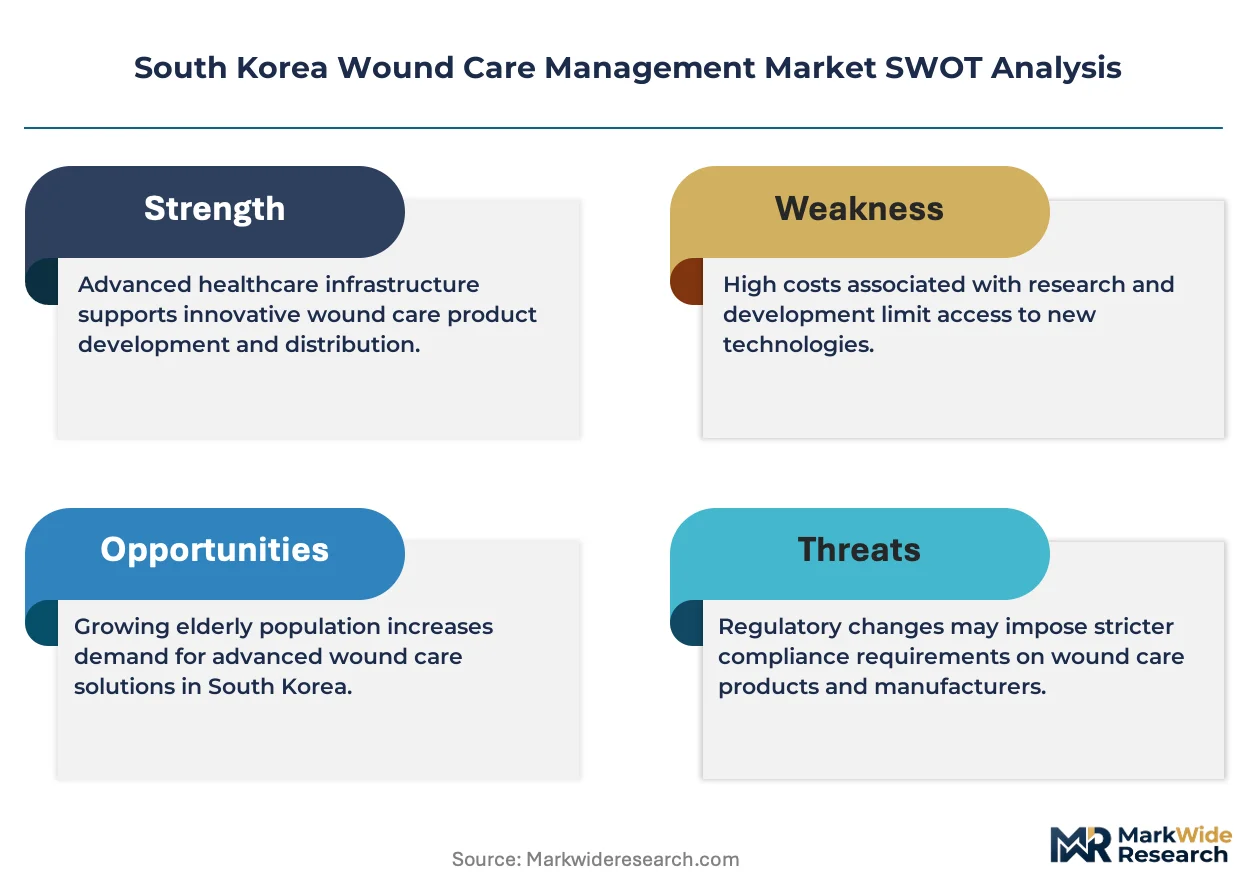
MFDS regulatory alignment with MDR-equivalent standards is compressing product registration timelines and forcing technical documentation resubmissions, advantaging domestic incumbents with established quality-management systems while delaying multinational market entry.
Growth Catalysts
- Home Healthcare Expansion:Post-acute patients in Seoul's metropolitan networks actively seek alternatives to extended hospital stays, broadening the addressable patient base beyond traditional institutional settings.
- MFDS Reimbursement Tier Adjustments:The Ministry of Health and Welfare's revised reimbursement categories for moist-wound-healing efficacy are creating procurement premiums that reward polymer science differentiation in advanced dressings.
- Biologics Penetration:Skin-substitute grafts and growth-factor formulations are accelerating adoption within diabetic foot ulcer protocols, representing the fastest-expanding technology segment by clinical application.
Market Restraints
- Petrochemical Input Volatility:Hydrocolloid and foam substrate production depends on petroleum-derived polymer feedstocks, exposing domestic manufacturers like Young Chemical Co Ltd to raw material cost swings.
- Seoul Metropolitan Supply Concentration:Hospital network procurement decisions cluster within the capital region, creating geographic dependency risk for distributors serving provincial wound clinics.
- MFDS Technical Documentation Resubmission:MDR-equivalent compliance requirements are generating registration delays of 12-18 months for multinational advanced dressing manufacturers lacking prior Korean quality-system certifications.
Strategic Opportunities
- Provincial Clinic Penetration:Daewoong Pharmaceutical's pharmaceutical-distribution integration model offers a template for extending reach into underserved Gyeongsang and Jeolla region outpatient facilities.
- Telemedicine-Home Care Convergence:Caregiver training standards and remote monitoring platforms are maturing simultaneously, enabling new product-form requirements for home-based negative pressure wound therapy.
- Biologics Reimbursement Expansion:Post-acute bundling reforms under Ministry of Health and Welfare review are expected to create coverage pathways for cellular and tissue-based products previously restricted to self-pay.
Industry Challenges
- Clinical Evidence Generation Capacity:Multinational manufacturers face compressed timelines to generate Korean patient population data supporting moist-wound-healing efficacy claims under MFDS evidentiary standards.
- Legacy Distribution Integration:Pharmaceutical-distribution networks require substantial workflow reconfiguration to accommodate temperature-sensitive biologics alongside traditional dressing inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Korea Wound Care Management Market |
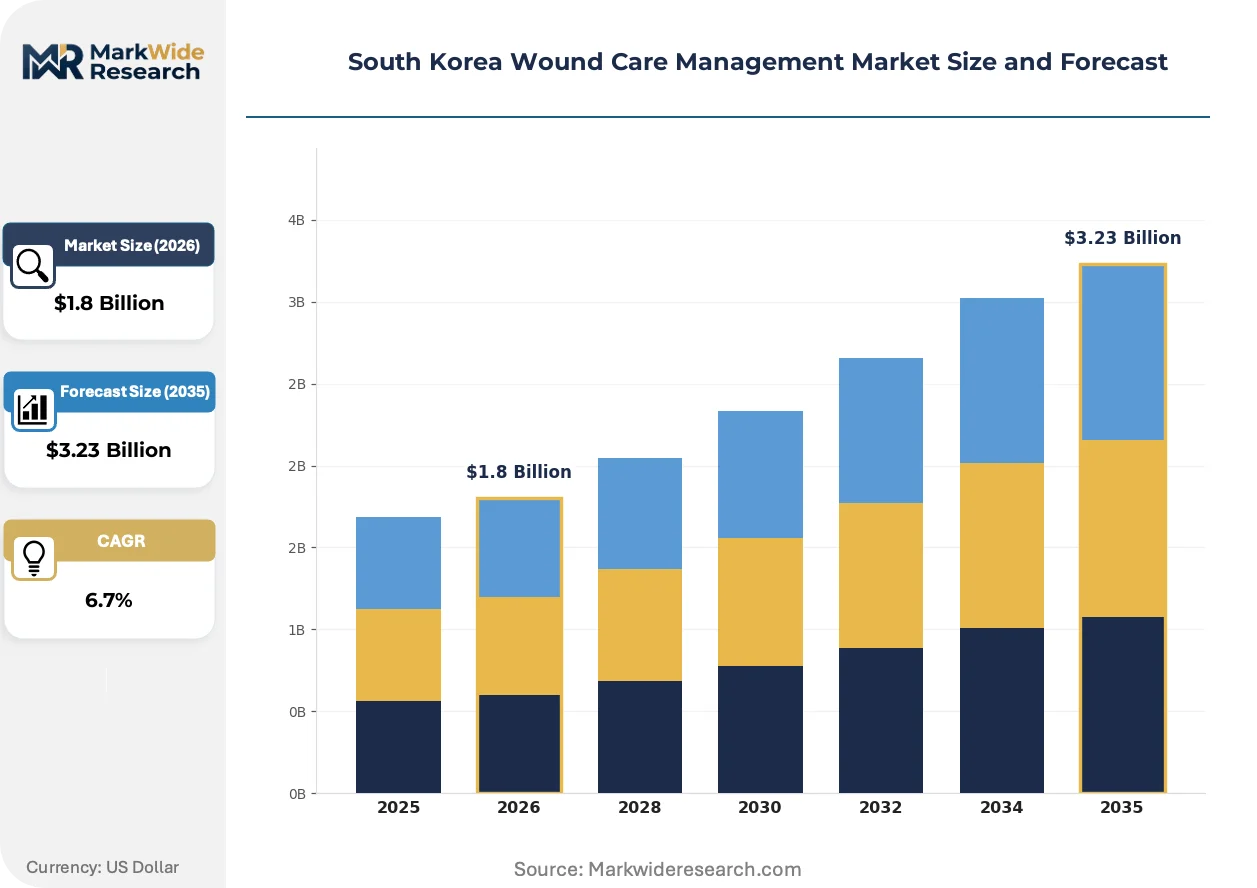
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dressings, Gels, Bandages, Ointments End User: Hospitals, Clinics, Home Healthcare, Long-term Care Facilities Application: Chronic Wounds, Surgical Wounds, Traumatic Wounds, Burns Technology: Advanced Dressings, Biologics, Foam Dressings, Hydrocolloid Dressings |
| Companies Covered | Molnlycke Health Care, Beiersdorf AG, Johnson & Johnson (Ethicon), Young Chemical Co Ltd, Essity Aktiebolag, Smith & Nephew, Medtronic, Daewoong Pharmaceutical, Convatec Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Korea Wound Care Management Market Evolving Landscape
Telemedicine platforms and remote patient monitoring systems are actively restructuring how wound assessment and dressing changes are supervised outside hospital walls, compressing the traditional care continuum.
Antimicrobial silver-ion and iodine-impregnated dressings are integrating with wearable biosensors that transmit moisture levels and infection biomarkers to centralized monitoring dashboards. Seoul's affiliated outpatient wound clinics are piloting these systems for diabetic foot ulcer patients, enabling earlier intervention and reducing unplanned readmissions. The technology is integrating clinical workflows with logistics platforms that trigger automated replenishment of advanced dressings based on healing trajectory algorithms.
MFDS implementation of MDR-equivalent technical documentation standards is forcing manufacturers to resubmit clinical evidence packages previously accepted under legacy device directives. Domestic incumbents with ISO 13485-certified quality systems are accelerating product line extensions while multinational competitors navigate extended review queues. Advanced dressing classifications with moist-wound-healing claims face the most stringent scrutiny, reshaping registration pathway economics across the competitive landscape.
Hospital procurement committees are consolidating vendor relationships and unbundling after-sales clinical training from product pricing. Major metropolitan networks in Seoul and Busan are negotiating multi-year supply agreements that specify outcome-based performance thresholds for healing time reduction. Provincial clinics lag this consolidation by approximately 18-24 months, maintaining fragmented purchasing patterns that sustain smaller domestic distributors.
South Korea Wound Care Management Market Segmentation
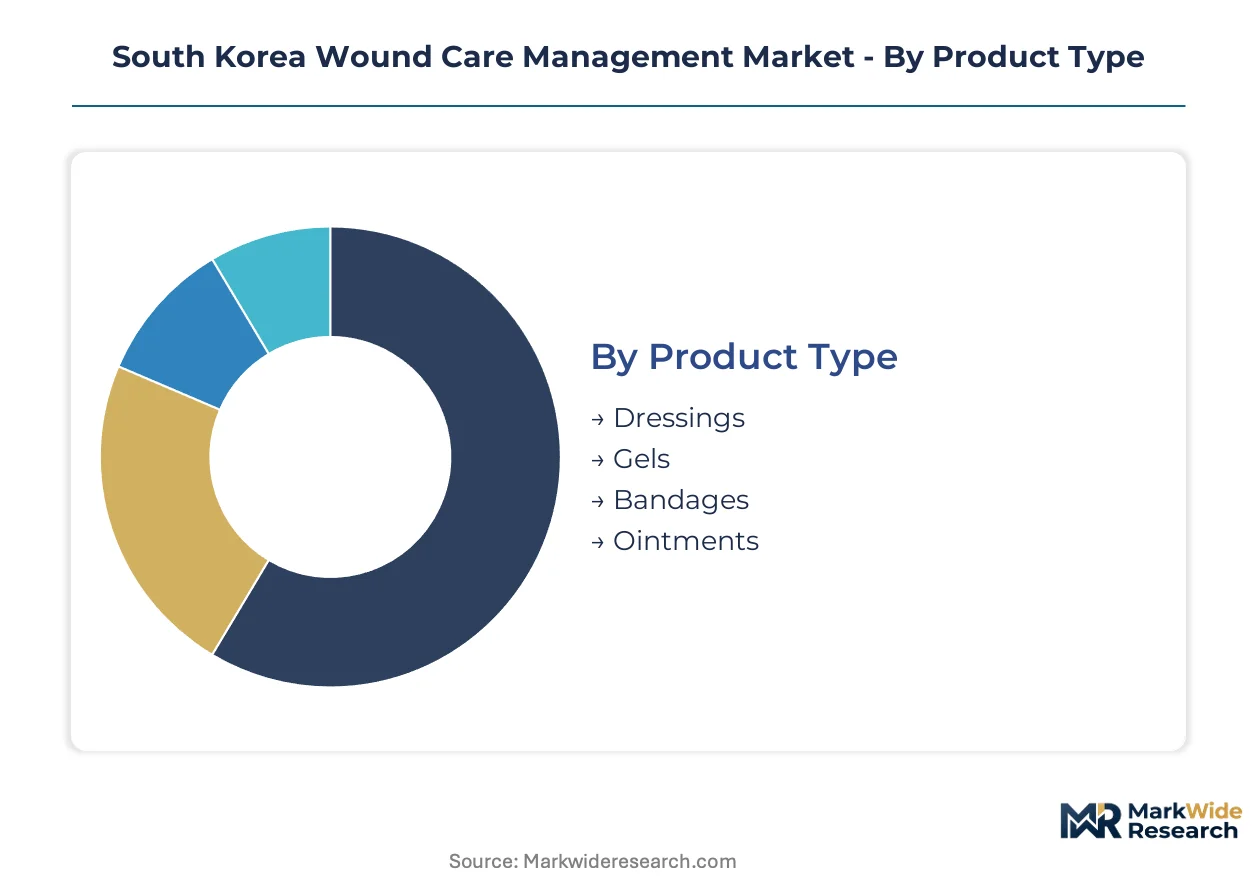
Product form and clinical setting dictate reimbursement tiers and procurement pathways across South Korea's wound care landscape. Segmentation reveals where polymer science differentiation commands premium positioning versus where commodity absorption drives volume economics.
Product Type:
Customization intensity spans from sterile single-use films to compounded topical formulations requiring pharmacy preparation.
- Dressings:Polymer-based substrates including hydrocolloid, foam, and alginate matrices engineered for moisture-retentive environments. Seoul's metropolitan hospital networks concentrate demand for advanced variants with silver-ion antimicrobial integration.
- Gels:Hydrogel and amorphous formulations delivering hydration to desiccated wound beds. Post-acute facilities in Busan and Daegu are expanding gel procurement as home healthcare protocols mature.
- Bandages:Adhesive strips and conforming rolls for minor trauma and fixation layering.
- Ointments:Petrolatum-based and antimicrobial topical preparations for superficial epidermal injuries.
Most installed capacity flows through Dressings. Expansion is steepest in Gels.
End User:
Channel economics diverge sharply between centralized procurement committees and fragmented direct-to-patient supply.
- Hospitals:Tertiary and secondary acute care institutions managing complex surgical and trauma cases through centralized purchasing. Seoul's five major university-affiliated networks dominate volume concentration and vendor consolidation decisions.
- Home Healthcare:Post-acute patients receiving dressing changes through visiting nurse services or family caregiver protocols. MFDS reimbursement expansion for remote monitoring is accelerating channel migration from institutional settings.
- Clinics:Outpatient wound centers and primary care facilities handling debridement and chronic wound maintenance.
- Long-term Care Facilities:Nursing homes and rehabilitation centers managing pressure ulcer prevention and maintenance.
Hospital procurement absorbs the largest revenue share. Home Healthcare channels are gaining share fastest as telemedicine integration matures.
Application:
Wound etiology determines the clinical evidence burden for product registration and reimbursement qualification.
- Chronic Wounds:Diabetic foot ulcers, venous leg ulcers, and pressure injuries persisting beyond standard healing timelines. Gyeongsang region diabetes prevalence is driving concentration of advanced dressing trials for this indication.
- Surgical Wounds:Incision sites from elective and emergency procedures requiring infection prevention and optimal scar formation.
- Traumatic Wounds:Acute lacerations, abrasions, and penetrating injuries from industrial and traffic incidents.
- Burns:Thermal, chemical, and electrical injuries requiring specialized moisture management and infection control.
Chronic Wounds command the highest per-patient expenditure. Surgical Wounds maintain the steadiest volume throughput.
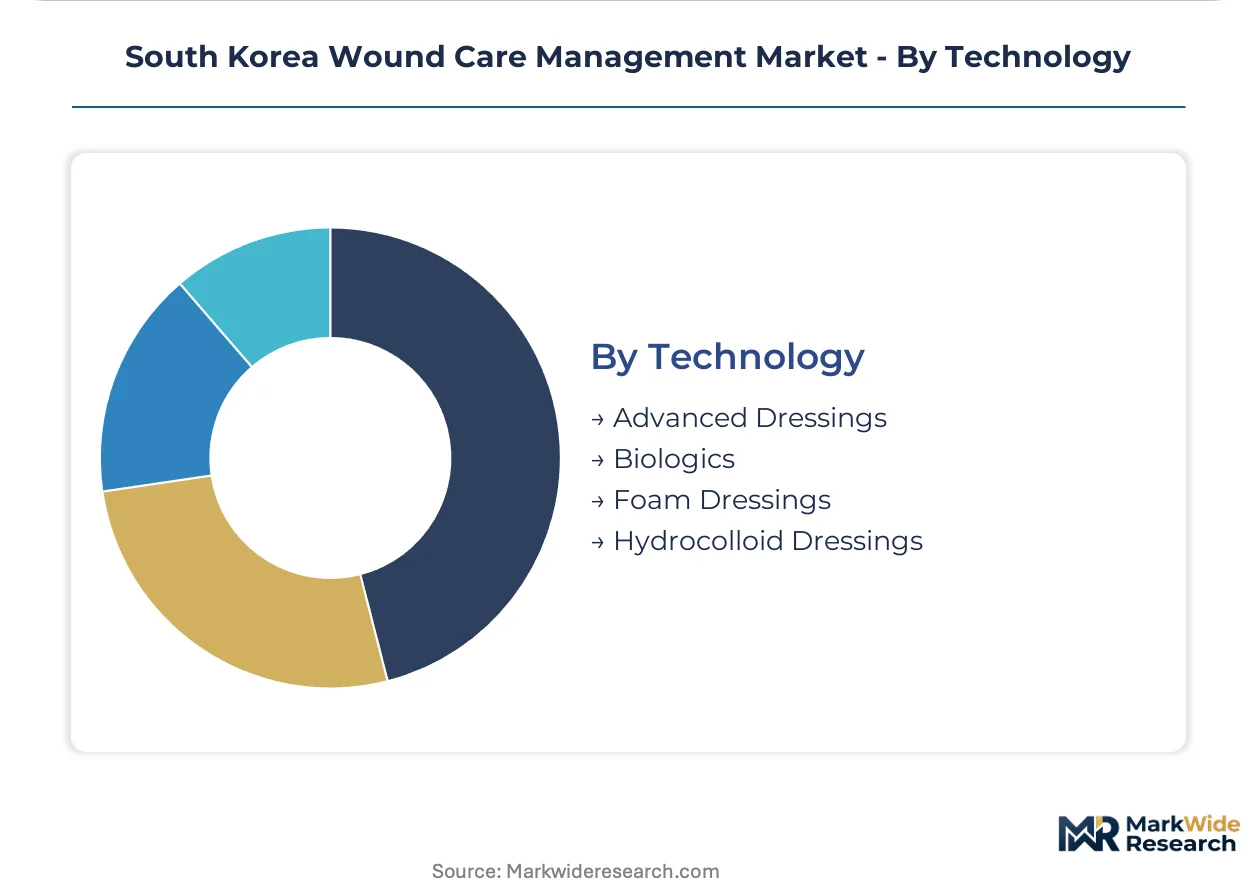
Technology:
Regulatory scrutiny intensity increases with biological activity claims and polymer complexity.
- Advanced Dressings:Moisture-retentive substrates with integrated antimicrobial agents or selective permeability membranes. MFDS MDR-equivalent documentation requirements are compressing registration timelines for multinational manufacturers lacking prior Korean quality certifications.
- Biologics:Cellular and tissue-based products including skin substitutes and growth-factor formulations. Jeolla region academic medical centers are piloting reimbursement pathways for diabetic foot ulcer applications previously restricted to self-pay.
- Foam Dressings:Polyurethane absorbent layers for moderate-to-heavy exudate management.
- Hydrocolloid Dressings:Gel-forming carboxymethylcellulose matrices for low-to-moderate exudate environments.
Advanced Dressings anchor current revenue concentration. Biologics are climbing the fastest as post-acute bundling reforms create coverage pathways.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MFDS regulatory alignment with MDR-equivalent standards has opened a cost-of-compliance gap that favors domestic manufacturers with established Korean quality-management certifications over multinational entrants facing 12-18 month documentation resubmissions.
Seoul Capital Area
Seoul's five major university-affiliated hospital networks concentrate procurement decisions for advanced dressings with silver-ion antimicrobial integration. MFDS reimbursement tier adjustments for moist-wound-healing efficacy are creating procurement premiums that reward polymer science differentiation. The metropolitan outpatient wound clinics are piloting wearable biosensor systems for diabetic foot ulcer patients.
Busan-Ulsan
Post-acute facilities in this southeastern corridor are expanding hydrogel procurement as home healthcare protocols mature and telemedicine integration accelerates channel migration. The Ministry of Health and Welfare's revised reimbursement categories are enabling coverage expansion for remote monitoring services. Ulsan's industrial base supplies petroleum-derived polymer feedstocks for hydrocolloid and foam substrate production.
Daegu-Gyeongbuk
Gyeongsang region diabetes prevalence is driving concentration of advanced dressing trials for chronic wound indications. Provincial clinics here maintain fragmented purchasing patterns that sustain smaller domestic distributors. Daewoong Pharmaceutical's pharmaceutical-distribution integration model extends reach into these underserved outpatient facilities.
Daejeon-Sejong
Regulatory expertise concentrates in this administrative corridor where MFDS technical documentation review occurs. Biologics reimbursement expansion is under active Ministry of Health and Welfare review for post-acute bundling reforms. Sejong's policy proximity enables faster regulatory intelligence translation for manufacturers navigating compliance transitions.
Gwangju-Honam
Jeolla region academic medical centers are piloting reimbursement pathways for cellular and tissue-based products previously restricted to self-pay. Geographic distance from Seoul procurement committees creates pricing flexibility for domestic incumbents. The Honam corridor's rehabilitation centers are expanding pressure ulcer prevention protocols for long-term care populations.
South Korea Wound Care Management Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational premium-positioned players facing compressed registration timelines while domestic incumbents exploit established quality-system advantages. The vendor base organizes into three tiers: European heritage manufacturers with advanced dressing portfolios, Korean chemical conglomerates with localized substrate production, and pharmaceutical-distribution integrators extending into provincial channels. Dominant competitive moves include multi-year supply agreements with outcome-based performance thresholds and vertical integration into polymer feedstock supply.
Among European heritage manufacturers, Molnlycke Health Care exemplifies premium-tier positioning sustained by manufacturing heritage in advanced dressing categories. Young Chemical Co Ltd anchors domestic supply chain control through localized production of hydrocolloid and foam substrates. Daewoong Pharmaceutical occupies the pharmaceutical-distribution integration archetype, extending commercial reach into provincial clinics beyond Seoul's metropolitan concentration.
| Leading Market Players |
|---|
| Molnlycke Health Care |
| Beiersdorf AG |
| Johnson & Johnson (Ethicon) |
| Young Chemical Co Ltd |
| Essity Aktiebolag |
| Smith & Nephew |
| Medtronic |
| Daewoong Pharmaceutical |
| Convatec Inc. |
| Others |
Value Network & Pricing Analysis
Seoul metropolitan hospital procurement committees are consolidating vendor relationships and demanding outcome-based performance thresholds, forcing manufacturers to absorb clinical training costs into pricing while domestic incumbents with captive substrate production exploit margin buffers. This buyer-side consolidation compresses channel economics and rewards backward integration into polymer feedstock supply.
Pricing Analysis
Distributor margin compression runs through pharmaceutical-distribution networks as Daewoong Pharmaceutical's integrated model sets benchmark terms for provincial clinic penetration. Pricing stratifies across premium, standard, and economy tiers based on MFDS moist-wound-healing efficacy certification and silver-ion antimicrobial integration. Cost compression in economy hydrocolloid segments is intensifying because Young Chemical Co Ltd's localized production anchors volume pricing. Provincial wound clinics exhibit highest price sensitivity while Seoul's university-affiliated networks prioritize clinical outcomes over per-unit cost.
Supply Chain Analysis
MFDS MDR-equivalent quality-system certification gates supplier qualification, advantaging domestic incumbents with ISO 13485-certified facilities over multinational entrants facing documentation resubmission delays. Manufacturing draws from South Korea, Germany, and Sweden for advanced dressing polymer science, with petroleum-derived carboxymethylcellulose and polyurethane foam feedstocks sourced from Ulsan's industrial petrochemical base. Single-source vulnerability concentrates in silver-ion antimicrobial active ingredient supply. Distribution runs through pharmaceutical wholesalers to hospital procurement committees and direct-to-clinic field sales for advanced dressings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The South Korea wound care management market reads as a late-cycle quality story where MFDS reimbursement tier adjustments for moist-wound-healing efficacy are shifting procurement premiums toward clinically differentiated advanced dressings.
For Market Incumbents: Anchor defensive positioning through backward integration into hydrocolloid and foam substrate production to offset petrochemical input volatility, while securing multi-year supply agreements with Seoul's five major university-affiliated networks that embed outcome-based healing time reduction clauses. Threat substitution from biologics penetration in diabetic foot ulcer protocols demands parallel investment in skin-substitute graft distribution partnerships.
For New Entrants and Emerging Players: The price-point gap between Molnlycke Health Care premium positioning and domestic economy-tier hydrocolloid suppliers creates white-space opportunity for mid-tier antimicrobial foam variants targeting Busan-Ulsan post-acute facilities. Most penetrable entry vector lies in telemedicine-integrated home healthcare channels where caregiver training standards are maturing. Go-to-market execution should leverage pharmaceutical-distribution integration templates for provincial Gyeongsang and Jeolla region clinic access.
For Investors and Strategic Acquirers: Asymmetric upside sits with domestic chemical conglomerates possessing ISO 13485-certified quality systems and captive polymer substrate production, as MFDS regulatory alignment with MDR-equivalent standards extends multinational registration delays. Long-term viability over a 5-10 year window favors acquisition targets with established hospital procurement committee relationships and biologics reimbursement pathway positioning. Signal to monitor is Ministry of Health and Welfare post-acute bundling reform implementation creating coverage expansion for cellular and tissue-based products.
| Strategic Initiative | Industry Significance |
|---|---|
| MFDS MDR-Equivalent Compliance Investment | Accelerates product registration timelines for manufacturers with pre-existing Korean quality-system certifications versus multinational documentation resubmission delays. |
| Telemedicine-Home Care Integration | Enables remote monitoring platform partnerships with Seoul metropolitan outpatient wound clinics for diabetic foot ulcer patient cohorts. |
| Biologics Reimbursement Strategy | Positions skin-substitute graft portfolios for Ministry of Health and Welfare post-acute bundling reform coverage expansion. |
| Pharmaceutical-Distribution Channel Control | Extends commercial reach into underserved Gyeongsang and Jeolla provincial clinics through Daewoong Pharmaceutical integration templates. |
| Backward Integration into Polymer Feedstocks | Captures margin buffers against petroleum-derived hydrocolloid and foam substrate cost volatility from Ulsan petrochemical supply. |
Research Methodology
Coverage spans Seoul Capital Area, Busan-Ulsan corridor, Daegu-Gyeongbuk region, Daejeon-Sejong administrative zone, and Gwangju-Honam belt, with primary inputs from each geography triangulated against secondary validation. Primary interviews engaged hospital procurement managers, GPO contracts specialists, biomedical engineers, wound care clinicians, and pharmaceutical-distribution executives. Secondary sources included MFDS medical device registration databases, Ministry of Health and Welfare reimbursement bulletins, hospital procurement committee minutes, and trade customs data for polymer substrate imports. Bottom-up patient-flow modeling and top-down expenditure analysis were cross-validated.
Rate-of-change decomposition across the analysis window segmented volume and value trajectories by product type, end-user channel, wound etiology application, and technology tier including advanced dressings versus biologics. CAGRs were derived from installed base evolution, replacement cycle dynamics, and reimbursement pathway expansion assumptions. Industry-specific forecast inputs incorporated MFDS regulatory review queue durations and Ministry of Health and Welfare post-acute bundling reform implementation probability.
Caveats apply where MFDS technical documentation resubmission timelines or Ministry of Health and Welfare reimbursement tier adjustments could materially shift the outlook for multinational versus domestic manufacturer competitive positioning. Forecasts reflect assumptions around telemedicine-home care convergence velocity and biologics clinical evidence generation capacity. A model refresh is warranted upon material change in post-acute bundling reform implementation schedule.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wound Care
Wound Healing Nutrition Market
Wound Care
Bioactive Wound Care Market
Wound Care
Wound Closure and Advanced Wound Care Market
Wound Care
Advanced Wound Dressings Market
Wound Care
Maggot Debridement Market
Wound Care
Asia Pacific Negative Pressure Wound Therapy Market
Wound Care
Global Digital Wound Measurement Devices Market
Wound Care
North America Advanced Wound Care Market
Wound Care
Autologous Wound Patches Market
Wound Care
Bioadhesive Wound Care Market
Wound Care
Asia Pacific Wound Care Biologics Market
Wound Care
Negative Pressure Wound Therapy Market
Wound Care
Mexico Wound Care Management Devices Market
Wound Care
Animal Wound Care Market
Wound Care
Biopatches Market
Wound Care
South Korea Wound Care Market