
 Hemoglobinopathy Treatment Drug Market | 2026-2036
Hemoglobinopathy Treatment Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Hemoglobinopathy Treatment Drug Market Insights
Specialized gene therapy manufacturing talent is reorganizing competitive dynamics across the hemoglobinopathy landscape. Novartis AG leverages its established cell and gene therapy infrastructure to sustain manufacturing scale for lentiviral vector production. bluebird bio anchors its position through deep specialization in autologous stem cell gene therapy for transfusion-dependent beta-thalassemia. Bristol-Myers Squibb competes via differentiated oncology-to-hematology pipeline extension, applying CAR-T expertise toward sickle cell modalities.
Hemoglobinopathy treatment drugs comprise pharmaceutical and biologic agents designed to modify hemoglobin polymerization, reactivate fetal hemoglobin expression, or correct underlying genetic defects through ex vivo gene editing. These therapies target erythrocyte pathophysiology at molecular level, with CRISPR-based exagamglogene autotemcel representing a functional cure paradigm through BCL11A erythroid enhancer disruption. Pharmacological agents currently dominate commercial volume due to established reimbursement and oral administration convenience, while gene therapy segments command concentrated margin pools despite restricted center availability. Intravenous delivery modes retain infrastructure dependency on infusion center networks, whereas subcutaneous formulations are expanding addressable patient populations through reduced treatment site burden.
FDA, EMA, and WHO prequalification frameworks collectively shape market access through divergent evidentiary standards for gene therapy durability and safety surveillance. FDA's accelerated approval pathway demands confirmatory trials, while EMA's ATMP classification imposes centralized manufacturing inspection requirements that filter market entrants. Stakeholders must monitor evolving long-term follow-up obligations and real-world evidence generation mandates as conditional approvals mature into standard care designations.
Market Dynamics
Gene therapy manufacturing capacity constraints are reshaping competitive positioning across the hemoglobinopathy landscape, as lentiviral vector production bottlenecks limit treatment center expansion and concentrate margin capture among established infrastructure holders.
Growth Catalysts
- Medicaid Reimbursement Reform:United States state-level coverage expansions for curative therapies reduce patient out-of-pocket barriers and accelerate treatment center enrollment for gene-modified interventions.
- EMA Priority Medicines Designation:Accelerated regulatory review timelines compress development-to-commercialization pathways for advanced therapy medicinal products targeting transfusion-dependent beta-thalassemia.
- Specialized Treatment Center Density:Geographic clustering of academic medical centers with apheresis and cryopreservation capabilities creates concentrated uptake corridors for ex vivo gene editing protocols.
Market Restraints
- Plasmid DNA Supply Concentration:Limited qualified suppliers for GMP-grade plasmid vectors create single-source dependencies that amplify production risk and input cost volatility.
- FDA Confirmatory Trial Obligations:Accelerated approval pathways impose post-marketing study requirements that extend regulatory surveillance timelines and compress near-term revenue recognition.
- Allogeneic Stem Cell Transplant Substitution:Established curative protocols for matched sibling donors retain cost advantages in select patient populations, constraining addressable market expansion for novel gene therapies.
Strategic Opportunities
- Brazil ANVISA Pathway Expansion:Emerging market regulatory frameworks for advanced therapies create first-mover positioning for manufacturers establishing local treatment center partnerships.
- Subcutaneous Formulation Development:Route-of-administration innovation expands addressable populations beyond infusion-center-dependent geographies into community hematology practice settings.
- Real-World Evidence Generation Mandates:Conditional approval frameworks in the European Union create competitive differentiation for sponsors with established patient registry infrastructure and long-term follow-up capabilities.
Industry Challenges
- Vector Manufacturing Scale-Up:Lentiviral production requires specialized cleanroom facilities and skilled cell culture technicians that outpace current training pipeline output.
- Cross-Border Cryologistics Coordination:Autologous cell therapy supply chains demand synchronized temperature-controlled transport across multiple jurisdictions with divergent customs protocols.
- Intellectual Property Fragmentation:CRISPR-Cas9 licensing complexity from multiple foundational patent holders creates transaction cost burdens and freedom-to-operate uncertainty for new entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemoglobinopathy Treatment Drug Market |
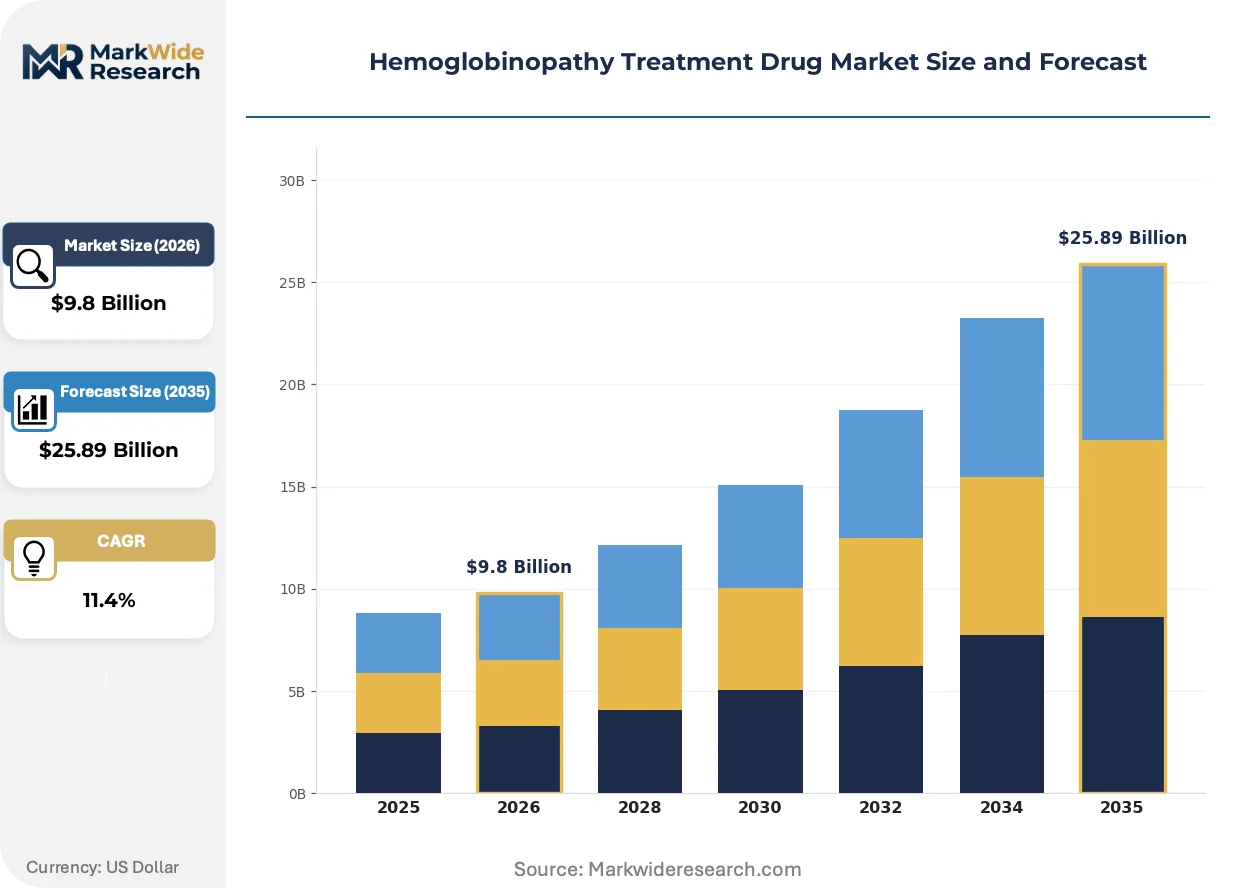
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $25.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gene Therapy, Pharmacological Agents, Hematopoietic Stem Cell Transplant, Supportive Care Delivery Mode: Intravenous, Subcutaneous, Oral, Inhalation Patient Type: Pediatric, Adult, Geriatric, Special Needs Therapeutic Area: Sickle Cell Disease, Thalassemia, Blood Disorders, Rare Diseases |
| Companies Covered | Novartis AG, bluebird bio, Bristol-Myers Squibb, Sanofi, Pfizer, Emmaus Life Sciences, Global Blood Therapeutics, Vertex Pharmaceuticals, Acceleron Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemoglobinopathy Treatment Drug Market Trends and Innovations
Platform convergence between gene editing and cell therapy manufacturing is compressing development timelines and reshaping how hemoglobinopathy interventions reach commercial scale.
CRISPR-based ex vivo gene editing is miniaturizing the treatment footprint required for curative hemoglobinopathy interventions. Academic medical centers in the United States are adopting compact automated cell processing systems that reduce cleanroom square footage requirements by half. This footprint compression is miniaturizing the capital barrier to treatment center establishment, enabling community hospital participation in gene therapy delivery networks.
EMA's Advanced Therapy Medicinal Product classification is imposing centralized manufacturing inspection requirements that filter market entrants based on quality system maturity. European sponsors now face mandatory batch release testing at qualified control laboratories before cross-border distribution. Small and mid-cap developers without established European quality infrastructure are responding through contract manufacturing organization partnerships rather than owned facility investment.
Patient advocacy organizations are consolidating procurement influence through centralized referral networks that direct treatment-seeking populations toward centers with established gene therapy programs. United States-based sickle cell disease foundations now maintain validated center directories that shape physician referral patterns and concentrate volume at high-throughput sites. This behavioral shift is most visible in Medicaid-managed care populations where care coordination requirements amplify foundation guidance effects.
Hemoglobinopathy Treatment Drug Market Segmentation
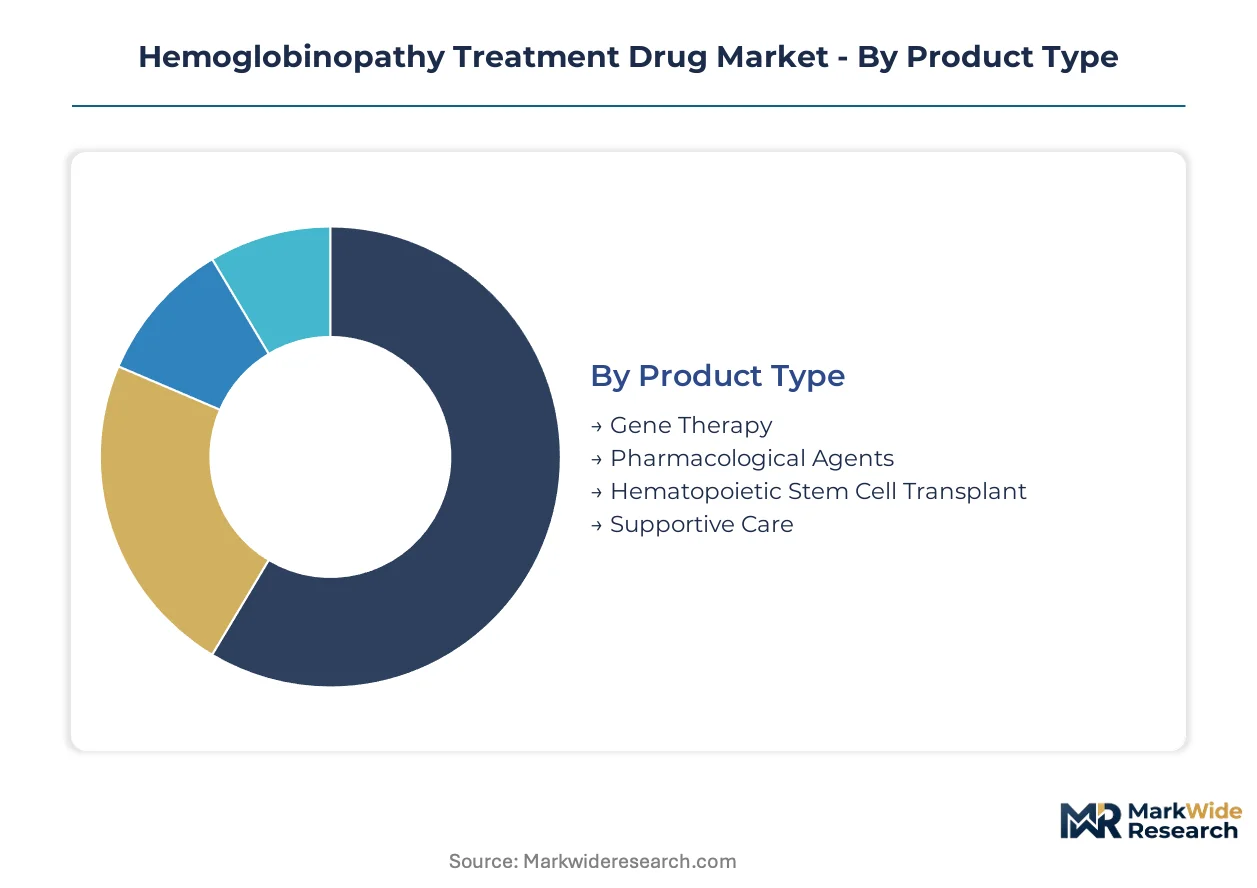
Hemoglobinopathy treatment drugs fragment across curative intent, administration complexity, and patient life-stage requirements. Each segmentation axis reveals distinct reimbursement pathways, manufacturing scale constraints, and center-of-care dependencies that reshape competitive entry strategies.
Product Type:
Gene therapy production concentrates at domestic manufacturing hubs in the United States and Switzerland, while pharmacological agents flow through established export corridors into Brazil and India.
- Gene Therapy:CRISPR-based ex vivo editing and lentiviral vector delivery systems require apheresis collection, cryopreservation, and cleanroom expansion protocols. Demand clusters at academic medical centers in Boston, Basel, and Durham where Medicaid reimbursement reforms and EMA ATMP inspection readiness create concentrated uptake corridors.
- Pharmacological Agents:Oral hydroxyurea, voxelotor, and crizanlizumab modify hemoglobin polymerization or reduce vaso-occlusive crises through established retail pharmacy distribution. Volume concentrates in United States Medicaid-managed care populations and Nigerian national sickle cell programs where oral administration convenience supports community-based delivery.
- Hematopoietic Stem Cell Transplant:Allogeneic transplant from matched sibling donors retains curative positioning for transfusion-dependent beta-thalassemia patients with suitable donors.
- Supportive Care:Transfusion protocols, iron chelation, and pain management regimens sustain patient stability across disease-modifying treatment gaps.
Pharmacological agents command the established base. The steepest expansion runs through gene therapy.
Delivery Mode:
Route selection dictates site-of-care economics, with infusion-dependent modes concentrating margin at specialized centers and self-administered forms expanding into community hematology.
- Intravenous:Gene therapy conditioning regimens and monoclonal antibody infusions require infusion center infrastructure with apheresis capability and cryologistics coordination. United States academic medical centers in Atlanta, Philadelphia, and San Francisco anchor volume through Medicaid-funded treatment center density.
- Subcutaneous:Crizanlizumab and emerging gene therapy conditioning alternatives reduce treatment site burden, enabling expansion into Brazilian and Saudi Arabian community hematology practices where infusion center scarcity constrains intravenous adoption.
- Oral:Hydroxyurea and voxelotor tablets support daily self-administration with established retail pharmacy reimbursement.
- Inhalation:Investigational nitric oxide mimetics target acute vaso-occlusive crisis management through emergency department delivery.
Intravenous delivery retains the revenue concentration. Subcutaneous formulations are climbing the fastest.
Patient Type:
Pediatric programs concentrate at quaternary referral centers with transplant infrastructure, while adult populations distribute across community hematology networks.
- Pediatric:Curative intent dominates treatment design, with gene therapy trials and matched sibling transplant prioritized before end-organ damage accumulates. Enrollment concentrates at Children's Hospital of Philadelphia, Boston Children's Hospital, and Great Ormond Street Hospital where FDA and EMA pediatric investigation plans guide protocol design.
- Adult:Disease-modifying pharmacotherapy and transition-of-care programs from pediatric centers dominate, with hydroxyurea adherence and transition clinic access shaping outcomes. Nigerian and Brazilian national health systems prioritize adult sickle cell survival through hydroxyurea access programs.
- Geriatric:Comorbidity-burdened populations require modified dosing and cardiovascular risk stratification.
- Special Needs:Cognitive impairment and geographic isolation necessitate care coordination adaptations.
Adult populations anchor volume scale. Pediatric segments are expanding most quickly through curative therapy trial enrollment.
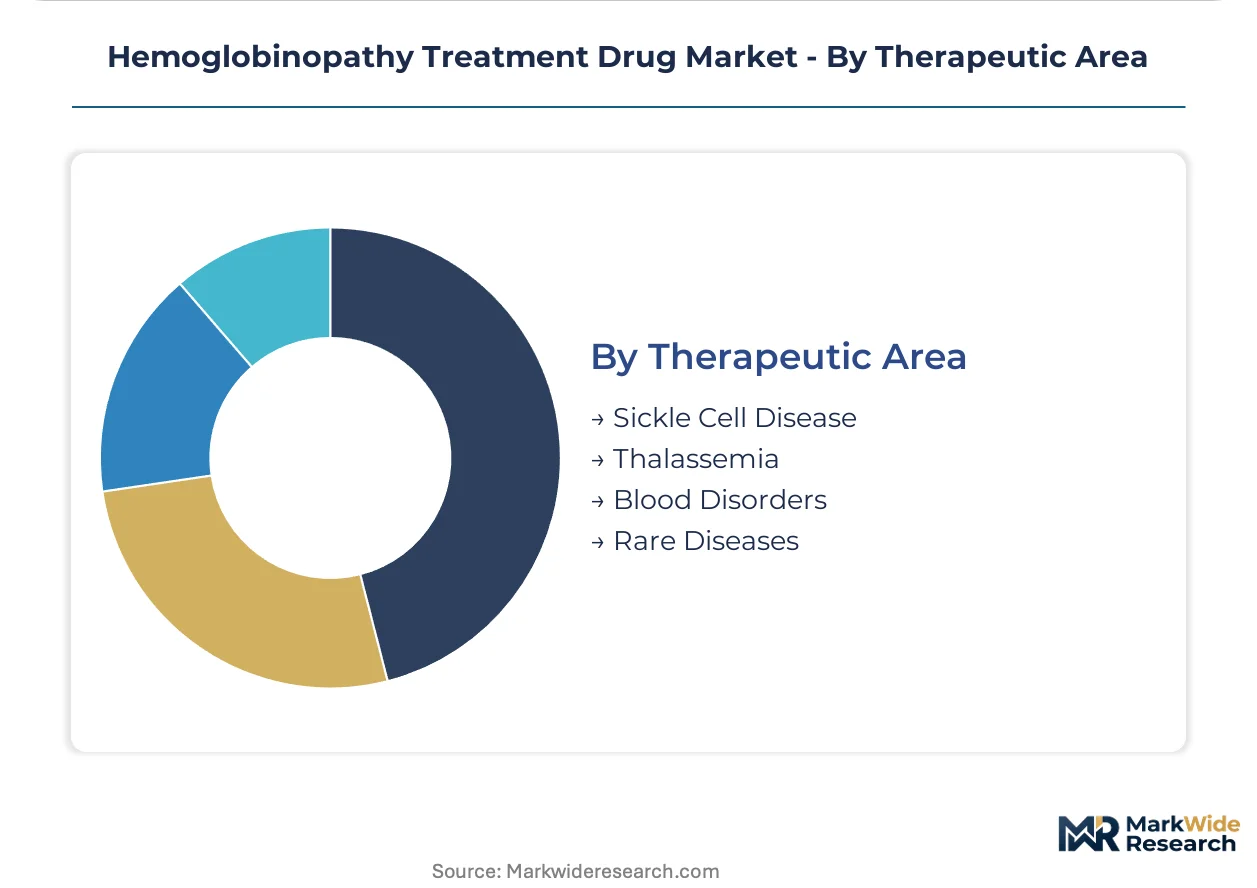
Therapeutic Area:
Sickle cell disease programs concentrate in United States and Nigerian treatment networks, while thalassemia demand clusters in Mediterranean, Middle Eastern, and South Asian geographies.
- Sickle Cell Disease:Vaso-occlusive crisis prevention, stroke risk reduction, and curative gene editing define the therapeutic paradigm. United States Medicaid reimbursement reforms and Nigerian national sickle cell centers drive pharmacological volume; FDA accelerated approval pathways compress gene therapy timelines at Boston and Durham sites.
- Thalassemia:Transfusion dependence and iron overload management dominate, with gene therapy for beta-thalassemia gaining conditional EMA approval. Demand concentrates in Italian, Greek, and Iranian national thalassemia programs where TFR2 and HBB mutation prevalence supports treatment center specialization.
- Blood Disorders:Overlapping hemoglobinopathy phenotypes require diagnostic clarification before therapy selection.
- Rare Diseases:Orphan hemoglobin variants and compound heterozygous states access regulatory incentives and specialized center referral networks.
Sickle cell disease holds the patient volume base. Thalassemia gene therapies are gaining share fastest through EMA ATMP designations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA accelerated approval pathways anchor the United States as the dominant geography, with Medicaid reimbursement reforms and specialized treatment center density creating concentrated uptake corridors for novel hemoglobin-modifying agents.
United States
Medicaid reimbursement reforms and pediatric sickle cell program expansions drive demand concentration. FDA accelerated approval pathways compress development timelines for gene therapy candidates. Academic medical centers in Boston, Philadelphia, and Durham anchor manufacturing scale and patient enrollment for lentiviral vector production.
Switzerland
EMA priority medicines designation and ATMP inspection readiness attract gene therapy investment. Swissmedic centralized manufacturing requirements filter market entrants based on quality system maturity. Basel anchors Novartis AG's cell and gene therapy infrastructure for lentiviral vector sustainment.
United Kingdom
NHS specialized commissioning frameworks and NICE technology appraisals shape reimbursement for curative therapies. MHRA post-Brexit regulatory autonomy enables accelerated access pathways for advanced therapy medicinal products. Great Ormond Street Hospital anchors pediatric gene therapy trial enrollment and transition-of-care protocols.
Brazil
National sickle cell program scale-up and community hematology network expansion drive pharmacological volume. ANVISA emerging regulatory frameworks for advanced therapies create first-mover positioning opportunities. São Paulo and Rio de Janeiro anchor treatment center partnerships for subcutaneous formulation adoption.
Nigeria
National sickle cell center programs and hydroxyurea access initiatives prioritize adult survival outcomes. The country's national pharmaceutical regulator manages import licensing for disease-modifying agents. Lagos and Abuja anchor community-based delivery networks for oral administration convenience.
Hemoglobinopathy Treatment Drug Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with manufacturing infrastructure maturity and vector production scale separating competitive positions. The landscape organizes around three strategic archetypes: established pharmaceutical conglomerates with cell and gene therapy platforms, pure-play gene editing specialists with autologous stem cell expertise, and oncology-to-hematology pipeline extenders applying CAR-T capabilities. Dominant competitive moves include contract manufacturing organization partnerships for European quality infrastructure and subcutaneous formulation development to expand beyond infusion-center geographies.
Among the integrated pharmaceutical tier, Novartis AG and Bristol-Myers Squibb occupy positions leveraging established infrastructure. Novartis AG exemplifies the conglomerate archetype with cell and gene therapy platform breadth. bluebird bio sits within the pure-play specialist tier, representing deep autologous stem cell gene therapy concentration. Bristol-Myers Squibb anchors the oncology-to-hematology extension pattern, applying CAR-T expertise toward sickle cell modalities.
| Leading Market Players |
|---|
| Novartis AG |
| bluebird bio |
| Bristol-Myers Squibb |
| Sanofi |
| Pfizer |
| Emmaus Life Sciences |
| Global Blood Therapeutics |
| Vertex Pharmaceuticals |
| Acceleron Pharma |
| Others |
Pricing and Supply Chain Analysis
Sixty-to-ninety-day vector manufacturing lead times concentrate pricing power among United States and Swiss facilities with EMA ATMP inspection readiness, while Medicaid reimbursement rate compression in American state programs feeds backward into plasmid DNA sourcing decisions and contract manufacturing organization selection criteria.
Pricing Analysis
United States gene therapy pricing runs at substantial premiums to European reference benchmarks due to Medicaid-managed care carve-out structures and center-of-excellence concentration in Boston and Durham. Three-tier pricing structure across premium gene-editing protocols, standard pharmacological maintenance, and economy hydroxyurea access programs reflects FDA accelerated approval tiering and manufacturing scale differentials. Cost compression in the pharmacological tier is intensifying because Nigerian and Brazilian national tender programs prioritize oral generic availability. Medicaid-managed care populations exhibit highest price sensitivity; quaternary academic medical centers with established apheresis infrastructure demonstrate lowest sensitivity due to bundled reimbursement mechanisms.
Supply Chain Analysis
Container availability constraints on trans-Atlantic lanes and cryologistics bottlenecks at Frankfurt and Miami hubs elevate inbound logistics costs for European-sourced lentiviral vectors destined for United States treatment centers. Manufacturing concentrates in the United States, Switzerland, and the United Kingdom, drawing from GMP-grade plasmid DNA suppliers, fetal bovine serum media, and single-use bioreactor consumables. Single-source vulnerability in qualified plasmid vector suppliers amplifies production risk. Distribution runs through temperature-controlled specialty couriers with synchronized batch release testing at qualified control laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where CRISPR editing protocols, lentiviral manufacturing platforms, and patient registry infrastructure are consolidating into interoperable treatment ecosystems rather than standalone product offerings.
For Market Incumbents: Fortify manufacturing scale advantages through captive plasmid DNA production and cryopreservation network density in Medicaid expansion states. Gene therapy manufacturing capacity constraints and emerging allogeneic stem cell transplant substitution threats demand backward integration into vector production. EMA centralized inspection readiness serves as the critical certification lever for European margin defense. For New Entrants and Emerging Players: Differentiate on subcutaneous formulation development and community hematology practice access in Brazilian and Saudi Arabian markets where infusion center scarcity constrains intravenous adoption. White-space concentration sits with ANVISA pathway partnerships and real-world evidence generation infrastructure. A go-to-market angle anchored on reduced treatment site burden unlocks addressable population expansion beyond academic medical center corridors. For Investors and Strategic Acquirers: Long-term, this sits as a manufacturing-infrastructure play because lentiviral vector production bottlenecks and skilled cell culture technician scarcity will outlast individual product approval cycles. Acquisition targets center on contract manufacturing organizations with EMA ATMP inspection history and established European quality infrastructure. The signal to watch is Medicaid reimbursement reform velocity in United States state programs.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | Captive lentiviral vector production reduces plasmid DNA single-source dependency for Novartis AG and bluebird bio. |
| Regulatory Approval Pathway | FDA accelerated approval compresses confirmatory trial timelines for CRISPR-based exagamglogene autotemcel candidates. |
| Strategic Partnership | Contract manufacturing organization alliances enable European quality infrastructure without owned facility investment. |
| Geographic Expansion | ANVISA pathway partnerships in Brazil create first-mover positioning for subcutaneous formulation adoption. |
| Pipeline Diversification | Oncology-to-hematology extension applies Bristol-Myers Squibb CAR-T expertise toward sickle cell modalities. |
Research Methodology
Operator-level perspectives from gene therapy manufacturing executives, Medicaid formulary directors, academic medical center apheresis coordinators, and EMA regulatory affairs leads anchored the qualitative base. Secondary validation drew from FDA accelerated approval filings, EMA ATMP inspection reports, ClinicalTrials.gov pediatric sickle cell program listings, and United States state Medicaid reimbursement bulletins. Bottom-up patient enrollment modeling and top-down pharmaceutical revenue triangulation converged on segment-level estimates.
Sensitivity analysis across vector manufacturing yield assumptions, Medicaid expansion scenarios, and EMA inspection timeline variations shaped the analytical framework. Segmentation dimensions included curative intent, delivery mode complexity, patient life-stage requirements, and regional regulatory cluster. CAGRs were derived from treatment center capacity buildout curves and pharmacological volume trends across the projection horizon. Forecast inputs incorporated pediatric program enrollment trajectories and conditional approval conversion rates.
Material uncertainties — gene therapy durability data maturation, plasmid DNA supplier consolidation, and cross-border cryologistics regulatory harmonization — sit outside the modeled envelope. Forecasts reflect documented assumptions about Medicaid reimbursement reform velocity and EMA inspection capacity expansion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Paroxysmal Nocturnal Hemoglobinuria (PNH) Treatment Market
Hematology
Hemoglobin Analyzer Market
Hematology
Warm Autoimmune Hemolytic Anemia Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Global Bleeding Disorders Market
Hematology
Hemostatic Spray Market
Hematology
Single Blood Drop Analysis Market
Hematology
Graft vs Host Disease Market
Hematology
Hemocytometer Market
Hematology
Blood Screening Market
Hematology
Global Hemoglobin Meter Market
Hematology
Sickle Cell Disease Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Burkitt Lymphoma Treatment Market
Hematology
Hypereosinophilic Syndrome Market