
 Hemostatic Spray Market | 2026-2036
Hemostatic Spray Market Size, Share, and Industry Trends Forecast 2026-2036
Hemostatic Spray Market Insights
A shift from single-source fibrin concentrate supply toward multi-source biopolymer procurement is pivoting how contract manufacturers secure raw materials for sprayable hemostat production. Baxter International leverages captive plasma fractionation capacity to stabilize input costs across its sealant portfolio. Johnson & Johnson sustains brand loyalty in laparoscopic suites through Ethicon's dedicated spray applicator training programs. Medtronic competes by extending its cardiac surgery installed base into adjacent vascular closure applications.
Hemostatic spray comprises a pressurized or mechanically propelled formulation of thrombogenic proteins, oxidized cellulose, or synthetic peptides designed to achieve topical coagulation across non-suturable wound surfaces within 60 to 120 seconds of application. The product category serves primarily to reduce operative blood loss in minimally invasive procedures where conventional electrocautery or ligature placement remains technically constrained. Fibrin sealants command the largest revenue share due to established reimbursement codes and surgeon familiarity, while sprayable adhesives represent the fastest-expanding margin pool as polymer chemistry advances enable synthetic substitutes at lower production cost. Device-based delivery systems increasingly determine purchasing decisions, with hospitals favoring integrated aerosol-spray units that reduce operating room setup time.
The FDA's 510(k) pathway and the EU Medical Device Regulation (MDR) establish divergent clinical evidence requirements that shape market entry sequencing and product labeling claims across jurisdictions. ISO 10993 biocompatibility testing and ASTM F2392 thrombogenicity standards further constrain formulation choices for manufacturers targeting dual-territory registration. Stakeholders must monitor evolving CMS procedural bundling decisions and national health technology assessment outcomes in Germany and France, as these will determine whether premium spray formats achieve sustainable reimbursement parity with conventional hemostatic pads.
Market Dynamics
Hospital procurement departments are consolidating sprayable hemostat purchasing into centralized formulary committees, compressing vendor access and forcing manufacturers to demonstrate total cost-of-ownership superiority over conventional hemostatic pads.
Growth Catalysts
- Trauma Center Modernization:United States military medical programs are funding next-generation battlefield hemorrhage control, expanding addressable demand for portable spray systems.
- EU Medical Device Regulation streamlining:The MDR's updated classification guidance for absorbable hemostats is accelerating CE marking timelines for novel biopolymer formulations.
- Synthetic peptide chemistry:Recombinant thrombin alternatives derived from microbial fermentation are reducing plasma dependency and stabilizing raw material supply.
Market Restraints
- Plasma fractionation concentration:North American and European plasma collection networks dominate fibrinogen supply, exposing manufacturers to donor pool volatility and geopolitical sourcing risk.
- Reimbursement compression:CMS procedural bundling for laparoscopic surgery is narrowing the allowable cost delta between premium spray formats and conventional hemostatic agents.
- Technical limitation in large-volume bleeding:Sprayable hemostats demonstrate reduced efficacy in coagulopathic patients with platelet counts below 50,000/μL, constraining addressable surgical indications.
Strategic Opportunities
- Ambulatory surgery center penetration:United States outpatient procedural volume growth is creating demand for simplified, single-use spray applicators with minimal OR setup requirements.
- Veterinary surgical crossover:Companion animal orthopedic procedures represent an underpenetrated indication where human-grade hemostatic sprays command premium pricing without equivalent regulatory burden.
- Japan's PMDA fast-track pathway:The Sakigake designation for regenerative medicine products is enabling accelerated approval for novel hemostatic biologics with demonstrated superior efficacy endpoints.
Industry Challenges
- Formulation stability engineering:Lyophilized fibrin sealants require cold-chain integrity through final reconstitution, complicating distribution to rural and military forward surgical teams.
- ASTM F2392 thrombogenicity validation:Standardized in vitro testing protocols demand significant capital investment in flow-chamber equipment and specialized hematology personnel.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemostatic Spray Market |
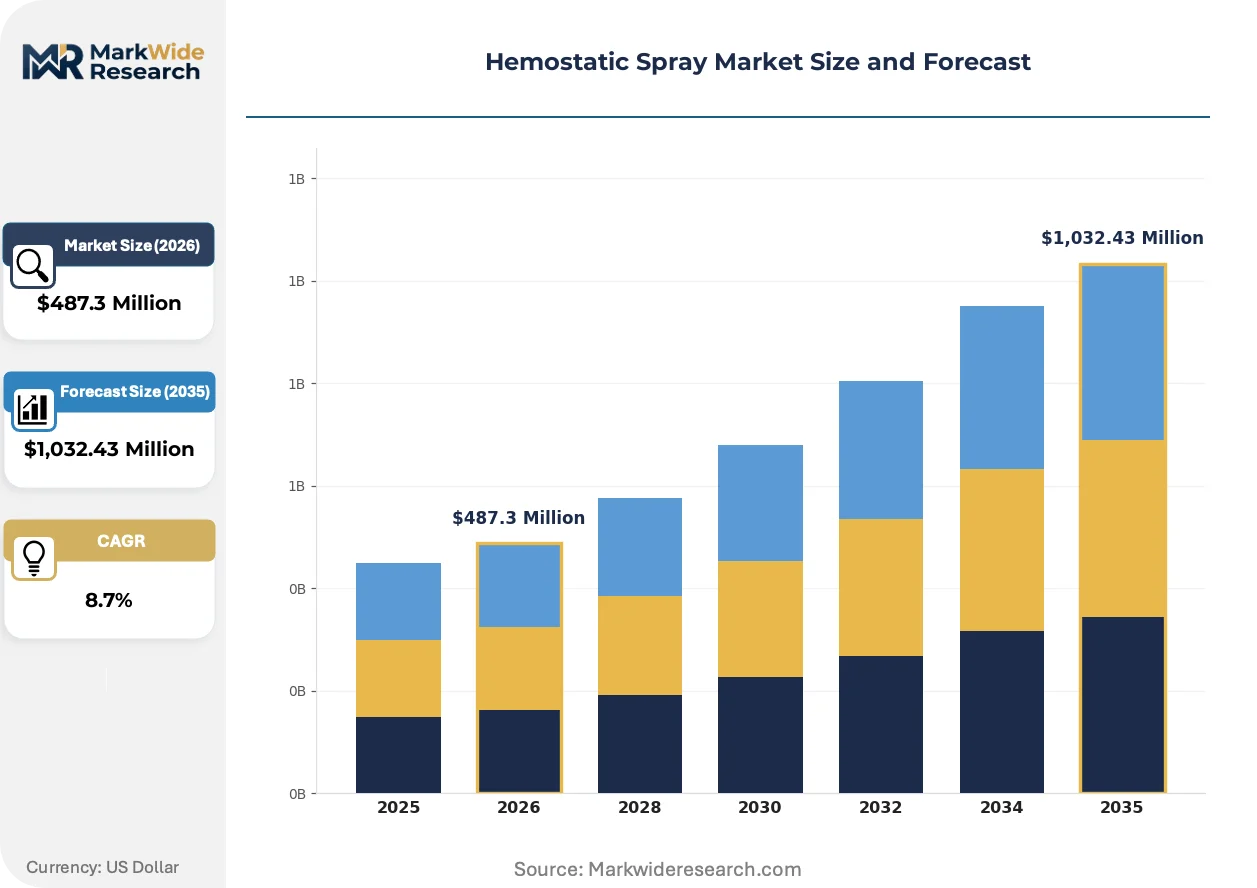
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fibrin Sealants, Collagen-based Agents, Sprayable Adhesives, Clotting Factors Application: Wound Care, Surgical Procedures, Trauma Management, Dental Applications End User: Hospitals, Ambulatory Surgical Centers, Sports Clinics, Military Medical Facilities Delivery Mode: Aerosol, Syringe, Device-based Delivery, Other |
| Companies Covered | Baxter International, Johnson & Johnson, Ethicon, Medtronic, Becton Dickinson, Teleflex, Biom'up, CryoLife, Medcura, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemostatic Spray Market Trends and Innovations
Spray delivery hardware is converging with digital surgical platforms, creating integrated systems where hemostat application parameters feed directly into operative documentation and supply chain analytics.
Dual-chamber mixing systems are modularizing fibrin sealant preparation by separating thrombin and fibrinogen components until point-of-use activation, eliminating pre-mixed product waste and extending shelf stability. Ambulatory surgery centers in the United States are adopting these systems fastest, driven by inventory carrying cost reduction. The technology is modularizing competitive differentiation away from raw biopolymer sourcing toward device engineering and user-interface design.
EU MDR Article 117 requirements for notified body involvement in Class III absorbable device reviews are extending technical documentation timelines for hemostatic spray manufacturers seeking CE marking renewals. The regulation is forcing portfolio prioritization toward highest-margin indications rather than broad surgical claims. German and French health technology assessment bodies are responding with parallel evidence requirements that favor synthetic peptide formulations over plasma-derived alternatives.
Hospital value analysis committees are unbundling hemostat procurement from traditional surgical supply distributors, establishing direct manufacturer contracts with performance guarantees tied to blood transfusion reduction metrics. The shift is compressing distributor margins while rewarding vendors with robust clinical outcome data. Academic medical centers in the United States are piloting these arrangements most aggressively, with tiered pricing tied to annual volume commitments and staff training compliance.
Hemostatic Spray Market Segmentation
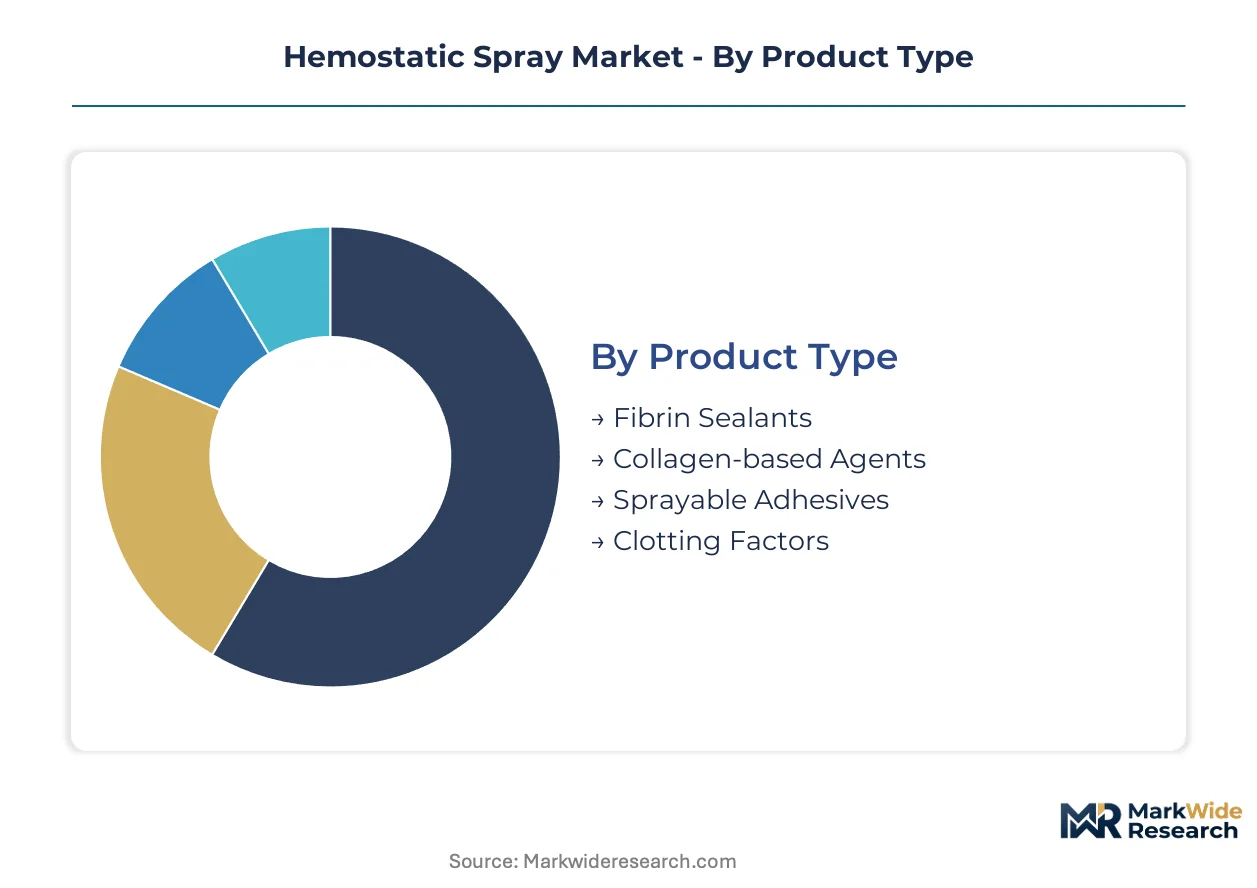
Hemostatic spray manufacturers configure product portfolios around procedural workflow integration rather than raw material chemistry alone. Segment boundaries increasingly blur as dual-chamber delivery systems accommodate multiple active ingredients within single hardware platforms.
Product Type:
Standalone fibrin sealants dominate high-complexity cardiac and thoracic procedures, while embedded polymer systems penetrate cost-sensitive surgical segments through simplified application protocols.
- Fibrin Sealants:These dual-component formulations combine human-derived fibrinogen with thrombin to replicate final coagulation cascade stages. Demand concentrates in United States academic medical centers where CMS reimbursement codes recognize their efficacy in reducing transfusion requirements.
- Collagen-based Agents:Derived from bovine or porcine tissue sources, these agents accelerate platelet aggregation at wound surfaces. German hospital procurement committees favor collagen formulations for their established CE marking history under EU MDR Class III absorbable device pathways.
- Sprayable Adhesives:Synthetic cyanoacrylate and polyethylene glycol formulations offer room-temperature stability without cold-chain dependency.
- Clotting Factors:Recombinant thrombin concentrates and factor VIIa preparations address coagulopathic patient populations.
Volume placements concentrate in fibrin sealants; the faster expansion belongs to sprayable adhesives.
Application:
Cost tier stratification separates premium surgical indications from commoditized wound management, with trauma applications commanding emergency procurement premiums.
- Wound Care:Chronic diabetic foot ulcers and pressure injuries drive outpatient consumption of hemostatic sprays as alternatives to traditional gauze packing. United States Medicare Advantage plans increasingly cover these applications under bundled wound care payments.
- Surgical Procedures:Laparoscopic and robotic-assisted surgeries generate the highest per-procedure consumption rates as surgeons deploy sprays for hemostasis in confined anatomical spaces where suture placement remains technically constrained.
- Trauma Management:Battlefield hemorrhage control and civilian emergency department protocols favor portable, single-use spray systems.
- Dental Applications:Oral surgery suites utilize hemostatic sprays for extraction site management and implant placement procedures.
Revenue margins peak in surgical procedures; trauma management is climbing the fastest as military medical modernization programs expand.
End User:
Customer type determines packaging specifications, with hospital systems demanding bulk institutional formats while ambulatory settings prioritize unit-dose convenience.
- Hospitals:Integrated delivery networks negotiate multi-year supply agreements with performance guarantees tied to blood product utilization reduction. These contracts typically specify dual-chamber mixing systems with standardized applicator interfaces across surgical service lines.
- Ambulatory Surgical Centers:Freestanding outpatient facilities in the United States represent the fastest-expanding installation base for simplified, pre-mixed spray formulations with minimal preparation requirements.
- Sports Clinics:Orthopedic-focused ambulatory settings utilize hemostatic sprays for arthroscopic procedures and soft tissue repair.
- Military Medical Facilities:Forward surgical teams and combat support hospitals prioritize lyophilized, temperature-stable formats.
Procurement volume aggregates in hospitals; ambulatory surgical centers are gaining share fastest as United States outpatient migration accelerates.
Delivery Mode:
Supply concentration among contract manufacturers with specialized aerosol filling capabilities shapes competitive access to pressurized delivery formats.
- Aerosol:Pressurized propellant systems achieve uniform tissue coating across irregular wound geometries. FDA 510(k) clearance pathways for aerosol devices require validated particle size distribution data to demonstrate consistent deposition patterns.
- Syringe:Manual plunger-actuated systems remain prevalent in cost-sensitive markets and veterinary applications where precision volume control outweighs speed of application.
- Device-based Delivery:Integrated electromechanical applicators with pressure sensors and flow meters command premium pricing in robotic surgery environments.
- Other:Emerging formats include brush-applied gels and sponge-impregnated solutions for specialized anatomical indications.
Installed base concentrates in syringe formats; device-based delivery shows the steepest expansion trajectory as digital surgical platform integration advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma fractionation capacity in the United States and Germany anchors raw material supply for sprayable hemostat production. Trauma center modernization programs and military medical procurement drive demand concentration in North American and Western European markets.
United States
Academic medical centers in Boston and Baltimore are piloting value-based procurement contracts tied to blood transfusion reduction metrics. The FDA's 510(k) premarket notification pathway for absorbable hemostatic devices streamlines commercial entry for novel formulations. Military medical modernization programs at Walter Reed National Military Medical Center and Fort Sam Houston are expanding battlefield hemorrhage control protocols.
Germany
Hospital procurement committees in Munich and Berlin favor collagen-based agents with established CE marking history under EU MDR Class III absorbable device pathways. The EU MDR Article 117 requirements for notified body involvement extend technical documentation timelines for manufacturers seeking CE marking renewals. The Tübingen-Stuttgart medical technology cluster hosts specialized contract manufacturers with aerosol filling capabilities for pressurized delivery formats.
Japan
PMDA's Sakigake designation for regenerative medicine products accelerates approval timelines for novel hemostatic biologics with demonstrated superior efficacy endpoints. Tokyo and Osaka academic hospitals drive adoption of device-integrated spray systems in robotic surgery environments. The Kobe biomedical innovation cluster supports translation of synthetic peptide formulations from laboratory to clinical validation.
United Kingdom
NHS England's value analysis committees are unbundling hemostat procurement from traditional surgical supply distributors. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR standards for absorbable hemostatic device classification. London and Cambridge teaching hospitals are piloting direct manufacturer contracts with performance guarantees tied to operative blood loss metrics.
France
ANSM oversight of Class III absorbable medical devices shapes market entry sequencing for sprayable hemostat manufacturers. The Paris-Saclay medical technology cluster concentrates formulation development expertise for lyophilized fibrin sealants. French health technology assessment bodies favor synthetic peptide formulations over plasma-derived alternatives in reimbursement determinations.
Hemostatic Spray Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers secure captive plasma fractionation capabilities to stabilize fibrinogen input costs. The market structure consolidates around diversified medical technology conglomerates with established surgical suite relationships and specialized hemostasis-focused innovators with polymer chemistry expertise. Three archetypes define competitive positioning: integrated plasma processors controlling upstream raw material supply, device-engineering specialists differentiating through delivery system innovation, and synthetic formulation developers reducing plasma dependency. M&A activity and strategic partnerships concentrate among firms seeking dual-chamber mixing technology and point-of-care activation capabilities.
Among diversified medical technology conglomerates, Baxter International and Johnson & Johnson exemplify integrated market presence through captive supply chain control and established surgical training infrastructure. Ethicon occupies a position within the device-differentiation archetype through dedicated spray applicator programs. Medtronic represents the cardiac surgery installed base extension model, leveraging vascular closure expertise into adjacent hemostatic applications. Specialized innovators including Biom'up and CryoLife sit within the biopolymer formulation tier, focusing on synthetic and collagen-based alternatives to plasma-derived products.
| Leading Market Players |
|---|
| Baxter International |
| Johnson & Johnson |
| Ethicon |
| Medtronic |
| Becton Dickinson |
| Teleflex |
| Biom'up |
| CryoLife |
| Medcura |
| Others |
Pricing and Supply Chain Analysis
Dual-chamber mixing technology is displacing pre-mixed fibrin sealant formats across United States hospital systems, simultaneously compressing per-unit manufacturing costs and concentrating procurement leverage among device-engineering specialists with aerosol filling capabilities. This production-method transition feeds directly into pricing power asymmetries between plasma-integrated conglomerates and synthetic peptide developers.
Pricing Analysis
Warranty and training bundling separates premium device-integrated spray systems from unbundled syringe formats sold through distributors. Three-tier pricing structure across premium, standard, and economy levels tracks certification tier and cold-chain requirement intensity. Cost compression in standard fibrin sealants is intensifying because CMS procedural bundling narrows reimbursement deltas against conventional hemostatic pads. Ambulatory surgical centers exhibit highest price sensitivity; academic medical centers with value-based contracts show lowest.
Supply Chain Analysis
Direct-to-hospital contracts handle hyperscale integrated delivery network demand, bypassing traditional surgical supply distributors. Plasma fractionation capacity concentrates in the United States, Germany, and Austria, drawing from human donor pools and bovine collagen harvest networks. Raw material dependencies rest on fibrinogen concentrate, thrombin, and oxidized cellulose. Single-source vulnerability in North American plasma collection exposes manufacturers to donor pool volatility. Distribution runs through specialized medical device distributors with cold-chain logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma fractionation capacity constraints prop pricing power for manufacturers with captive supply, locking synthetic formulation developers into multi-year raw material offtake negotiations.
For Market Incumbents: Acquire captive plasma fractionation assets or dual-chamber mixing technology patents to secure input cost stability against recombinant thrombin substitution threats. Expand aerosol filling capacity in the Tübingen-Stuttgart cluster to serve EU MDR compliance timelines. Deepen hospital system partnerships through blood transfusion reduction performance guarantees. For New Entrants and Emerging Players: Contract manufacturing partnerships with German notified bodies offer fastest CE marking pathways for novel biopolymer formulations. Veterinary surgical applications in companion animal orthopedics present underpenetrated white space with reduced regulatory burden versus human-grade pathways. Target ambulatory surgical center procurement committees with room-temperature stable synthetic peptide formats. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified medical technology conglomerates seeking dual-chamber device capabilities. Long-term viability favors synthetic formulation developers reducing plasma dependency over pure-play fibrin sealant manufacturers. Watch PMDA Sakigake designation approvals as signal for accelerated regulatory pathway viability.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Fractionation Capacity Expansion | Captive supply secures fibrinogen input cost stability against donor pool volatility. |
| Dual-Chamber Mixing Technology Acquisition | Device engineering differentiation shifts procurement decisions away from raw material chemistry. |
| EU MDR Notified Body Partnership | Accelerated CE marking timelines enable earlier market entry for novel biopolymer formulations. |
| Hospital Value-Based Contracting | Performance guarantees tied to transfusion reduction metrics lock in multi-year supply agreements. |
| Synthetic Peptide R&D Investment | Recombinant thrombin alternatives reduce plasma dependency and stabilize raw material supply. |
Research Methodology
Document review covered FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contracts, complemented by interviews with surgeons, hospital purchasing committee members, biomedical engineers, and plasma fractionation executives. Secondary sources included CMS Medicare reimbursement data, ASTM F2392 thrombogenicity standards, and ISO 10993 biocompatibility testing protocols. Bottom-up demand modeling and top-down supply capacity estimates were triangulated to validate market sizing.
Segment-level revenue and volume outputs were generated across product type, application, end user, and delivery mode dimensions over the projection horizon. CAGRs were derived from surgical procedure volume growth trajectories, military medical modernization program budgets, and ambulatory surgery center expansion rates. Plasma fractionation capacity utilization and synthetic peptide fermentation yield improvements served as key forecast inputs.
Several conditions sit outside the modeled scope, including geopolitical disruptions to plasma collection networks, breakthrough synthetic adhesive formulations displacing fibrin sealants, and fundamental CMS reimbursement category restructuring. Forecasts reflect assumptions about EU MDR implementation timelines and PMDA Sakigake pathway throughput. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Single Blood Drop Analysis Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Sickle Cell Disease Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Congenital Amegakaryocytic Thrombocytopenia (CAMT) Market
Hematology
Global Hematology Diagnostics Market
Hematology
Hematopoietic Agents Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Thalassemia Treatment Market
Hematology
Bleeding Disorders Therapeutics Market
Hematology
Allogeneic Stem Cell Therapy Market
Hematology
Hemocytometer Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Pancytopenia Market
Hematology
Marginal Zone Lymphoma Treatment Market
Hematology
Small Lymphocytic Lymphoma Market