
 Thalassemia Treatment Market | 2026-2036
Thalassemia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Thalassemia Treatment Market Outlook
Iron chelation agents are rebalancing toward oral formulations as first-line therapy, reducing hospital dependency and shifting cost structures across the value chain. Novartis AG leverages its transfusion medicine portfolio to sustain leadership in iron overload management. Bristol-Myers Squibb anchors its position through Luspatercept's differentiated mechanism in beta-thalassemia. Bluebird Bio competes on gene therapy manufacturing scale, though reimbursement complexity remains a structural hurdle.
Thalassemia treatment encompasses therapeutic interventions for inherited hemoglobin disorders characterized by defective globin chain synthesis, requiring lifelong management through transfusion support, iron chelation, and curative modalities including allogeneic stem cell transplantation and lentiviral vector-based gene addition therapy. The primary purpose is to correct anemia, prevent iron-mediated organ damage, and ultimately modify disease trajectory toward transfusion independence. Gene therapy represents the fastest-growing product type segment, with margin pools concentrating among vector manufacturers and specialized treatment centers capable of administering conditioning regimens. Blood transfusion remains the volume anchor across all therapy areas, particularly in major and intermedia classifications where transfusion dependence defines clinical management.
FDA accelerated approval and EMA conditional marketing authorization frameworks shape development timelines and commercial access for novel thalassemia therapies, while WHO prequalification standards influence procurement in endemic regions. Reimbursement negotiation complexity across Medicare, national health systems, and private payers directly determines patient access to high-cost curative interventions. Stakeholders must monitor real-world evidence generation requirements and manufacturing capacity constraints as gene therapy transitions from clinical trial to standard-of-care consideration.
Market Dynamics
Gene therapy manufacturing scale-up is compressing clinical-to-commercial timelines for beta-thalassemia treatments, forcing hospital systems to restructure conditioning protocols and payer contracts simultaneously.
Growth Catalysts
- FDA Accelerated Approval:The pathway compresses Phase III-to-launch intervals for gene therapies targeting transfusion-dependent patients, enabling earlier revenue recognition for developers.
- Oral Iron Chelators:Deferasirox and deferiprone formulations reduce infusion center dependency, expanding addressable patient populations in rural and underserved catchment areas.
- Thailand's National Screening Program:Universal newborn hemoglobinopathy testing expands the diagnosed patient pool and creates predictable demand for chronic transfusion services.
Market Restraints
- Vector Manufacturing Bottlenecks:Lentiviral vector production concentrates among three contract manufacturers, creating single-source vulnerability for gene therapy sponsors.
- Allogeneic Transplant Donor Scarcity:HLA-matched unrelated donor availability remains below 25% for patients of Southeast Asian and Mediterranean ancestry, limiting curative access.
- EMA Conditional Marketing Authorization:Post-authorization evidence requirements extend reimbursement uncertainty for gene therapies, delaying hospital formulary adoption.
Strategic Opportunities
- India's PLI Scheme for Biologics:Production-linked incentives for recombinant protein manufacturing attract contract development investment for regional chelator supply.
- Gene Editing Convergence:CRISPR-Cas9 integration with autologous stem cell collection protocols promises conditioning-free curative approaches, reducing treatment center infrastructure requirements.
- Direct-to-Patient Distribution:Specialty pharmacy channels bypass hospital markup layers for oral chelation maintenance, capturing margin from institutional settings.
Industry Challenges
- Apheresis Technician Shortage:Stem cell collection for gene therapy requires certified operators; training pipeline gaps constrain treatment slot expansion.
- GMP Vector Release Timelines:Potency assay variability extends quality control cycles, disrupting patient scheduling and conditioning synchronization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thalassemia Treatment Market |
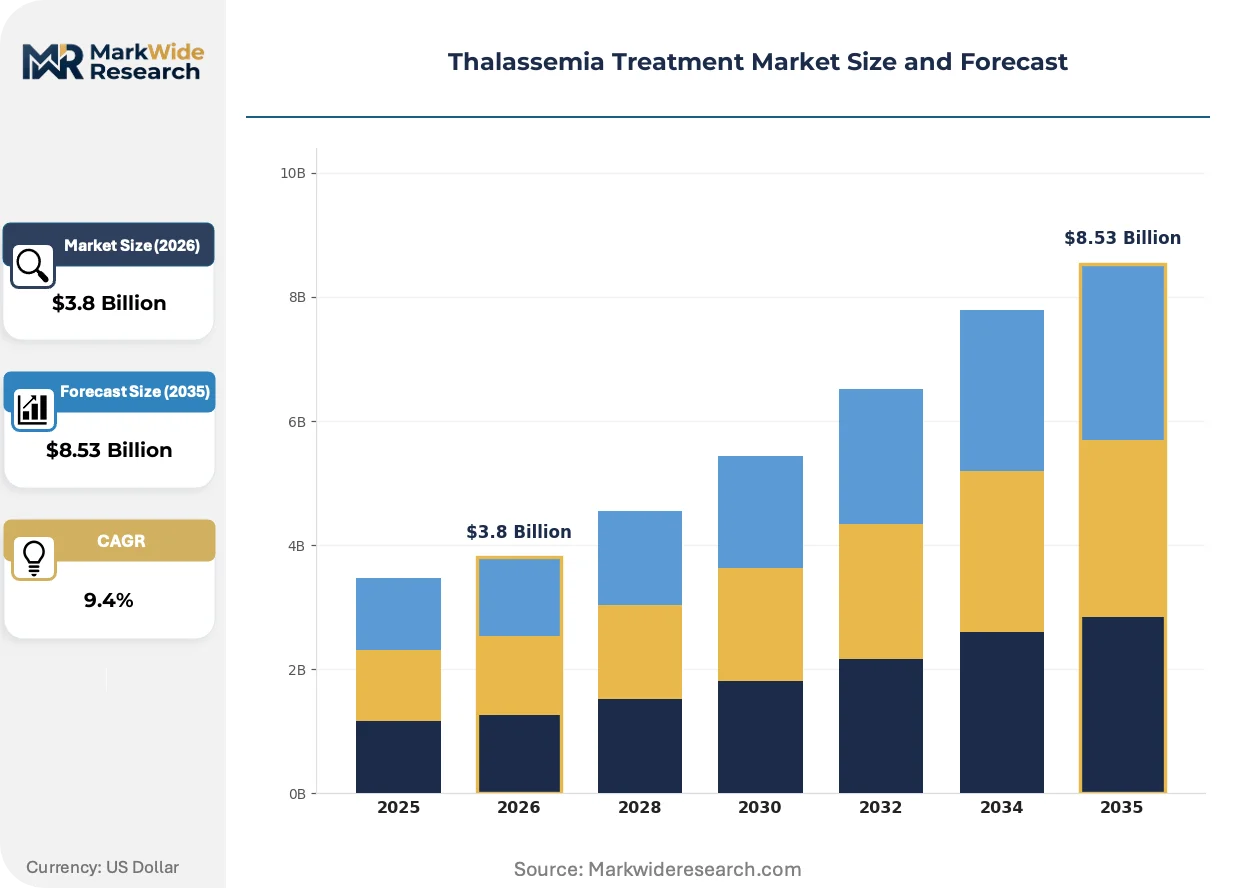
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Transfusion, Iron Chelation Therapy, Stem Cell Transplantation, Gene Therapy Therapy Area: Beta-Thalassemia, Alpha-Thalassemia, Intermedia, Major Delivery Mode: Oral, Intravenous, Subcutaneous, Intraportal End User: Hospitals, Clinics, Home Care, Diagnostic Centers |
| Companies Covered | Agios Pharmaceuticals, Bristol-Myers Squibb, Novartis AG, Ionis Pharmaceuticals, Merck & Co., Bluebird Bio, Vertex Pharmaceuticals, Novo Nordisk, Pfizer Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thalassemia Treatment Market Strategic Shifts
Conditioning regimen minimization is redrawing the boundary between transplant and gene therapy candidates, collapsing historical treatment hierarchies and reallocating specialty pharmacy volumes.
Lentiviral vector manufacturing is decentralizing from centralized bioreactor facilities to distributed, automated closed-system production at academic medical centers. Hospital-based vector suites in Milan, Boston, and Bangkok are adopting scale-out rather than scale-up architectures, reducing cold-chain logistics burdens and enabling just-in-time patient-matched production. This shift is compressing the geographic radius between vector release and patient infusion from transcontinental to intracity.
EMA's ATMP GMP Annex revision tightens environmental monitoring requirements for gene therapy production sites, forcing facility retrofit investments and selective site consolidation. Manufacturers with legacy open-process suites face compliance cliffs, while greenfield entrants capture capacity share through purpose-built containment infrastructure. Italian and German treatment centers are prioritizing sponsors with certified EU manufacturing over US-imported vectors.
Patient advocacy organizations are penetrating traditional prescriber decision-making, shifting treatment selection from hematologist-driven to family-centered evaluation frameworks. Thalassemia International Federation chapters in Cyprus, Lebanon, and the United Arab Emirates are building parallel education infrastructure that bypasses physician gatekeeping, accelerating gene therapy inquiry volumes and compressing conventional transfusion pathway loyalty.
Thalassemia Treatment Market Segmentation
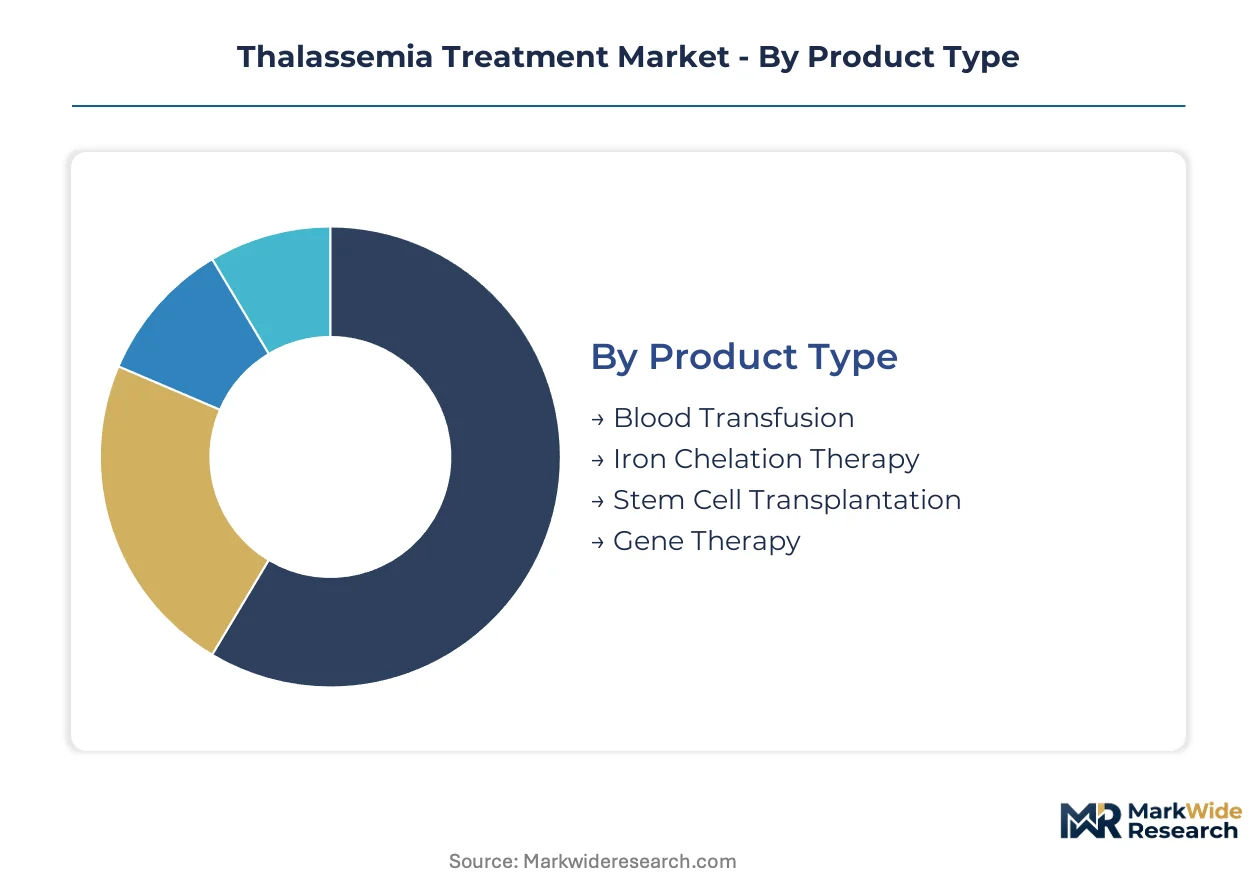
Treatment modality selection in thalassemia care follows disease severity gradients and curative intent. Segmentation reveals how chronic management, disease-modifying therapy, and one-time interventions partition patient flows and reimbursement pools across healthcare systems.
Product Type:
Technology intensity separates volume-driven chronic therapies from high-margin curative platforms.
- Gene Therapy:Lentiviral vector-mediated autologous stem cell transduction delivers functional beta-globin genes. Manufacturing scale constraints limit treatment slots to specialized centers in Milan, Boston, and Bangkok, where conditioning infrastructure and apheresis capacity concentrate.
- Blood Transfusion:Leukocyte-reduced packed red cell units remain the volume foundation for transfusion-dependent patients. Demand concentrates in Thailand's national screening catchments and Mediterranean basin referral networks where thalassemia major prevalence sustains dedicated transfusion services.
- Iron Chelation Therapy:Deferasirox, deferoxamine, and deferiprone formulations manage transfusion-induced iron overload. Oral deferasirox tablets displace infusion-dependent deferoxamine in maintenance settings across Italy and the United States.
- Stem Cell Transplantation:Allogeneic hematopoietic stem cell grafts from HLA-matched siblings offer curative potential. Donor availability constraints restrict access to patients of Northern European ancestry with favorable sibling match rates.
Mature deployment sits with Blood Transfusion. Newer deployment is concentrated in Gene Therapy.
Therapy Area:
Disease classification determines transfusion dependence, iron burden trajectory, and curative candidacy.
- Beta-Thalassemia:Defective beta-globin chain synthesis produces the largest addressable population for gene therapy trials. FDA accelerated approval pathways prioritize transfusion-dependent beta-thalassemia major patients with matched sibling donor absence.
- Major:Complete absence of functional globin chains mandates lifelong transfusion and chelation. Hospital systems in Cyprus, Lebanon, and the United Arab Emirates maintain dedicated thalassemia units serving this severity class.
- Intermedia:Variable transfusion requirements create heterogeneity in iron overload management intensity. Deferasirox prescribing patterns track hemoglobin stability and splenectomy status across Mediterranean treatment centers.
- Alpha-Thalassemia:Reduced alpha-globin output spans silent carrier states to hydrops fetalis. Hemoglobin H disease subtypes in Southeast Asian populations drive intermittent transfusion needs distinct from beta-thalassemia protocols.
Volume concentration rests with Beta-Thalassemia. Steepest expansion trajectory belongs to gene-eligible Major classifications.
Delivery Mode:
Route of administration directly shapes site-of-care economics and patient adherence profiles.
- Oral:Deferasirox dispersible tablets and film-coated formulations enable outpatient iron chelation without infusion center dependency. Home administration expands rural patient access in Thailand's provincial health districts.
- Intravenous:Deferoxamine continuous infusion requires pump-equipped infusion chairs or overnight hospitalization. Deferiprone IV formulations retain niche use in acute iron toxicity settings.
- Subcutaneous:Deferoxamine ambulatory pumps deliver overnight chelation for patients failing oral therapy. Site reaction rates and compliance fatigue limit long-term retention in pediatric populations.
- Intraportal:Hepatic-directed gene therapy vector infusion targets iron-loading organ pathology. Experimental protocols at Italian academic medical centers explore catheter-based portal vein delivery for localized transgene expression.
Patient preference is consolidating around Oral administration for maintenance. Investigational deployment is advancing through Intraportal routes.
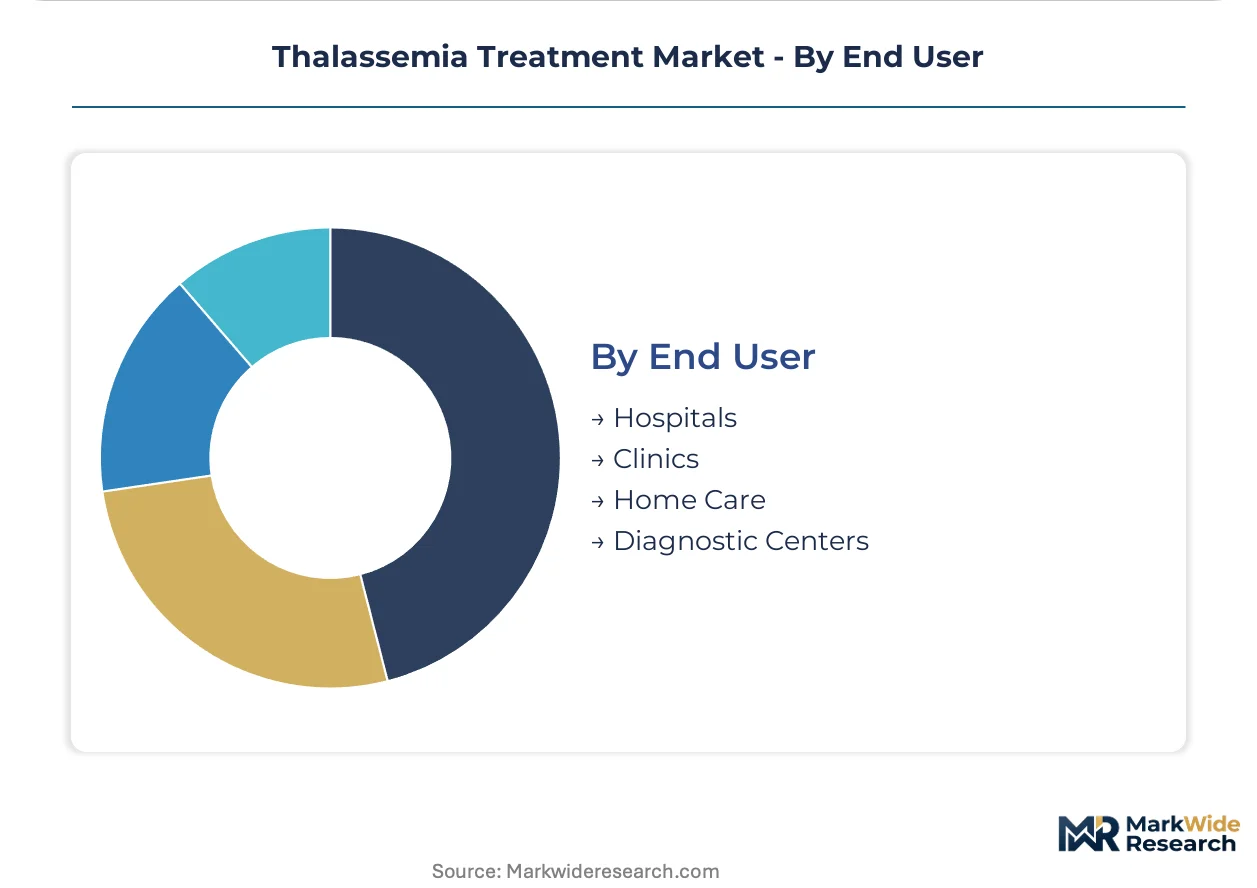
End User:
Care setting fragmentation reflects therapy complexity, reimbursement structure, and acuity requirements.
- Hospitals:Tertiary centers integrate transfusion services, apheresis collection, and conditioning regimens for gene therapy. Academic medical centers in Boston and Milan anchor regional referral networks with vector manufacturing partnerships.
- Home Care:Oral chelator dispensing and transfusion independence monitoring shift low-acuity management from institutional settings. Specialty pharmacy channels in the United States capture margin from hospital-avoidance protocols.
- Clinics:Community hematology practices manage stable transfusion schedules and chelator dose titration. Italian regional health systems deploy hub-and-spoke models linking university hospitals to provincial clinics.
- Diagnostic Centers:Newborn hemoglobinopathy screening and prenatal carrier testing generate patient identification pipelines. Thailand's universal screening program channels confirmed diagnoses into national treatment registries.
High-complexity therapy remains hospital-anchored. Chronic maintenance is decentralizing toward Home Care and Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for thalassemia treatment concentrates where disease prevalence intersects with specialized infrastructure. The United States, Italy, and Thailand anchor patient volumes, while Mediterranean and Southeast Asian clusters sustain chronic transfusion networks.
United States
FDA accelerated approval pathways compress gene therapy commercialization timelines for transfusion-dependent beta-thalassemia patients. Medicare reimbursement negotiations determine access to high-cost curative interventions at academic medical centers. Boston anchors regional referral networks with integrated apheresis collection and vector manufacturing partnerships.
Italy
Universal newborn screening and dedicated thalassemia units in Cyprus-linked populations sustain chronic transfusion demand. EMA conditional marketing authorization frameworks shape hospital formulary adoption of novel therapies. Milan concentrates gene therapy manufacturing scale with hospital-based vector suites adopting distributed production architectures.
Thailand
National hemoglobinopathy screening programs expand diagnosed patient pools and create predictable demand for transfusion services. WHO prequalification standards influence procurement patterns for iron chelation agents in provincial health districts. Bangkok treatment centers integrate conditioning infrastructure with regional referral catchments.
United Arab Emirates
Thalassemia International Federation chapters bypass traditional physician gatekeeping to accelerate gene therapy inquiry volumes. Family-centered evaluation frameworks shift treatment selection authority from hematologists to patient advocates. Dubai and Abu Dhabi medical cities concentrate specialized transfusion services for intermedia and major classifications.
India
Production-linked incentives for recombinant protein manufacturing attract contract development investment for regional chelator supply. CDSCO regulatory pathways shape market entry timelines for oral iron chelator formulations. Maharashtra and Gujarat clusters anchor diagnostic center networks channeling confirmed diagnoses into treatment registries.
Thalassemia Treatment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical incumbents dominating chronic management and biotech developers capturing curative therapy margins. The market structure tiers between volume-driven iron chelation portfolios and high-margin gene therapy platforms. Three archetypes predominate: diversified transfusion medicine incumbents, gene therapy manufacturing specialists, and rare disease-focused biotech developers. Competitive moves concentrate on vector manufacturing partnerships and conditioning protocol standardization.
Within the diversified pharmaceutical tier, Novartis AG and Bristol-Myers Squibb occupy positions anchored by transfusion medicine and erythroid maturation expertise respectively. Bluebird Bio exemplifies the gene therapy manufacturing specialist archetype, with scale constraints defining competitive positioning. Vertex Pharmaceuticals represents the precision medicine developer category, with portfolio expansion into hemoglobinopathies.
| Leading Market Players |
|---|
| Agios Pharmaceuticals |
| Bristol-Myers Squibb |
| Novartis AG |
| Ionis Pharmaceuticals |
| Merck & Co. |
| Bluebird Bio |
| Vertex Pharmaceuticals |
| Novo Nordisk |
| Pfizer Inc. |
| Others |
Value Chain & Pricing Dynamics
Lentiviral vector manufacturing labor costs in Milan, Boston, and Bangkok cascade through three distinct pricing tiers for gene therapy, with apheresis technician wages and GMP facility certification expenses separating premium hospital-based treatment slots from standard regional center access and economy-tier chronic transfusion alternatives.
Pricing Analysis
Volume concentrates in blood transfusion and oral iron chelation, while margins pool in gene therapy slots limited by manufacturing scale. Pricing stratifies across premium, standard, and economy tiers based on conditioning protocol complexity and vector provenance certification. Cost compression in chronic chelation is intensifying as India's PLI scheme expands regional supply. Payers in Thailand's provincial health districts exhibit highest price sensitivity; US academic medical centers demonstrate lowest sensitivity due to Medicare reimbursement floors.
Supply Chain Analysis
Apheresis technician scarcity in Italy, Germany, and the United States constrains stem cell collection capacity for gene therapy candidates. Manufacturing draws from plasmid DNA, cell culture media, and specialized bioreactor components. Single-source vulnerability concentrates among three contract vector manufacturers. Distribution runs through hospital-anchored cold chains for vectors and specialty pharmacy channels for oral chelators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vector manufacturing slot scarcity props pricing power for gene therapy developers, with GMP facility certification backlogs creating a structural capacity bottleneck that sustains premium tier access.
For Market Incumbents: Lock in apheresis collection partnerships at Milan and Bangkok academic medical centers to secure patient flow against emerging CRISPR-Cas9 developers. Deepen backward integration into lentiviral vector production through hospital-based suite investments, reducing reliance on contract manufacturers facing EMA ATMP GMP Annex retrofit cliffs. For New Entrants and Emerging Players: Launch via direct-to-patient specialty pharmacy distribution for oral deferasirox formulations in Thailand's provincial health districts, bypassing hospital markup capture. Target India's Maharashtra and Gujarat diagnostic center networks as the most penetrable geography, leveraging CDSCO regulatory pathways and PLI scheme incentives for regional manufacturing. For Investors and Strategic Acquirers: FDA accelerated approval pathway expansion for transfusion-dependent beta-thalassemia is the leading indicator that gene therapy manufacturing specialists will command sustained premium valuations. Five-to-ten year viability favors precision medicine developers with conditioning-free editing platforms. Watch EMA conditional marketing authorization post-authorization evidence requirements as the signal for reimbursement risk recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | FDA accelerated approval pathway enrollment compresses Phase III-to-launch intervals for gene therapy sponsors. |
| Manufacturing Scale-Up | Hospital-based vector suites in Milan and Bangkok reduce cold-chain logistics burdens through distributed production. |
| Regulatory Approval Pathway | EMA ATMP GMP Annex compliance investments differentiate certified EU manufacturing from US-imported vectors. |
| Reimbursement Strategy | Medicare negotiation frameworks determine patient access to high-cost curative interventions at US academic centers. |
| Strategic Partnership | Thalassemia International Federation chapter alliances accelerate family-centered treatment selection bypassing physician gatekeeping. |
Study Parameters
FDA filings, EMA submissions, and ClinicalTrials.gov formed the secondary backbone, supplemented by formulary database audits and WHO prequalification records. Primary interviews with gene therapy manufacturing executives, hospital apheresis directors, payer access specialists, and thalassemia patient advocacy leads validated quantitative assumptions. Bottom-up patient flow modeling and top-down revenue triangulation anchored segmentation outputs.
Historical trendline analysis across diagnosed patient registries, transfusion service utilization rates, and gene therapy slot deployment informed projection frameworks. Segmentation dimensions spanned treatment modality, disease severity classification, delivery route, and care setting economics. CAGRs derived from vector manufacturing capacity expansion curves and oral chelator prescription volume trajectories. Forecast inputs incorporated conditioning protocol standardization timelines and EMA post-authorization evidence requirement compliance rates.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-Cas9 conditioning-free approaches would alter the outlook. Forecasts reflect assumptions regarding vector release timeline stability and apheresis technician training pipeline recovery. Material deviation in FDA accelerated approval pathway utilization or EMA conditional marketing authorization withdrawal triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Global Non-Hodgkin Lymphoma Therapeutics Market
Hematology
Rare Hematology Market
Hematology
Blood Plasma Market
Hematology
Sickle Cell Treatment Market
Hematology
Malignant Lymphoma Market
Hematology
Langerhans Cell Histiocytosis Management Market
Hematology
Lymphoma Treatment Market
Hematology
Single Blood Drop Analysis Market
Hematology
Peripheral T-Cell Lymphoma Treatment Market
Hematology
Graft vs Host Disease Market
Hematology
Sickle-Cell Anemia Therapeutics Market
Hematology
Mantle Cell Lymphoma Treatment Market
Hematology
Bone Marrow Transplant Market
Hematology
Hypereosinophilic Syndrome Market
Hematology
Polycythemia Vera Treatment Market
Hematology
Aplastic Anemia Treatment Market