
 Tropical Spastic Paraparesis Market | 2026-2036
Tropical Spastic Paraparesis Market Size, Share, and Industry Trends Forecast 2026-2036
Tropical Spastic Paraparesis Market Analytics
Rehabilitation center demand is consolidating as the fastest-rising end-use vertical, reflecting broader shifts toward outpatient chronic neurological care. Pfizer Inc. leverages its antiviral research infrastructure to sustain pipeline visibility in tropical neurology indications. Merck & Co. Inc. anchors its position through long-standing relationships with infectious disease research consortia in endemic zones. Bayer AG competes by extending its neurorehabilitation device portfolio into emerging market access channels.
Tropical spastic paraparesis constitutes a chronic progressive myelopathy caused by human T-lymphotropic virus type 1 (HTLV-1) infection, characterized by spastic weakness of the lower extremities, sensory disturbances, and bladder dysfunction, with diagnosis relying on HTLV-1 serology combined with clinical exclusion of other spinal cord pathologies. Therapeutics command the dominant product type position due to persistent unmet need for disease-modifying agents, while diagnostic kits represent the fastest-expanding segment as PCR-based confirmation protocols displace serological screening in specialized centers. Monitoring tools occupy a narrower but higher-margin niche, serving longitudinal disability tracking in chronic phase management.
The FDA orphan drug program shapes therapeutic development incentives through tax credits and market exclusivity provisions for HTLV-1 targeted interventions. Brazil's ANVISA and national HTLV-1 control program establish the regulatory foundation for endemic-country diagnostic standardization and treatment reimbursement. Stakeholders must weigh geographic prioritization between established endemic markets with infrastructure gaps and non-endemic regions where diagnostic awareness remains nascent.
Market Dynamics
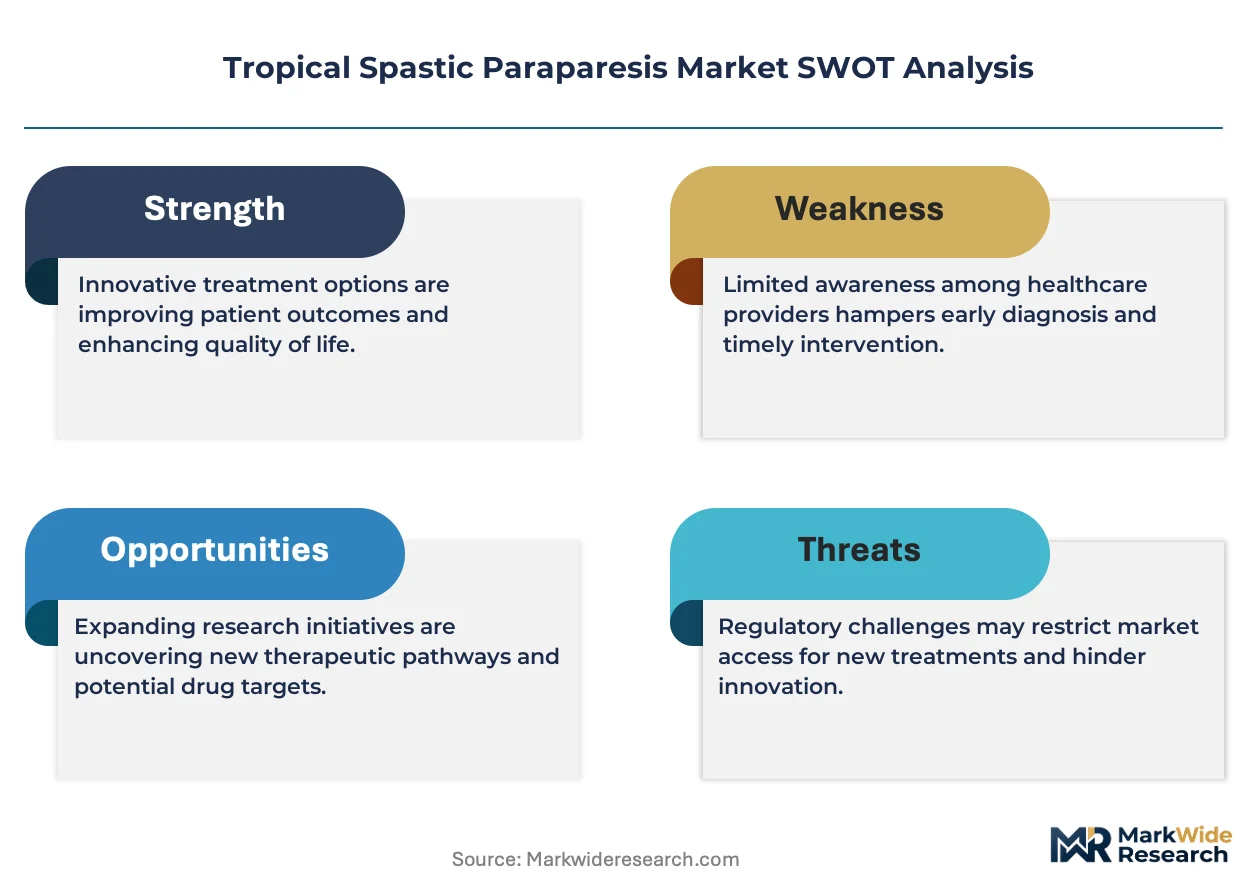
The FDA's orphan drug designation pathway is compressing development timelines for HTLV-1 targeted therapeutics while Brazil's ANVISA standardization mandates reshape diagnostic procurement across endemic zones. Neurology departments in tertiary hospitals are consolidating purchasing power around integrated diagnostic-rehabilitation protocols.
Growth Catalysts
- Orphan drug incentives:The FDA's tax credit and market exclusivity provisions accelerate therapeutic pipelines for HTLV-1 associated myelopathy interventions.
- PCR-based confirmation protocols:Specialized diagnostic centers in Brazil are displacing serological screening with molecular diagnostic standards.
- Rehabilitation service expansion:Outpatient chronic neurological care infrastructure is deepening across Brazil's endemic regions.
Market Restraints
- Diagnostic kit input costs:Reagent supply concentration in specialized PCR manufacturing creates pricing volatility for confirmation protocols.
- Specialist workforce scarcity:Tropical neurology expertise concentrates in São Paulo and Rio de Janeiro academic medical centers.
- Reimbursement fragmentation:Brazil's SUS public health system maintains uneven coverage for disease-modifying agents versus rehabilitation services.
Strategic Opportunities
- Minas Gerais and Bahia penetration:Secondary cities with rising HTLV-1 prevalence lack specialized diagnostic infrastructure.
- Telemedicine integration:Remote spasticity monitoring converges with wearable sensor platforms for longitudinal disability tracking.
- ANVISA fast-track pathways:Expedited review mechanisms for tropical disease diagnostics create regulatory tailwinds for kit manufacturers.
Industry Challenges
- HTLV-1 serology interpretation:Laboratory technicians require specialized training to distinguish true infection from cross-reactivity in low-prevalence settings.
- Rehabilitation device integration:Neurorehabilitation platforms must interface with existing hospital information systems in public sector facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tropical Spastic Paraparesis Market |
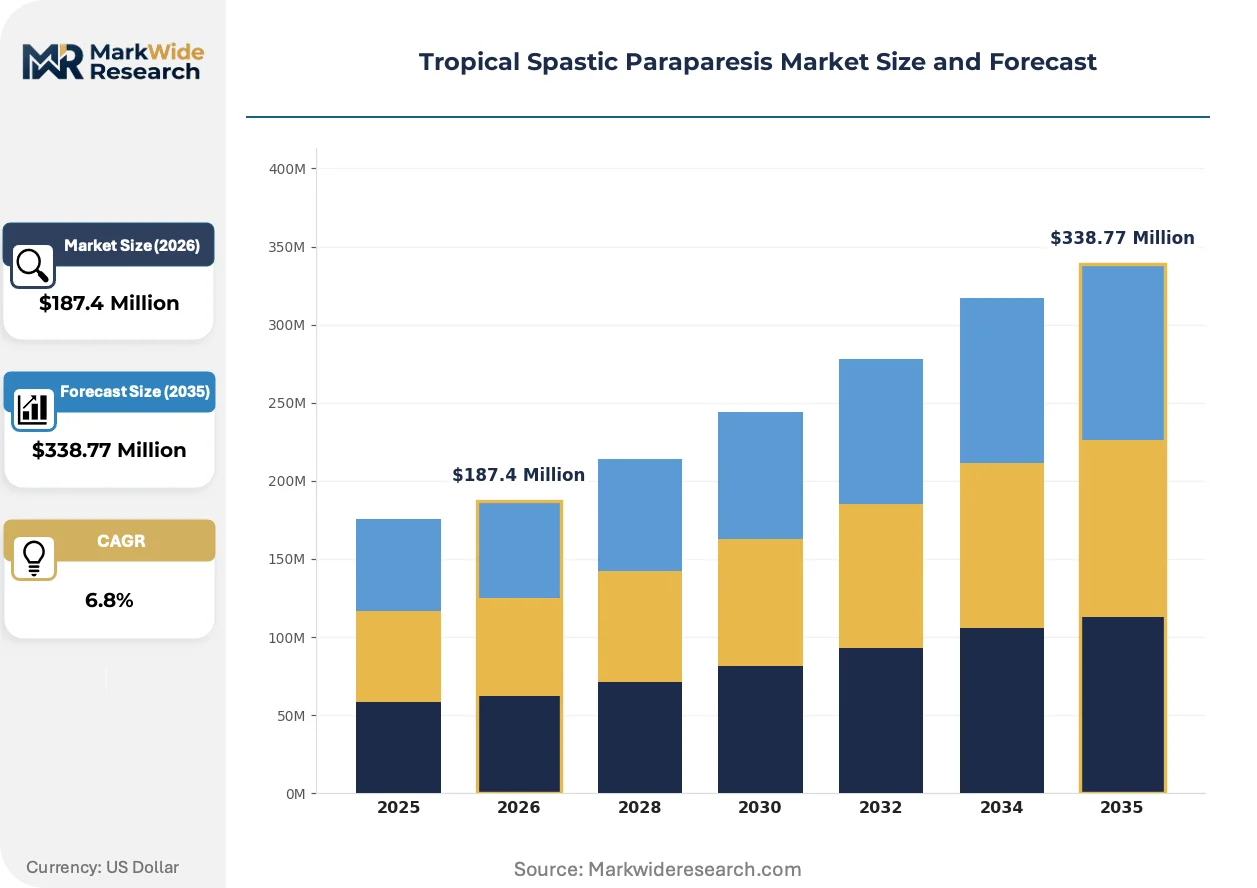
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Therapeutics, Diagnostic Kits, Supportive Devices, Monitoring Tools End User: Hospitals, Clinics, Rehabilitation Centers, Home Care Providers Treatment Stage: Acute Phase, Chronic Phase, Remission Phase, Palliative Care Delivery Mode: Intravenous, Oral, Intramuscular, Subcutaneous |
| Companies Covered | Pfizer Inc., Merck & Co. Inc., Johnson & Johnson Services Inc., Bayer AG, Sanofi SA, Bristol-Myers Squibb Company, AstraZeneca Plc, Novartis AG, Quest Diagnostics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tropical Spastic Paraparesis Market Evolving Landscape
Digital health infrastructure is rewriting how tropical neurology services reach dispersed patient populations. Three convergent developments are compressing diagnostic delays and expanding rehabilitation access beyond metropolitan academic centers.
Quantitative PCR platforms with automated extraction modules are rewriting laboratory workflows for HTLV-1 confirmation. Tertiary hospital neurology departments in Brazil are adopting these systems within twelve-month procurement cycles. The technology is rewriting cost structures by reducing technician hands-on time and enabling same-day result delivery.
ANVISA's updated IVD registration requirements for infectious disease diagnostics are mandating local clinical validation studies for imported kits. Manufacturers must establish Brazilian reference laboratory partnerships to satisfy post-market surveillance obligations. Diagnostic distributors are responding by building captive clinical trial capabilities in São Paulo.
Specialized rehabilitation centers are unbundling inpatient spasticity management into outpatient day-hospital programs. Physical therapy practices in Brazil's Northeast region are displacing hospital-based care with community-based neurorehabilitation networks. This restructuring is most visible in Recife and Salvador, where HTLV-1 patient density supports dedicated clinic economics.
Tropical Spastic Paraparesis Market Segmentation
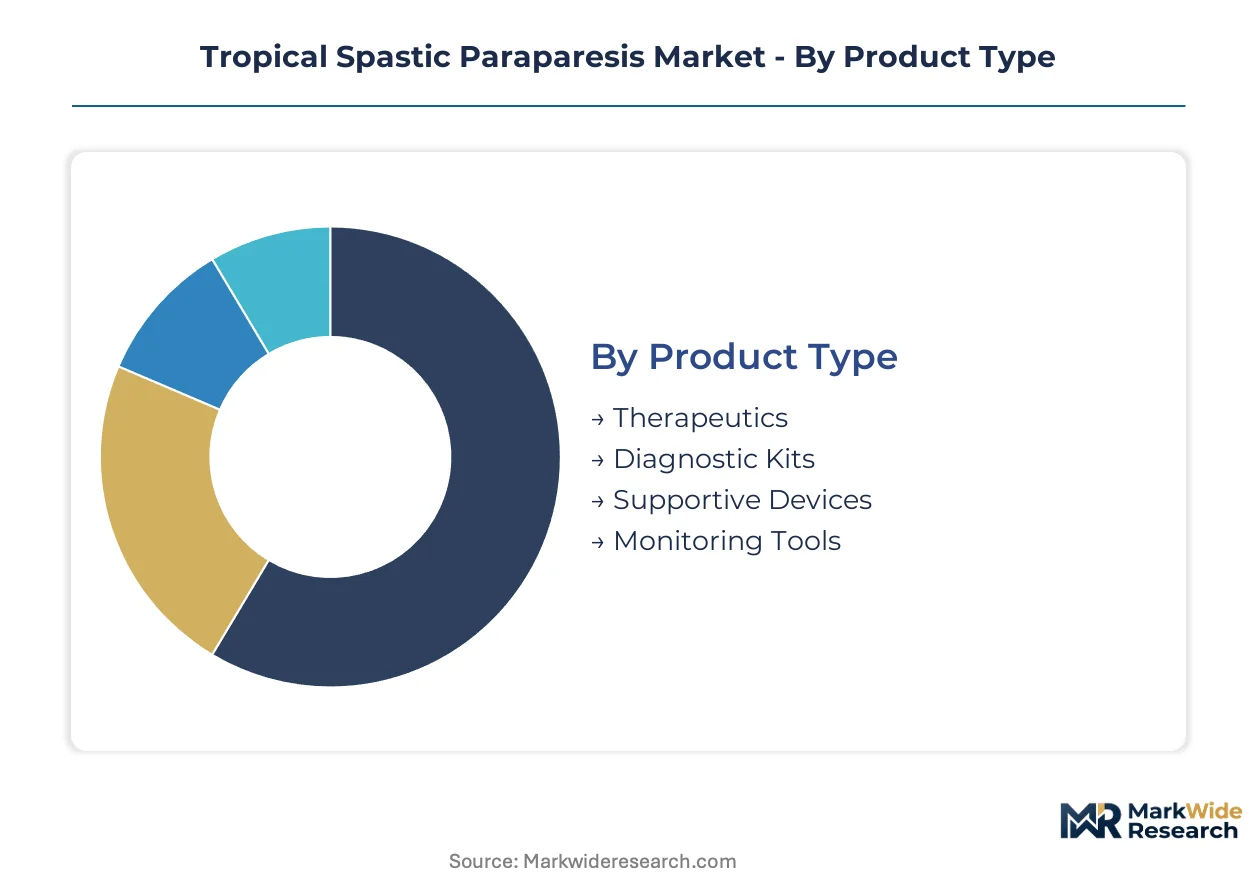
Tropical spastic paraparesis market segmentation reveals distinct procurement patterns across acute intervention versus longitudinal management. Product type stratification shows therapeutics commanding standalone purchasing decisions while diagnostic and monitoring tools embed within integrated care protocols. End-user configuration determines whether solutions deploy in centralized hospital settings or distributed community-based networks.
Product Type:
Integration depth separates standalone pharmaceutical purchasing from embedded diagnostic-rehabilitation systems across neurology departments.
- Therapeutics:Disease-modifying agents and symptomatic treatments including antiviral candidates, corticosteroids, and immunomodulators constitute the revenue core. Hospital pharmacies in São Paulo and Rio de Janeiro academic centers concentrate procurement for intravenous biologics and oral spasticity agents. Unmet need for HTLV-1 targeted mechanisms sustains pipeline investment despite clinical trial complexity.
- Diagnostic Kits:PCR-based confirmation assays and serological screening platforms represent the fastest-expanding segment. Specialized neurology laboratories in Brazil's Northeast region displace legacy serology with automated quantitative systems. ANVISA's updated IVD registration mandates drive local validation partnerships for imported molecular diagnostics.
- Supportive Devices:Orthotic braces, mobility aids, and bladder management systems serve chronic phase disability mitigation. Rehabilitation centers in Recife and Salvador integrate these into outpatient day-hospital programs.
- Monitoring Tools:Wearable spasticity sensors and longitudinal disability tracking platforms occupy a higher-margin niche. Telemedicine providers deploy these for remote patient monitoring beyond metropolitan academic centers.
Therapeutics leads volumes today; diagnostic kits are gaining share fastest.
End User:
Customer type determines reimbursement pathway complexity and procurement decision centralization across Brazil's healthcare system.
- Hospitals:Tertiary academic medical centers in São Paulo, Rio de Janeiro, and Salvador anchor complex diagnostic confirmation and acute intervention capacity. SUS reimbursement fragmentation creates uneven access to disease-modifying agents versus rehabilitation services.
- Clinics:Outpatient neurology practices in Minas Gerais and Bahia secondary cities concentrate stable patient monitoring and oral therapy management. Specialist workforce scarcity outside metropolitan cores limits service expansion.
- Rehabilitation Centers:Physical therapy networks in Brazil's Northeast region unbundle inpatient spasticity care into community-based day programs. HTLV-1 patient density in Recife supports dedicated clinic economics and dedicated neurorehabilitation infrastructure.
- Home Care Providers:Nursing services and domiciliary physical therapy serve advanced disability patients with bladder dysfunction and mobility limitations. Family caregiver training programs extend reach into rural endemic zones lacking specialist access.
Hospitals dominate procurement value; rehabilitation centers show the steepest expansion trajectory.
Treatment Stage:
Clinical phase dictates intervention intensity and product mix across the progressive myelopathy course.
- Acute Phase:Initial diagnostic workup and inflammatory exacerbation management require intensive hospital-based resources. HTLV-1 serology confirmation combined with spinal cord imaging protocols concentrates in tertiary neurology departments.
- Chronic Phase:Long-term spasticity management, bladder dysfunction treatment, and mobility preservation define the dominant patient population. Outpatient rehabilitation protocols and oral medication regimens sustain recurring revenue streams.
- Remission Phase:Disease stability periods emphasize monitoring and early relapse detection. Quantitative disability tracking tools and scheduled serological surveillance maintain patient engagement.
- Palliative Care:Advanced disability management focuses on comfort, pressure sore prevention, and caregiver support. Home-based nursing and hospice services coordinate with hospital specialists.
Chronic phase captures the largest patient volume; acute phase interventions carry the highest per-episode cost.
Delivery Mode:
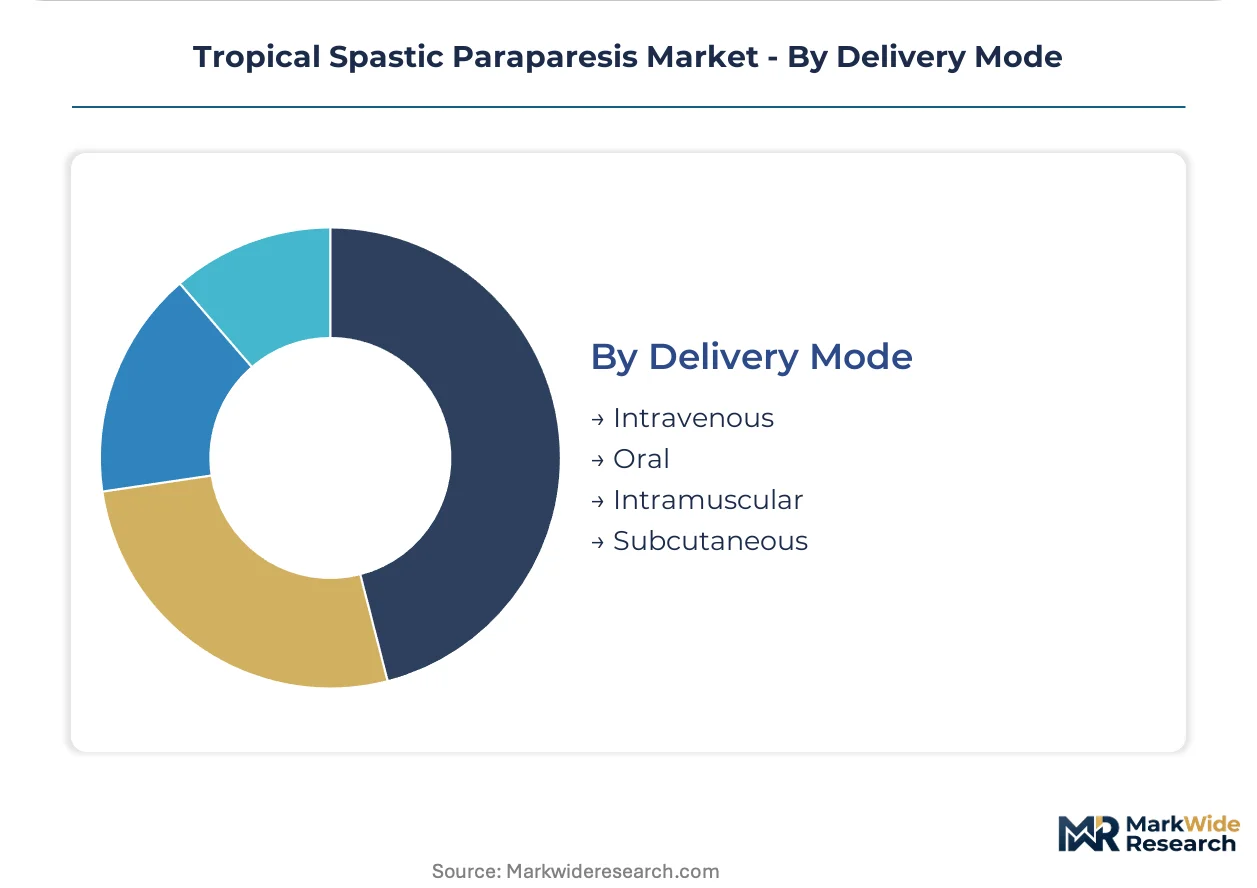
Route of administration shapes manufacturing complexity, cold chain requirements, and patient compliance patterns.
- Intravenous:Hospital-administered biologics and high-dose corticosteroid protocols require infusion center infrastructure. São Paulo academic centers concentrate this capacity for acute exacerbation management.
- Oral:Spasticity agents, pain management, and bladder dysfunction medications enable outpatient chronic phase maintenance. Pharmacy distribution networks reach into secondary cities and rural endemic zones.
- Intramuscular:Depot formulations and botulinum toxin injections for localized spasticity control bridge hospital and clinic settings. Specialist administration requirements limit service points.
- Subcutaneous:Emerging self-administered biologic candidates target patient convenience and healthcare system cost reduction. Clinical validation for HTLV-1 indications remains in development pipelines.
Oral delivery dominates prescription volumes; intravenous commands the highest revenue per patient.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Northeast corridor anchors regional demand concentration for HTLV-1 associated myelopathy services. São Paulo and Rio de Janeiro academic medical centers concentrate specialized diagnostic capacity and rehabilitation infrastructure. Secondary cities in Minas Gerais and Bahia present infrastructure gaps amid rising case detection.
Brazil
ANVISA's national HTLV-1 control program mandates standardized PCR confirmation protocols across public laboratories. The SUS reimbursement system fragments coverage between disease-modifying agents and rehabilitation services. Recife and Salvador rehabilitation centers unbundle inpatient spasticity care into community-based day-hospital programs.
United States
FDA orphan drug designation accelerates therapeutic development timelines through tax credits and market exclusivity provisions. Tertiary hospital neurology departments deepen investment in tropical neurology protocols amid diagnostic awareness campaigns. Miami and Los Angeles academic centers concentrate HTLV-1 expertise within immigrant population corridors.
Japan
PMDA's tropical disease review pathways expedite market authorization for imported diagnostic kits. Nagasaki and Kagoshima prefectures maintain endemic HTLV-1 clusters with specialized screening programs. Regional health bureaus coordinate longitudinal patient tracking through integrated disability registries.
United Kingdom
EMA's orphan medicinal product designation aligns with national reimbursement frameworks for rare neurological conditions. London teaching hospitals concentrate serological confirmation capacity and specialist neurology consultation. Manchester and Birmingham regional centers expand outreach clinics for dispersed patient populations.
France
ANSM's post-market surveillance requirements for IVD devices mandate local clinical validation for molecular diagnostics. Paris academic hospitals anchor national reference laboratory functions for HTLV-1 confirmation. Lyon and Marseille regional centers develop telemedicine protocols for rural patient monitoring.
Tropical Spastic Paraparesis Market Competitive Landscape
Strategic partnerships dominate the current landscape as pharmaceutical and diagnostic players consolidate around integrated care protocols. The vendor base stratifies across multinational research-intensive firms, specialized diagnostic manufacturers, and regional rehabilitation service providers. Three archetypes define competitive positioning: antiviral research specialists, molecular diagnostic developers, and neurorehabilitation platform operators. Portfolio diversification and geographic expansion constitute the dominant competitive moves as participants seek endemic market penetration.
Among research-intensive pharmaceutical developers, Pfizer Inc. and Merck & Co. Inc. occupy positions within the antiviral therapeutic archetype. Bayer AG exemplifies the neurorehabilitation device extension strategy through emerging market access channel development. These three entities represent distinct competitive vectors—therapeutic innovation, diagnostic infrastructure, and rehabilitation platform integration—without implying specific market share or operational scale claims.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co. Inc. |
| Johnson & Johnson Services Inc. |
| Bayer AG |
| Sanofi SA |
| Bristol-Myers Squibb Company |
| AstraZeneca Plc |
| Novartis AG |
| Quest Diagnostics Inc. |
| Others |
Value Network & Pricing Analysis
Specialized PCR reagent spot prices cascade through diagnostic kit manufacturing into tiered hospital procurement contracts across Brazil's endemic zones. Input cost volatility in nucleic acid extraction chemistry compresses margins for molecular diagnostic assemblers while amplifying pricing power for integrated platform suppliers.
Pricing Analysis
Input-cost pass-through from reagent supply concentration governs pricing dynamics for HTLV-1 confirmation assays. Three-tier pricing structure across premium automated platforms, standard benchtop systems, and economy manual kits reflects certification grade differentiation under ANVISA's IVD registration tiers. Cost compression in the economy segment intensifies as public laboratory budgets tighten under SUS reimbursement constraints. Tertiary academic medical centers exhibit lowest price sensitivity due to research funding buffers; municipal public health laboratories face acute budget elasticity.
Supply Chain Analysis
ANVISA's local clinical validation mandates for imported diagnostics are reshaping sourcing toward Brazilian reference laboratory partnerships. Geographic supply concentration centers on the United States for automated extraction modules, Germany for optical detection components, and Japan for polymerase enzyme biochemistry. Raw material dependencies span fluorescent probe chemistries, precision microfluidic cartridges, and thermal cycling hardware. Single-source vulnerability in specialized Taq polymerase manufacturing creates procurement risk during global biologics demand surges. Distribution runs through authorized diagnostic distributors with captive technical service capabilities in São Paulo and Rio de Janeiro.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tropical spastic paraparesis market dynamics form a stable compounder anchored by irreversible HTLV-1 endemicity and chronic disease management requirements. Orphan drug incentives and diagnostic protocol standardization sustain predictable revenue visibility for positioned participants.
For Market Incumbents: Anchor defensive positioning through backward integration into PCR reagent supply and captive clinical trial infrastructure in São Paulo. Consolidate channel control by acquiring specialized distributors with ANVISA regulatory affairs capabilities. Threats from emerging molecular diagnostic entrants with automated platform offerings necessitate rapid certification investment to maintain hospital procurement relationships. For New Entrants and Emerging Players: Launch via telemedicine-integrated remote monitoring platforms targeting Minas Gerais and Bahia secondary cities lacking specialist access. The most penetrable white-space sits in outpatient rehabilitation center networks unbundling inpatient spasticity care. Go-to-market execution should prioritize ANVISA fast-track pathway navigation for tropical disease diagnostic designation. For Investors and Strategic Acquirers: Asymmetric upside sits with neurorehabilitation platform operators combining wearable sensor technology with established physical therapy network relationships. Long-term viability over the extended patient management horizon favors vertically integrated service models spanning diagnosis through chronic care. Monitor HTLV-1 seroprevalence surveillance data releases from Brazil's Ministry of Health as inflection indicators for service demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Fast-Track Pathway Navigation | Expedited IVD registration compresses time-to-revenue for PCR-based confirmation assays in endemic zones. |
| Rehabilitation Center Network Acquisition | Consolidated outpatient physical therapy infrastructure captures recurring chronic phase patient volumes. |
| Telemedicine Platform Integration | Remote spasticity monitoring extends reach beyond São Paulo and Rio de Janeiro specialist concentration. |
| Backward Integration into Reagent Supply | In-house production of nucleic acid chemistry buffers margin pressure from global supply volatility. |
| Orphan Drug Clinical Trial Advancement | FDA tax credit eligibility enhances return profiles for disease-modifying therapeutic candidates. |
Research Methodology
Direct dialogue with neurology department heads, diagnostic laboratory directors, rehabilitation center operators, and ANVISA regulatory consultants grounded the qualitative foundation. Secondary validation drew from FDA orphan drug designation filings, ANVISA IVD registration databases, Brazil Ministry of Health HTLV-1 surveillance reports, and SUS reimbursement schedule documentation. Bottom-up patient population estimates and top-down healthcare expenditure flows underwent iterative reconciliation.
Segment-level projections across therapeutics, diagnostic kits, supportive devices, and monitoring tools were generated through the analysis window. Modeling incorporated treatment stage distribution, delivery mode preference shifts, and end-user procurement centralization patterns. CAGRs were derived from epidemiological prevalence trajectories, protocol adoption curves, and pricing elasticity assumptions specific to tropical neurology indications.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ANVISA regulatory timeline delays or HTLV-1 vaccine breakthrough announcements. Assumptions reflect current reimbursement fragmentation and specialist workforce distribution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Eosinophilia Therapeutics Market
Specialty Medicine
Esophageal Atresia Treatment Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Enzyme Replacement Therapy Market
Specialty Medicine
Autoimmune Hemolytic Anemia Therapeutics Market
Specialty Medicine
APAC Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Bleeding Disorders Treatment Market
Specialty Medicine
Global Pigmentation Disorders Treatment Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Tonsil Cancer Market
Specialty Medicine
Cat Scratch Disease (CSD) Treatment Market
Specialty Medicine
Global Parkinsons Disease Treatment Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
Cervical Cancer Therapeutics Market