
 Global Enema Based Products Market | 2026-2036
Global Enema Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Global Enema Based Products Market Foresight
A shift from hospital-centric procurement to diversified multi-source contracts is restructuring supply dynamics for enema based products. Baxter International Inc leverages its intravenous fluid manufacturing infrastructure to anchor saline enema supply chains, while B Braun Melsungen AG competes through specialized disposable delivery systems. Coloplast Group differentiates by controlling direct-to-patient channels in European home care markets.
Enema based products constitute rectally administered fluid preparations—typically 100-150 mL volumes of saline, mineral oil, or phosphate-buffered solutions—designed to evacuate bowel contents or deliver topical medication. Manufacturers produce these through aseptic filling processes with pH-controlled formulations and tamper-evident polymer packaging to ensure sterility and patient safety. Among product types, saline enema retains the largest volume position due to its electrolyte compatibility and broad clinical acceptance, while phosphate enema faces structural pressure from renal safety warnings that redirect margin pools toward oil-based and medicated alternatives. Home care patients represent the fastest-growing end-user segment as reimbursement shifts favor at-home bowel management protocols over institutional administration.
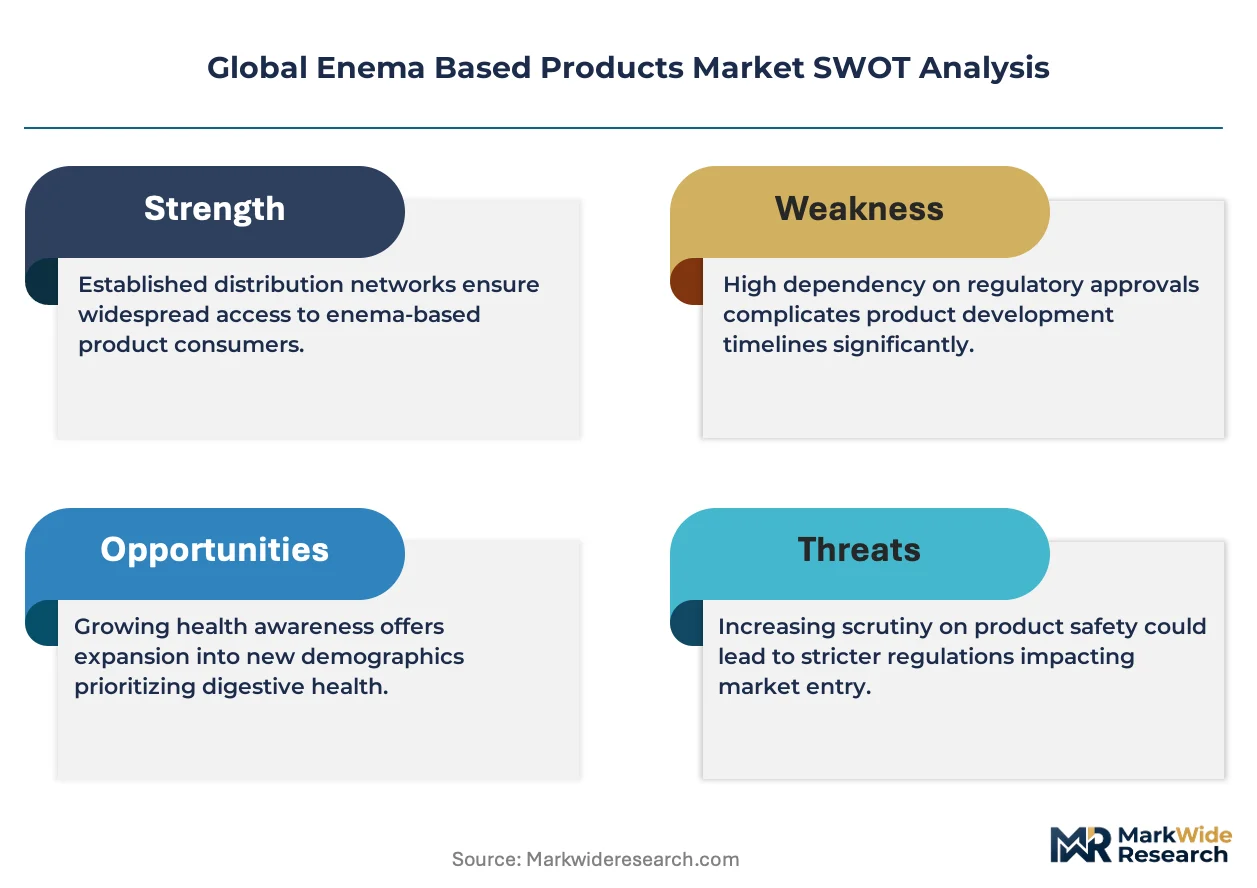
The U.S. FDA mandates boxed warnings on sodium phosphate enemas for renal impairment risk, while the European Medicines Agency monitors osmotic laxative safety through periodic benefit-risk reviews, and ISO 13485 certification governs quality management for device-drug combination enema kits. These regulatory layers elevate compliance costs for new entrants but protect incumbent manufacturers with established pharmacovigilance systems. Stakeholders must monitor evolving renal safety protocols and home care reimbursement codes to align portfolio investments with the shifting boundary between clinical and self-administered bowel care.
Market Dynamics
The FDA's boxed warning mandate on sodium phosphate enemas has triggered a wholesale reformulation race, redirecting R&D investment toward saline and oil-based alternatives while compressing margins for legacy phosphate manufacturers.
Growth Catalysts
- Home care reimbursement expansion:Medicare and European national health funds now cover at-home bowel management protocols, accelerating patient discharge and creating durable demand for self-administered enema kits.
- REACH compliance as quality signal:Manufacturers achieving full EU chemical safety registration command premium shelf placement in German and French pharmacy chains, converting regulatory burden into competitive moat.
- Aging demographics in Japan:METI data shows over-65 households now constitute the fastest-growing consumer segment for ostomy and bowel care accessories, driving volume in Tokyo-Osaka corridor pharmacies.
Market Restraints
- Phosphate raw material volatility:Sodium phosphate supply concentrates among Chinese industrial chemical producers, exposing formulation costs to export quota fluctuations and ocean freight spikes.
- Renal safety litigation exposure:The FDA's 2014 boxed warning created ongoing product liability exposure that elevates insurance premiums and constrains DTC marketing for osmotic laxative variants.
- Suppository substitution:Glycerin and bisacodyl suppositories capture pediatric and travel-use occasions where enema administration proves impractical, capping category expansion in convenience-oriented segments.
Strategic Opportunities
- Brazil's ANVISA pathway simplification:Recent medical device registration streamlining reduces time-to-market for disposable enema kits, opening Latin America's largest healthcare procurement market to first-mover entrants.
- Telehealth-integrated bowel programs:Remote patient monitoring platforms in US accountable care organizations now prescribe enema protocols with automated refill triggers, embedding product into chronic care workflows.
- Bioplastic packaging mandates:France's AGEC law and Italy's plastic tax create first-mover advantage for manufacturers deploying PLA-based enema bottles ahead of 2025 compliance deadlines.
Industry Challenges
- Aseptic filling technician scarcity:parenteral-grade manufacturing expertise concentrates among legacy intravenous fluid producers, constraining capacity expansion for new enema market entrants.
- ISO 13485 audit backlog:Notified body congestion extends device-drug combination kit certification timelines to 14-18 months, delaying product launches and freezing R&D amortization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Enema Based Products Market |
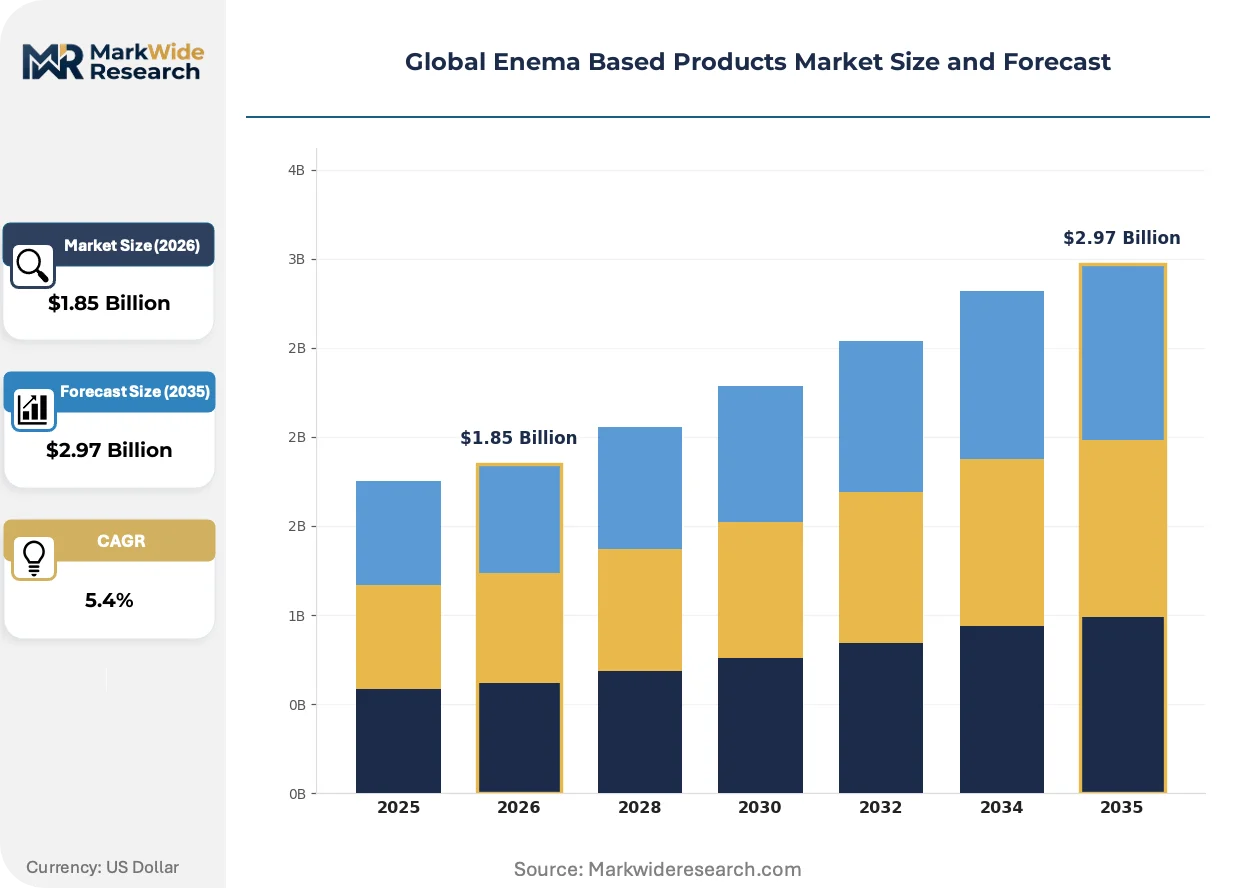
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Saline Enema, Oil-Based Enema, Medicated Enema, Retention Enema, Phosphate Enema Application: Constipation Relief, Bowel Cleansing, Diagnostic Preparation, Therapeutic Administration, Detoxification End User: Hospitals, Ambulatory Surgical Centers, Home Care Patients, Nursing Facilities, Gastroenterology Clinics Packaging Type: Single-Use Bottles, Multi-Use Containers, Pre-Filled Syringes, Disposable Bags, Reusable Kits |
| Companies Covered | Baxter International Inc, Hollister Incorporated, B Braun Melsungen AG, Coloplast Group, Medline Industries Inc, Fresenius Kabi AG, Medtronic plc, ConvaTec Group PLC, Fleet Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Enema Based Products Market Shifts & Advancements
Formulation chemistry, regulatory safety architecture, and patient administration settings are converging to reshape competitive advantage in bowel care, with automation and channel integration now determining margin capture.
Pre-filled saline enema systems with integrated temperature sensors are automating compliance documentation for home care nurses and family caregivers, reducing documentation burden by embedding dose verification directly into delivery hardware. Home health agencies in Florida and Texas are piloting these connected devices, compressing the boundary between clinical supervision and independent patient administration.
The European Medicines Agency's periodic benefit-risk review framework for osmotic laxatives is forcing manufacturers to maintain active pharmacovigilance databases that track real-world renal function outcomes. This regulatory architecture most heavily impacts phosphate enema portfolios, with German and UK manufacturers accelerating saline diversification to preempt safety-driven formulary exclusion.
Direct-to-patient subscription models are displacing traditional pharmacy wholesale channels for chronic constipation management, with automated 90-day refill cycles locking in patient adherence and reducing acute episode escalation. This channel shift concentrates most visibly in US Medicare Advantage plans, where bowel management quality metrics now influence star ratings and reimbursement tiers.
Global Enema Based Products Market Segmentation
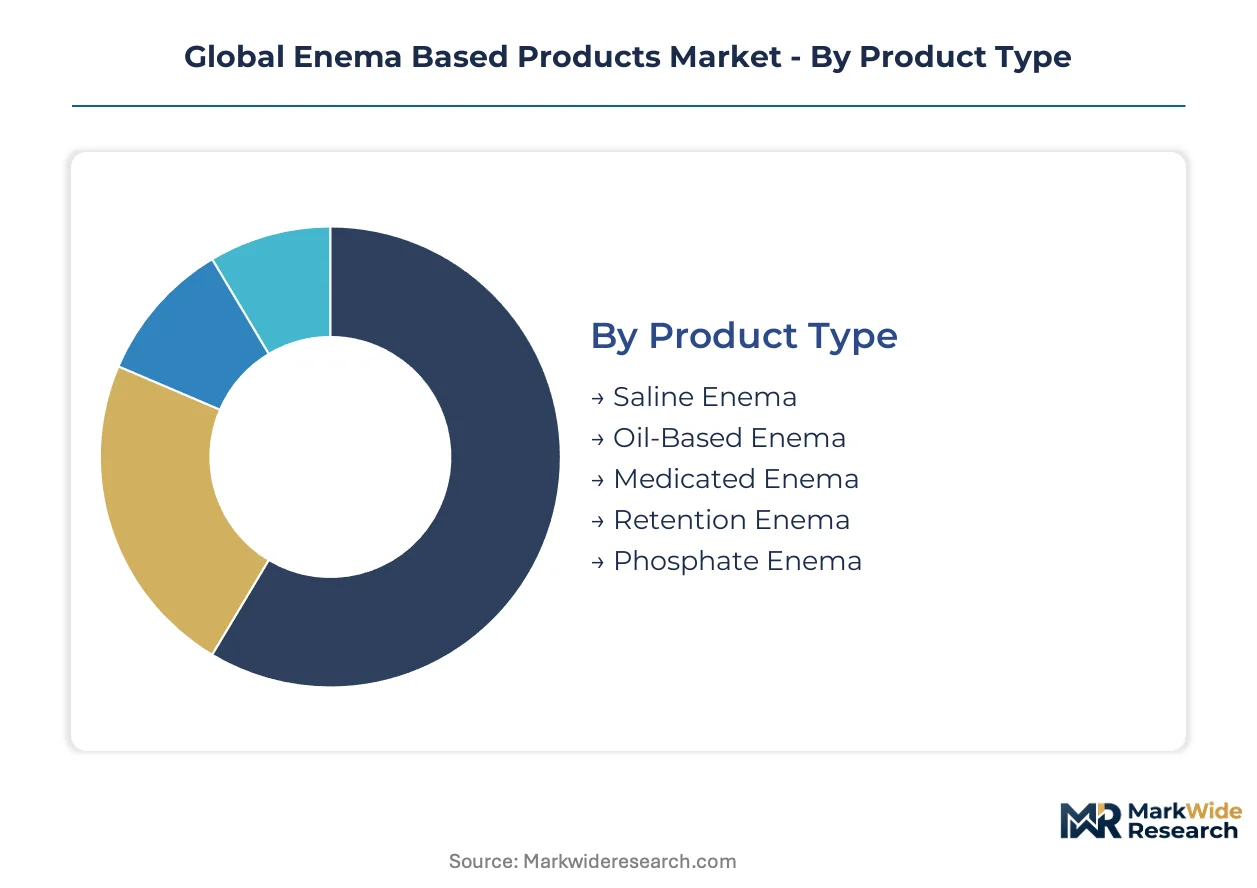
Enema product portfolios fragment across formulation chemistry, clinical setting, and administration mode, with each dimension imposing distinct manufacturing constraints and margin structures. Capital allocation decisions hinge on matching production capabilities to the reimbursement and regulatory profiles of specific segments.
Product Type:
Saline and phosphate formulations demand the heaviest upfront investment in parenteral-grade aseptic filling lines and pH-controlled buffer systems.
- Saline Enema:Electrolyte-balanced sodium chloride solutions at 0.9% concentration dominate hospital formularies due to renal safety profiles. Baxter International and B Braun Melsungen anchor supply through intravenous fluid manufacturing infrastructure, with US hospital procurement concentrating volume in 100 mL and 150 mL single-use presentations.
- Oil-Based Enema:Mineral oil and glycerin formulations lubricate stool passage without osmotic water shift, capturing pediatric and elderly populations with electrolyte sensitivity. German pharmacy chains favor these for home care discharge protocols, while Japanese METI procurement guidelines emphasize oil-based options for long-term bowel management.
- Medicated Enema:Corticosteroid and mesalamine suspensions deliver topical therapy for inflammatory bowel conditions, requiring validated stability testing and cold-chain distribution in some formulations.
- Retention Enema:Low-volume, high-viscosity preparations designed for extended mucosal contact in ulcerative colitis management, with specialized compounding pharmacy production.
- Phosphate Enema:Sodium phosphate buffered solutions face structural contraction following FDA boxed warnings on acute phosphate nephropathy; manufacturers redirect capacity toward saline alternatives while maintaining phosphate lines for emergency department protocols.
Saline enema absorbs the bulk of installed capacity; oil-based enema is expanding most quickly.
Application:
Diagnostic preparation commands premium pricing through bundled colonoscopy protocols, while chronic constipation management drives recurring volume.
- Constipation Relief:The foundational use case spans acute episodic treatment and chronic idiopathic constipation maintenance, with US Medicare Advantage plans now covering 90-day home supply cycles that embed products into value-based care workflows.
- Bowel Cleansing:Pre-operative and pre-procedural evacuation protocols require high-volume, rapid-action formulations; hospitals in the Tokyo-Osaka corridor specify phosphate or saline enemas as adjuncts to oral polyethylene glycol regimens.
- Diagnostic Preparation:Colonoscopy and sigmoidoscopy readiness demands precise evacuation completeness; US ambulatory surgery centers bundle enema kits with procedure scheduling to reduce same-day cancellations.
- Therapeutic Administration:Direct rectal delivery of anti-inflammatory or anti-infective agents bypasses hepatic first-pass metabolism, with gastroenterology clinics in France and Germany specializing in compounding medicated retention enemas.
- Detoxification:Alternative medicine applications claim systemic toxin removal through coffee or herbal enemas, operating largely outside reimbursed healthcare channels with minimal regulatory oversight.
Bowel cleansing generates the highest per-unit revenue; constipation relief produces the steepest volume trajectory.
End User:
Hospital procurement leverages centralized purchasing power, while home care channels reward direct-to-patient logistics capabilities.
- Home Care Patients:Aging populations and discharge acceleration shift administration from institutions to residential settings, with US home health agencies piloting temperature-sensor equipped enema systems for remote compliance documentation.
- Hospitals:Emergency departments and surgical units maintain phosphate and saline stocks for rapid bowel evacuation, with formulary decisions driven by pharmacy and therapeutics committees focused on renal safety protocols.
- Ambulatory Surgical Centers:Same-day procedure volume concentrates demand for pre-packaged cleansing kits that reduce nursing preparation time.
- Nursing Facilities:Long-term care settings balance staff administration efficiency against resident dignity preferences, favoring discreet single-use packaging.
- Gastroenterology Clinics:Specialty practices integrate enema protocols into inflammatory bowel disease management, with German clinics maintaining in-house compounding for customized medicated formulations.
Hospitals retain the largest absolute volume; home care patients are climbing the fastest.
Packaging Type:
Pre-filled syringes and single-use bottles require the most sophisticated blow-fill-seal automation, while multi-use containers demand sterilization validation investments.
- Single-Use Bottles:Polyethylene or polypropylene containers with pre-lubricated tips dominate retail pharmacy and hospital supply, with French AGEC law bioplastic mandates driving PLA-based bottle development ahead of 2025 deadlines.
- Pre-Filled Syringes:Integrated plunger-and-barrel systems enable precise volume control for medicated enemas, with Coloplast Group and specialized device manufacturers competing on tip ergonomics and seal integrity.
- Multi-Use Containers:Rubber bulb or pump systems with replaceable tips serve cost-conscious institutional buyers and travel-use occasions.
- Disposable Bags:Gravity-fed flexible reservoirs with flow-control clamps accommodate high-volume cleansing protocols in home and clinical settings.
- Reusable Kits:Silicone or stainless steel components appeal to environmental sustainability segments and chronic users, though regulatory classification varies across jurisdictions.
Single-use bottles command the greatest production throughput; pre-filled syringes are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sodium phosphate feedstock concentration in Chinese industrial chemical zones shapes cost structures for formulation-dependent manufacturers worldwide. Regulatory divergence between the FDA and EMA safety frameworks fragments compliance requirements across major demand centers. Brazil's ANVISA pathway simplification accelerates Latin American market entry timelines for disposable kit producers.
United States
Medicare Advantage bowel management quality metrics and direct-to-consumer pharmacy channels sustain category volume. The FDA's boxed warning mandate on sodium phosphate enemas redirects manufacturer portfolios toward saline alternatives. Florida and Texas home health agencies pilot temperature-sensor equipped enema systems for remote compliance documentation.
Germany
REACH compliance serves as a quality signal commanding premium shelf placement in pharmacy chains. The EMA's periodic benefit-risk review framework for osmotic laxatives forces active pharmacovigilance database maintenance. German manufacturers accelerate saline diversification to preempt safety-driven formulary exclusion.
Japan
METI data identifies over-65 households as the fastest-growing consumer segment for ostomy and bowel care accessories. The PMDA maintains stringent device-drug combination kit standards under MDR-aligned reforms. Tokyo-Osaka corridor pharmacies concentrate demand for long-term bowel management protocols.
Brazil
ANVISA's recent medical device registration streamlining reduces time-to-market for disposable enema kits. The national health fund's expanding home care reimbursement creates procurement opportunities for first-mover entrants. São Paulo's hospital procurement networks anchor Latin America's largest healthcare market.
France
The AGEC law's bioplastic packaging mandates drive PLA-based enema bottle development ahead of compliance deadlines. ANSM monitors osmotic laxative safety through post-market surveillance programs. Paris-based pharmacy chains favor oil-based formulations for home care discharge protocols.
Global Enema Based Products Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and distribution channel control. The market structure consolidates around intravenous fluid manufacturers repurposing aseptic filling infrastructure, specialized disposable device producers, and direct-to-patient channel operators. Three archetypes dominate: parenteral-grade manufacturers leveraging existing sterile production lines, device specialists optimizing tip ergonomics and seal integrity, and logistics-integrated players controlling home care fulfillment networks. Competitive moves concentrate on portfolio diversification away from phosphate formulations and geographic expansion through regulatory pathway optimization.
Among diversified healthcare conglomerates, Baxter International Inc and B Braun Melsungen AG occupy positions anchored by intravenous fluid manufacturing infrastructure. Coloplast Group exemplifies the direct-to-patient channel archetype with European home care market penetration. These three represent distinct strategic vectors: sterile production scale, disposable delivery system specialization, and patient-centric logistics integration.
| Leading Market Players |
|---|
| Baxter International Inc |
| Hollister Incorporated |
| B Braun Melsungen AG |
| Coloplast Group |
| Medline Industries Inc |
| Fresenius Kabi AG |
| Medtronic plc |
| ConvaTec Group PLC |
| Fleet Laboratories |
| Others |
Supply & Pricing Matrix
Medicare Advantage bowel management quality metrics in the United States are compressing procurement timelines and forcing manufacturers to absorb documentation technology costs into kit pricing. This demand-side pressure redirects margin pools toward suppliers with captive aseptic filling capacity and away from contract-dependent formulators.
Pricing Analysis
Service bundling separates enema kit suppliers into two camps: those including remote compliance documentation and automated refill management versus unbundled transactional sellers. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 certification status and integration with telehealth platforms. Pricing pressure stems from phosphate formulation liability exposure and the resulting portfolio restructuring costs. Hospital procurement committees exhibit lowest price sensitivity due to bundled colonoscopy protocol budgets, while retail pharmacy channels face acute margin compression from direct-to-patient subscription displacement.
Supply Chain Analysis
Single-source vulnerability sits with Chinese industrial chemical producers controlling sodium phosphate feedstock and German blow-fill-seal equipment manufacturers. Aseptic filling infrastructure draws from the United States, Germany, and Japan, while polymer resin supply rests on Saudi Arabian and South Korean petrochemical output. Tariff exposure runs through Chinese phosphate export quota volatility. Distribution runs through hospital group purchasing organizations in North America and pharmacy wholesale networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The enema based products market is transitioning from phosphate-centric osmotic formulations to saline and oil-based alternatives with integrated temperature-sensor documentation. This technology shift rewards manufacturers with intravenous fluid manufacturing heritage and punishes legacy phosphate specialists.
For Market Incumbents: Anchor sterile production scale in existing parenteral-grade facilities to defend against device-specialist entrants lacking aseptic filling certification. Accelerate saline diversification ahead of EMA formulary exclusion protocols. Prioritize backward integration into polymer resin molding to capture bioplastic packaging premiums under France's AGEC law. For New Entrants and Emerging Players: ANVISA pathway simplification in Brazil opens a window for disposable enema kit manufacturers to establish Latin American footholds before incumbent GPO contract renewals. Target home care patient segments with telehealth-integrated subscription models bypassing traditional pharmacy wholesale. Pursue white-label partnerships with US accountable care organizations embedding automated refill triggers into chronic care workflows. For Investors and Strategic Acquirers: Re-rating potential sits with device-drug combination kit specialists given ISO 13485 audit backlog extending certification timelines to 14-18 months. Long-term viability favors manufacturers with diversified formulation chemistry and direct-to-patient channel control. Monitor ANVISA registration velocity as inflection indicator for Latin American market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Saline Formulation Diversification | FDA boxed warnings on phosphate enemas redirect R&D investment toward electrolyte-compatible alternatives. |
| Bioplastic Packaging Transition | France's AGEC law mandates PLA-based bottles by 2025, rewarding first-mover manufacturers with premium shelf placement. |
| Telehealth Platform Integration | Remote compliance documentation compresses boundaries between clinical supervision and home administration in US Medicare Advantage plans. |
| ANVISA Registration Acceleration | Brazil's streamlined medical device pathway reduces time-to-market for disposable kit producers seeking Latin American expansion. |
| Direct-to-Patient Subscription Models | Automated 90-day refill cycles lock in adherence and displace traditional pharmacy wholesale channels for chronic constipation management. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with hospital procurement managers, GPO contracts specialists, biomedical engineers, and home health agency administrators combined with FDA 510(k) databases, EMA periodic safety review reports, and ISO certification registries. Bottom-up volume modeling and top-down value reconciliation triangulated market estimates across formulation chemistry, end-user setting, and regional regulatory clusters.
Reconciliation of shipment data, import statistics, and manufacturer production disclosures informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application, end user, packaging format, and regional reimbursement protocol. CAGRs were derived from trend extrapolation of home care discharge acceleration and phosphate formulation contraction. Forecast inputs incorporated METI household survey data from Japan and CMS Medicare Advantage quality metric weightings.
The model assumes a particular technology adoption path; alternative pathways for connected temperature-sensor enema systems would alter the outlook if reimbursement codes fail to recognize remote compliance documentation. Forecasts reflect assumptions regarding EMA formulary exclusion timelines and ANVISA implementation consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Global Non-PVC IV Bags Market
Medical Supplies
France Hospital Supplies Market
Medical Supplies
Bladder Liners Market
Medical Supplies
Unit Dose Tubes Market
Medical Supplies
Asia Pacific Medical Rubber and Balloon Product Market
Medical Supplies
Butterfly Needle Sets Market
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Menthol Patches Market
Medical Supplies
Middle East and Africa Hospital Supplies Market
Medical Supplies
Cell Culture Media Bags Market
Medical Supplies
Medical Instruments Disinfection Market
Medical Supplies
Europe Amniotic Membrane Market
Medical Supplies
North America Surgical Glue Market
Medical Supplies
Global Lancets Market
Medical Supplies
Safety Lancet Market
Medical Supplies
Cryoboxes Market