
 Nasal Oxygen Cannula Market | 2026-2036
Nasal Oxygen Cannula Market Size, Share, and Industry Trends Forecast 2026-2036
Nasal Oxygen Cannula Market Foresight
Micro-lumen tubing extrusion and over-molded nasal prong geometries is rewriting how manufacturers balance oxygen delivery efficiency with patient comfort. Fisher & Paykel Healthcare Limited anchors the high-flow therapy segment through integrated humidification systems. Medtronic plc leverages its hospital contracting scale to dominate acute care procurement channels. Salter Labs specializes in pediatric configurations with color-coded sizing and softer durometer materials.
A nasal oxygen cannula is a bilateral nasal tube device, typically extruded from medical-grade PVC or silicone with lumen diameters of 2-4 mm, designed to deliver supplemental oxygen at flow rates from 0.5 to 6 liters per minute for hypoxic patients. High-flow nasal cannula systems now command premium positioning as they interface directly with heated humidifiers and blenders for precise FiO2 control. The homecare end-user segment represents the fastest-growing channel as durable medical equipment suppliers extend remote patient monitoring capabilities alongside oxygen concentrator rentals. PVC material formulations retain volume dominance despite silicone variants gaining share in long-wear applications where skin breakdown prevention matters.
The FDA's Quality System Regulation and ISO 13485 certification requirements shape manufacturing protocols and supplier qualification timelines for all US-market entrants. The EU MDR's tightened clinical evidence standards for Class I reusable devices are extending technical documentation obligations for European distribution. China's NMPA medical device registration pathways now mandate in-country biocompatibility testing, adding compliance layers for imported cannula assemblies. Stakeholders must monitor how payer pre-authorization algorithms for home oxygen therapy reshape cannula replacement schedules and volume forecasting.
Market Dynamics
The migration of oxygen therapy from acute care facilities to domiciliary settings is restructuring procurement volumes and cannula replacement cadences across the supply chain. This shift compresses hospital purchasing power while elevating durable medical equipment distributors as volume gatekeepers.
Growth Catalysts
- Medicare Reimbursement Expansion:CMS durable medical equipment coverage for home oxygen therapy sustains replacement demand for nasal cannula assemblies across the United States patient base.
- High-Flow Therapy Adoption:Heated humidification interfaces are penetrating respiratory care protocols, requiring specialized cannula geometries with integrated temperature sensing ports.
- Silicone Material Transition:Long-wear applications in pediatric and geriatric populations are pulling demand toward softer durometer formulations that reduce nasal vestibule trauma.
Market Restraints
- Medical-Grade PVC Feedstock Volatility:Resin price swings tied to petrochemical supply chains compress margin predictability for extrusion-dependent manufacturers.
- Biocompatibility Testing Burden:FDA strengthened cytotoxicity and sensitization requirements for Class I devices, extending new product qualification timelines by 8-14 months.
- Single-Use Plastic Restrictions:EU Single-Use Plastics Directive and analogous state-level mandates in California and New York threaten volume economics for disposable cannula configurations.
Strategic Opportunities
- Remote Patient Monitoring Integration:Bluetooth-enabled flow sensors embedded in cannula tubing enable oxygen saturation tracking, creating recurring revenue streams for homecare equipment lessors.
- Pediatric Configuration Gap:Premature infant and neonatal sizing below 2mm lumen diameter remains underserved, with only two qualified suppliers holding ISO 13485 certification for this range.
- India Homecare Infrastructure:PLI scheme incentives for medical device manufacturing and expanding private health insurance penetration are establishing domestic production and distribution pathways.
Industry Challenges
- Micro-Extrusion Talent Scarcity:Precision tubing operations requiring sub-millimeter tolerance control face recruitment gaps for polymer process engineers with ISO 13485 audit experience.
- Legacy Sterilization Validation:Ethylene oxide residual limits under EPA National Emission Standards are forcing revalidation of entire sterilization cycles for established product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nasal Oxygen Cannula Market |
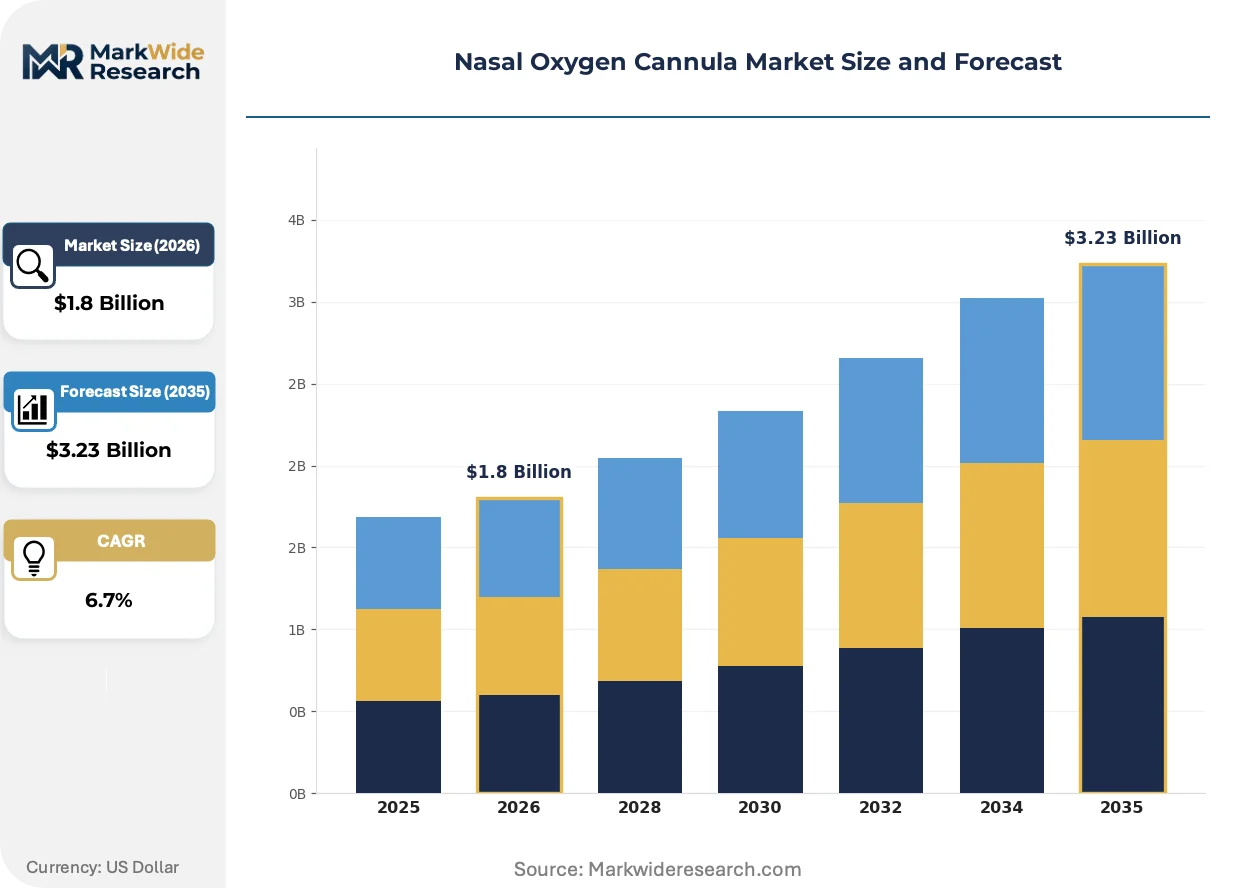
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Flow, Low-Flow, Pediatric, Adult Material: PVC, Silicone, Rubber, Polycarbonate End User: Homecare, Hospitals, Ambulatory Surgery Centers, Clinics Application: Respiratory Support, Anesthesia, Emergency Care, Pulmonary Rehabilitation |
| Companies Covered | Teleflex Incorporated, Fisher & Paykel Healthcare Limited, Flexicare Medical Ltd., Vapotherm Inc., ResMed Inc., Salter Labs, Medtronic plc, Allied Medical LLC, Well Lead Medical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nasal Oxygen Cannula Market Shifts & Advancements
Material science advances and regulatory tightening are converging to redefine cannula performance specifications and manufacturing protocols. Three developments are commanding strategic attention from product development teams.
Micro-lumen co-extrusion with embedded copper filament for real-time temperature monitoring is rendering obsolete passive high-flow delivery systems that rely on external probe placement. Academic medical centers in the United States and Germany are piloting these smart cannula configurations for ICU step-down protocols. The technology compresses nursing workflow burden while enabling closed-loop humidification control.
EU MDR's tightened clinical evidence standards for Class I reusable devices are extending technical documentation obligations for European distribution. Manufacturers must now submit biocompatibility testing against ISO 10993-5 and ISO 10993-10 for every material variant, not just initial platform approvals. Pediatric and long-term oxygen therapy segments face the steepest compliance cost escalation as patient-contact duration triggers higher evidence tiers.
Hospital purchasing cooperatives are consolidating oxygen therapy procurement under single-source agreements that bundle cannula supply with concentrator and liquid oxygen equipment leases. This disintermediates traditional durable medical equipment distributors in favor of manufacturer-direct contracting. The concentration is most visible in United States integrated delivery networks exceeding 50 hospital beds, where GPOs now control 60-70 percent of cannula volume allocation.
Nasal Oxygen Cannula Market Segmentation
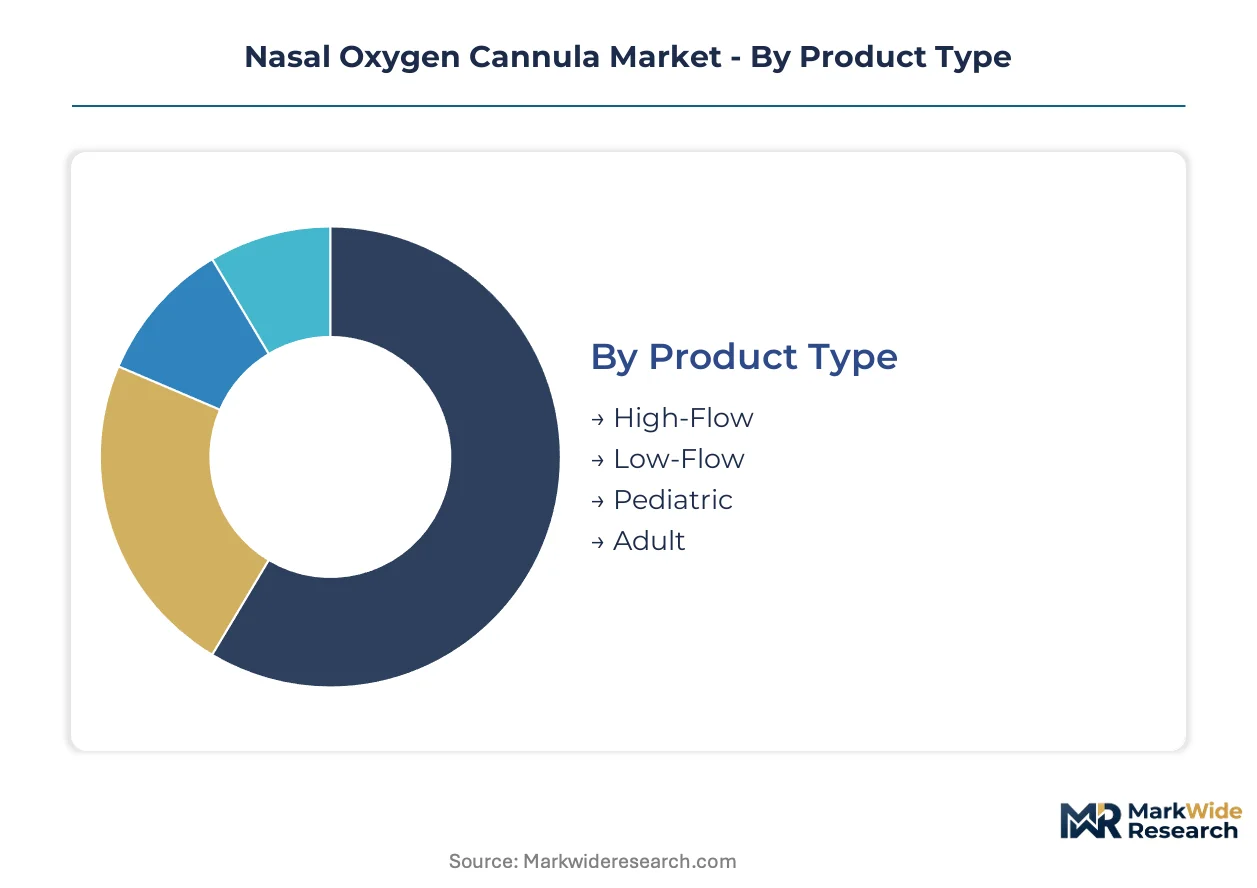
Segmentation in the nasal oxygen cannula market reveals distinct replacement cadences and margin profiles across product configurations. Cycle times range from 24-hour hospital disposables to 30-day homecare rentals, reshaping inventory strategies for distributors and manufacturers alike.
Product Type:
Replacement velocity varies dramatically across flow specifications, with acute care products turning over in days while homecare configurations persist for weeks.
- High-Flow:Heated humidification interfaces with integrated temperature sensing ports command premium positioning in ICU step-down protocols. Demand concentrates in United States academic medical centers adopting closed-loop oxygen delivery systems, driven by nursing workflow compression mandates and reimbursement codes for complex respiratory care.
- Low-Flow:Standard 0.5-6 LPM configurations dominate Medicare-funded home oxygen therapy, where durable medical equipment suppliers bundle cannula replacement with concentrator leases. PVC extrusions retain volume leadership despite silicone variants gaining traction in long-wear applications.
- Pediatric:Sub-2mm lumen diameters with color-coded sizing address neonatal and premature infant oxygenation needs.
- Adult:Universal-fit geometries with adjustable head strap configurations serve the broadest patient population across care settings.
Low-Flow dominates installed base. High-Flow is where expansion concentrates.
Material:
Raw material selection dictates biocompatibility testing burden and per-unit manufacturing cost, with petroleum-derived formulations facing regulatory headwinds.
- PVC:Medical-grade extrusions with plasticizer stabilization retain cost advantage for high-volume disposable applications. United States hospital purchasing cooperatives favor PVC configurations under bundled procurement agreements, constrained by FDA cytotoxicity requirements for Class I devices.
- Silicone:Softer durometer formulations reduce nasal vestibule trauma in pediatric and geriatric populations requiring extended wear. Demand pulls toward homecare channels where skin breakdown prevention justifies higher replacement costs.
- Rubber:Latex-alternative compounds serve niche applications requiring extreme flexibility.
- Polycarbonate:Rigid structural components enable integrated flow sensor housings for remote patient monitoring.
PVC commands current volume. Silicone is gaining share fastest.
End User:
Channel structure determines pricing power and replacement scheduling, with institutional buyers leveraging scale against fragmented homecare distributors.
- Homecare:Durable medical equipment lessors bundle cannula supply with oxygen concentrator rentals, extending remote patient monitoring capabilities via Bluetooth-enabled flow sensors. Medicare reimbursement expansion sustains replacement demand across United States patient base.
- Hospitals:Integrated delivery networks exceeding 50 beds consolidate procurement under GPO single-source agreements, disintermediating traditional distributors. Acute care turnover compresses margin but guarantees volume.
- Ambulatory Surgery Centers:Same-day discharge protocols drive disposable consumption with minimal inventory holding.
- Clinics:Outpatient pulmonary rehabilitation programs require mid-cycle replacement schedules.
Hospitals anchor procurement volume. Homecare shows the steepest expansion trajectory.
Application:
Clinical use case shapes performance specifications and regulatory evidence requirements, with emergency applications demanding rapid deployment features.
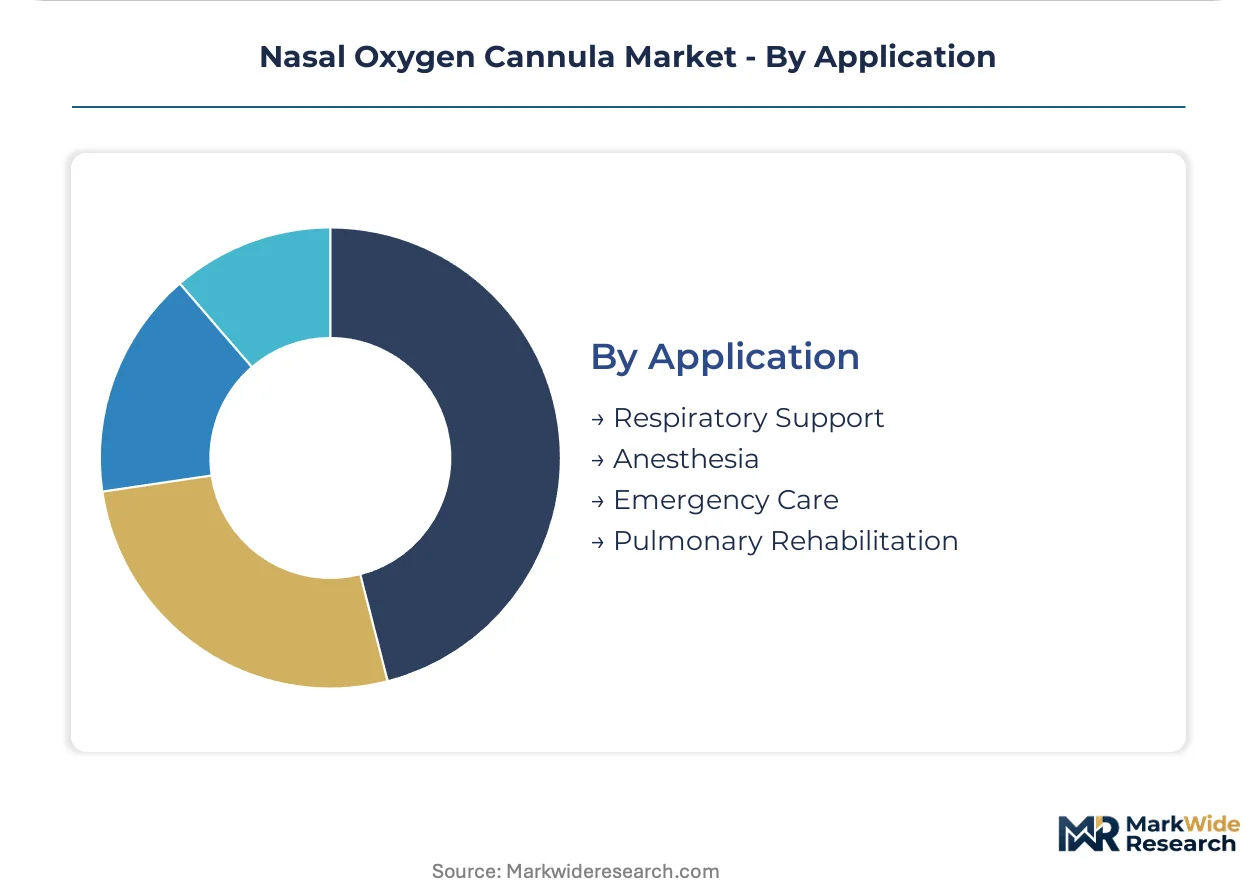
- Respiratory Support:Chronic hypoxia management in COPD and interstitial lung disease populations drives recurring cannula consumption. United States prevalence of chronic obstructive pulmonary disease sustains volume leadership through Medicare durable medical equipment channels.
- Anesthesia:Perioperative oxygenation requires single-use configurations with guaranteed sterility assurance levels.
- Emergency Care:Pre-hospital and trauma bay applications prioritize packaging efficiency and rapid deployment.
- Pulmonary Rehabilitation:Exercise tolerance protocols in outpatient settings require comfortable long-wear geometries.
Respiratory Support dominates installed base. Pulmonary Rehabilitation is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexican extrusion houses supply PVC tubing assemblies to United States durable medical equipment distributors, anchoring a cross-border supply corridor that feeds Medicare-funded home oxygen therapy channels.
United States
Chronic obstructive pulmonary disease prevalence and Medicare reimbursement for durable medical equipment sustain volume leadership. FDA strengthened biocompatibility requirements for Class I devices elevate material standards across the supply chain. Minnesota and Massachusetts host medical device clusters where heated humidification interfaces undergo clinical validation.
Germany
Academic medical centers pilot smart cannula configurations with embedded temperature monitoring for ICU step-down protocols. EU MDR tightened clinical evidence standards for Class I reusable devices extend technical documentation obligations. Baden-Württemberg precision extrusion specialists supply micro-lumen tubing to ventilator OEMs.
China
Expanding private health insurance penetration and NMPA medical device registration pathways mandate in-country biocompatibility testing. Domestic production scales under medical device manufacturing incentives. Jiangsu and Zhejiang provinces concentrate tubing extrusion capacity serving Asia-Pacific distribution networks.
India
PLI scheme incentives for medical device manufacturing establish domestic production pathways alongside expanding homecare infrastructure. CDSCO regulatory harmonization accelerates import substitution for critical care consumables. Gujarat and Karnataka medical device parks attract extrusion equipment investments.
Japan
Aging demographics drive long-term oxygen therapy adoption with preference for softer durometer silicone formulations. PMDA quality system requirements shape supplier qualification timelines for reusable device platforms. Osaka-based polymer processors specialize in pediatric configuration development.
Nasal Oxygen Cannula Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement tiers. Hospital purchasing cooperatives and durable medical equipment distributors function as volume gatekeepers, compressing margin for manufacturers without direct contracting scale. Three archetypes dominate: integrated respiratory therapy platforms, standalone consumable specialists, and regional extrusion houses serving private-label distributors. Competitive moves concentrate on backward integration into polymer compounding and strategic partnerships with oxygen concentrator OEMs.
Among diversified healthcare conglomerates, Medtronic plc and ResMed Inc. occupy positions spanning acute care procurement channels and homecare equipment integration. Fisher & Paykel Healthcare Limited exemplifies the therapy-system specialist archetype, anchoring premium positioning through humidification platform control. Salter Labs represents the standalone consumable specialist model with focused pediatric configuration expertise.
| Leading Market Players |
|---|
| Teleflex Incorporated |
| Fisher & Paykel Healthcare Limited |
| Flexicare Medical Ltd. |
| Vapotherm Inc. |
| ResMed Inc. |
| Salter Labs |
| Medtronic plc |
| Allied Medical LLC |
| Well Lead Medical Co., Ltd. |
| Others |
Supply & Pricing Matrix
Medical-grade PVC resin price volatility tied to petrochemical feedstock swings compresses margin predictability for extrusion-dependent manufacturers while simultaneously widening pricing spreads between commodity PVC configurations and silicone-based premium tiers. This input-cost instability forces procurement managers to dual-source resin contracts and accelerates substitution toward softer durometer materials where reimbursement codes permit.
Pricing Analysis
The technology-generation pricing gap separates passive high-flow systems from next-generation smart cannulas with embedded temperature monitoring and Bluetooth-enabled flow sensing. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by biocompatibility certification tier and integrated sensor capability. Pricing pressure stems from hospital GPO consolidation under single-source agreements that bundle cannula supply with oxygen concentrator leases. Homecare durable medical equipment distributors exhibit highest price sensitivity due to Medicare reimbursement compression, while academic medical centers purchasing closed-loop ICU systems show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from United States hospital purchasing cooperatives strain working capital for Mexican extrusion houses supplying PVC tubing assemblies across the border. Geographic supply concentrates in Mexico, China, and Germany, with Jiangsu and Zhejiang provinces hosting tubing extrusion capacity and Baden-Württemberg specialists serving ventilator OEMs. Raw material dependencies rest on medical-grade PVC resin, silicone elastomer compounds, and copper filament for sensor integration. Single-source vulnerability runs through Mexican cross-border corridors exposed to tariff and customs disruption. Distribution runs through durable medical equipment lessors bundling cannula replacement with concentrator rentals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Non-invasive ventilation interfaces and portable oxygen concentrators with integrated nasal delivery represent credible substitution threats that cannula incumbents must neutralize through performance differentiation and therapy-system integration.
For Market Incumbents: Entrench market position through backward integration into polymer compounding to secure medical-grade PVC and silicone supply against resin volatility, while deepening hospital GPO relationships to lock out standalone consumable competitors. Priority investment targets ISO 10993-5 and ISO 10993-10 certification expansion for pediatric sub-2mm configurations where qualified supplier scarcity protects margin. For New Entrants and Emerging Players: India's underpenetrated homecare infrastructure offers white-space expansion, with PLI scheme incentives and CDSCO regulatory harmonization reducing import dependency for critical care consumables. Target neonatal and premature infant sizing below 2mm lumen diameter where only two ISO 13485-certified suppliers currently operate. Go-to-market angle emphasizes direct contracting with private health insurers expanding coverage for domiciliary oxygen therapy. For Investors and Strategic Acquirers: EU MDR's tightened clinical evidence standards for Class I reusable devices reshapes the acquisition landscape toward targets with established technical documentation and biocompatibility testing infrastructure. Long-term viability centers on respiratory therapy platform consolidation over pure-play consumable exposure. Signal to watch: FDA enforcement discretion on cytotoxicity testing timelines for Class I device amendments.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Smart Cannula | Accelerates market access for Bluetooth-enabled flow sensor configurations with closed-loop humidification control. |
| CE Marking Pathway under EU MDR | Unlocks European distribution for reusable device platforms requiring ISO 10993-5 and ISO 10993-10 documentation. |
| Hospital System Partnership | Secures volume allocation within integrated delivery networks exceeding 50 beds through GPO single-source agreements. |
| Software Companion Development | Enables remote patient monitoring revenue streams via oxygen saturation tracking integrated with concentrator lessor platforms. |
| Reimbursement Strategy Alignment | Positions premium silicone configurations within Medicare durable medical equipment coverage expansion for long-wear applications. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with respiratory therapy stakeholders and secondary validation across regulatory and procurement databases. Interview sources included clinicians managing ICU step-down protocols, hospital purchasing committee members, biomedical engineers specifying humidification interfaces, GPO contracts managers allocating cannula volumes, and durable medical equipment lessors bundling oxygen therapy services. Secondary sources encompassed FDA 510(k) filings, CMS Medicare reimbursement schedules, hospital procurement databases, GPO contract disclosures, and ISO 13485 certification registries. Bottom-up demand modeling triangulated against top-down market sizing across product type, material, end user, and application dimensions.
Forecast inputs considered replacement cadence variation between 24-hour hospital disposables and 30-day homecare rentals, Medicare reimbursement expansion trajectories, and high-flow therapy adoption curves in academic medical centers. Segmentation dimensions modeled included flow specification tier, material formulation, care setting, patient population age bracket, and regional regulatory cluster. CAGRs derived from installed base turnover rates, procedure volume projections, and equipment lease penetration assumptions. Industry-specific inputs incorporated FDA biocompatibility testing timeline extensions and EU MDR technical documentation obligations.
The forecast holds incumbent behavior within observed patterns; aggressive moves by ventilator OEMs integrating cannula supply or oxygen concentrator manufacturers backward into tubing extrusion would shift outcomes. Macroeconomic deviation in petrochemical feedstock pricing, regulatory acceleration of single-use plastic restrictions, or technological breakthrough in non-invasive ventilation interfaces would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Supplies
Saudi Arabia Medical Disposables Market
Medical Supplies
Chemo Graded Nitrile Powder-Free Medical Examination Gloves Market
Medical Supplies
Nursing Breast Pads Market
Medical Supplies
Safety Pen Needles Market
Medical Supplies
Plastic Blood Bags Market
Medical Supplies
X-Ray Aprons Market
Medical Supplies
Culture Media Preparators Market
Medical Supplies
Global Disposable Blood Bags Market
Medical Supplies
Plastic Medicine Spoons Market
Medical Supplies
Surgical Gowns Market
Medical Supplies
Cell Culture Media Storage Containers Market
Medical Supplies
Global Enema Based Products Market
Medical Supplies
Skin Tac Market
Medical Supplies
Contrast Media Consumables Market
Medical Supplies
Global Hospital Linen Supply and Management Services Market
Medical Supplies
Saudi Arabia Hospital Supplies Market