
 Switzerland Transportation Infrastructure Construction Market | 2026-2036
Switzerland Transportation Infrastructure Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Transportation Infrastructure Construction Market Analytics
Skilled tunnel engineering labor is rotating toward alpine rail projects as Switzerland advances its Gotthard Base Tunnel network expansion and secondary pass links. Implenia Schweiz AG dominates complex underground construction through its heritage in Swiss rail infrastructure. Marti Holding AG anchors civil works across cantonal road programs with deep equipment fleets. Frutiger Unternehmungen AG leverages regional contracting relationships in western Switzerland to secure recurring municipal bridge awards.
Switzerland transportation infrastructure construction encompasses the planning, engineering, and physical assembly of roads, railways, bridges, and tunnels using materials engineered to withstand alpine seismic loads, freeze-thaw cycles, and grades exceeding six percent. These structures enable freight transit through the Gotthard and Lötschberg corridors while connecting multimodal hubs across the Swiss Plateau and mountain cantons. Concrete remains the volume leader in tunnel linings and bridge superstructures, though steel competes for long-span alpine crossings where weight reduction matters. Composite materials represent the fastest-growing construction material category as cantonal authorities specify fiber-reinforced polymers for corrosion-resistant bridge decks in salt-exposed valleys.
Swiss Federal Railways coordinates with the Federal Office of Transport to enforce tunnel safety standards under the AlpTransit framework, while the Swiss Society of Engineers and Architects maintains SIA structural codes that govern load-bearing design across all cantonal projects. Swissmedic and federal environmental offices do not regulate this sector; instead, the State Secretariat for Economic Affairs shapes market access through public procurement rules favoring domestic contractor participation. Stakeholders must monitor how forthcoming revisions to CO2 emission benchmarks for construction materials reshape supplier qualification criteria and long-dated project tendering schedules.
Market Dynamics
Switzerland's alpine rail corridor expansion is compressing project timelines and concentrating specialized tunnel engineering capacity around the Gotthard Base Tunnel network, forcing cantonal procurement offices to accelerate contractor qualification cycles.
Growth Catalysts
- AlpTransit framework:Federal tunnel safety mandates under this program are mandating seismic retrofit investments across existing alpine rail links, generating sustained engineering demand.
- Low-carbon concrete specifications:Federal climate legislation tightening CO2 emissions benchmarks for construction materials is pulling innovative binder technologies into tunnel lining contracts.
- Zurich-Geneva-Basel corridor:Intercity connectivity upgrades across this economic spine are accelerating bridge rehabilitation procurement cycles.
Market Restraints
- Alpine cement supply concentration:Domestic clinker production capacity concentrates in limited mountain valley sites, exposing project cost structures to regional logistics bottlenecks.
- Specialized tunnel boring equipment:European machinery manufacturers control the majority of large-diameter TBM supply, creating procurement lead time volatility for complex underground segments.
- Freeze-thaw durability standards:SIA structural codes mandate extended curing protocols for high-altitude concrete placements, compressing seasonal construction windows.
Strategic Opportunities
- Secondary alpine pass links:Cantonal road authorities in Valais and Graubünden are advancing feasibility studies for new tunnel connections bypassing existing seasonal closures.
- Fiber-reinforced polymer bridge decks:Salt-exposed valley municipalities are specifying composite materials for corrosion-resistant superstructures, opening material substitution pathways.
- Swiss Federal Railways modernization budgets:Federal rail electrification and digital signaling investments are expanding the addressable market for integrated civil-electrical contractors.
Industry Challenges
- Geotechnical engineering specialization:The finite pool of engineers qualified for high-pressure alpine tunnel design is creating bidding competition bottlenecks for complex underground packages.
- Multimodal hub integration:Urban rail-cargo interchanges in Basel and Zurich require coordination across federal, cantonal, and municipal permitting layers, extending project authorization timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Transportation Infrastructure Construction Market |
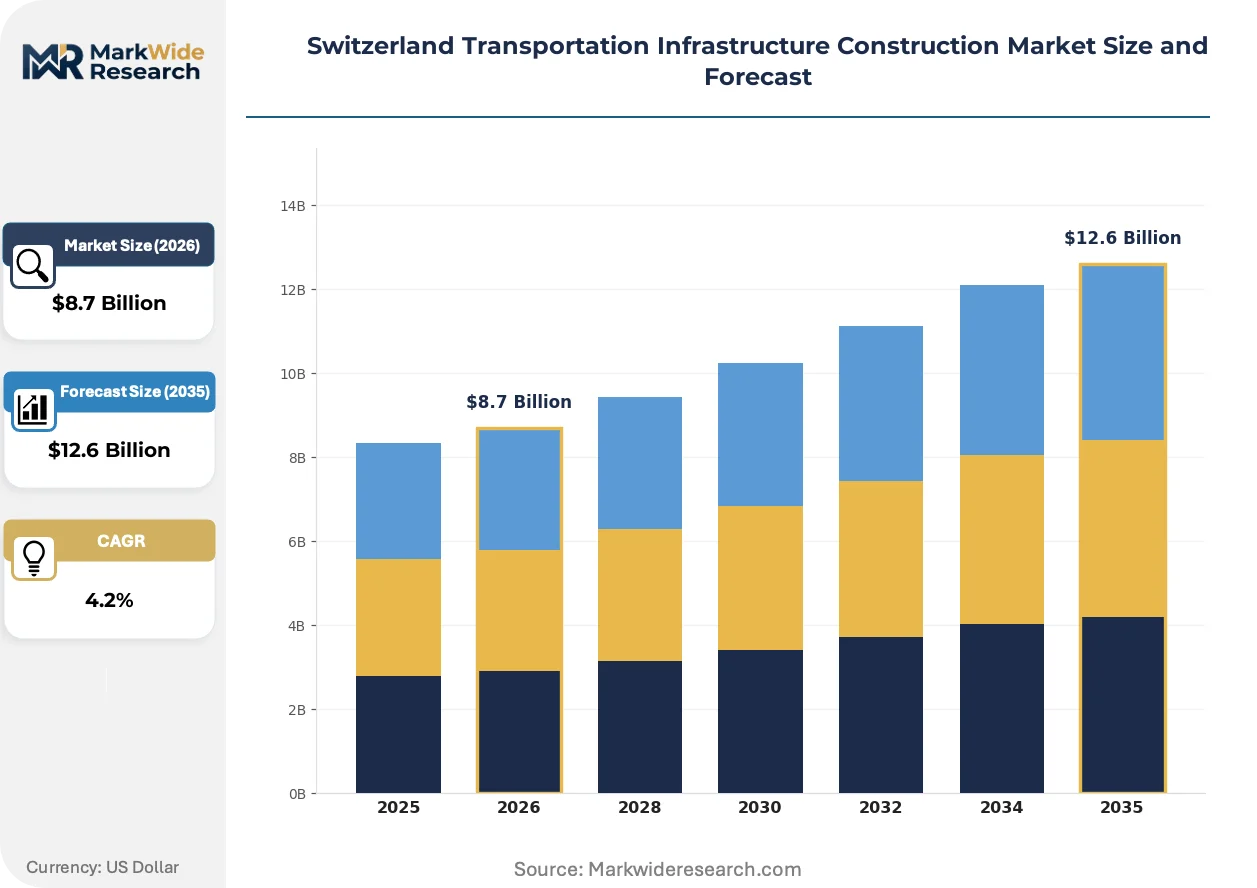
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $12.6 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Roads, Railways, Bridges, Tunnels Construction Material: Concrete, Steel, Asphalt, Composite End User: Government, Contractors, Consultants, Investors Funding Source: Public Funding, Private Investment, Grants, Loans |
| Companies Covered | Frutiger Unternehmungen AG, Cellere-Gruppe, Implenia Schweiz AG, Strabag, Georges Chetelat SA, WALO, Induni & Cie SA, Keller-Frei Zurich, Marti Holding AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Transportation Infrastructure Construction Market Evolving Landscape
Alpine construction methodologies are converging with digital monitoring systems and low-carbon material science, reshaping how Swiss contractors deliver seismic-resilient infrastructure against compressed federal climate deadlines.
Geotechnical instrumentation arrays embedded within tunnel linings are enabling real-time structural health monitoring throughout the operational lifecycle. Swiss Federal Railways is mandating these sensor networks for all new AlpTransit corridor segments. The technology is miniaturizing installation footprints while expanding data capture frequency, allowing predictive maintenance scheduling that extends asset replacement cycles.
Federal amendments to Switzerland's CO2 emissions standards for construction materials are forcing binder suppliers to document embodied carbon across project deliveries. The regulation is disqualifying conventional Portland cement formulations from cantonal bridge tenders above specified volume thresholds. Western Switzerland municipalities are responding by pre-qualifying suppliers with verified low-clinker mix designs before tender release.
Cantonal procurement offices are consolidating multi-year maintenance contracts with single civil works contractors rather than fragmenting projects across seasonal bidding cycles. This bundling is concentrating recurring revenue with established regional players and compressing market entry opportunities for new bidders. The shift is most visible in Aargau and Bern, where bridge inspection and repair obligations now span decade-long performance periods.
Switzerland Transportation Infrastructure Construction Market Segmentation
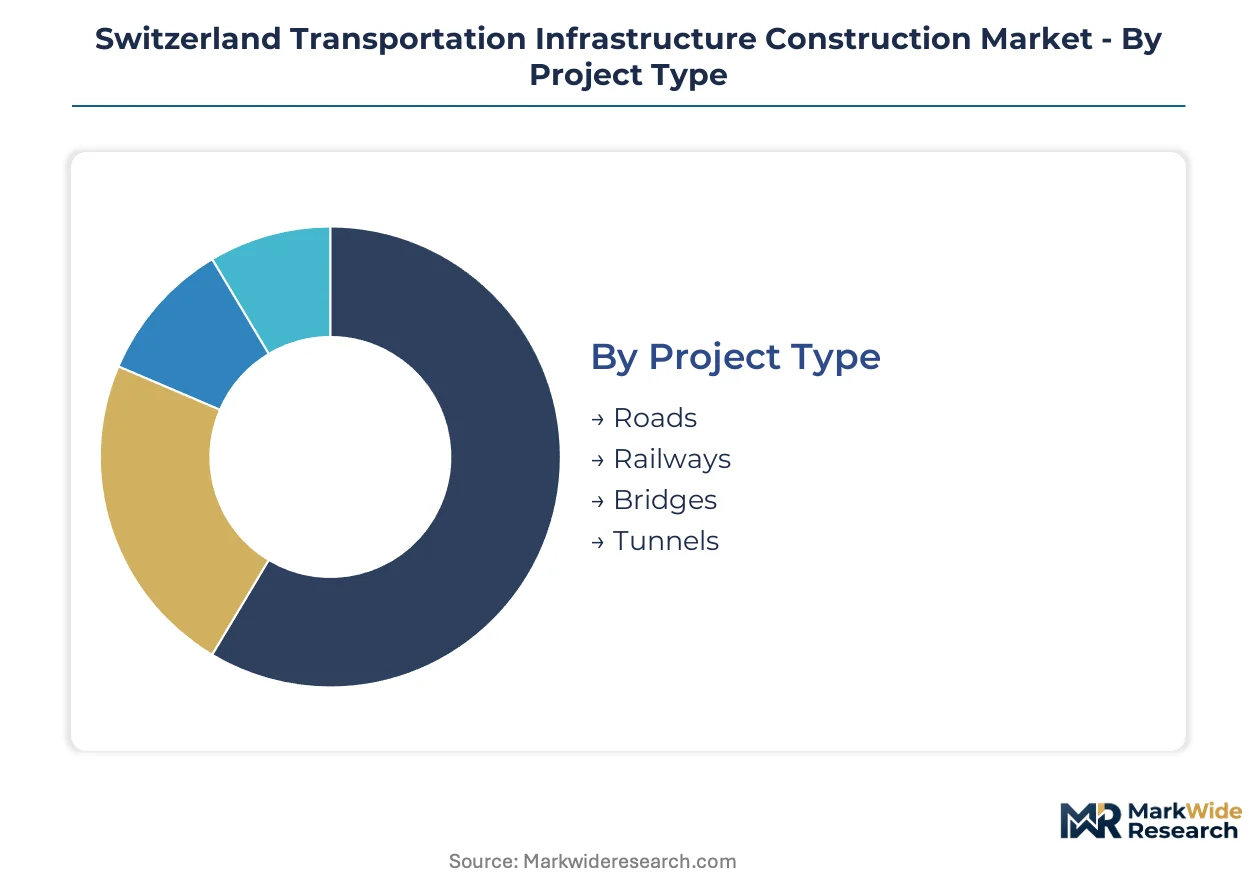
Switzerland's transportation infrastructure construction market segments along project delivery channels that reflect the federal-cantonal funding split and the specialized engineering requirements of alpine terrain. Each segmentation dimension reveals distinct procurement pathways, material specifications, and stakeholder risk allocations that shape contractor positioning.
Project Type:
Roads and railways flow through cantonal procurement offices with multi-year maintenance bundling, while bridges and tunnels channel through federal AlpTransit frameworks with stricter safety mandates.
- Roads:Cantonal highway authorities specify asphalt and concrete surfaces engineered for grades exceeding six percent and freeze-thaw durability. Demand clusters in the Zurich-Geneva-Basel corridor where intercity connectivity upgrades are compressing procurement cycles.
- Railways:Swiss Federal Railways coordinates electrification and digital signaling investments under federal modernization budgets. Alpine seismic loads and tunnel safety standards under the AlpTransit framework mandate specialized civil-electrical contractor qualifications.
- Bridges:Municipal and cantonal authorities drive rehabilitation demand across salt-exposed valleys.
- Tunnels:Gotthard Base Tunnel network expansion and secondary pass links concentrate specialized tunnel boring equipment procurement.
Roads dominate installed base by lane-kilometers. Railways is where expansion concentrates as federal climate legislation accelerates modal shift investment.
Construction Material:
Material selection tracks altitude exposure and structural load requirements, with cost tiers separating commodity concrete from premium composite specifications.
- Concrete:Volume leader in tunnel linings and bridge superstructures, formulated with low-carbon binder technologies to meet tightened CO2 emissions benchmarks. Extended curing protocols for high-altitude placements compress seasonal construction windows.
- Steel:Competes for long-span alpine crossings where weight reduction matters against seismic load constraints. European mill supply concentration creates procurement lead time volatility.
- Asphalt:Standard for road surfaces across the Swiss Plateau with regional logistics bottlenecks from limited mountain valley production sites.
- Composite:Fiber-reinforced polymers specified for corrosion-resistant bridge decks in salt-exposed valleys, climbing the fastest as municipalities pre-qualify suppliers with verified performance data.
Concrete dominates installed base by volume. Composite is where expansion concentrates as cantonal authorities specify material substitution for durability-critical applications.
End User:
Customer type determines contract scale and risk allocation, with government buyers driving public procurement rules favoring domestic contractor participation.
- Government:Federal and cantonal procurement offices enforce domestic participation preferences and multi-year performance bundling. Swiss Federal Railways and cantonal highway authorities represent the primary demand concentration.
- Contractors:Implenia Schweiz AG and Marti Holding AG anchor complex underground and civil works delivery through heritage equipment fleets and regional contracting relationships.
- Consultants:Geotechnical engineering specialists face bidding competition bottlenecks from finite qualified pools for high-pressure alpine tunnel design.
- Investors:Limited private capital participation in core infrastructure, concentrated in ancillary multimodal hub development.
Government dominates installed base by contract value. Contractors is where expansion concentrates as cantonal procurement offices consolidate recurring revenue with established regional players.
Funding Source:
Finance structure shapes project authorization timelines and stakeholder coordination requirements across federal, cantonal, and municipal permitting layers.
- Public Funding:Federal rail modernization budgets and cantonal road programs represent the dominant capital source, with State Secretariat for Economic Affairs shaping market access through procurement rules.
- Private Investment:Concentrated in urban rail-cargo interchanges in Basel and Zurich requiring complex multi-layer permitting coordination.
- Grants:Federal climate legislation channels support toward low-carbon material innovation and CO2 emissions reduction verification systems.
- Loans:Cantonal infrastructure banks finance secondary alpine pass feasibility studies in Valais and Graubünden.
Public funding dominates installed base by project count. Grants is where expansion concentrates as federal amendments to construction material emissions standards reshape supplier qualification criteria.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Swiss Federal Office of Transport coordinates infrastructure investment across federal-cantonal boundaries, concentrating procurement authority in the Zurich-Geneva-Basel economic corridor where intercity connectivity upgrades drive contract flow.
Zurich Metropolitan Area
Rail electrification and digital signaling investments dominate capital allocation. Swiss Federal Railways mandates seismic retrofit standards under the AlpTransit framework. Tunnel boring equipment procurement concentrates around the Gotthard Base Terminal expansion in Rapperswil-Jona.
Geneva-Canton Vaud Corridor
Intercity rail capacity expansion absorbs federal modernization budgets. The State Secretariat for Economic Affairs enforces domestic contractor participation rules in public tenders. Bridge rehabilitation clusters along the Rhône valley where salt-exposure drives composite material specification.
Basel Region
Multimodal freight interchanges require coordination across federal, cantonal, and municipal permitting layers. Swiss Federal Railways prioritizes cargo-rail integration at the tri-national logistics hub. Urban tunnel projects face compressed authorization timelines from layered regulatory review.
Valais Alpine Zone
Secondary pass link feasibility studies advance through cantonal infrastructure bank financing. SIA structural codes mandate extended curing protocols for high-altitude concrete placements. New tunnel connections bypassing seasonal closures concentrate geotechnical engineering demand in Brig and Sion.
Graubünden Eastern Cantons
Alpine road tunnel maintenance bundling contracts consolidate with established regional players. Federal climate legislation channels grant support toward low-carbon binder technologies for mountain valley cement production. Albula and Bernina corridor upgrades drive specialized contractor qualification cycles.
Switzerland Transportation Infrastructure Construction Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with scale advantages concentrating in firms controlling heritage equipment fleets and multi-decade cantonal relationships. The upper tier commands complex underground packages through accumulated tunnel engineering expertise, while mid-size contractors compete for recurring municipal bridge awards. Two strategic archetypes dominate: integrated civil-electrical contractors capturing federal rail modernization budgets, and regional specialists anchoring cantonal road maintenance bundling. Competitive moves center on multi-year performance contract consolidation and low-carbon material pre-qualification ahead of tender release.
Within the integrated tier, Implenia Schweiz AG and Marti Holding AG exemplify scale-driven positioning through equipment depth and federal-cantonal procurement access. Frutiger Unternehmungen AG occupies a specialist position in western Switzerland, leveraging regional contracting density for recurring municipal awards. These three firms represent contrasting pathways to market presence: heritage rail infrastructure integration, civil works fleet scale, and geographic relationship concentration.
| Leading Market Players |
|---|
| Frutiger Unternehmungen AG |
| Cellere-Gruppe |
| Implenia Schweiz AG |
| Strabag |
| Georges Chetelat SA |
| WALO |
| Induni & Cie SA |
| Keller-Frei Zurich |
| Marti Holding AG |
| Others |
Value Network & Pricing Analysis
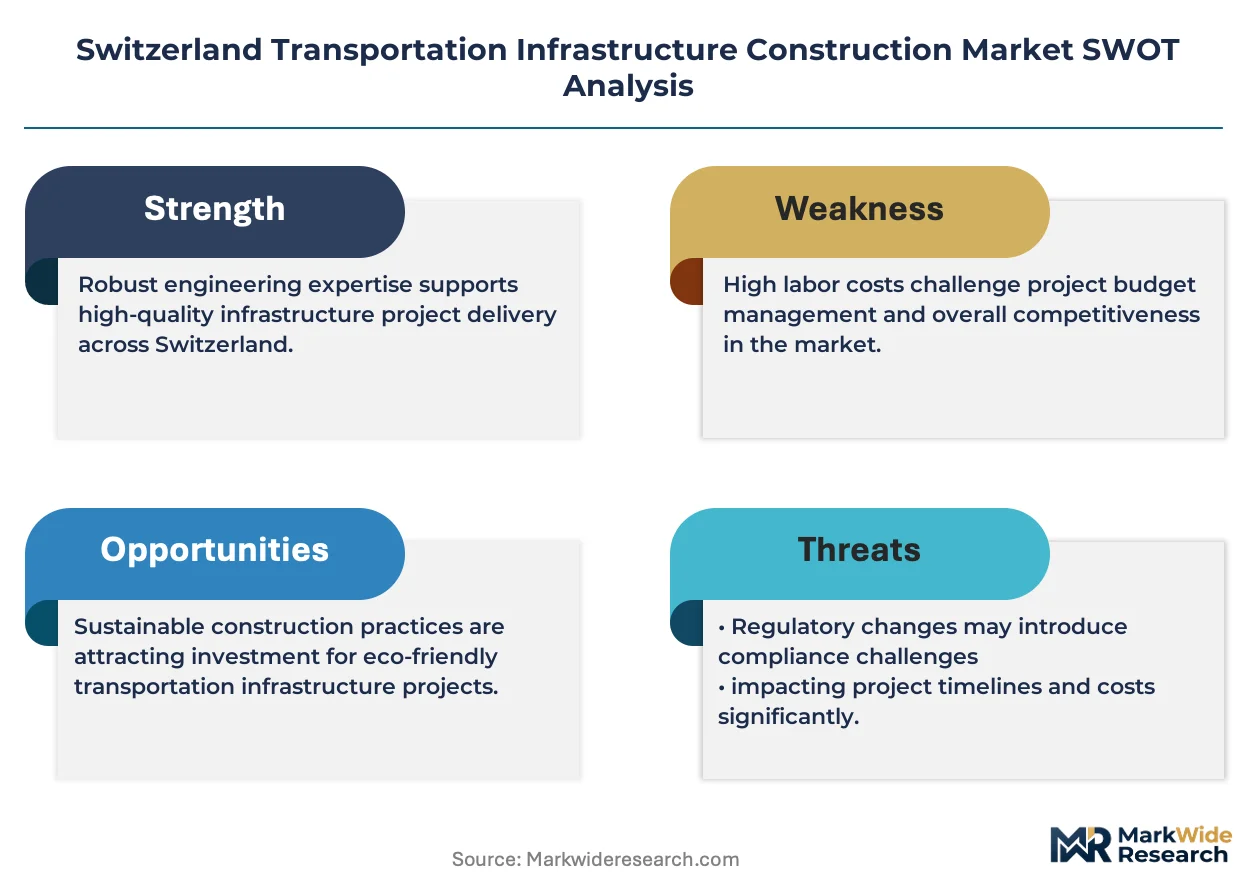
Twelve-to-eighteen-month lead times for large-diameter tunnel boring equipment procurement compress contractor bidding windows and amplify pricing power for European machinery manufacturers serving alpine rail projects. This inventory-to-delivery gap concentrates cost pressure on cantonal procurement offices while reinforcing premiums for specialized tunnel engineering capacity.
Pricing Analysis
Alpine valley-to-Plateau price spreads of fifteen to twenty-five percent separate high-altitude concrete placements from standard-grade formulations. Project-based contract structures dominate, with price differentiation tracking SIA certification tiers and low-carbon binder compliance levels. Cost compression in conventional Portland cement mixes is intensifying because federal CO2 emissions standards disqualify high-clinker formulations from cantonal tenders above volume thresholds. Municipal bridge authorities show highest price sensitivity, while Swiss Federal Railways electrification contracts demonstrate lowest sensitivity due to performance-bundling requirements.
Supply Chain Analysis
Strategic stockpiling of alpine cement clinker dominates inventory strategy, with cantonal authorities mandating ninety-day buffer stocks against mountain valley logistics disruptions. Domestic supply concentrates in limited Valais and Graubünden production sites, with secondary sourcing from Germany and Italy for steel reinforcement. Raw material dependencies center on limestone aggregate, low-carbon binder feedstocks, and specialized TBM cutterhead components. Single-source vulnerability runs through European machinery manufacturers controlling large-diameter boring equipment. Distribution runs through cantonal procurement offices with multi-year performance bundling to established regional contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Switzerland's transportation infrastructure construction market functions as a regulatory entrenchment story, where decades of AlpTransit framework compliance and SIA certification accumulation create switching costs that lock out unqualified bidders.
For Market Incumbents: Fortify position through backward integration into low-carbon binder production and exclusive equipment leasing arrangements for specialized tunnel boring machinery. Federal climate legislation tightening CO2 emissions benchmarks threatens margin compression for contractors dependent on external cement supply. Capacity addition in Valais clinker production secures supply chain control against alpine logistics bottlenecks. For New Entrants and Emerging Players: Differentiate on fiber-reinforced polymer bridge deck specialization, targeting salt-exposed valley municipalities in western Switzerland with pre-qualified composite material portfolios. Secondary alpine pass links in Graubünden represent the most penetrable geography, with cantonal infrastructure bank financing reducing capital barriers. Go-to-market execution should anchor on decade-long maintenance bundling proposals rather than fragmented project bidding. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified European construction groups seeking to monetize non-core Swiss alpine rail capabilities. Long-term viability hinges on regulatory compliance depth rather than cyclical volume exposure. Acquisition focus should center on civil-electrical contractors with integrated Swiss Federal Railways relationships. The signal to watch is forthcoming revisions to embodied carbon verification thresholds for construction material suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Carbon Binder Technology Investment | Pre-qualifies contractors for federal climate legislation-compliant tenders before competitor adaptation. |
| Multi-Year Maintenance Bundling Consolidation | Concentrates recurring revenue with established players in Aargau and Bern cantonal programs. |
| Geotechnical Engineering Capability Acquisition | Addresses bidding competition bottlenecks for high-pressure alpine tunnel design packages. |
| Fiber-Reinforced Polymer Deck Specialization | Captures corrosion-resistant bridge replacement demand across Rhône valley municipalities. |
| Alpine Logistics Infrastructure Control | Mitigates clinker supply concentration risk through Valais production site ownership or long-term offtake. |
Research Methodology
The analysis maps tunnel construction, bridge rehabilitation, road maintenance, and rail electrification sub-sectors, each validated through project procurement officers at cantonal highway authorities, Swiss Federal Railways planning executives, and geotechnical engineering directors. Primary interviews combined with secondary validation from SEC filings of listed European contractors, Swiss Federal Office of Transport project databases, and SIA structural code documentation. Bottom-up project pipeline aggregation and top-down federal budget appropriation analysis provided triangulation across data sources.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include project type, construction material specification, end-user procurement tier, and funding source structure. CAGRs were derived from project authorization timeline analysis and contractor backlog conversion rates. Forecast inputs incorporated AlpTransit framework investment schedules and cantonal climate legislation implementation trajectories without year-specific assumptions.
Material uncertainties — federal CO2 emissions benchmark revisions, alpine seismic event frequency, and European machinery manufacturer capacity allocation — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding contractor qualification cycle durations and cantonal procurement consolidation trends. Revision becomes warranted when low-carbon material compliance thresholds cross implementation thresholds ahead of supplier adaptation capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infrastructure Construction
Global Manhole Covers Market
Infrastructure Construction
Road & Highway Infrastructure Market
Infrastructure Construction
Russia Transportation Infrastructure Construction Market
Infrastructure Construction
Vietnam Data Center Construction Market
Infrastructure Construction
Italy Transportation Infrastructure Construction Market
Infrastructure Construction
Transmission and Distribution Infrastructure Market
Infrastructure Construction
Conventional Overhead Conductor Market
Infrastructure Construction
Thailand Data Center Construction Market
Infrastructure Construction
China Infrastructure Market
Infrastructure Construction
Canada Commercial Construction Market
Infrastructure Construction
Bahrain Transportation Infrastructure Construction Market
Infrastructure Construction
APAC Data Center Construction Market
Infrastructure Construction
Global Rail Infrastructure Market
Infrastructure Construction
US Pipeline Construction Market
Infrastructure Construction
Offshore Pipeline Infrastructure Market
Infrastructure Construction
North America Transportation Infrastructure Construction Market