
 US Heavy Movable Bridges Market | 2026-2036
US Heavy Movable Bridges Market Size, Share, and Industry Trends Forecast 2026-2036
US Heavy Movable Bridges Market Intelligence
The shift towards long-term public-private partnership (P3) financing models is narrowing the field of prime contractors to those with significant capital access and risk management capabilities. Skanska leverages its global experience in P3 projects to secure large-scale government contracts for new bridge construction. In contrast, AECOM positions itself through its deep expertise in engineering and design consulting, often leading complex retrofit and maintenance projects for state transportation authorities. Railway operators like CSX Corporation and BNSF Railway Company focus on maintaining their own critical movable bridge assets.
A heavy movable bridge is a structure engineered to change position to provide clearance for maritime traffic on navigable waterways. These bridges utilize complex electromechanical or hydraulic systems to operate, and must meet stringent load-bearing specifications for rail or highway traffic, often exceeding AASHTO HS-20 loading standards. Vertical lift bridge designs are gaining favor for new construction projects due to their ability to provide greater vertical and horizontal clearances compared to older bascule or swing bridge types. Transportation Agencies remain the dominant end-user segment, directing funds primarily toward maintenance and replacement installations.
The market operates under a strict regulatory framework governed by the US Coast Guard (USCG) and the Federal Highway Administration (FHWA). USCG regulations dictate the operational requirements and navigation clearances for bridges over waterways, directly influencing design and engineering choices. Concurrently, FHWA standards define the structural integrity, materials, and inspection protocols for the bridge's road or rail components. Stakeholder decisions will increasingly center on allocating capital between technologically advanced new builds and the extensive, costly upkeep of existing bridge inventories.
Market Dynamics
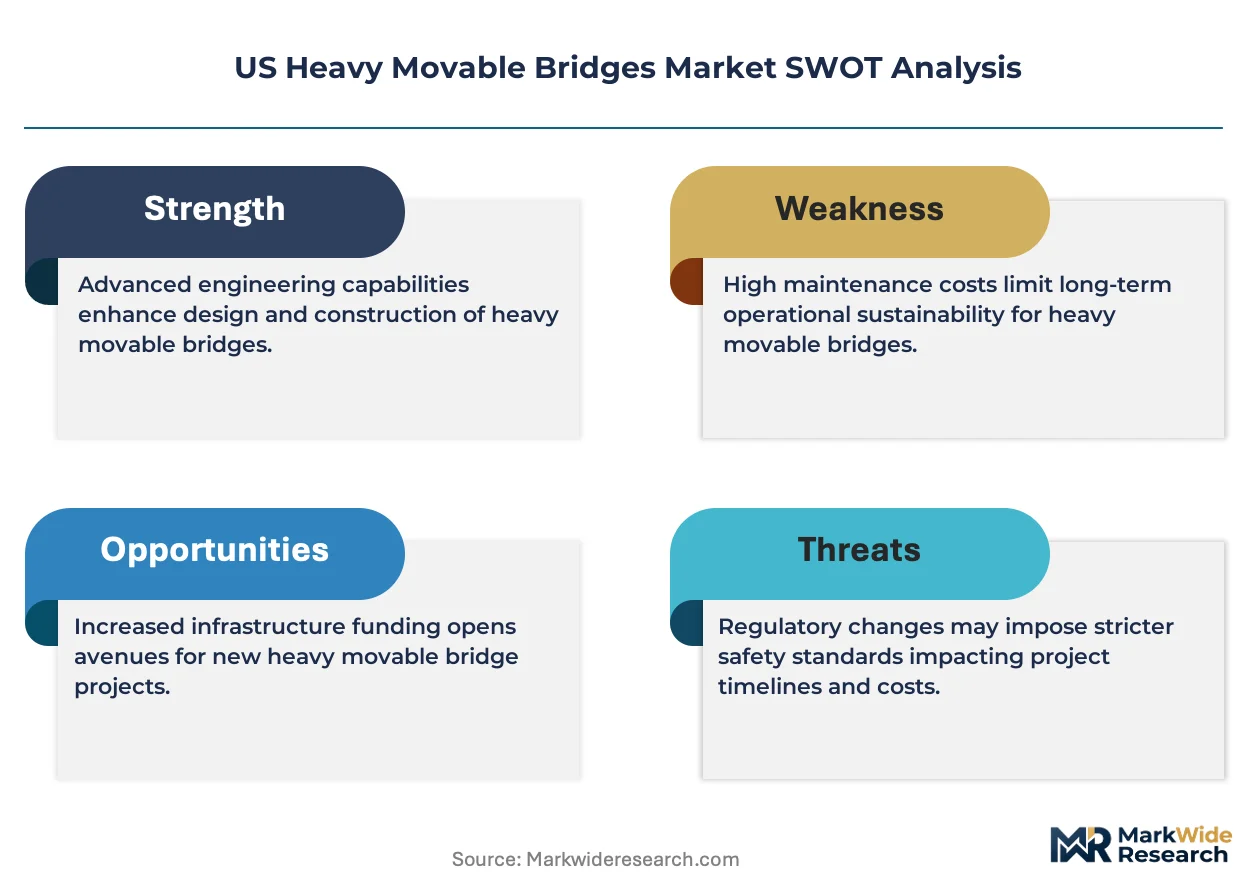
The central dynamic in the US heavy movable bridge market is the capital allocation tension between constructing technologically advanced new structures and funding the extensive, costly maintenance of a vast inventory of aging bridges, a conflict amplified by new federal infrastructure investment programs.
Growth Catalysts
- Federal Infrastructure Spending:Increased funding through federal transportation bills administered by the FHWA is directly accelerating state-led projects to replace or substantially rehabilitate structurally deficient and functionally obsolete movable bridges.
- Coastal Waterway Development:Continued commercial and residential development along inland waterways, particularly in states like Florida and Louisiana, necessitates new movable crossings to support expanded road networks without impeding maritime traffic.
- Superior Design Adoption:Transportation Agencies are increasingly specifying vertical lift designs for new projects, citing their ability to provide greater navigational clearances compared to older bascule or swing bridge types, thus creating demand for specialized engineering.
Market Restraints
- P3 Financing Barriers:The shift toward public-private partnership models for large projects creates a high barrier to entry, favoring large contractors with significant capital access and excluding smaller, specialized engineering and construction firms.
- Dual Regulatory Oversight:Projects face complex, often lengthy approval processes from both the USCG, which governs navigational clearance, and the FHWA, which dictates structural and highway standards, creating potential for delays.
- Specialized Component Costs:The high cost and long lead times for critical components, such as custom-fabricated large bearings, high-capacity hydraulic systems, and electromechanical drive machinery, act as a significant restraint on project budgets and timelines.
Strategic Opportunities
- Digital Twin Services:Engineering firms can develop offerings around digital twins for movable bridges, providing Transportation Agencies with powerful tools for predictive maintenance, operational simulation, and asset life-cycle management.
- Climate Resilience Retrofits:A significant opportunity exists in retrofitting existing bridges in coastal zones to enhance their resilience against sea-level rise and extreme weather events, a growing priority for state DOTs.
- Automated Control Systems:Developing and deploying advanced, remotely operated control and monitoring systems presents an opportunity to improve operational safety, reduce long-term staffing costs, and centralize bridge network management for end-users.
Industry Challenges
- Specialized Talent Scarcity:The industry faces a persistent shortage of engineers and skilled tradespeople with the combined expertise in heavy structural, mechanical, and electrical systems required for movable bridge design, construction, and maintenance.
- Integrating Modern Technology:Retrofitting modern sensor networks, control automation, and communication systems onto aging bridges with decades-old mechanical infrastructure presents significant technical and logistical challenges for contractors and agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Heavy Movable Bridges Market |
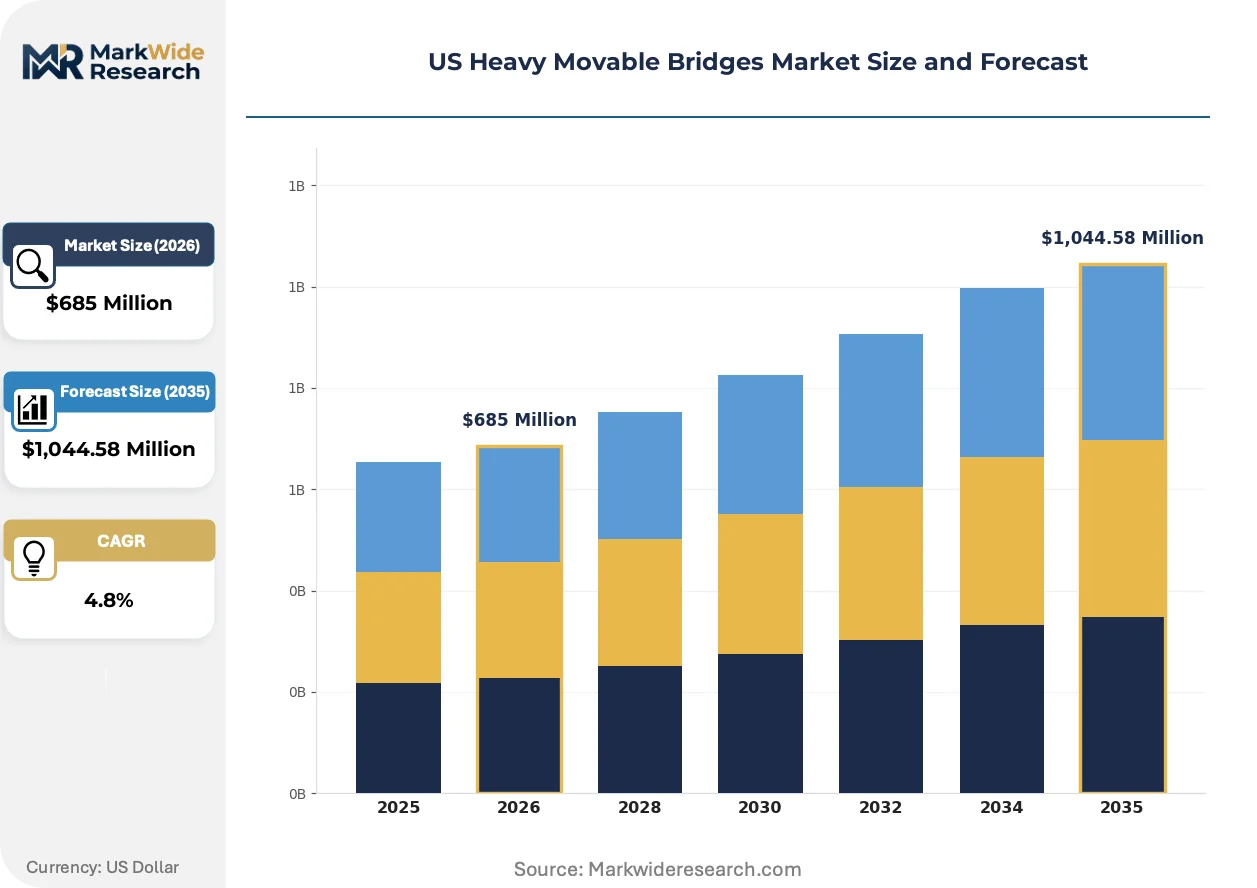
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $1,044.58 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Bridge Type: Drawbridge, Bascule Bridge, Vertical Lift Bridge, Swing Bridge Material Used: Steel, Concrete, Composite, Aluminum End User: Government, Transportation Agencies, Engineering Firms, Contractors Installation Type: New Construction, Maintenance, Retrofit, Replacement |
| Companies Covered | Canadian Pacific, AECOM, BNSF Railway Company, Skanska, Eaton Corporation, Amtrak, Canadian National Railway Company, Acrow, CSX Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Heavy Movable Bridges Market Strategic Shifts & Innovations
The market is being reshaped by a push toward intelligent and resilient infrastructure. This involves integrating digital design and management tools while simultaneously hardening physical assets against new environmental and operational stresses, defining the next generation of movable bridge projects.
Building Information Modeling (BIM) and digital twin technologies are becoming standard for complex movable bridge projects. State transportation authorities and their engineering consultants are adopting these platforms for design coordination and clash detection. This technology is virtualizing the entire project lifecycle, from construction sequencing to long-term operational planning, significantly reducing costly physical rework and improving asset management.
New FHWA guidance on climate resilience is altering design parameters for federally funded bridge projects. This regulatory evolution compels engineers to incorporate projections for sea-level rise and increased storm intensity directly into structural and foundation designs. Projects in vulnerable coastal states like Florida, North Carolina, and Louisiana are most affected, requiring higher vertical clearances and more robust protection for mechanical systems.
A clear shift is occurring from traditional design-bid-build project delivery to alternative models like public-private partnerships (P3) and Construction Manager at Risk (CMAR). This change disrupts the conventional bidding process by bundling design, construction, and long-term maintenance, favoring large contractors with deep financial capacity. The trend is most visible in major bridge replacement programs undertaken by state Departments of Transportation aiming to transfer lifecycle cost risk.
US Heavy Movable Bridges Market Segmentation
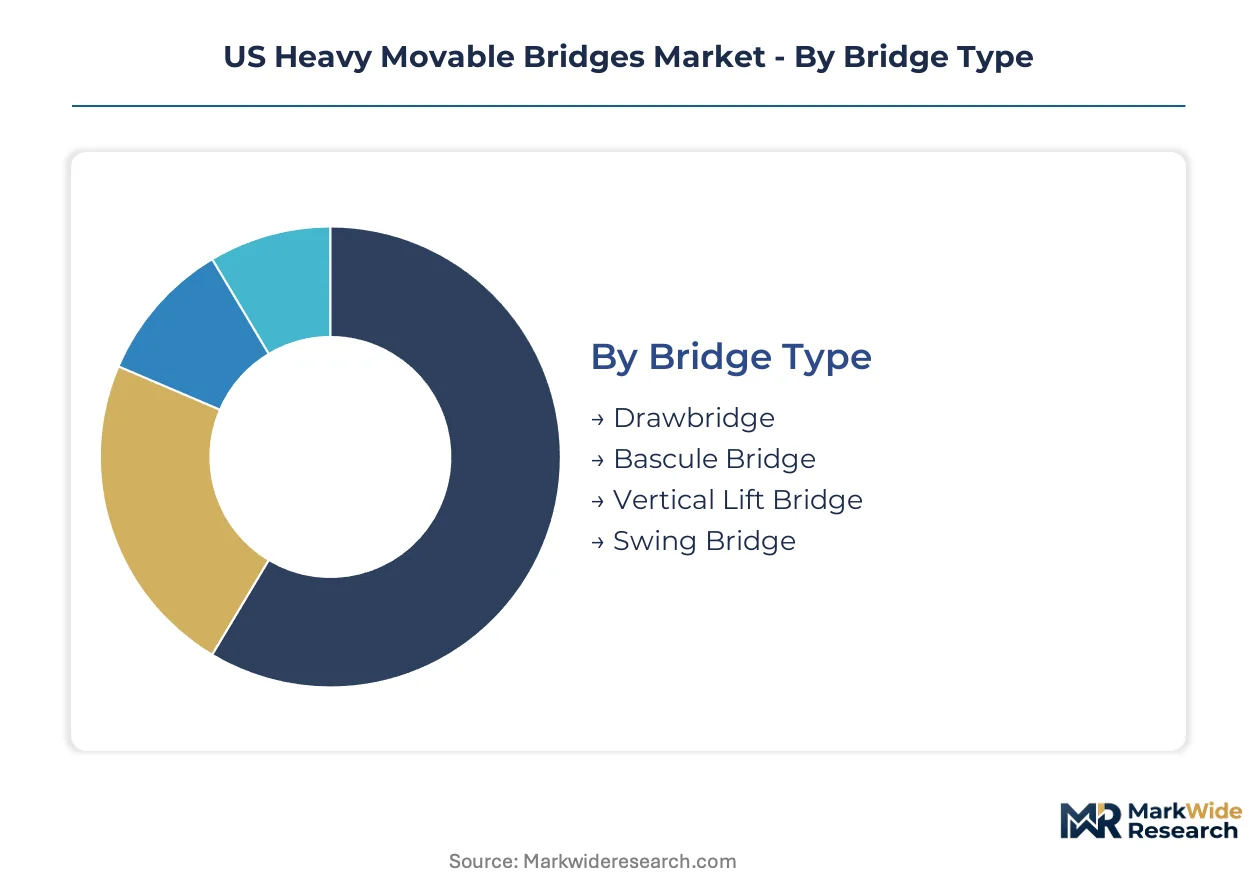
The US heavy movable bridges market is segmented to analyze the diverse technical specifications, operational requirements, and stakeholder priorities driving investment and project execution. Understanding these distinct segments helps identify where capital is deployed, which technologies are gaining traction, and the specific needs of various end-users across the United States.
Bridge Type:
The market for movable bridges exhibits a spectrum of designs, ranging from mature, widely deployed technologies to newer, more specialized solutions.
- Vertical Lift Bridge:This design features a movable span that lifts vertically between two towers, providing maximum vertical and horizontal clearance for maritime traffic. Transportation Agencies increasingly specify these for new construction due to their ability to accommodate larger vessels and future navigation demands.
- Bascule Bridge:A bascule bridge pivots upward around a horizontal axis, allowing one or two sections (leaves) to open. These bridges are prevalent in coastal states like Florida, where extensive inland waterways necessitate frequent, reliable openings for marine vessels.
- Drawbridge:A drawbridge is a general term for any movable bridge, often referring to older designs that can be raised or drawn aside. Many existing drawbridges are candidates for retrofit or replacement projects under federal infrastructure programs.
- Swing Bridge:A swing bridge pivots horizontally on a central pier, rotating to open a channel for watercraft. These designs are less common for new builds but remain critical assets for railway operators like CSX Corporation.
Bascule Bridge retains volume leadership due to its extensive installed base; Vertical Lift Bridge holds the steepest expansion curve for new projects.
Material Used:
Material selection for heavy movable bridges is driven by a balance of structural integrity, durability, and life-cycle cost considerations for US infrastructure projects.
- Steel:Steel is a traditional material, valued for its high strength-to-weight ratio and proven performance in critical load-bearing applications. It remains a primary choice for structural components in both new construction and major rehabilitation projects due to its robustness.
- Concrete:Concrete is widely used for bridge decks, piers, and counterweights, offering excellent compressive strength and durability, particularly in marine environments. Its application is often seen in combination with steel for hybrid structures.
- Composite:Composite materials, such as fiber-reinforced polymers, are emerging for their lightweight properties, corrosion resistance, and reduced maintenance requirements. State DOTs are exploring composites for specific components to extend asset life.
- Aluminum:Aluminum alloys are utilized in specialized applications where weight reduction is paramount, such as pedestrian bridge sections or certain machinery enclosures. Its application is limited by cost and specific structural requirements.
The demand for Steel continues to be sustained by its structural reliability, while Composite is seeing accelerated uptake due to its maintenance advantages.
End User:
The end-user landscape for heavy movable bridges in the US is dominated by public sector entities responsible for critical infrastructure and their direct partners.
- Transportation Agencies:State Departments of Transportation and local transportation authorities are the primary end-users, directing significant federal and state funds towards new construction, replacement, and extensive maintenance. These agencies manage the vast majority of public movable bridge assets.
- Government:This segment encompasses broader federal and local government entities, including the US Coast Guard and the Federal Highway Administration, which establish regulations and provide funding mechanisms. Government bodies set the regulatory framework governing design and operation.
- Engineering Firms:Engineering firms like AECOM are crucial partners, providing specialized design, consulting, and project management services for complex movable bridge projects. They translate agency requirements into detailed plans.
- Contractors:Construction contractors, including large firms like Skanska, are responsible for the physical construction, installation, and rehabilitation of movable bridges. These firms execute the designs and manage project delivery.
While Transportation Agencies represent the primary funding channel, Engineering Firms play a critical role in project execution.
Installation Type:
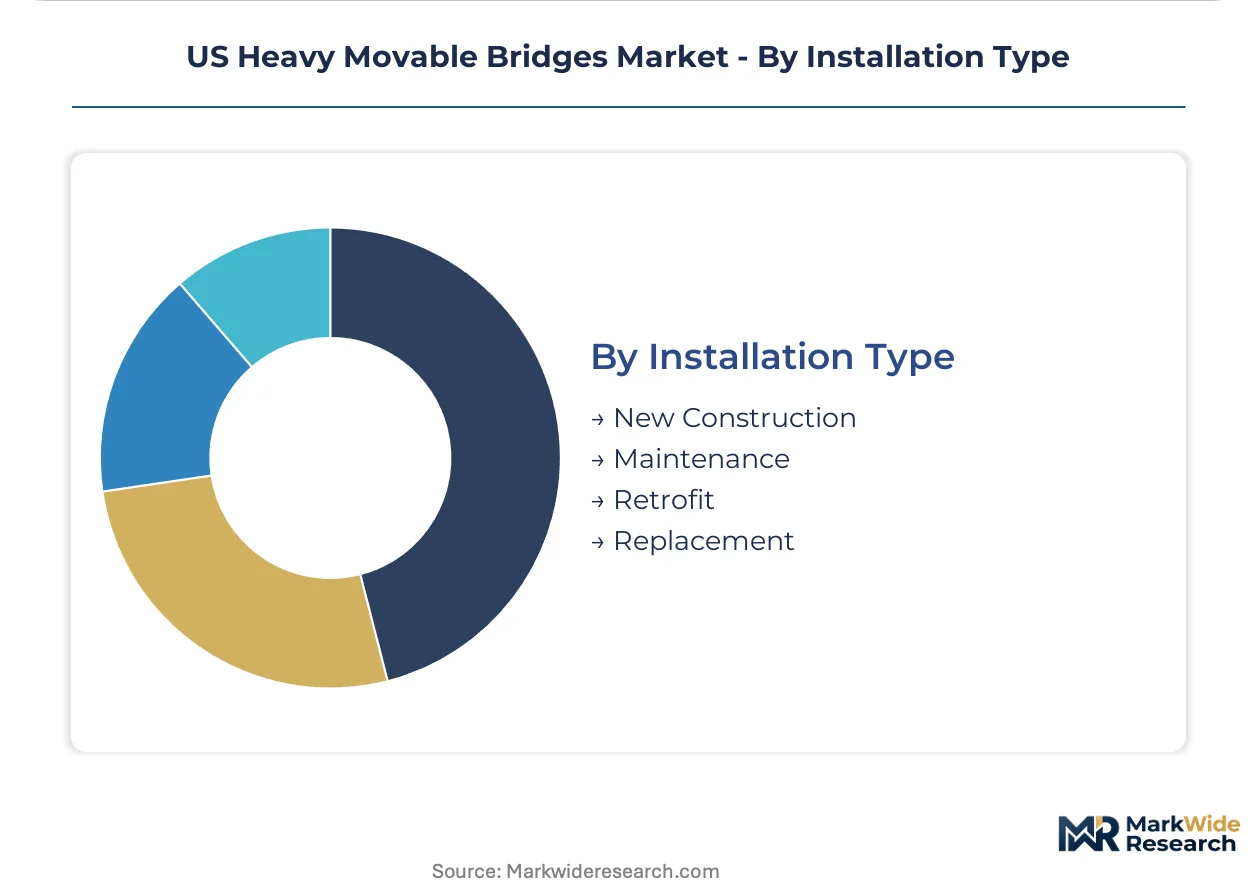
Projects within the US heavy movable bridges market are categorized by their installation type, reflecting different stages of the asset lifecycle and investment priorities.
- New Construction:This segment involves building entirely new movable bridges, often in response to increased traffic demands or the need for greater navigational clearances. Federal infrastructure spending is accelerating new construction projects in coastal development zones.
- Maintenance:Maintenance activities are continuous and extensive, focusing on preserving the operational integrity and extending the lifespan of existing movable bridges. This segment represents a significant portion of annual spending for Transportation Agencies.
- Retrofit:Retrofit projects involve upgrading existing bridges with new components or technologies, such as advanced control systems or enhanced structural elements. Climate resilience initiatives are driving demand for retrofits in vulnerable regions.
- Replacement:Replacement projects entail demolishing an old bridge and constructing a new one in its place, typically for structurally deficient or functionally obsolete assets. Federal funding initiatives are specifically targeting these high-priority projects.
Investment in Maintenance remains foundational, but New Construction projects are gaining strategic importance with new federal programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure investment programs are significantly influencing the US heavy movable bridges market. These programs channel substantial funds to state transportation agencies for critical replacement and retrofit projects. This national commitment ensures sustained demand for specialized bridge solutions across various regions.
Florida
Continued commercial and residential development along Florida's extensive inland waterways drives demand for new movable crossings. USCG regulations heavily influence design and operational requirements for these bridges, particularly concerning navigation clearances. Florida Department of Transportation (FDOT) initiatives in coastal cities like Miami and Fort Lauderdale focus on upgrading existing bascule bridges and constructing new vertical lift designs.
Northeast Corridor
The Northeast Corridor faces significant challenges with an aging inventory of movable bridges supporting vital rail and highway networks. Federal Highway Administration (FHWA) standards guide extensive rehabilitation and replacement projects for these critical assets. Major metropolitan areas such as New York City and Boston are undertaking multi-year programs to modernize functionally obsolete structures.
Pacific Northwest
Commercial shipping and port activities along the Columbia River and Puget Sound necessitate reliable movable bridges in the Pacific Northwest. State DOTs in Washington and Oregon prioritize maintenance and strategic upgrades to ensure maritime and land traffic flow. Projects in urban centers like Seattle and Portland often involve complex engineering to integrate new structures within existing infrastructure.
Gulf Coast
The Gulf Coast region experiences demand driven by the energy sector, commercial shipping, and the need for hurricane resilience in coastal zones. USCG mandates for navigational clearances are paramount for bridges over waterways connecting to the Gulf of Mexico. Cities like Houston and New Orleans are investing in robust designs and advanced control systems to withstand extreme weather events.
US Heavy Movable Bridges Market Key Industry Players
Channel-controlling players compete with product-specialist players in the US heavy movable bridges market. This market exhibits a tiered structure, with large-scale prime contractors operating alongside specialized engineering consultants and critical asset owners. Strategic partnerships and advanced technology integration are dominant competitive moves. Firms leverage expertise in P3 financing to secure complex government projects.
Prime contractors like Skanska exemplify firms with global experience and significant capital access, enabling them to pursue large-scale government contracts for new bridge construction. Engineering firms such as AECOM occupy a distinct position, specializing in design consulting and project management for complex retrofit and maintenance projects. Railway operators like CSX Corporation represent a segment focused on maintaining their own extensive critical movable bridge assets.
| Leading Market Players |
|---|
| Canadian Pacific |
| AECOM |
| BNSF Railway Company |
| Skanska |
| Eaton Corporation |
| Amtrak |
| Canadian National Railway Company |
| Acrow |
| CSX Corporation |
| Others |
Cost & Logistics Intelligence
US coastal manufacturing hubs, specializing in large-scale steel fabrication, influence the pricing power for heavy movable bridge components. Their specialized capacity directly impacts project costs and overall market competitiveness for critical infrastructure.
Pricing Analysis
Specialized engineering complexity creates the primary spread in project pricing for heavy movable bridges. Project-based pricing models dominate, reflecting the custom nature of each installation and unique site requirements. Price differentiation stems from bespoke design elements and integrated long-term maintenance contracts. Pricing pressure trends upwards due to the high cost of custom-fabricated components and talent scarcity.
Supply Chain Analysis
Stringent USCG and FHWA regulatory controls limit the flow of compliant components, influencing the supply chain for heavy movable bridges. Supply concentration for custom steel fabrication and specialized electromechanical systems rests primarily within the United States. Key component dependencies include high-capacity hydraulic cylinders and custom large bearings. A significant supply chain risk involves the long lead times for these specialized, custom-engineered parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as incumbents must navigate the threat of aging infrastructure obsolescence leading to traffic diversion or economic stagnation. Proactive modernization prevents the need for more drastic, costly alternative transportation solutions.
For Market Incumbents: Insulate core market share by investing heavily in digital twin technologies for predictive maintenance and operational optimization. Expand capabilities in public-private partnership (P3) models to secure larger, long-term government contracts. Address the specialized talent scarcity through targeted workforce development programs and strategic university partnerships. Prioritize R&D in advanced materials like composites to reduce lifecycle costs and enhance climate resilience.
For New Entrants and Emerging Players: Coastal state niche markets represent a significant underpenetration for specialized retrofit services. Target smaller state Departments of Transportation seeking cost-effective upgrades for specific bridge components. Focus on developing advanced control systems and remote monitoring solutions that integrate with existing infrastructure. A compelling go-to-market angle involves offering comprehensive climate resilience retrofits for vulnerable coastal assets.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized engineering firms with proprietary advanced control systems or expertise in new materials. Long-term viability is strong, driven by sustained federal infrastructure investment and the critical need to modernize aging assets. Acquisition targets should include companies offering digital twin platforms or climate resilience engineering. A key signal to watch is the increased allocation of federal funds specifically for advanced technology integration in existing bridges.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Development | Provides Transportation Agencies with powerful tools for predictive maintenance and asset life-cycle management. |
| P3 Model Expansion | Secures large-scale government contracts by leveraging capital access and risk management capabilities. |
| Climate Resilience Specialization | Addresses growing demand for retrofits in vulnerable coastal regions against sea-level rise. |
| Workforce Development Programs | Mitigates the persistent scarcity of skilled engineers and tradespeople for complex projects. |
| Advanced Materials R&D | Reduces long-term maintenance costs and extends the operational lifespan of bridge components. |
Research Approach
Desk research of FHWA reports, USCG regulations, and industry association publications preceded structured interviews with Transportation Agency officials, engineering consultants, and prime contractors. This approach combined primary insights with secondary validation to ensure robust data collection. A bottom-up analysis informed market sizing, while top-down triangulation validated overall market trends and segment projections.
The forecast assumed stable federal infrastructure spending and consistent regulatory frameworks across the analysis window. Segmentation dimensions modeled included bridge type, material used, installation type, end-user, and US regional demand. Compound Annual Growth Rates were derived from historical data and projected investment trends. Industry-specific forecast inputs included federal funding commitments and maritime traffic growth projections.
The forecast holds incumbent behavior within observed patterns; aggressive moves by specialized component manufacturers or large prime contractors would shift outcomes. Forecasts reflect documented assumptions regarding technological adoption and regulatory stability. Material shifts in federal infrastructure policy or unforeseen climate events would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Structural Construction
GCC Structural Steel Fabrication Market
Structural Construction
Saudi Arabia Structural Steel Fabrication Market
Structural Construction
Global Rebar Splice Market
Structural Construction
Self-Consolidating Concrete (SCC) Market
Structural Construction
Supported Scaffolding Market
Structural Construction
Prefabricated Steel Bridge Market
Structural Construction
China Structural Steel Fabrication Market
Structural Construction
South Korea Construction Market
Structural Construction
Saudi Arabia Roofing Market
Structural Construction
Vietnam Structural Steel Fabrication Market
Structural Construction
Global Concrete Contractor Market
Structural Construction
Ceiling Expansion Joint Market
Structural Construction
Bridge Construction Market
Structural Construction
Steel Beam Market
Structural Construction
GCC Prefabricated Building and Structural Steel Market
Structural Construction
Canada Composite Repair Market