

Conventional Overhead Conductor Market Size, Share, and Industry Trends Forecast 2026-2036
Conventional Overhead Conductor Market Insights
Skilled lineworker shortages across North America and Western Europe is reorganizing contractor strategies and forcing utilities to bundle conductor procurement with installation services. Prysmian Group leverages integrated cable-to-installation offerings to capture turnkey contracts. Nexans sustains manufacturing scale across multiple continental facilities. Southwire Company anchors domestic supply chains through its extensive U.S. distribution footprint.
Conventional overhead conductors are stranded metallic cables, typically comprising aluminum wires wrapped around a steel core, engineered to carry electrical current across long distances while maintaining mechanical tension under environmental load. Aluminum Conductor Steel Reinforced dominates transmission corridors due to its strength-to-weight ratio and decades of field-proven reliability. All Aluminum Alloy Conductor commands premium positioning in coastal and corrosive environments where reduced sag and extended service life justify higher initial outlay. Distribution Networks represent a mature, replacement-driven segment, whereas Railway Electrification offers concentrated growth as operators double-track routes and upgrade legacy catenary systems.
FERC Order 1920 mandates regional transmission planning in the United States, directly expanding conductor procurement horizons for interstate projects. The EU Green Deal and associated CSRD disclosures pressure European utilities to document supply chain emissions, favoring producers with certified low-carbon aluminum smelting partnerships. India's CEA technical standards for conductor ratings and PLI scheme incentives for domestic manufacturing reshape competitive access across South Asia. Stakeholders must weigh raw material hedging strategies against the accelerating substitution risk posed by composite core alternatives in high-performance applications.
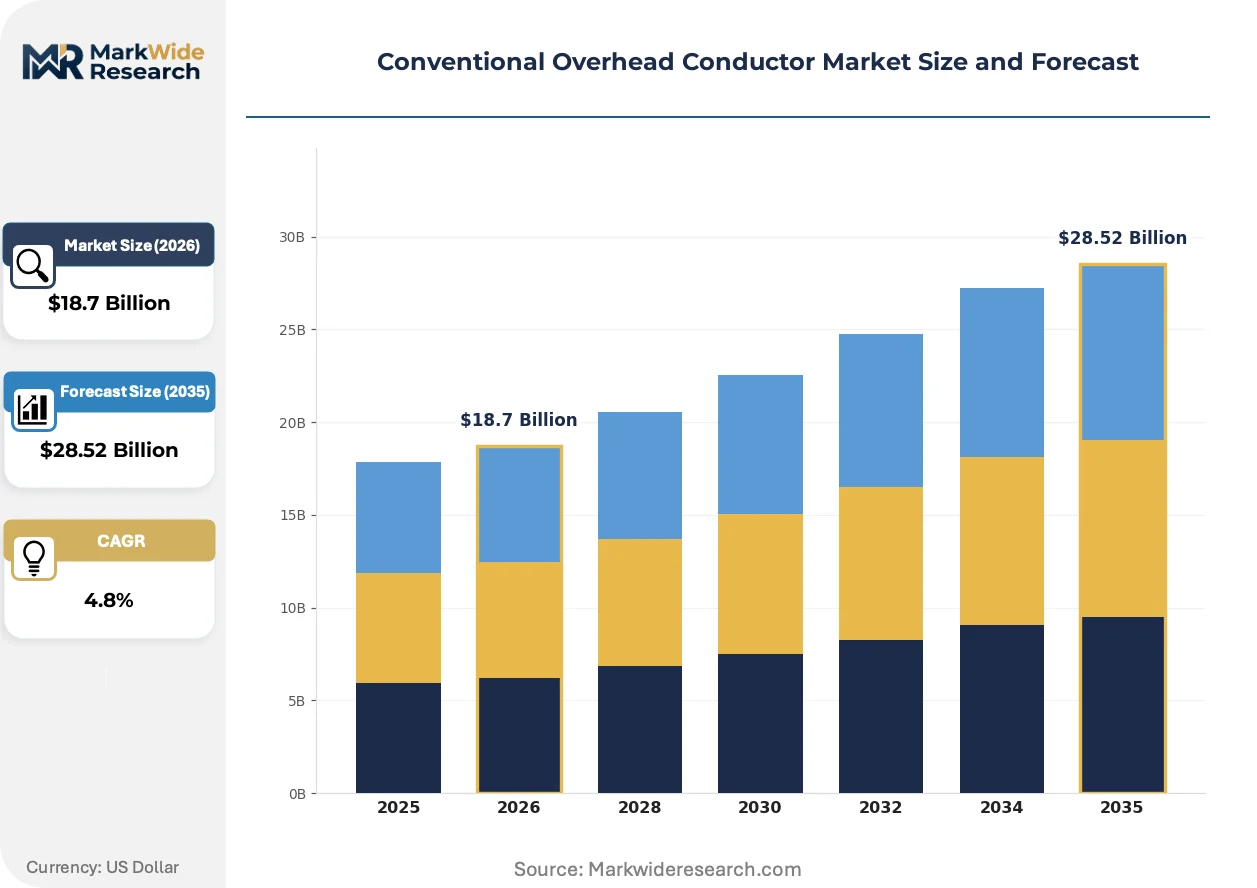
Market Dynamics
Grid interconnection mandates and renewable energy zone development are compressing procurement timelines for high-capacity transmission corridors, forcing utilities to pre-position conductor inventories ahead of formal project authorization.
Growth Catalysts
- FERC Order 1920:Regional transmission planning mandates in the United States expand procurement horizons for interstate conductor projects spanning multiple utility territories.
- Railway Electrification:Operators across India and Western Europe are double-tracking routes and upgrading legacy catenary systems with high-tension overhead networks.
- Aluminum smelting partnerships:Certified low-carbon primary metal sourcing is displacing conventional supply in European utility tenders subject to CSRD disclosure requirements.
Market Restraints
- Steel core price volatility:Galvanized steel wire input costs fluctuate with scrap metal and zinc coating premiums, compressing margin predictability for stranded conductor producers.
- Composite core substitution:Carbon fiber reinforced alternatives are capturing high-performance transmission applications where thermal sag reduction justifies premium outlay.
- Skilled lineworker scarcity:North American and Western European contractor pools cannot scale to match utility installation schedules, elongating project completion windows.
Strategic Opportunities
- India's PLI scheme:Domestic manufacturing incentives for electrical equipment create localized supply advantages for producers establishing South Asian production capacity.
- Turnkey installation bundling:Procurement patterns favor single-source contracts combining conductor supply with erection services, rewarding integrated service capabilities.
- Coastal corrosion environments:All Aluminum Alloy Conductor specifications command premium positioning in maritime zones where extended service life offsets higher initial capital.
Industry Challenges
- Lineworker certification pipelines:Journeyman apprenticeship programs cannot replenish retirement-driven attrition in North American electrical trades.
- Legacy system integration:New conductor specifications must interface with decades-old transmission tower hardware and tensioning equipment without full infrastructure replacement.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conventional Overhead Conductor Market Trends and Innovations
Material science advances and procurement model compression are restructuring how transmission-grade conductors are specified, sourced, and deployed across voltage classes.
High-temperature low-sag designs incorporating annealed aluminum and composite core materials are displacing conventional ACSR in reconductoring projects where existing tower structures constrain physical loading. European transmission system operators are accelerating adoption to avoid right-of-way expansion costs. This displacement is compressing addressable volume for traditional stranded steel-core products in premium transmission segments.
CSRD disclosure requirements under the EU Green Deal are mandating documented supply chain emissions from aluminum smelting through final conductor delivery. European utilities are now screening suppliers against certified low-carbon primary metal partnerships. Distribution network operators in Germany and France are revising tender specifications to preference producers with integrated smelter traceability.
Bundle procurement combining conductor manufacturing with installation and commissioning services is consolidating vendor relationships. Utilities in India and the United States are reducing supplier counts to capture schedule certainty and single-point accountability. This consolidation is most visible in rural electrification programs where project velocity outweighs unit cost optimization.
Conventional Overhead Conductor Market Segmentation
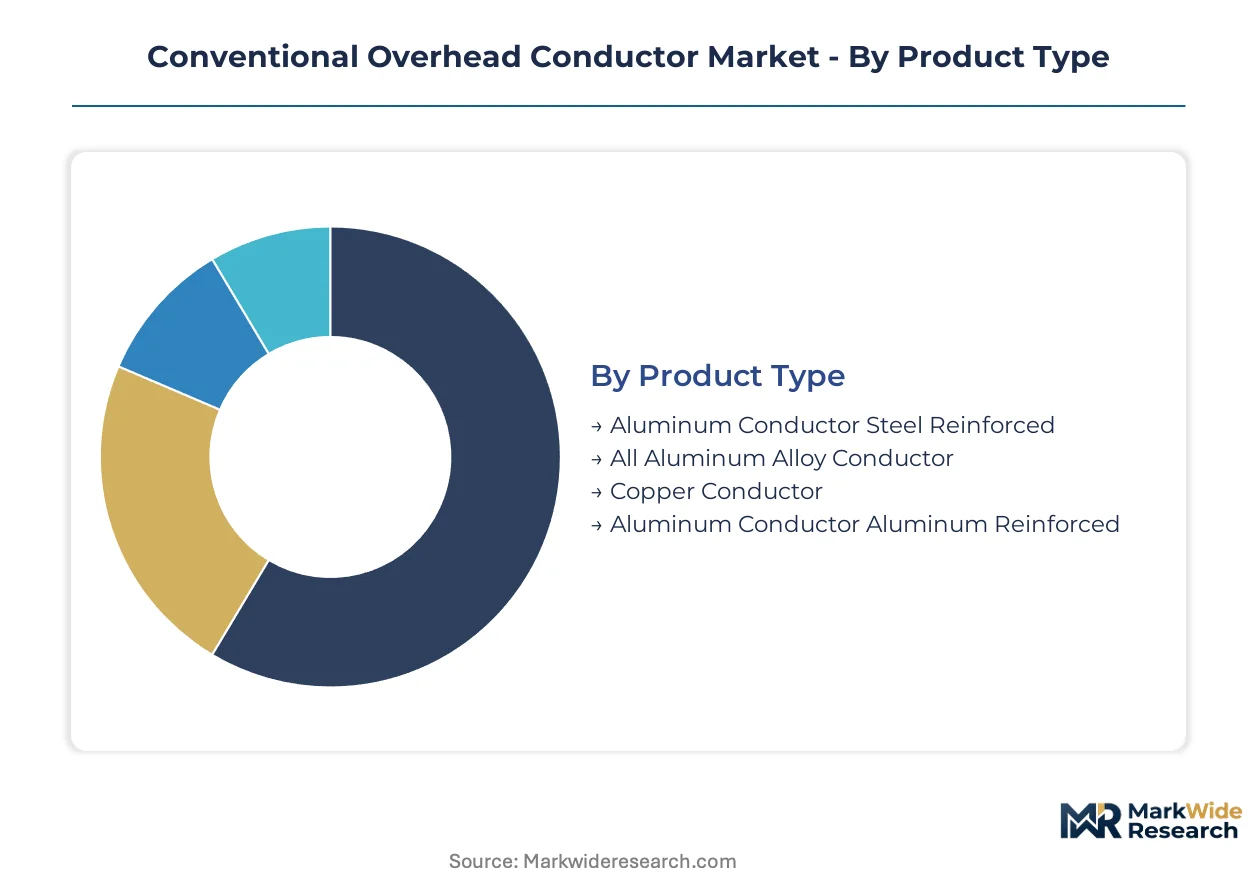
Conductor specification varies sharply across voltage classes and environmental exposure, driving divergent procurement patterns. Regulatory mandates from FERC, the EU Green Deal, and India's CEA reshape how utilities evaluate material composition against lifecycle performance.
Product Type:
FERC Order 1920 and EU CSRD disclosure requirements differentiate procurement based on embodied carbon and thermal performance specifications.
- Aluminum Conductor Steel Reinforced:Stranded aluminum wires helically wrapped around a galvanized steel core deliver optimal strength-to-weight ratios for long-span transmission corridors. Demand concentrates in India's renewable energy zones and U.S. interstate projects where decades of field-proven reliability outweigh premium alternatives. CEA technical standards in India explicitly reference ACSR ratings for high-tension rural electrification networks.
- All Aluminum Alloy Conductor:Heat-treated aluminum-magnesium-silicon alloys eliminate steel cores entirely, reducing sag and corrosion susceptibility in coastal environments. European utilities under CSRD pressure favor AAAC tenders specifying certified low-carbon smelter partnerships for maritime zone installations.
- Copper Conductor:Superior conductivity justifies deployment in compact urban distribution networks where right-of-way constraints dominate.
- Aluminum Conductor Aluminum Reinforced:Aluminum alloy cores replace steel for reduced weight in medium-voltage applications with moderate span requirements.
Established volume favors Aluminum Conductor Steel Reinforced; emerging adoption favors All Aluminum Alloy Conductor.
Application:
Grid interconnection timelines compress procurement cycles differently across voltage tiers and infrastructure ages.
- Electric Power Transmission:High-voltage corridors exceeding 66kV require conductors rated for continuous thermal loading and ice-loading mechanical stress. India's greenfield renewable energy zones and U.S. interstate projects under FERC Order 1920 are expanding procurement horizons for bulk transmission-grade specifications.
- Railway Electrification:25kV AC catenary systems demand high-tension overhead conductors with precise sag tolerance for pantograph contact reliability. Indian Railways and European operators are double-tracking routes and upgrading legacy systems, creating concentrated demand for specialized alloy formulations.
- Telecommunication Lines:Optical ground wire composite conductors integrate fiber cores for utility communication networks.
- Distribution Networks:Mature replacement cycles dominate as North American and European utilities address aging infrastructure.
Replacement economics govern Distribution Networks; Railway Electrification climbs the fastest.
Installation Type:
Right-of-way constraints and aesthetic regulations determine physical deployment configurations across urban-rural divides.
- Overhead Lines:Traditional lattice tower or pole-mounted conductors remain dominant for high-capacity corridors where visual impact restrictions are minimal. Rural electrification programs in India and transmission buildouts across the United States rely on conventional overhead construction for cost efficiency at scale.
- Aerial Bundled Cables:Insulated phase conductors twisted into compact bundles reduce fault rates and tree-contact outages in forested or urban fringe zones. European distribution operators and Indian urban utilities specify ABC for reliability-critical feeders.
- Guy Wires:Tensioned support cables stabilize transmission structures against wind and ice loading in exposed terrain.
- Distribution Footpaths:Underground-adjacent routing through dedicated utility corridors serves dense municipal environments.
Cost efficiency sustains Overhead Lines; reliability premiums expand Aerial Bundled Cables.
End User:
Procurement sophistication varies with scale, regulatory exposure, and in-house technical capacity.
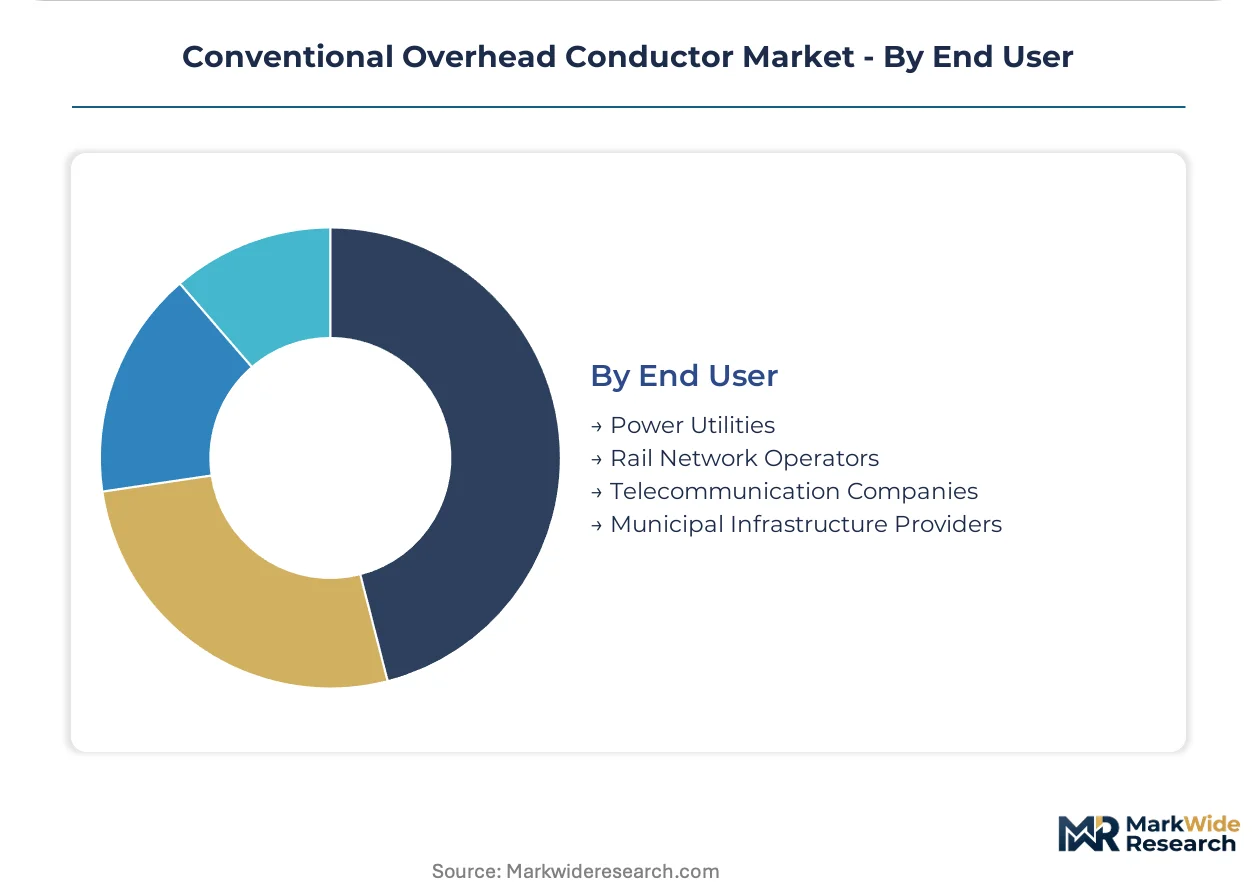
- Power Utilities:Vertically integrated transmission and distribution operators specify conductors against decades-long asset lifecycle models. State-owned utilities in India and investor-owned utilities in the United States are bundling procurement with installation services to mitigate lineworker scarcity.
- Rail Network Operators:Electrification agencies operate dedicated procurement functions for catenary system upgrades with stringent mechanical tolerance requirements. Indian Railways and European national operators are consolidating supplier relationships for double-tracking projects.
- Telecommunication Companies:Fiber-integrated optical ground wire purchases align with utility co-location agreements.
- Municipal Infrastructure Providers:City-scale distribution operators prioritize localized supplier relationships and rapid response logistics.
Scale concentration favors Power Utilities; project velocity elevates Rail Network Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India consumes conventional overhead conductors for rural electrification and renewable interconnection at scales unmatched elsewhere, while European utilities prioritize low-carbon sourcing certifications and U.S. procurement accelerates under federal transmission mandates.
United States
FERC Order 1920 mandates regional transmission planning across interstate corridors, expanding procurement horizons for high-capacity conductor projects. Investor-owned utilities bundle conductor procurement with installation services to mitigate skilled lineworker scarcity. Texas and California anchor domestic demand through renewable energy zone buildouts and wildfire-hardening infrastructure programs.
India
Central Electricity Authority technical standards govern conductor ratings for high-tension rural electrification networks spanning renewable energy zones. The Production Linked Incentive scheme incentivizes domestic manufacturing capacity for electrical equipment. Gujarat and Maharashtra concentrate greenfield transmission infrastructure serving solar and wind generation clusters.
Germany
Corporate Sustainability Reporting Directive disclosures pressure utilities to document supply chain emissions from aluminum smelting through final delivery. Distribution network operators revise tender specifications to preference producers with integrated smelter traceability. The Ruhr industrial region and Bavaria host transmission system operators accelerating high-temperature low-sag conductor adoption.
China
National dual carbon goals reshape procurement criteria for grid infrastructure materials across ultra-high voltage transmission corridors. State Grid Corporation specifications increasingly weight embodied carbon metrics in conductor sourcing decisions. The Yangtze River Delta concentrates manufacturing capacity serving both domestic buildouts and export markets.
Brazil
National grid operator ONS specifications govern conductor mechanical ratings for Amazon basin transmission extensions and southeastern industrial corridor reinforcement. BNDES financing conditions increasingly incorporate environmental compliance criteria for transmission infrastructure. São Paulo state anchors demand through urban distribution network modernization and industrial load growth.
Conventional Overhead Conductor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in conventional overhead conductor supply. The upper tier combines manufacturing scale with installation service capabilities to capture turnkey contracts from utilities facing workforce constraints. Mid-tier specialists compete on alloy formulation expertise and regional logistics proximity. Dominant competitive moves include backward integration into aluminum smelting partnerships and geographic expansion through licensed production arrangements.
Within the integrated service tier, Prysmian Group and Nexans exemplify manufacturers bundling conductor supply with erection capabilities to capture single-source accountability contracts. Southwire Company anchors domestic U.S. supply chains through extensive distribution infrastructure. These three occupy positions spanning premium transmission-grade specifications through standard distribution network products.
| Leading Market Players |
|---|
| Prysmian Group |
| Nexans |
| Southwire Company |
| Sumitomo Electric Industries |
| APAR Industries |
| CTC Global |
| Bekaert |
| LS Cable & System |
| Elsewedy Electric |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Chinese aluminum smelters and Indian conductor extrusion plants shapes global price floors by determining when marginal capacity enters the market. FERC Order 1920 project bundling in the United States and EU CSRD disclosure requirements in Europe compress procurement timelines, forcing utilities to accept price premiums for guaranteed delivery slots.
Pricing Analysis
Long-term offtake contracts dominate utility procurement for interstate transmission corridors, insulating buyers from spot aluminum volatility while locking in steel core pricing quarterly. Premium-mid-economy pricing differentiation rests on thermal performance ratings and certified low-carbon smelter partnerships. Cost compression in standard ACSR grades is intensifying because Chinese export capacity is flooding distribution network tenders. Distribution network operators exhibit highest price sensitivity, whereas railway electrification agencies accept premium alloy formulations for sag tolerance.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes and port congestion at Indian west coast terminals elevate inbound logistics costs for European and North American buyers. Primary aluminum draws from China, India, and Russia; galvanized steel wire feeds from Chinese and Turkish mills. Single-source vulnerability concentrates in composite core precursor materials. Distribution runs through utility-approved vendor lists and EPC contractor procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
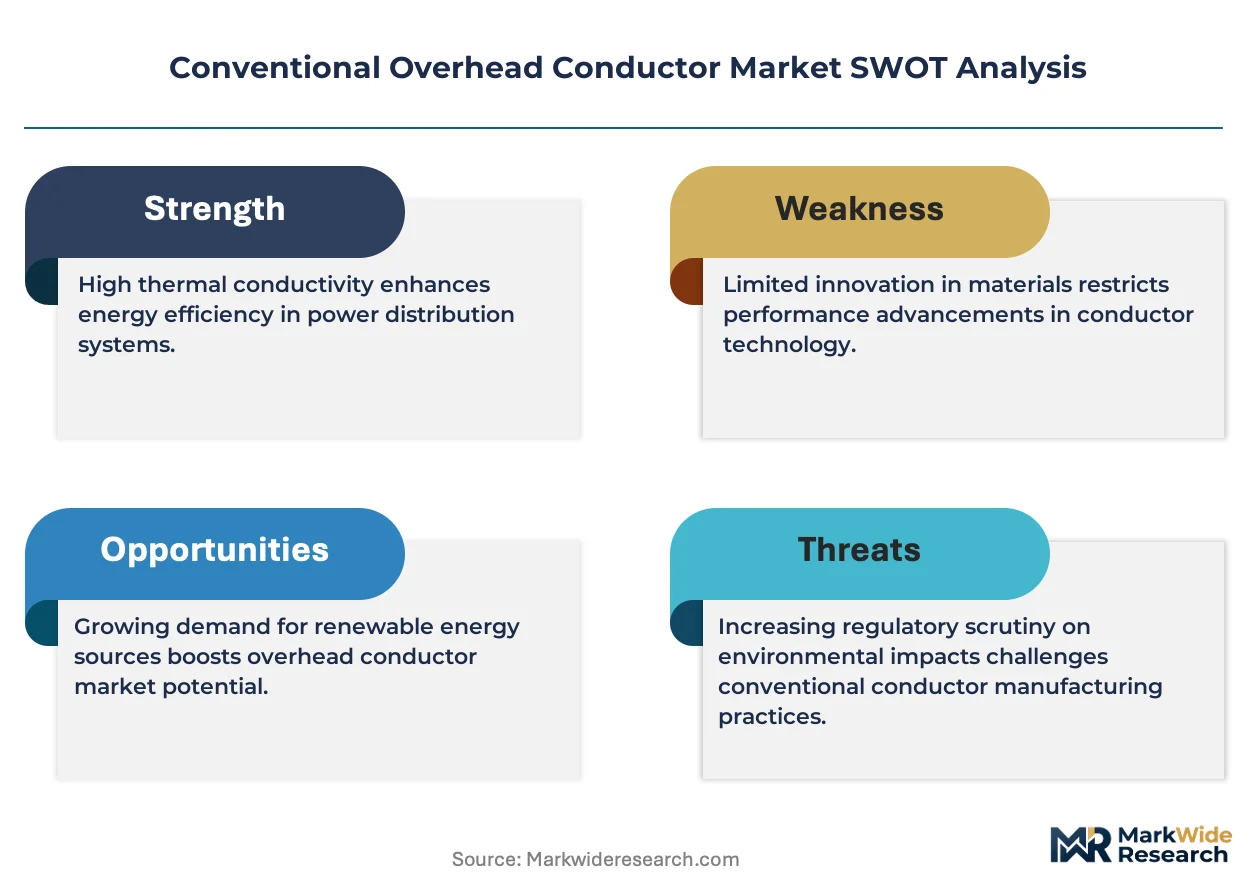
Fragmentation opportunity exists as skilled lineworker scarcity and turnkey bundling demands create service-integrated niches alongside pure manufacturing players. Renewable interconnection mandates are splintering procurement into high-performance transmission and cost-optimized distribution streams.
For Market Incumbents: Compound manufacturing scale with installation service capabilities to capture bundled contracts from utilities facing workforce constraints. Prysmian Group's integrated cable-to-installation model demonstrates defensible positioning against pure-play manufacturers. Backward integration into certified low-carbon aluminum smelting partnerships secures preferential access to European tenders under CSRD disclosure rules. For New Entrants and Emerging Players: Differentiate on coastal corrosion specialization through All Aluminum Alloy Conductor formulations for maritime zone utilities. India's PLI scheme incentives offer the most penetrable entry path for establishing South Asian production capacity. Target state-owned distribution utilities with rapid-response logistics capabilities that incumbent multinationals cannot match. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-integrated manufacturers with multi-year maintenance contracts on installed conductor networks. Long-term viability favors producers with captive smelter partnerships and regional installation workforces. Watch for FERC Order 1920 project authorization velocity as the signal indicating transmission-grade demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Smelting | Secures certified low-carbon metal supply for EU CSRD-compliant tenders from German and French utilities. |
| Turnkey Installation Service Expansion | Captures bundled procurement contracts from Indian and U.S. utilities mitigating skilled lineworker scarcity. |
| High-Temperature Low-Sag Product Line Development | Displaces conventional ACSR in European reconductoring projects avoiding right-of-way expansion costs. |
| Licensed Production Arrangements in India | Accesses PLI scheme incentives while serving Gujarat and Maharashtra renewable energy zone buildouts. |
| Coastal Corrosion Alloy Specialization | Commands premium positioning in maritime environments where extended service life offsets higher capital outlay. |
Research Methodology
Initial hypotheses were tested against primary input from utility procurement directors, EPC contractor project managers, aluminum smelter commercial leads, and railway electrification engineers and refined through secondary validation. Utility planning databases, FERC interconnection queue filings, Indian CEA technical standards, EU transmission system operator tender documents, and customs trade data provided triangulation anchors. Bottom-up volume estimates from conductor tonnage by voltage class were reconciled with top-down transmission infrastructure investment flows.
Variance decomposition across product type, application voltage tier, installation configuration, and end-user procurement sophistication informed the analytical framework. CAGRs were derived from segment-level volume trajectories mapped against regulatory project pipelines. Forecast inputs incorporated FERC Order 1920 regional transmission planning timelines, Indian renewable energy zone interconnection schedules, and EU Green Deal grid modernization commitments.
Material uncertainties — aluminum price volatility, composite core substitution velocity, lineworker training pipeline recovery — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory project authorization cadence and smelter capacity expansion schedules. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.