
 Industrial Counterweights Market | 2026-2036
Industrial Counterweights Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Counterweights Market Foresight
REACH compliance is broadening the cost-of-entry calculus for European foundries supplying counterweight castings. Caterpillar Inc. leverages its captive steelmaking capacity to insulate margin structures from volatile scrap prices. Komatsu Ltd. anchors its counterweight procurement through long-term agreements with Japanese specialty foundries. Sany Heavy Industry Co., Ltd. competes on scale by operating integrated casting facilities serving its domestic crane assembly lines.
Industrial counterweights are mass elements engineered from cast iron, steel, concrete, or lead alloys, typically ranging from one ton to above twenty tons, designed to offset overturning moments in mobile and fixed lifting equipment. Their primary function ensures structural stability during load handling, preventing tip-over incidents in cranes, forklifts, and elevator systems. Cast iron dominates product type volumes due to its density-to-cost ratio and machinability in complex geometries, though steel variants are capturing share in applications demanding higher tensile integrity. The above twenty tons weight capacity segment leads absolute value contribution, driven by harbor cranes and heavy-lift crawler installations, while the six to ten tons bracket grows fastest from telehandler and industrial forklift expansion.
The EPA regulates foundry air emissions under MACT standards, while OSHA mandates crane load testing protocols that directly specify counterweight integrity verification. The EU F-Gas Regulation indirectly shapes material choices by restricting processes tied to certain smelting inputs, nudging producers toward lower-carbon steel grades. Stakeholders must monitor how emerging carbon border adjustment mechanisms reshape sourcing economics between domestic foundries and import-dependent fabricators.
Market Dynamics
Foundry emissions compliance under the EU Green Deal is compressing production economics for cast iron counterweights, forcing capacity consolidation toward electric arc furnace operators with integrated scrap recycling capabilities.
Growth Catalysts
- Harbor crane modernization:Port authorities in Hamburg and Rotterdam are replacing aging heavy-lift fleets, driving demand for above-twenty-ton cast iron units with precision-machined mounting interfaces.
- REACH substance restrictions:ECHA's tightening limits on heavy metal content in industrial castings is accelerating certified clean-feedstock sourcing from Nordic electric arc furnace mills.
- Telehandler fleet expansion:Agricultural mechanization in Poland and Romania is pulling six-to-ten-ton steel counterweight volumes for telescopic handler OEM assembly lines.
Market Restraints
- Scrap price volatility:Electric arc furnace operators face margin compression when shredded auto scrap spikes, squeezing foundries without backward integration into raw steel production.
- German foundry concentration:Three-quarters of EU heavy-lift counterweight casting capacity clusters in Baden-Württemberg and Bavaria, creating single-point-of-failure exposure for pan-European crane builders.
- Concrete composite substitution:Polymer-matrix concrete formulations with steel fiber reinforcement are capturing share in static elevator applications below five tons where density precision matters less.
Strategic Opportunities
- Eastern European manufacturing migration:Czech and Slovak foundries with EU structural fund modernization grants offer lower-cost casting capacity for mid-weight forklift counterweights.
- Carbon border adjustment readiness:Early certification against the EU CBAM framework creates preferential positioning for exports into German crane assembly plants facing Scope 3 disclosure mandates.
- Digital twin integration:Convergence of finite element analysis software with additive-manufactured sand cores enables rapid prototyping of complex-geometry counterweights for custom crawler crane configurations.
Industry Challenges
- MACT compliance engineering:EPA-mandated baghouse upgrades and emissions monitoring systems require seven-figure capital deployment at US gray iron foundries serving domestic crane builders.
- Metallurgical technician scarcity:Electric arc furnace process control and spectrographic chemistry verification skills are retiring faster than vocational programs in Poland and Italy can replenish them.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Counterweights Market |
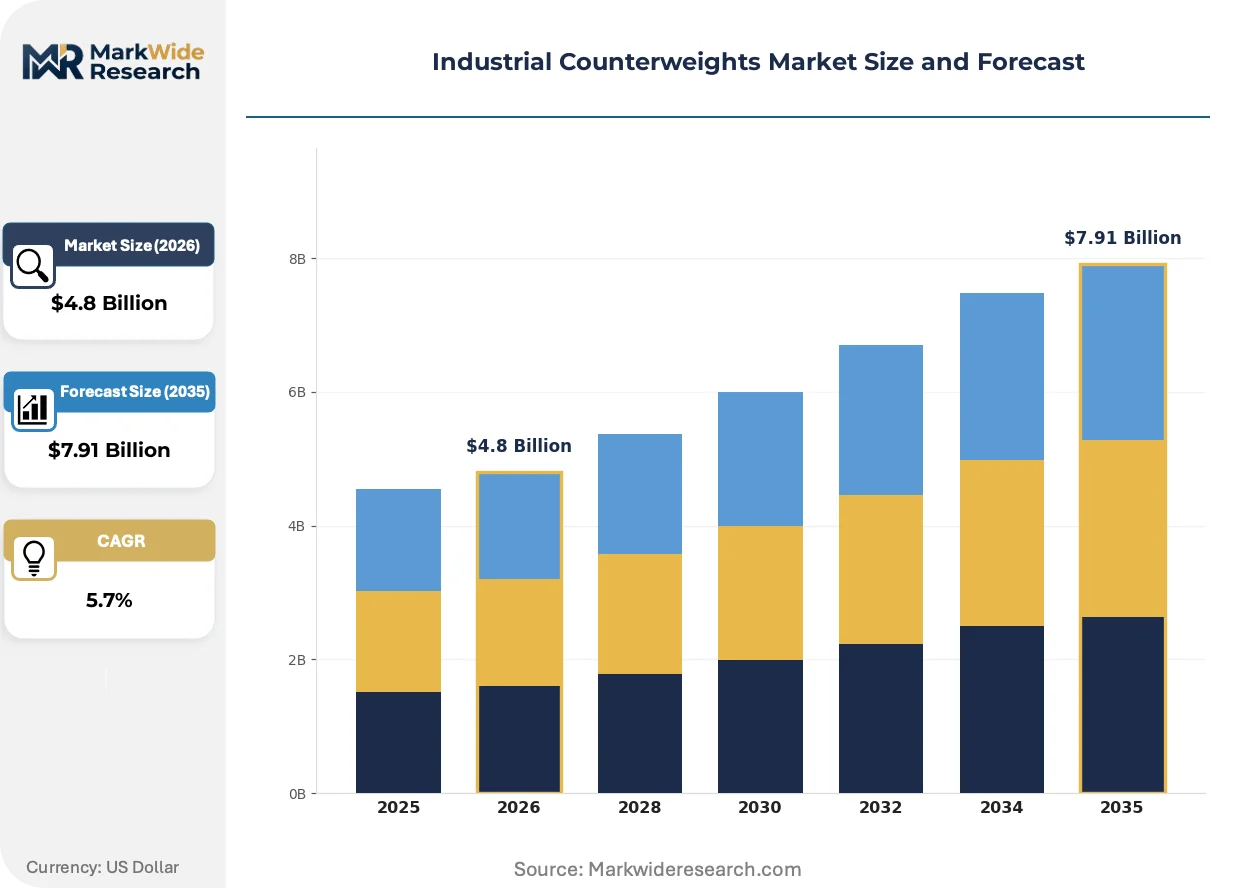
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cast Iron, Steel, Concrete, Lead Application: Cranes, Forklifts, Elevators, Machinery End User: Construction, Manufacturing, Logistics, Transportation Weight Capacity: 1-5 Tons, 6-10 Tons, 11-20 Tons, Above 20 Tons |
| Companies Covered | Liebherr-International Deutschland GmbH, Tadano Ltd., Caterpillar Inc., Crescent Foundry, Konecranes Plc, Terex Corporation, Sany Heavy Industry Co., Ltd., Blackwood Engineering, Komatsu Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Counterweights Market Shifts & Advancements
Material substitution pressures and digital manufacturing integration are compressing traditional casting lead times while fragmenting supplier tiers between commodity foundries and precision-machining specialists.
High-density compacted graphite iron is consolidating its position in mobile crane counterweight applications where tensile strength requirements exceed standard gray iron capabilities. OEMs in Finland and Sweden are specifying this material for harbor crane retrofits requiring twenty-year service life guarantees. The shift is consolidating procurement volumes toward Scandinavian mills with in-house nodularization process control.
The EU F-Gas Regulation's phase-down of fluorinated greenhouse gases used in certain smelting fluxes is redirecting foundry chemistry toward boron-based alternatives with lower warming potential. German casting houses serving Liebherr and Konecranes are reformulating melt recipes to maintain fluidity without restricted additives. This regulatory compression is most acute in the above-fifteen-ton segment where melt volumes amplify flux consumption.
Buyers are unbundling casting supply from finished machining, creating two-tier procurement where foundries compete on melt cost and specialized machine shops capture margin on precision boring and surface treatment. This pattern is visible in the German crane cluster, where Konecranes now sources rough castings from Polish foundries while retaining finish work at its own facilities. The disintermediation is compressing traditional full-service foundry margins while rewarding logistics-coordinated multi-supplier arrangements.
Industrial Counterweights Market Segmentation
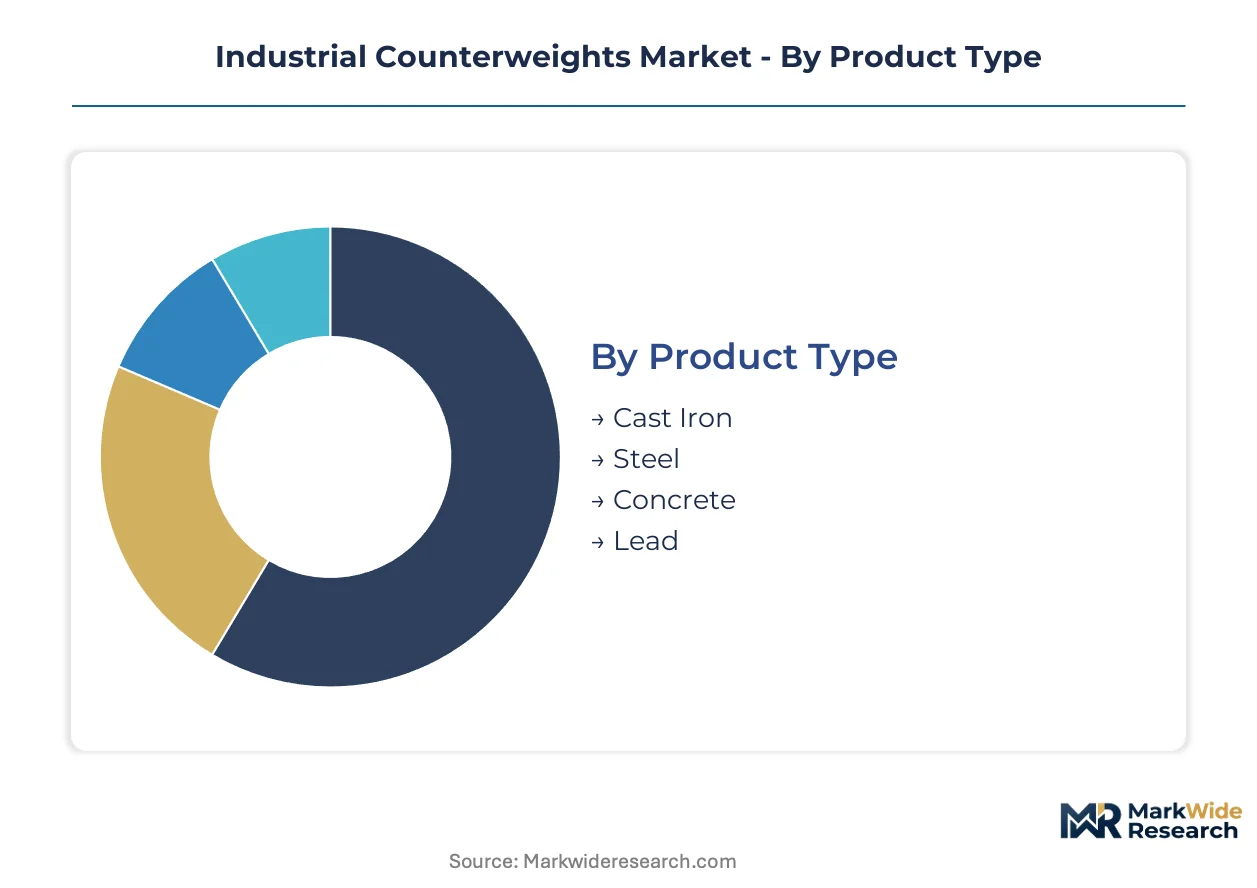
Counterweight procurement splits sharply between commodity foundry outputs and precision-engineered units demanding metallurgical certification. Segmentation clarity enables buyers to match density specifications, regulatory compliance tiers, and lifecycle cost structures to specific lifting equipment categories.
Product Type:
Volume production concentrates in gray iron grades, while premium positioning shifts toward engineered alloys with traceability documentation.
- Cast Iron:Gray iron dominates unit volumes through its density-to-cost ratio and machinability in complex geometries. Harbor crane OEMs in Hamburg and Rotterdam specify this material for above-twenty-ton units requiring precision-machined mounting interfaces.
- Steel:Higher tensile integrity drives specification in telehandler and crawler crane applications where dynamic loading exceeds cast iron fatigue limits. Polish and Romanian agricultural mechanization is pulling six-to-ten-ton steel volumes for telescopic handler assembly lines.
- Concrete:Polymer-matrix formulations with steel fiber reinforcement serve static elevator applications below five tons where density precision matters less than installation cost.
- Lead:Specialized radiation shielding and compact marine applications exploit lead's extreme density, though REACH substance restrictions compress addressable demand.
Mature deployment sits with Cast Iron. Newer deployment is concentrated in Steel.
Application:
Mobile equipment demands dynamic-load-rated materials, while fixed installations prioritize static stability and corrosion resistance.
- Cranes:Mobile harbor units and heavy-lift crawlers require above-twenty-ton cast iron or compacted graphite iron with twenty-year service guarantees. Finnish and Swedish OEMs are consolidating procurement toward Scandinavian mills with in-house nodularization control.
- Forklifts:Counterbalance trucks and telehandlers span six-to-ten-ton steel specifications, with Czech and Slovak foundries capturing mid-weight casting volumes through EU structural fund modernization.
- Elevators:Static traction systems below five tons increasingly substitute concrete composites for traditional cast iron where density tolerance permits.
- Machinery:General industrial equipment spans all material grades depending on overturning moment calculations and foundation constraints.
Crane applications command premium metallurgical certification. Forklift volumes are expanding most quickly through Eastern European manufacturing migration.
End User:
Construction sector procurement emphasizes load-testing documentation, while logistics operators prioritize total cost of ownership across fleet replacement cycles.
- Construction:Crane fleet modernization in German port authorities drives demand for certified clean-feedstock castings with ECHA-compliant heavy metal limits.
- Manufacturing:Heavy machinery OEMs source through long-term agreements with Japanese specialty foundries or captive steelmaking operations insulating margin structures from scrap volatility.
- Logistics:Warehouse automation and distribution center expansion pull standard-weight forklift counterweights through logistics-coordinated multi-supplier arrangements.
- Transportation:Rail maintenance and intermodal handling equipment represent specialized demand for corrosion-resistant specifications in coastal environments.
Construction leads absolute value contribution. Logistics represents the steepest expansion trajectory through fleet standardization.
Weight Capacity:
Foundry economics favor scale in melt volumes, fragmenting supplier tiers between commodity bulk casters and precision finish-machining specialists.
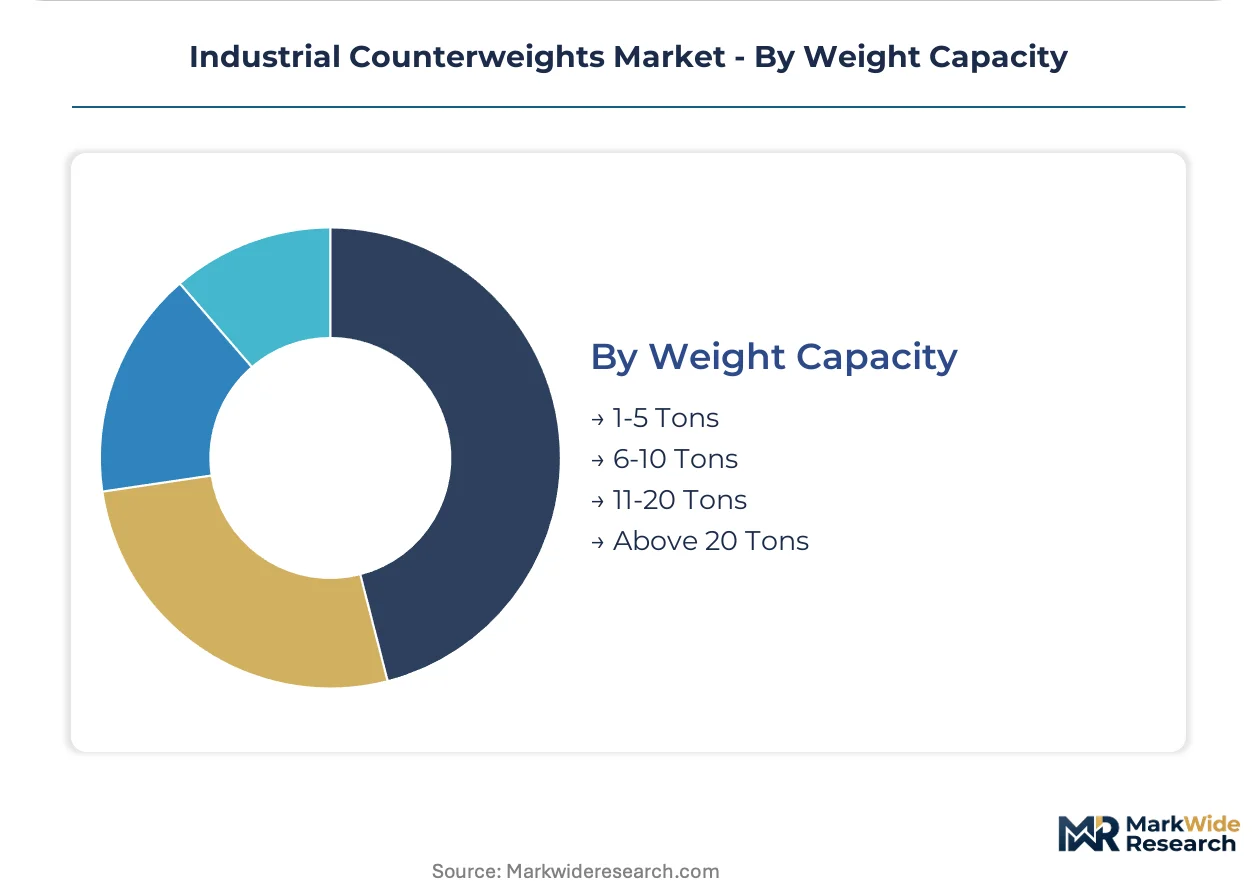
- 1-5 Tons:Elevator and light forklift applications where concrete substitution pressures are most acute. REACH compliance broadens cost-of-entry for lead alloy alternatives.
- 6-10 Tons:Telehandler and industrial forklift expansion in Polish and Romanian agricultural mechanization drives fastest volume growth. Polish foundries serve German crane builders with rough castings for finish machining at Konecranes facilities.
- 11-20 Tons:Mid-capacity mobile cranes requiring certified clean-feedstock sourcing from Nordic electric arc furnace mills with integrated scrap recycling.
- Above 20 Tons:Harbor crane retrofits and heavy-lift crawler installations lead absolute value contribution. EU F-Gas Regulation phase-down redirects foundry chemistry toward boron-based flux alternatives in this high-volume melt segment.
Above 20 Tons commands premium pricing through metallurgical complexity. 6-10 Tons is gaining share fastest through Eastern European capacity expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's Baden-Württemberg and Bavaria regions concentrate foundry capacity serving heavy-lift equipment manufacturers. Tax incentives under the EU Green Deal accelerate electric arc furnace adoption at these sites. Production clusters here supply precision-machined castings for harbor crane retrofits across Northern Europe.
United States
Port modernization programs in Houston and Long Beach drive demand for above-twenty-ton steel counterweights. EPA MACT standards mandate baghouse upgrades at gray iron foundries in Pennsylvania and Ohio. Pittsburgh-area casting houses now serve domestic crawler crane builders with certified clean-feedstock units.
China
Sany Heavy Industry's integrated casting facilities in Changsha anchor domestic supply for telehandler and mobile crane assembly. MIIT emission standards push foundries toward scrap-based electric arc furnace routes. Yangtze River Delta clusters in Jiangsu province export rough castings to German finish-machining specialists.
Japan
Komatsu Ltd.'s long-term agreements with specialty foundries in Osaka and Nagoya secure steel counterweight volumes for construction equipment. METI industrial decarbonization roadmaps favor low-carbon steel grades in heavy machinery components. Chubu region mills maintain nodularization process control for compacted graphite iron specifications.
India
Crescent Foundry operates casting capacity in West Bengal serving forklift OEMs and elevator manufacturers. BIS quality certification requirements broaden cost-of-entry for foundries supplying infrastructure projects. Gujarat-based foundries capture export volumes to Middle Eastern construction equipment distributors.
Finland
Scandinavian mills with in-house nodularization control supply compacted graphite iron for harbor crane retrofits requiring twenty-year service guarantees. EU F-Gas Regulation phase-down redirects foundry chemistry toward boron-based flux alternatives. Tampere-area engineering clusters integrate finite element analysis with casting prototyping for custom crawler configurations.
Industrial Counterweights Market Competitive Landscape
German producers anchor one tier; Chinese specialists hold scale-driven positions in integrated manufacturing. The vendor base splits between captive foundry operations at equipment OEMs and independent casting houses serving multiple crane builders. Three archetypes dominate: vertically integrated machinery manufacturers, precision-machining specialists unbundled from raw casting, and commodity foundries competing on melt cost. Competitive moves concentrate on backward integration into scrap recycling and geographic expansion through Polish and Czech capacity partnerships.
Among Germany-based fabricators, Liebherr-International Deutschland GmbH and Konecranes Plc exemplify the captive-foundry archetype, retaining rough casting supply from Eastern European partners while controlling finish machining in-house. Sany Heavy Industry Co., Ltd. occupies a position representing integrated scale, with Changsha-based casting facilities feeding domestic crane assembly lines. These three companies illustrate how procurement patterns fragment between logistics-coordinated multi-supplier arrangements and fully integrated production systems.
| Leading Market Players |
|---|
| Liebherr-International Deutschland GmbH |
| Tadano Ltd. |
| Caterpillar Inc. |
| Crescent Foundry |
| Konecranes Plc |
| Terex Corporation |
| Sany Heavy Industry Co., Ltd. |
| Blackwood Engineering |
| Komatsu Ltd. |
| Others |
Supply & Pricing Matrix
EU Green Deal emissions mandates gate both qualified supply and premium-tier pricing access for counterweight castings, concentrating certified production at electric arc furnace mills with integrated scrap recycling while compressing margins at legacy foundries lacking backward integration into clean-feedstock steelmaking.
Pricing Analysis
Lead-time-driven pricing stratification rewards rapid fulfillment with premium positioning while spot inventory commands discounts. Three-tier pricing structure across certified clean-feedstock, standard-grade, and commodity-casting levels separates buyers by ECHA compliance documentation requirements. Cost compression in the commodity tier intensifies because Polish and Czech foundries compete on melt cost for rough casting volumes. Logistics operators with fleet standardization programs exhibit highest price sensitivity, while German harbor crane OEMs prioritize metallurgical certification over unit cost.
Supply Chain Analysis
Freight cost escalation from Eastern European rough casting sources to German finish-machining facilities is reshaping procurement economics. Supply concentrates in Germany, Poland, and China, with Baden-Württemberg anchoring precision machining and Changsha feeding integrated domestic assembly. Raw material flows draw from shredded auto scrap, electric arc furnace steel billet, and boron-based flux formulations. Single-source vulnerability concentrates in German foundry clusters serving Liebherr and Konecranes assembly lines. Distribution runs through logistics-coordinated multi-supplier arrangements unbundling casting from finish work.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over scrap recycling and electric arc furnace capacity determines margin sustainability across EU Green Deal compliance tiers.
For Market Incumbents: To counter concrete composite substitution in sub-five-ton elevator applications, Liebherr-International Deutschland GmbH and Konecranes Plc should deepen captive control over nodularization process technology for compacted graphite iron specifications. Capacity partnerships with Czech and Slovak foundries receiving EU structural fund modernization grants will defend cost position in mid-weight forklift counterweights against Polish competitors.
For New Entrants and Emerging Players: Digital-channel procurement platforms for certified clean-feedstock castings offer entry into fragmented logistics operator segments where fleet standardization programs lack dedicated sourcing teams. Target agricultural mechanization in Romania and Poland where telehandler OEMs seek six-to-ten-ton steel volumes with shorter lead times than German foundries provide. Position through additive-manufactured sand core prototyping services for custom crawler crane configurations.
For Investors and Strategic Acquirers: Early EU CBAM certification against carbon border adjustment frameworks is the leading indicator that a foundry will capture preferential positioning in German crane assembly plants facing Scope 3 disclosure mandates. Five-to-ten-year viability hinges on electric arc furnace integration with scrap recycling capabilities. Acquire Scandinavian mills with in-house nodularization control serving Finnish and Swedish harbor crane OEMs.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Scrap Recycling | Electric arc furnace operators with captive shredded auto scrap sourcing insulate margin structures from price volatility. |
| EU CBAM Certification Program | Early compliance creates preferential supply positioning for German crane builders under Scope 3 disclosure mandates. |
| Digital Twin Integration | Finite element analysis convergence with additive-manufactured sand cores accelerates prototyping for custom crawler configurations. |
| Eastern European Capacity Partnership | Czech and Slovak foundries with structural fund grants offer lower-cost casting for mid-weight forklift counterweights. |
| Clean-Feedstock Sourcing Agreement | Nordic electric arc furnace mills with integrated recycling secure ECHA-compliant heavy metal limits for harbor crane OEMs. |
Research Methodology
Trade flow databases, EU emissions registry filings, and foundry association production statistics formed the secondary backbone, cross-referenced with primary interviews involving crane OEM procurement directors, foundry operations managers, electric arc furnace process engineers, and logistics fleet standardization leads. Bottom-up volume estimates from individual facility capacities were triangulated against top-down demand calculations from harbor crane retrofit programs and telehandler assembly line expansions.
Historical trendline analysis established baseline growth patterns across material type, weight capacity tier, and end-use application segments. The projection framework modeled product type substitution dynamics, geographic manufacturing migration patterns, and regulatory compliance cost pass-through effects throughout the forecast period. CAGRs were derived from weighted average growth contributions across above-twenty-ton harbor crane demand, six-to-ten-ton telehandler expansion, and concrete substitution erosion in elevator applications.
The model holds under stable EU Green Deal implementation timelines and continued ECHA heavy metal limit enforcement; deviation in carbon border adjustment mechanism rollout schedules or abrupt scrap price shocks would shift volume trajectories between electric arc furnace and integrated foundry operators. Stakeholders should weight assumptions against their own operating context and captive supply capabilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Australia Forklift Market
Material Handling Equipment
Vibrating Feed Conveyors Market
Material Handling Equipment
Firewood Processors Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Roll Slitting Machines Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Industrial Fasteners Market
Material Handling Equipment
Overhead Conveyor Systems Market
Material Handling Equipment
United States Automated Material Handling Market
Material Handling Equipment
Compactor Market
Material Handling Equipment
Global Large Conveyor Chain Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Gravity Conveyor Market
Material Handling Equipment
Rolling Mill Machine Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market