
 Global Boom Truck Market | 2026-2036
Global Boom Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Global Boom Truck Market Analysis
ANSI A92.2 aerial platform certification is bifurcating the competitive landscape between qualified and non-qualified suppliers. Terex Corporation leverages its Genie brand manufacturing scale to sustain North American channel dominance. Palfinger AG anchors European utility demand through specialized loader crane integration. XCMG Group competes on cost-engineered telescopic units for emerging market infrastructure programs.
A boom truck combines a hydraulic lifting mechanism mounted on a commercial chassis, typically offering working heights from 30 to 200 feet with payload capacities up to 50 tons depending on configuration. These units serve essential functions in overhead line maintenance, structural steel erection, and material placement where terrain or building access prevents stationary crane deployment. Telescopic boom trucks dominate rental fleet composition due to simpler operation and lower maintenance overhead. Articulating boom trucks command premium positioning in utility applications where up-and-over clearance requirements predominate. Spider boom trucks represent the fastest-growing product category as urban densification restricts traditional chassis access in European and Asian city centers.
FAA regulations governing airport proximity operations, OSHA 1926 Subpart L aerial lift provisions, and EU machinery directive CE marking requirements collectively determine product design standards and market access thresholds across major demand zones. Compliance documentation burdens favor established manufacturers with dedicated homologation engineering teams. Stakeholders must monitor evolving electrification mandates for chassis powertrains and their compatibility with hydraulic lift duty cycles.
Market Dynamics
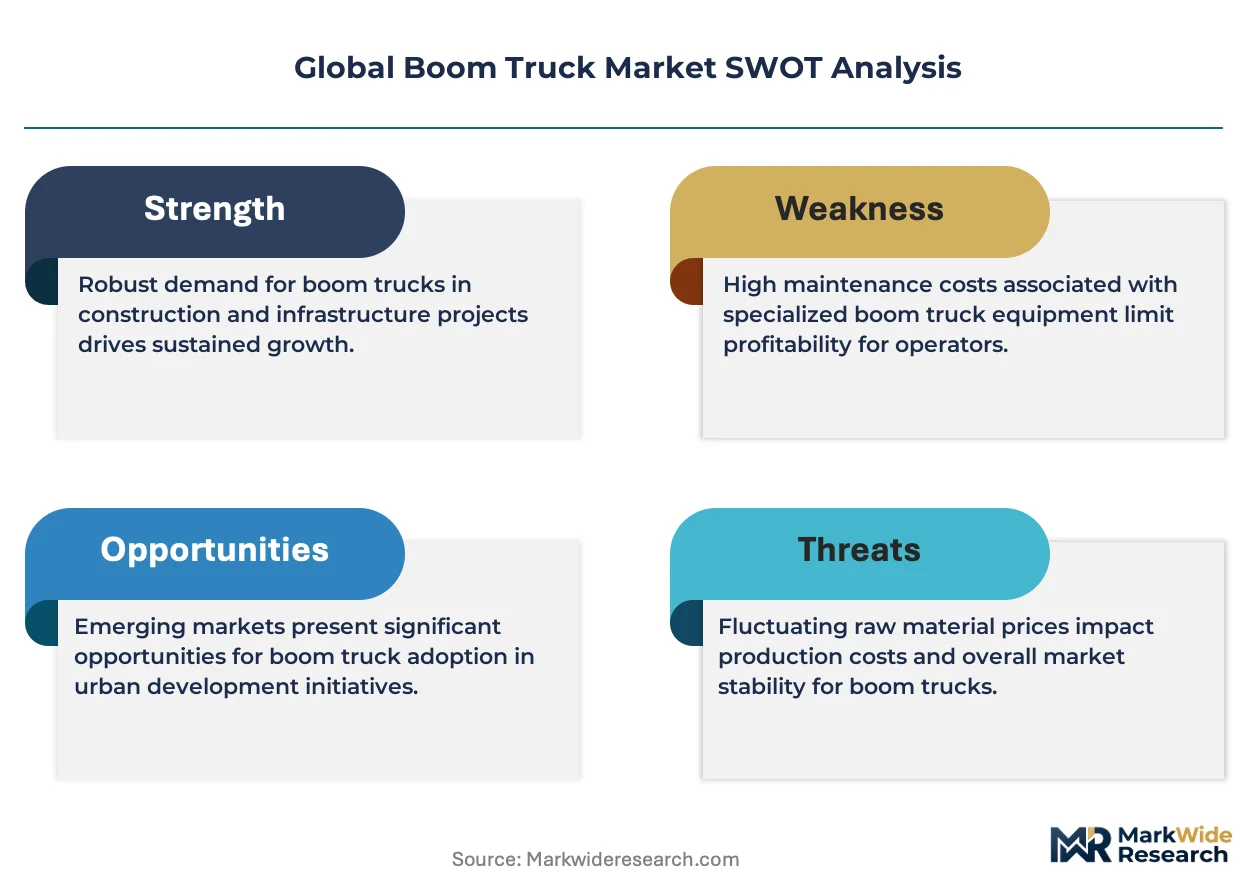
Utility fleet electrification mandates are compressing chassis procurement timelines as operators reconcile hydraulic lift duty cycles with battery-electric powertrain limitations. ANSI A92.2 recertification cycles are simultaneously extending equipment replacement windows for compliant assets while accelerating obsolescence for non-certified inventory.
Growth Catalysts
- OSHA 1926 Subpart L enforcement:Tightened aerial lift inspection protocols in United States construction corridors are forcing rental fleet upgrades toward qualified boom truck configurations.
- Transmission line hardening:Grid resilience programs across Texas and California utility corridors are expanding insulated aerial platform deployment for storm recovery operations.
- Spider boom morphology:Urban densification in European and Asian city centers is accelerating demand for compact footprint units capable of narrow street access.
Market Restraints
- Steel and hydraulic component volatility:Boom fabrication costs fluctuate with specialty alloy pricing and precision cylinder lead times from concentrated European suppliers.
- Chassis supply concentration:North American commercial truck chassis allocation prioritizes freight haulage over specialty body applications, constraining boom truck build slots.
- CE marking documentation burdens:EU machinery directive compliance costs favor established manufacturers with dedicated homologation engineering teams.
Strategic Opportunities
- India transmission infrastructure:Central Electricity Authority grid expansion targets create demand for cost-engineered telescopic units in distribution network construction.
- Hybrid-electric chassis convergence:Integration of battery-electric powertrains with optimized hydraulic systems opens municipal fleet segments with idling restrictions.
- Rental channel digitization:Telematics-enabled fleet management platforms allow equipment-as-a-service models penetrating mid-sized contractor segments.
Industry Challenges
- Certified technician scarcity:ANSI A92.2 operator and mechanic credentialing programs face enrollment gaps limiting fleet utilization rates.
- Multi-homologation complexity:Simultaneous FAA, OSHA, and EU machinery directive compliance extends product development cycles for airport-proximity specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Boom Truck Market |
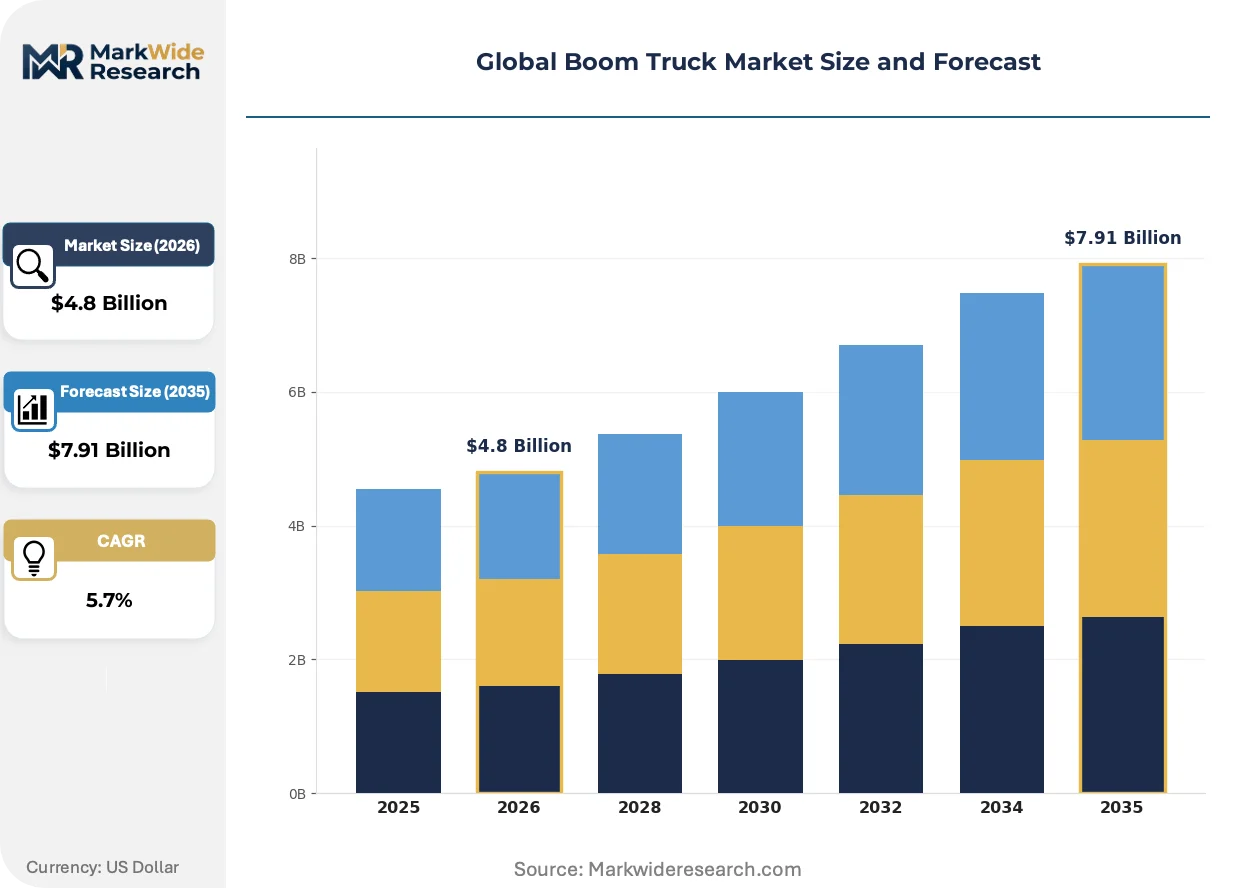
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic Boom Trucks, Articulating Boom Trucks, Spider Boom Trucks, Rough Terrain Boom Trucks End User: Construction, Maintenance Services, Utilities, Aerial Lift Providers Application: Building Construction, Road Maintenance, Landscaping, Emergency Services Deployment Model: Rental, Direct Purchase, Leasing, Used Equipment |
| Companies Covered | The Manitowoc Company, Inc., Terex Corporation, Fassi Gru S.p.A., Altec Industries, Palfinger AG, Tadano Ltd., XCMG Group, Zoomlion Heavy Industry Science & Technology Co., Liebherr-International AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Boom Truck Market Emerging Trajectories
Equipment morphology and powertrain architecture are diverging as urban access constraints and emissions mandates reshape boom truck design priorities. Three concurrent developments are altering competitive positioning.
Lithium-ion battery packs configured for chassis integration are miniaturizing while maintaining hydraulic pump duty cycle requirements. Municipal fleet operators in German and French city centers are piloting these configurations for low-emission zones. The technology is miniaturizing footprint constraints that previously excluded boom trucks from historic European cores.
EU Green Deal commercial vehicle CO2 performance standards are accelerating zero-emission chassis development timelines. Manufacturers must reconcile battery weight penalties with payload and working height specifications. Articulating boom configurations for utility applications face the steepest engineering trade-offs under these constraints.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-tier electrical contractors. Rental fleet operators are unbundling maintenance and telematics from hourly rates, creating transparent utilization-based pricing. United States utility cooperatives are adopting these structures fastest where seasonal demand volatility complicates ownership economics.
Global Boom Truck Market Segmentation
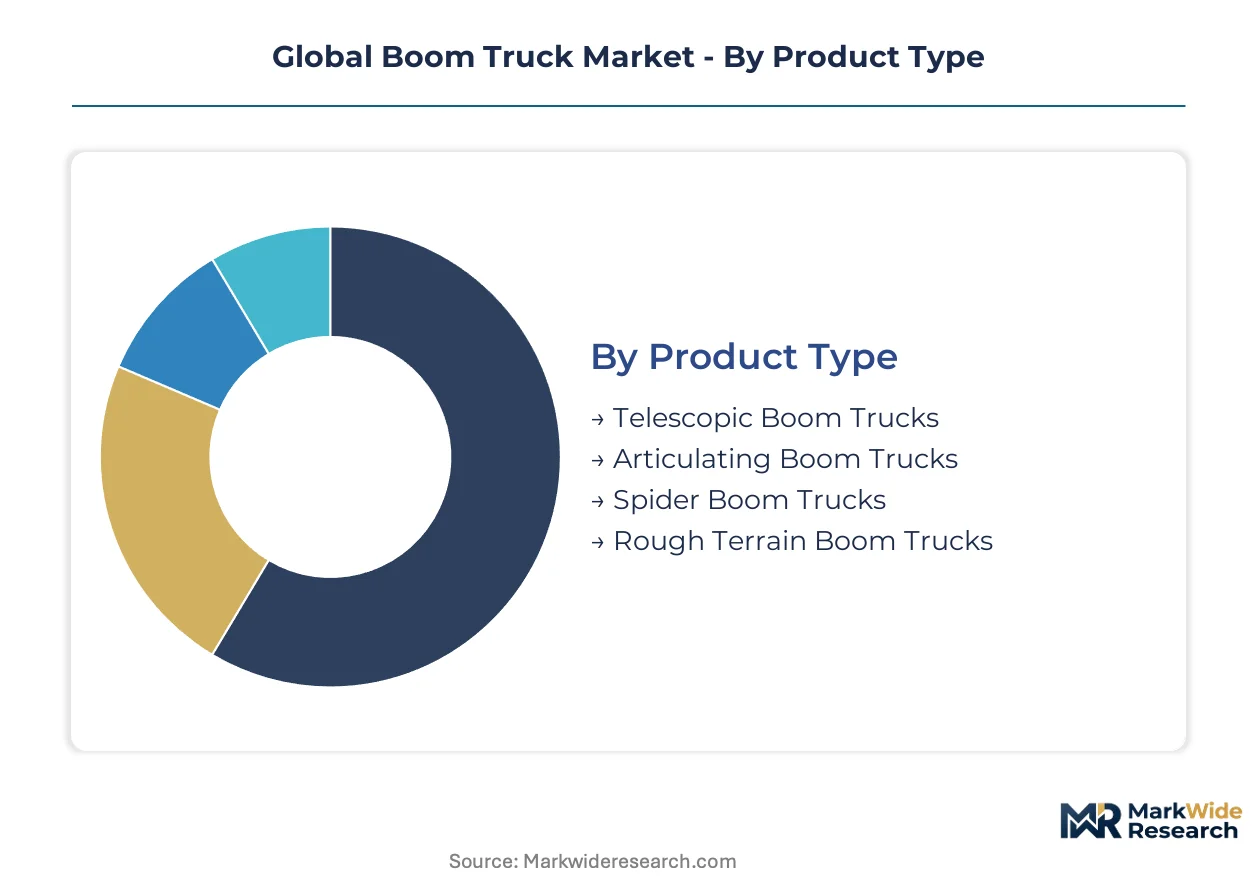
Boom truck procurement decisions cascade through multiple technical and commercial dimensions. Regulatory compliance tiers, duty cycle requirements, and capital deployment preferences each filter equipment selection into distinct purchasing behaviors.
Product Type:
OSHA 1926 Subpart L and ANSI A92.2 certification requirements create divergent qualification burdens across boom morphologies, concentrating procurement toward compliant configurations.
- Telescopic Boom Trucks:Single-section or multi-section hydraulic cylinders extend nested boom segments for vertical reach up to 200 feet. Rental fleet operators in Texas and California utility corridors favor these units for simplified operator training and reduced maintenance overhead.
- Articulating Boom Trucks:Multiple hinged joints enable up-and-over positioning for obstacle clearance. Utility sector demand concentrates here where overhead line maintenance requires precise platform placement around energized conductors.
- Spider Boom Trucks:Compact outrigger configurations deploy on narrow European and Asian streets where traditional chassis access is restricted.
- Rough Terrain Boom Trucks:Four-wheel-drive chassis with oversized tires navigate unpaved construction sites and emergency response zones.
Telescopic configurations handle the majority of fleet throughput; spider boom trucks are climbing the fastest on share.
End User:
Capital intensity and utilization predictability separate purchasing authority across customer categories, with municipal electrification mandates reshaping procurement timelines.
- Utilities:Investor-owned and cooperative operators deploy insulated aerial platforms for transmission line hardening and storm recovery. Grid resilience programs across Texas and California corridors are expanding insulated platform deployment.
- Construction:General and specialty contractors source telescopic units for structural steel erection and material placement where terrain prevents stationary crane deployment.
- Maintenance Services:Facility and infrastructure service providers favor articulating configurations for building envelope access.
- Aerial Lift Providers:National and regional rental fleets concentrate on telematics-enabled units for equipment-as-a-service contracting.
Utilities dominate capital deployment volume; aerial lift providers are expanding most quickly through subscription-based fleet models.
Application:
Site access constraints and payload requirements filter boom specifications by task environment, with urban densification compressing equipment footprints.
- Building Construction:Structural steel erection and facade installation demand working heights exceeding 100 feet with material handling capacity.
- Road Maintenance:Highway departments deploy rough terrain units for bridge inspection and signage installation.
- Landscaping:Arboriculture and grounds maintenance favor compact articulating units for tree canopy access.
- Emergency Services:Fire departments and search-and-rescue teams require rapid-deployment configurations with all-terrain mobility.
Building construction absorbs the greatest equipment tonnage; emergency services are gaining share fastest through municipal fleet modernization.
Deployment Model:
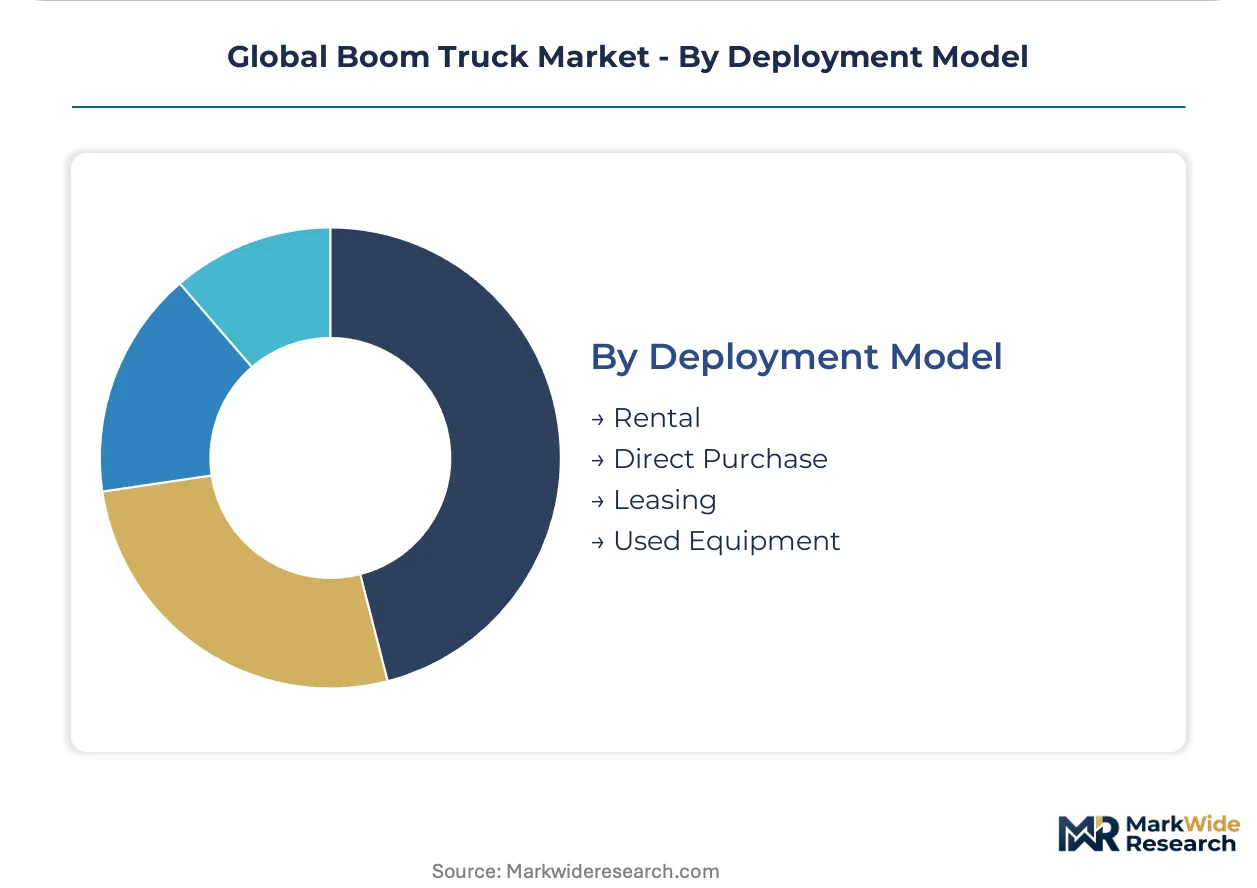
Balance sheet treatment and residual value risk allocate procurement across ownership structures, with telematics penetration enabling new contracting mechanics.
- Rental:Hourly and daily rates with bundled maintenance dominate mid-sized contractor access. United States utility cooperatives are adopting these structures fastest where seasonal demand volatility complicates ownership economics.
- Direct Purchase:Large fleet operators with predictable utilization and in-house maintenance capability retain capital ownership.
- Leasing:Operating leases transfer residual value risk to lessors for operators with cyclical demand patterns.
- Used Equipment:Secondary market liquidity concentrates on ANSI A92.2 certified units with documented inspection histories.
Rental channels transact the majority of unit-hours; leasing is expanding most quickly as fleet operators reconcile electrification transition risks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility cooperatives and municipal fleet operators concentrate procurement authority across distinct national regulatory environments. Grid hardening mandates and aerial lift certification cycles compress replacement timelines in mature markets while infrastructure expansion drives volume in emerging economies.
United States
Texas and California utility corridors absorb the majority of insulated aerial platform orders as storm resilience programs accelerate. OSHA 1926 Subpart L enforcement tightens inspection protocols, forcing rental fleet upgrades toward qualified configurations. Houston and Dallas-Fort Worth anchor distribution network construction for transmission line hardening.
Germany
Municipal fleet operators in Munich and Hamburg pilot battery-electric chassis configurations for low-emission zones. EU Green Deal commercial vehicle CO2 performance standards accelerate zero-emission development timelines. Stuttgart and Cologne concentrate engineering resources for hybrid-electric hydraulic system integration.
China
Central Electricity Authority grid expansion targets drive demand for cost-engineered telescopic units in distribution network construction. GB standards for aerial work platforms tighten safety certification requirements for domestic manufacturers. Yangtze River Delta manufacturing clusters around Shanghai optimize production scale for emerging market export programs.
India
State electricity boards in Maharashtra and Gujarat expand transmission infrastructure procurement for rural electrification completion targets. Central Electricity Authority technical specifications mandate insulated platform deployment for live-line maintenance. Mumbai and Pune industrial corridors concentrate assembly operations for cost-optimized utility configurations.
Japan
Tokyo Electric Power and regional utilities deploy compact articulating units for dense urban overhead line maintenance. METI energy efficiency standards influence hydraulic system design specifications for domestic fleet operators. Osaka and Nagoya manufacturing bases specialize in precision cylinder fabrication for premium utility applications.
Global Boom Truck Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive chassis supply relationships and specialized aerial platform manufacturers with certification engineering depth. Market structure concentrates around three strategic tiers: North American utility specialists with ANSI A92.2 homologation scale, European loader crane integrators with CE marking expertise, and Chinese scale fabricators serving cost-sensitive emerging market demand. Dominant competitive moves include backward integration into hydraulic component supply and strategic partnerships with commercial chassis OEMs to secure build slots.
Among North American utility specialists, Terex Corporation and Altec Industries occupy positions defined by aerial platform certification depth and utility channel relationships. European loader crane integrators include Palfinger AG and Fassi Gru S.p.A., representing archetypes of specialized hydraulic system integration. At the scale-driven end, XCMG Group and Zoomlion Heavy Industry Science & Technology Co., Ltd. exemplify cost-engineered production configurations targeting infrastructure expansion markets. Terex Corporation and Palfinger AG sit within the premium-tier vector where regulatory compliance documentation creates defensive positioning.
| Leading Market Players |
|---|
| The Manitowoc Company, Inc. |
| Terex Corporation |
| Fassi Gru S.p.A. |
| Altec Industries |
| Palfinger AG |
| Tadano Ltd. |
| XCMG Group |
| Zoomlion Heavy Industry Science & Technology Co. |
| Liebherr-International AG |
| Others |
Supply Flow & Price Mechanics
Twelve-to-sixteen-week hydraulic cylinder lead times from European suppliers concentrate pricing power with fabricators holding strategic alloy inventories, while chassis allocation constraints force buyers into premium slot-reservation contracts.
Pricing Analysis
Cost-plus contracts indexed to specialty steel alloy benchmarks dominate long-term procurement between utility fleet operators and established manufacturers. Three-tier pricing structure across ANSI A92.2-certified premium, standard utility-grade, and non-certified economy configurations separates qualified from marginal suppliers. Cost compression in the economy tier is intensifying as Chinese scale fabricators penetrate emerging market distribution. Municipal cooperatives exhibit highest price sensitivity due to seasonal utilization volatility, while investor-owned utilities prioritize certification compliance over unit cost.
Supply Chain Analysis
Strategic stockpiling of high-strength steel plate and precision hydraulic components prevails over just-in-time approaches given European supplier concentration and alloy price volatility. Manufacturing gravity centers on Germany, China, and the United States for boom fabrication, with Italy and Japan supplying critical cylinder subsystems. Raw material dependencies span specialty alloy steel, precision-machined hydraulic seals, and commercial truck chassis from captive OEM relationships. Single-source vulnerability in precision cylinder supply creates disruption exposure. Distribution runs through manufacturer-direct channels for large fleet operators and specialized equipment dealers serving mid-tier contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat arena where ANSI A92.2 certification entrenchment creates switching costs that lock utility procurement relationships across multi-year replacement cycles.
For Market Incumbents: Compound certification engineering depth through backward integration into hydraulic component supply, securing cylinder fabrication capacity against European supplier bottlenecks. Expand captive chassis partnerships with commercial truck OEMs to defend build-slot allocation against freight haulage priority. Prioritize telematics platform development to capture equipment-as-a-service recurring revenue before rental channel digitization commoditizes fleet management.
For New Entrants and Emerging Players: Lead with spider boom morphology specialization targeting European and Asian urban densification corridors where compact footprint requirements exclude established chassis-dominant competitors. Penetrate the India transmission infrastructure expansion through cost-engineered telescopic units aligned with Central Electricity Authority specifications. Deploy direct municipal fleet contracting to bypass dealer channel concentration.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across hybrid-electric chassis development programs as battery weight penalties force payload-working height engineering trade-offs. Target acquisition profiles center on ANSI A92.2-certified manufacturers with dedicated homologation teams and utility channel relationships. Monitor lithium-ion battery pack miniaturization trajectories as the inflection signal for municipal fleet electrification viability.
| Strategic Initiative | Industry Significance |
|---|---|
| ANSI A92.2 Certification Investment | Creates defensive positioning against non-qualified supplier displacement as OSHA enforcement tightens. |
| Hybrid-Electric Chassis Integration | Opens municipal fleet segments facing EU Green Deal CO2 performance standards and low-emission zone mandates. |
| Telematics Platform Development | Enables equipment-as-a-service contracting models penetrating mid-sized contractor price-sensitive segments. |
| Backward Integration into Hydraulic Supply | Secures cylinder fabrication capacity against European supplier concentration and lead time volatility. |
| Spider Boom Product Line Expansion | Captures urban densification demand in European and Asian city centers with narrow street access constraints. |
Methodological Framework
The analysis maps telescopic, articulating, spider, and rough terrain boom truck morphologies, each validated through utility fleet procurement directors, rental channel operations managers, hydraulic component sourcing leads, and municipal equipment specification engineers. Primary fieldwork combined structured interviews with secondary triangulation across OSHA enforcement databases, ANSI A92.2 certification registries, utility cooperative capital expenditure disclosures, and commercial chassis allocation reports from North American truck OEMs. Bottom-up unit demand modeling and top-down market sizing reconstructions were cross-validated for consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product morphology, end-user category, application environment, and deployment model, with additional granularity on certification tier and chassis powertrain architecture. CAGRs were derived from fitted growth curves incorporating utility fleet replacement cycle analysis, grid hardening program commitments, and electrification mandate compliance timelines. Forecast inputs encompass transmission line construction pipeline data, rental fleet telematics penetration rates, and municipal procurement budget trajectories.
Forecasts assume regulatory continuity in OSHA aerial lift enforcement, EU machinery directive CE marking requirements, and FAA airport proximity specifications; material policy shifts would require re-modeling. Revision becomes warranted when hybrid-electric chassis payload penalties exceed utility working height specifications or when ANSI A92.2 recertification cycles compress replacement windows beyond modeled parameters.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
China Full-Truck-Load (FTL) Market
Heavy-Duty Trucks
Truck Tank Market
Heavy-Duty Trucks
Truck Headache Rack Market
Heavy-Duty Trucks
Utility Trucks Market
Heavy-Duty Trucks
Malaysia Fire Truck Market
Heavy-Duty Trucks
Big Rig Trucks Market
Heavy-Duty Trucks
Articulated Dump Trucks Market
Heavy-Duty Trucks
Articulated Hauler Market
Heavy-Duty Trucks
India Vacuum Truck Market
Heavy-Duty Trucks
Europe Fire Truck Market
Heavy-Duty Trucks
Asia Pacific Garbage Truck Bodies Market
Heavy-Duty Trucks
Truck Bedliner Market
Heavy-Duty Trucks
North America Heavy Commercial Vehicle (HCV) TMPS Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
China Full Truckload Road Freight Transport Market
Heavy-Duty Trucks
Stacker Truck Market