
 Automotive Switch Market | 2026-2036
Automotive Switch Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Switch Market Analysis
EV-first OEMs are reorganizing supplier relationships around haptic and capacitive switch portfolios. Alps Alpine Co. Ltd leverages its film-insert molding expertise to dominate premium EV cockpit contracts. Robert Bosch GmbH anchors its position through integrated power management modules that bundle switching with battery control logic. Continental AG differentiates via software-defined switch platforms that support over-the-air reconfiguration.
An automotive switch is an electromechanical or solid-state control device that completes or interrupts circuits within vehicle systems, typically rated for operational lives exceeding one million cycles and temperature ranges from minus forty to eighty-five degrees Celsius. Its primary purpose is to enable reliable human-machine interface control across lighting, climate, and propulsion functions. Push button switches command the largest volume share as starter and drive-mode selectors proliferate across EV architectures, while capacitive technology captures the fastest expansion as flush-surface designs eliminate mechanical wear points. Electronic switching segments concentrate margin pools where software integration and diagnostic capability create tiered value capture.
NHTSA, EPA, and EU REACH frameworks govern material composition, electromagnetic compatibility, and chemical restrictions for automotive switch assemblies. REACH substance limitations on heavy metals and flame retardants are forcing reformulation of contact platings and housing polymers. Stakeholders must monitor convergence between functional safety standards and software liability regimes as touch-based controls assume critical vehicle functions.
Market Dynamics
Capacitive touch interfaces are systematically dismantling the mechanical switch supply base, forcing tier-two suppliers to retool for solid-state production or exit cockpit electronics entirely. This technology transition concentrates procurement power among OEMs with in-house software capabilities.
Growth Catalysts
- EU REACH substance mandates:Heavy metal restrictions on contact platings are accelerating migration to polymer-based conductive films, opening specification windows for specialized material suppliers.
- EV platform proliferation:Drive-mode selectors and regenerative braking controls multiply switch points per vehicle, with premium architectures integrating fifteen to twenty additional interface elements.
- Stuttgart-Toyota City-Detroit production clusters:Geographic concentration of premium vehicle assembly creates dense supplier ecosystems where prototyping cycles compress from months to weeks.
Market Restraints
- Palladium and silver price volatility:Contact plating materials face input cost swings that erode margin predictability for mid-tier switch manufacturers.
- Single-source dependency on Malaysian PCB substrate suppliers:Southeast Asian concentration risk exposes assembly lines to geopolitical disruption and shipping bottlenecks.
- Functional safety certification under ISO 26262:ASIL-D ratings for steering and braking interfaces impose eighteen-month validation timelines that freeze design iterations.
Strategic Opportunities
- Indian passenger vehicle electrification:Local PLI scheme incentives for EV component manufacturing create first-mover advantages for switch suppliers establishing Pune and Chennai production.
- Over-the-air reconfigurable interfaces:Software-defined switch platforms enable subscription-based feature activation, transforming one-time component sales into recurring revenue streams.
- Integration of haptic feedback with voice control:Multimodal interface convergence opens specification roles for suppliers combining actuator hardware with acoustic processing algorithms.
Industry Challenges
- Embedded software engineering scarcity:Competent firmware developers for capacitive sensing algorithms command premium compensation that strains R&D budgets at subscale suppliers.
- Legacy 12V electrical architecture coexistence:Hybrid vehicle programs require dual-voltage switch designs that multiply validation matrices and inventory complexity.
- Cross-border electromagnetic compatibility testing:Divergent FCC, ETSI, and ARIB certification regimes force redundant laboratory expenditures for globally positioned product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Switch Market |
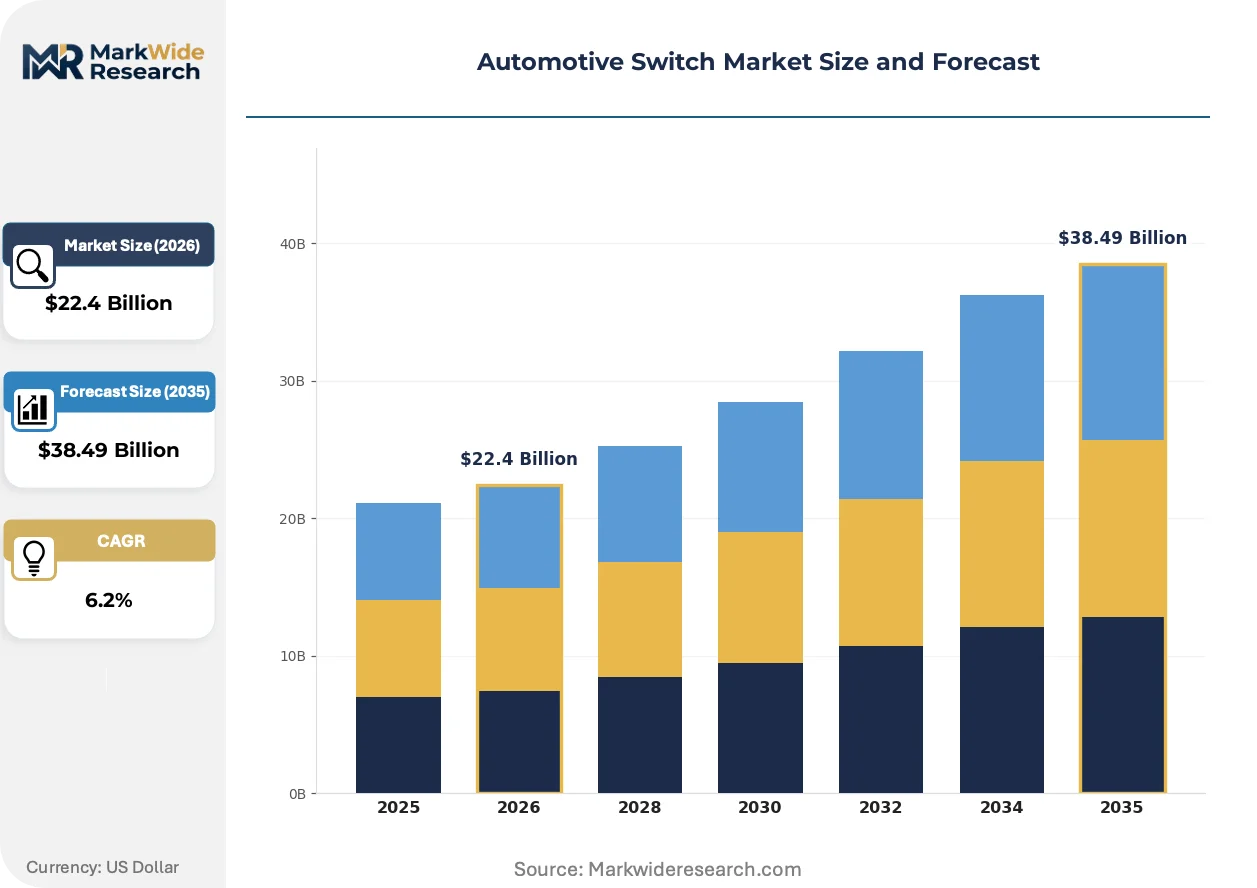
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $38.49 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toggle Switches, Push Button Switches, Rotary Switches, Rocker Switches Technology: Mechanical, Electronic, Piezoelectric, Capacitive Application: Lighting Control, Power Management, Infotainment Systems, HVAC Control End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Alps Alpine Co. Ltd, Panasonic Corporation, Robert Bosch GmbH, Johnson Electric Holdings Limited, Leopold Kostal GmbH & Co. KG, Continental AG, Valeo SA, Marquardt GmbH, ZF Friedrichshafen AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Switch Market Emerging Trajectories
Haptic feedback systems are rewriting the tactile vocabulary of vehicle interiors, replacing the mechanical certainty of detents with programmable response profiles. This shift demands entirely new competencies from suppliers accustomed to spring-and-contact engineering.
Surface-mounted force sensors are fragmenting the traditional stack-up of mechanical switches, eliminating plungers, springs, and housings in favor of laminated film assemblies. Tier-one cockpit integrators are adopting these architectures for center-stack controls, compressing the addressable market for conventional electromechanical suppliers by half within premium segments. The technology is fragmenting procurement categories that once bundled mechanical and electronic sourcing into separate commodity silos.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are pressuring suppliers to eliminate SF6 from high-voltage switch insulation in electric powertrains. Manufacturers are reformulating with dry air and vacuum interruption technologies, particularly for 800V architectures where arc quenching demands intensify. German KBA type-approval timelines have extended by four to six months as validation protocols adapt to these material transitions.
Fleet procurement departments are consolidating switch specifications across multiple nameplates to extract volume pricing from reduced supplier panels. This behavior is compressing the viable vendor base from twelve to fifteen qualified sources per OEM to five or six strategic partners, with survivors absorbing engineering responsibilities previously borne by customer technical staffs. The concentration is most visible in North American full-line manufacturers where platform sharing has reached eighty percent commonality across light truck and SUV portfolios.
Automotive Switch Market Segmentation
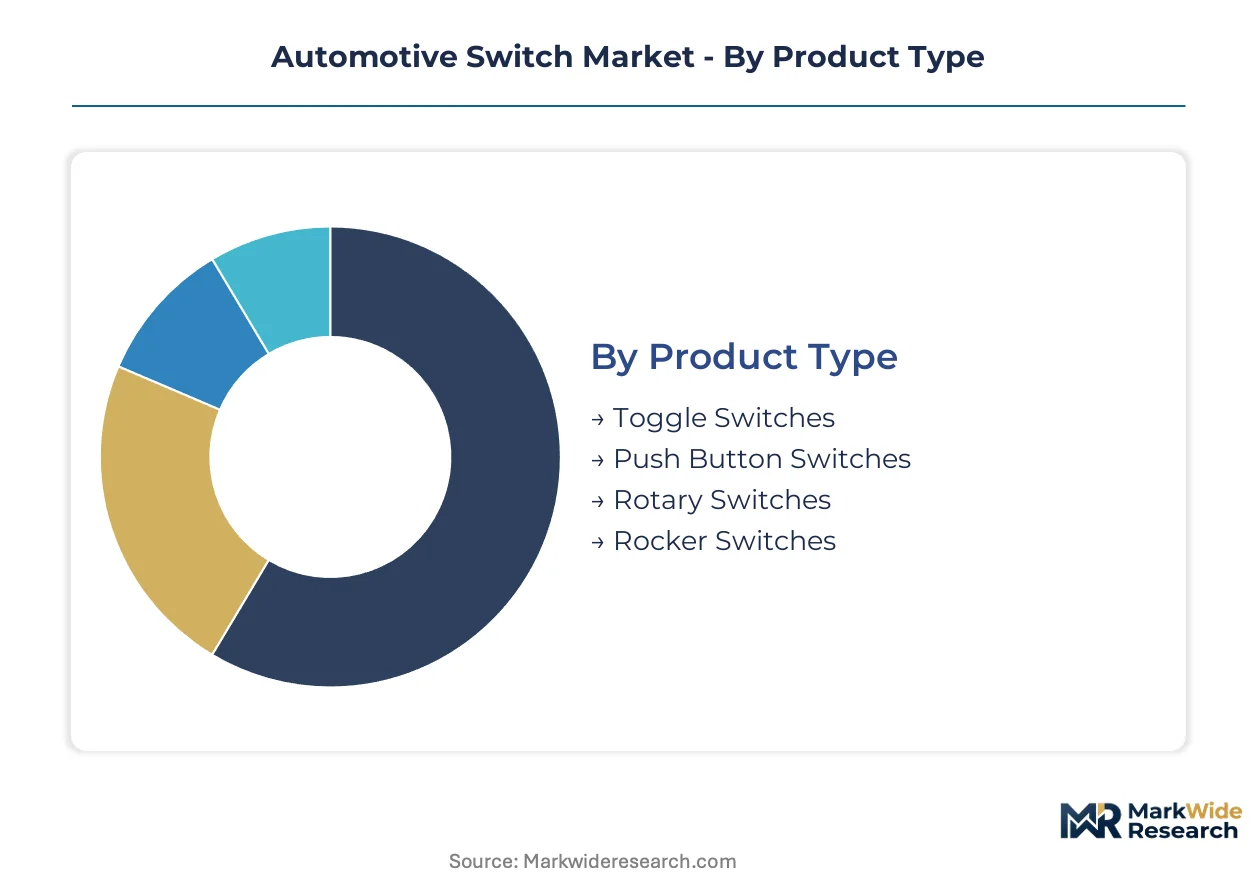
Automotive switch segmentation reveals how value migrates across electromechanical and solid-state technologies. Procurement patterns differ sharply between legacy vehicle programs and EV-first platforms, with margin pools shifting toward software-integrated electronic segments.
Product Type:
Margin concentration follows the transition from mechanical complexity to electronic integration, with premium EV architectures driving specification changes.
- Push Button Switches:These electromechanical devices employ momentary-contact mechanisms rated for high cycle life. Drive-mode selectors and starter controls on Stuttgart-produced EV platforms concentrate demand here. OEMs specify these for critical vehicle functions where tactile feedback remains mandatory.
- Toggle Switches:Maintained-contact designs with lever actuation dominate auxiliary power and lighting circuits. Fleet procurement departments favor these for light truck and SUV portfolios manufactured in Detroit-area assembly plants, prioritizing durability over aesthetic refinement.
- Rotary Switches:Multi-position detent mechanisms serve climate control and lighting intensity adjustment. Japanese OEMs in Toyota City specify these for center-stack integration where rotary input preserves driver attention.
- Rocker Switches:Bipolar actuation designs occupy door panel and overhead console applications. Cost-sensitive vehicle programs specify these for high-volume economy segments.
The dominant share belongs to Push Button Switches, while Capacitive technology is closing the gap fastest.
Technology:
Cost tier stratification separates commodity mechanical production from premium electronic and capacitive segments where firmware development costs dominate bill-of-materials.
- Capacitive:Field-effect sensing through laminated electrode arrays eliminates mechanical wear. Flush-surface designs on German premium EV platforms concentrate specification activity here. Alps Alpine Co. Ltd and Continental AG compete for cockpit integration contracts requiring haptic feedback integration.
- Electronic:Solid-state switching with embedded diagnostic capability enables over-the-air reconfiguration. Robert Bosch GmbH bundles these with battery management modules for 800V architectures. ASIL-D functional safety certification under ISO 26262 extends development timelines.
- Mechanical:Spring-and-contact assemblies with precious metal plating serve legacy 12V electrical systems. Palladium price volatility erodes margin predictability for mid-tier manufacturers.
- Piezoelectric:Crystalline actuation generates electrical signals from mechanical pressure, suited for sealed environments. Limited adoption concentrates in specialty off-road and marine-adjacent vehicle applications.
Mechanical technology retains volume leadership, though Capacitive segments are expanding most quickly as flush-surface designs proliferate.
Application:
Volume concentration tracks vehicle electrical architecture complexity, with premium segments integrating fifteen to twenty additional interface elements per platform.
- Power Management:High-voltage switching for propulsion and charging circuits operates at 400V to 800V. EU F-Gas Regulation restrictions on SF6 insulation are forcing dry air and vacuum interruption reformulations. German KBA type-approval timelines have extended four to six months.
- Infotainment Systems:Capacitive touch interfaces with force sensing replace mechanical controls. Tier-one cockpit integrators specify surface-mounted film assemblies that compress procurement categories previously separated into mechanical and electronic silos.
- HVAC Control:Temperature and airflow adjustment interfaces balance tactile feedback with surface integration. Rotary and rocker configurations dominate mid-market vehicle programs.
- Lighting Control:Headlamp mode and ambient lighting switches span mechanical and electronic technologies. NHTSA safety mandates govern durability benchmarks for exterior lighting interfaces.
Power Management commands the dominant application share, while Infotainment Systems are gaining share fastest through capacitive interface proliferation.
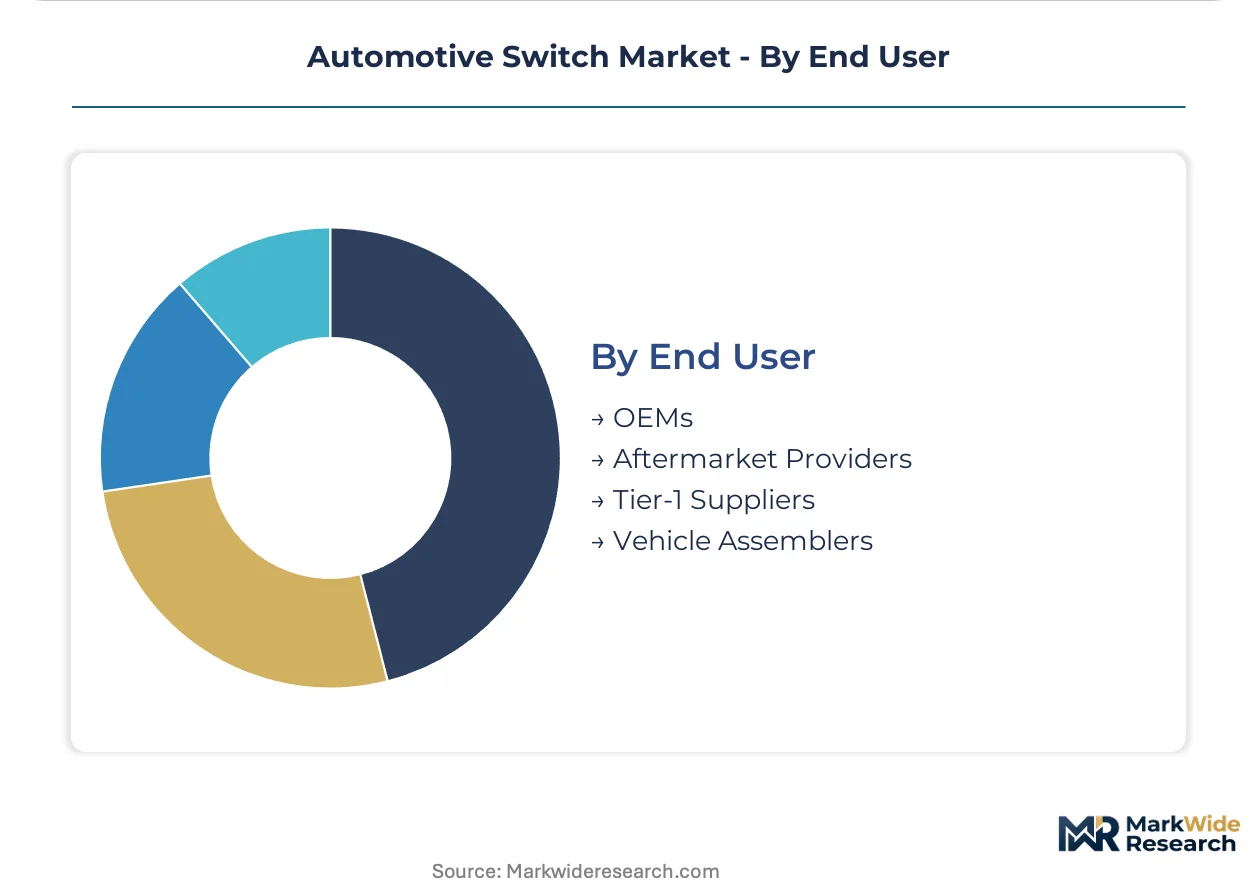
End User:
Customer type determines specification authority and procurement consolidation patterns, with fleet departments reducing qualified supplier panels from twelve to five sources.
- OEMs:Brand-holding manufacturers with in-house software capabilities concentrate procurement power. EV-first OEMs reorganize supplier relationships around haptic and capacitive portfolios, internalizing firmware development.
- Tier-1 Suppliers:Cockpit integrators bundle switch sourcing with display and controller assembly. These stakeholders absorb engineering responsibilities previously borne by OEM technical staffs.
- Vehicle Assemblers:Contract manufacturing operations follow OEM specifications with limited sourcing autonomy. Platform sharing at eighty percent commonality across light truck portfolios reduces specification variation.
- Aftermarket Providers:Replacement and accessory channels serve vehicle aging and customization demand. REACH substance limitations on heavy metals complicate cross-border inventory management.
OEMs retain the dominant procurement share, though Tier-1 Suppliers are consolidating influence fastest through cockpit integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German switch exports supply Stuttgart-based EV assembly lines serving premium buyers across Western Europe and North America. Japanese manufacturers ship capacitive interface components from Toyota City to Southeast Asian EV joint ventures. This trade-flow architecture concentrates specification authority in three production clusters.
Germany
EU F-Gas Regulation restrictions on SF6 insulation are forcing dry air reformulations for 800V powertrain switches. KBA type-approval timelines have extended four to six months as validation protocols adapt. Stuttgart production clusters host Alps Alpine and Continental AG engineering centers where haptic feedback prototypes compress from months to weeks.
Japan
METI carbon neutrality roadmaps are accelerating capacitive touch adoption across Toyota City EV platforms. JIS electromagnetic compatibility standards govern diagnostic capability integration for solid-state switching modules. Nagoya-area suppliers specialize in rotary switch detent mechanisms for center-stack climate controls.
United States
NHTSA safety mandates on exterior lighting interface durability are tightening cycle-life benchmarks for Detroit-area switch procurement. EPA material composition rules intersect with REACH substance limitations for cross-border inventory management. Michigan production clusters concentrate toggle switch demand for light truck and SUV fleet programs.
China
MIIT new energy vehicle subsidies are multiplying drive-mode selector switch points per domestic EV platform. GB standards for high-voltage switching govern 400V to 800V arc quenching specifications. Yangtze River Delta manufacturing hubs supply surface-mounted force sensor assemblies for center-stack capacitive interfaces.
India
PLI scheme incentives for EV component manufacturing are attracting switch suppliers to Pune and Chennai production. BIS certification requirements for automotive electronics are extending validation timelines for imported capacitive modules. Tamil Nadu assembly clusters concentrate demand for cost-sensitive rocker configurations in economy vehicle programs.
Automotive Switch Market Vendor Landscape
Player mix skews toward diversified tier-one cockpit integrators with bundled electronics capabilities. Mid-tier mechanical specialists face retooling pressure as capacitive interfaces displace spring-and-contact engineering. Two archetypes dominate: integrated power management bundlers and software-defined switch platform developers. Competitive moves concentrate on strategic partnerships for haptic feedback integration and portfolio diversification into solid-state sensing technologies.
Within the diversified tier-one tier, Alps Alpine Co. Ltd, Robert Bosch GmbH, and Continental AG occupy positions reflecting distinct capability emphases. Alps Alpine represents film-insert molding specialists leveraging tactile interface expertise. Robert Bosch GmbH exemplifies integrated systems architects bundling switching with battery control logic. Continental AG anchors software-defined platform development for over-the-air reconfigurable interfaces.
| Leading Market Players |
|---|
| Alps Alpine Co. Ltd |
| Panasonic Corporation |
| Robert Bosch GmbH |
| Johnson Electric Holdings Limited |
| Leopold Kostal GmbH & Co. KG |
| Continental AG |
| Valeo SA |
| Marquardt GmbH |
| ZF Friedrichshafen AG |
| Others |
Supply Flow & Price Mechanics
Twenty-two-week prototyping cycles for haptic feedback modules concentrate procurement leverage among Stuttgart and Toyota City OEMs, compressing margin pools for mid-tier mechanical suppliers unable to retool for solid-state production. This lead-time compression amplifies pricing power for tier-one integrators while fragmenting residual demand across cost-sensitive economy segments.
Pricing Analysis
The technology-generation pricing gap separates legacy mechanical switches from capacitive electronic modules and emerging force-sensor film assemblies. Three-tier pricing structure across premium, standard, and economy levels reflects ASIL-D certification grade and software integration depth. Cost compression in mechanical tiers is intensifying because palladium price volatility erodes contact plating margins. Fleet procurement departments exhibit highest price sensitivity, while premium EV OEMs prioritize haptic feedback performance over unit cost.
Supply Chain Analysis
Inventory concentration for PCB substrates and conductive films rests on Malaysian, Chinese, and Japanese manufacturing nodes. Raw material dependencies center on palladium and silver contact platings, polymer-based conductive films, and force-sensor electrode arrays. Single-source vulnerability on Malaysian PCB suppliers exposes assembly lines to geopolitical disruption. Distribution runs through tier-one cockpit integrators who bundle switch sourcing with display and controller assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as EV platform proliferation restarts procurement cycles frozen by legacy powertrain transition delays.
For Market Incumbents: Fortify haptic feedback engineering capabilities through captive software development or targeted acquisition of capacitive sensing specialists. Mechanical switch portfolios face substitution pressure from surface-mounted force sensors; backward integration into polymer film manufacturing secures margin control against material suppliers. For New Entrants and Emerging Players: Firmware customization services represent a service-layer gap where incumbents under-serve mid-market OEMs lacking in-house embedded software teams. Target Indian PLI scheme jurisdictions for manufacturing footprint establishment. Pursue direct engineering contracts with domestic EV assemblers in Pune and Chennai bypassing entrenched tier-one relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because procurement panel reduction from twelve to five qualified sources concentrates engineering value capture among survivors. Target capacitive interface specialists with ISO 26262 certification progress and established OEM pilot programs. Watch KBA type-approval timeline compression as inflection signal for technology transition completion.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Over-the-air reconfigurable interfaces enable subscription revenue streams for Continental AG and Robert Bosch GmbH. |
| Geographic Manufacturing Footprint | Pune and Chennai production under PLI scheme incentives captures Indian EV electrification procurement windows. |
| Platform Standardization | Eighty percent commonality across light truck portfolios reduces specification variation for Detroit-area assemblers. |
| Battery Supply Agreement | Integrated power management modules bundle switching logic with 800V battery control systems. |
| Charging Infrastructure Partnership | High-voltage switching for 400V to 800V circuits demands dry air insulation reformulation under EU F-Gas Regulation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs/trade records. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads inform demand-side validation. Bottom-up bill-of-materials analysis triangulates against top-down production volume estimates.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from regression analysis across the projection horizon, incorporating switch point multiplication rates on EV platforms and functional safety certification timeline impacts. Industry-specific inputs include NHTSA safety mandate compliance costs and REACH substance limitation reformulation expenditures.
Underlying assumptions cover EV adoption trajectory, palladium price stabilization, and semiconductor supply normalization, with deviation risk concentrated in geopolitical disruption to Malaysian PCB substrate flows and extended KBA type-approval timelines for SF6-free insulation technologies. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Electronics & Wiring
Automotive Optical Fiber Data Cable Systems Market
Automotive Electronics & Wiring
Automotive Over-The-Air (OTA) Updates Market
Automotive Electronics & Wiring
Two-Wheeler ECU Market
Automotive Electronics & Wiring
Global Phone Car Mounts Market
Automotive Electronics & Wiring
Vehicle Intercom System Market
Automotive Electronics & Wiring
Automotive Halogen Lights Market
Automotive Electronics & Wiring
Automotive Haptic Technology Market
Automotive Electronics & Wiring
Automotive Speedometer Cable Market
Automotive Electronics & Wiring
Automotive Surround View Systems Market
Automotive Electronics & Wiring
Global Automotive Audio Speakers Market
Automotive Electronics & Wiring
Car Speaker Market
Automotive Electronics & Wiring
Automotive Glow Plug Market
Automotive Electronics & Wiring
Global Automotive FPC Market
Automotive Electronics & Wiring
North America Automotive Display Market
Automotive Electronics & Wiring
Automotive Micro Switch Market
Automotive Electronics & Wiring
Zonal Wiring Harness Platforms for Software-Defined Vehicles Market