
 Platooning Trucks Market | 2026-2036
Platooning Trucks Market Size, Share, and Industry Trends Forecast 2026-2036
Platooning Trucks Market Analytics
Vehicle-to-vehicle communication paired with sensor fusion is rewriting the architecture of commercial freight conveyance. Peloton Technology leverages proprietary algorithms to synchronize braking distances between paired heavy-duty trucks. Volvo Group anchors its competitive stance through deep integration of automated steering with existing powertrain platforms. Robert Bosch GmbH dominates sensor supply for adaptive cruise control modules deployed across European logistics corridors.
Platooning trucks are multi-unit commercial vehicles electronically tethered through dedicated short-range communication, maintaining gaps as tight as 15 meters to exploit aerodynamic drafting and reduce fuel burn by 7-10 percent for trailing units. Long-distance haulage commands the dominant application share, as sustained highway speeds maximize the aerodynamic efficiency gains that justify technology investment. Freight transportation within the logistics provider end-user segment exhibits the fastest expansion trajectory, driven by pressure on operating margins across parcel and less-than-truckload networks. Electric trucks represent the emerging vehicle type frontier, where cooperative automation extends range by reducing energy consumption per kilometer traveled.
The European Union's F-Gas Regulation and MDR framework shape component certification requirements for sensor and communication modules, while the US NHTSA and FMCSA jointly govern on-highway testing permissions for automated convoy operations. Japan's METI has issued specific guidelines for truck platooning trials on designated expressway segments, creating a tripartite regulatory landscape that vendors must navigate simultaneously. Stakeholders should monitor how divergent liability standards between jurisdictions affect insurance product design and fleet procurement timelines.
Market Dynamics
The platooning trucks market is being fundamentally restructured by the collision of cooperative automation standards with divergent liability frameworks across freight corridors. Fleet operators now face simultaneous pressure to deploy vehicle-to-vehicle communication systems while navigating incompatible insurance and certification requirements that fragment procurement decisions.
Growth Catalysts
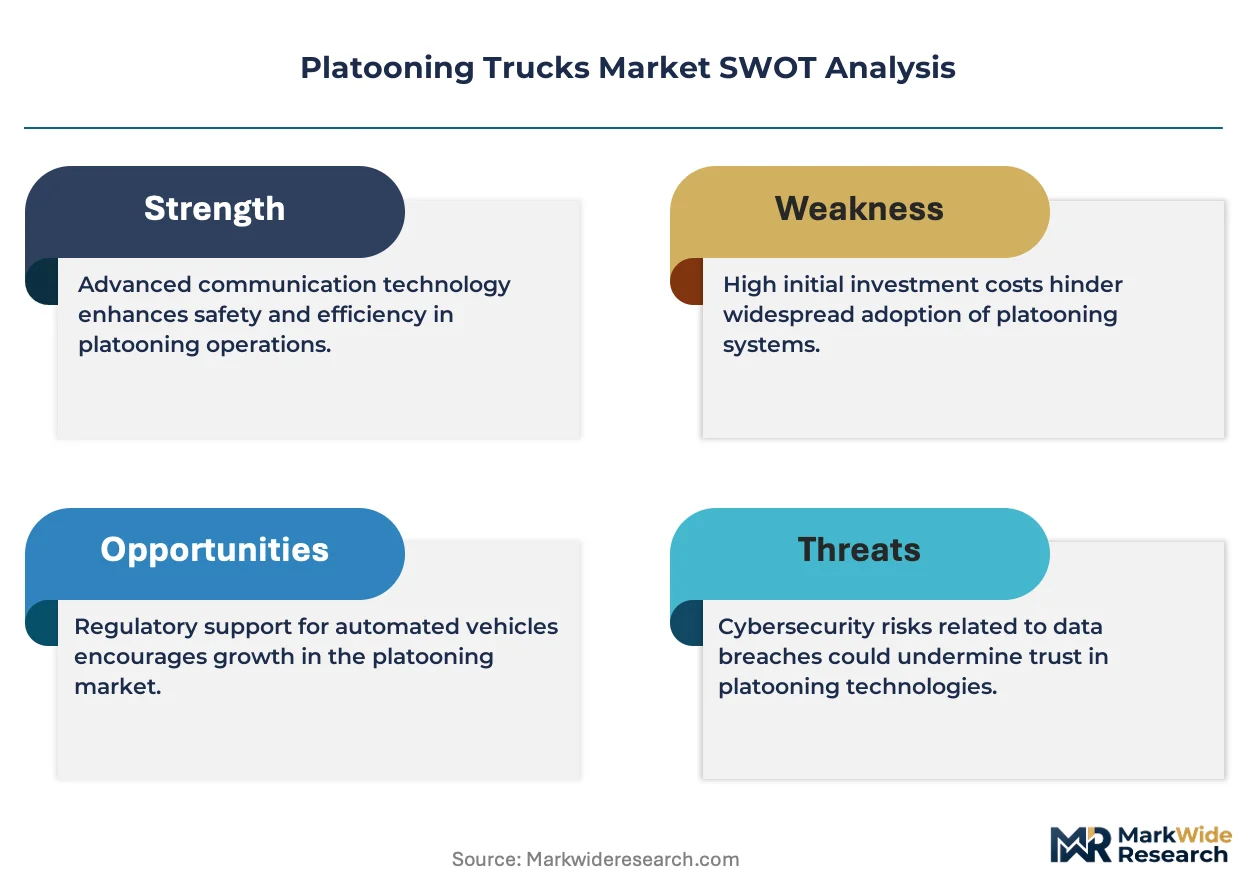
- F-Gas Regulation compliance pressure:European fleet operators must retrofit existing vehicles with cooperative adaptive cruise control to meet tightening emission thresholds for commercial transport.
- Sensor fusion maturation:Lidar-radar integration is reducing false-positive braking events, making platooning viable for parcel networks operating at highway speeds.
- Logistics corridor density:Germany's concentrated freight volume between Rotterdam and Milan creates viable platooning routes that justify dedicated short-range communication infrastructure investment.
Market Restraints
- Lithium-ion cost volatility:Electric truck battery pack prices fluctuate with cobalt and nickel spot markets, compressing total cost of ownership calculations for fleet procurement committees.
- Sensor supply concentration:European adaptive cruise control module production clusters in southern Germany, creating single-source vulnerability for logistics providers scaling multi-country operations.
- Interoperability fragmentation:Dedicated short-range communication protocols lack cross-border harmonization, forcing redundant hardware configurations for international haulage.
Strategic Opportunities
- Less-than-truckload network penetration:Parcel consolidation hubs in the Netherlands and Belgium remain underserved by platooning technology, offering first-mover positioning for cooperative automation vendors.
- Electric truck convergence:Cooperative adaptive cruise control extends battery range per charge, addressing range anxiety in Nordic freight corridors where charging infrastructure remains sparse.
- MDR certification pathway:The EU's medical device regulation framework is being adapted for autonomous vehicle component validation, potentially streamlining sensor module approval timelines.
Industry Challenges
- Telematics integration complexity:Legacy fleet management systems from disparate vendors resist real-time data exchange with platooning control units, forcing expensive middleware development.
- Commercial driver certification gaps:Cooperative automation operation requires specialized training that existing heavy vehicle licensing frameworks in member states have not yet incorporated.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Platooning Trucks Market |
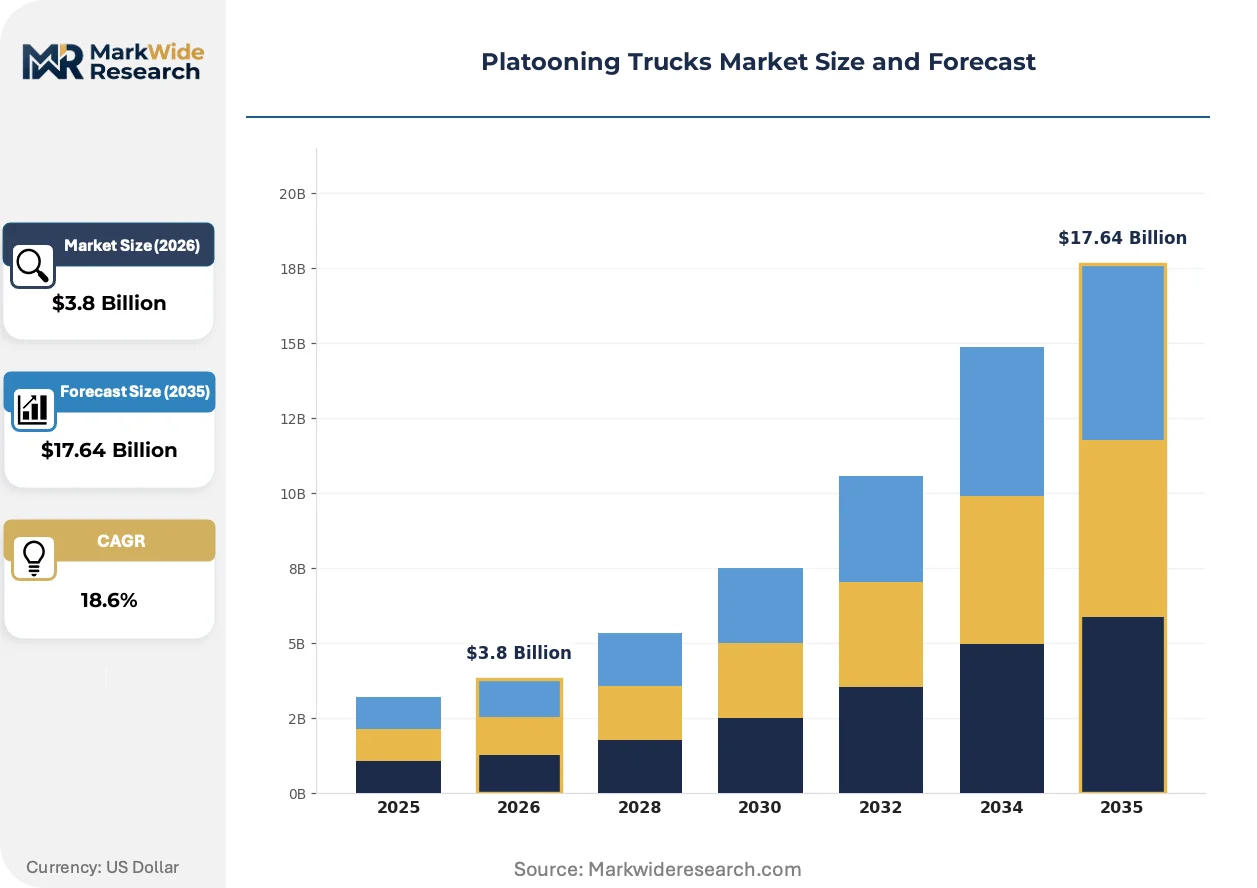
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: V2V Communication, Automated Steering, Adaptive Cruise Control, Sensor Fusion End User: Logistics Providers, Fleet Operators, E-commerce Companies, Transportation Services Application: Long-Distance Haulage, Urban Delivery, Freight Transportation, Intermodal Transport Vehicle Type: Heavy-Duty Trucks, Light-Duty Trucks, Commercial Vans, Electric Trucks |
| Companies Covered | Volvo Group, Daimler Truck AG, Scania AB, Continental AG, Peloton Technology, Robert Bosch GmbH, DAF Trucks, IVECO, Toyota Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Platooning Trucks Market Evolving Landscape
Cooperative automation is hybridizing with electrification architectures to reshape how freight operators calculate vehicle lifecycle economics. Three convergent developments are compressing deployment timelines while introducing new technical dependencies.
Sensor fusion technology is hybridizing radar and camera inputs to enable tighter following distances without sacrificing safety margins. Long-distance haulage operators in Germany and the Netherlands are piloting 12-meter gap configurations, down from 15-meter baselines. This compression is enabling fuel burn reductions that justify dedicated short-range communication hardware costs within eighteen-month payback windows.
The EU AI Act's risk classification framework is imposing documentation burdens on automated steering algorithm developers. Component suppliers must now maintain technical file repositories that satisfy notified body scrutiny equivalent to medical device manufacturers. European logistics providers are responding by consolidating procurement around vendors with pre-certified sensor module portfolios.
Freight procurement committees are unbundling vehicle acquisition from telematics service contracts. Parcel networks are demanding API-accessible platooning performance data as a standalone purchase criterion, separate from maintenance agreements. This behavioral shift is most pronounced in Belgian and Dutch less-than-truckload operations, where route optimization software vendors now compete directly with truck OEMs for data integration contracts.
Platooning Trucks Market Segmentation
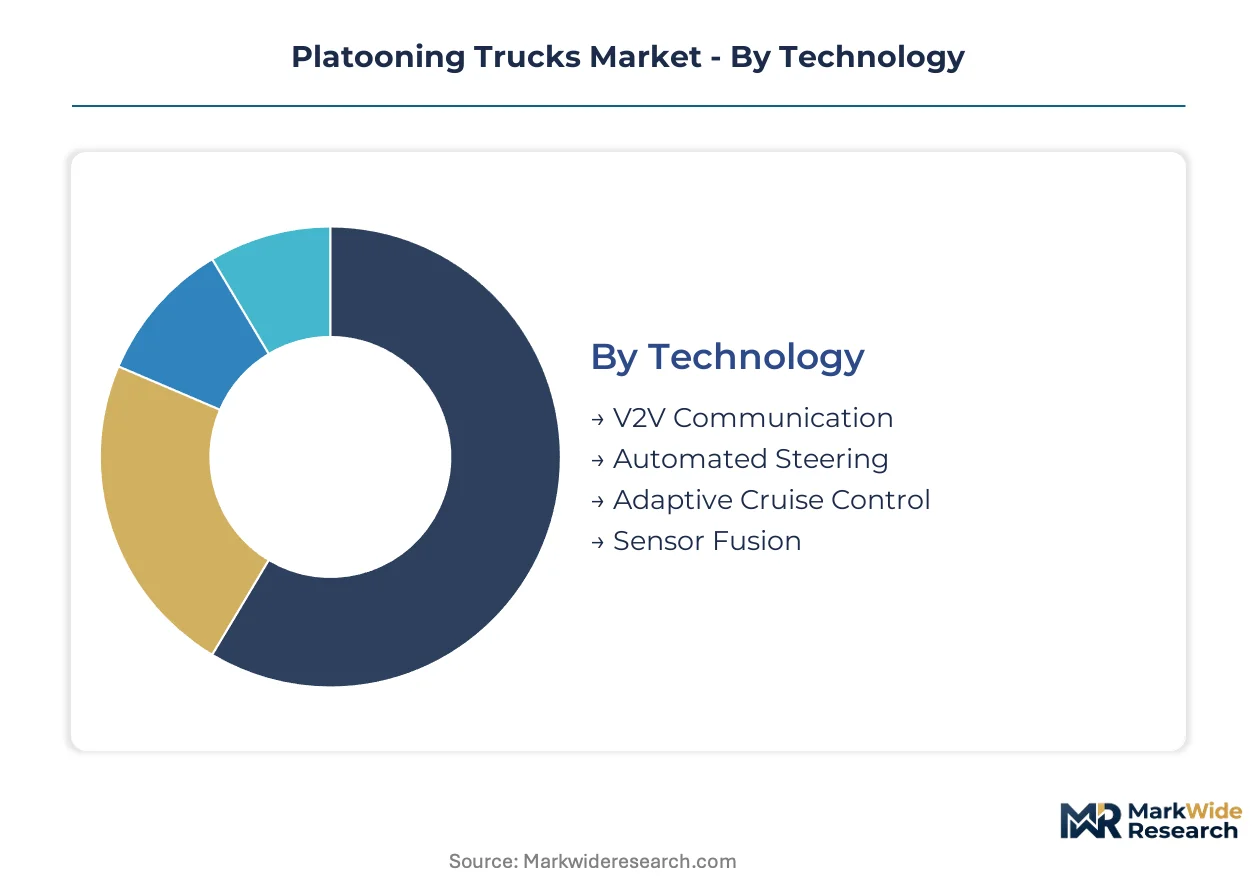
Platooning technology deployment varies sharply across operational contexts. Technology maturity, end-user sophistication, and vehicle specifications create distinct investment profiles that vendors must address separately.
Technology:
Mature V2V protocols coexist with emerging sensor fusion architectures, creating a bifurcated procurement landscape where fleet operators balance proven reliability against performance gains.
- V2V Communication:Dedicated short-range communication modules enable real-time data exchange between paired vehicles, maintaining gap consistency through standardized protocols. German logistics corridors between Rotterdam and Milan concentrate demand, driven by EU mandates for cooperative intelligent transport systems.
- Sensor Fusion:Lidar-radar-camera integration reduces false-positive braking events and enables tighter following distances. Parcel networks operating at highway speeds in the Netherlands and Belgium are early adopters, seeking fuel burn reductions that justify hardware costs within compressed payback windows.
- Automated Steering:Lane-keeping actuators handle lateral control during convoy operations.
- Adaptive Cruise Control:Cooperative variants synchronize acceleration and braking across vehicle pairs.
V2V Communication retains volume leadership; Sensor Fusion holds the steepest expansion curve.
End User:
Customer type determines procurement complexity, from integrated fleet operators seeking full-stack solutions to fragmented e-commerce players demanding modular deployments.
- Logistics Providers:Integrated parcel and less-than-truckload networks pursue cooperative automation to compress operating margins. Belgian and Dutch consolidation hubs exhibit particular urgency, as route density creates viable platooning economics.
- Fleet Operators:Asset-heavy hauliers with dedicated long-distance lanes deploy paired trucks across fixed corridors. Pressure from the EU F-Gas Regulation accelerates retrofit decisions for existing diesel fleets.
- E-commerce Companies:Last-mile and regional fulfillment networks represent emerging demand with distinct technical requirements.
- Transportation Services:Third-party haulage contractors face adoption barriers due to irregular route structures and asset fragmentation.
Logistics Providers command the largest addressable base; E-commerce Companies are climbing the fastest.
Application:
Route characteristics dictate technology configuration, with sustained highway exposure enabling maximum aerodynamic gains.
- Long-Distance Haulage:Extended highway segments at consistent speeds maximize drafting efficiency and fuel reduction. German freight corridors exhibit the densest deployment activity, supported by concentrated DSRC infrastructure investment.
- Freight Transportation:General cargo movement across mixed networks balances efficiency gains against operational flexibility requirements.
- Urban Delivery:Stop-start traffic patterns and intersection density limit platooning viability.
- Intermodal Transport:Port-to-rail terminal shuttles present specialized use cases with fixed schedules but short distances.
Long-Distance Haulage dominates current deployment; Freight Transportation is gaining share fastest.
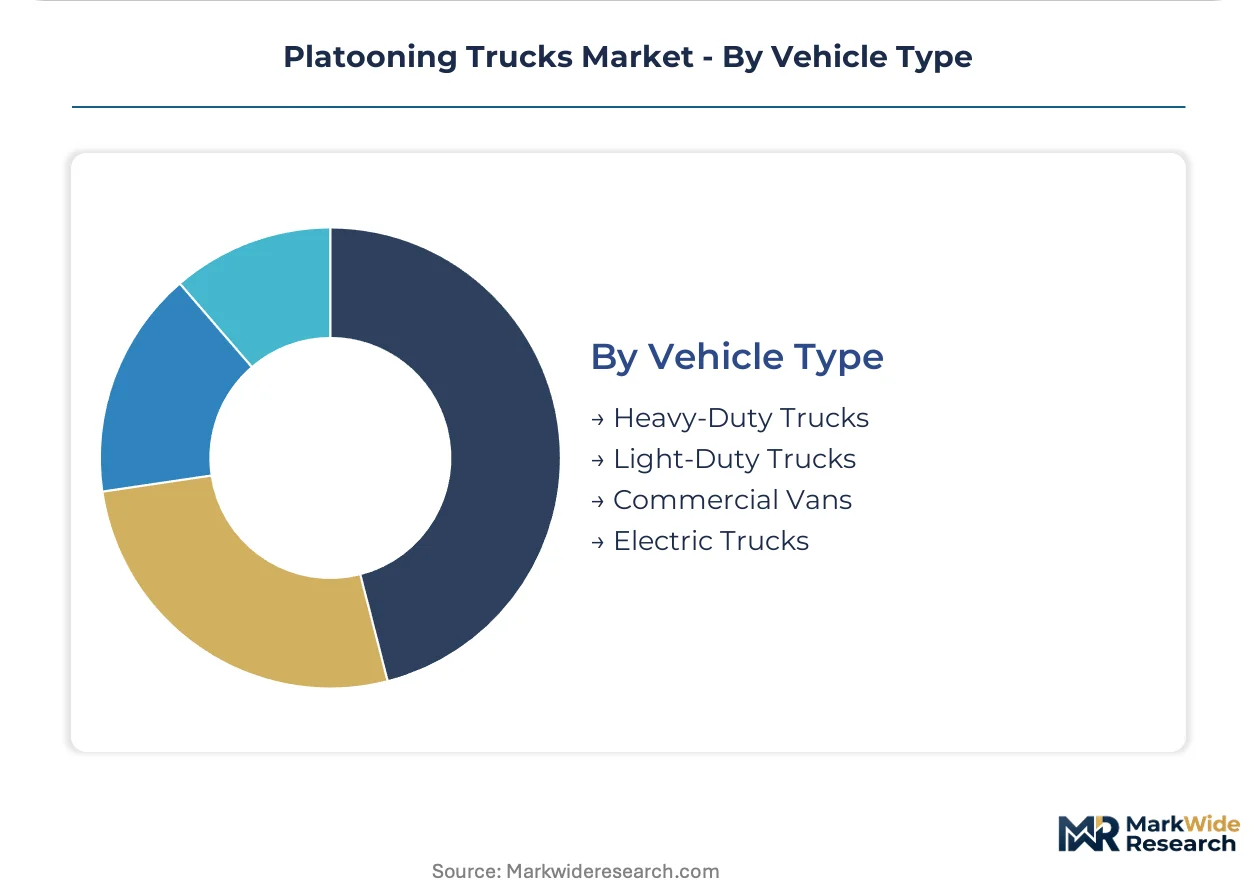
Vehicle Type:
Powertrain architecture and payload capacity create divergent integration pathways for cooperative automation systems.
- Heavy-Duty Trucks:Class 8 tractors with sleeper cabs dominate platooning pilots, as mass and frontal area maximize aerodynamic drafting benefits. Fleet procurement committees in Germany prioritize cooperative adaptive cruise control retrofits to meet tightening emission thresholds.
- Electric Trucks:Battery-electric platforms integrate cooperative automation to extend range per charge. Nordic freight corridors with sparse charging infrastructure exhibit concentrated interest, as energy consumption reductions address range anxiety directly.
- Light-Duty Trucks:Regional delivery applications with moderate payload requirements.
- Commercial Vans:Parcel final-mile operations where platooning offers limited utility due to route fragmentation.
Heavy-Duty Trucks anchor current volume; Electric Trucks are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Freight corridor density and regulatory harmonization determine platooning deployment viability more than fleet size alone. Countries with concentrated long-haul routes and aligned cooperative intelligent transport systems standards attract disproportionate technology investment. Export-oriented logistics networks in Northern Europe and North American manufacturing belts currently exhibit the tightest pilot-to-deployment conversion rates.
Germany
The Rotterdam-Milan freight corridor generates sustained platooning demand as logistics providers seek fuel efficiency gains across predictable highway segments. The KBA governs vehicle type approval for automated convoy systems under EU framework harmonization. Stuttgart and Munich host concentrated R&D clusters where Daimler Truck AG and Robert Bosch GmbH coordinate sensor module development with fleet operators.
United States
Interstate highway density between Dallas-Fort Worth and Atlanta supports commercial platooning pilots targeting parcel network efficiency. The NHTSA and FMCSA jointly administer on-highway testing permissions through coordinated rulemaking. Michigan's automotive testing corridors and California's freight technology validation zones attract multi-state fleet operators seeking regulatory clarity before scale deployment.
Netherlands
Port of Rotterdam throughput creates fixed-route shuttle demand ideal for paired-truck convoy operations. The country's national transport regulator aligns with EU cooperative intelligent transport systems deployment timelines. Eindhoven and Rotterdam logistics consolidation hubs concentrate less-than-truckload operators piloting sensor fusion configurations for European cross-border haulage.
Japan
Expressway freight volume between Tokyo and Nagoya supports dedicated platooning lane trials on designated segments. METI guidelines structure commercial testing permissions with specific safety performance thresholds. Chubu region manufacturing supply chains and Kanto distribution networks provide concentrated demand for cooperative adaptive cruise control integration with existing fleet assets.
Sweden
Nordic freight corridors with sparse charging infrastructure drive electric truck platooning interest for range extension. The Swedish Transport Agency coordinates with EU emission reduction frameworks for commercial vehicle certification. Gothenburg's automotive technology cluster anchors Volvo Group's automated convoy development programs targeting timber and retail freight networks.
Platooning Trucks Market Competitive Landscape
On the supply side, the industry is consolidating around integrated truck manufacturers with captive sensor development capabilities. Tiered competition separates full-stack OEMs controlling powertrain and automation architecture from modular component suppliers competing on certification speed. Strategic archetypes include vertically integrated truck builders, sensor module specialists, and cooperative software platform vendors. Dominant competitive moves encompass technology licensing partnerships between OEMs and component suppliers, plus geographic expansion of validation corridors to secure regulatory precedents.
Among European-based integrated manufacturers, Daimler Truck AG, Volvo Group, and Scania AB exemplify the full-stack archetype with in-house control over vehicle platforms and cooperative automation systems. Robert Bosch GmbH and Continental AG occupy the component specialist tier, supplying sensor modules and adaptive cruise control hardware across multiple OEM customer bases. Peloton Technology represents the cooperative software platform model, developing convoy coordination algorithms deployable across heterogeneous truck fleets. Toyota Motor Corporation anchors Asian participation through its commercial vehicle division's integration of platooning logic with hybrid powertrain architectures.
| Leading Market Players |
|---|
| Volvo Group |
| Daimler Truck AG |
| Scania AB |
| Continental AG |
| Peloton Technology |
| Robert Bosch GmbH |
| DAF Trucks |
| IVECO |
| Toyota Motor Corporation |
| Others |
Value Network & Pricing Analysis
Single-source dependency on southern German sensor module production creates simultaneous pricing tier compression and geographic vulnerability for fleet procurement committees. The F-Gas Regulation retrofit deadline tightens buyer negotiating timelines while concentrating supplier leverage, forcing logistics providers to accept premium pricing for certified hardware or risk compliance gaps.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with certification grade under EU MDR frameworks and volume scale as primary differentiation drivers. Cost compression in the standard tier is intensifying because parcel networks demand API-accessible performance data as standalone purchase criteria. Fleet operators with fixed-route density exhibit lowest price sensitivity; fragmented third-party haulage contractors face acute margin pressure.
Supply Chain Analysis
Extended payment terms from Tier 1 sensor suppliers to German module integrators reveal working capital stress rippling through the upstream. Manufacturing concentrates in Germany, the Netherlands, and Japan, with lidar components, radar substrates, and DSRC chipsets as critical dependencies. Single-source vulnerability around Bosch-controlled adaptive cruise control hardware creates chokepoint exposure. Distribution runs through OEM captive channels and specialized telematics integrators serving Belgian and Dutch less-than-truckload networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The platooning trucks market is entering a cyclical recovery phase as EU emission compliance deadlines force replacement demand across diesel-heavy fleets. Logistics corridor densification between Rotterdam and Milan provides the volume foundation sustaining this upswing.
For Market Incumbents: Build regulatory certification moats by accelerating MDR-aligned technical file repositories before notified body scrutiny tightens. Secure backward integration into lidar-radar fusion hardware to defend against modular software entrants. Prioritize capacity addition in Eindhoven and Stuttgart logistics clusters where route density justifies dedicated DSRC infrastructure investment.
For New Entrants and Emerging Players: Nordic electric truck corridors with sparse charging infrastructure represent underpenetrated territory where cooperative automation extends range per charge. Belgian parcel consolidation hubs remain underserved by sensor fusion configurations optimized for highway-speed parcel networks. Partner with route optimization software vendors to bypass OEM captive sales channels and capture data integration contracts directly.
For Investors and Strategic Acquirers: EU AI Act risk classification implementation reshapes the acquisition landscape by imposing documentation burdens that favor pre-certified sensor module portfolios. Five-to-ten year viability hinges on vendors controlling both hardware certification speed and cooperative software deployment flexibility. Target acquisition archetypes: mid-tier sensor fusion specialists with existing KBA validation relationships. Watch for NHTSA-FMCSA coordinated rulemaking clarity as the signal indicating North American scale-deployment readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| DSRC Infrastructure Partnership | Rotterdam-Milan corridor densification enables 12-meter gap pilot expansion with payback compression. |
| Sensor Module Certification Investment | MDR-aligned technical files streamline EU notified body approval timelines for adaptive cruise control hardware. |
| Electric Truck Platform Integration | Volvo Group's automated steering convergence with battery architectures addresses Nordic range anxiety directly. |
| Telematics API Unbundling | Parcel networks in Belgium and Netherlands now procure platooning performance data separate from maintenance contracts. |
| Cross-Border Protocol Harmonization | Dedicated short-range communication standardization reduces redundant hardware configurations for international haulage. |
Research Methodology
The analysis maps V2V communication protocols, sensor fusion architectures, automated steering systems, and adaptive cruise control modules, each validated through fleet procurement directors, OEM platform engineers, Tier 1 supplier account managers, and logistics corridor planners. Primary interview findings triangulate against customs trade data, KBA type approval filings, EU transport emission databases, and SEC disclosures from listed truck manufacturers. Bottom-up unit economics for corridor-specific deployments reconcile with top-down market sizing across the projection horizon.
Assumptions hold EU F-Gas Regulation compliance timelines fixed while varying lithium-ion cost trajectories and DSRC infrastructure rollout speeds. Segmentation dimensions include technology maturity tier, end-user integration depth, application route characteristics, and vehicle powertrain architecture. CAGRs derive from corridor-density weighted adoption curves and retrofit cycle analysis. Industry-specific inputs incorporate charging infrastructure density for electric truck variants and notified body certification queue lengths for sensor module approvals.
The forecast holds incumbent behavior within observed patterns; aggressive moves by battery-electric pure-play entrants or DSRC protocol challengers would shift outcomes. Macroeconomic freight volume contraction, regulatory delay in cross-border harmonization, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Heavy-Duty Trucks
Europe Medium & Heavy-Duty Truck Rental Market
Heavy-Duty Trucks
Truck Diagnostic Market
Heavy-Duty Trucks
Heavy-Duty Truck Axle Locking Actuator Components Market
Heavy-Duty Trucks
Full Truck Load (FTL) Market
Heavy-Duty Trucks
Middle East Refrigerated Truck Market
Heavy-Duty Trucks
Dump Trucks and Mining Trucks Market
Heavy-Duty Trucks
Global Vocational Truck Market
Heavy-Duty Trucks
Garbage Collection Trucks Market
Heavy-Duty Trucks
Global Snow Sweeper Truck Market
Heavy-Duty Trucks
Airport Catering Truck Market
Heavy-Duty Trucks
Global Connected Truck Market
Heavy-Duty Trucks
Global Oversized Cargo Transportation Market
Heavy-Duty Trucks
Saudi Arabia Refrigerated Truck Market
Heavy-Duty Trucks
North America Vacuum Truck Market
Heavy-Duty Trucks
Stacker Truck Market
Heavy-Duty Trucks
Europe Medium and Heavy-Duty Commercial Vehicles Market