
 Mining Truck Market | 2026-2036
Mining Truck Market Size, Share, and Industry Trends Forecast 2026-2036
Mining Truck Market Intelligence
The capital-intensity gap between tier-one OEMs and mid-tier challengers is collapsing as electrification R&D costs escalate and autonomous system development demands scale. Caterpillar Inc sustains its position through captive powertrain manufacturing and integrated autonomy stacks deployed across Pilbara and Carajás operations. Komatsu Ltd leverages its FrontRunner autonomous haulage system to anchor long-term fleet contracts with tier-one miners. BelAZ competes on extreme payload specialization, dominating the 400-ton-plus segment with its Belarus-built ultra-class rigid trucks.
Mining trucks are heavy-duty off-highway vehicles engineered for bulk material transport in surface and subterranean extraction environments, typically featuring frame ratings exceeding 100 tons gross vehicle weight and purpose-built suspension systems for unimproved haul roads. Their primary commercial purpose centers on minimizing cost-per-ton of material moved over multi-kilometer circuits from excavation face to processing infrastructure. Rigid trucks occupy the dominant share of open-pit deployments where high-volume, low-gradient haulage governs fleet economics, while electric trucks represent the fastest-expanding category as battery-electric and trolley-assist architectures displace pure diesel in emissions-regulated jurisdictions. The 201-400 ton load capacity band captures the deepest margin pools, balancing capital efficiency against the operational density that 400-ton-plus ultra-class units demand.
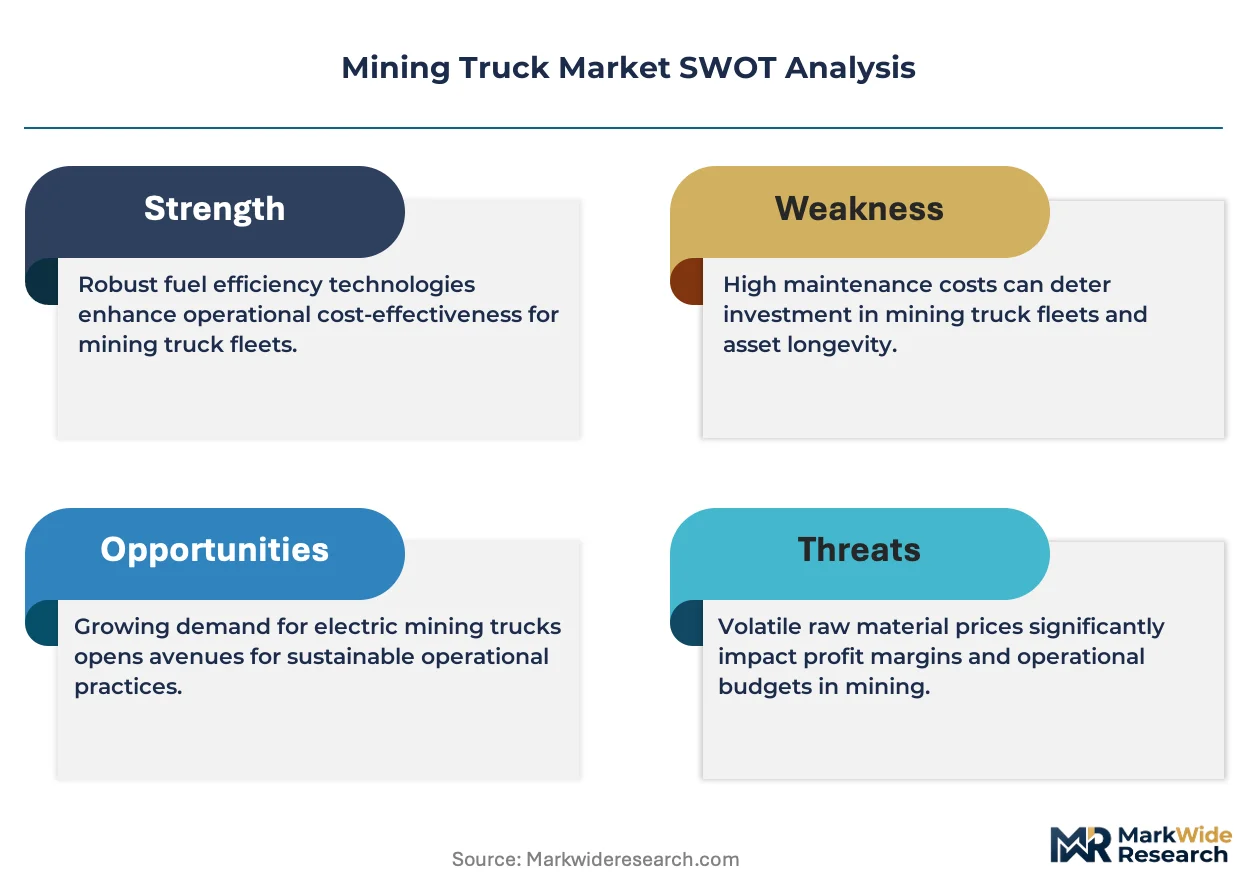
EPA Tier 4 Final and EU Stage V emission frameworks are forcing diesel powertrain redesigns and accelerating hybrid-electric adoption across North American and European-serving fleets. ISO 17757 autonomous machine safety standards and MSHA surface haulage regulations are reshaping procurement specifications, with compliance now prerequisite for market access in regulated mining jurisdictions. Stakeholders must weigh electrification capex against fuel cost trajectories and autonomy integration timelines when structuring fleet replacement cycles.
Market Dynamics
Autonomous haulage deployment is compressing replacement cycles and rewriting procurement specifications across surface mining operations, forcing OEMs to bundle hardware with perpetual software service agreements rather than discrete equipment sales.
Growth Catalysts
- Declining ore grades in Chilean copper:Lower mineral concentration requires moving larger waste volumes, expanding fleet counts and accelerating replacement timelines for ultra-class rigid trucks.
- EPA Tier 4 Final compliance deadlines:North American emission mandates are compelling diesel-electric hybrid retrofits and new powertrain architectures that extend equipment service life.
- Trolley-assist infrastructure expansion:Electrified haul road segments in Kazakhstan and South Africa are cutting fuel consumption by 50-90% on uphill gradients, validating capital-intensive grid investments.
Market Restraints
- Lithium-ion battery supply concentration:Cathode precursor refining clusters in the Democratic Republic of Congo and Indonesia create geopolitical exposure for battery-electric truck programs.
- Ultra-class tire supply oligopoly:Three manufacturers control 90% of 57-inch and larger tire production, creating 18-24 month order backlogs that constrain fleet expansion.
- EU Stage V retrofit complexity:Aftertreatment system integration into legacy 201-400 ton rigid frames demands structural redesigns that OEMs have deprioritized.
Strategic Opportunities
- Underpenetrated underground battery-electric segment:Narrow vein operations in Canada and Sweden lack purpose-built 50-ton electric haulers, creating white space for specialized entrants.
- Autonomous retrofit kits for incumbent fleets:ISO 17757-compliant perception and control packages can upgrade 2016-2020 vintage trucks without full replacement.
- Green hydrogen pilot corridors:Pilbara iron ore routes with fixed haul profiles suit fuel cell range and refueling economics, attracting government co-funding in Western Australia.
Industry Challenges
- Autonomy systems integration talent scarcity:Mining OEMs compete with automotive and defense sectors for embedded software engineers with ISO 26262 functional safety credentials.
- MSHA surface haulage certification timelines:New autonomous truck approvals require 12-18 months of documented operational data, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mining Truck Market |
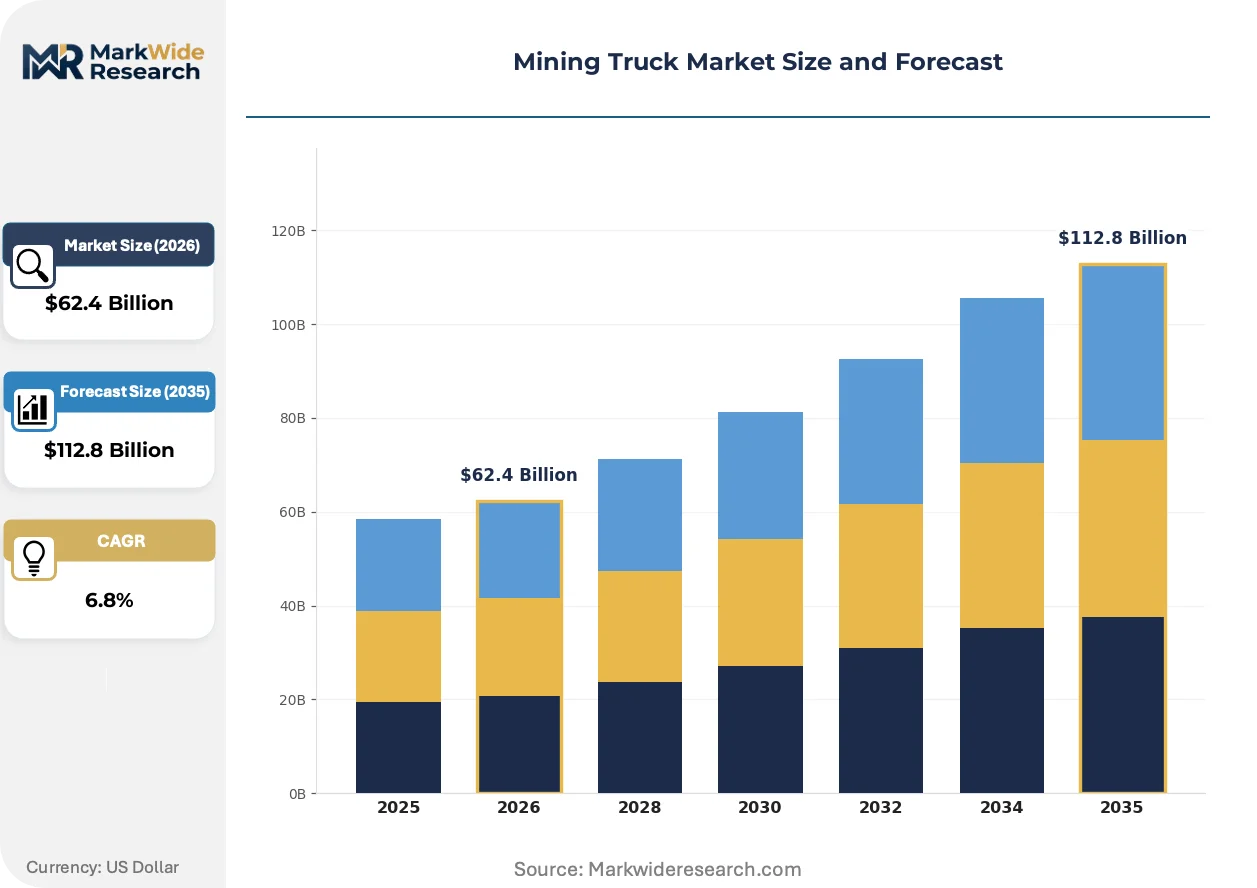
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $112.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Truck Type: Articulated Trucks, Rigid Trucks, Electric Trucks, Diesel Trucks Load Capacity: 50-100 Tons, 101-200 Tons, 201-400 Tons, 401+ Tons Application: Open-Pit Mining, Underground Mining, Quarrying, Infrastructure Development Engine Type: Tier 3, Tier 4, Hybrid, Gas |
| Companies Covered | BelAZ, Volvo Construction Equipment, Caterpillar Inc, XCMG Group, SANY Group, Komatsu Ltd, Hitachi Construction Machinery Co. Ltd, Terex Corporation, Liebherr Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mining Truck Market Strategic Shifts & Innovations
Powertrain electrification and machine autonomy are converging to redefine fleet economics, compressing the traditional 15-year replacement cycle and shifting value capture from hardware sales to integrated performance contracts.
Battery-electric architectures are fragmenting the historical diesel monopoly in surface mining. Trolley-assist systems on uphill haul segments now dominate greenfield Pilbara installations, while battery-swapping stations at crusher stations eliminate range anxiety for 200-ton class trucks. OEMs with captive cell supply chains capture margin pools that diesel-engine suppliers once controlled.
EU Stage V emission frameworks are forcing exhaust aftertreatment redesigns across European-serving fleets. Selective catalytic reduction and diesel particulate filter integration adds 800-1200 kilograms to powertrain mass, degrading payload capacity unless compensated through structural lightweighting. Western Australian operators with EU export exposure are accelerating hybrid-electric orders to bypass aftertreatment complexity.
Performance-based maintenance contracts are displacing time-and-materials service agreements across tier-one miner procurement departments. Komatsu and Caterpillar now bundle guaranteed availability percentages with autonomous haulage subscriptions, transferring operational risk from Pilbara and Carajás operators to OEM balance sheets. This compression of the traditional parts-and-service profit pool is visible in Chilean copper fleet renewals.
Mining Truck Market Segmentation
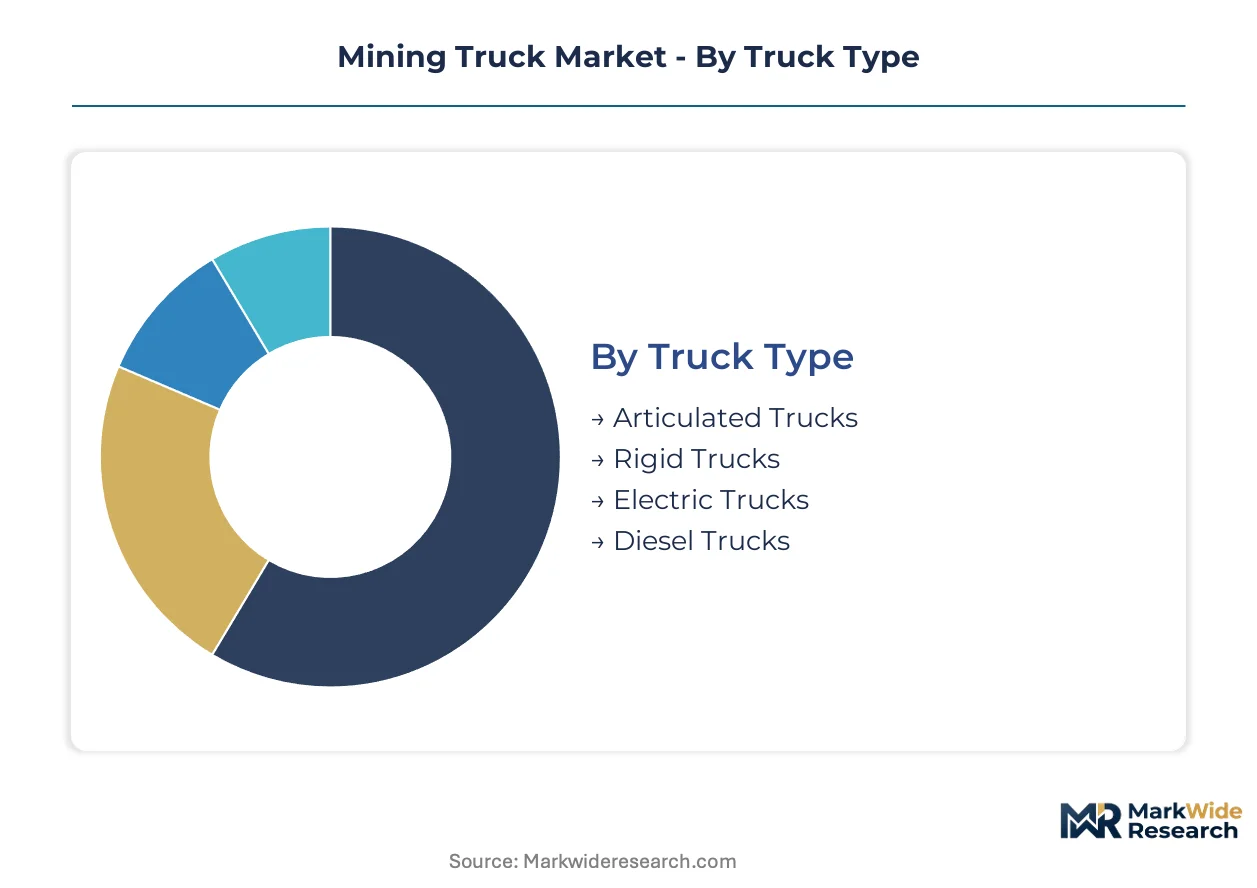
Segmentation in mining trucks reveals how electrification and autonomy are fragmenting historically unified demand pools. Fleet operators now specify powertrains, automation readiness, and payload bands as distinct procurement dimensions rather than bundled equipment categories.
Truck Type:
Electric trucks face the most acute substitution pressure as trolley-assist infrastructure and battery-swapping networks displace diesel architectures in regulated jurisdictions.
- Rigid Trucks:Frame-stressed designs with non-articulated chassis dominate open-pit copper and iron ore circuits where high-volume, low-gradient haulage governs economics. Pilbara operators in Western Australia specify rigid platforms for autonomous retrofit compatibility.
- Electric Trucks:Battery-electric and trolley-assist architectures eliminate diesel particulate filter complexity while cutting fuel costs on electrified haul segments. Kazakhstan and South African mines validate these systems on uphill gradients where grid connection density justifies capital deployment.
- Articulated Trucks:Pivot-steered configurations with oscillating hitches navigate sub-15% grades in underground vein operations and quarry development where maneuverability trumps payload density.
- Diesel Trucks:Conventional mechanical-driveline units persist in frontier mining districts lacking grid infrastructure or facing extreme ambient temperatures that degrade lithium-ion performance.
Rigid trucks retain volume leadership; electric trucks hold the steepest expansion curve.
Load Capacity:
Cost tier differentiation separates capital-efficient mid-payload units from ultra-class behemoths demanding dedicated haul road geometry and maintenance infrastructure.
- 201-400 Tons:The operational sweet spot balancing capital efficiency against fleet density requirements, these units capture the deepest margin pools in Chilean copper and Pilbara iron ore. Tier-one miners standardize on this band for autonomous fleet homogeneity.
- 401+ Tons:Ultra-class rigid trucks engineered for minimum cost-per-ton on 5+ kilometer haul circuits require 30-meter haul road width and specialized tire maintenance facilities. BelAZ dominates this segment through extreme payload specialization.
- 101-200 Tons:Mid-tier capacity serving smaller open-pit gold and phosphate operations where fleet flexibility outweighs unit-scale economies.
- 50-100 Tons:Entry-scale rigid and articulated units for quarrying and contractor mining where rapid site relocation governs equipment selection.
The 201-400 ton band anchors procurement volume; 401+ ton units are climbing the fastest as ore grade decline forces waste volume expansion.
Application:
Geographic deployment patterns concentrate autonomous haulage investment in surface extraction while underground operations lag electrification readiness.
- Open-Pit Mining:Surface extraction environments with bench-sequenced excavation favor rigid truck fleets on fixed circuits where autonomy ROI compounds across 24-hour operations. Western Australia's Pilbara district governs global specification trends.
- Underground Mining:Confined vein operations with ventilation constraints drive demand for battery-electric haulers that eliminate diesel particulate exposure. Canadian narrow-vein copper and Swedish iron ore operations lack purpose-built 50-ton electric alternatives.
- Quarrying:Limestone and aggregate extraction favors smaller articulated fleets with rapid cycle times and minimal infrastructure investment.
- Infrastructure Development:Earthmoving contractors deploy rental and leased mining-class trucks for dam construction and port expansion with seasonal utilization patterns.
Open-pit mining commands the dominant equipment base; underground mining is gaining share fastest as ventilation regulations tighten.
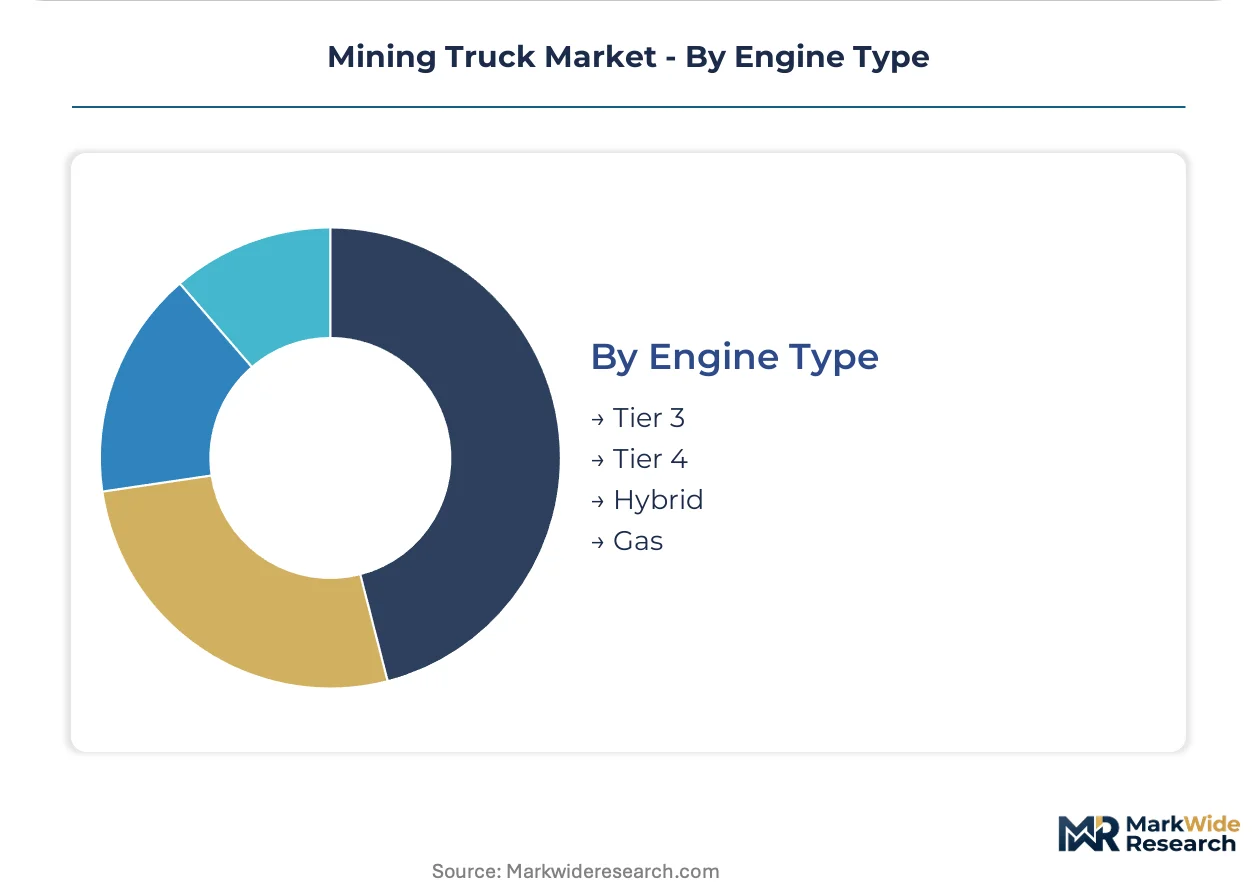
Engine Type:
Regulatory compliance tiers are forcing technology transitions faster than natural replacement cycles, compressing residual value for legacy powertrains.
- Tier 4:EPA Tier 4 Final and EU Stage V aftertreatment systems with selective catalytic reduction and diesel particulate filters add 800-1200 kilograms to powertrain mass. North American and European-serving fleets face compressed retrofit timelines.
- Hybrid:Diesel-electric architectures with onboard battery buffers capture regenerative braking energy on downhill segments and enable trolley-assist connection on uphill grades. Western Australian operators bypass aftertreatment complexity through hybrid orders.
- Tier 3:Pre-emission-control diesel engines persist in non-regulated mining jurisdictions and secondary equipment markets where capital constraints override compliance requirements.
- Gas:Compressed natural gas and liquefied natural gas conversions for captive fueling infrastructure at remote mine sites with stranded gas resources.
Tier 4 configurations dominate regulated market procurement; hybrid systems are expanding most quickly as autonomy integration demands electrical architecture readiness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Western Australian operators command pricing leverage over OEMs through autonomous fleet standardization, while Chilean copper miners absorb premium equipment costs as declining ore grades force volume expansion. This asymmetry concentrates procurement power in iron ore districts while fragmenting negotiating positions in base metal extraction.
Australia
Pilbara iron ore operators specify autonomous-ready rigid trucks for 24-hour haulage circuits, with Western Australia state regulations mandating ISO 17757 compliance for surface autonomous vehicles. Perth-based engineering clusters coordinate fleet standardization across BHP and Rio Tinto operations, compressing OEM margins through consolidated procurement.
Chile
Copper extraction in the Atacama Desert drives ultra-class truck demand as ore grades fall below 0.6%, with Chile's Ministry of Mining enforcing tailings dam safety protocols that accelerate fleet replacement cycles. Antofagasta and Calama mining districts host concentrated haulage operations where BelAZ and Caterpillar compete for 400-ton contracts.
China
Domestic coal and rare earth expansion in Inner Mongolia and Shanxi Province sustains demand for 200-ton class rigid trucks, with MIIT emission standards tightening diesel powertrain requirements. Xuzhou and Changsha manufacturing clusters supply both captive mines and export markets across Central Asia.
United States
Copper porphyry operations in Arizona and Nevada face EPA Tier 4 Final compliance deadlines that favor diesel-electric hybrid architectures, with MSHA surface haulage regulations extending autonomous certification timelines. Phoenix and Elko serve as equipment distribution hubs for Southwestern open-pit fleets.
Kazakhstan
Trolley-assist infrastructure on uphill haul segments at copper and coal mines cuts fuel consumption dramatically, with national grid expansion programs supporting electrified haul road investment. The Karaganda and Pavlodar mining basins validate capital-intensive grid connections through operational cost savings.
Mining Truck Market Key Industry Players
Concentration sits with integrated full-line OEMs that bundle autonomous systems with captive powertrain manufacturing. The vendor base stratifies across three tiers: multinational machinery conglomerates with mining divisions, specialized ultra-class rigid truck fabricators, and emerging Chinese construction equipment groups expanding into mining applications. Competitive intensity centers on M&A activity targeting autonomy software capabilities and strategic partnerships for battery supply chain security.
Within the integrated multinational tier, Caterpillar Inc and Komatsu Ltd exemplify full-stack autonomy providers that anchor long-term fleet contracts through guaranteed availability subscriptions. BelAZ occupies a distinct position as a state-backed specialist in extreme payload rigid trucks, representing the ultra-class pure-play archetype against diversified competitors. These three anchors illustrate how competitive positioning fragments between autonomy-integrated service models and payload-maximizing specialization.
| Leading Market Players |
|---|
| BelAZ |
| Volvo Construction Equipment |
| Caterpillar Inc |
| XCMG Group |
| SANY Group |
| Komatsu Ltd |
| Hitachi Construction Machinery Co. Ltd |
| Terex Corporation |
| Liebherr Group |
| Others |
Cost & Logistics Intelligence
EPA Tier 4 Final compliance deadlines gate both supplier qualification and price differentiation simultaneously, as OEMs must certify powertrain architectures to access North American fleets while emission-control integration costs stratify equipment tiers. Tier-one miners in Western Australia and Chile absorb premium pricing for autonomous-ready platforms, whereas mid-tier operators in Kazakhstan and South Africa face compressed budgets that favor retrofit solutions over new-build procurement.
Pricing Analysis
The customization-premium spread spans 25-40% above base configuration for autonomous retrofit compatibility and trolley-assist electrical architecture. Three-tier pricing structure across premium, standard, and economy levels reflects autonomy integration depth, powertrain electrification readiness, and bundled service contract duration. Cost compression in the 101-200 ton band intensifies because Chinese OEMs expand export capacity with competitive base pricing. Junior miners and contractor fleets exhibit highest price sensitivity, while Pilbara iron ore operators prioritize guaranteed availability over unit acquisition cost.
Supply Chain Analysis
Inventory cycles for 57-inch and larger ultra-class tires now extend 18-24 months, constraining fleet expansion timelines regardless of equipment availability. Manufacturing concentration centers on China, Japan, and the United States for final assembly, while cathode precursor refining for battery-electric programs clusters in Indonesia and the Democratic Republic of Congo. Supply chain vulnerability rests on single-source dependency for specialized tire compounds and rare earth magnet materials. Distribution runs through OEM-owned service depots in Perth, Phoenix, and Antofagasta, with aftermarket parts flowing through certified dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The mining truck sector sits in early-cycle expansion as trolley-assist infrastructure validates capital-intensive electrification and autonomous haulage programs rewrite procurement specifications. Battery-electric adoption in surface mining remains below 15% penetration, creating substantial runway for technology substitution.
For Market Incumbents: Secure captive battery supply agreements through upstream partnerships with cathode precursor refiners in Indonesia and the Democratic Republic of Congo. Lock in long-term tire supply contracts with the three dominant ultra-class manufacturers to insulate against 18-24 month order backlogs that constrain fleet delivery commitments.
For New Entrants and Emerging Players: Anchor in the underpenetrated underground battery-electric segment, specifically purpose-built 50-ton haulers for Canadian narrow-vein copper and Swedish iron ore operations. Target autonomous retrofit kits for 2016-2020 vintage fleets as the fastest path to revenue without competing head-to-head against integrated OEM service contracts.
For Investors and Strategic Acquirers: EU Stage V emission mandates reshape the acquisition landscape by compressing residual value for legacy diesel platforms and elevating hybrid-electric specialists. Focus diligence on autonomy software capabilities and ISO 17757 compliance documentation as durable competitive moats. Watch lithium-ion cell supply contract renegotiations as the inflection signal for margin compression or expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Trolley-Assist Infrastructure Deployment | Validates electrified haul road economics in Kazakhstan and South African copper belts. |
| Autonomous Retrofit Kit Development | Upgrades 2016-2020 vintage fleets without full replacement capital expenditure. |
| Battery Supply Chain Integration | Captures margin pools previously controlled by diesel engine suppliers. |
| Ultra-Class Tire Manufacturing Partnership | Resolves 18-24 month order backlogs constraining 400-ton-plus fleet expansion. |
| Green Hydrogen Pilot Corridor | Attracts Western Australian government co-funding for Pilbara iron ore routes. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with fleet managers, maintenance directors, OEM procurement teams, and aftermarket service heads; and secondary validation through customs/trade data, SEC 10-K filings, mining equipment registration databases, and MSHA surface haulage compliance records. Bottom-up unit economics modeling triangulated against top-down market sizing across truck type, load capacity, application, and engine type segmentation dimensions.
Across the analysis window, volume and value outputs reflect integration of replacement cycle dynamics, ore grade decline trajectories, and emission compliance timelines. CAGRs derive from weighted average of equipment shipment forecasts and service contract revenue recognition patterns. Key inputs include autonomous haulage adoption curves in Pilbara operations and trolley-assist infrastructure buildout schedules in Kazakhstan.
Decision-makers should treat outputs as directional under assumptions of sustained copper demand and stable lithium-ion supply chains; material deviation in either would warrant model refresh. Specific risks include MSHA certification timeline extensions for autonomous platforms and geopolitical disruption to cathode precursor supply. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Commercial Vehicles
Waste or Garbage Collection Vehicle Market
Commercial Vehicles
Indonesia Box Truck Market
Commercial Vehicles
Commercial Vehicle Calibration Market
Commercial Vehicles
Refrigerated Vans Market
Commercial Vehicles
Europe Light Commercial Vehicle Trailer Market
Commercial Vehicles
Cryogenic Road Tankers Market
Commercial Vehicles
Compact Utility Vehicles Market
Commercial Vehicles
Philippines Commercial Vehicles Market
Commercial Vehicles
Tank Car Market
Commercial Vehicles
Asia-Pacific Commercial Vehicles Market
Commercial Vehicles
Commercial Truck Trailer Market
Commercial Vehicles
Commercial Vehicle Steering Column Market
Commercial Vehicles
Mini Truck Market
Commercial Vehicles
UAE Commercial Vehicles Market
Commercial Vehicles
Heavy Haulage Trucks Market
Commercial Vehicles
Utility Vehicle Market