
 Small Bore Connectors Market | 2026-2036
Small Bore Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Small Bore Connectors Market Outlook
Aftermarket service revenue for legacy connector refurbishment is narrowing as hospitals shift capital toward disposable, compliance-ready inventory. BD sustains dominant manufacturing scale across North American health systems. Elcam Medical specializes in ISO 80369-compliant bio-compatible designs for neonatal and oncology segments. B. Braun anchors European hospital supply chains through vertically integrated polymer-to-sterile-packaging operations.
Small bore connectors are precision-molded fluid interface components, typically ranging from 1.6 mm to 6.2 mm in diameter, engineered from polypropylene, silicone, or stainless steel to prevent misconnection hazards in pressurized medical and laboratory lines. Their primary purpose is to ensure leak-free, mechanically secure transfer of liquids or gases between devices, tubing sets, and patient access points while eliminating cross-threading risks that caused historical sentinel events. Single-use polypropylene connectors lead volume in hospital fluid delivery applications where sterilization economics favor disposability over reprocessing, while silicone variants command premium positioning in peristaltic pump circuits requiring biocompatibility and flex fatigue resistance. Stainless steel segments occupy durable industrial automation and laboratory equipment niches where autoclave cycles and chemical exposure exceed polymer tolerance thresholds.
FDA enforcement of ISO 80369 dimensional and performance standards shapes product development timelines and market access for US manufacturers, while EMA adoption through the EU Medical Device Regulation tightens conformity assessment pathways for European entrants. China's NMPA alignment with GB standards for small-diameter medical connectors is accelerating domestic substitution programs and import qualification burdens. Stakeholders must monitor regulatory divergence between FDA-recognized consensus standards and emerging national variants in India and Brazil to avoid redundant testing protocols and delayed market authorization.
Market Dynamics
ISO 80369 compliance mandates are compressing product development cycles while hospital procurement consolidators demand single-use bio-compatible connectors that eliminate reprocessing liability.
Growth Catalysts
- FDA ISO 80369-3 enforcement:Enteral feeding misconnection prevention rules are accelerating hospital replacement of legacy Luer fittings with non-interconnectable designs across US acute care networks.
- Neonatal intensive care unit expansion:Specialized low-dose fluid delivery systems in Germany and the United States require ultra-miniaturized 1.6 mm connectors with validated bio-compatibility.
- Peristaltic pump silicone adoption:Oncology drug compounding centers are specifying platinum-cured silicone connectors for flex fatigue resistance in 24-hour infusion cycles.
Market Restraints
- Medical-grade polymer supply concentration:Polypropylene resin for single-use connectors depends on Gulf Coast petrochemical complexes vulnerable to hurricane disruption.
- ISO 80369-7 dimensional tolerances:Luer lock legacy compatibility requirements force dual-tooling investments that extend breakeven timelines for new product families.
- Stainless steel substitution threat:Industrial automation fluid lines are migrating to corrosion-resistant alloys that outlast polymer connectors in autoclave-intensive environments.
Strategic Opportunities
- China NMPA GB standard alignment:Domestic substitution programs are opening qualification pathways for locally manufactured ISO 80369-compliant connectors in tier-one city hospital systems.
- Home infusion therapy expansion:Self-administered biologic delivery is creating demand for patient-safe connectors with intuitive mechanical encoding.
- EMA MDR Article 10 technical documentation:Conformity assessment streamlining for bio-compatible materials is reducing time-to-market for European entrants with established polymer-to-sterile packaging control.
Industry Challenges
- Micro-molding precision engineering talent:Tolerance control below 0.05 mm for 1.6 mm bore connectors requires specialized mold flow simulation expertise concentrated in southern Germany and Massachusetts medical device clusters.
- Legacy Luer inventory integration:Hospital supply chains must maintain parallel stocking during multi-year transition periods, complicating just-in-time logistics and expiration management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Bore Connectors Market |
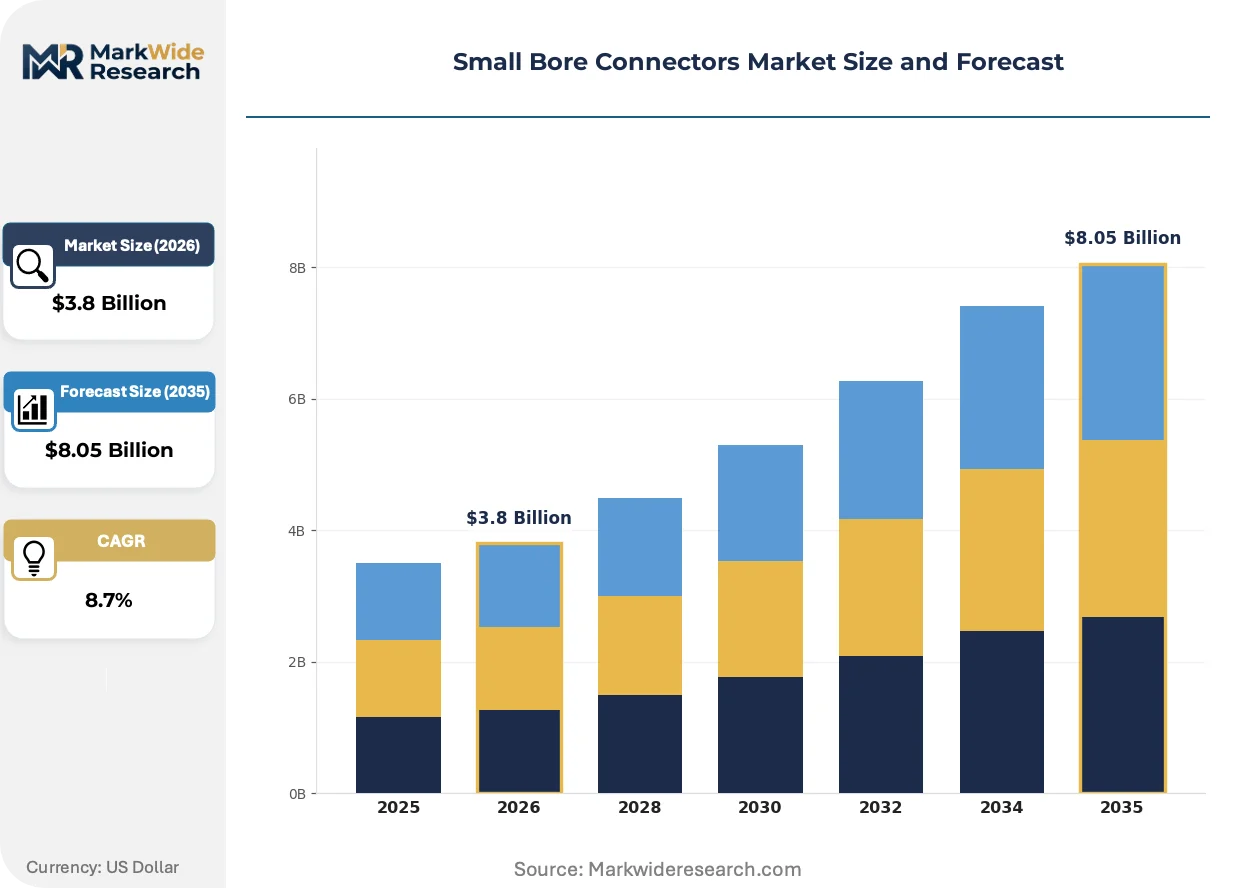
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Single-Use, Reusable, Bio-compatible, Customizable Material: Polypropylene, PVC, Silicone, Stainless Steel Application: Medical Devices, Laboratory Equipment, Industrial Automation, Fluid Transfer End User: Hospitals, Clinics, Research Labs, Manufacturing Facilities |
| Companies Covered | Baxter International Inc., B. Braun, BD, ICU Medical Inc., Merit Medical Systems, Inc., Smiths Medical, Nordson Corporation, Elcam Medical, NeoMed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Bore Connectors Market Strategic Shifts
Connector intelligence is embedding traceability and anti-counterfeiting directly into fluid interface hardware, shifting competitive advantage from mechanical precision to data-layer integration.
RFID-enabled small bore connectors are digitizing supply chain authentication and bedside verification workflows. US health system procurement departments are piloting these devices in high-value oncology biologic infusion lines. The technology is digitizing inventory reconciliation from warehouse receipt through patient administration, compressing documentation labor and diversion risk simultaneously.
EMA MDR Article 120 transition timelines are forcing connector manufacturers to rebuild technical documentation for legacy products. European notified bodies are extending review queues for bio-compatibility testing protocols. German hospital supply chains are responding by qualifying dual-source suppliers with pre-submitted MDR technical files to avoid single-source exposure.
Consolidated procurement through regional hospital networks is displacing distributor-mediated purchasing for standard connector SKUs. US group purchasing organizations are mandating ISO 80369-3 compliance as a minimum qualification threshold. This concentration is most visible in the southeastern United States, where multi-hospital systems are consolidating fluid delivery contracts under single-source agreements with direct manufacturer relationships.
Small Bore Connectors Market Segmentation
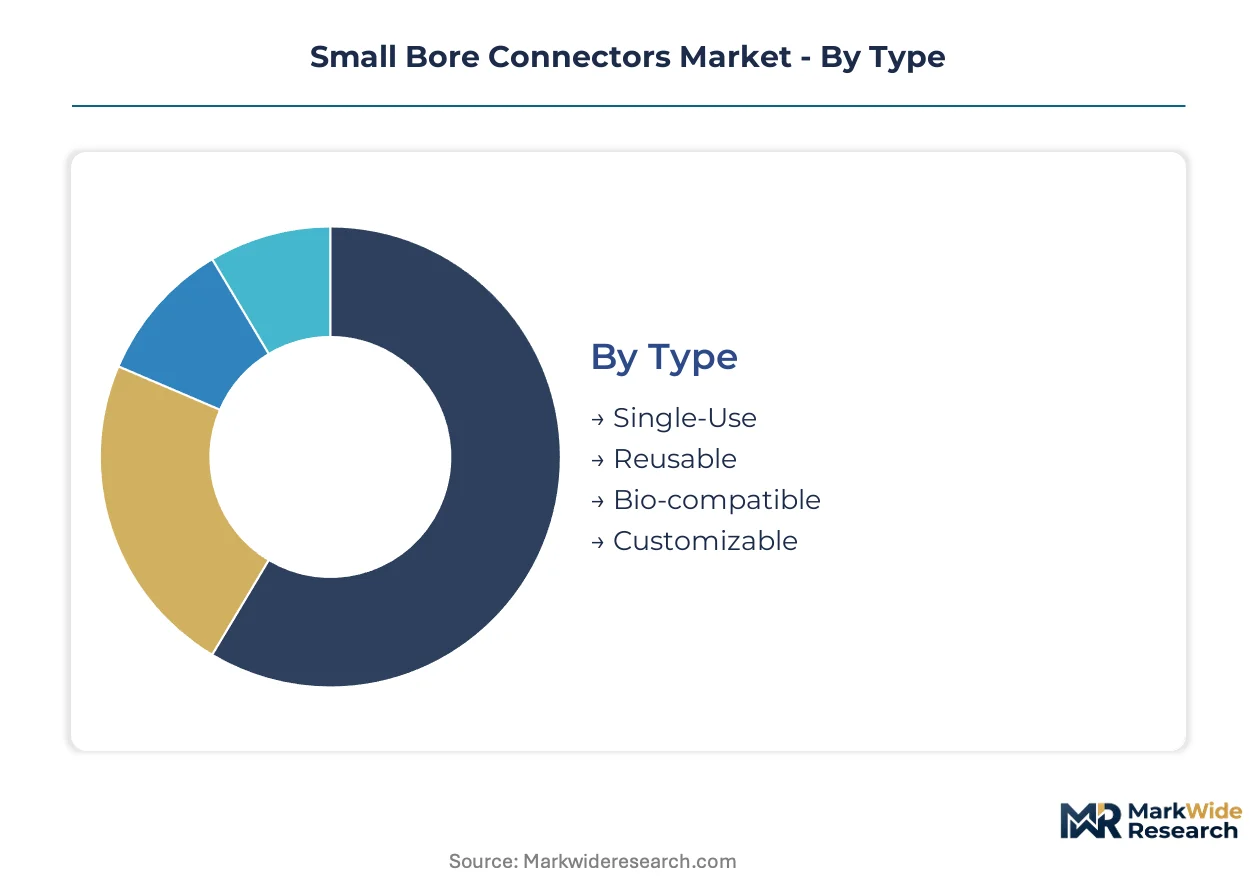
Small bore connector purchasing splits sharply between regulated healthcare environments demanding compliance documentation and industrial buyers prioritizing durability cycles. Procurement patterns diverge by sterilization economics, bio-compatibility requirements, and misconnection risk tolerance across these four dimensions.
Type:
Mature single-use formats dominate hospital volume while emerging bio-compatible variants capture oncology and neonatal premium positioning.
- Single-Use:Polypropylene connectors molded for one-time fluid delivery dominate acute care procurement. US hospital group purchasing organizations mandate ISO 80369-3 compliance as baseline qualification, compressing legacy Luer inventory.
- Bio-compatible:Platinum-cured silicone connectors engineered for 24-hour infusion cycles resist flex fatigue in peristaltic pump circuits. German oncology compounding centers specify these for biologic drug delivery where material extractables testing exceeds USP Class VI standards.
- Reusable:Stainless steel variants withstand autoclave cycles in industrial automation fluid lines where polymer degradation accelerates replacement costs.
- Customizable:Patient-specific mechanical encoding for home infusion therapy requires mold-flow simulation expertise concentrated in Massachusetts medical device clusters.
Single-use connectors handle the majority of throughput; bio-compatible variants are expanding most quickly on share.
Material:
Cost tiers separate commodity polymers from premium elastomers and corrosion-resistant alloys.
- Polypropylene:Medical-grade resin from Gulf Coast petrochemical complexes feeds high-volume disposable production. Hurricane disruption vulnerability concentrates supply risk for North American manufacturers.
- Silicone:Platinum-cured grades command 3-4x polypropylene pricing for validated bio-compatibility in neonatal intensive care units. Flex fatigue resistance justifies premium in 24-hour chemotherapy infusion protocols.
- PVC:Legacy material faces EMA MDR scrutiny over plasticizer migration in long-dwell applications.
- Stainless Steel:316L grade occupies laboratory and industrial niches where chemical exposure exceeds polymer tolerance thresholds.
Polypropylene anchors volume economics; silicone climbs the fastest on margin contribution.
Application:
Customer type stratifies between regulated patient care and non-regulated equipment supply.
- Medical Devices:Enteral feeding misconnection prevention drives FDA-enforced replacement of legacy Luer fittings across US acute care networks. ISO 80369 dimensional tolerances force dual-tooling investments.
- Laboratory Equipment:Automated liquid handling systems specify stainless steel for autoclave-intensive protocols in analytical chemistry workflows.
- Industrial Automation:Corrosion-resistant alloys outlast polymers in pressurized process lines where chemical compatibility trumps bio-compatibility.
- Fluid Transfer:General-purpose connectors bridge medical and industrial specifications with intermediate validation requirements.
Medical device applications concentrate regulatory scrutiny; laboratory equipment gains share fastest in aftermarket service contracts.
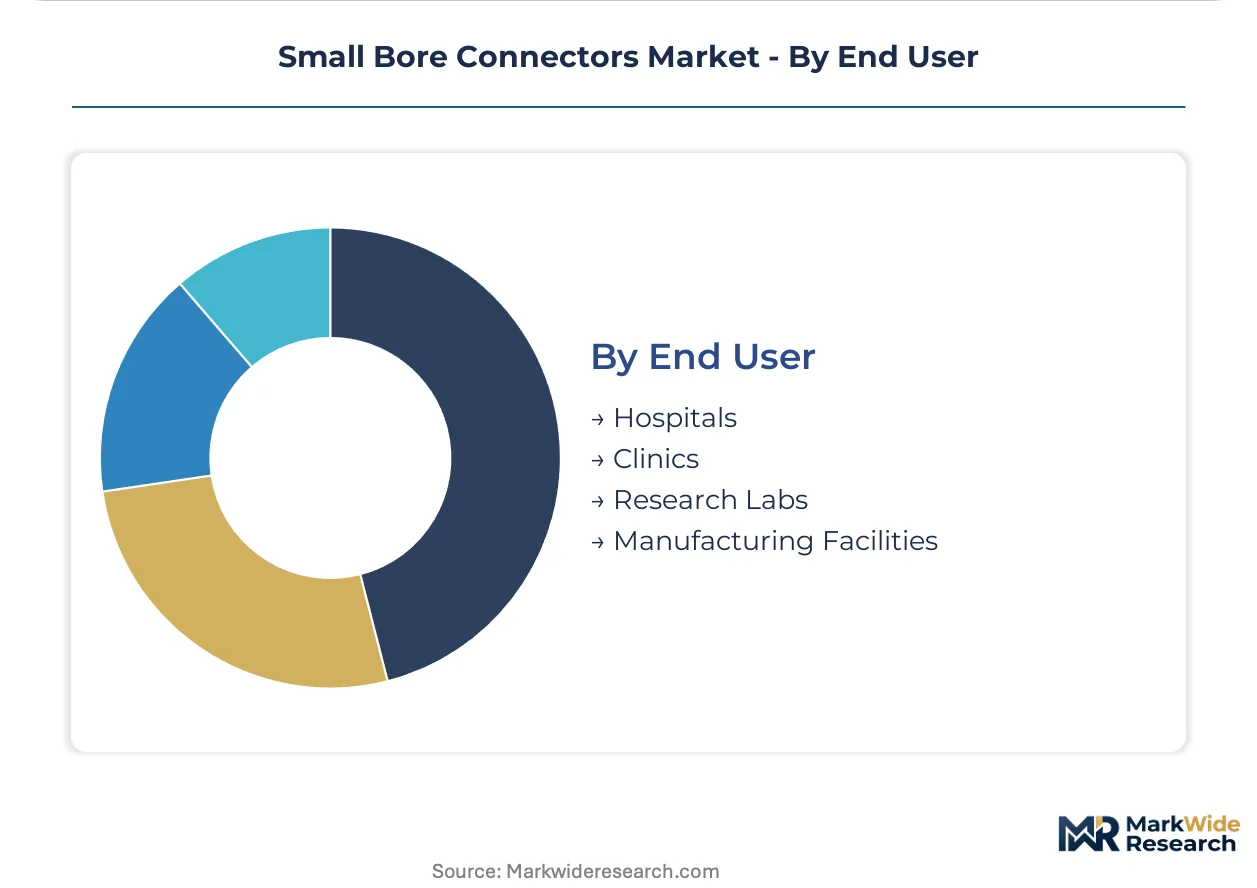
End User:
Procurement consolidation reshapes distributor relationships across care settings.
- Hospitals:Regional network consolidation in the southeastern United States displaces distributor-mediated purchasing for standard SKUs. Direct manufacturer contracts now dominate fluid delivery procurement.
- Research Labs:Academic and pharmaceutical R&D facilities specify customizable connectors for protocol-specific fluid handling with extended validation documentation.
- Clinics:Outpatient settings lag acute care in ISO 80369 transition timelines, maintaining parallel legacy inventory.
- Manufacturing Facilities:Industrial buyers prioritize total cost of ownership over unit price, favoring stainless steel durability in high-cycle environments.
Hospitals command the steepest volume concentration; research labs show the strongest pricing inelasticity for specialized configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement departments in Germany and the United States exhibit the lowest price elasticity, prioritizing ISO 80369 compliance and bio-compatibility validation over unit cost. Chinese health systems demonstrate higher elasticity, driving domestic substitution programs that compress margins for import-dependent suppliers.
United States
FDA enforcement of ISO 80369-3 enteral feeding standards is accelerating hospital replacement of legacy Luer fittings across acute care networks. Group purchasing organizations in the southeastern United States now mandate compliance as a baseline qualification threshold. Massachusetts medical device clusters concentrate mold-flow simulation expertise for micro-molding precision below 0.05 mm tolerance.
Germany
Neonatal intensive care unit expansion drives demand for ultra-miniaturized 1.6 mm connectors with validated bio-compatibility in oncology and pediatric segments. EMA MDR Article 10 conformity assessment pathways are tightening technical documentation requirements for European market access. Southern Germany's medical device engineering clusters supply specialized precision-molding capabilities to tier-one city hospital systems.
China
NMPA alignment with GB standards for small-diameter medical connectors is accelerating domestic substitution programs in tier-one city hospital procurement. Import qualification burdens are compressing market access timelines for foreign manufacturers. Yangtze River Delta manufacturing hubs are scaling ISO 80369-compliant production to serve regional health system consolidation.
Japan
PMDA medical device review timelines for bio-compatible materials are shaping product development cycles for peristaltic pump silicone connectors. Platinum-cured grades command premium positioning in 24-hour chemotherapy infusion protocols. Kanto region medical device clusters concentrate expertise in flex fatigue resistance validation for oncology drug compounding centers.
India
CDSCO medical device rules are tightening registration requirements for imported small bore connectors while domestic manufacturing incentives expand. Hospital procurement in metropolitan centers shows accelerating ISO 80369 awareness but lags acute care transition timelines. Maharashtra and Gujarat medical device manufacturing corridors are building polymer-to-sterile packaging capabilities to serve regional demand.
Small Bore Connectors Market Competitive Environment
Capability concentration sits with specialized precision-molding tier; scale advantage sits with diversified health system suppliers. The market structure shows moderate consolidation around vertically integrated polymer-to-packaging operations and precision-engineering specialists. Three archetypes dominate: diversified health system suppliers with captive hospital contracts, specialized bio-compatibility-focused manufacturers, and industrial fluid handling diversifiers. Competitive moves center on M&A for sterile packaging capabilities and capacity expansion in ISO 80369-compliant product families.
Among diversified health system suppliers, BD and B. Braun occupy positions anchoring North American and European hospital procurement respectively. Elcam Medical exemplifies the specialized bio-compatibility tier, with its focus on ISO 80369-compliant designs for neonatal and oncology segments representing the precision-engineering archetype. These three companies illustrate the competitive spectrum from scale-driven supply chain integration to niche clinical application expertise.
| Leading Market Players |
|---|
| Baxter International Inc. |
| B. Braun |
| BD |
| ICU Medical Inc. |
| Merit Medical Systems, Inc. |
| Smiths Medical |
| Nordson Corporation |
| Elcam Medical |
| NeoMed |
| Others |
Value Chain & Pricing Dynamics
Hurricane exposure at Gulf Coast petrochemical complexes compresses polypropylene resin availability for medical-grade connector production, forcing tiered spreads between spot-priced commodity batches and contracted pharmaceutical-grade supply while reshaping inventory strategies across North American health system procurement departments.
Pricing Analysis
Aftermarket service contracts for legacy Luer refurbishment once anchored lifetime value, but hospital procurement departments now prioritize per-unit transactional pricing for single-use ISO 80369-compliant inventory. Pricing stratifies across platinum-cured silicone premium tiers, validated bio-compatible mid-tiers, and commodity polypropylene economy levels. Cost compression in standard polypropylene connectors is intensifying because Gulf Coast resin volatility feeds through to molders. Group purchasing organizations in the southeastern United States exhibit lowest price sensitivity; tier-two city hospitals in China show highest elasticity.
Supply Chain Analysis
Medical-grade polypropylene resin feeds from United States Gulf Coast complexes, German petrochemical corridors, and Yangtze River Delta refineries. Platinum-cured silicone elastomers draw from Japanese specialty chemical producers and Massachusetts medical device clusters. Single-source vulnerability concentrates in hurricane-prone Texas-Louisiana resin infrastructure. Distribution runs through regional hospital network consolidators displacing traditional distributor mediation for standard SKUs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro-molding precision engineering talent below 0.05 mm tolerance control represents the critical scarcity constraining expansion in neonatal and oncology connector segments, with mold-flow simulation expertise concentrated in southern Germany and Massachusetts clusters limiting qualified supplier proliferation.
For Market Incumbents: Build captive sterile packaging capabilities as a procurement-lock moat against emerging regional challengers. Anchor hospital system contracts through direct manufacturer relationships in southeastern United States consolidated networks. Add ISO 80369-7 dual-tooling capacity in Massachusetts medical device corridors to compress replacement cycle capture. Defend against Chinese domestic substitution by pre-submitting EMA MDR technical files for European dual-source qualification. For New Entrants and Emerging Players: Pursue home infusion therapy segments where patient-safe mechanical encoding requirements outpace incumbent R&D bandwidth. Target tier-two Chinese city hospitals where NMPA GB standard alignment creates qualification pathways for locally manufactured bio-compatible variants. Enter through customizable connector prototyping services for research labs demanding protocol-specific validation documentation. For Investors and Strategic Acquirers: The market sits at a regulatory-transition phase that favors precision-engineering specialists with pre-cleared MDR technical files. Five-to-ten year viability hinges on sterile packaging integration depth rather than molding scale alone. Acquire mold-flow simulation boutiques in southern Germany or Massachusetts clusters. Watch FDA ISO 80369-3 enforcement intensity as inflection indicator for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 80369 Compliance Certification | EMA MDR Article 10 pathways reduce time-to-market for European entrants with established documentation. |
| RFID-Enabled Connector Development | US health system oncology biologic lines pilot digitized authentication compressing diversion risk. |
| Platinum-Cured Silicone Capacity Expansion | German oncology compounding centers specify validated extractables testing exceeding USP Class VI. |
| Regional Hospital Network Direct Contracts | Southeastern United States GPO consolidation displaces distributor mediation for fluid delivery SKUs. |
| Micro-Molding Talent Acquisition | Massachusetts medical device clusters concentrate sub-0.05 mm tolerance control expertise. |
Study Parameters
A standing panel of hospital procurement directors, biomedical engineers, GPO contracts managers, and polymer resin procurement leads provided ongoing calibration across the study period. Primary interviews with neonatal intensive care unit clinicians and oncology drug compounding technicians combined with secondary validation against FDA 510(k) filings, EMA MDR technical documentation databases, hospital procurement contract registries, and ISO 80369 standards committee records. Bottom-up segment sizing triangulated against top-down health system expenditure flows.
Scenario-bracketing anchored the analytical framework across the projection horizon, with sensitivity testing for regulatory enforcement intensity and resin supply disruption events. Segmentation dimensions modeled include connector type, material grade, application setting, and end-user procurement consolidation tier. CAGRs derived from fitted growth curves applied to validated base-year estimates, with cross-reference to peristaltic pump silicone adoption rates and home infusion therapy expansion trajectories.
Macroeconomic conditions sit as an overlay; deviation in Gulf Coast hurricane frequency, medical-grade polymer spot pricing, or FDA enforcement cadence would shift the trajectory. Forecasts reflect documented assumptions regarding ISO 80369 transition timelines and hospital capital allocation priorities. Cross-checking against GPO contract award databases and notified body MDR review queue lengths is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Connector for PV System Market
Connectors
Global Wired Interface Market
Connectors
SATA Connector Market
Connectors
Filtered Connectors Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Circular Connectors Market
Connectors
High-Reliability Connectors Market
Connectors
3C Electronics Precision Connectors Market
Connectors
PCI-E Connectors Market
Connectors
Mexico Connector Market
Connectors
India Connector Market
Connectors
Global Board to Board (BTB) Connectors Market
Connectors
DIN Connectors Market
Connectors
Latin America Connector Market
Connectors
Automotive Data Connectors Market
Connectors
Circular Waterproof Connector Market