
 Circular Waterproof Connector Market | 2026-2036
Circular Waterproof Connector Market Size, Share, and Industry Trends Forecast 2026-2036
Circular Waterproof Connector Market Intelligence
IP67 certification under IEC 60529 is rotating as the baseline qualification threshold, filtering out suppliers lacking validated test protocols. TE Connectivity leverages vertical integration across contact plating and overmolding to sustain cost discipline at volume. Hirose Electric anchors its position through precision miniaturization for consumer electronics and transportation suppliers. Amphenol LTW dominates marine-equipment specifications with salt-spray-resistant metal shell connectors.
A circular waterproof connector is a cylindrical electromechanical interconnect engineered with elastomeric seals and threaded or bayonet coupling to maintain electrical continuity under liquid immersion and particulate exposure, typically rated from IP67 through IP69K depending on seal geometry and housing material. Its primary purpose is to secure signal and power transmission in environments where moisture, dust, or pressure washing threatens standard connector integrity. Pin connectors and socket connectors constitute the mature volume core, while IP68 and IP69K waterproof technologies command expanding margin pools as renewable energy systems and railway signaling applications specify deeper submersion resistance. PCB mount connectors are gaining share in industrial automation where space constraints and vibration tolerance intersect.
FCC equipment authorization rules shape electromagnetic compatibility requirements for connectors deployed in US telecommunication infrastructure, while REACH and RoHS frameworks in Europe restrict hazardous substances in plating chemistries and housing polymers. The EU Green Deal and associated Ecodesign regulations are pressing energy producers and transportation suppliers to specify recyclable materials and extended lifecycle ratings in procurement tenders. Stakeholders must monitor how evolving IP rating interpretations across ISO and IEC test houses reshape competitive qualification timelines and regional market access.
Market Dynamics
Defense procurement cycles and IEC 60529 certification tightening are compressing supplier qualification timelines while concentrating volume among vertically integrated manufacturers with captive test facilities.
Growth Catalysts
- Renewable energy infrastructure:Offshore wind and solar farm deployments specify IP68-rated interconnects for submersion resistance in marine and washdown environments.
- REACH and RoHS frameworks:European hazardous substance restrictions are filtering out suppliers dependent on legacy plating chemistries and non-compliant housing polymers.
- Railway signaling modernization:Electrification projects across Germany, France, and Japan specify sealed connectors for vibration-tolerant trackside equipment.
Market Restraints
- Copper and gold price volatility:Contact plating materials constitute 15-25% of connector bill-of-materials, exposing margins to commodity swings.
- Specialized elastomer supply concentration:Fluorosilicone seal production concentrates among Japanese and German chemical suppliers, creating single-source vulnerability.
- IP69K test protocol complexity:High-pressure steam-jet certification requires capital-intensive test chambers that smaller manufacturers cannot justify.
Strategic Opportunities
- India industrial automation:PLI scheme incentives for electronics manufacturing are attracting connector assembly investments to serve domestic automotive and machinery demand.
- Wireless power convergence:Integration of inductive charging coils into sealed connector housings opens marine and medical equipment applications.
- Ecodesign procurement mandates:EU Green Deal tender requirements for recyclable materials and extended lifecycle ratings favor suppliers with validated circularity protocols.
Industry Challenges
- Cross-functional engineering talent scarcity:Combined expertise in electromechanical design, polymer science, and IEC test methodology concentrates among senior engineers at established suppliers.
- Legacy system integration friction:Retrofitting IP67+ connectors into existing industrial equipment requires custom adapter development and field validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circular Waterproof Connector Market |
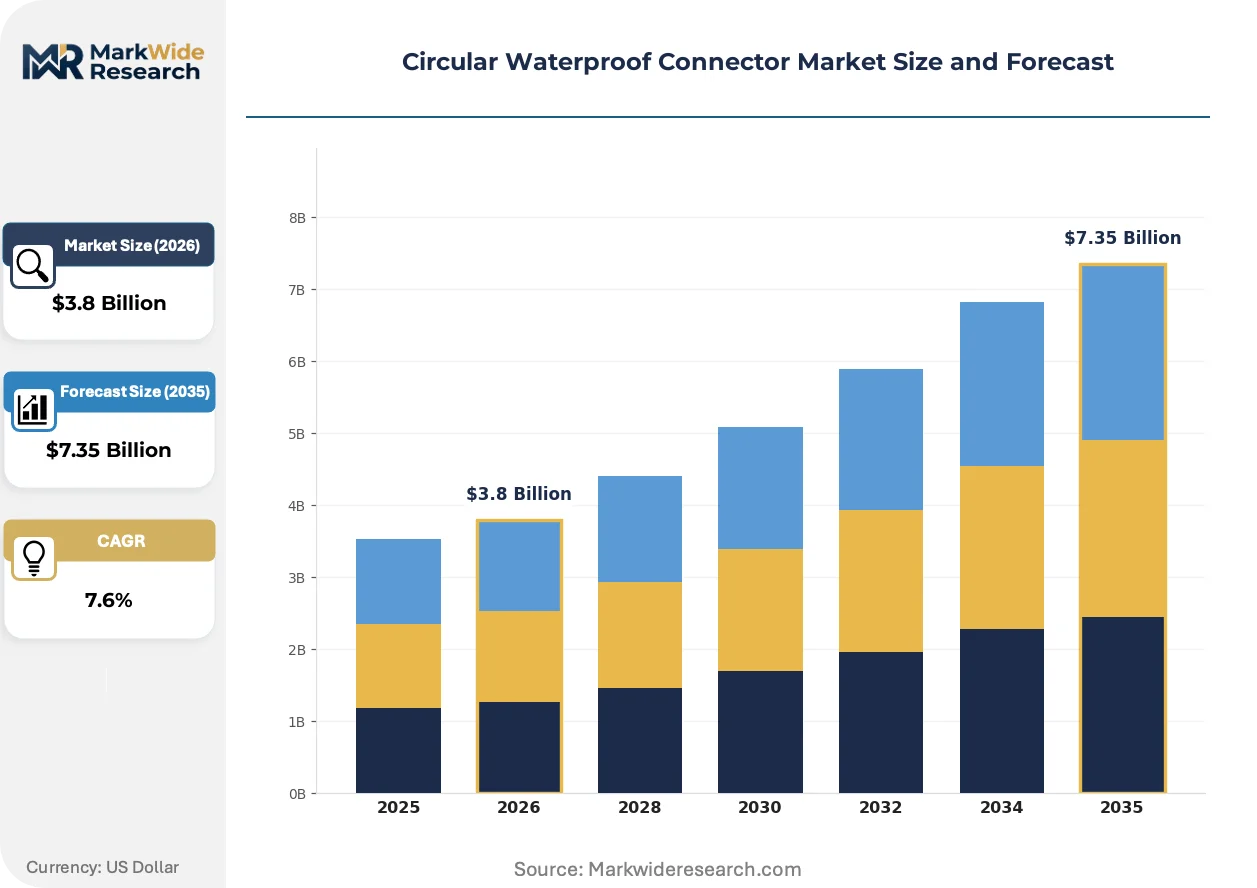
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.35 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pin Connectors, Socket Connectors, Cable Mount Connectors, PCB Mount Connectors, Inline Connectors Technology: IP67 Waterproof, IP68 Waterproof, IP69K Waterproof, Sealed Connectors, Metal Shell Connectors Application: Marine Equipment, OEM Manufacturing, Renewable Energy Systems, Industrial Automation, Railway Signaling End User: Telecommunication Providers, Defense Contractors, Consumer Electronics Makers, Energy Producers, Transportation Suppliers |
| Companies Covered | Hirose Electric, HARTING Technology Group, Molex, JST, Amphenol LTW, Amphenol, Switchcraft, Legrand, TE Connectivity, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circular Waterproof Connector Market Strategic Shifts & Innovations
Connector architecture is fragmenting into modular subsystems as end-users demand field-repairable seals and interchangeable contact inserts without full cable replacement.
Hybrid metal-polymer shell construction is decomposing the traditional trade-off between electromagnetic shielding and weight reduction. Aerospace and drone manufacturers specify aluminum-core housings with thermoplastic overmolding to achieve 40% mass reduction versus all-metal designs. This convergence is compressing the addressable market for pure brass and stainless steel shell suppliers.
FCC equipment authorization rules are tightening electromagnetic compatibility documentation for connectors deployed in US telecommunications infrastructure. The revised testing protocols extend qualification timelines by 8-12 weeks for non-compliant submissions. Suppliers serving 5G small cell and fiber-to-the-home deployments are restructuring regulatory affairs teams to manage parallel FCC and CE marking tracks.
Specification-driven procurement is consolidating purchasing authority among tier-one automotive and industrial OEMs. Buyers now mandate pre-validated IP rating test reports from IEC-recognized laboratories rather than accepting manufacturer self-certification. This behavioral shift is raising barriers for mid-tier suppliers lacking established relationships with TÜV, SGS, or UL test houses, particularly in German and Japanese supply chains.
Circular Waterproof Connector Market Segmentation
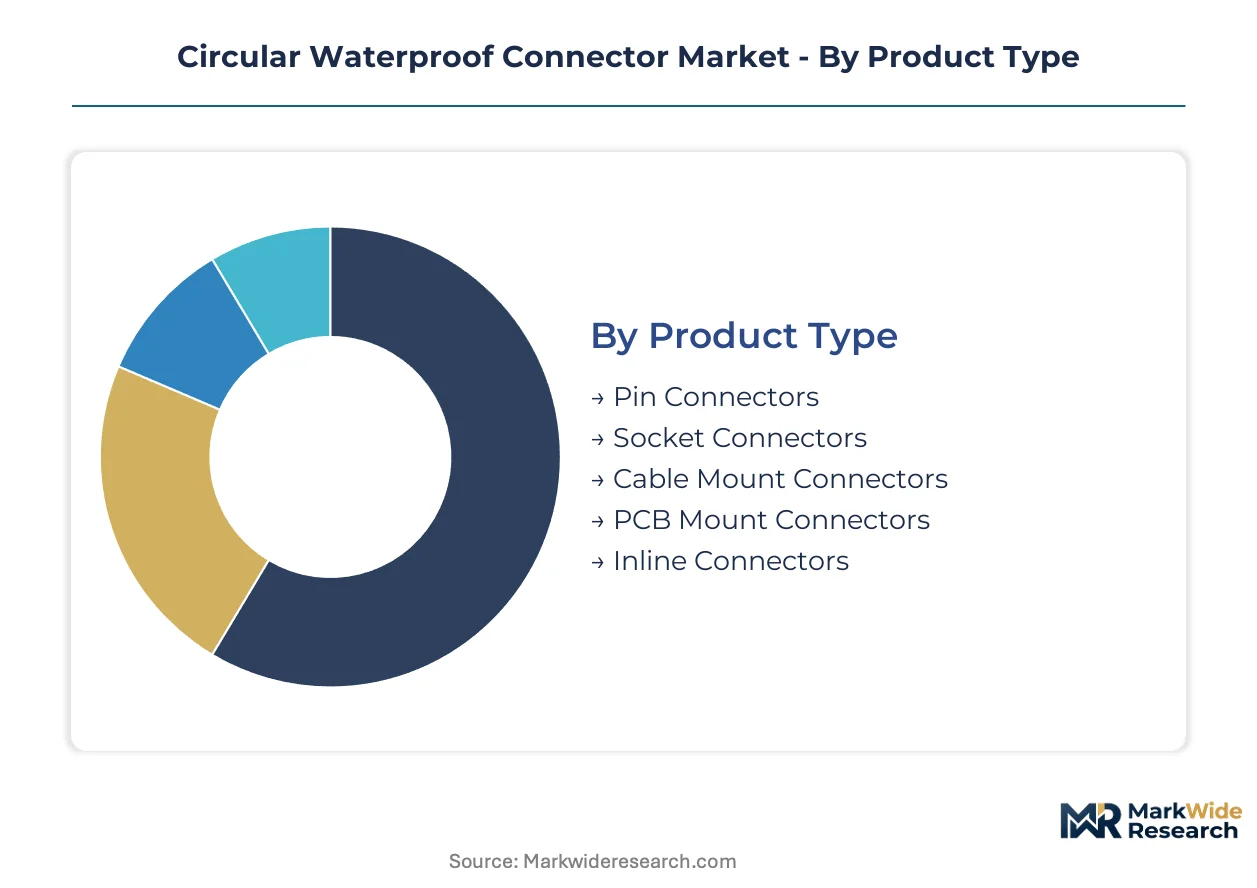
Segmentation in the circular waterproof connector market reveals how specification tiers, certification grades, and end-use environments fragment procurement patterns. Buyers sort suppliers across four intersecting dimensions: physical form factor, ingress protection rating, deployment setting, and customer industry vertical.
Product Type:
Pin connectors and socket connectors anchor domestic production volumes in Germany and Japan, while cable mount and inline variants concentrate in export-led manufacturing across Southeast Asia. PCB mount connectors split between captive consumption by industrial automation OEMs and merchant market supply to contract manufacturers.
- Pin Connectors:Male contact inserts with crimp or solder termination dominate legacy industrial equipment retrofits. Demand concentrates in German automotive supplier parks where IP67-rated variants serve engine bay harness assemblies facing thermal cycling and pressure washing.
- Socket Connectors:Female receptacles with panel-mount or free-hanging configurations constitute the mating half of circular interconnect pairs. Japanese consumer electronics and transportation suppliers specify miniaturized versions with sub-10mm shell diameters for space-constrained applications.
- Cable Mount Connectors:Field-attachable designs with screw-terminal or insulation-displacement contacts enable on-site assembly without specialized tooling. Energy producers in offshore wind deployments favor these for turbine nacelle harness repairs.
- PCB Mount Connectors:Right-angle and vertical headers with through-hole or surface-mount terminations integrate directly into printed circuit assemblies. Industrial automation controller manufacturers in Stuttgart and Shenzhen specify vibration-tolerant locking mechanisms.
- Inline Connectors:Cable-to-cable joining devices with environmental sealing enable harness extension and repair without panel penetration. Marine equipment OEMs specify these for deck-mounted sensor networks exposed to salt spray and UV degradation.
Pin and socket connectors command the established base. The steepest expansion runs through PCB mount connectors.
Technology:
Cost tiers stratify sharply by certification grade, with IP67-rated products serving price-sensitive industrial automation and IP68/IP69K variants capturing premium positioning in marine and food-processing equipment.
- IP67 Waterproof:Dust-tight construction with temporary immersion resistance to one meter depth represents the baseline qualification threshold. German automotive and machinery OEMs now mandate this rating as minimum viable for new platform designs.
- IP68 Waterproof:Extended submersion ratings with manufacturer-specified depth and duration parameters serve renewable energy and marine applications. Offshore wind developers in the North Sea specify these for inter-array cable junction boxes.
- IP69K Waterproof:High-pressure steam-jet resistance for washdown environments in food processing and heavy equipment. Test protocol complexity limits qualified suppliers, compressing effective supply base to vertically integrated manufacturers with captive chambers.
- Sealed Connectors:General environmental protection without specific IP rating certification serves cost-constrained applications where particulate exclusion matters more than liquid immersion. Agricultural machinery manufacturers specify these for cab-interior electronics.
- Metal Shell Connectors:Brass, aluminum, or stainless steel housings with elastomeric seals provide electromagnetic shielding and mechanical durability. Defense contractors specify salt-spray-resistant variants for naval shipboard systems.
IP67-rated products anchor volume shipments. IP68 configurations are climbing the fastest as offshore infrastructure deployment accelerates.
Application:
Volume concentration varies by customer procurement maturity, with railway signaling and renewable energy specifying certified interconnects through formal tender processes while OEM manufacturing absorbs merchant-market supply through distributor channels.
- Marine Equipment:Salt-spray-resistant interconnects for vessel electronics, navigation systems, and deck machinery. Norwegian and Greek shipyards specify metal shell connectors with 500-hour minimum salt spray test performance.
- OEM Manufacturing:Captive consumption by original equipment builders across automotive, industrial, and consumer product categories. Contract manufacturers in Vietnam and Mexico assemble IP67-rated harnesses for export to US and European brand owners.
- Renewable Energy Systems:Solar inverters, wind turbine controls, and battery storage interconnects requiring UV resistance and thermal cycling tolerance. German and Danish offshore wind developers drive specification upgrades to IP68 for subsea cable terminations.
- Industrial Automation:Programmable logic controllers, motor drives, and sensor networks in factory environments. Japanese machinery builders specify M12 and M23 circular formats with vibration-locking threads for robotic applications.
- Railway Signaling:Trackside equipment, rolling stock controls, and tunnel communication systems requiring fire-smoke toxicity compliance. French and Japanese railway operators mandate EN 45545-2 certified materials alongside IP ratings.
OEM manufacturing commands the established base. Renewable energy systems are gaining share fastest as electrification infrastructure deployment accelerates.
End User:
Customer type determines procurement channel structure, with defense contractors and telecommunication providers qualifying suppliers through multi-year certification programs while consumer electronics makers rotate vendors based on cost and miniaturization capability.
- Telecommunication Providers:5G small cell, fiber-to-the-home, and data center infrastructure requiring FCC and CE electromagnetic compatibility compliance. US carriers specify pre-tested connector assemblies to compress field deployment timelines.
- Defense Contractors:Ruggedized field equipment with MIL-STD qualification requirements and supply chain security protocols. Sealed interconnect procurement concentrates among domestic suppliers with cleared facility access.
- Consumer Electronics Makers:Wearables, action cameras, and portable power systems demanding sub-miniature form factors. Japanese and South Korean brands specify precision-molded connectors with 0.4mm pitch contacts.
- Energy Producers:Utilities and independent power developers specifying extended lifecycle ratings for generation and grid infrastructure. EU Green Deal tender requirements press these buyers toward recyclable material specifications.
- Transportation Suppliers:Automotive tier-ones, rail system integrators, and aerospace subcontractors with IATF 16949 or AS9100 quality mandates. German automotive supplier parks concentrate demand for IP67+ rated interconnects.
Transportation suppliers command the established base. Energy producers represent the steepest expansion trajectory as grid modernization and renewable deployment accelerate procurement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense contractors and industrial automation OEMs concentrate procurement authority in Germany, Japan, and the United States, with certification requirements from IEC, FCC, and national defense agencies filtering supplier access across export markets.
Germany
Automotive supplier parks in Stuttgart and Munich drive IP67+ specification upgrades for engine bay harness assemblies. REACH and RoHS frameworks from ECHA restrict hazardous substances in plating chemistries. The Baden-Württemberg industrial cluster concentrates demand for vibration-tolerant PCB mount connectors serving robotic applications.
Japan
Consumer electronics and transportation suppliers specify miniaturized connectors with sub-10mm shell diameters for space-constrained devices. METI oversees JIS standards alignment with IEC 60529 certification protocols. The Kanto region around Tokyo anchors precision molding capabilities for 0.4mm pitch contact assemblies.
United States
Telecommunication providers and defense contractors qualify suppliers through multi-year certification programs for 5G infrastructure and ruggedized field equipment. FCC equipment authorization rules tighten electromagnetic compatibility documentation requirements. The Southeast manufacturing corridor absorbs contract assembly investments to serve domestic automotive and machinery demand.
China
Industrial automation controller manufacturers in Shenzhen specify vibration-tolerant locking mechanisms for factory sensor networks. MIIT coordinates GB standards alignment with international ingress protection test protocols. The Yangtze River Delta concentrates export-oriented connector assembly serving European and North American brand owners.
India
Electronics manufacturing incentives under the PLI scheme attract connector assembly investments to serve domestic automotive and machinery demand. BIS oversees mandatory certification for industrial electrical components. The Maharashtra-Gujarat industrial corridor hosts emerging production capacity for IP67-rated harness assemblies.
Circular Waterproof Connector Market Key Industry Players
Player mix skews toward vertically integrated manufacturers with captive test facilities and specialized miniaturization specialists serving consumer electronics. The supply base concentrates among three strategic archetypes: scale-driven diversified interconnect houses, precision-focused Japanese specialists, and marine-environment experts with salt-spray-resistant metal shell capabilities. Competitive moves center on backward integration into contact plating and overmolding operations, plus geographic expansion into Southeast Asian contract manufacturing zones to capture cost-sensitive industrial automation demand.
Within the diversified interconnect tier, TE Connectivity and Amphenol occupy positions as scale-driven manufacturers with broad certification portfolios across defense, automotive, and telecommunications verticals. Hirose Electric exemplifies the precision miniaturization archetype, anchoring Japanese supply chains for consumer electronics and transportation applications. Amphenol LTW represents the marine-environment specialization vector, with metal shell connector capabilities concentrated in salt-spray-resistant specifications for offshore and naval equipment procurement.
| Leading Market Players |
|---|
| Hirose Electric |
| HARTING Technology Group |
| Molex |
| JST |
| Amphenol LTW |
| Amphenol |
| Switchcraft |
| Legrand |
| TE Connectivity |
| Others |
Cost & Logistics Intelligence
Eighteen-to-twenty-four week lead times for IEC 60529 certification testing compress supplier margins and concentrate pricing power among vertically integrated manufacturers with captive test chambers in Germany and Japan. This lead-time band locks out smaller competitors from premium IP68 and IP69K tiers, reinforcing cost-plus contract structures indexed to copper and gold plating material indices.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper and gold price indexation dominate procurement between defense contractors and established suppliers. Pricing stratifies across IP67 baseline, IP68 premium, and IP69K ultra-premium certification tiers, with differentiation driven by seal geometry complexity and salt-spray test duration. Cost compression in IP67 industrial automation supply is intensifying because contract manufacturers in Vietnam and Mexico absorb volume assembly. Automotive tier-ones in Stuttgart exhibit lowest price sensitivity due to platform-specification lock-in, while agricultural machinery OEMs purchasing sealed connectors for cab-interior electronics show highest sensitivity.
Supply Chain Analysis
Inventory cycles stretching to ninety days for fluorosilicone seal compounds expose assemblers to Japanese and German chemical supplier scheduling. Manufacturing concentrates in Germany for automotive-qualified production, Japan for precision miniaturization, and China for export-oriented industrial automation assembly. Raw material dependencies center on copper contact stock, gold plating chemistry, and elastomeric seal polymers. Single-source vulnerability in fluorosilicone production creates structural risk for IP68 and IP69K rated connector supply. Distribution runs through authorized distributor networks serving OEM manufacturing and direct qualification programs for defense contractors and telecommunication providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-moat story where IEC 60529 certification entrenchment and multi-year OEM qualification timelines create switching costs that defend incumbent positions against price-based competition.
For Market Incumbents: Compound defensive positioning through backward integration into captive contact plating operations and expansion of IEC-recognized test chamber capacity in Southeast Asian manufacturing zones. Threat from emerging miniaturization specialists in South Korea pressures consumer electronics connector margins. Certification investment remains the critical lever for IP69K tier defense. For New Entrants and Emerging Players: Differentiate on wireless power integration for marine and medical equipment applications where inductive charging coil sealing represents uncaptured specification space. Most penetrable segment sits in India's PLI-subsidized automotive and machinery connector assembly serving domestic industrial automation demand. Go-to-market angle centers on field-repairable modular seal architectures for offshore wind turbine maintenance contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underutilized circular waterproof connector divisions lacking IEC 60529 captive testing infrastructure. Five-to-ten year viability hinges on regulatory certification entrenchment deepening rather than commoditization. Acquisition target archetype: mid-scale marine-environment specialists with salt-spray-resistant metal shell IP68 capabilities. Signal to watch: BIS mandating IP67 minimum ratings for Indian industrial electrical component imports.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Test Chamber Investment | Vertically integrated IEC 60529 certification compresses qualification timelines for defense contractors. |
| Fluorosilicone Seal Backward Integration | In-house elastomer production insulates margins from Japanese chemical supplier concentration. |
| Wireless Power Module Integration | Inductive charging coil sealing opens marine and medical equipment specification opportunities. |
| India PLI Zone Manufacturing Footprint | Domestic assembly capacity captures automotive and machinery demand under BIS certification requirements. |
| Recyclable Material Protocol Development | Validated circularity credentials align with EU Green Deal tender mandates from energy producers. |
Research Approach
The analysis maps IP67 baseline, IP68 extended submersion, and IP69K steam-jet certification tiers, each validated through procurement directors at automotive tier-ones, certification engineers at IEC test houses, and supply chain managers at offshore wind developers. Primary fieldwork combined structured interviews with connector design engineers, regulatory affairs specialists, and distributor inventory planners across Germany, Japan, and the United States. Secondary validation drew from ECHA REACH substance restriction filings, FCC equipment authorization databases, customs trade records for copper and gold plating chemistry, and SEC filings from diversified interconnect manufacturers. Bottom-up assembly cost modeling and top-down end-use demand estimation triangulate volume and value outputs.
Consistency checks against external benchmarks validated projection outputs against observed procurement cycle timing and certification backlog data from TÜV and SGS test houses. The analytical framework segments by product type, ingress protection technology tier, application environment, and end-user procurement channel across the projection horizon. CAGRs derive from segment-level demand elasticity modeling and input cost trajectory assumptions. Industry-specific forecast inputs include offshore wind inter-array cable deployment schedules and German automotive platform electrification timelines.
The analysis sits within stated boundaries; outcomes outside sustained IEC 60529 certification tightening or stable copper and gold commodity pricing would require recalibration. Forecasts reflect assumptions regarding defense procurement cycle continuity and REACH framework substance restriction evolution. Specific risks that could revise projections include fluorosilicone supply disruption, BIS accelerating mandatory IP rating requirements, or FCC electromagnetic compatibility documentation rule changes extending qualification timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Connector and Terminal Systems for Harsh Environment Wiring Market
Connectors
Connector Market
Connectors
3C Electronics Precision Connectors Market
Connectors
India Connector Market
Connectors
Connector for PV System Market
Connectors
Filtered Connectors Market
Connectors
LCP Connectors Market
Connectors
PCI-E Connectors Market
Connectors
Global Multi Coaxial Connectors Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Press Fit Connector Market
Connectors
USB Type-C Market
Connectors
Latin America Connector Market
Connectors
Heavy-Duty Connector Market
Connectors
SATA Connector Market
Connectors
Underwater Mate Connectors Market