
 Connector and Terminal Systems for Harsh Environment Wiring Market | 2026-2036
Connector and Terminal Systems for Harsh Environment Wiring Market Size, Share, and Industry Trends Forecast 2026-2036
Connector and Terminal Systems for Harsh Environment Wiring Market Insights
Buyer concentration among aerospace primes and tier-one defense contractors is restructuring procurement patterns across the connector value chain. TE Connectivity leverages captive manufacturing in precision-machined contact systems to sustain long-term supply agreements with major platform integrators. Amphenol anchors its position through deep specialization in hermetic sealing technologies for submersible and high-altitude applications.
Connector and terminal systems for harsh environment wiring encompass electromechanical interfaces engineered to maintain signal and power integrity under extreme thermal cycling, corrosive exposure, and mechanical shock, typically manufactured from beryllium copper or nickel-aluminum bronze with fluoropolymer insulators rated beyond 200°C continuous operation. These assemblies serve critical functions where standard commercial interconnects would degrade from moisture ingress, galvanic corrosion, or electromagnetic interference. Cable assemblies and sealed connectors command the dominant share of current procurement volumes, while EMI shielding and vibration-resistant technologies represent the fastest-expanding technology categories as electrified platforms proliferate. Terminal blocks remain a mature, price-sensitive segment with thinner margin pools concentrated among electrical contractor channels.
FAA airworthiness directives and MIL-DTL-38999 military specifications govern qualification pathways for aerospace and defense applications, while IEC 60529 ingress protection ratings and EU RoHS substance restrictions shape baseline product standards for industrial and marine deployments. Germany's KBA and France's ANSM impose additional national certification layers for rail and nuclear applications respectively. Stakeholders must monitor evolving F-Gas Regulation restrictions on sealing compounds and accelerating OEM demands for digital traceability across supplier tiers.
Market Dynamics
Defense procurement agencies across NATO member states are consolidating orders for military-grade interconnect systems, compressing supplier qualification timelines and favoring manufacturers with captive precision-machining capabilities.
Growth Catalysts
- REACH and RoHS substance restrictions:European regulations are accelerating material substitutions toward halogen-free thermoplastic compounds, creating replacement demand across installed industrial bases.
- Electrified platform proliferation:Automotive and rail OEMs in Germany's industrial corridor are co-locating with specialized connector manufacturers, shortening development cycles for vibration-resistant assemblies.
- Defense procurement consolidation:NATO member states are expanding multi-year supply agreements for MIL-DTL-38999 qualified systems, locking in volume commitments with certified suppliers.
Market Restraints
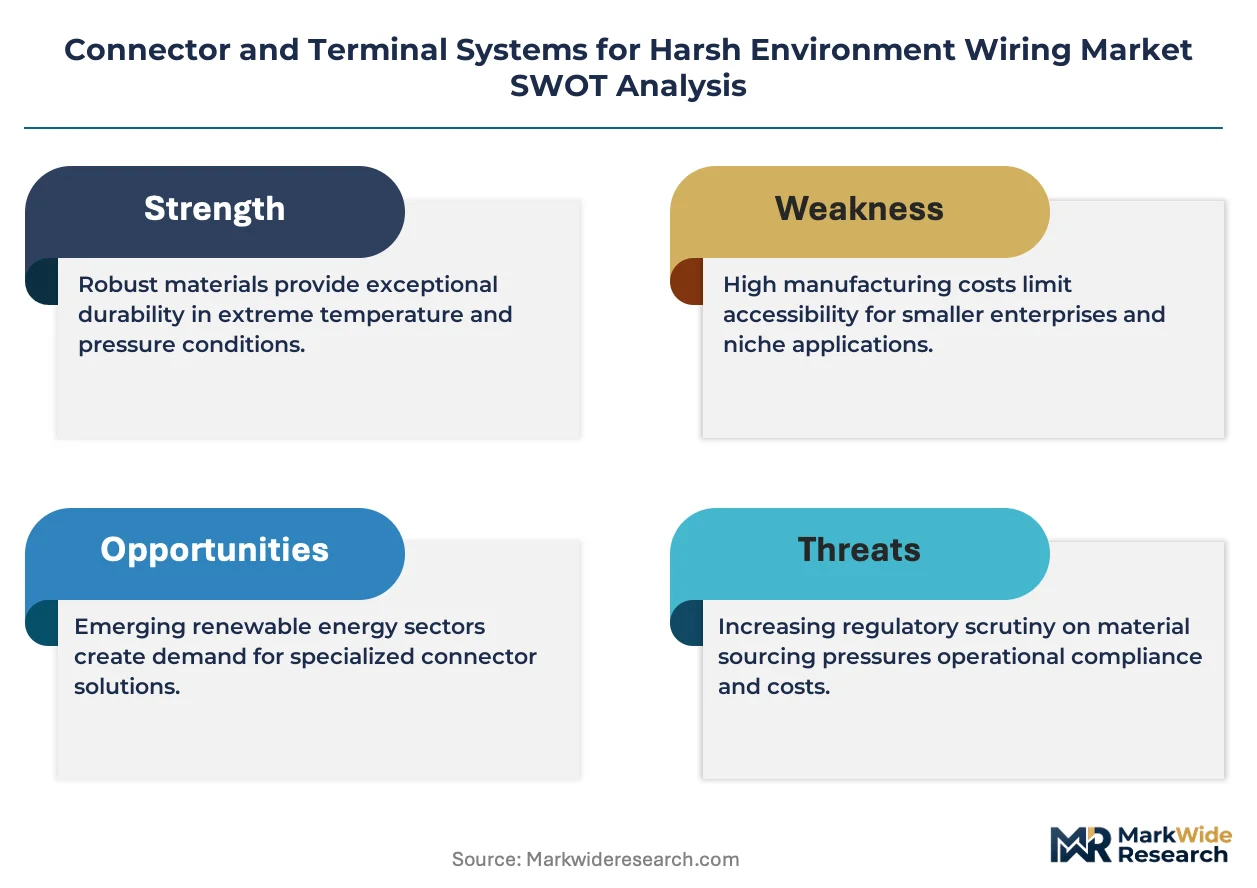
- Beryllium copper supply concentration:Precision-machined contact systems depend on limited North American and Chinese raw material sources, exposing pricing volatility to mining output fluctuations.
- F-Gas Regulation sealing compound restrictions:EU limits on fluorinated greenhouse gases are forcing reformulation of hermetic sealing technologies before qualified alternatives achieve equivalent performance.
- Additive manufacturing substitution limits:Powder-bed fusion processes cannot yet replicate the grain structure of wrought beryllium copper for high-cycle contact applications.
Strategic Opportunities
- Digital traceability mandates:Accelerating OEM requirements for supplier-tier data transparency are creating first-mover advantages for manufacturers with integrated quality management systems.
- EMI shielding convergence:The intersection of composite shielding materials with fiber-optic signal paths is opening specification windows in avionics and satellite platforms.
- Nuclear certification pathways:France's ANSM is expanding qualified supplier lists for containment-rated interconnects, with adjacent demand from small modular reactor programs.
Industry Challenges
- MIL-DTL-38999 qualification timelines:Defense airworthiness certification cycles extend 18-24 months, freezing design iterations and compressing product refresh windows.
- Hermetic sealing skill scarcity:Glass-to-metal seal engineering expertise concentrates among retiring specialist workforces in Connecticut and Bavaria manufacturing clusters.
- Legacy platform integration:New connector architectures must maintain backward compatibility with decades-old airframe wiring harnesses, constraining form factor innovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Connector and Terminal Systems for Harsh Environment Wiring Market |
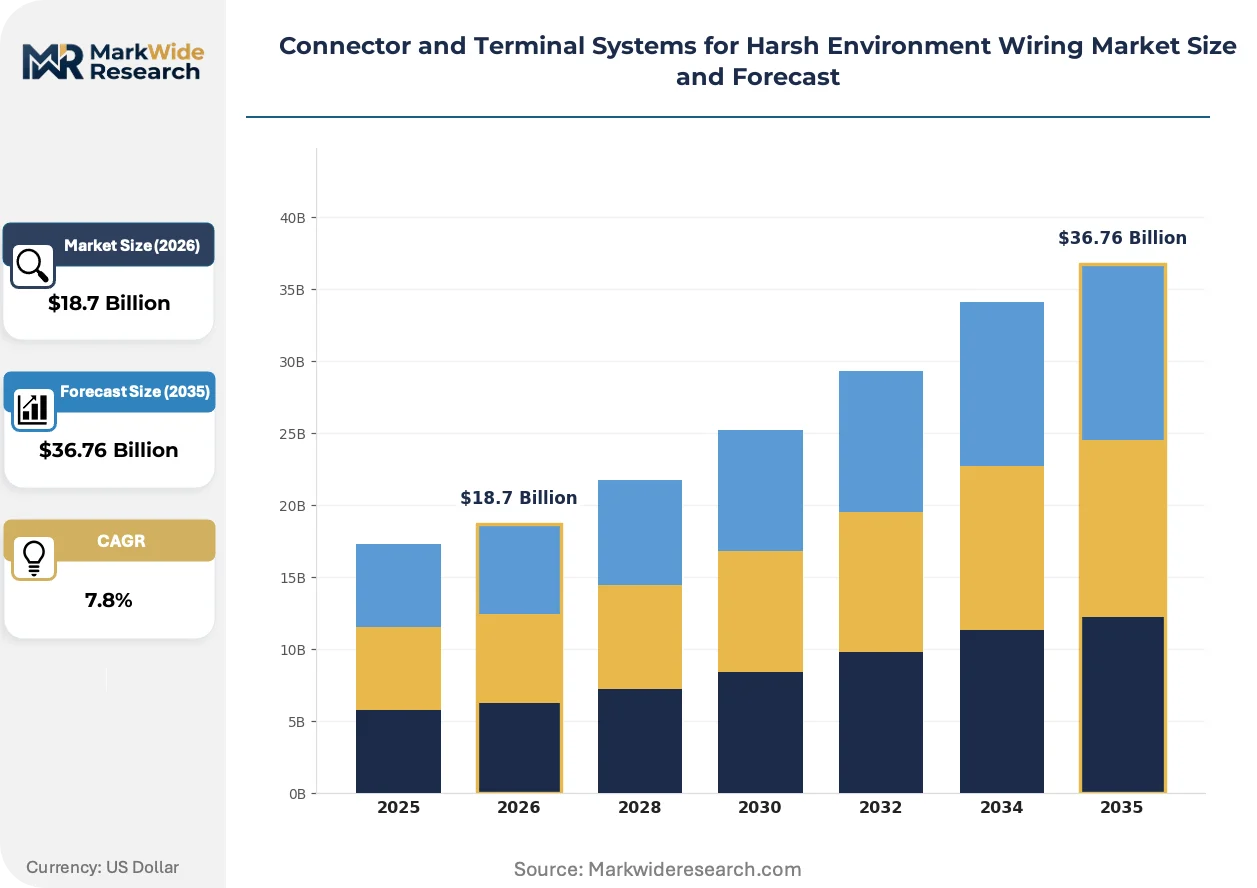
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pin Contacts, Socket Contacts, Cable Assemblies, Terminal Blocks, Cord Sets Technology: Sealed Connectors, Waterproof Coatings, EMI Shielding, Vibration Resistance, High Temperature Resistance Application: Aerospace, Marine Vessels, Railway Systems, Heavy Machinery, Military Equipment End User: OEMs, System Integrators, Maintenance Providers, Electrical Contractors, Industrial Manufacturers |
| Companies Covered | TE Connectivity, Amphenol, Molex, Aptiv, Yazaki, ITT, Smiths Interconnect, Hirose Electric, Fischer Connectors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Connector and Terminal Systems for Harsh Environment Wiring Market Trends and Innovations
Active reshaping in this market stems from regulatory chemistry restrictions, platform electrification architectures, and procurement consolidation among prime contractors. These forces are compressing supplier hierarchies and accelerating qualification pathway divergence across defense and industrial segments.
Modular connector architectures with field-replaceable contact modules are modularizing maintenance protocols for deployed military and rail fleets. Platform operators in Germany and the United States are specifying these systems for line-replaceable unit applications, reducing aircraft-on-ground downtime. This technology is modularizing the traditional integrated connector-assembly value chain, separating contact system suppliers from housing manufacturers.
EU F-Gas Regulation restrictions on perfluorinated sealing compounds are forcing compound reformulation across hermetic connector product lines. Manufacturers serving aerospace and submersible applications must validate alternative elastomers against MIL-STD-810 salt-fog and thermal shock requirements. Marine and offshore deployments in North Sea installations face the most acute compliance deadlines, driving accelerated testing programs at certification laboratories.
Long-term supply agreements with platform integrators are displacing spot-market purchasing for critical interconnect systems. Tier-one defense contractors are consolidating vendor lists to three qualified sources per connector family, extracting volume commitments and technical roadmapping collaboration. This concentration is most visible in United States Department of Defense procurement, where sole-source justifications face heightened congressional scrutiny.
Connector and Terminal Systems for Harsh Environment Wiring Market Segmentation
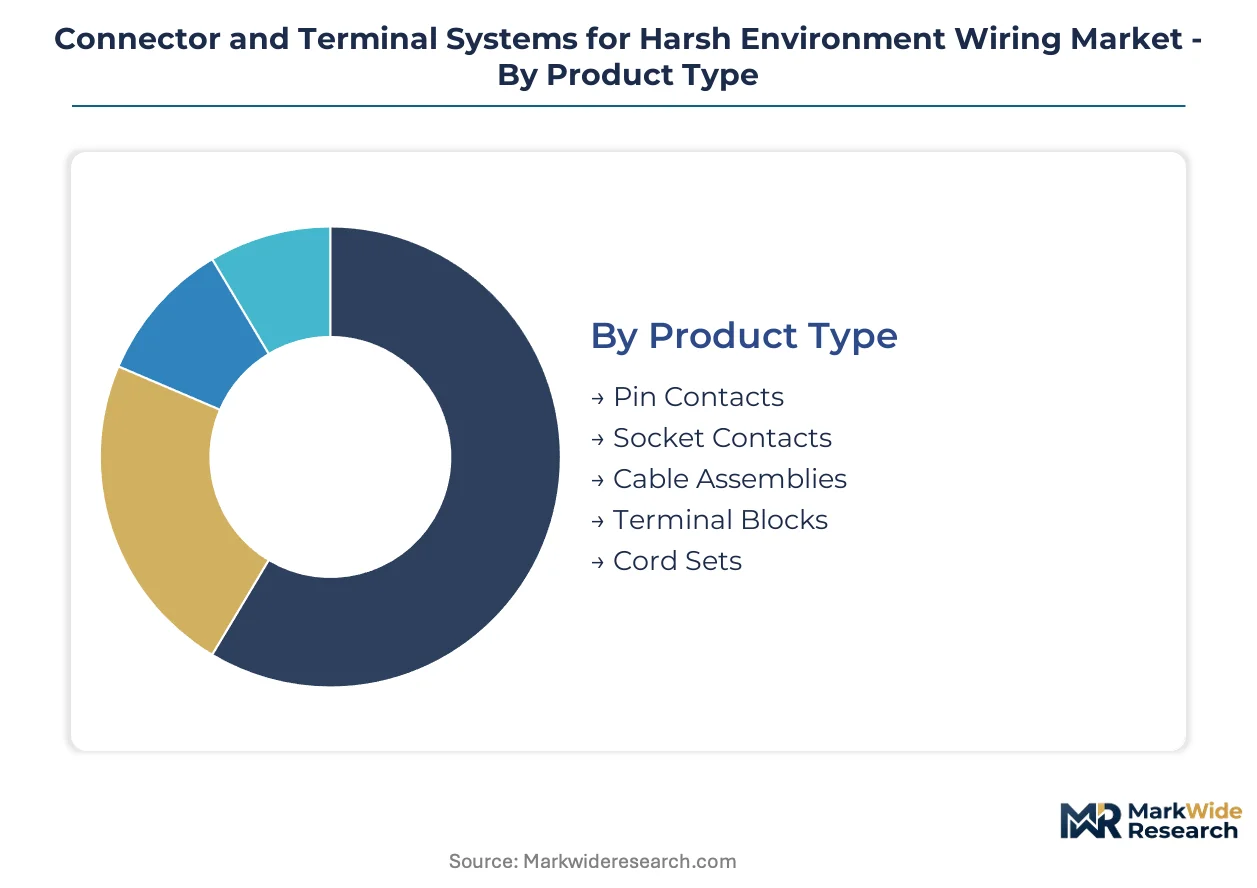
Segmentation in harsh environment wiring systems reveals how procurement authority concentrates among platform integrators while technology specialization fragments across defense, rail, and marine verticals. Understanding these splits exposes where qualification investments yield durable competitive position versus commoditization risk.
Product Type:
Standardization dominates high-volume contact systems while cable assemblies demand application-specific engineering, creating divergent margin profiles across this spectrum.
- Cable Assemblies:Integrated harness systems combining conductors, shielding, and overmolded connectors into platform-specific configurations. Procurement concentrates among German rail OEMs and U.S. defense primes seeking MIL-DTL-38999 qualified integrated solutions with digital traceability documentation.
- Terminal Blocks:Modular connection points for wire-to-wire and wire-to-board interfaces, typically DIN-rail mounted in industrial enclosures. Demand clusters among electrical contractor channels serving factory automation retrofits across France and Italy, where price sensitivity limits supplier differentiation.
- Pin Contacts:Precision-machined male contact elements from beryllium copper or phosphor bronze alloys, plated with gold or tin.
- Socket Contacts:Female receptacle counterparts designed for high-insertion-cycle durability in vibration-prone environments.
- Cord Sets:Pre-terminated cable assemblies with molded connectors for plug-and-play installation in field equipment.
Most installed capacity flows through Cable Assemblies. Expansion is steepest in Terminal Blocks as industrial electrification accelerates replacement cycles.
Technology:
Performance premiums concentrate in shielding and sealing technologies where regulatory compliance creates qualification barriers, while thermal and vibration resistance approaches commoditization in mature applications.
- EMI Shielding:Composite conductive materials and braided shielding architectures preventing electromagnetic interference in avionics and satellite systems. Specification activity concentrates among French aerospace suppliers facing tightened FCC and EU electromagnetic compatibility directives for next-generation platforms.
- Sealed Connectors:Hermetic and environmental sealing systems maintaining integrity against moisture, dust, and pressure differentials. NATO defense procurement and North Sea offshore operators drive qualification demand for IP67+ and MIL-STD-810 compliant designs with F-Gas Regulation compliant elastomers.
- Waterproof Coatings:Polymeric barrier layers applied to connector housings and contact surfaces for marine and outdoor industrial exposure.
- Vibration Resistance:Mechanical retention features including jackscrews, bayonet locks, and floating mount systems for rail and heavy machinery.
- High Temperature Resistance:Fluoropolymer insulators and ceramic contact supports rated beyond 200°C continuous operation.
Sealed Connectors command the dominant procurement volumes. EMI Shielding is climbing the fastest as composite airframes and electrified avionics proliferate.
Application:
Certification intensity varies sharply across verticals, with aerospace and military demanding multi-year qualification cycles while heavy machinery tolerates faster supplier switching.
- Military Equipment:Land, sea, and air platforms requiring MIL-DTL-38999 and MIL-STD-1553 qualified interconnects for mission-critical signal and power distribution. Procurement consolidates among U.S. Department of Defense and NATO member state agencies favoring manufacturers with captive precision-machining and long-term supply agreement capacity.
- Aerospace:Commercial and defense aviation applications governed by FAA airworthiness directives and EASA certification pathways. Germany's KBA and France's DGAC impose national overlays on connector specifications for regional aircraft programs.
- Railway Systems:Rolling stock and infrastructure wiring subject to EN 50155 and national railway safety authority requirements.
- Marine Vessels:Shipboard and submersible systems facing Lloyd's Register and DNV classification society standards.
- Heavy Machinery:Construction, mining, and agricultural equipment with less stringent qualification demands but extreme environmental exposure.
Military Equipment absorbs the largest qualification investments. Railway Systems are gaining share fastest as European rail electrification accelerates fleet modernization.
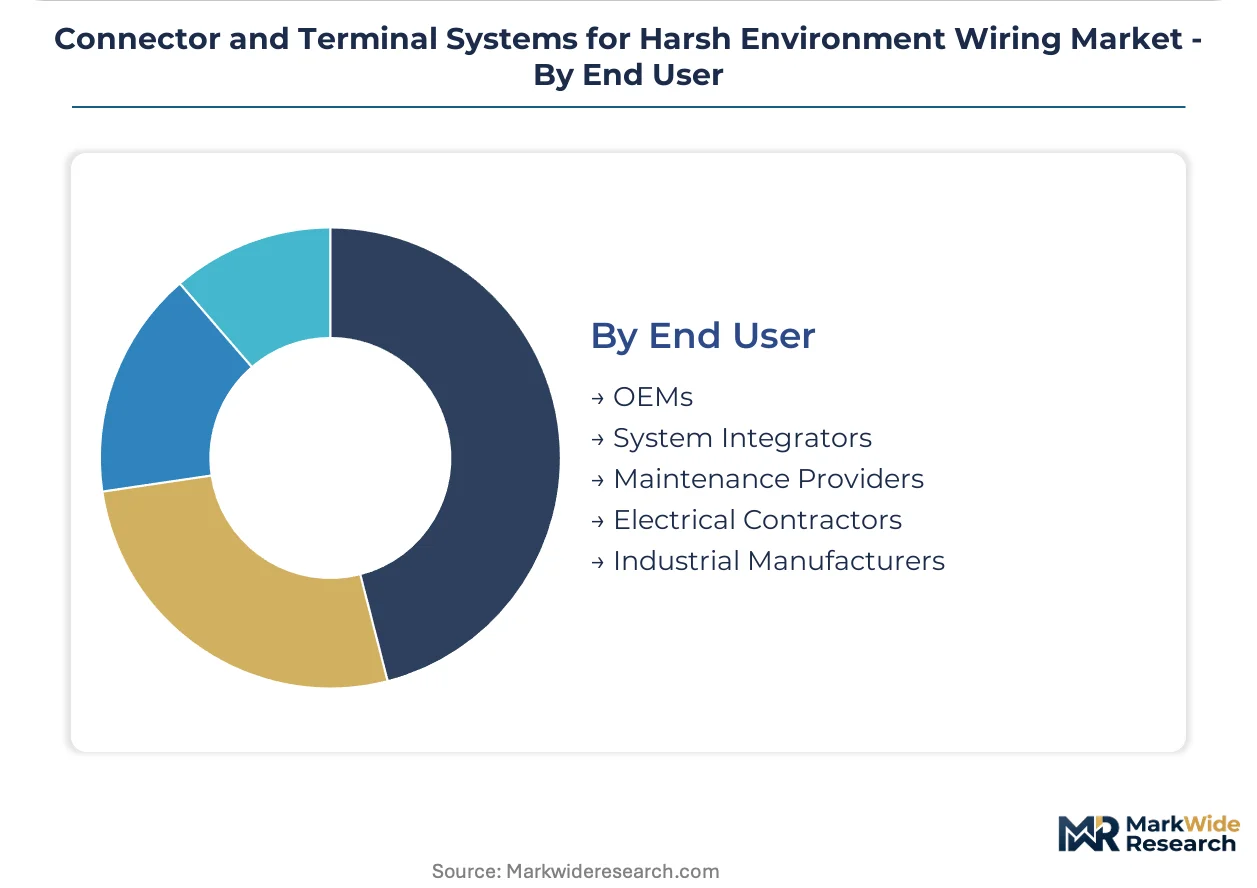
End User:
Procurement authority concentrates upstream with OEMs and system integrators who specify connector families, while downstream channels compete on availability and technical support.
- OEMs:Original equipment manufacturers with platform design authority specifying connector architectures during development phases. German automotive and rail OEMs co-located with specialized connector manufacturers in Baden-Württemberg and Bavaria compress development cycles through direct engineering collaboration.
- System Integrators:Tier-one contractors assembling subsystems for defense and aerospace primes, consolidating vendor lists to three qualified sources per connector family.
- Maintenance Providers:Fleet operators and third-party MRO facilities sourcing replacement connectors for line-replaceable unit applications.
- Electrical Contractors:Installation and retrofit specialists serving industrial and commercial building infrastructure.
- Industrial Manufacturers:Factory operators procuring connectors for in-house equipment builds and process automation.
Most specification authority rests with OEMs. System Integrators are expanding procurement influence fastest as defense primes outsource subsystem integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Glass-to-metal seal engineering expertise concentrates among retiring specialist workforces in Connecticut and Bavaria manufacturing clusters, while NATO defense procurement agencies consolidate multi-year supply agreements with certified suppliers.
United States
Defense procurement agencies consolidate orders for MIL-DTL-38999 qualified systems, compressing supplier qualification timelines to 18-24 months. FAA airworthiness directives govern certification pathways for aerospace applications. Connecticut manufacturing clusters anchor hermetic sealing production, though specialist workforce attrition threatens capacity.
Germany
Automotive and rail OEMs in Baden-Württemberg and Bavaria co-locate with specialized connector manufacturers, shortening development cycles for vibration-resistant assemblies. KBA imposes additional national certification layers for rail applications. Industrial electrification across the industrial corridor accelerates replacement demand for halogen-free thermoplastic compounds.
France
ANSM expands qualified supplier lists for containment-rated interconnects, with adjacent demand from small modular reactor programs. DGAC overlays national specifications on connector standards for regional aircraft programs. Aerospace suppliers in the Île-de-France cluster face tightened electromagnetic compatibility directives for next-generation platforms.
United Kingdom
Defense primes consolidate vendor lists to three qualified sources per connector family, extracting volume commitments and technical roadmapping collaboration. BSI standards align with IEC 60529 ingress protection ratings for industrial and marine deployments. Submarine and naval platform procurement drives demand for pressure-rated hermetic systems.
Japan
Electronics manufacturers source precision-machined contact systems for high-cycle applications in factory automation and robotics. METI industrial policy supports domestic supply chain resilience for critical interconnect components. Automotive OEMs in the Chubu and Kansai regions specify vibration-resistant assemblies for electrified platform architectures.
Connector and Terminal Systems for Harsh Environment Wiring Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. Market structure concentrates procurement authority among platform integrators who specify connector families during development phases. Three archetypes dominate: captive precision-machining specialists, hermetic sealing technology holders, and modular architecture integrators. Competitive moves center on long-term supply agreement capture and qualification pathway acceleration.
Within the diversified conglomerate tier, TE Connectivity and Amphenol occupy positions shaped by manufacturing scale and certification depth. TE Connectivity exemplifies the captive precision-machining archetype through sustained supply relationships with major platform integrators. Amphenol represents hermetic sealing specialization for submersible and high-altitude applications. Molex anchors the modular architecture vector, with Japanese and European specialists including Hirose Electric and Fischer Connectors occupying niche qualification positions.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol |
| Molex |
| Aptiv |
| Yazaki |
| ITT |
| Smiths Interconnect |
| Hirose Electric |
| Fischer Connectors |
| Others |
Pricing and Supply Chain Analysis
Defense prime contractors and tier-one system integrators concentrate procurement authority for MIL-DTL-38999 qualified interconnects, locking in contract-based long-term offtake pricing with volume commitments that insulate certified suppliers from spot-market volatility. This buyer concentration enables premium pricing for hermetic sealing and precision-machined contact systems while compressing margins on commoditized terminal blocks sold through electrical contractor channels.
Pricing Analysis
Bundled integrated harness systems with digital traceability documentation command substantial premiums over unbundled component sales, with three-tier pricing structure across premium, standard, and economy levels differentiated by certification grade and captive precision-machining capability. Price differentiation stems from MIL-STD-810 qualification status and hermetic sealing technology ownership, with aerospace and defense applications showing least price sensitivity due to airworthiness mandate compliance costs. Pricing pressure stems from REACH and RoHS material substitution requirements forcing reformulation investments, while terminal blocks face intensifying cost compression in industrial retrofit channels across France and Italy.
Supply Chain Analysis
Dual-sourcing requirements mandated by NATO defense procurement agencies and U.S. Department of Defense prime contractors force qualification of at least three approved suppliers per connector family, dispersing supply across Germany, the United States, and Japan for precision-machined components. Raw material dependencies center on beryllium copper from North American and Chinese mining sources, fluoropolymer insulators, and halogen-free thermoplastic compounds subject to F-Gas Regulation restrictions. Single-source vulnerability concentrates in glass-to-metal seal engineering expertise tethered to aging specialist workforces in Connecticut and Bavaria manufacturing clusters. Distribution runs through platform integrators and OEM specification authority, with long-term supply agreements displacing spot-market purchasing for critical interconnect systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Germany's industrial corridor, where automotive and rail OEM co-location compresses development cycles, and France's nuclear certification pathway, where ANSM containment-rated interconnect demand carries premium pricing power absent in commoditized industrial segments.
For Market Incumbents: Deepen captive precision-machining capabilities in beryllium copper contact systems to defend against additive manufacturing substitution threats while accelerating hermetic sealing skill transfer programs before Connecticut and Bavaria specialist workforce attrition erodes capacity. Lock in multi-year supply agreements with NATO defense procurement agencies to forestall vendor list consolidation, and invest in F-Gas Regulation compliant elastomer reformulation ahead of marine compliance deadlines in North Sea installations.
For New Entrants and Emerging Players: Enter via modular connector architectures with field-replaceable contact modules, targeting maintenance provider channels for line-replaceable unit applications in deployed military and rail fleets where incumbent integrated-assembly models create service rigidity. France's expanding ANSM qualified supplier lists for small modular reactor containment-rated interconnects offer the most penetrable certification pathway, with technical roadmapping collaboration as the essential go-to-market mechanism.
For Investors and Strategic Acquirers: Tier-one defense contractors are the most active acquirer in this space, consolidating vendor lists to extract volume commitments and accelerate MIL-DTL-38999 qualification timelines. Long-term viability over a 5-10 year window rests on digital traceability infrastructure ownership and hermetic sealing technology portfolios. Watch for inflection in small modular reactor deployment commitments, which would expand containment-rated interconnect demand beyond France's domestic nuclear maintenance base.
| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Supply Agreement Capture | Locks in volume commitments with NATO defense procurement agencies and U.S. Department of Defense primes. |
| Hermetic Sealing Technology Acquisition | Addresses skill scarcity in glass-to-metal seal engineering concentrated among retiring Connecticut and Bavaria workforces. |
| F-Gas Regulation Compliant Reformulation | Validates alternative elastomers against MIL-STD-810 requirements before North Sea marine compliance deadlines. |
| Digital Traceability Infrastructure Investment | Creates first-mover advantage as OEMs mandate supplier-tier data transparency across platform integrators. |
| Modular Architecture Development | Separates contact system suppliers from housing manufacturers in line-replaceable unit applications. |
Research Methodology
Coverage spans the United States, Germany, France, the United Kingdom, and Japan, with primary inputs from each market combining structured interviews with platform integration engineers, defense procurement officers, hermetic sealing specialists, rail OEM sourcing directors, and nuclear containment certification coordinators. Secondary validation draws from FAA airworthiness directive filings, MIL-DTL-38999 specification updates, ECHA REACH substance restriction databases, ANSM qualified supplier registries, and KBA rail safety certification records. Bottom-up segment sizing triangulates against top-down procurement budget analysis across NATO member state defense agencies.
Rate-of-change decomposition separates volume expansion from price-mix effects across the projection horizon, with segmentation modeling across product type, technology performance tier, application certification intensity, and end-user procurement authority. CAGRs derive from platform electrification adoption curves, defense modernization cycle timing, and regulatory compliance deadline clustering. Industry-specific forecast inputs include beryllium copper supply concentration risk assessments and F-Gas Regulation phase-out schedules affecting sealing compound availability.
Inputs from defense procurement agencies and hermetic sealing specialist workforces were available through the study window; gaps in small modular reactor deployment timelines and additive manufacturing substitution readiness introduce uncertainty bands around nuclear certification pathway and long-term contact system demand projections. Deviation in NATO defense spending commitments or F-Gas Regulation enforcement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
Connector Adapter Kits Market
Connectors
Circular Connectors Market
Connectors
Global Automotive Connector Market
Connectors
India Connector Market
Connectors
High-Reliability Connectors Market
Connectors
Terminal Pins Market
Connectors
Japan Connector Market
Connectors
China Connector Market
Connectors
Telecom Mounting Hardware Market
Connectors
AS-Interface Market
Connectors
Underwater Mate Connectors Market
Connectors
Power Connector Market
Connectors
Latin America Connector Market
Connectors
3C Electronics Precision Connectors Market
Connectors
Smart Crimper Market
Connectors
Hybrid Fiber Optic Connectors Market