
 Hybrid Fiber Optic Connectors Market | 2026-2036
Hybrid Fiber Optic Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
Hybrid Fiber Optic Connectors Market Intelligence
Defense procurement channels for tactical communications systems is tilting toward suppliers with certified ruggedized portfolios. Amphenol Corporation leverages its MIL-SPEC qualification breadth to sustain long-term program awards across U.S. and allied military platforms. TE Connectivity anchors its position through backward integration into cable assembly operations that shorten lead times for integrated fiber-to-the-antenna solutions. LEMO competes on precision Swiss manufacturing standards that command premium positioning in medical imaging and test instrumentation segments.
Hybrid fiber optic connectors combine optical fiber terminations with electrical contacts or fluid channels within a single sealed housing, typically achieving insertion loss below 0.5 dB and operating across temperature ranges from -55°C to +125°C depending on material grade and sealing specification. These devices serve applications requiring simultaneous data transmission, power delivery, and environmental protection in confined spaces. The LC interface category leads volume in data center environments where density and push-pull latching dominate rack architecture decisions, while ceramic ferrule materials capture margin pools in single-mode applications demanding sub-micron alignment precision. MPO/MTP variants represent the fastest structural expansion as parallel optics architectures displace discrete duplex channels in hyperscale compute fabrics.
The U.S. Department of Defense MIL-PRF-64266B specification shapes product development roadmaps for military-qualified suppliers, mandating salt spray, vibration, and shock survival that civilian telecommunications standards do not address. The European ETSI EN 302 099 framework governs electromagnetic compatibility and environmental testing for outdoor fiber installations across EU member states, creating compliance cost barriers for non-European entrants. Stakeholders must monitor how IEC 61753-1 performance categories evolve to encompass hybrid configurations that blend optical and electrical pathways, as this standard will determine interchangeability assurances for next-generation industrial networks.
Market Dynamics
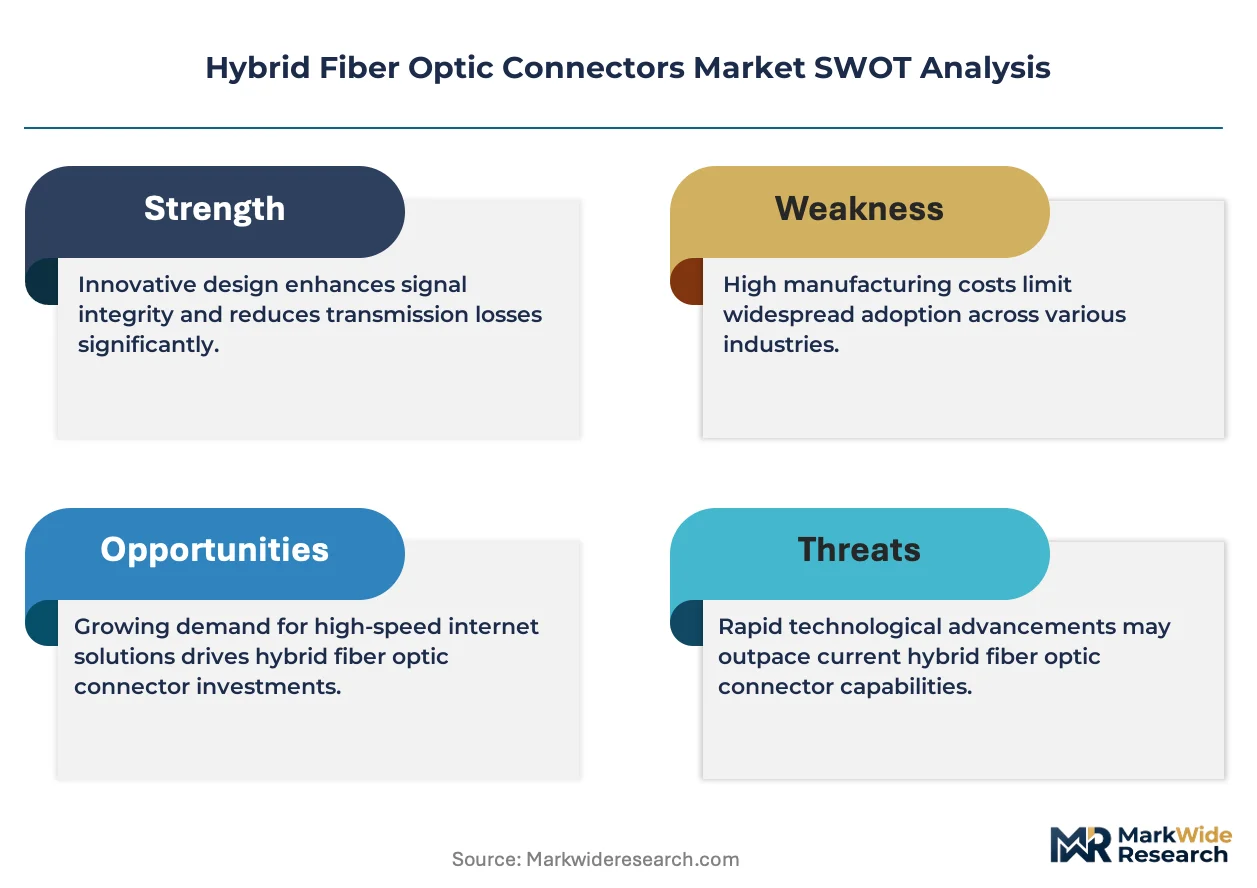
Parallel optics architectures in hyperscale data centers are compressing connector port counts per rack unit while multiplying fiber density requirements, forcing suppliers to reconcile MPO/MTP form factors with legacy LC infrastructure.
Growth Catalysts
- MIL-PRF-64266B tightening:The U.S. Department of Defense specification mandates salt spray and shock survival thresholds that civilian standards omit, channeling defense procurement toward pre-qualified ruggedized portfolios.
- German industrial automation:Automotive fiber networks in Stuttgart and Munich manufacturing clusters specify hybrid connectors for simultaneous power and data delivery in robotic assembly cells.
- Ceramic ferrule precision:Sub-micron alignment tolerances in single-mode applications capture margin pools as data centers upgrade to coherent optics.
Market Restraints
- Zirconia ferrule supply concentration:Japanese and Taiwanese ceramic suppliers control precision ferrule feedstock, exposing connector assemblers to input cost volatility and allocation risk.
- ETSI EN 302 099 compliance barriers:European electromagnetic compatibility testing requirements create cost friction for non-EU entrants seeking outdoor fiber installation contracts.
- Copper-cable substitution in short-reach:Active copper assemblies displace optical links under 7 meters in hyperscale server-to-switch connections.
Strategic Opportunities
- Indian defense modernization:The country's naval systems procurement under indigenous equipment mandates creates openings for ruggedized hybrid connectors meeting MIL-SPEC equivalents.
- Medical imaging convergence:Swiss precision manufacturing standards align with MRI and endoscopy OEM requirements for sealed hybrid power-data-fluid connectors.
- IEC 61753-1 hybrid expansion:Performance category evolution toward blended optical-electrical pathways will determine interchangeability certifications for next-generation industrial networks.
Industry Challenges
- Precision alignment technician scarcity:Single-mode connector termination requires sub-micron polishing skills that vocational programs in North America and Europe have not scaled to meet demand.
- Dual certification timelines:Simultaneous MIL-SPEC and IEC qualification processes extend product launch cycles by 18-24 months for multi-market suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hybrid Fiber Optic Connectors Market |
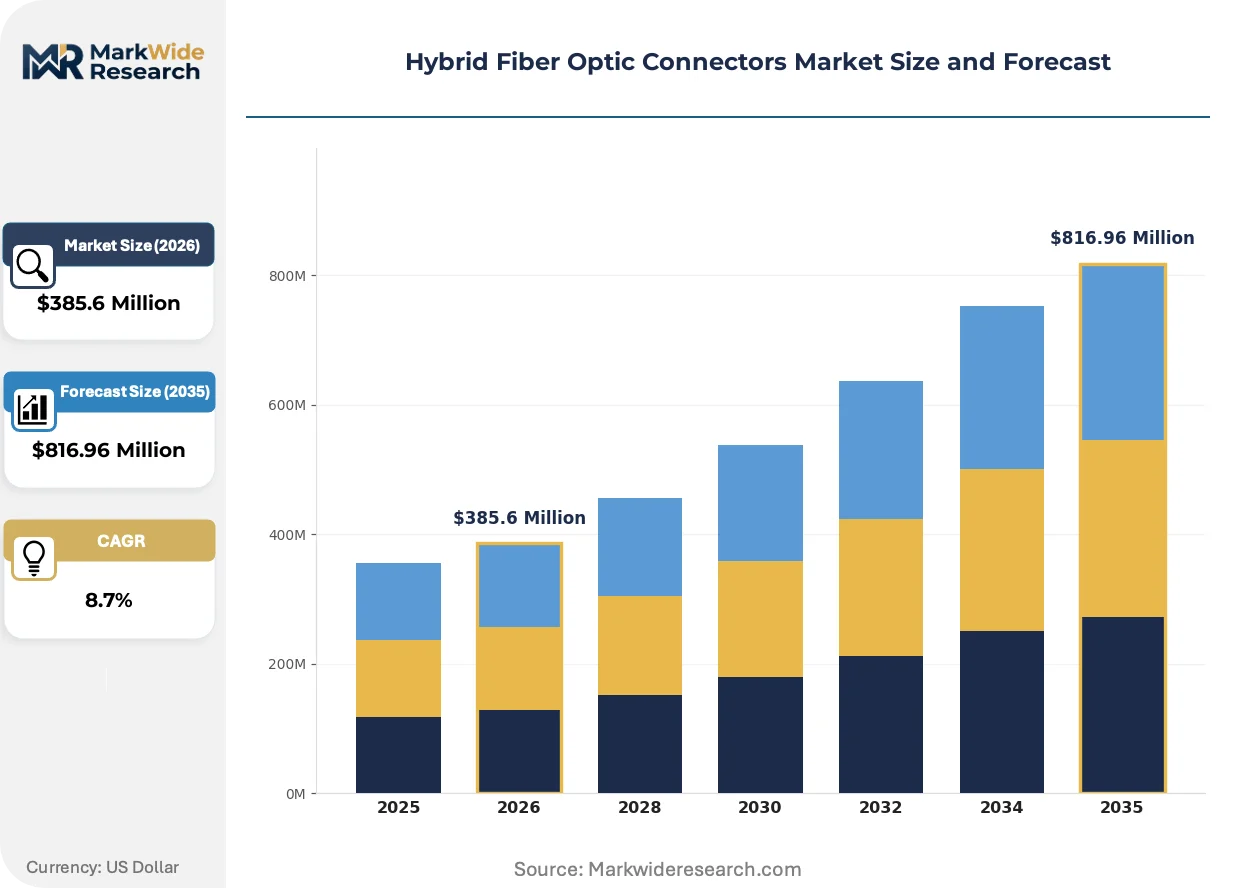
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SC, LC, ST, MPO Material: Plastic, Metal, Ceramic, Glass Connector Interface: Single-Mode, Multi-Mode, Hybrid, MPO/MTP Installation Type: Indoor, Outdoor, Modular, Custom |
| Companies Covered | Amphenol Corporation, Diamond SA, LEMO, Hirose Electric Company, Staubli International AG, QPC Fiber Optic, LLC, Smiths Interconnect, Inc., TE Connectivity, Fischer Connectors SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hybrid Fiber Optic Connectors Market Strategic Shifts & Innovations
Connector architectures are virtualizing physical layer boundaries as parallel optics and co-packaged optics compress the distance between switch silicon and fiber termination points.
Co-packaged optics is virtualizing the traditional pluggable transceiver form factor by embedding photonic chips directly adjacent to switch ASICs. Hyperscale operators in Oregon, Virginia, and Singapore data center clusters are piloting 51.2 Tbps switch platforms with internal fiber connectivity. This compression is virtualizing the discrete connector port as a permanent internal assembly, reducing field-replaceable connector counts while demanding higher-density MPO/MTP backplane integration.
REACH substance restrictions are tightening material specifications for connector housings and cable jacketing across EU member states. ECHA candidate list updates now scrutinize halogenated flame retardants common in military-grade cable assemblies. German automotive OEMs and French aerospace suppliers are accelerating qualification of phosphorus-nitrogen intumescent alternatives to maintain CE marking compliance without sacrificing -55°C cold-bend performance.
Buyer consolidation among hyperscale cloud operators is compressing supplier qualification cycles while extending contract durations. Amazon Web Services, Microsoft Azure, and Google Cloud now specify multi-year fiber infrastructure frameworks with integrated connector-cable assembly sourcing. This concentration is forcing mid-tier connector manufacturers to anchor through backward integration into cable assembly operations or risk disintermediation by vertically integrated competitors.
Hybrid Fiber Optic Connectors Market Segmentation
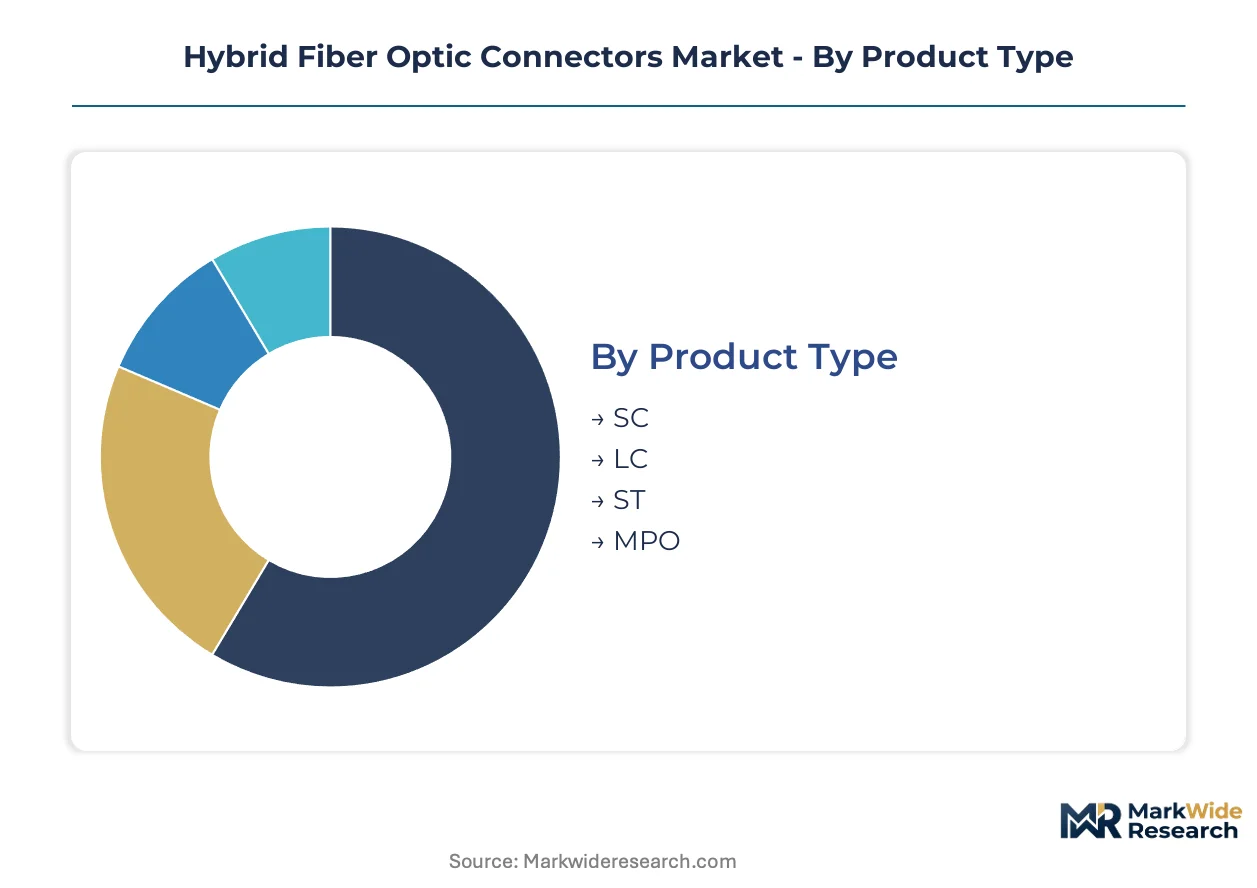
Segmentation in hybrid fiber optic connectors reveals divergent procurement rhythms across defense, data center, and industrial channels. Cycle times range from decade-long military qualification programs to quarterly hyperscale refresh schedules, forcing suppliers to maintain parallel product pipelines.
Product Type:
LC and MPO variants turn inventory fastest in hyperscale deployments, while SC and ST connectors linger in legacy infrastructure with replacement cycles stretching seven to ten years.
- SC:The square snap-in coupling mechanism endures in military avionics and submarine systems where MIL-PRF-64266B qualification investments resist form factor migration. Demand concentrates in U.S. naval procurement channels where backward compatibility with existing cable plant outweighs density advantages.
- LC:The reduced-form-factor push-pull latch dominates rack architecture decisions in Oregon and Virginia data center clusters, with ceramic ferrule variants capturing premium positioning in coherent optics upgrades. Stuttgart automotive fiber networks specify LC hybrids for robotic assembly cell integration.
- ST:Bayonet twist-lock mechanisms persist in industrial process control installations and legacy telecommunications central offices where technician familiarity reduces field installation errors.
- MPO:Multi-fiber push-on connectors align with parallel optics architectures displacing discrete duplex channels in 51.2 Tbps switch platforms.
SC dominates installed base. MPO is where expansion concentrates.
Material:
Cost tiers separate commodity plastic housings from precision ceramic ferrules, with metal and glass occupying intermediate positions defined by environmental sealing requirements.
- Plastic:Injection-molded polymer housings serve indoor data center environments where halogenated flame retardant restrictions under REACH are accelerating phosphorus-nitrogen intumescent formulation shifts. ECHA candidate list scrutiny is forcing German automotive OEMs to requalify jacketing materials.
- Ceramic:Zirconia ferrules achieve sub-micron alignment tolerances essential for single-mode coherent optics, though Japanese and Taiwanese feedstock concentration exposes assemblers to allocation risk. Precision polishing requirements outstrip vocational program output in North America.
- Metal:Aluminum and stainless steel shells satisfy salt spray and shock survival thresholds in naval systems procurement under tightening MIL-SPEC requirements.
- Glass:Hermetic sealing applications in medical imaging and aerospace instrumentation leverage borosilicate ferrules for thermal expansion matching.
Ceramic commands margin concentration. Plastic handles volume scale.
Connector Interface:
Application intensity varies sharply, with single-mode interfaces demanding precision alignment labor while multi-mode and hybrid configurations accommodate less skilled field termination.
- Single-Mode:9-micron core diameter mandates sub-micron ferrule concentricity for coherent optics transmission, concentrating demand in long-haul telecommunications and data center interconnects exceeding 10 kilometers.
- Multi-Mode:50-micron and 62.5-micron core diameters dominate building backbone and campus installations where LED and VCSEL sources tolerate looser alignment tolerances.
- Hybrid:Combined optical-electrical-fluid pathways serve MRI and endoscopy OEM requirements in Swiss precision manufacturing corridors, with sealed housings achieving -55°C to +125°C operational ranges.
- MPO/MTP:8-fiber and 16-fiber array connectors align with co-packaged optics compression of switch-to-fiber distances in Singapore and Virginia pilot deployments.
Multi-mode anchors legacy infrastructure. MPO/MTP is climbing the fastest.
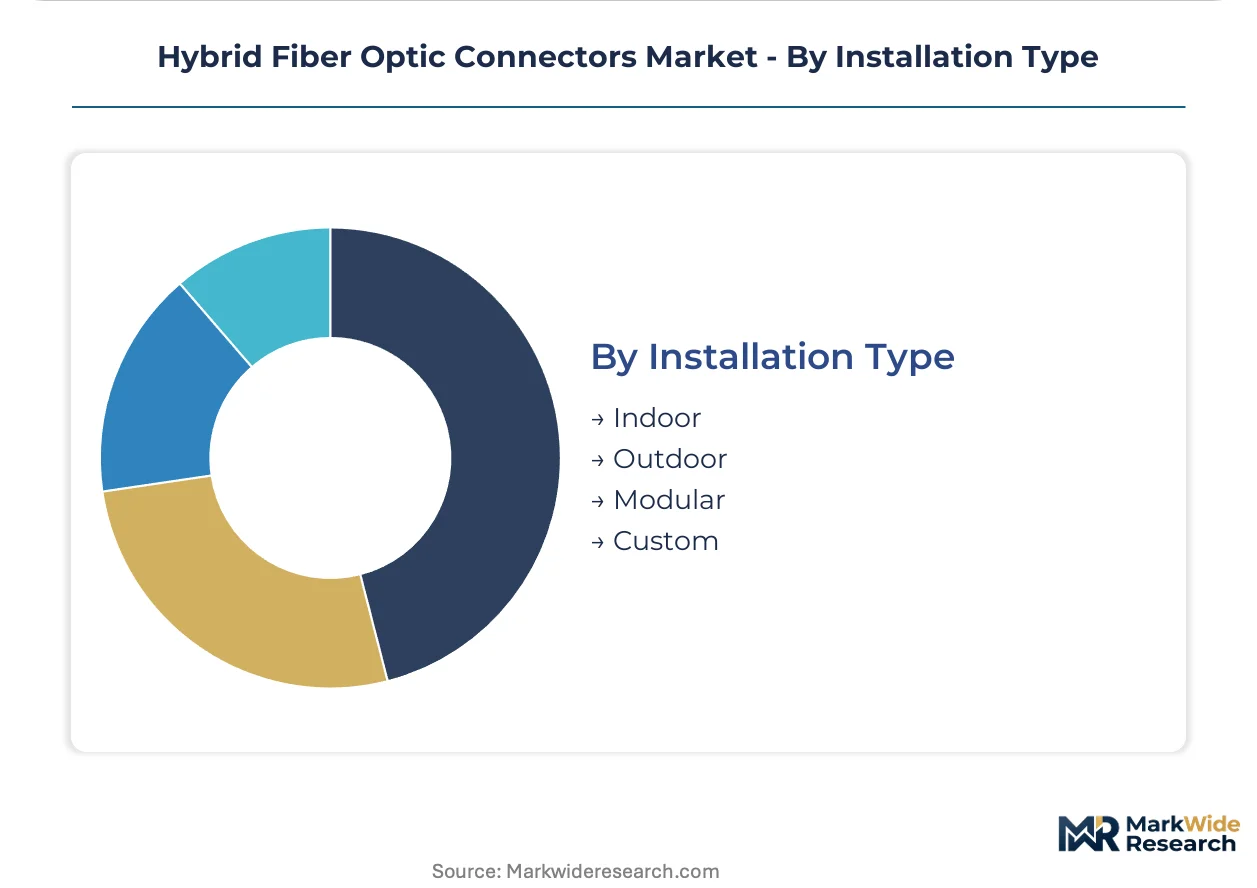
Installation Type:
Customer type stratification separates standardized indoor volumes from engineered outdoor and custom defense programs with elongated qualification timelines.
- Indoor:Controlled environment specifications dominate enterprise LAN and hyperscale data center procurement, with push-pull latching and bend-insensitive fiber dominating rack-and-cable management decisions.
- Outdoor:ETSI EN 302 099 electromagnetic compatibility and environmental testing requirements create compliance friction for non-EU entrants seeking European fiber installation contracts, mandating UV-resistant jacketing and gel-sealed closures.
- Modular:Field-configurable connector systems serve broadcast and live event infrastructure where rapid redeployment outweighs permanent installation economics.
- Custom:Defense and aerospace contractors specify ruggedized hybrid configurations with integrated power and fluid channels, with MIL-SPEC qualification cycles extending 18-24 months for multi-market suppliers.
Indoor dominates shipment volumes. Custom captures program value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive fiber networks command pricing premiums against U.S. defense procurement channels, where MIL-SPEC qualification costs compress supplier margins. Japanese ceramic ferrule suppliers extract upstream value from Taiwanese precision manufacturing clusters. Indian naval modernization programs under indigenous equipment mandates are reshaping sourcing patterns for ruggedized hybrid connectors.
United States
Defense procurement channels for tactical communications systems concentrate demand in Virginia and California aerospace corridors. The Department of Defense MIL-PRF-64266B specification tightens insertion loss and environmental sealing requirements quarterly. Hyperscale data center operators in Oregon and Virginia pilot 51.2 Tbps switch platforms with internal fiber connectivity.
Germany
Industrial automation and automotive fiber networks in Stuttgart and Munich manufacturing clusters specify hybrid connectors for robotic assembly cells. ECHA scrutiny of halogenated flame retardants under REACH accelerates phosphorus-nitrogen intumescent requalification. Baden-Württemberg precision tooling suppliers feed ceramic ferrule polishing equipment to connector assemblers.
Japan
Zirconia ferrule feedstock concentration in Osaka-Kobe ceramic manufacturing districts exposes connector assemblers to allocation risk. METI industrial standards govern precision alignment tolerances for single-mode coherent optics. Nagoya automotive electronics suppliers integrate LC hybrid connectors into vehicle-to-infrastructure communication modules.
India
Naval systems procurement under indigenous equipment mandates creates openings for ruggedized hybrid connectors meeting MIL-SPEC equivalents. The Ministry of Defence PLI scheme incentivizes local assembly of fiber optic interconnects. Chennai and Mumbai shipyard clusters specify sealed hybrid configurations for sonar and combat management systems.
Switzerland
Swiss precision manufacturing standards align with MRI and endoscopy OEM requirements for sealed hybrid power-data-fluid connectors. Swissmedic medical device regulations govern biocompatibility and hermetic sealing validation. Geneva and Neuchâtel instrumentation clusters source LEMO-compatible interfaces for diagnostic imaging equipment.
Hybrid Fiber Optic Connectors Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in ferrule and housing supply. The vendor base stratifies across three tiers: defense-qualified ruggedized portfolios, hyperscale-optimized density platforms, and precision medical instrumentation lines. Strategic differentiation runs through backward integration into cable assembly operations and dual MIL-SPEC plus IEC qualification breadth. M&A activity concentrates on ceramic ferrule suppliers and regional cable assembly assets.
Within the defense-qualified tier, Amphenol Corporation and TE Connectivity anchor positions through MIL-SPEC qualification breadth and integrated fiber-to-the-antenna solutions. LEMO occupies a premium position exemplifying Swiss precision manufacturing standards for medical imaging and test instrumentation segments. These three represent divergent competitive vectors: scale-driven program awards, operational integration for lead time compression, and precision-margin capture in regulated medical channels.
| Leading Market Players |
|---|
| Amphenol Corporation |
| Diamond SA |
| LEMO |
| Hirose Electric Company |
| Staubli International AG |
| QPC Fiber Optic, LLC |
| Smiths Interconnect, Inc. |
| TE Connectivity |
| Fischer Connectors SA |
| Others |
Cost & Logistics Intelligence
Osaka-Kobe ceramic manufacturing districts anchor zirconia ferrule feedstock availability, translating upstream concentration into asymmetric pricing power for Japanese suppliers against connector assemblers in North America and Europe. MIL-SPEC qualification investments and REACH compliance costs compound input price volatility, forcing tiered margin structures that separate defense-qualified portfolios from commercial-grade alternatives.
Pricing Analysis
Configured-to-order pricing for ruggedized hybrid connectors commands 40-60% premiums over standard LC and MPO variants due to MIL-PRF-64266B certification investments and extended qualification timelines. Three-tier pricing structure across premium, standard, and economy levels separates ceramic ferrule single-mode assemblies from plastic-housed multi-mode volumes, with customization depth and certification grade as primary differentiation drivers. Cost compression in standard data center connectors intensifies as hyperscale buyers consolidate procurement frameworks, while defense and medical segments exhibit lower price sensitivity due to regulatory switching costs and hermetic sealing requirements.
Supply Chain Analysis
Upstream zirconia feedstock draws from Japanese and Taiwanese precision ceramic clusters, with borosilicate glass ferrules and aluminum housing alloys as secondary material dependencies. Single-source vulnerability concentrates in sub-micron ferrule polishing equipment supplied by Baden-Württemberg tooling specialists, exposing assemblers to allocation risk during capacity expansions. Distribution runs through integrated cable assembly operations for hyperscale contracts, while defense procurement channels favor qualified component suppliers with captive terminations capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across defense, hyperscale, and medical instrumentation channels creates niche entry points as co-packaged optics and parallel architectures displace legacy form factors. The divergence in qualification timelines—quarterly refresh cycles versus multi-year MIL-SPEC programs—prevents scale economics from consolidating the vendor base.
For Market Incumbents: Insulate program positions through backward integration into ceramic ferrule supply and dual MIL-SPEC plus IEC qualification breadth. Threats from active copper substitution under 7 meters and REACH substance restrictions demand captive polishing capacity and phosphorus-nitrogen intumescent material requalification investments. For New Entrants and Emerging Players: Build out precision alignment technician training partnerships with Stuttgart and Munich vocational clusters to address scarcity bottlenecks in single-mode termination. The most penetrable white space sits in Indian naval modernization under indigenous equipment mandates, with MIL-SPEC equivalent certification as the critical go-to-market enabler. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors ceramic ferrule suppliers and regional cable assembly assets with hyperscale framework access. Long-term viability hinges on interchangeability certification under evolving IEC 61753-1 hybrid performance categories, with co-packaged optics pilot deployments in Singapore and Virginia as the signal to watch for field-replaceable connector displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrule Supply | Captive zirconia feedstock secures margin pools against Japanese supplier allocation risk. |
| Dual Certification Investment | Simultaneous MIL-PRF-64266B and IEC 61753-1 qualification opens defense and industrial network procurement channels. |
| Regional Cable Assembly Expansion | Localized terminations capability satisfies ETSI EN 302 099 compliance for EU outdoor installation contracts. |
| Precision Technician Training Partnerships | Stuttgart vocational cluster alliances address sub-micron polishing skills scarcity constraining single-mode output. |
| Phosphorus-Nitrogen Material Requalification | ECHA REACH compliance maintains CE marking for German automotive OEM fiber network specifications. |
Research Approach
The analysis maps LC, MPO, SC, and ST connector variants alongside ceramic, plastic, metal, and glass material tiers, each validated through procurement managers at defense contractors, data center infrastructure engineers, and automotive fiber network specialists. Primary interviews with TE Connectivity and Amphenol program directors, LEMO medical instrumentation account leads, and Indian Ministry of Defence PLI scheme administrators combined with secondary validation through MIL-PRF-64266B specification documents, ECHA REACH candidate list updates, and IEC 61753-1 draft standards. Bottom-up shipment data from Osaka-Kobe ceramic districts and top-down hyperscale capex disclosures enabled triangulation across connector interface and installation type segments.
Assumptions held fixed include sustained U.S. defense procurement under MIL-SPEC tightening, continued REACH substance restriction enforcement across EU member states, and coherent optics upgrade cycles in data center interconnects. Variables stress-tested encompass zirconia ferrule supply allocation disruptions, active copper substitution thresholds in short-reach links, and co-packaged optics adoption rates in 51.2 Tbps switch platforms. CAGRs derive from segment-level volume projections across product type, material, connector interface, and installation type dimensions, with ceramic ferrule precision requirements and hybrid configuration complexity as industry-specific demand drivers.
Stress conditions across Japanese feedstock concentration, ETSI compliance cost escalation, and technician training pipeline constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions, with revision triggers including IEC standard finalization timing and Indian PLI localization thresholds. Cross-checking against hyperscale cloud operator fiber infrastructure framework disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Connectors
5G Connector Market
Connectors
Terminal Pins Market
Connectors
Connector Market
Connectors
Global Fiber Optic Connectors Market
Connectors
Magnetic Connector Market
Connectors
Micro-Miniature Co-Axial Adapter Market
Connectors
Australia Connector Market
Connectors
DIN Connectors Market
Connectors
China Connector Market
Connectors
Relay Sockets Market
Connectors
Circular Waterproof Connector Market
Connectors
Middle East Connector Market
Connectors
Space Grade Connectors Market
Connectors
Global Cables and Connector Market
Connectors
Japan Connector Market
Connectors
Cable Connectors and Adapters Market