
 Automotive Smart Faceplate Market | 2026-2036
Automotive Smart Faceplate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Smart Faceplate Market Outlook
The capital-intensity divergence between display foundry operators and assembly-tier suppliers is unwinding competitive stability across the supply base. Robert Bosch GmbH leverages captive semiconductor sourcing to sustain margin control across integrated cockpit programs. Continental AG anchors European OEM relationships through its haptic research center in Regensburg. DENSO Corporation dominates thermal-managed interface production for Japanese and North American vehicle platforms.
An automotive smart faceplate is a human-machine interface panel integrating capacitive touch layers, haptic feedback actuators, and ambient light guides into a single trim-integrated module, typically operating between minus forty and eighty-five degrees Celsius for cabin durability. Its primary commercial purpose is consolidating climate, infotainment, and vehicle setting controls into a software-updatable surface that reduces mechanical switch count. Touchscreens capture the dominant share of value among product types due to their position as the central control anchor in premium vehicle architectures. Gesture recognition technology leads growth within the technology dimension as OEMs seek eyes-off-road compliance advantages. Cloud-connected systems within the deployment category concentrate margin pools through recurring software revenue attachments.
The EU Cyber Resilience Act and CE marking requirements under the EU AI Act are mandating security-by-design documentation for connected faceplate units entering European vehicle programs. China's SAMR enforces GB standards for in-vehicle data transmission that dictate encryption levels for NFC and Wi-Fi-enabled faceplates sold domestically. Stakeholders must monitor divergent certification timelines across Brussels and Beijing to avoid platform redesign cycles that compress development budgets.
Market Dynamics
Haptic feedback integration is compressing development cycles across the automotive smart faceplate supply base, forcing tier-one suppliers to consolidate touch-layer and actuator competencies under single engineering teams.
Growth Catalysts
- EU Cyber Resilience Act:Mandates security-by-design documentation for cloud-connected faceplate systems, accelerating OEM procurement of certified modules.
- Gesture recognition technology:Premium electric vehicle architectures in Germany and China are embedding non-contact interfaces to meet eyes-off-road compliance standards.
- Yangtze River Delta automotive cluster:Concentrated demand from domestic EV manufacturers is pulling capacity expansion from display foundry operators.
Market Restraints
- Indium tin oxide price volatility:Transparent conductor layer costs fluctuate with mining output constraints, squeezing margin at assembly-tier suppliers.
- Single-source haptic actuator supply:Precision linear resonant actuator production concentrates among three East Asian component houses, creating concentration risk.
- GB standards compliance friction:China's SAMR encryption requirements for NFC-enabled faceplates force parallel certification tracks for export-bound versus domestic-only production.
Strategic Opportunities
- Recurring software revenue attachment:Cloud-connected faceplate systems enable over-the-air feature activation, shifting margin pools toward firmware licensing.
- India's PLI scheme for automotive electronics:Component manufacturing incentives are pulling assembly investment away from traditional China-centric sourcing.
- Capacitive-piezoelectric convergence:Hybrid force-sensing architectures are opening design wins in commercial vehicle cabins where glove-operation durability matters.
Industry Challenges
- Multi-standard certification timelines:Divergent EU AI Act CE marking and China GB validation cycles compress platform development budgets.
- Thermal management integration complexity:Operating between minus forty and eighty-five degrees Celsius requires coordinated simulation across materials science and firmware teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Smart Faceplate Market |
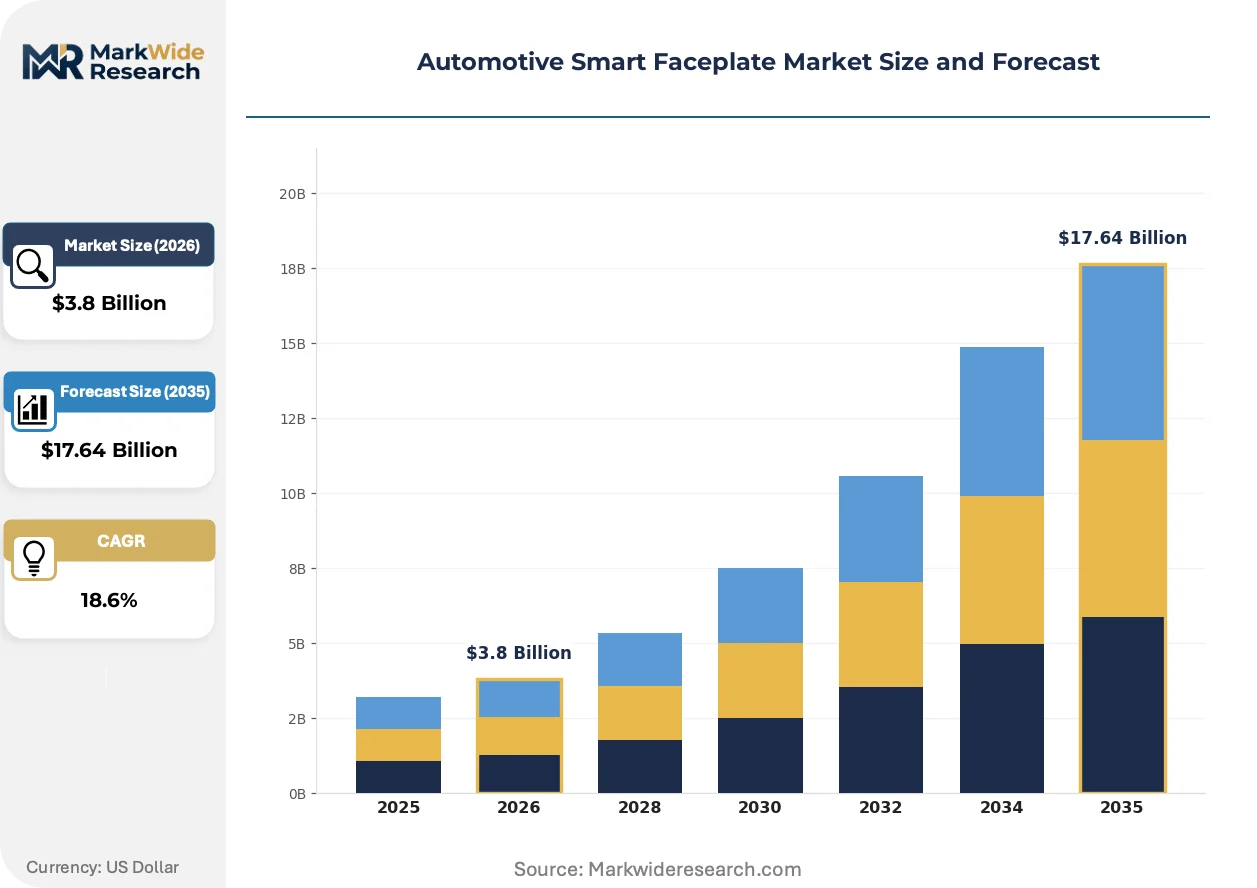
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Displays, Touchscreens, Voice Control Units, Interface Modules Technology: Bluetooth, NFC, Wi-Fi, Gesture Recognition End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships Deployment: Integrated Solutions, Standalone Units, Cloud-Connected Systems, Retrofit Kits |
| Companies Covered | Robert Bosch GmbH, Continental AG, DENSO Corporation, Visteon Corporation, Panasonic Corporation, LG Display Co., Ltd., Hyundai Mobis, Japan Display Inc., Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Smart Faceplate Market Strategic Shifts
Interface modality convergence is collapsing the boundary between climate, infotainment, and vehicle setting controls into unified software-updatable surfaces.
Force-sensitive resistor arrays are displacing traditional mechanical switch banks in heavy-duty truck cabins, where vibration tolerance and sealed-environment durability outweigh cost sensitivity. Fleet operators at North American logistics companies are specifying these interfaces for reduced warranty claims. The technology is displacing legacy toggle-switch suppliers from Tier 2 positions in commercial vehicle programs.
The EU AI Act's CE marking requirements are mandating algorithmic transparency documentation for gesture-recognition faceplate modules entering European vehicle programs. OEMs must submit training data governance records to notified bodies before series production approval. Premium German manufacturers are responding by segregating AI-enabled and non-AI product lines to isolate compliance risk.
Subscription-activated feature unlocking is restructuring how OEMs monetize faceplate hardware, with climate-control gestures and ambient-light themes sold as post-purchase digital upgrades. This unbundles traditional trim-level packaging and compresses the effective replacement cycle for interface software. The shift is most visible in China, where domestic EV brands use this model to maintain price competitiveness while protecting margin through service attach rates.
Automotive Smart Faceplate Market Segmentation
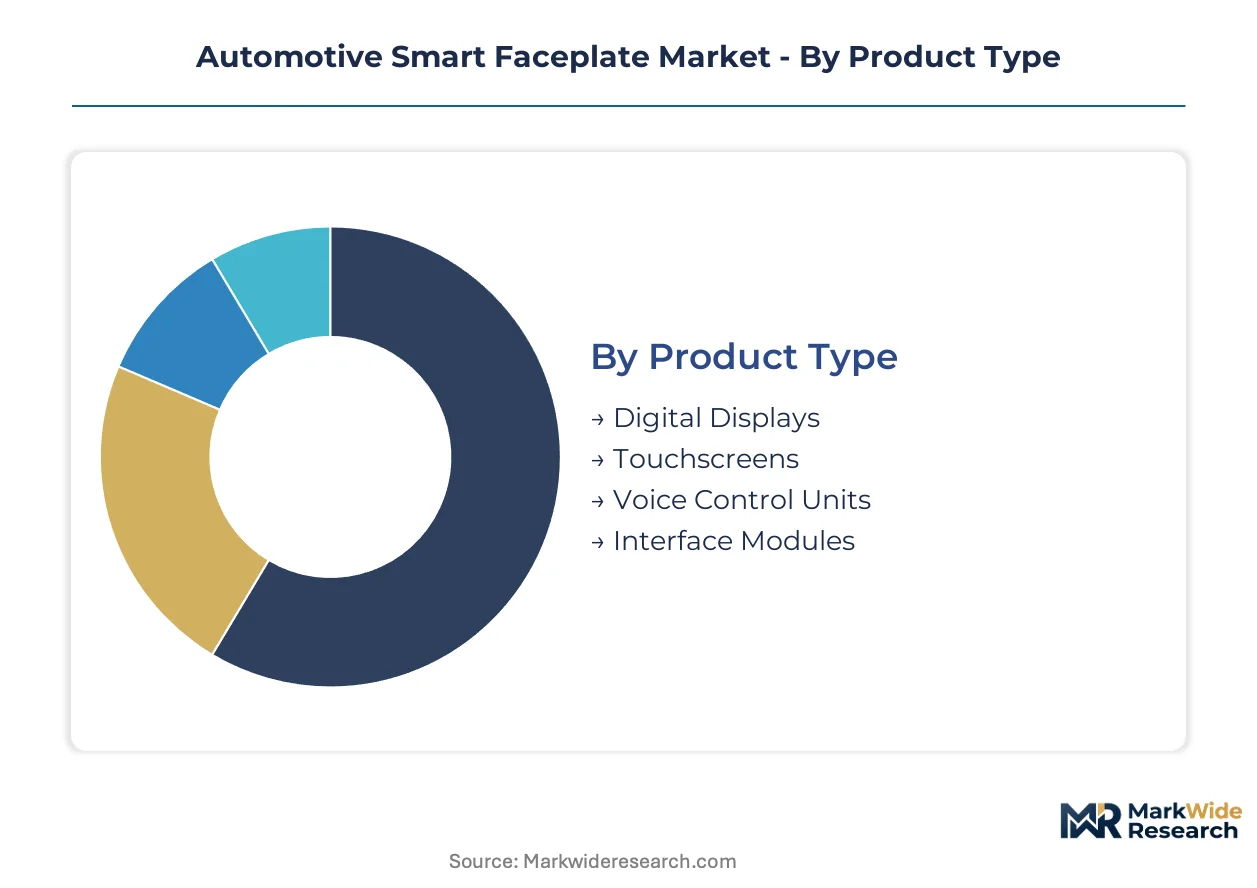
Smart faceplate procurement patterns diverge sharply between integrated cockpit programs and standalone replacement channels. Understanding these segment boundaries clarifies where margin pools concentrate versus where price competition erodes returns.
Product Type:
Touchscreens face intensifying substitution pressure from voice-first and gesture-based alternatives as OEMs pursue eyes-off-road compliance targets.
- Touchscreens:Capacitive multi-layer panels dominate premium vehicle architectures as the central control anchor. German and Chinese EV manufacturers specify haptic-enabled variants to reduce mechanical switch count while maintaining tactile feedback for climate and infotainment functions.
- Digital Displays:Thin-film transistor backplane assemblies with ambient light integration serve secondary readout positions in instrument clusters and passenger zones. Demand concentrates in the Yangtze River Delta cluster where domestic display foundries supply local EV platforms at compressed lead times.
- Voice Control Units:Far-field microphone arrays with natural language processing offload visual interaction demands in commercial vehicle cabins.
- Interface Modules:Trim-integrated assemblies combining multiple input modalities for unified cockpit aesthetics.
Touchscreens anchor the volume base while gesture recognition modules gain share at the steepest rate.
Technology:
Wireless connectivity tiers stratify by data throughput requirements rather than hardware cost alone.
- Gesture Recognition:Time-of-flight and radar-based non-contact sensing enables eyes-off-road operation for safety-critical adjustments. Premium German manufacturers embed these systems to meet EU AI Act algorithmic transparency requirements while isolating AI-enabled product lines from compliance risk.
- Bluetooth:Low-energy protocol stacks handle smartphone pairing and audio streaming at minimal power draw. Aftermarket retrofit channels in North America specify these modules for legacy vehicle compatibility where full system replacement proves uneconomical.
- NFC:Near-field authentication enables secure device pairing and digital key functionality.
- Wi-Fi:High-bandwidth connectivity supports over-the-air updates and cloud service attachment.
Bluetooth sustains the largest installed base as gesture recognition climbs the fastest.
End User:
Procurement authority shifts upstream as OEMs consolidate cockpit integration responsibility under direct supplier relationships.
- OEMs:Vehicle manufacturers specifying complete faceplate systems for new platform development. China's domestic EV brands leverage subscription-activated feature unlocking to separate hardware procurement from software monetization.
- Tier-1 Suppliers:System integrators combining display, haptic, and control layer competencies under single engineering teams. Robert Bosch GmbH and Continental AG anchor European sourcing through captive semiconductor and haptic research capabilities respectively.
- Aftermarket Providers:Independent channels serving vehicle modification and repair demand outside warranty coverage.
- Dealerships:Authorized retail networks handling warranty replacements and trim-level upgrades.
OEMs drive the majority of specification value while Tier-1 Suppliers capture the steepest engineering margin expansion.
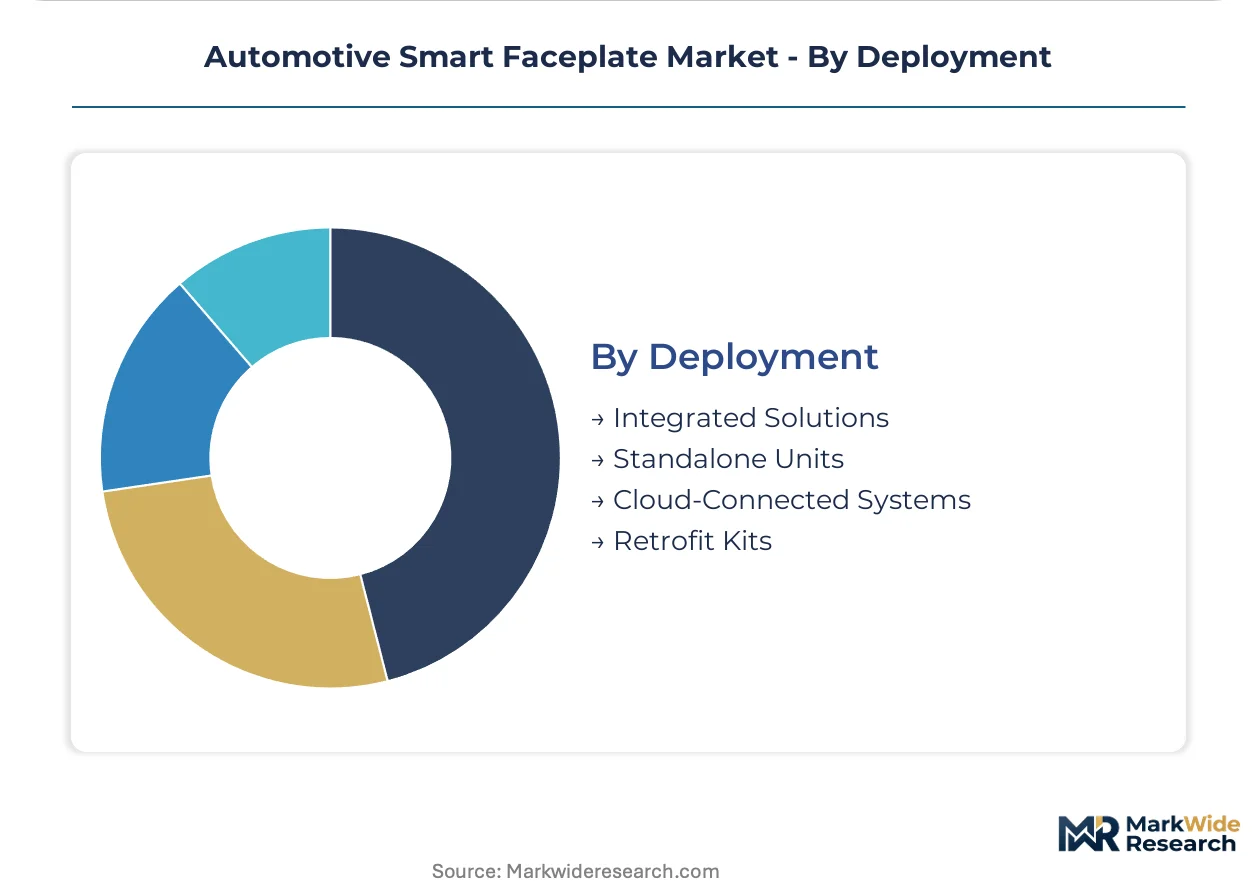
Deployment:
Architecture choices determine recurring revenue attachment potential versus one-time hardware monetization.
- Cloud-Connected Systems:Firmware-updatable platforms enabling over-the-air feature activation and telemetry services. China's GB standards for in-vehicle data transmission mandate encryption levels that concentrate margin pools among suppliers with SAMR-certified security documentation.
- Integrated Solutions:Factory-installed modules embedded within unified cockpit electronics. Bavaria's supplier corridor ships these configurations to premium German manufacturers pursuing reduced wiring harness complexity.
- Standalone Units:Self-contained replacements for damaged or obsolete faceplates.
- Retrofit Kits:Aftermarket packages adapting legacy vehicles to contemporary interface standards.
Integrated Solutions dominate unit volume as Cloud-Connected Systems expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates with German and Chinese OEMs while assembly-tier suppliers in Southeast Asia absorb margin compression from indium tin oxide volatility. The EU Cyber Resilience Act and China's GB standards are forcing parallel certification investments that favor suppliers with regulatory scale. Regional demand clusters around automotive electronics corridors where display foundries and haptic research centers co-locate.
Germany
Premium electric vehicle manufacturers in Bavaria specify haptic-enabled faceplate modules to consolidate cockpit controls. The EU AI Act mandates CE marking with algorithmic transparency documentation for gesture-recognition systems. Continental AG's haptic research center in Regensburg anchors supplier engineering capacity for European OEM programs.
China
Domestic EV brands in the Yangtze River Delta leverage subscription-activated feature unlocking to separate hardware procurement from software monetization. SAMR enforces GB standards for in-vehicle data transmission requiring encryption for NFC and Wi-Fi-enabled faceplates. Display foundry operators in Suzhou and Shanghai are expanding capacity to serve local automotive cluster demand.
United States
Fleet operators at North American logistics companies specify force-sensitive resistor arrays for heavy-duty truck cabins to reduce warranty claims. NHTSA eyes-off-road compliance standards accelerate gesture recognition procurement for safety-critical adjustments. Midwest automotive suppliers ship thermal-managed interface modules to Detroit-area OEM integration facilities.
Japan
DENSO Corporation dominates thermal-managed interface production for domestic and North American vehicle platforms. METI industrial policy supports capacitive-piezoelectric convergence research for commercial vehicle durability applications. Nagoya-area suppliers coordinate materials science and firmware simulation for minus forty to eighty-five degrees Celsius operating ranges.
India
The PLI scheme for automotive electronics pulls assembly investment toward component manufacturing incentives outside traditional China-centric sourcing. BIS certification requirements for imported electronic subassemblies create localization pressure for faceplate system integrators. Tamil Nadu and Gujarat automotive corridors attract tier-one supplier engineering centers serving export-bound production.
Automotive Smart Faceplate Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated cockpit specialists commanding engineering premiums while display foundry operators compete on scale. The market structures around three tiers: semiconductor-captive system integrators, haptic research-anchored European suppliers, and thermal-management-focused Japanese manufacturers. Consolidation pressure intensifies as OEMs reduce mechanical switch count and demand single-source accountability for touch-layer and actuator integration. Dominant competitive moves include captive semiconductor sourcing and haptic competency consolidation under unified engineering teams.
Among Germany-based system integrators, Robert Bosch GmbH and Continental AG exemplify the semiconductor-captive and haptic-research archetypes respectively. DENSO Corporation represents the thermal-management specialist position anchored in Japanese production heritage. These three companies illustrate how geographic clustering around regulatory corridors—Bavaria for EU AI Act compliance, Aichi Prefecture for METI-supported durability standards—shapes competitive positioning without requiring identical capability profiles.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| DENSO Corporation |
| Visteon Corporation |
| Panasonic Corporation |
| LG Display Co., Ltd. |
| Hyundai Mobis |
| Japan Display Inc. |
| Magna International Inc. |
| Others |
Value Chain & Pricing Dynamics
Ninety-day inventory cycles for indium tin oxide transparent conductor layers tie pricing power directly to display foundry concentration in Suzhou and Shanghai, amplifying margin compression for assembly-tier suppliers when mining output constraints tighten. This lead-time band forces tier-one integrators to choose between captive material sourcing and spot-market exposure, restructuring how haptic-enabled modules are costed for European and Chinese OEM programs.
Pricing Analysis
The customization-premium spread between configured-to-order haptic faceplates and standard touchscreen assemblies runs three-tier pricing structure across premium, standard, and economy levels, with certification tier under the EU Cyber Resilience Act and China's GB standards as the primary differentiation driver. Price erosion runs through the standard tier as display foundry operators compete on scale, while premium variants with algorithmic transparency documentation for gesture recognition capture margin insulation. Fleet operators in North American logistics show highest price sensitivity due to warranty claim risk, whereas German premium EV manufacturers exhibit lowest sensitivity given consolidated cockpit integration budgets.
Supply Chain Analysis
Single-source haptic actuator production concentrates among three East Asian component houses, creating concentration risk that ripples through tier-one assembly schedules when precision linear resonant actuator allocation tightens. Geographic supply concentration centers on China for display foundry output, Germany for haptic research and system integration, and Japan for thermal-managed interface production. Raw material dependencies draw from indium tin oxide for transparent conductors, piezoelectric ceramics for force-sensing arrays, and semiconductor backplanes for touch-layer controllers. Distribution runs through Bavaria's supplier corridor for European OEM direct relationships and the Yangtze River Delta automotive cluster for domestic Chinese EV platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
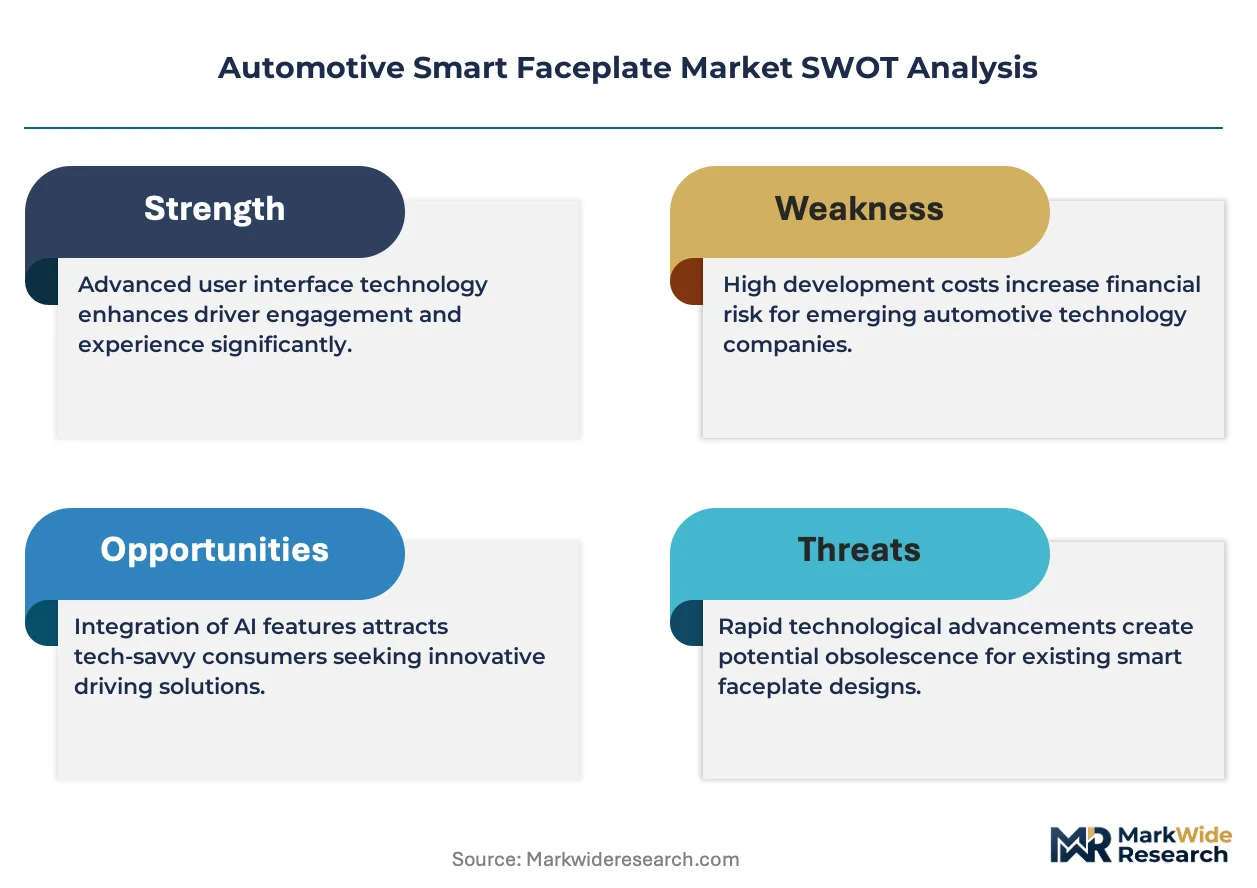
This market tracks as a cyclical recovery anchored to automotive production normalization following semiconductor shortage de-stocking, with EV platform ramp schedules in Germany and China serving as the demand swing factor.
For Market Incumbents: Consolidate touch-layer and actuator competencies under unified engineering teams to compress development cycles threatened by haptic feedback integration complexity. Secure SAMR-certified security documentation for cloud-connected systems to defend against emerging Chinese domestic suppliers leveraging GB standards compliance as a procurement wedge. Add captive semiconductor sourcing capacity to isolate margin control from indium tin oxide price volatility. For New Entrants and Emerging Players: CE marking fast-track for gesture-recognition modules under EU AI Act algorithmic transparency requirements opens white-space in European premium EV programs where incumbent certification backlogs create procurement gaps. Target India's PLI scheme corridor in Tamil Nadu and Gujarat for assembly investment pulled outside China-centric sourcing. Lead with force-sensitive resistor arrays for commercial vehicle cabins where glove-operation durability specifications exceed incumbent vibration tolerance. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because subscription-activated feature unlocking restructures OEM monetization toward firmware licensing attach rates. Acquisition candidates cluster around thermal-management specialists with minus forty to eighty-five degrees Celsius simulation capabilities and haptic research labs with Regensburg-style OEM anchoring. Monitor cloud-connected faceplate penetration in China's domestic EV brands as the inflection signal for software margin pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Haptic Competency Consolidation | Single-source accountability for touch-layer and actuator integration reduces OEM supplier count and accelerates platform development timelines. |
| GB Standards Certification Investment | SAMR encryption documentation for NFC-enabled faceplates unlocks domestic Chinese EV procurement channels closed to uncertified competitors. |
| Cloud-Connected Architecture Deployment | Over-the-air feature activation enables recurring software revenue attachments that shift margin pools beyond one-time hardware monetization. |
| Force-Sensing Array Commercialization | Capacitive-piezoelectric convergence targets heavy-duty truck cabins where North American fleet operators prioritize warranty claim reduction. |
| India PLI Scheme Localization | Component manufacturing incentives in Tamil Nadu and Gujarat pull assembly investment toward BIS-compliant export production. |
Study Parameters
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributors, and dealership operations managers, and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed automotive electronics suppliers, and customs records for indium tin oxide trade flows. Bottom-up segment sizing across product type, technology, end user, and deployment categories was triangulated with top-down market boundary checks from regulatory filing analysis.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics, with segmentation modeled across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from fitted growth curves calibrated to EV platform ramp schedules and haptic module adoption curves, with specific inputs including EU AI Act CE marking timeline assumptions and China SAMR GB standards enforcement intensity.
Underlying assumptions cover automotive production normalization, semiconductor supply continuity, and regulatory certification timeline convergence, with deviation risk concentrated in indium tin oxide mining output constraints and divergent EU-China validation cycle synchronization. Practitioners should keep alternative scenarios live as EV subsidy phase-out schedules and cyber resilience enforcement intensity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
Automotive Multi-Layer Display Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Heat Shield Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Exterior Car Accessories Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Auto Internal Connector Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
North America Automotive Seat Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Automotive Smart Window Market