
 Automotive Roof Liners Market | 2026-2036
Automotive Roof Liners Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Roof Liners Market Outlook
Automotive textile manufacturing in Mexico's Bajío corridor is restructuring capacity to serve North American electric vehicle assembly. Grupo Antolin leverages vertical integration from yarn to finished headliner to control cost positions across premium programs. Toyota Boshoku anchors Japanese OEM supply relationships through dedicated engineering centers in Kentucky and Ontario.
Automotive roof liners are laminated composite assemblies, typically combining a thermoplastic or fiberglass substrate with foam insulation and fabric facing, designed to provide acoustic damping, thermal insulation, and interior aesthetic finish in passenger compartments. The product type segment shows fiberglass substrates gaining share in electric vehicle platforms where weight reduction intersects with fire-resistance requirements, while polyurethane dominates mainstream ICE applications through established cost curves. Among end users, OEMs capture the dominant value pool through long-term supply agreements, though aftermarket providers compete on replacement cycle timing and regional logistics density.
EPA vehicle interior air quality guidelines and REACH substance restrictions in Europe constrain adhesive and foam chemistries, pushing suppliers toward water-based bonding systems and recycled polyester content. China's SAMR enforces GB standards for volatile organic compound emissions that directly determine material qualification for domestic production. Stakeholders must monitor evolving chemical compliance thresholds as regulatory divergence between North America and Europe accelerates formulation complexity.
Market Dynamics
Electric vehicle platform architectures are compressing roof liner specifications toward unified lightweight-acoustic designs that satisfy both thermal management and fire-resistance requirements simultaneously.
Growth Catalysts
- REACH substance restrictions:ECHA's evolving chemical frameworks are accelerating water-based adhesive adoption across European supply chains, creating qualified supplier advantages for compliant formulators.
- Bajío manufacturing corridor:Mexico's concentrated automotive textile capacity is capturing North American EV assembly demand through proximity logistics and tariff-advantaged positioning.
- Recycled PET fiber integration:Circular material specifications from premium OEM programs are pulling post-consumer polyester content into headliner facing layers at scale.
Market Restraints
- Polyol price volatility:Crude-linked polyurethane foam feedstock costs create margin compression for suppliers locked into annual OEM pricing agreements.
- Substrate supplier concentration:Thermoplastic sheet capacity concentrates among specialized compounders in Germany and Japan, creating single-source vulnerability for tier-2 laminators.
- Flammability standard divergence:FMVSS 302 in the United States and ECE R118 in Europe maintain incompatible test protocols, forcing parallel certification investments.
Strategic Opportunities
- Czech Republic production hub:Central European automotive clusters offer underutilized lamination capacity for suppliers seeking REACH-adjacent qualification without German cost structures.
- SAMR GB standards alignment:China's volatile organic compound emission mandates create first-mover advantage for suppliers achieving simultaneous GB and REACH compliance.
- Thermoplastic composite convergence:Glass-mat thermoplastic substrates are merging with in-mold decoration processes to eliminate secondary fabric wrapping operations.
Industry Challenges
- Acoustic engineer scarcity:OEM technical centers face recruitment gaps for specialists capable of integrating multi-physics simulation across substrate-foam-fabric interfaces.
- Tooling amortization pressure:Deep-draw thermoforming molds for complex roof geometries require capital deployment against uncertain EV platform volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Roof Liners Market |
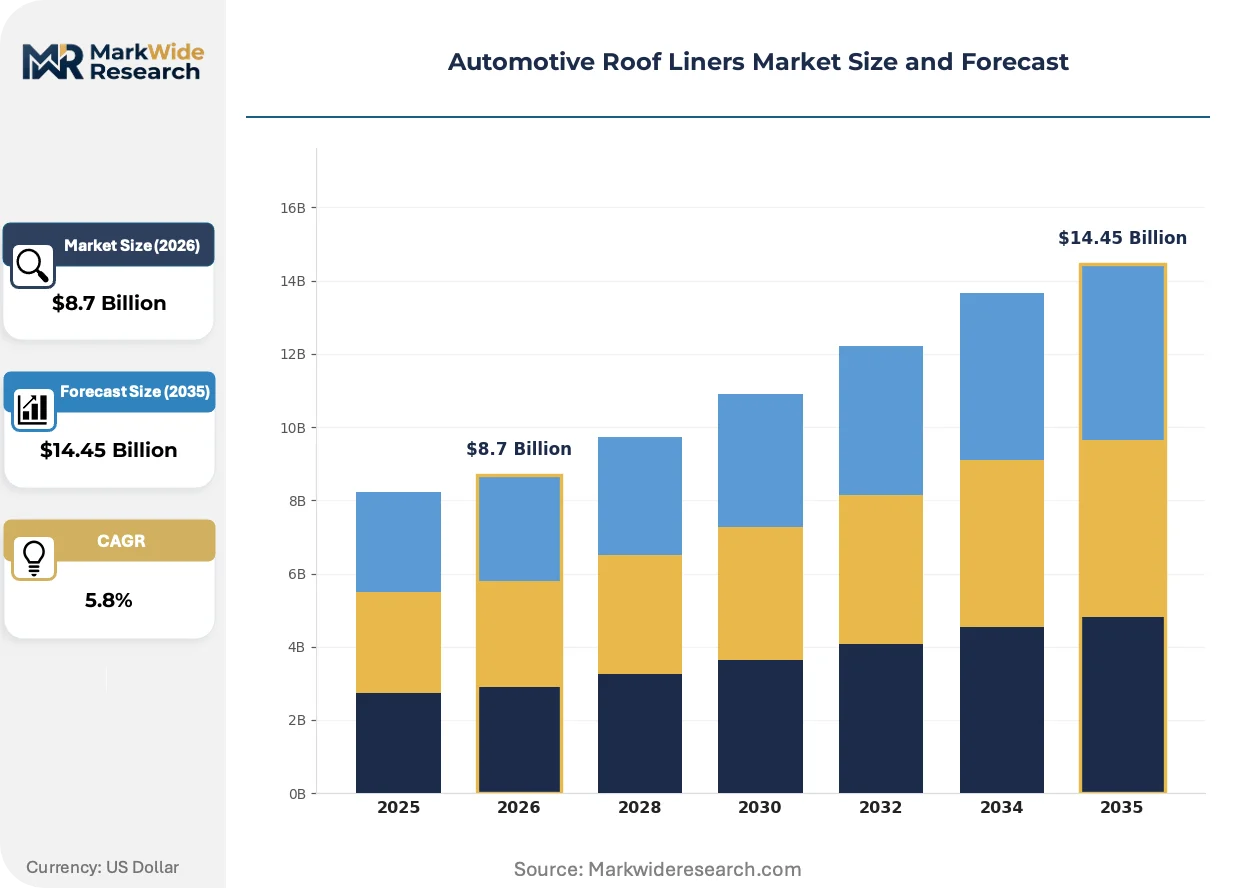
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
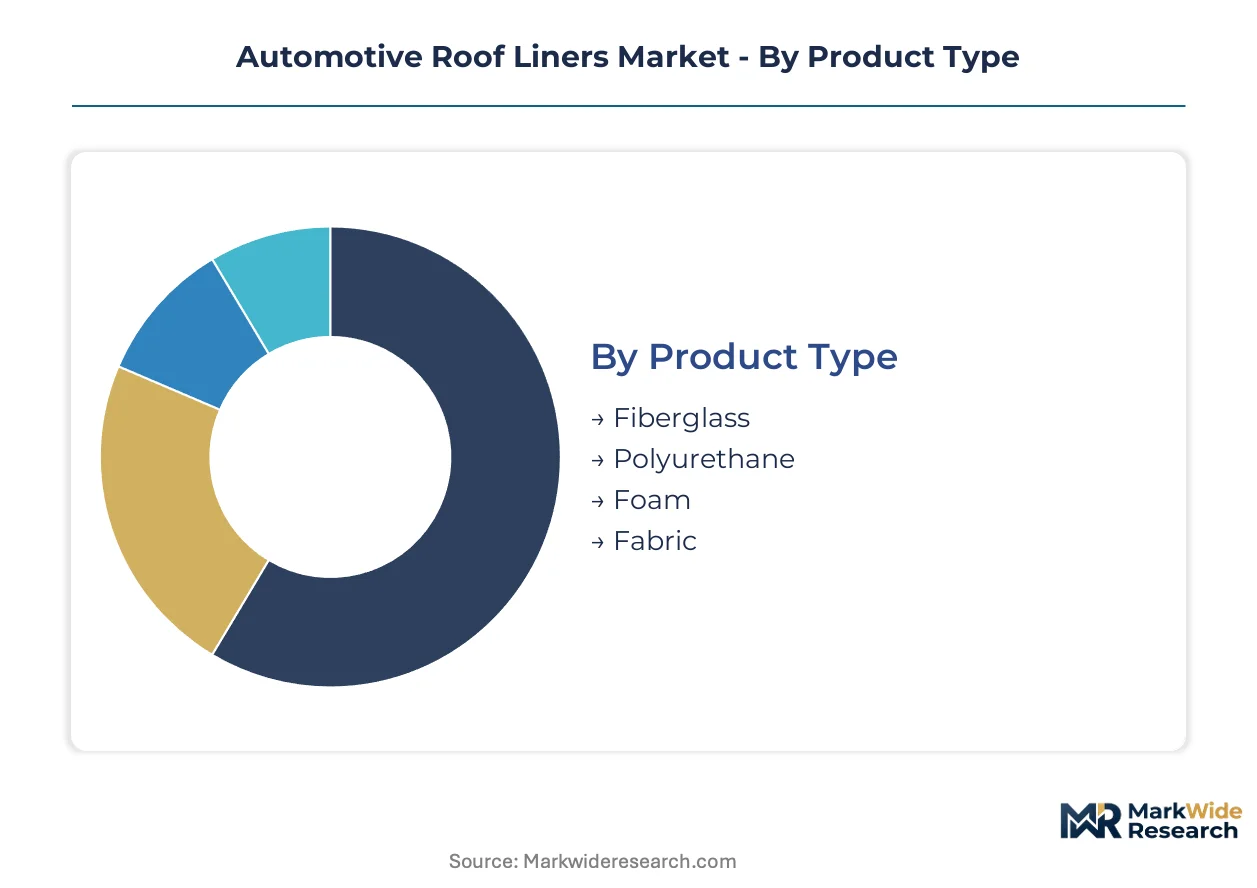
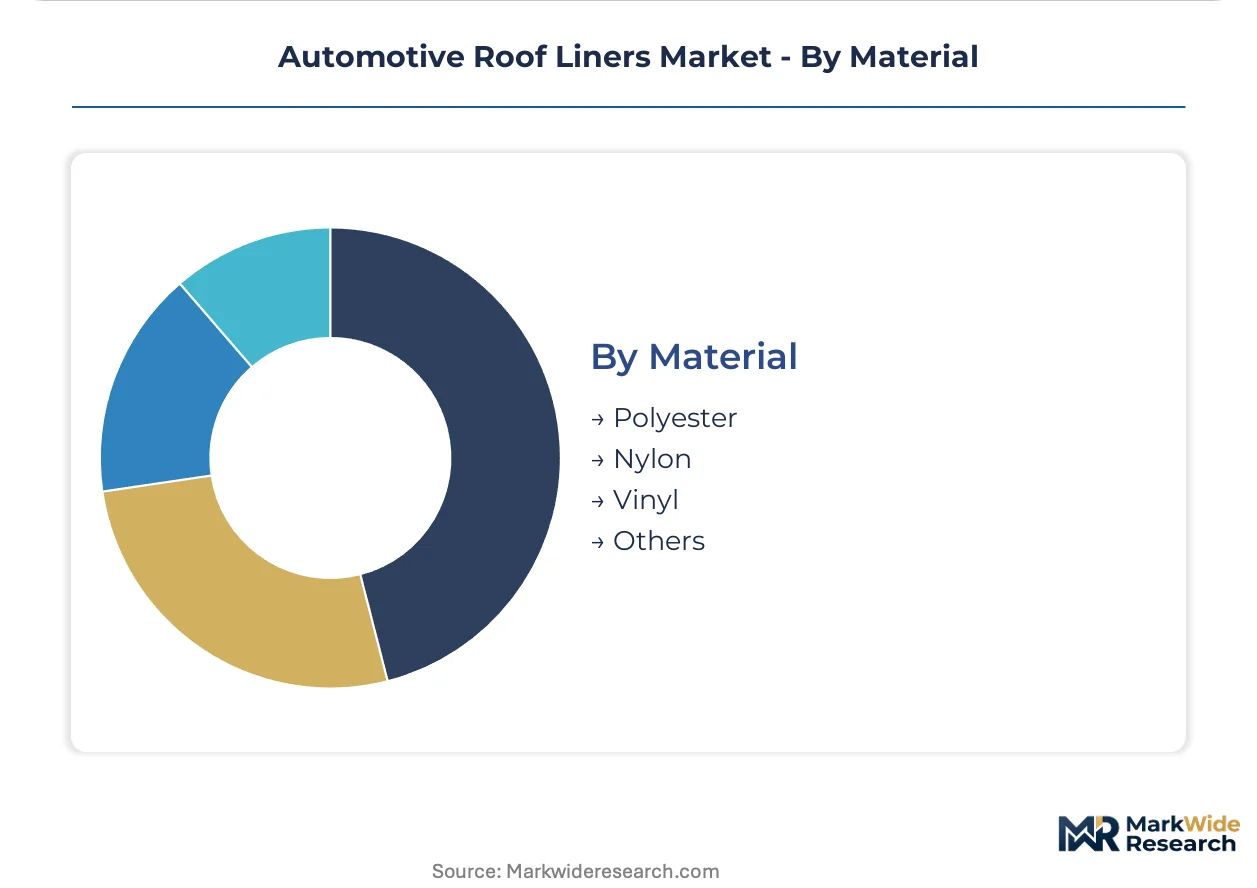
| Segmentation | Product Type: Fiberglass, Polyurethane, Foam, Fabric End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Dealers Installation Type: Direct Fit, Custom Fit, Universal Fit, Snap-In Material: Polyester, Nylon, Vinyl, Others |
| Companies Covered | Grupo Antolin, Toyota Boshoku Corporation, Motus Integrated Technologies, IAC Group, Lear Corporation, Howa Co., Ltd., UGN, Inc., SA Automotive, Hayashi Telempu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Roof Liners Market Strategic Shifts
Material science advances and regulatory chemistry constraints are converging to redefine roof liner construction methods, compressing traditional multi-step lamination into integrated forming processes.
Glass-mat thermoplastic substrates are consolidating substrate and carrier functions into single-layer structures that accept direct textile bonding without intermediate foam cores. Premium electric vehicle programs in Germany and the United States are specifying these consolidated assemblies for weight-critical applications. The technology is consolidating three-tier supply chains into direct substrate-to-OEM relationships that displace independent foam converters.
REACH Annex XVII substance restrictions are eliminating certain flame-retardant chemistries from polyurethane formulations, forcing reformulation toward phosphorus-based alternatives with modified processing windows. European tier-1 suppliers are absorbing compliance costs through dedicated chemical management teams. The passenger van segment faces the steepest transition curve due to stringent fire-resistance requirements combined with cost-sensitive procurement.
Program-based sourcing contracts are compressing supplier selection timelines and unbundling engineering services from unit pricing. Tier-1 laminators in Ontario and Kentucky are responding with embedded design teams that quote tooling and piece-price simultaneously. This pattern is most visible in Japanese OEM supply relationships where single-source agreements dominate platform life cycles.
Automotive Roof Liners Market Segmentation
Roof liner procurement decisions cascade through specification hierarchies where substrate chemistry, installation protocol, and material compliance intersect. Segment boundaries are hardening as electric vehicle platforms consolidate around unified lightweight-acoustic designs that satisfy multiple performance thresholds simultaneously.
Product Type:
Substrate specification determines lamination complexity, acoustic performance, and fire-resistance certification pathways. Material selection here locks in downstream supplier relationships and tooling investments.
- Fiberglass:Woven glass-mat thermoplastic composites serve as unified carrier-bonding layers that eliminate separate foam cores. Premium electric vehicle programs in Germany and the United States specify these substrates for weight-critical roof assemblies where FMVSS 302 and ECE R118 compliance must coexist.
- Polyurethane:Open-cell foam formulations dominate mainstream internal combustion engine applications through established cost curves and deep supplier familiarity. Polyol price volatility creates margin pressure for laminators locked into annual OEM pricing agreements.
- Foam:Reticulated and closed-cell variants provide acoustic damping density gradients in multi-layer assemblies. Passenger van programs demand specialized fire-retardant formulations that satisfy stringent ECE R118 protocols.
- Fabric:Woven and knitted facing layers deliver interior aesthetic finish and tactile quality. Recycled PET fiber integration is climbing fastest as circular material specifications from premium OEM programs pull post-consumer content into headliner production.
Mature deployment sits with polyurethane. Newer deployment is concentrated in fiberglass.
End User:
Procurement authority and volume concentration vary sharply across the value chain, with long-term agreements favoring integrated suppliers over fragmented service providers.
- OEMs:Original equipment manufacturers capture the dominant value pool through platform-life supply agreements that bundle engineering services with unit pricing. Program-based sourcing contracts are compressing supplier selection timelines and unbundling design from manufacturing quotes.
- Aftermarket Providers:Replacement cycle timing and regional logistics density determine competitive position. Inventory velocity constraints limit SKU breadth compared to OEM-directed production.
- Vehicle Assemblers:Contract manufacturing operations source roof liners as part of complete interior module assemblies. Proximity logistics in Mexico's Bajío corridor are capturing North American EV assembly demand.
- Dealers:Service channel distribution handles warranty replacement and collision repair volumes. Customer-facing operations prioritize same-day availability over specification breadth.
Volume concentration sits with OEMs. Margin expansion is concentrated in aftermarket providers.
Installation Type:
Assembly protocol selection reflects trade-offs between manufacturing efficiency, design flexibility, and field serviceability across vehicle lifecycle stages.
- Direct Fit:Pre-engineered assemblies match specific vehicle roof geometries without secondary modification. OEM production lines specify these variants to eliminate in-plant trimming operations and reduce warranty exposure.
- Custom Fit:Tailored dimensions accommodate specialty vehicle conversions and premium coachbuilding applications. Low volume and high engineering touch limit supplier participation to dedicated interior specialists.
- Universal Fit:Adjustable mounting systems serve aftermarket replacement where vehicle-specific tooling investment is uneconomical. Price competition is intense with minimal differentiation beyond material grade.
- Snap-In:Modular retention clips enable rapid installation and non-destructive removal for sunroof service access. Electric vehicle platforms are adopting these systems to simplify battery thermal management routing above the headliner plane.
Production scale sits with direct fit. Service flexibility is expanding most quickly in snap-in.
Material:
Facing layer chemistry determines volatile organic compound emissions, recyclability pathways, and tactile quality perception in passenger compartments.
- Polyester:Recycled PET fiber integration is scaling rapidly as REACH Annex XVII restrictions and China's GB standards push suppliers toward circular feedstocks. European tier-1 suppliers are absorbing compliance costs through dedicated chemical management teams.
- Nylon:High-tenacity yarns deliver abrasion resistance for commercial vehicle applications with elevated duty cycles. Premium passenger programs specify nylon for superior dimensional stability in climate-extreme operating environments.
- Vinyl:Thermoplastic facing layers offer cost-efficient moisture resistance and cleanability for fleet and rental vehicle segments. Regulatory pressure on plasticizer chemistries is constraining formulation flexibility.
- Others:Natural fiber composites and bio-based polymers occupy niche sustainability-focused programs. Technical maturity gaps limit deployment beyond concept vehicles and limited-production showcases.
Specification breadth sits with polyester. Sustainability positioning is climbing the fastest in others.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyol feedstock availability from Gulf Coast petrochemical complexes anchors North American polyurethane foam supply. German glass-mat thermoplastic substrate production serves premium electric vehicle architectures across European OEM programs. Chinese polyester fiber capacity scales recycled PET integration for interior facing layers under tightening emission mandates.
United States
Kentucky and Ontario engineering centers anchor Japanese OEM supply relationships through dedicated technical facilities. EPA vehicle interior air quality guidelines constrain adhesive and foam chemistries for domestic production. The Southeast automotive corridor concentrates lamination capacity to serve electric vehicle assembly expansion.
Germany
Premium electric vehicle programs specify lightweight acoustic roof assemblies combining thermal management with fire-resistance certification. ECHA's REACH Annex XVII substance restrictions eliminate certain flame-retardant chemistries from polyurethane formulations. Stuttgart and Munich automotive clusters host specialized substrate compounders supplying consolidated carrier-bonding layers.
China
SAMR enforces GB standards for volatile organic compound emissions that determine material qualification for domestic manufacturing. Yangtze River Delta automotive textile producers scale post-consumer polyester content into headliner facing layers. Shanghai-based engineering centers coordinate formulation alignment with European REACH thresholds.
Mexico
The Bajío corridor restructures textile manufacturing capacity to capture North American electric vehicle assembly demand through proximity logistics. Tariff-advantaged positioning attracts tier-1 laminators seeking to serve US-based OEM programs. Guanajuato and Querétaro host expanding lamination facilities with direct rail links to Texas assembly plants.
Czech Republic
Central European automotive clusters offer underutilized lamination capacity for suppliers seeking REACH-adjacent qualification. ECE R118 fire-resistance protocols govern passenger van programs sourcing from regional production hubs. Ostrava and Mladá Boleslav concentrate textile finishing capacity for German OEM supply relationships.
Automotive Roof Liners Market Competitive Environment
Global majors compete with regional champions across substrate technology and geographic proximity vectors. The vendor base organizes around three tiers: integrated interior module suppliers controlling substrate-to-finished assembly chains, specialized laminators competing on formulation chemistry, and regional fabricators capturing aftermarket replacement cycles. Consolidation pressure intensifies as program-based sourcing contracts compress supplier selection timelines. Dominant competitive moves include captive supply of recycled PET feedstocks and embedded engineering teams quoting tooling simultaneously with piece-price.
Among Japanese-anchored fabricators, Toyota Boshoku Corporation and Hayashi Telempu Corporation exemplify the integrated module supplier archetype through dedicated technical center investments. Grupo Antolin occupies a position representing European vertical consolidation from yarn through finished headliner production. These three companies anchor the premium-tier competitive vector where long-term platform agreements bundle engineering services with manufacturing scale.
| Leading Market Players |
|---|
| Grupo Antolin |
| Toyota Boshoku Corporation |
| Motus Integrated Technologies |
| IAC Group |
| Lear Corporation |
| Howa Co., Ltd. |
| UGN, Inc. |
| SA Automotive |
| Hayashi Telempu Corporation |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII substance restrictions in Europe gate qualified supply access and premium-tier pricing power, forcing laminators to absorb compliance costs through dedicated chemical management teams while OEMs unbundle engineering services from unit pricing.
Pricing Analysis
Warranty and service bundling separates OEM platform-life agreements from aftermarket replacement transactions. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Cost compression in polyurethane foam formulations is intensifying because polyol feedstock volatility outpaces annual pricing agreement adjustments. Aftermarket providers exhibit highest price sensitivity due to inventory velocity constraints limiting SKU breadth.
Supply Chain Analysis
Dual-sourcing requirements from German and Japanese OEMs mandate multi-supplier qualification for thermoplastic sheet substrates. Manufacturing concentrates in Germany, China, and Mexico, with raw material dependencies spanning glass-mat thermoplastics, polyol formulations, and recycled PET fiber. Single-source vulnerability in specialized substrate compounders creates supply chain risk. Distribution runs through tier-1 laminators with embedded engineering teams quoting tooling simultaneously with piece-price.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Program-based sourcing contracts compress supplier selection timelines, forcing consolidation among tier-2 laminators unable to absorb tooling amortization pressure against uncertain EV platform volumes.
For Market Incumbents: Lock in long-term platform agreements by embedding design teams that quote tooling and piece-price simultaneously. Captive supply of recycled PET feedstocks defends margin position against REACH-driven formulation complexity. Prioritize certification investment for simultaneous GB and REACH compliance to capture first-mover advantage in Chinese premium EV programs.
For New Entrants and Emerging Players: SAMR GB standards alignment in China opens a window for qualified formulators to penetrate premium electric vehicle supply chains. Target the Czech Republic production hub where underutilized lamination capacity offers REACH-adjacent qualification without German cost structures. Lead with water-based adhesive expertise as the go-to-market angle.
For Investors and Strategic Acquirers: Toyota Boshoku and Grupo Antolin platform standardization announcements are the leading indicator that integrated module supplier archetypes will dominate the premium tier. Five-to-ten year viability favors vertically consolidated players controlling substrate-to-finished assembly chains. Monitor acoustic engineer scarcity at OEM technical centers as the signal for supplier engineering service premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Consolidates three-tier supply chains into direct substrate-to-OEM relationships displacing foam converters. |
| Backward Integration | Captive supply of recycled PET feedstocks defends margin position against REACH-driven circular material mandates. |
| Long-term Supply Agreement | Bundles engineering services with unit pricing across platform-life commitments with Japanese OEMs. |
| Geographic Manufacturing Footprint | Mexico's Bajío corridor captures North American EV assembly demand through tariff-advantaged proximity logistics. |
| Green Certification Program | Simultaneous GB and REACH compliance creates qualified supplier advantages in premium electric vehicle programs. |
Study Parameters
Independent corroboration across OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and acoustic R&D directors underwrites the qualitative findings. Secondary validation draws from vehicle production databases, IHS Markit registration data, customs and trade records, and ECHA substance restriction filings. Bottom-up segmentation modeling triangulates against top-down market sizing approaches.
Rate-of-change decomposition separates volume growth from value expansion across substrate chemistry, vehicle propulsion architecture, and regional production cluster dimensions. CAGRs derive from modeled adoption curves for glass-mat thermoplastic substrates and recycled PET fiber integration rates. Forecast inputs include polyol price volatility assumptions and electric vehicle platform volume trajectories throughout the projection horizon.
The model assumes a particular technology adoption path; alternative pathways for glass-mat thermoplastic substrate consolidation would alter the outlook. Deviation in REACH Annex XVII substance restriction timelines or SAMR GB standards enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Heated Seat Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Automotive Interior Cleaner Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Capacitive Touch Switch Panels for Vehicle Interiors Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Convertible Roof Control Unit Market
Automotive Interior & Exterior
Car Door Latch Market
Automotive Interior & Exterior
Automotive Convertible Top Market