
 Automotive Door Frame Market | 2026-2036
Automotive Door Frame Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Door Frame Market Analysis
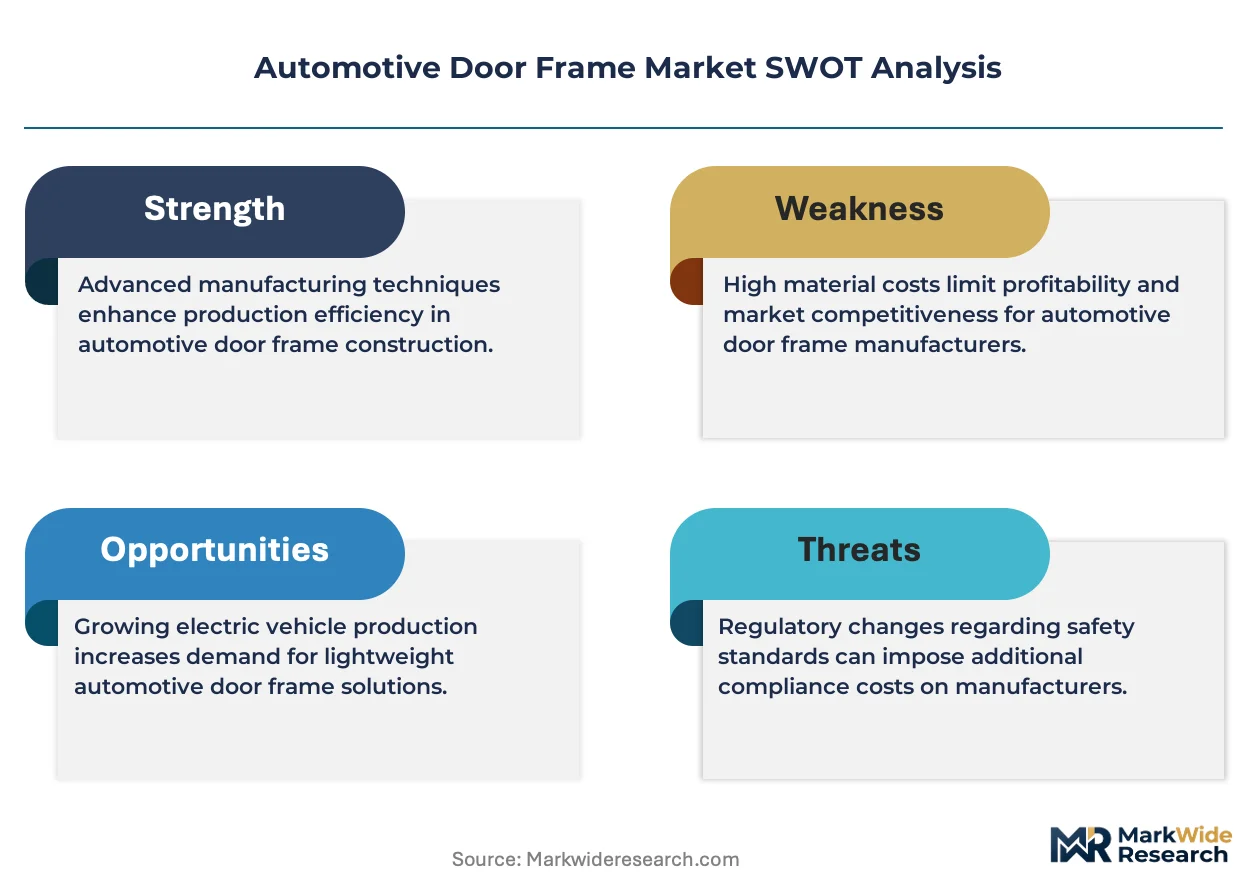
F-Gas Regulation is consolidating the cost-of-entry calculus for European door frame suppliers, forcing capital retooling toward low-emission joining technologies. ThyssenKrupp leverages its integrated steel-to-assembly footprint to sustain margin control across German OEM programs. Martinrea International anchors North American supply through proximity stamping operations near Detroit-based vehicle assemblers. Toyota Motor differentiates via captive production of high-strength steel door rings for hybrid platforms.
An automotive door frame is the structural perimeter member that supports hinge mounting, latching mechanisms, glass channels, and side-impact beams, typically fabricated from high-strength steel or 6xxx-series aluminum extrusions through progressive die stamping or hydroforming to achieve torsional rigidity targets exceeding 20 kN·m/deg. Its primary purpose is to maintain cabin structural integrity during side pole impacts while enabling modular assembly of sealing and glazing subsystems. Steel remains the dominant material segment due to established stamping infrastructure and crash-performance certification, though aluminum is gaining share where OEMs prioritize mass reduction for battery-electric range extension. Front door frames command the largest product type volume given higher replacement frequency and more complex integration of mirror mounts and beltline reinforcements.
NHTSA side-impact standards and IIHS small overlap protocols shape minimum section modulus requirements that directly dictate material gauge and reinforcement placement in North American designs. ECE R95 and China's GB standards for side pole intrusion create divergent test conditions that fragment tooling investments between regulatory zones. Stakeholders must monitor evolving UN R135 pole-impact severity levels and EPA lightweighting credit thresholds to calibrate material substitution timelines against capital recovery cycles.
Market Dynamics
Europe's F-Gas Regulation is compressing the viable tooling horizon for stamped steel door assemblies, forcing capital redeployment toward low-emission joining processes before amortization cycles complete.
Growth Catalysts
- Aluminum extrusion adoption:Battery-electric OEMs specify 6xxx-series aluminum door rings to offset pack mass, expanding hydroforming capacity at tier suppliers.
- India PLI scheme:Component manufacturing incentives attract door frame stamping investments for export-oriented vehicle programs.
- NHTSA side-impact protocols:Updated intrusion thresholds mandate reinforced beltline sections, sustaining high-strength steel demand in North American architectures.
Market Restraints
- Aluminum ingot volatility:LME price swings compress margin predictability for extrusion-dependent suppliers locked into annual OEM contracts.
- Tooling concentration in Germany:Progressive die manufacturing clusters around Stuttgart and Wolfsburg create single-point failure risk for European program launches.
- Weld-bonding technical ceiling:Dissimilar metal joining between steel hinges and aluminum frames remains unproven at volume cycle times.
Strategic Opportunities
- Thailand manufacturing corridor:Japanese and Chinese OEMs localize door frame supply for ASEAN export platforms, creating greenfield supplier entry points.
- GB standard harmonization:China's alignment with UN R135 test protocols reduces dual-certification burden for multi-region vehicle architectures.
- Closed-loop aluminum recycling:OEMs and mills co-locate scrap reprocessing to secure low-carbon billet supply under EU Green Deal carbon border adjustments.
Industry Challenges
- Multi-material simulation expertise:Finite element modeling for hybrid steel-aluminum door structures requires rare cross-trained engineering talent.
- Side pole certification timelines:UN R135 severity level upgrades extend validation cycles by 8-14 months, delaying program revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Door Frame Market |
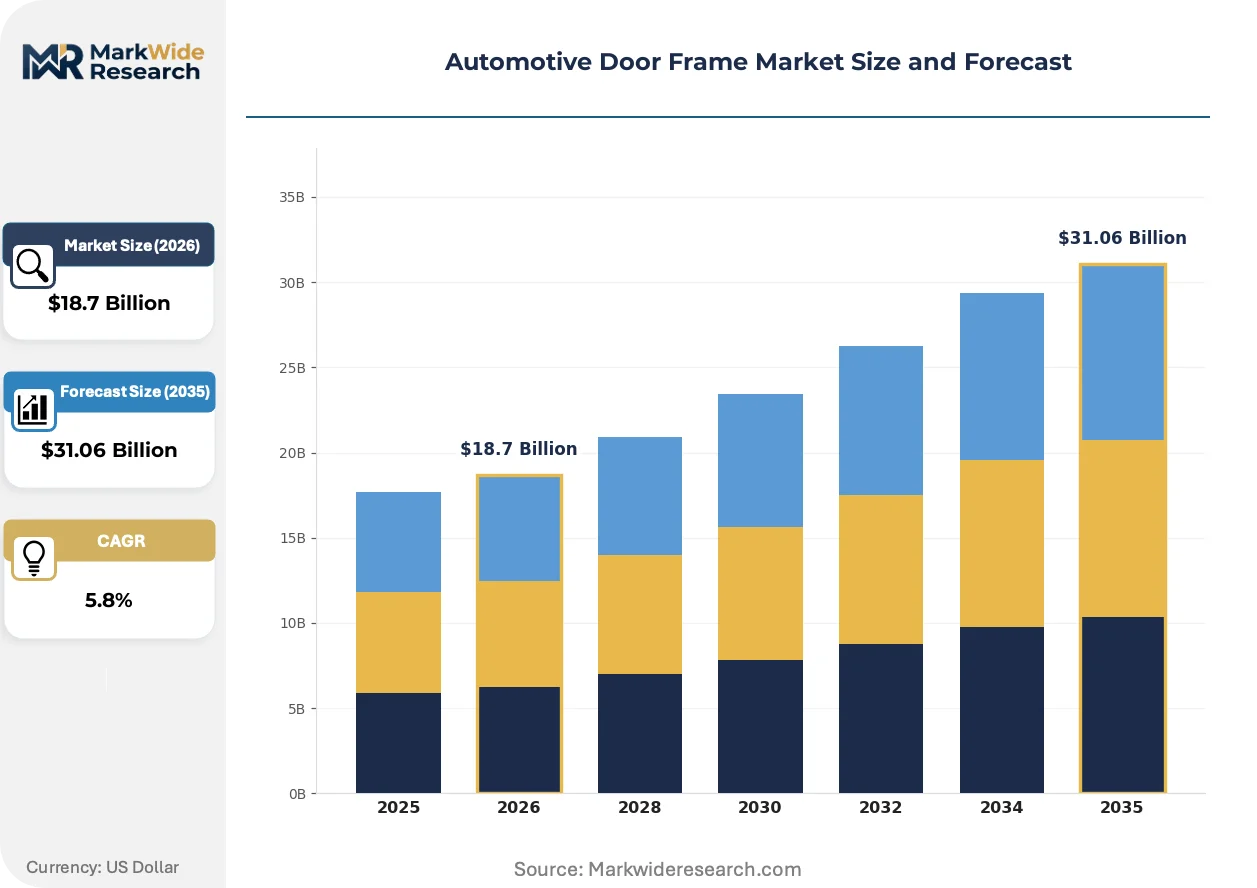
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Door Frame, Rear Door Frame, Side Door Frame, Liftgate Frame Material: Steel, Aluminum, Composite, Plastic Manufacturing Stage: Die Casting, Injection Molding, Stamping, Assembly End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Ford Motor Company, American Industrial, Martinrea International, Amino North America, Hayes Lemmerz International, ThyssenKrupp, Toyota Motor, AISIN U.S.A. Manufacturing, General Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Door Frame Market Emerging Trajectories
Material substitution and regulatory stringency are rewiring competitive advantage from stamping scale to joining precision and lifecycle carbon accounting.
Hot-stamped boron steel door rings are expanding into mass-market electric vehicle platforms as OEMs reconcile side-impact rigidity with cabin packaging constraints. Tier suppliers in Germany and Japan retrofit press lines with tailored tempering controls to meet 1500 MPa tensile specifications. This metallurgical shift is expanding into previously aluminum-dominated segments where crash performance now outweighs mass reduction priorities.
The EU F-Gas Regulation bans hydrofluorocarbon-based cooling in resistance welding operations, compelling door frame suppliers to adopt laser or mechanical joining for aluminum-steel interfaces. Industrial consequence includes accelerated depreciation of conventional spot-welding assets and retraining of production technicians. German OEMs now specify low-emission joining methods in RFQ documents, shifting supplier qualification criteria.
Consolidated procurement by battery-electric specialists is compressing supplier bases from five-tier to three-tier structures for door frame assemblies. Direct OEM relationships with aluminum extruders and steel mills displace traditional tier-one stampers in contract negotiations. This concentration is most visible in California and Shanghai, where vertical vehicle assemblers source perimeter structural members through single-source agreements with metallurgical processors.
Automotive Door Frame Market Segmentation
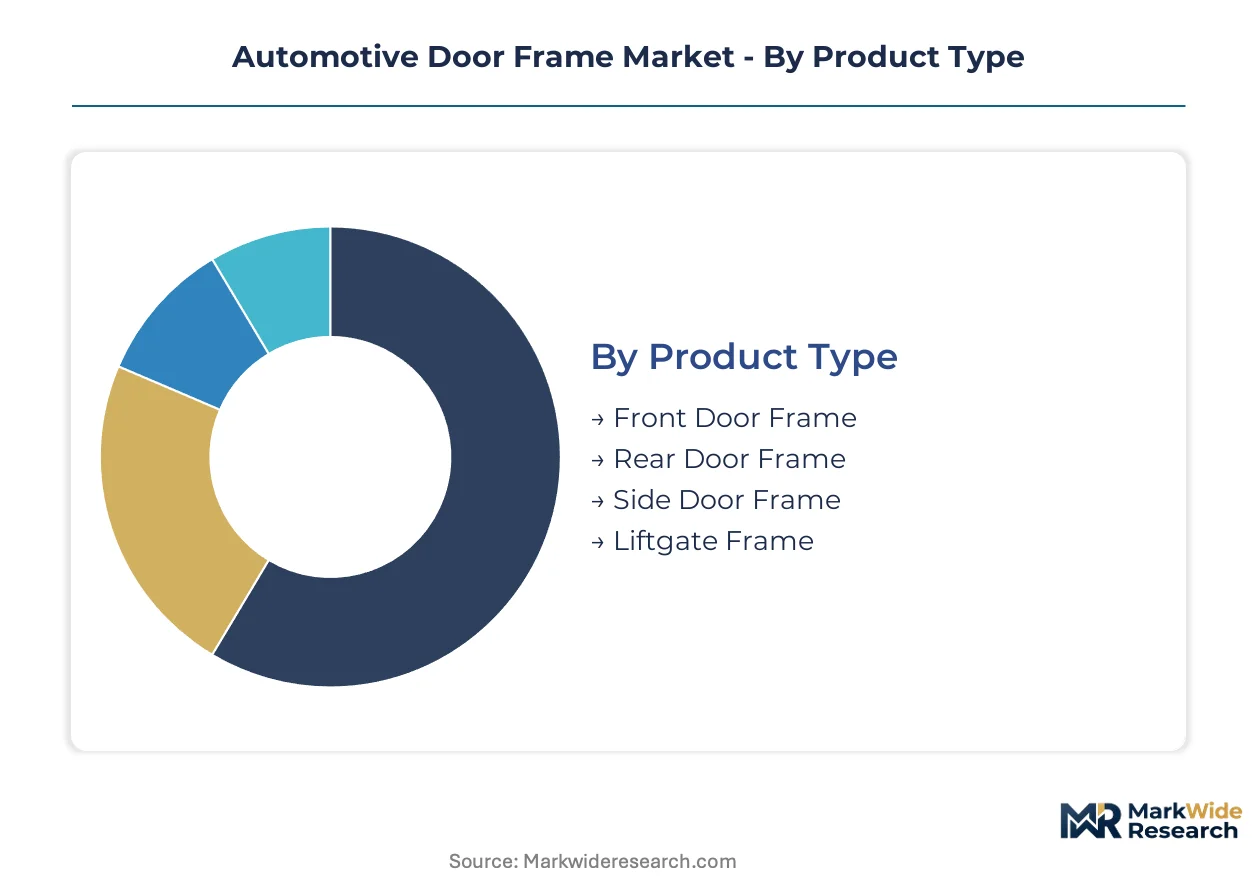
Automotive door frame procurement splits along material-performance tradeoffs and integration depth, with OEMs calibrating stamping investments against battery-electric range targets. Tier suppliers must maintain parallel competencies across steel stamping and aluminum extrusion to serve divergent program specifications without asset stranding.
Product Type:
Integration depth varies sharply: front and rear door frames ship as standalone modules to assembly plants, while liftgate frames embed within larger closure systems requiring deeper supplier-OEM engineering collaboration.
- Front Door Frame:Structural perimeter members integrate mirror mounts, beltline reinforcements, and side-impact beams, typically fabricated from high-strength steel or 6xxx-series aluminum extrusions. Demand concentrates in Germany's manufacturing corridor where premium OEMs specify complex hinge-latch integration for driver accessibility. NHTSA side-impact protocols sustain reinforced section requirements in North American programs.
- Rear Door Frame:Simpler geometry reduces hinge complexity but requires child-safety latch integration and tighter sealing tolerances. Procurement runs through tier-1 suppliers in Stuttgart and Wolfsburg serving European hatchback and sedan platforms where rear door replacement frequency lags front assemblies.
- Side Door Frame:Encompasses sliding door architectures in commercial vans and minivans, demanding roller-guided track integration absent from hinged designs. Japanese OEMs in Thailand's manufacturing corridor specify these for ASEAN export platforms.
- Liftgate Frame:Embedded within rear closure modules combining glass, wiper systems, and spoiler mounts, requiring deeper OEM-supplier co-development cycles. Battery-electric specialists in California source these through single-source metallurgical processor agreements.
Volume placements concentrate in Front Door Frame; the faster expansion belongs to Liftgate Frame as electric SUVs proliferate.
Material:
Cost tier stratification separates commodity steel from premium aluminum and developmental composites, with procurement teams arbitrating between stamping infrastructure amortization and mass-reduction credits.
- Steel:Dominant segment leveraging established progressive die infrastructure and crash-performance certification, with hot-stamped boron grades expanding into mass-market electric platforms. German suppliers retrofit press lines with tailored tempering controls to meet 1500 MPa tensile specifications for side-impact rigidity.
- Aluminum:6xxx-series extrusions specified by battery-electric OEMs to offset pack mass, though LME price swings compress margin predictability for suppliers locked into annual contracts. EU F-Gas Regulation accelerates substitution by banning hydrofluorocarbon-based welding.
- Composite:Carbon fiber reinforced polymers emerge in low-volume performance vehicles where mass reduction outweighs unit cost premiums. Technical validation cycles extend 8-14 months under evolving UN R135 severity protocols.
- Plastic:Limited to non-structural trim carriers and sealing subsystems, excluded from primary load-bearing applications by NHTSA intrusion thresholds and ECE R95 standards.
Steel retains the highest placement volumes; aluminum climbs the fastest as OEM procurement shifts toward range-extension architectures.
Manufacturing Stage:
Process maturity creates divergent capital recovery profiles, with stamping assets depreciating against regulatory timelines while hydroforming capacity expands.
- Die Casting:Deployed for aluminum hinge brackets and latch reinforcements requiring net-shape precision, with Chinese OEMs leveraging domestic equipment suppliers for cost positioning.
- Injection Molding:Seals glass run channels and trim carriers from engineered polymers, operating at cycle times incompatible with structural metal forming.
- Stamping:Core competency for high-strength steel door rings, with progressive die manufacturing concentrated around Stuttgart and Wolfsburg creating single-point failure risk for European launches.
- Assembly:Final integration of glass, seals, and hardware into door modules, with tier suppliers near Detroit anchoring North American supply through proximity stamping operations.
Stamping commands the deepest installed base; assembly operations gain share fastest as OEMs outsource complete door module integration.
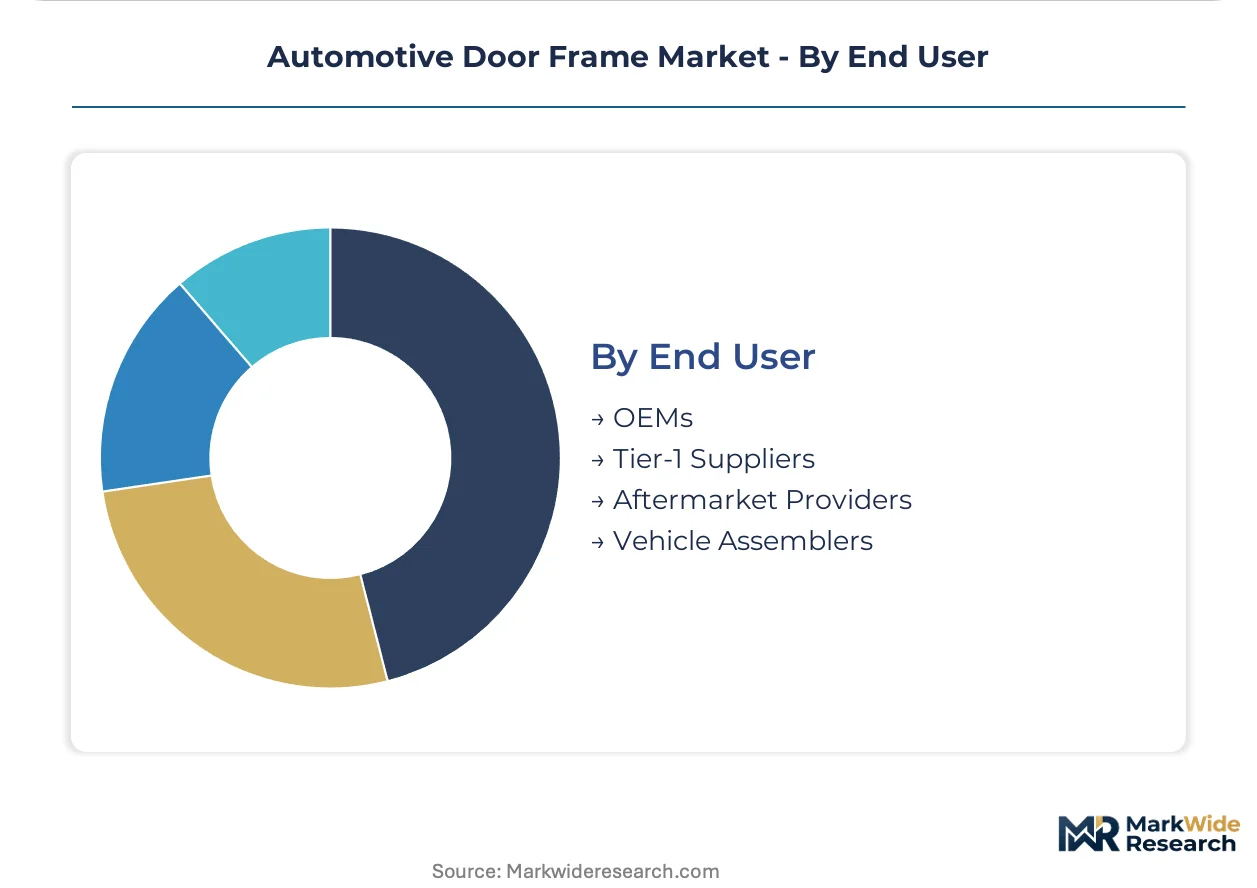
End User:
Customer type determines contract structure complexity, from multi-year OEM frame agreements to fragmented aftermarket replacement demand.
- OEMs:Direct procurement of perimeter structural members through single-source agreements with metallurgical processors, consolidating supplier bases from five-tier to three-tier structures in California and Shanghai.
- Tier-1 Suppliers:Martinrea International anchors North American supply through proximity stamping operations, while ThyssenKrupp leverages integrated steel-to-assembly footprints for German program margin control.
- Aftermarket Providers:Replacement demand concentrates in front door frames given higher collision damage frequency, with distribution fragmented across independent repair networks lacking OEM certification.
- Vehicle Assemblers:Contract manufacturers and emerging electric specialists bypass traditional tier structures, sourcing directly from extruders and mills.
Volume concentrates with Tier-1 Suppliers; Vehicle Assemblers expand procurement fastest as battery-electric specialists verticalize supply relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor tax incentives concentrate Japanese and Chinese OEM assembly operations, drawing tier suppliers into localized door frame production for ASEAN export platforms. This zone-driven pattern repeats across manufacturing corridors in Germany, the United States, China, and India where procurement gravity shapes supplier location decisions.
Germany
Stuttgart and Wolfsburg manufacturing clusters anchor European door frame demand as premium OEMs specify complex hinge-latch integration for driver accessibility. The F-Gas Regulation compels suppliers to abandon hydrofluorocarbon-based resistance welding, accelerating capital redeployment toward laser joining. ThyssenKrupp leverages its integrated steel-to-assembly footprint to sustain margin control across German OEM programs.
United States
Detroit-based vehicle assemblers sustain high-strength steel demand through NHTSA side-impact protocol compliance, with tier suppliers anchoring North American supply through proximity stamping operations. The EPA lightweighting credit thresholds calibrate material substitution timelines against capital recovery cycles. Martinrea International positions stamping capacity near Michigan assembly plants to serve just-in-sequence delivery requirements.
China
Yangtze River Delta and Pearl River Delta manufacturing zones concentrate battery-electric vehicle production, with OEMs specifying 6xxx-series aluminum door rings to offset battery pack mass. GB standard alignment with UN R135 test protocols reduces dual-certification burden for multi-region vehicle architectures. Shanghai-based vehicle assemblers source perimeter structural members through single-source agreements with metallurgical processors.
India
Maharashtra and Gujarat automotive corridors attract door frame stamping investments under the PLI scheme component manufacturing incentives for export-oriented vehicle programs. Domestic OEMs and multinational assemblers localize supply chains to serve Southeast Asian and Middle East export markets. Tier suppliers establish progressive die capacity near Pune and Chennai to meet regional content requirements.
Thailand
Rayong and Chonburi provinces within the Eastern Economic Corridor host Japanese and Chinese OEM assembly operations for ASEAN export platforms. Battery-electric specialists localize door frame supply to circumvent import tariffs and logistics costs. Greenfield supplier entry points emerge as traditional tier-one stampers establish hydroforming capacity for aluminum-intensive architectures.
Automotive Door Frame Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement tiers, with supplier bases consolidating from five-tier to three-tier structures in concentrated manufacturing zones. Steel-centric stampers maintain installed capacity advantages in crash-performance-certified architectures, while aluminum extrusion specialists capture share in battery-electric range-extension programs. Two strategic archetypes dominate: integrated steel-to-assembly conglomerates and proximity-focused tier-one stampers. Competitive moves center on M&A for joining technology capabilities and greenfield capacity placement near OEM assembly corridors.
Among North American fabricators, Martinrea International and Hayes Lemmerz International occupy positions within the tier-one stamper archetype, anchoring supply relationships through proximity manufacturing strategies. ThyssenKrupp represents the integrated conglomerate model, leveraging upstream metallurgical control through downstream assembly integration. Toyota Motor exemplifies captive production strategies, maintaining in-house door ring fabrication for hybrid platform differentiation. These three entities collectively illustrate the competitive tension between outsourced tier supply and vertical integration approaches.
| Leading Market Players |
|---|
| Ford Motor Company |
| American Industrial |
| Martinrea International |
| Amino North America |
| Hayes Lemmerz International |
| ThyssenKrupp |
| Toyota Motor |
| AISIN U.S.A. Manufacturing |
| General Motors |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between NHTSA-compliant high-strength steel and EU F-Gas-aligned aluminum extrusions manifests in parallel pricing ladders and geographically fragmented supply networks. OEM procurement teams arbitrage between amortized stamping infrastructure in Detroit and greenfield hydroforming capacity in Thailand's Eastern Economic Corridor.
Pricing Analysis
Short lead-time premiums attach to hot-stamped boron steel door rings from German progressive die clusters, while spot aluminum billet contracts trade at discounts reflecting LME volatility. Contract-based long-term offtake dominates OEM relationships, with price differentiation driven by crash-performance certification tier and geographic delivery cost. Pricing pressure stems from aluminum ingot swings compressing margin predictability for extrusion-dependent suppliers. Aftermarket providers exhibit highest price sensitivity due to fragmented repair network purchasing power.
Supply Chain Analysis
Direct-to-OEM channels handle battery-electric specialist demand through single-source metallurgical processor agreements in Shanghai and California. Supply concentrates in Germany, China, and Thailand, with raw material dependencies on 6xxx-series aluminum billet, hot-rolled high-strength steel coil, and boron-alloyed strip steel. Single-source vulnerability runs through Stuttgart and Wolfsburg progressive die manufacturing clusters. Distribution runs through tier-one stampers for legacy OEM programs and direct mill relationships for vertical vehicle assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive door frame sector sits in a metallurgical transition phase as laser joining and mechanical fastening displace hydrofluorocarbon-based resistance welding under EU F-Gas Regulation mandates.
For Market Incumbents: Deepen backward integration into aluminum billet supply through closed-loop recycling partnerships with European mills, securing carbon-border-adjusted feedstock. Retrofit German press lines with tailored tempering controls for 1500 MPa boron steel specifications before UN R135 severity upgrades extend validation timelines. Threat of consolidated three-tier procurement structures from battery-electric OEMs demands faster qualification cycles. For New Entrants and Emerging Players: Launch via greenfield hydroforming capacity in Thailand's Eastern Economic Corridor to capture Japanese and Chinese OEM ASEAN export platform demand. White-space targets include aluminum-intensive door rings for electric SUVs and laser-joining process development for mixed-material architectures. Go-to-market angle centers on low-emission joining certification ahead of EU Green Deal procurement criteria. For Investors and Strategic Acquirers: Re-rating potential sits with aluminum extrusion specialists possessing F-Gas-compliant joining capabilities given regulatory acceleration of steel-to-aluminum substitution. Long-term viability favors suppliers with parallel steel stamping and aluminum hydroforming competencies across the analysis window. Signal to watch: OEM RFQ documents specifying low-emission joining methods as mandatory qualification criteria.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Joining Technology Deployment | F-Gas Regulation compliance eliminates conventional spot-welding assets from European supplier qualification. |
| Closed-Loop Aluminum Recycling | EU Green Deal carbon border adjustments incentivize mill-processor co-location for low-carbon billet supply. |
| Thailand Manufacturing Footprint | Eastern Economic Corridor tax incentives concentrate ASEAN export platform supply near Japanese and Chinese OEM assembly. |
| Hot-Stamped Boron Steel Expansion | NHTSA side-impact protocols sustain reinforced section demand in North American electric vehicle architectures. |
| Three-Tier Supply Consolidation | Battery-electric specialists in California and Shanghai displace traditional tier-one stampers with direct mill relationships. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with OEM platform engineers, Tier 1 supplier procurement directors, aftermarket distributors, and dealership operations managers combined with vehicle production databases, IHS Markit registration data, SEC 10-K filings, and EU F-Gas implementation reports. Bottom-up segment sizing and top-down macro validation triangulated volume estimates across material, product type, and manufacturing stage dimensions.
Granularity-level modeling tracked propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster through the projection horizon. CAGRs derived from segment-level unit economics and input cost trajectory analysis. Forecast inputs included aluminum LME price scenarios, UN R135 severity adoption timelines, and PLI scheme incentive disbursement patterns.
Regulatory enforcement variance, commodity price volatility, and OEM platform launch delays are the dominant revision risks to modeled outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Automotive Floor Carpet Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Global Automotive Carpeting Market
Automotive Interior & Exterior
Global Light Vehicle (LV) Cabin AC Filters Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Glove Box Market