
 China Patient Monitoring Market | 2026-2036
China Patient Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
China Patient Monitoring Market Analysis
Modular multiparameter bundles is consolidating as the dominant configuration pattern across Chinese hospital procurement, replacing standalone device purchasing. Medtronic PLC leverages its integrated ecosystem strategy to anchor high-acuity contracts in Beijing and Shanghai tertiary centers. GE Healthcare competes through localized manufacturing scale in Wuxi, while Nihon Kohden Corporation specializes in electrocardiography monitoring subsystems for cardiology departments.
Patient monitoring encompasses continuous or intermittent physiological measurement through sensors, signal processors, and display interfaces, typically capturing electrocardiography, pulse oximetry, non-invasive blood pressure, and respiratory rate with sampling frequencies from 125 Hz to 1000 Hz depending on acuity level. Its primary commercial purpose spans early deterioration detection, post-operative surveillance, and chronic disease management across care settings. Bedside monitors occupy the largest revenue pool in urban hospital infrastructure, though remote monitoring systems represent the fastest-expanding segment as Cloud-Based technology enables real-time data transmission from homecare providers to centralized clinical teams. Wearable Devices capture growing interest among rehabilitation centers seeking ambulatory recovery tracking.
NMPA Class II and III device registration requirements shape product design standards and market access timelines for both domestic and imported monitoring equipment. GB 9706.1-2020 electrical safety standards and MIIT wireless spectrum allocations for medical Bluetooth and Wi-Fi transmission constrain hardware configurations and software architectures. Stakeholders must monitor provincial centralized procurement shifts toward volume-based purchasing agreements that reward interoperable platform commitments over discrete device margins.
Market Dynamics
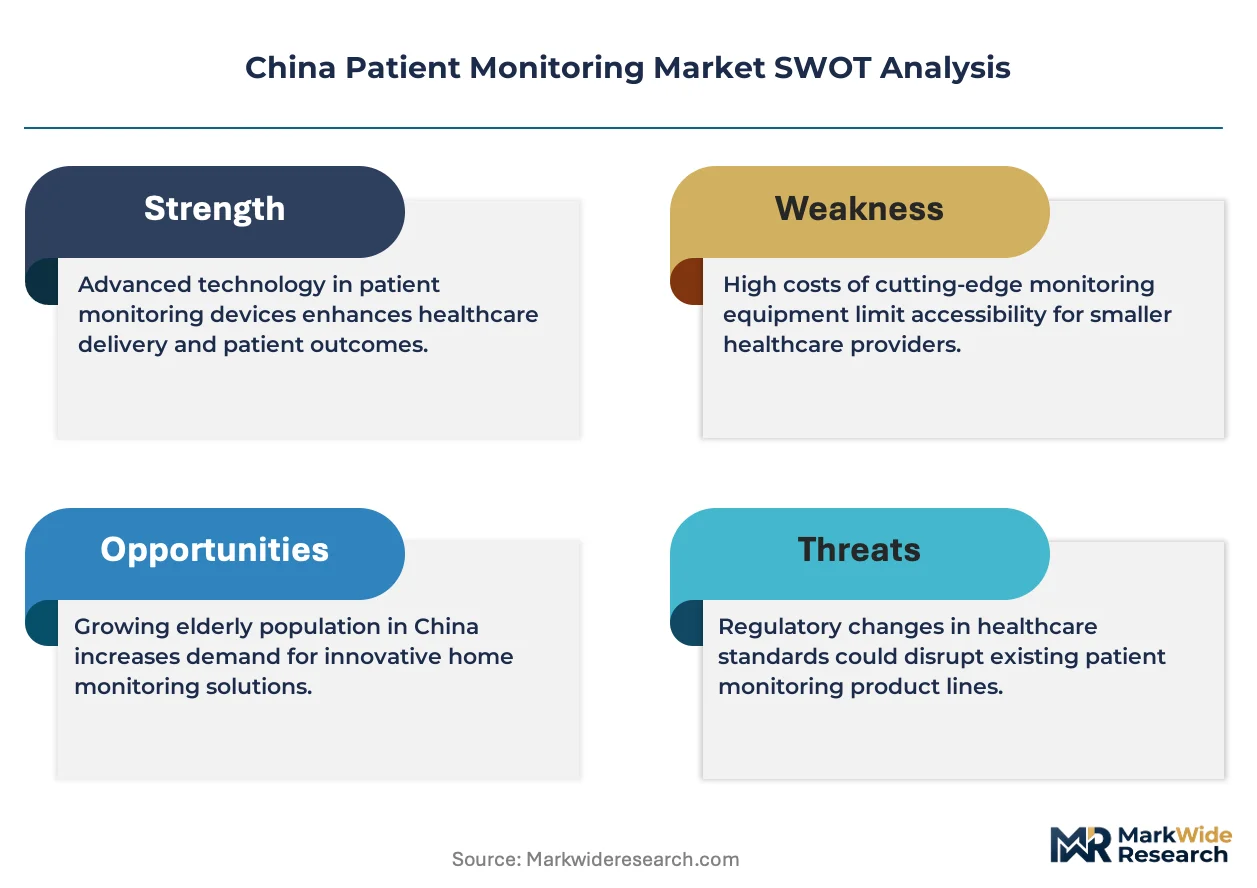
Provincial centralized procurement under China's 14th Five-Year Health Plan is compressing margins while mandating interoperable platform commitments from device manufacturers serving tier-3 municipal hospitals.
Growth Catalysts
- NMPA Class II registration reforms:Compressed approval timelines accelerate domestic manufacturer market access for multiparameter monitors, reducing time-to-revenue cycles.
- Homecare provider networks:Cloud-Based remote monitoring systems serving Yangtze River Delta clusters enable real-time data transmission to centralized clinical teams.
- Bluetooth and Wi-Fi spectrum allocation:MIIT wireless allocations for medical transmission standardize hardware configurations across rehabilitation centers deploying ambulatory tracking.
Market Restraints
- GB 9706.1-2020 compliance costs:Electrical safety standard upgrades require hardware redesigns that inflate production expenses for domestic manufacturers.
- Sensor module import dependency:Concentrated supply of pulse oximetry and electrocardiography components from specific overseas foundries creates input volatility.
- Standalone device substitution:Modular multiparameter bundles displace discrete monitor purchases, eroding margins on legacy single-function equipment.
Strategic Opportunities
- Sichuan and Hunan tier-3 expansion:Municipal hospital procurement waves under national health infrastructure mandates create volume concentration in central China provinces.
- Rehabilitation center wearable integration:Ambulatory recovery tracking devices converge with post-operative surveillance protocols in Beijing and Shanghai tertiary networks.
- Volume-based purchasing alignment:Provincial procurement shifts reward manufacturers committing to interoperable platform ecosystems over discrete device sales.
Industry Challenges
- Legacy hospital IT integration:Bedside monitor deployment requires middleware adaptation to existing hospital information systems, extending implementation timelines.
- Signal processing specialization gap:Shortage of engineers proficient in 125-1000 Hz sampling frequency optimization for high-acuity electrocardiography applications constrains product development velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Patient Monitoring Market |
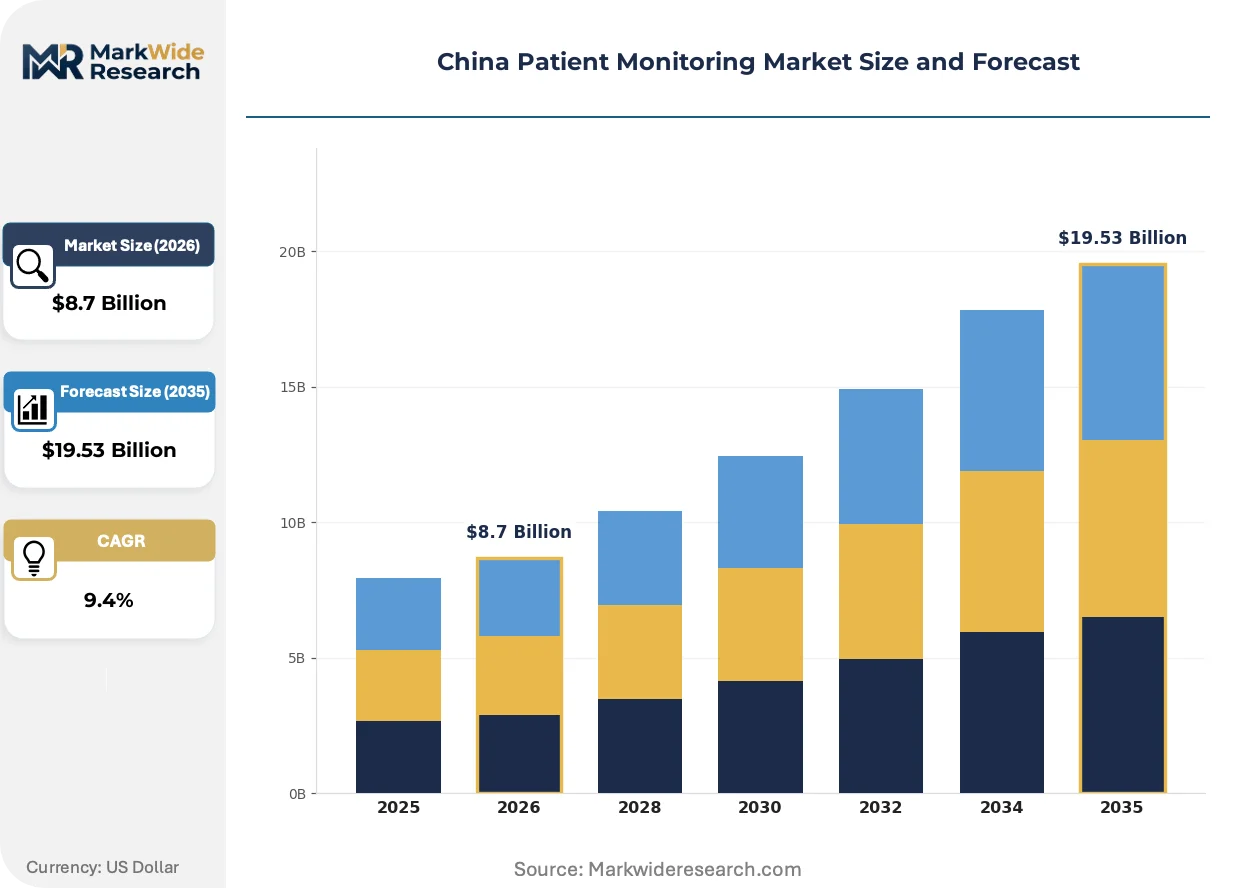
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Devices, Bedside Monitors, Handheld Monitors, Remote Monitoring Systems Technology: Bluetooth, Wi-Fi, Cellular, Cloud-Based End User: Hospitals, Homecare Providers, Long-Term Care Facilities, Rehabilitation Centers Delivery Mode: Remote Monitoring, In-Hospital Monitoring, Telehealth Services, Mobile Health Applications |
| Companies Covered | Medtronic PLC, Johnson & Johnson, Becton Dickinson and Company, Boston Scientific Corporation, Siemens Healthcare GmbH, GE Healthcare, Koninklijke Philips NV, Nihon Kohden Corporation, Abbott Laboratories, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Patient Monitoring Market Emerging Trajectories
Modular hardware architectures and cloud-native software stacks are displacing monolithic device designs across Chinese hospital procurement channels. Three developments define this transition.
Edge computing modules embedded in multiparameter monitors is converging with centralized hospital data lakes to enable real-time deterioration alerts without continuous cloud connectivity. Tier-3 municipal hospitals in Sichuan province are piloting these hybrid architectures for post-operative wards. The convergence is compressing latency requirements for critical care applications while reducing bandwidth costs for rural facility deployments.
NMPA's streamlined Class II device registration pathway is eliminating redundant clinical trial requirements for software-as-medical-device updates. Domestic manufacturers now submit algorithm modifications through post-market change notification channels rather than full re-registration. Cardiology departments in Shanghai tertiary centers are accelerating adoption of electrocardiography monitoring subsystems benefiting from this regulatory efficiency.
Hospital procurement committees are unbundling after-sales service contracts from device capital expenditure, creating standalone recurring revenue streams for technical support and calibration. Municipal health bureaus in Hunan province are mandating multi-year service level agreements as separate evaluation criteria. This behavior is most visible in multiparameter monitor tenders where total cost of ownership calculations now dominate initial purchase price comparisons.
China Patient Monitoring Market Segmentation
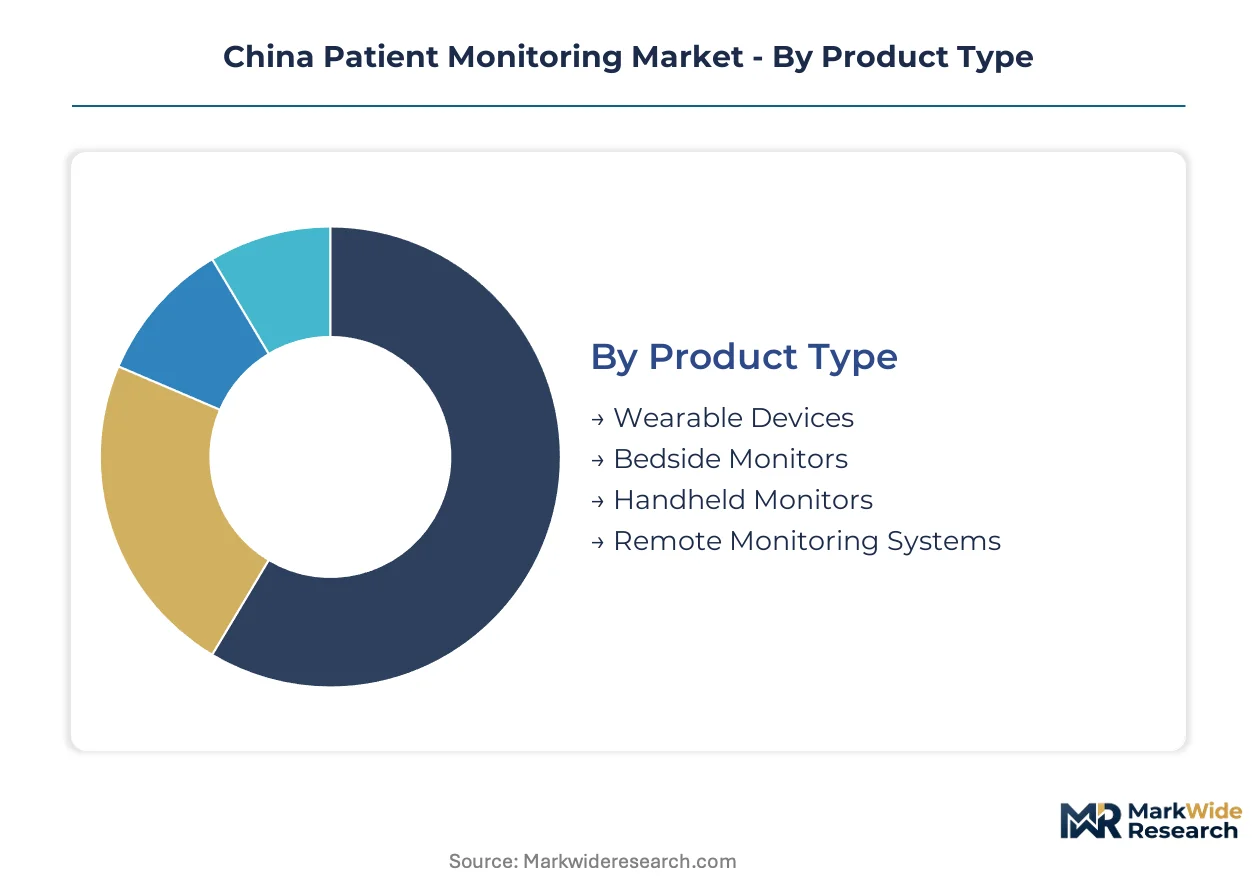
Segmentation in China's patient monitoring market reveals how NMPA Class II registration pathways and MIIT wireless spectrum allocations differentially shape commercial access across hardware configurations. Procurement committees in tier-3 municipal hospitals weight certification compatibility heavily when evaluating bundled device tenders.
Product Type:
NMPA Class II device registration requirements apply uniformly across all product configurations, though bedside monitors face additional GB 9706.1-2020 electrical safety scrutiny that extends approval timelines for imported hardware.
- Bedside Monitors:Multiparameter units integrate electrocardiography, pulse oximetry, non-invasive blood pressure, and respiratory rate sampling at 125-1000 Hz frequencies. Demand concentrates in Beijing and Shanghai tertiary centers where high-acuity contracts favor interoperable platform ecosystems over discrete device margins.
- Remote Monitoring Systems:Cloud-native architectures enable real-time data transmission from homecare providers to centralized clinical teams without continuous connectivity. Yangtze River Delta clusters are deploying these systems fastest under provincial health infrastructure mandates.
- Wearable Devices:Ambulatory recovery tracking devices serve rehabilitation centers seeking post-operative surveillance protocols outside hospital walls.
- Handheld Monitors:Portable multiparameter units target emergency departments and transport scenarios in tier-3 municipal hospitals.
Bedside monitors sit at the top of the volume ranking, with remote monitoring systems climbing the fastest.
Technology:
Cost tier differentiation separates premium cloud-native stacks from standardized connectivity modules, with cellular configurations commanding price premiums for rural deployments lacking reliable broadband infrastructure.
- Cloud-Based:Centralized data lakes with edge computing modules enable real-time deterioration alerts while reducing bandwidth costs. Sichuan province tier-3 hospitals pilot hybrid architectures for post-operative wards.
- Bluetooth:Low-energy protocols standardize hardware configurations for rehabilitation center ambulatory tracking under MIIT medical spectrum allocations.
- Wi-Fi:Hospital-grade transmission supports continuous monitoring in high-density bedside deployments across Hunan municipal procurement waves.
- Cellular:4G/5G modules extend coverage to homecare providers in Yangtze River Delta peripheral zones lacking fixed-line infrastructure.
Cloud-Based technology commands the highest unit economics, with Bluetooth gaining share fastest in volume terms.
End User:
Application urgency varies sharply across settings, with hospitals demanding 24/7 critical alert capabilities while homecare providers prioritize lightweight installation and patient self-management interfaces.
- Hospitals:Tertiary centers in Beijing and Shanghai anchor procurement volume for high-acuity multiparameter bundles with middleware integration to existing hospital information systems.
- Homecare Providers:Yangtze River Delta networks drive demand for remote monitoring systems enabling centralized clinical oversight of distributed patient populations.
- Rehabilitation Centers:Beijing and Shanghai tertiary networks are converging ambulatory recovery tracking with post-operative surveillance protocols.
- Long-Term Care Facilities:Central China provinces under 14th Five-Year Health Plan mandates are expanding monitoring infrastructure for chronic disease management.
Hospitals retain the dominant revenue pool, though homecare providers are expanding most quickly as cloud infrastructure matures.
Delivery Mode:
Customer type segmentation separates institutional purchasers with capital expenditure cycles from consumer-facing channels where mobile health applications bypass traditional procurement committees entirely.
- Remote Monitoring:Cloud-Based systems with real-time data transmission serve homecare provider networks across Yangtze River Delta clusters.
- In-Hospital Monitoring:Bedside and handheld configurations dominate tier-3 municipal hospital procurement in Sichuan and Hunan provinces.
- Telehealth Services:Integrated platforms combine video consultation with continuous physiological measurement for post-operative surveillance.
- Mobile Health Applications:Software-as-medical-device offerings bypass hardware procurement cycles, with NMPA streamlined registration enabling faster algorithm updates.
In-hospital monitoring holds the largest installed base, while mobile health applications are gaining share fastest through regulatory pathway advantages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's patient monitoring industry traces its modern scaling to the 2009 healthcare reform era, when domestic manufacturers first achieved NMPA Class II certification parity with imported equipment. Provincial health infrastructure mandates now distribute procurement volume across multiple economic clusters.
Yangtze River Delta
Shanghai tertiary centers and Jiangsu manufacturing hubs anchor demand for cloud-native remote monitoring systems serving homecare provider networks. MIIT wireless spectrum allocations for medical Bluetooth standardize hardware configurations across rehabilitation centers in the cluster. Suzhou and Hangzhou medical device parks concentrate electrocardiography subsystem production for cardiology department procurement.
Beijing-Tianjin-Hebei
Capital region tertiary hospitals drive high-acuity multiparameter monitor contracts favoring interoperable platform ecosystems. NMPA Class II registration reforms compress approval timelines for domestic manufacturers seeking access to municipal procurement channels. Beijing's Zhongguancun medical technology corridor hosts software-as-medical-device developers leveraging streamlined post-market change notifications.
Sichuan-Chongqing
Tier-3 municipal hospitals in Chengdu and Chongqing expand bedside monitor deployment under 14th Five-Year Health Plan infrastructure mandates. GB 9706.1-2020 electrical safety compliance requirements shape hardware redesign cycles for domestic manufacturers serving central China provinces. Mianyang medical device industrial zones supply pulse oximetry modules for provincial procurement waves.
Pearl River Delta
Guangdong province rehabilitation centers prioritize wearable ambulatory tracking devices for post-operative surveillance protocols outside hospital walls. SAMR market access regulations govern import licensing for overseas electrocardiography component suppliers. Shenzhen hardware ecosystems manufacture edge computing modules for hybrid cloud-local monitoring architectures.
Shandong Peninsula
Jinan and Qingdao medical device clusters produce handheld portable monitors targeting emergency department scenarios in tier-3 municipal hospitals. Provincial centralized procurement under national health infrastructure mandates rewards volume-based purchasing commitments from domestic manufacturers. Weihai sensor foundries face input volatility from concentrated overseas pulse oximetry component supply.
China Patient Monitoring Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification-grade and platform-integration dimensions in China's patient monitoring sector. The vendor base stratifies between multinational corporations with integrated ecosystem strategies and domestic manufacturers competing through localized production scale. Three archetypes dominate: ecosystem integrators anchoring high-acuity tertiary contracts, component specialists supplying electrocardiography subsystems, and scale-driven fabricators serving provincial procurement volume. Competitive moves concentrate on interoperability commitments for volume-based purchasing alignment and middleware adaptation to legacy hospital information systems.
Within the ecosystem integrator tier, Medtronic PLC and GE Healthcare occupy positions defined by platform breadth rather than discrete device margins. Koninklijke Philips NV exemplifies the multinational archetype competing through localized manufacturing presence. Nihon Kohden Corporation represents the specialization vector, anchoring cardiology department relationships through electrocardiography monitoring subsystem expertise. These three companies illustrate how foreign-origin players navigate NMPA registration pathways and provincial procurement committee evaluation criteria.
| Leading Market Players |
|---|
| Medtronic PLC |
| Johnson & Johnson |
| Becton Dickinson and Company |
| Boston Scientific Corporation |
| Siemens Healthcare GmbH |
| GE Healthcare |
| Koninklijke Philips NV |
| Nihon Kohden Corporation |
| Abbott Laboratories |
| Others |
Supply Flow & Price Mechanics
China's dual carbon goals gate qualified supply and premium-tier pricing access for patient monitoring equipment, as GB 9706.1-2020 electrical safety compliance and MIIT wireless spectrum certification become baseline requirements for tier-3 municipal hospital procurement committees evaluating multiparameter monitor tenders.
Pricing Analysis
Volume-based purchasing agreements with unbundled after-sales service contracts dominate procurement evaluation criteria across Sichuan and Hunan provinces. Price differentiation hinges on NMPA Class II registration tier and middleware integration depth to legacy hospital information systems. Cost compression in standard-grade bedside monitors intensifies because provincial centralized procurement rewards interoperable platform commitments over discrete device margins. Homecare providers in the Yangtze River Delta cluster demonstrate highest price sensitivity, while Beijing and Shanghai tertiary centers prioritize total cost of ownership calculations.
Supply Chain Analysis
Pulse oximetry and electrocardiography sensor modules rest on concentrated overseas foundry supply from Japan, South Korea, and select European specialty component producers. Domestic manufacturers source edge computing chipsets, Bluetooth low-energy protocols, and Wi-Fi transmission modules through Shenzhen hardware ecosystems and Suzhou medical device parks. Single-source vulnerability in high-frequency sampling components creates input volatility for 125-1000 Hz electrocardiography applications. Distribution runs through provincial health bureaus mandating multi-year service level agreements as separate tender evaluation criteria.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's patient monitoring sector offers margin-expansion pathways through cloud-native software stack differentiation and recurring service revenue unbundling from device capital expenditure.
For Market Incumbents: Cement platform ecosystem lock-in through middleware adaptation to legacy hospital information systems in tier-3 municipal hospitals. Deepen backward integration into edge computing module production within Shenzhen hardware corridors to defend against modular bundle procurement pressure. Prioritize NMPA Class III registration investment for high-acuity electrocardiography monitoring subsystems serving cardiology departments. For New Entrants and Emerging Players: Launch via software-as-medical-device pathways leveraging NMPA streamlined post-market change notification channels for algorithm updates. Target rehabilitation center wearable integration in Beijing and Shanghai tertiary networks where ambulatory recovery tracking converges with post-operative surveillance protocols. Pursue white-label electrocardiography subsystem supply to domestic manufacturers lacking 125-1000 Hz sampling frequency optimization expertise. For Investors and Strategic Acquirers: Roll-up economics work for software-as-medical-device developers because NMPA registration reforms compress approval timelines and enable recurring algorithm update revenue streams. Target domestic manufacturers with captive pulse oximetry module production in Mianyang and Weihai industrial zones. Watch provincial centralized procurement committee composition shifts toward technical evaluation dominance as inflection indicator for platform-versus-device preference.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class II Registration Streamlining | Compressed approval timelines accelerate domestic manufacturer market access for multiparameter monitors. |
| Cloud-Native Remote Monitoring Deployment | Real-time data transmission from Yangtze River Delta homecare providers enables centralized clinical oversight. |
| Edge Computing Module Integration | Hybrid cloud-local architectures reduce bandwidth costs for Sichuan province post-operative ward pilots. |
| After-Sales Service Contract Unbundling | Standalone recurring revenue streams separate technical support from device capital expenditure. |
| Provincial Procurement Committee Engagement | Volume-based purchasing alignment rewards interoperable platform commitments over discrete margins. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital procurement committee members, biomedical engineers, GPO contracts managers, and NMPA regulatory affairs specialists with secondary validation against hospital procurement databases, GPO contract filings, and MIIT wireless spectrum allocation records. Bottom-up installation base modeling and top-down expenditure flow analysis triangulated market sizing across product type, technology, end user, and delivery mode segmentation.
Segment-weighting approaches applied differential growth assumptions to bedside monitors, remote monitoring systems, wearable devices, and handheld configurations across cloud-based, Bluetooth, Wi-Fi, and cellular technology tiers. CAGRs derived from installed base expansion rates, replacement cycle compression, and average selling price trajectory modeling. Forecast inputs incorporated NMPA registration pipeline velocity, provincial health infrastructure mandate implementation schedules, and MIIT medical spectrum allocation expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under NMPA regulatory pathway delays or sensor module supply disruptions. Assumptions reflect documented procurement committee evaluation criteria, GB 9706.1-2020 compliance implementation schedules, and tier-3 municipal hospital budget allocation patterns. A small set of triggers—provincial procurement centralization acceleration, electrocardiography component tariff exposure, and software-as-medical-device reimbursement clarity—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Remote Home Monitoring Systems Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Fetal and Neonatal Heart Monitor Market
Patient Monitoring
US Remote Patient Monitoring and Care Market
Patient Monitoring
Portable Multi-Parameter Monitors Market
Patient Monitoring
Global Ambulatory Blood Pressure Monitoring (ABPM) Devices Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Brain Tissue Oxygen Monitoring Systems Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
South America Hemodynamic Monitoring Market
Patient Monitoring
Ambulatory Heart Monitor Market
Patient Monitoring
Middle East and Africa Respiratory Monitoring Market
Patient Monitoring
Global Patient Positioning System Market
Patient Monitoring
Mobile Continuous Patient Monitors Market
Patient Monitoring
MRI Compatible Patient Monitoring Systems Market
Patient Monitoring
Body Fat Measurement Market